
 Potassium Chlorate Market | 2026-2036
Potassium Chlorate Market Size, Share, and Industry Trends Forecast 2026-2036
Potassium Chlorate Market Outlook
Skilled chlor-alkali process engineers is unwinding capacity expansion timelines across the potassium chlorate value chain. Nouryon Chemicals Holding BV sustains integrated electrochemical production networks across Northern Europe. Tianjin Xinyuan Chemical dominates captive supply arrangements serving domestic oxidizer demand. ICL Group leverages mineral access in the Dead Sea basin to anchor bromine-chlorate co-production economics.
Potassium chlorate (KClO₃) is a white crystalline salt produced through electrolysis of sodium chloride followed by metathesis with potassium chloride, yielding a compound with molecular weight 122.55 g/mol and decomposition threshold near 400°C. The substance functions primarily as a controlled oxidizer in pyrotechnic formulations, bleaching sequences, and agricultural defoliation. Industrial Grade product commands the largest volume share as paper and textile bleaching operations in Asia maintain steady offtake, while Technical Grade material captures premium pricing from pyrotechnic blenders seeking specific particle size distributions. Fireworks application represents the fastest-expanding demand pool as consumer celebration markets in South Asia and Southeast Asia broaden distribution reach.
China's MEE enforces emission caps on chlor-alkali facilities that constrain mercury-cell and diaphragm-cell process expansion, redirecting investment toward membrane technology retrofits. India's CEA and state pollution control boards mandate storage and transport protocols for oxidizer-class chemicals that shape warehousing infrastructure requirements. REACH registration obligations in Europe limit non-compliant import volumes. Stakeholders must monitor membrane technology migration timelines and regional oxidizer substitution patterns to calibrate capacity commitments.
Market Dynamics
Membrane-cell electrochemistry is supplanting mercury and diaphragm processes across chlor-alkali installations, tightening feedstock availability for potassium chlorate manufacturers and compressing legacy capacity economics.
Growth Catalysts
- India's PLI scheme for chemicals:Production-linked incentives for specialty chemical manufacturing are drawing investment into domestic oxidizer synthesis infrastructure.
- Perchlorate substitution protocols:Environmental restrictions on perchlorate discharge in groundwater basins are redirecting pyrotechnic formulators toward potassium chlorate alternatives.
- Diwali celebration markets:Consumer fireworks consumption in Tamil Nadu and Uttar Pradesh is expanding distribution networks for technical-grade oxidizer supply.
Market Restraints
- Potassium chloride price volatility:Muriate of potash contract pricing swings with Belarusian and Russian supply disruptions strain metathesis process margins.
- China's dual carbon enforcement:Provincial emission intensity targets in Shandong and Jiangsu are capping chlor-alkali expansion regardless of membrane technology adoption.
- Perchlorate technical performance:Higher oxygen content and thermal stability in ammonium perchlorate limit potassium chlorate penetration in solid rocket propellant formulations.
Strategic Opportunities
- Indonesian fireworks manufacturing:Purbalingga and Ponorogo cluster development is creating import substitution demand for bleaching-grade oxidizer supply.
- Digital pyrotechnic ignition systems:Integration of wireless firing modules with traditional oxidizer chemistry is opening premium formulation segments.
- EU F-Gas Regulation phase-down:Refrigerant destruction protocols requiring controlled oxidizer chemistry are generating industrial waste treatment demand.
Industry Challenges
- Mercury-cell process decommissioning:Skilled technicians capable of membrane retrofit engineering command premium wages that extend project timelines.
- UN hazard classification harmonization:Divergent shipping codes between IMO and ADR frameworks complicate cross-border oxidizer logistics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Potassium Chlorate Market |
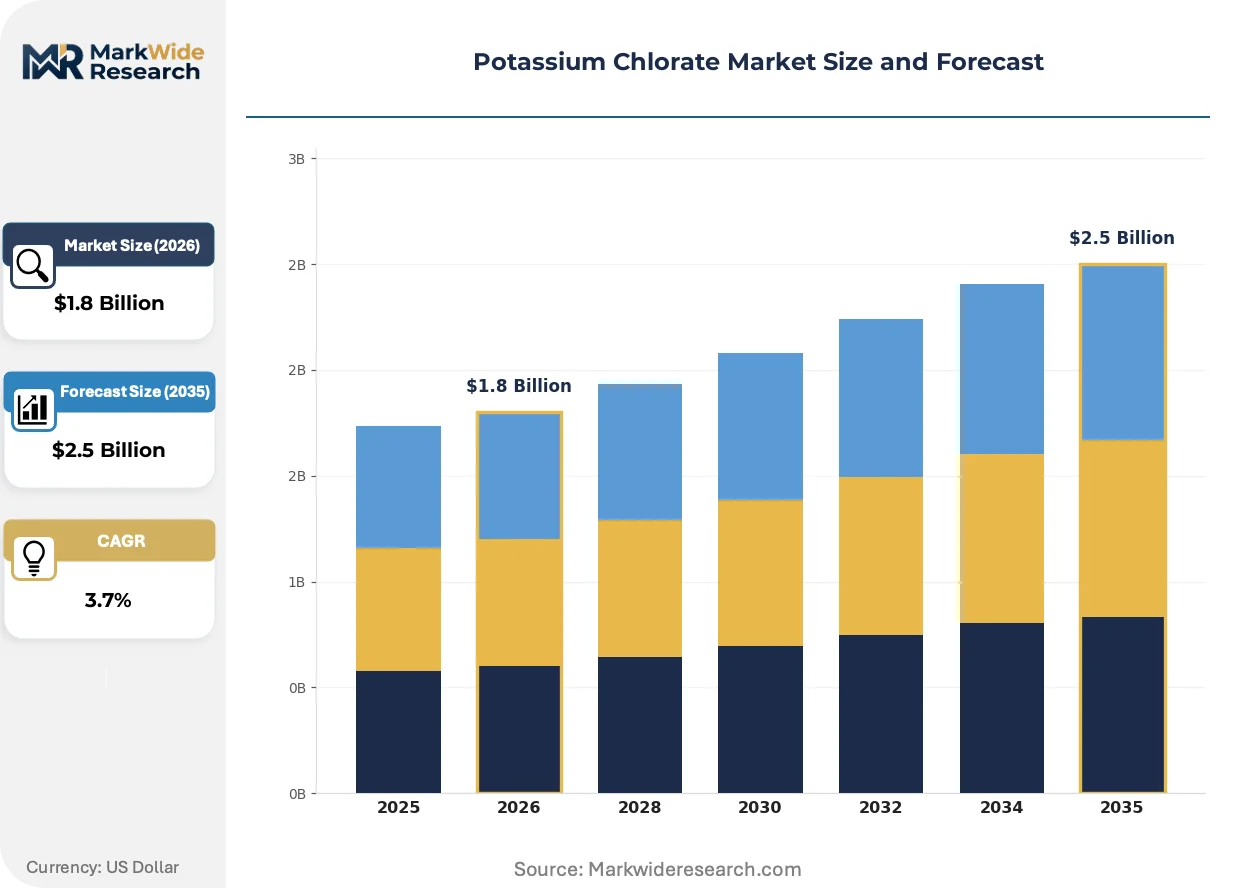
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.5 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Food Grade, Laboratory Grade, Technical Grade Application: Explosives, Oxidizing Agent, Herbicides, Fireworks End User: Chemical Industry, Pharmaceuticals, Agriculture, Food Processing Distribution Channel: Direct Sales, Distributors, Online Sales, Retailers |
| Companies Covered | Tianjin Xinyuan Chemical, Tessenderlo Group, Nouryon Chemicals Holding BV, Vaighai Agro, Cangzhou Goldlion Chemicals Co., Ltd., ICL Group, Nippon Chemical Industrial Co., Ltd., Hebei Xinji Chemical, Olin Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Potassium Chlorate Market Strategic Shifts
Process intensification and regulatory chemistry are compressing traditional production pathways while opening novel application vectors for controlled oxidizer compounds.
Membrane electrolysis with dimensionally stable anodes is supplanting graphite and platinum-coated titanium systems in chlor-alkali cells. Chinese state-owned chemical conglomerates are retrofitting Shandong installations at accelerated schedules. The technology shift is enabling concurrent chlorine and hydrogen production that alters potassium chlorate co-production economics.
REACH registration obligations for oxidizer-class substances are tightening import documentation requirements across European ports. ECHA substance evaluation protocols are extending dossier preparation timelines for non-EU manufacturers. Pyrotechnic blenders in Germany and Poland are consolidating supplier relationships to reduce compliance fragmentation.
Specification-driven purchasing is displacing spot-market oxidizer acquisition among large fireworks manufacturers. Long-term supply agreements with fixed particle size distribution parameters are replacing quarterly tender processes. Tamil Nadu-based processors are leading this contract structure adoption to secure festival-season inventory certainty.
Potassium Chlorate Market Segmentation
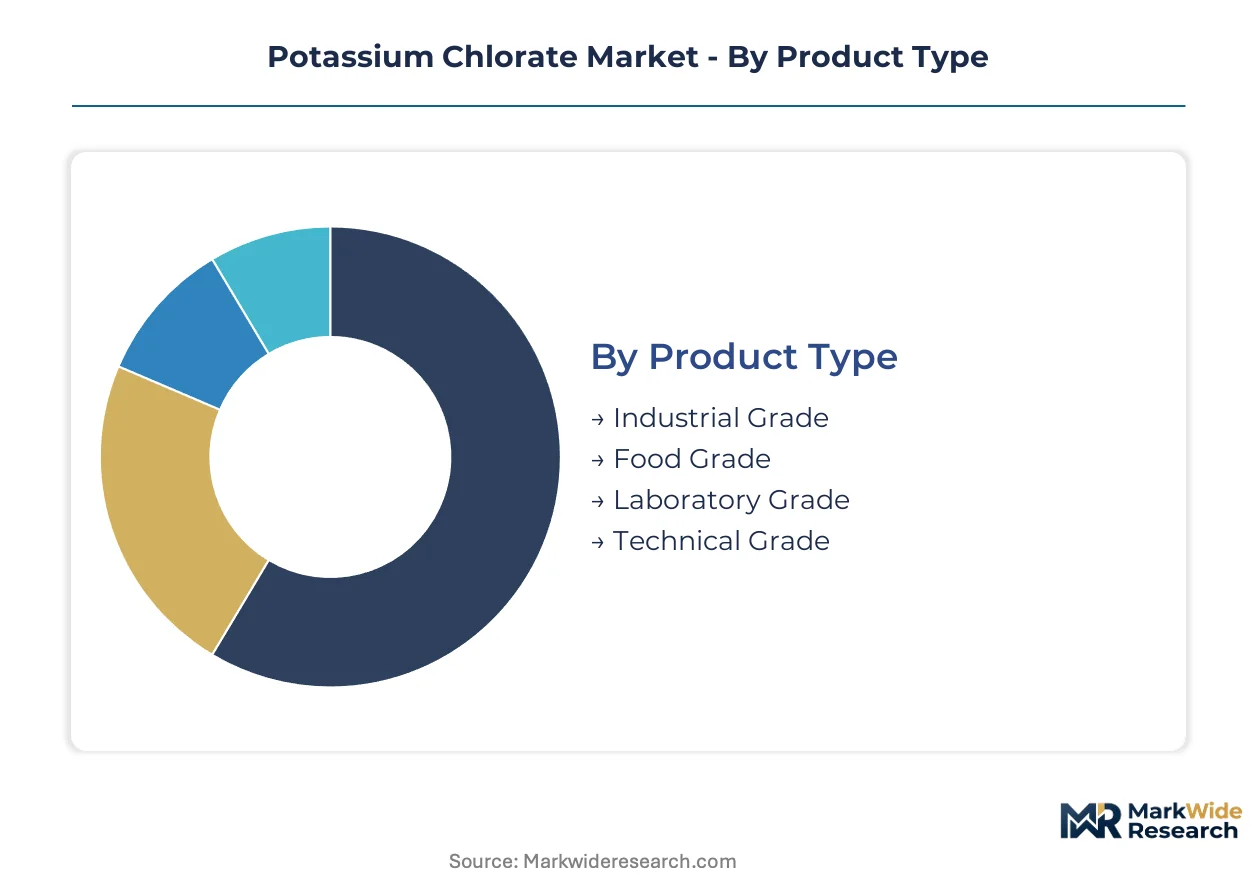
Potassium chlorate market segmentation reveals distinct procurement patterns across oxidizer applications. Grade specifications determine regulatory pathways and end-use eligibility. Distribution channel selection correlates directly with volume scale and hazard classification requirements.
Product Type:
Industrial Grade and Technical Grade segments serve predominantly domestic pyrotechnic and bleaching markets, while Laboratory Grade and Food Grade volumes concentrate in export-oriented specialty chemical trade.
- Industrial Grade:White crystalline salt with 99% minimum purity and controlled moisture content below 0.5%. Paper and textile bleaching operations in Shandong and Jiangsu provinces absorb the bulk of Asian offtake, constrained by MEE emission caps on chlor-alkali feedstock supply.
- Technical Grade:Engineered particle size distributions between 100-400 mesh for pyrotechnic ignition reliability. Tamil Nadu and Uttar Pradesh fireworks manufacturers drive specification-driven procurement with Diwali inventory cycles dictating contract timing.
- Food Grade:Meets FCC and JIS purity standards for controlled agricultural defoliation. Japanese citrus processing cooperatives specify this grade for pre-harvest leaf removal.
- Laboratory Grade:ACS-certified material for analytical reagent and educational demonstration use. European research institutions source through specialized chemical distributors under REACH registration protocols.
Industrial Grade holds the largest share; momentum sits with Technical Grade.
Application:
Cost tier differentiation separates commodity oxidizer sales from premium formulation contracts, with fireworks and explosives commanding price premiums over agricultural and industrial chemical uses.
- Fireworks:Primary oxidizer in flash powder and whistle compositions with 400°C decomposition threshold enabling controlled ignition sequences. Indonesian Purbalingga cluster expansion and Vietnamese export manufacturing are expanding technical-grade demand pools.
- Explosives:Blasting cap initiators and commercial mining charges utilize potassium chlorate-perchlorate hybrid formulations. South African platinum belt mining operations specify this chemistry for underground fragmentation.
- Oxidizing Agent:Industrial bleaching sequences in pulp processing and textile finishing. Indian paper mills in Vapi and Moradabad maintain steady offtake under state pollution control board storage mandates.
- Herbicides:Defoliant formulations for cotton and soybean harvest preparation. Brazilian Mato Grosso agricultural cooperatives apply potassium chlorate-based desiccants prior to mechanical harvesting.
Fireworks captures the steepest expansion trajectory; oxidizing agent maintains volume dominance.
End User:
Customer type segmentation distinguishes between integrated chemical producers with captive chlor-alkali capacity and merchant market purchasers exposed to potassium chloride price volatility.
- Chemical Industry:Chlor-alkali integrated producers and specialty oxidizer blenders. Nouryon Chemicals electrochemical networks and Tianjin Xinyuan captive supply arrangements illustrate vertical integration advantages.
- Agriculture:Crop desiccation and defoliation applications with seasonal concentration in harvest windows. Australian cotton gins and Turkish pistachio orchards represent distinct geographic demand nodes.
- Pharmaceuticals:Limited oxidizer applications in synthetic intermediate production. Indian CDSCO-regulated facilities source through import channels with DGFT license documentation.
- Food Processing:Regulatory-constrained usage for specific processing aids. Japanese METI food additive standards and EU EFSA evaluations govern permissible applications.
Chemical Industry holds the largest share; Agriculture presents the fastest volume climb.
Distribution Channel:
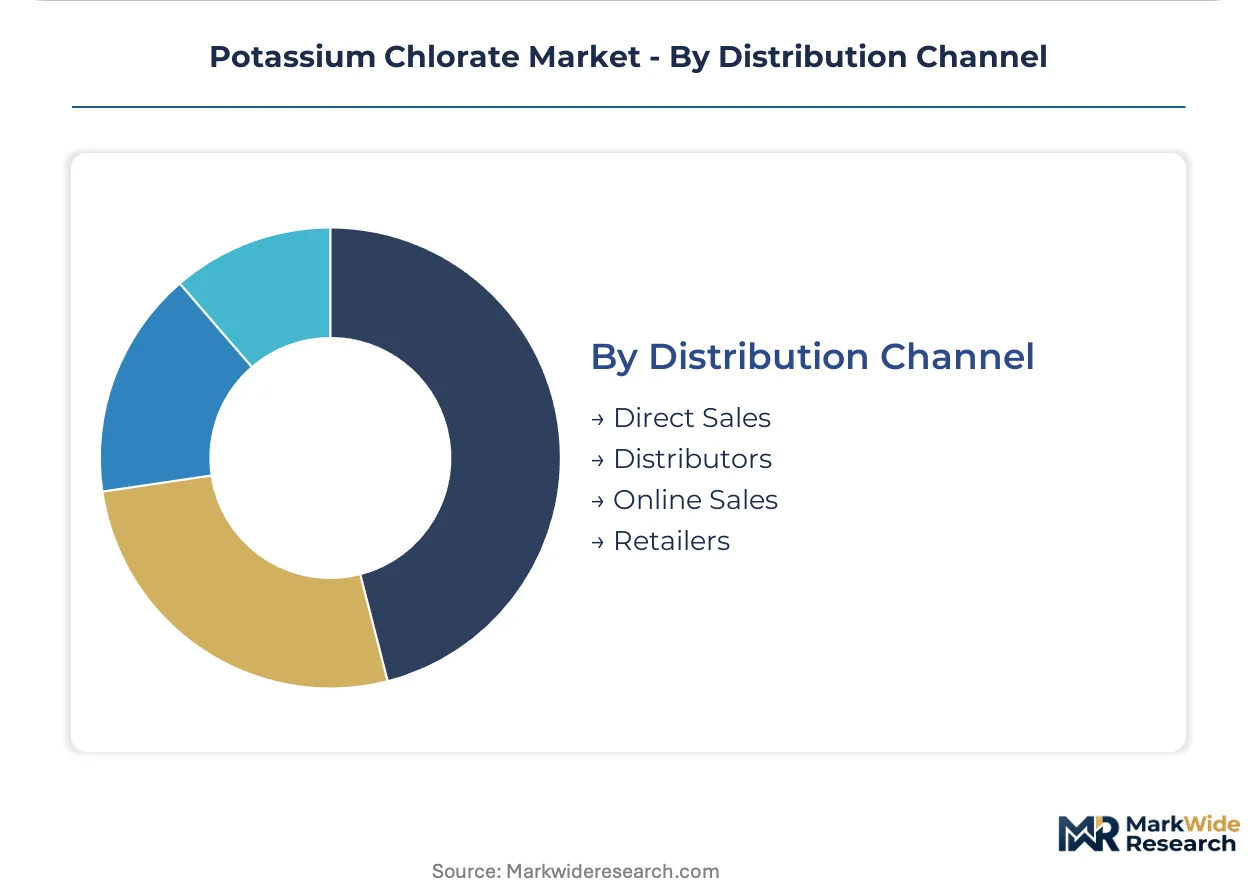
Supply concentration favors direct sales relationships for volume oxidizer offtake, while fragmented retailer networks serve small-scale pyrotechnic formulators with hazardous material handling limitations.
- Direct Sales:Long-term supply agreements with fixed particle size specifications. Large fireworks manufacturers in Sivakasi and Banten provinces negotiate annual contracts bypassing intermediary markups.
- Distributors:Regional chemical distributors with UN hazard classification compliance capabilities. European pyrotechnic blenders in Germany and Poland consolidate supplier relationships to reduce REACH documentation fragmentation.
- Online Sales:Laboratory-grade and small-batch technical sales through specialized chemical marketplaces. Academic institutions and small formulators source limited quantities under controlled shipping protocols.
- Retailers:Local agricultural supply stores for herbicide-grade material in cotton-growing regions. Texas High Plains and Australian Riverina farm supply cooperatives stock seasonal defoliant inventories.
Direct Sales holds the largest share; Distributors are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MEE emission caps on chlor-alkali facilities are reshaping production economics across East Asian chemical processing clusters. Provincial dual carbon enforcement in Shandong and Jiangsu provinces is redirecting investment toward membrane technology retrofits.
China
Shandong and Jiangsu provinces host the dominant chlor-alkali installations feeding potassium chlorate synthesis. MEE provincial emission intensity targets cap expansion regardless of membrane technology adoption. Tianjin-based chemical conglomerates maintain captive oxidizer supply arrangements serving domestic pyrotechnic demand.
India
Tamil Nadu and Uttar Pradesh fireworks manufacturers drive technical-grade oxidizer procurement with Diwali inventory cycles dictating contract timing. CEA and state pollution control boards mandate storage and transport protocols for oxidizer-class chemicals. Sivakasi cluster processors are consolidating supplier relationships to secure festival-season inventory certainty.
Japan
METI food additive standards govern Food Grade potassium chlorate applications in citrus processing cooperatives. JIS purity specifications constrain import documentation requirements for agricultural defoliation use. Kyushu-based agricultural processors specify pre-harvest leaf removal chemistry for domestic fruit cultivation.
Germany
REACH registration obligations tighten import documentation requirements for oxidizer-class substances across European ports. ECHA substance evaluation protocols extend dossier preparation timelines for non-EU manufacturers. Pyrotechnic blenders in Germany and Poland are consolidating supplier relationships to reduce compliance fragmentation.
Indonesia
Purbalingga and Ponorogo cluster development is creating import substitution demand for bleaching-grade oxidizer supply. Consumer fireworks manufacturing expansion in Central Java is broadening distribution networks for technical-grade material. Domestic formulators are negotiating direct supply agreements bypassing regional intermediary markups.
Potassium Chlorate Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in the potassium chlorate value chain. Chlor-alkali integrated producers with captive electrochemical capacity command margin advantages over merchant market purchasers exposed to potassium chloride price volatility. The competitive terrain separates membrane-technology retrofit leaders from legacy mercury-cell operators facing decommissioning timelines. Strategic moves center on backward integration into chlor-alkali feedstock and long-term supply agreements with fixed particle size specifications.
Among Dutch- and Belgian-based chemical conglomerates, Nouryon Chemicals Holding BV and Tessenderlo Group occupy positions within the integrated electrochemical tier. Tianjin Xinyuan Chemical exemplifies the China-based captive supply model serving domestic oxidizer demand. These three entities represent distinct archetypes: Northern European integrated networks, Chinese state-aligned chemical producers, and regional specialists with mineral access advantages.
| Leading Market Players |
|---|
| Tianjin Xinyuan Chemical |
| Tessenderlo Group |
| Nouryon Chemicals Holding BV |
| Vaighai Agro |
| Cangzhou Goldlion Chemicals Co., Ltd. |
| ICL Group |
| Nippon Chemical Industrial Co., Ltd. |
| Hebei Xinji Chemical |
| Olin Corporation |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake agreements with fixed particle size specifications lock in supply access and price visibility for Tamil Nadu fireworks manufacturers facing Diwali inventory cycles, while spot-market exposure concentrates among small-scale agricultural formulators in cotton-growing regions.
Pricing Analysis
Price spreads between Chinese membrane-cell producers and Indian merchant-market purchasers reflect potassium chloride contract volatility and membrane retrofit capital recovery timelines. Three-tier pricing structure across Technical Grade, Industrial Grade, and Food Grade levels tracks certification burden and particle engineering requirements. Pricing pressure stems from Belarusian and Russian muriate of potash supply disruptions straining metathesis process margins. Agricultural herbicide buyers exhibit highest price sensitivity; pyrotechnic blenders absorbing specification premiums show lowest.
Supply Chain Analysis
Container availability constraints on Shanghai-Rotterdam and Shanghai-Mumbai trade lanes extend chlor-alkali feedstock delivery schedules for European pyrotechnic blenders. Supply concentrates in China, India, and Germany, with membrane-cell installations in Shandong and Jiangsu provinces feeding captive oxidizer networks. The chain rests on sodium chloride electrolysis capacity, potassium chloride metathesis chemistry, and dimensionally stable anode technology. Single-source vulnerability sits with mercury-cell decommissioning timelines compressing skilled technician availability. Distribution runs through direct sales relationships for volume offtake and regional distributors for REACH-compliant European channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Membrane-cell electrochemical engineering expertise has become the constraining asset across potassium chlorate value chains, with retrofit timelines extending 18-24 months beyond original schedules as qualified technicians command premium wages.
For Market Incumbents: Shield integrated electrochemical margins by accelerating membrane technology migration ahead of MEE provincial emission deadlines in Shandong and Jiangsu. Consolidate supplier relationships with Sivakasi cluster processors through multi-year particle specification contracts. Lock in potassium chloride offtake agreements before Belarusian supply volatility transmits into Q4 contract pricing. For New Entrants and Emerging Players: Anchor in Indonesian Purbalingga and Ponorogo cluster development, where import substitution demand for bleaching-grade oxidizer supply outpaces domestic membrane-cell capacity installation. Target technical-grade procurement from Vietnamese export manufacturers seeking alternatives to Chinese captive supply arrangements. Pursue direct supply agreements with Central Java formulators bypassing regional intermediary markups. For Investors and Strategic Acquirers: Chlor-alkali integrated specialists with captive oxidizer synthesis and Dead Sea mineral access represent the priority acquisition archetype for margin insulation. Long-term viability hinges on membrane technology retrofit completion and dual carbon compliance positioning across the analysis window. Watch for MEE provincial emission intensity target acceleration as inflection indicator for capacity constraint severity.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Technology Retrofit | MEE emission caps in Shandong and Jiangsu provinces mandate mercury-cell phase-out regardless of expansion permits. |
| Backward Integration into Chlor-Alkali | Tianjin Xinyuan captive supply model eliminates potassium chloride price volatility exposure for oxidizer synthesis. |
| Long-term Supply Agreement | Sivakasi cluster processors negotiate annual particle specification contracts securing Diwali inventory certainty. |
| Joint Venture in Indonesian Cluster | Purbalingga formulators seek bleaching-grade oxidizer partnerships reducing Chinese import dependency. |
| REACH Registration Consolidation | German and Polish pyrotechnic blenders reduce ECHA documentation fragmentation through supplier relationship concentration. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of trade customs data, chlor-alkali industry association reports, and SEC filings from listed chemical producers. Discussions with membrane-cell process engineers, fireworks manufacturer procurement leads, and regional chemical distributors informed capacity constraint and pricing dynamics assessment. Secondary validation drew from MEE emission disclosure databases, ECHA substance evaluation protocols, and Indian state pollution control board storage mandate documentation. Bottom-up grade-segment volume builds triangulated against top-down chlor-alkali capacity allocation estimates.
Segmentation dimensions modeled span grade tier (Industrial, Technical, Food, Laboratory), end-use application (fireworks, explosives, oxidizing agent, herbicides), and regional production hub concentration. CAGRs derived from electrolysis capacity installation schedules cross-referenced against pyrotechnic demand growth in South and Southeast Asian celebration markets across the projection horizon. Forecast inputs incorporated membrane technology migration timelines and potassium chloride contract pricing volatility assumptions.
Decision-makers should treat outputs as directional under base assumptions of MEE emission cap enforcement continuity and no major potassium chloride supply corridor disruption; material deviation would warrant model refresh. Specific risk factors include accelerated mercury-cell decommissioning mandates, Indonesian import substitution policy shifts, and perchlorate substitution protocol reversals. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Picric Acid Market
Bulk Chemicals
United States Fumaric Acid Market
Bulk Chemicals
Malathion Market
Bulk Chemicals
Global Phosphoric Acid Market
Bulk Chemicals
2-Methylfuran Market
Bulk Chemicals
Global Naphthenic Base Oil Market
Bulk Chemicals
Global Ammonium Chloride Market
Bulk Chemicals
Asia-Pacific Choline Chloride Market
Bulk Chemicals
Needle Coke Market
Bulk Chemicals
Carbonate Market
Bulk Chemicals
Borates Market
Bulk Chemicals
Formic Acid Market
Bulk Chemicals
Copper Sulphate Market
Bulk Chemicals
Nitric Acid Market
Bulk Chemicals
Linear Alkylbenzene (LAB) Market
Bulk Chemicals
Sodium Molybdate Market