
 Global Basic Chemicals Market | 2026-2036
Global Basic Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Global Basic Chemicals Market Analysis
Buyer concentration among automotive and construction offtakers is hardening as tier-one suppliers consolidate procurement across North America and Europe. Dow Chemical Company leverages integrated ethylene crackers along the US Gulf Coast to sustain feedstock cost advantages against import-dependent rivals. BASF anchors its European position through the Ludwigshafen Verbund site, the world's largest integrated chemical complex. Sinopec dominates domestic Chinese supply chains, controlling pipeline access to Shengli oilfield feedstocks that competitors cannot replicate.
Basic chemicals comprise commodity-grade inorganic and organic compounds—ethylene, propylene, benzene, chlorine, caustic soda, and ammonia—produced via steam cracking, catalytic reforming, and chlor-alkali electrolysis at purity grades typically exceeding 99.5 percent for industrial use. These intermediates serve as molecular building blocks for plastics, synthetic fibers, agrochemicals, and coatings across virtually all manufacturing sectors. Alkylamines and acetic acid within the product type dimension carry elevated margin profiles due to pharmaceutical and food-grade certification requirements that commodity ethylene glycol cannot command. The application split between plastics and paints reveals divergent growth trajectories, with plastics tied to packaging volume cycles and paints exposed to construction cyclicality in China and the United States.
The US Environmental Protection Agency enforces National Emission Standards for Hazardous Air Pollutants that limit benzene fugitive emissions from chemical manufacturing, while REACH in Europe mandates registration and hazard communication for all substances above one tonne annual volume. China's Ministry of Ecology and Environment enforces dual carbon intensity targets that are forcing coal-to-chemicals producers toward natural gas and biomass feedstock pivots. Stakeholders must monitor feedstock switching economics and carbon border adjustment mechanisms to decide whether to relocate cracking capacity to low-carbon hydrogen hubs or invest in point-source carbon capture retrofits at legacy sites.
Market Dynamics
Feedstock switching economics are compressing legacy coal-to-chemicals operations while hydrogen hub investments and carbon border adjustments force capacity relocation decisions across the US Gulf Coast, Rotterdam, and Ningbo.
Growth Catalysts
- Automotive lightweighting mandates:Polymer demand from vehicle weight reduction programs is hardening procurement volumes across Germany, Japan, and the United States.
- EU Green Deal emissions benchmarks:Tightening standards for ethylene and ammonia production are accelerating capital flows into low-carbon retrofits and green hydrogen pilots.
- Shale gas economics:Cost-advantaged feedstock positions along the US Gulf Coast petrochemical corridor sustain export-competitive ethylene cracking against naphtha-dependent rivals.
Market Restraints
- Natural gas price volatility:European crackers dependent on LNG imports face margin compression during winter demand spikes and pipeline supply disruptions.
- Chinese coal-to-chemicals concentration:Overcapacity in methanol and ammonia from coal gasification creates export dumping pressure that destabilizes regional pricing.
- REACH registration friction:European hazard communication mandates for substances above one tonne annual volume impose compliance costs that disadvantage small-batch specialty producers.
Strategic Opportunities
- India specialty amines underpenetration:Pharmaceutical-grade alkylamine capacity gaps create import substitution potential for domestic producers achieving CDSCO certification.
- Biomass feedstock pivots:China's dual carbon goals are forcing MEE enforcement that redirects coal-based producers toward agricultural residue and municipal waste gasification.
- Carbon capture retrofits:Point-source CCUS integration at legacy steam crackers offers compliance hedging against EU carbon border adjustment mechanisms.
Industry Challenges
- Process control engineering scarcity:DCS optimization and advanced process control expertise for integrated crackers commands premium compensation that inflates opex at greenfield sites.
- Multi-year certification timelines:Pharmaceutical-grade acetic acid qualification through FDA and EMA audits extends 18-24 months, freezing working capital in inventory builds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Basic Chemicals Market |
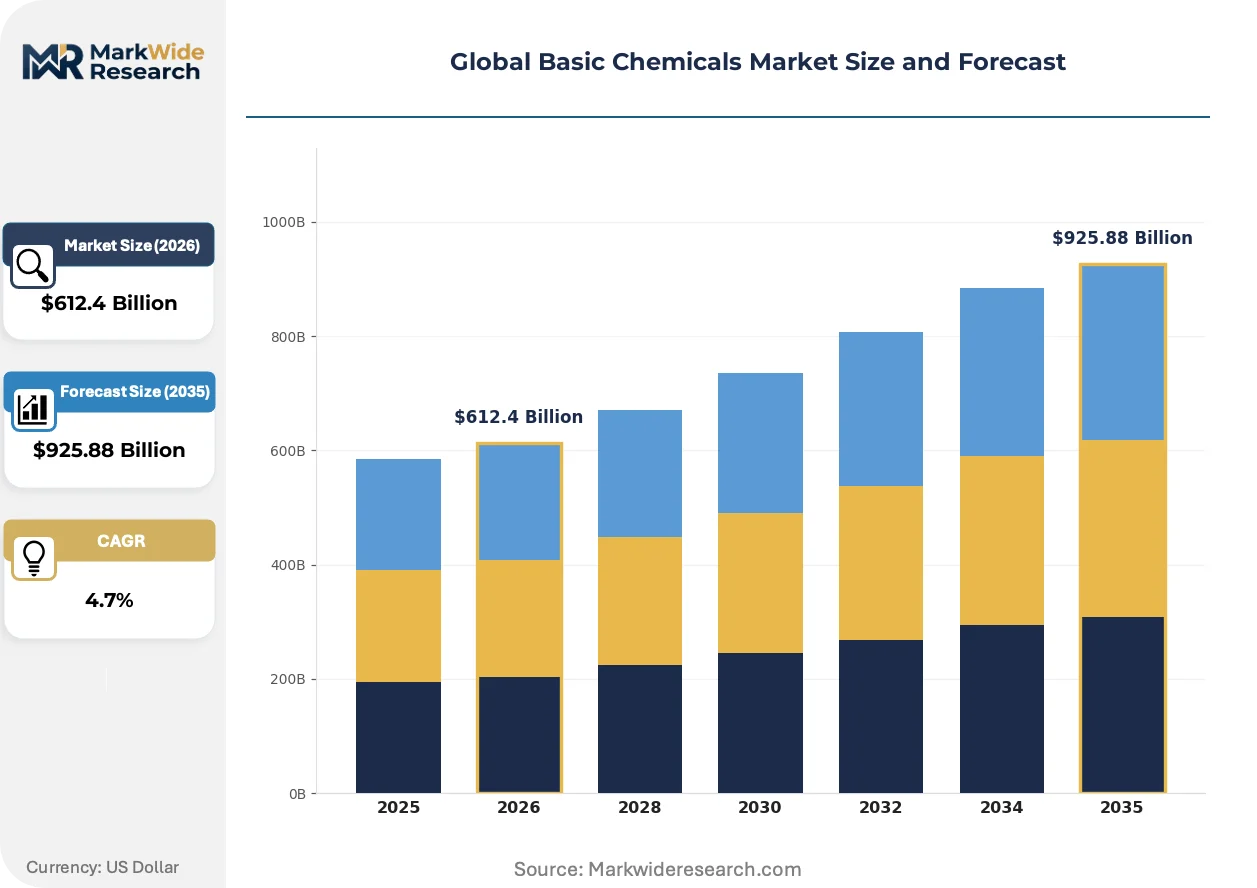
| Market Size in 2026 | $612.4 Billion |
| Market Size in 2035 | $925.88 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alkylamines, Ethylene Glycol, Propylene Glycol, Acetic Acid Application: Solvents, Synthetic Fibers, Plastics, Paints End Use Industry: Automotive, Agriculture, Pharmaceuticals, Construction Distribution Channel: Direct Sales, Wholesalers, Retailers, E-Commerce |
| Companies Covered | Dow Chemical Company, Linde, BASF, Shin-Etsu Chemical, Air Liquide, Sinopec, SABIC, INEOS, LyondellBasell Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Basic Chemicals Market Emerging Trajectories
Electrification of steam cracking and AI-driven yield optimization are compressing the capital-efficiency frontier while regulatory carbon accounting forces molecular-level traceability through supply chains.
Electrified cracking furnaces using renewable power inputs are converging with traditional fired heaters in pilot deployments at Rotterdam and Antwerp clusters. BASF and Dow pilot units target 90% Scope 1 reduction for ethylene production. This technology is converging with conventional cracking economics by 2028-2030, forcing feedstock-flexible asset strategies.
REACH authorization requirements for Substances of Very High Concern are extending compliance obligations to downstream formulators in coatings and adhesives. ECHA's 2024-2027 work program prioritizes endocrine disruptors in plasticizers and flame retardants. Polymer compounders serving automotive interiors face reformulation cycles that compress product lifecycles from five years to eighteen months.
Automotive tier-one suppliers are consolidating basic chemicals procurement through single-source framework agreements that bundle ethylene, propylene, and benzene volumes. This disintermediates traditional distributor networks in the US Midwest and Germany's Ruhr industrial belt. Volkswagen and BMW procurement offices now mandate mass-balance certification for all polymer feedstocks, shifting supplier qualification criteria from price to carbon intensity metrics.
Global Basic Chemicals Market Segmentation
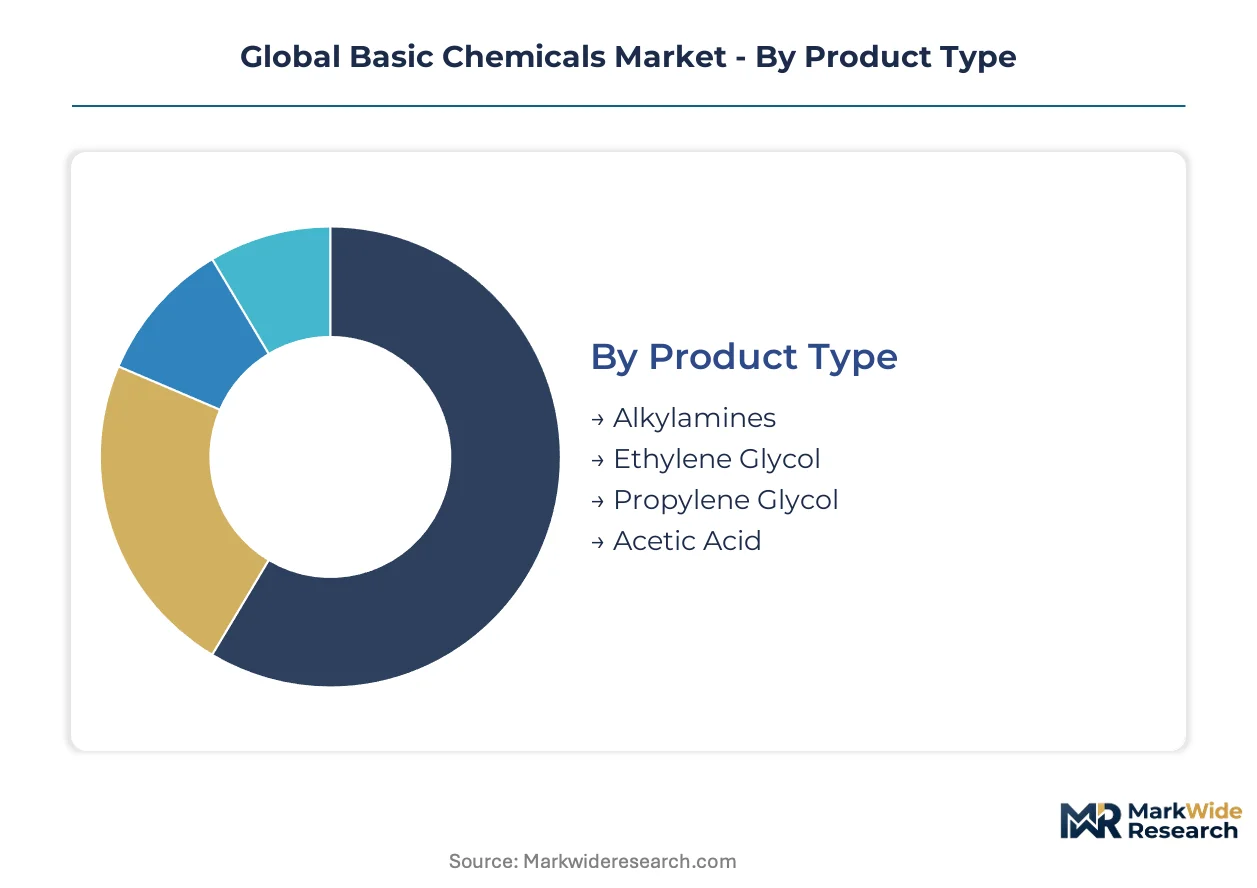
Basic chemicals segmentation reveals divergent margin architectures across certification tiers. Pharmaceutical-grade specifications command qualification timelines that commodity solvents bypass entirely. Understanding these stratified approval burdens determines viable entry points for new capacity investments.
Product Type:
Pharmaceutical-grade alkylamines and acetic acid carry FDA and EMA certification requirements that commodity ethylene glycol and propylene glycol escape entirely. Food-grade specifications add FSSAI or EFSA compliance layers that inflate working capital cycles.
- Alkylamines:Methyl, ethyl, and butylamine derivatives serve as pharmaceutical intermediates and agrochemical precursors. Demand concentrates in India and China where CDSCO and NMPA registrations gate market access for generic drug manufacturers. Multi-step synthesis routes require dedicated hydrogenation trains that cap production flexibility.
- Acetic Acid:Carboxylic acid produced via methanol carbonylation or acetaldehyde oxidation, with food-grade specifications demanding heavy metal testing below 10 ppm. European REACH registration above one tonne annual volume mandates full toxicological dossiers that commodity grades avoid. Vinyl acetate monomer offtake from construction adhesives drives volume in Germany and the United States.
- Ethylene Glycol:Polyester fiber precursor manufactured through ethylene oxide hydration, with industrial-grade purity tolerances allowing faster qualification cycles than pharmaceutical segments.
- Propylene Glycol:Humectant and solvent applications span food additives and unsaturated polyester resins, with USP certification creating price premiums over technical grades.
Leading the category by volume: Ethylene Glycol. Growing fastest: Alkylamines.
Application:
Margin structures vary sharply by end-use exposure to construction cyclicality versus packaging stability. Solvent applications face substitution pressure from bio-based alternatives while synthetic fibers track textile demand in Bangladesh and Vietnam.
- Plastics:Polymer feedstocks including polyethylene and polypropylene resins derived from ethylene and propylene cracking. Automotive lightweighting programs in Germany, Japan, and the United States concentrate procurement volumes among tier-one suppliers. Mass-balance certification requirements from Volkswagen and BMW procurement offices now filter supplier qualification.
- Solvents:Dissolution media for coatings, adhesives, and cleaning formulations, with VOC emission regulations in California and the EU F-Gas Regulation restricting permissible formulations. Water-based alternatives are displacing petrochemical solvents in architectural coatings.
- Synthetic Fibers:Polyester and nylon precursors tied to textile manufacturing clusters in China, India, and Turkey. Fast fashion inventory cycles create demand volatility that commodity chemical producers struggle to match.
- Paints:Alkyd resins and pigment dispersions exposed to construction spending cycles in China and the United States. REACH authorization for titanium dioxide additives extends compliance obligations to downstream formulators.
Highest volume concentration: Plastics. Steepest expansion trajectory: Solvents facing bio-based substitution pressure.
End Use Industry:
Customer procurement patterns diverge between consolidated automotive frameworks and fragmented construction spot markets. Pharmaceutical offtakers demand multi-year supply agreements that agriculture cannot match.
- Automotive:Interior polymers, underhood composites, and coating systems governed by OEM material specifications. Tier-one suppliers consolidate procurement through single-source framework agreements that bundle ethylene, propylene, and benzene volumes. BMW and Volkswagen mandate mass-balance certification for all polymer feedstocks.
- Pharmaceuticals:Active pharmaceutical ingredient synthesis and excipient manufacturing requiring GMP compliance and 18-24 month FDA or EMA qualification timelines. Working capital freezes in inventory builds during audit periods.
- Agriculture:Fertilizer and crop protection chemical inputs with seasonal demand spikes tied to planting windows in Brazil, India, and the United States Midwest.
- Construction:Insulation foams, adhesives, and protective coatings tracking residential and commercial building permits in China, the United States, and Germany.
Most consolidated procurement: Automotive. Most fragmented demand: Construction.
Distribution Channel:
Channel economics reflect shipment scale and customer technical service requirements. Bulk terminal deliveries favor direct relationships while specialty grades require distributor technical support.
- Direct Sales:Pipeline and railcar deliveries to integrated chemical processors and large polymer compounders. Dow Chemical leverages Gulf Coast ethylene crackers for direct supply to automotive tier-ones.
- Wholesalers:Regional inventory positioning for mid-volume offtakers lacking dedicated storage infrastructure. Rotterdam and Singapore hubs consolidate mixed-product shipments.
- Retailers:Small-package sales to maintenance-repair-operations customers and specialty formulators requiring less-than-truckload flexibility.
- E-Commerce:Digital procurement platforms for standard-grade solvents and acids, with limited penetration in pharmaceutical-certified segments requiring audit trails.
Dominant channel by volume: Direct Sales. Expanding most quickly: E-Commerce for standard grades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shale gas deposits along the US Gulf Coast anchor North American feedstock economics. Germany's Ludwigshafen cluster and China's Ningbo-Zhoushan port complex concentrate cracking capacity near import terminals.
United States
Automotive lightweighting programs in Michigan and Ohio harden polymer procurement volumes from tier-one suppliers. The EPA enforces National Emission Standards for Hazardous Air Pollutants limiting benzene fugitive emissions. Houston and Corpus Christi host integrated ethylene crackers that leverage cost-advantaged shale gas feedstocks against naphtha-dependent rivals.
Germany
REACH authorization requirements for Substances of Very High Concern extend compliance obligations to downstream formulators in coatings and adhesives. The EU Green Deal tightens emissions benchmarks for ethylene and ammonia production. The Ludwigshafen Verbund site anchors European supply through the world's largest integrated chemical complex.
China
Dual carbon goals from the Ministry of Ecology and Environment force coal-to-chemicals producers toward natural gas and biomass feedstock pivots. NMPA registrations gate pharmaceutical-grade alkylamine market access for generic drug manufacturers. The Ningbo-Zhoushan petrochemical cluster concentrates methanol carbonylation capacity near deepwater import terminals.
Saudi Arabia
Ethane feedstock availability from associated gas production sustains cost positions in polyethylene and polypropylene export markets. The national industrial development strategy prioritizes downstream chemical diversification beyond commodity exports. The Jubail industrial city hosts integrated crackers that supply polymer volumes to European and Asian converters.
India
Pharmaceutical-grade alkylamine capacity gaps create import substitution potential for domestic producers achieving CDSCO certification. FSSAI compliance layers for food-grade specifications inflate working capital cycles compared to technical grades. The Gujarat chemical cluster concentrates acetic acid and solvent production near Mundra port export infrastructure.
Global Basic Chemicals Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue certification-grade specialization and bio-based feedstock pivots. The vendor base stratifies across integrated majors with captive ethylene supply and regional distributors serving fragmented construction spot markets. Three archetypes dominate: Gulf Coast shale gas crackers, European Verbund-integrated complexes, and Asian coal-to-chemicals operators. Competitive moves center on point-source carbon capture retrofits and mass-balance certification for automotive polymer feedstocks.
Within the integrated multinational tier, Dow Chemical Company and BASF exemplify divergent geographic anchoring strategies. Dow occupies a position tied to US Gulf Coast shale economics, while BASF anchors European supply through German Verbund integration. Sinopec represents the national champion archetype, controlling domestic pipeline access that competitors cannot replicate. These three entities illustrate how feedstock security and regulatory compliance capabilities separate viable scale operators from margin-compressed regional players.
| Leading Market Players |
|---|
| Dow Chemical Company |
| Linde |
| BASF |
| Shin-Etsu Chemical |
| Air Liquide |
| Sinopec |
| SABIC |
| INEOS |
| LyondellBasell Industries |
| Others |
Supply Flow & Price Mechanics
Shale gas feedstock economics cascade from wellhead through ethylene cracker margins to polymer compounder procurement tiers, with US Gulf Coast producers commanding cost positions that naphtha-dependent European and Asian rivals cannot match without carbon border adjustment exposure.
Pricing Analysis
Certification-bundled pricing separates pharmaceutical-grade alkylamines with FDA and EMA audit trails from technical-grade solvents sold spot. Price differentiation hinges on qualification timeline burden and mass-balance carbon certification demanded by automotive OEM procurement offices. Cost compression in commodity ethylene glycol runs through Chinese coal-to-chemicals overcapacity exports. Construction sector spot buyers exhibit highest price sensitivity; pharmaceutical offtakers under multi-year supply agreements show least.
Supply Chain Analysis
CDSCO and NMPA registrations gate pharmaceutical-grade supply into India and China, filtering qualified producers from commodity exporters. Feedstock concentration centers on the United States, Saudi Arabia, and China. Ethane, naphtha, and coal gasification syngas feed cracking trains. Single-source vulnerability sits with Shengli oilfield pipeline access controlled by Sinopec. Distribution runs through direct pipeline and railcar to integrated processors, with Rotterdam and Singapore hubs serving mid-volume offtakers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH authorization timelines and dual carbon enforcement erect compliance moats that reward incumbent investment in point-source carbon capture while screening out undercapitalized entrants.
For Market Incumbents: Acquire stranded ethylene cracker assets in European port clusters before carbon border adjustment mechanisms activate. Consolidate pharmaceutical-grade certification capabilities to defend against bio-based alkylamine substitutes. Prioritize mass-balance audit infrastructure for automotive polymer feedstock qualification. For New Entrants and Emerging Players: Electrified steam cracking pilots using renewable power inputs offer technology-first entry against legacy fired-heater economics. Target India pharmaceutical-grade alkylamine capacity gaps where CDSCO registration barriers filter competition. Pursue joint development agreements with generic drug manufacturers to share qualification timeline risk. For Investors and Strategic Acquirers: Distressed-cycle entries favor European Verbund-integrated complexes with captive hydrogen infrastructure in Germany and Belgium. Long-term viability over a decade horizon rests on feedstock flexibility and regulatory compliance automation. Watch EU carbon border adjustment implementation as inflection signal for asset relocation decisions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethylene Cracking | Dow Chemical's Gulf Coast crackers lock in cost advantages against naphtha-dependent import rivals. |
| Green Manufacturing Transition | BASF and Linde pilot electrified furnaces targeting Scope 1 reduction for EU Green Deal alignment. |
| Long-term Supply Agreement | Automotive tier-one bundles of ethylene, propylene, and benzene volumes disintermediate distributor networks. |
| Joint Venture | Sinopec's pipeline access to Shengli feedstocks creates non-replicable domestic supply chain control. |
| Capacity Expansion | SABIC's Jubail complex leverages associated gas ethane for export-competitive polyethylene volumes. |
Methodological Framework
Document review covered customs trade data, SEC 10-K filings, and ACC/Cefic industry reports, complemented by interviews with plant managers at integrated crackers, procurement leads at automotive tier-one suppliers, distribution channel partners in Rotterdam and Singapore, and technical R&D directors overseeing electrified furnace pilots. Bottom-up capacity modeling and top-down demand triangulation validated volume estimates across the analysis window.
Segment-level outputs reflect grade tier, end-use industry exposure, and regional production hub configurations throughout the projection horizon. CAGRs derive from ethylene cracking margin trajectories, automotive lightweighting procurement volumes, and pharmaceutical-grade qualification pipeline flows. Shale gas price bands and carbon border adjustment mechanism assumptions feed sensitivity testing.
Several conditions sit outside the modeled scope, including abrupt LNG supply disruptions, unilateral REACH authorization withdrawals, and breakthrough biomass gasification cost parity. Forecasts assume documented feedstock switching economics and regulatory enforcement calendars. A model refresh is warranted upon material change in EU carbon border adjustment implementation timing or Chinese dual carbon intensity target acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Hydrochloric Acid Market
Bulk Chemicals
Zinc Acetate Market
Bulk Chemicals
Global Lithium Fluoride Market
Bulk Chemicals
Brazil Magnesium Phosphate Market
Bulk Chemicals
Asia-Pacific Formic Acid Market
Bulk Chemicals
North America Sodium Chloride Market
Bulk Chemicals
Europe Caustic Potash Market
Bulk Chemicals
Bulk Liquid Containers Market
Bulk Chemicals
India Lime Market
Bulk Chemicals
Sodium Permanganate Market
Bulk Chemicals
Nitric Acid Market
Bulk Chemicals
Global Butyl Acrylate Market
Bulk Chemicals
Lignin Waste Market
Bulk Chemicals
Putty Powder Market
Bulk Chemicals
Malathion Market
Bulk Chemicals
Global Purified Terephthalic Acid (PTA) Market