
 Trona Market | 2026-2036
Trona Market Size, Share, and Industry Trends Forecast 2026-2036
Trona Market Intelligence
The gap between premium processed trona and commodity natural ore is broadening as end-users demand lower impurity levels for specialty glass and lithium carbonate precursor applications. Genesis Alkali leverages its integrated Wyoming mining and refining complex to sustain cost leadership in dense soda ash. Ciner Resources Corporation anchors North American supply through its Green River basin operations, while Solvay competes in European markets with synthetic process alternatives.
Trona is a naturally occurring sodium sesquicarbonate mineral (Na2CO3·NaHCO3·2H2O) mined primarily from evaporite deposits and calcined to produce soda ash, with Green River Basin ore grades typically exceeding 90% mineral purity. Glass manufacturing consumes the majority of processed output, where trona-derived soda ash lowers silica melting temperatures by 300°C compared to raw batch processing. Powder form dominates industrial procurement due to faster dissolution kinetics in chemical reactors, while flake and crystal grades command premium positioning in water treatment and specialized chemical synthesis where controlled release matters.
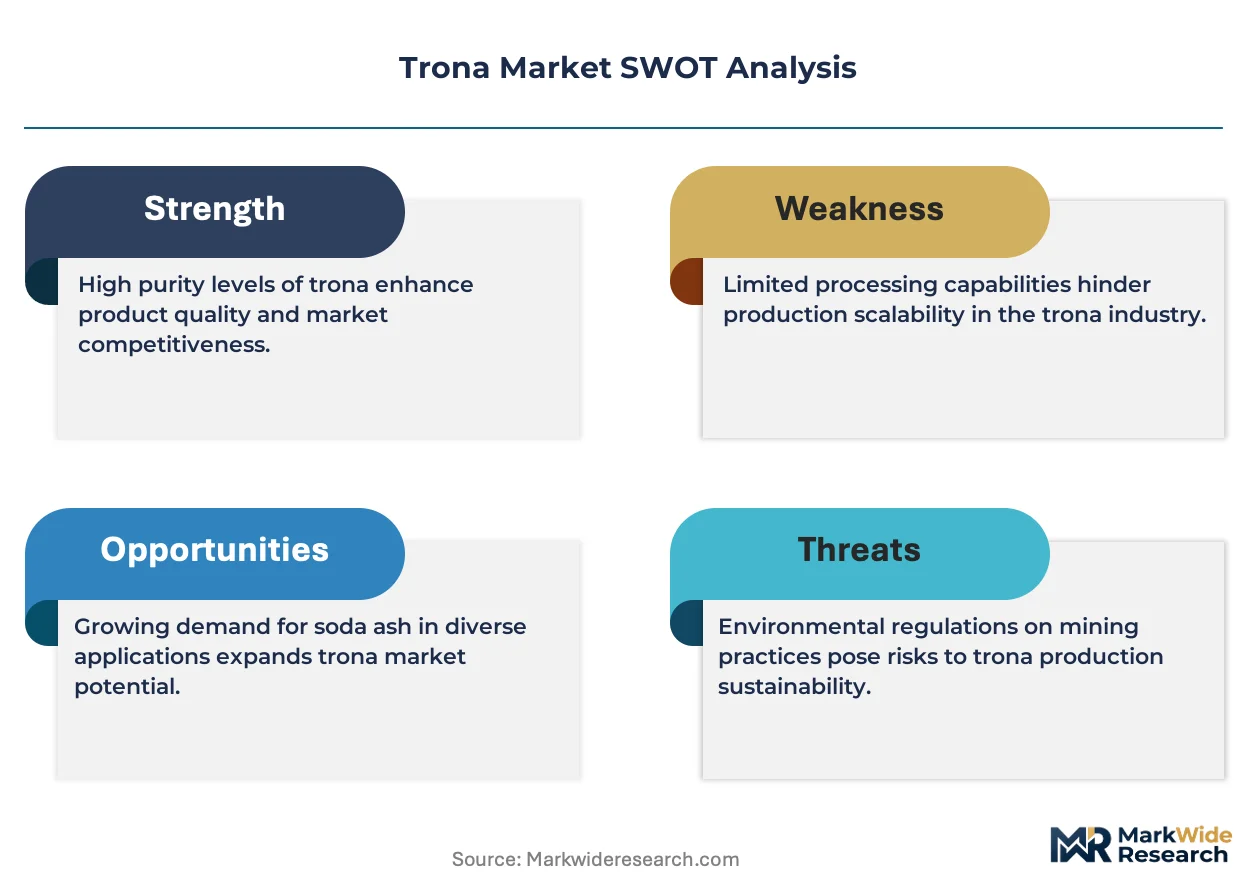
The US EPA and Wyoming Department of Environmental Quality regulate surface mining permits and groundwater protection standards that directly shape extraction economics and reserve access timelines. OSHA dust exposure limits and REACH compliance requirements in Europe constrain processing facility design and worker safety investments for exporters. Stakeholders must monitor how evolving carbon border mechanisms and state-level renewable energy mandates reshape the cost calculus between natural trona and synthetic soda ash routes.
Market Dynamics
US EPA and Wyoming Department of Environmental Quality permit tightening is forcing trona operators toward cleaner calcination technologies and reserve-access negotiations, fundamentally restructuring extraction economics across the Green River Basin.
Growth Catalysts
- Flat-glass capacity expansion:Chinese and Indian glass manufacturers are scaling soda ash procurement from trona feedstock as architectural and automotive glass output rises.
- REACH compliance in Europe:The EU's chemical registration framework is favoring naturally-derived soda ash over synthetic alternatives in detergent and chemical processing applications.
- Solvent extraction efficiency:Advanced trona refining methods are lowering energy intensity in lithium carbonate precursor production for battery supply chains.
Market Restraints
- Natural gas price volatility:Calcination operations in Wyoming face input cost swings that compress margin structures for dense soda ash production.
- Green River Basin supply concentration:Over 90% of US trona reserves sit in a single geological formation, creating geographic vulnerability to localized regulatory or environmental disruptions.
- Synthetic soda ash substitution:Solvay-process alternatives from European and Asian chemical complexes compete on price during energy market dislocations.
Strategic Opportunities
- India detergent sector expansion:Domestic formulators are substituting imported synthetic ash with trona-derived dense grades as local glass and chemical industries scale.
- Carbon border adjustment mechanisms:The EU's CBAM framework creates tariff advantages for low-carbon-intensity natural trona versus coal-fired synthetic production routes.
- Digital mining integration:Real-time ore-grade sensors and autonomous haulage are converging to optimize extraction sequencing and waste reduction.
Industry Challenges
- Process engineer scarcity:Specialized expertise in sesquicarbonate calcination and impurity control is concentrated among retiring workforces in Wyoming and Turkey.
- Legacy equipment retrofit timelines:Existing rotary kiln installations require extended shutdown windows to accommodate emissions-control upgrades demanded by state regulators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Trona Market |
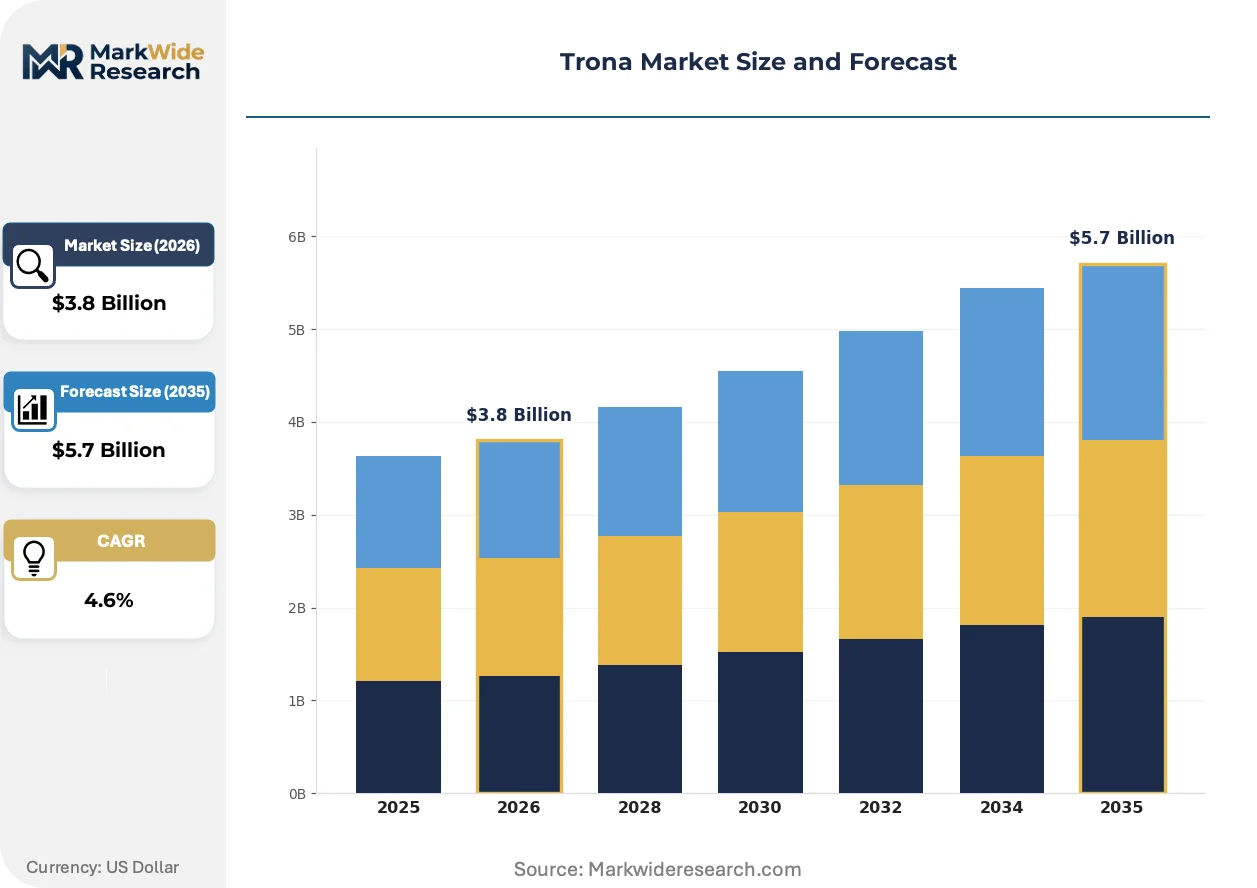
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Trona, Processed Trona, Trona Ash, Trona Soda End Use: Glass Manufacturing, Chemical Production, Water Treatment, Pulp & Paper Form: Powder, Granule, Flake, Crystals Distribution Channel: Direct Sales, Distributors, Online Retail, Others |
| Companies Covered | FMC Corporation, WE Soda Ltd., OCI Company Ltd., ANSAC, Tata Chemicals Ltd., Genesis Alkali, Ciner Resources Corporation, Solvay, Searles Valley Minerals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Trona Market Strategic Shifts & Innovations
Processing technology and regulatory compliance frameworks are actively restructuring competitive advantage in trona-derived chemicals, with cleaner production methods and demand-side specification tightening as dominant themes.
Advanced solution mining with selective dissolution is overtaking traditional room-and-pillar extraction in Wyoming operations. Specialty glass manufacturers in South Korea and Japan are adopting ultra-low-iron dense soda ash specifications at accelerated procurement cycles. This technology is overtaking conventional mechanical mining by enabling higher-purity output without surface disturbance, compressing the cost gap between premium and standard grades.
REACH authorization requirements for synthetic soda ash byproducts are tightening discharge standards across EU chemical manufacturing. The European Chemicals Agency is extending registration obligations to cover calcination emissions and waste brine management. Dense soda ash imports from Turkish and Kenyan natural deposits are capturing share as European buyers seek pre-registered supply chain pathways.
Direct procurement contracts between trona miners and lithium carbonate refiners are displacing merchant chemical distribution in battery supply chains. Chinese cathode material producers are negotiating multi-year offtake agreements with Wyoming operators to secure low-magnesium precursor inputs. This pattern is most visible in Jiangsu and Sichuan provinces where integrated battery chemical parks are consolidating feedstock sourcing.
Trona Market Segmentation
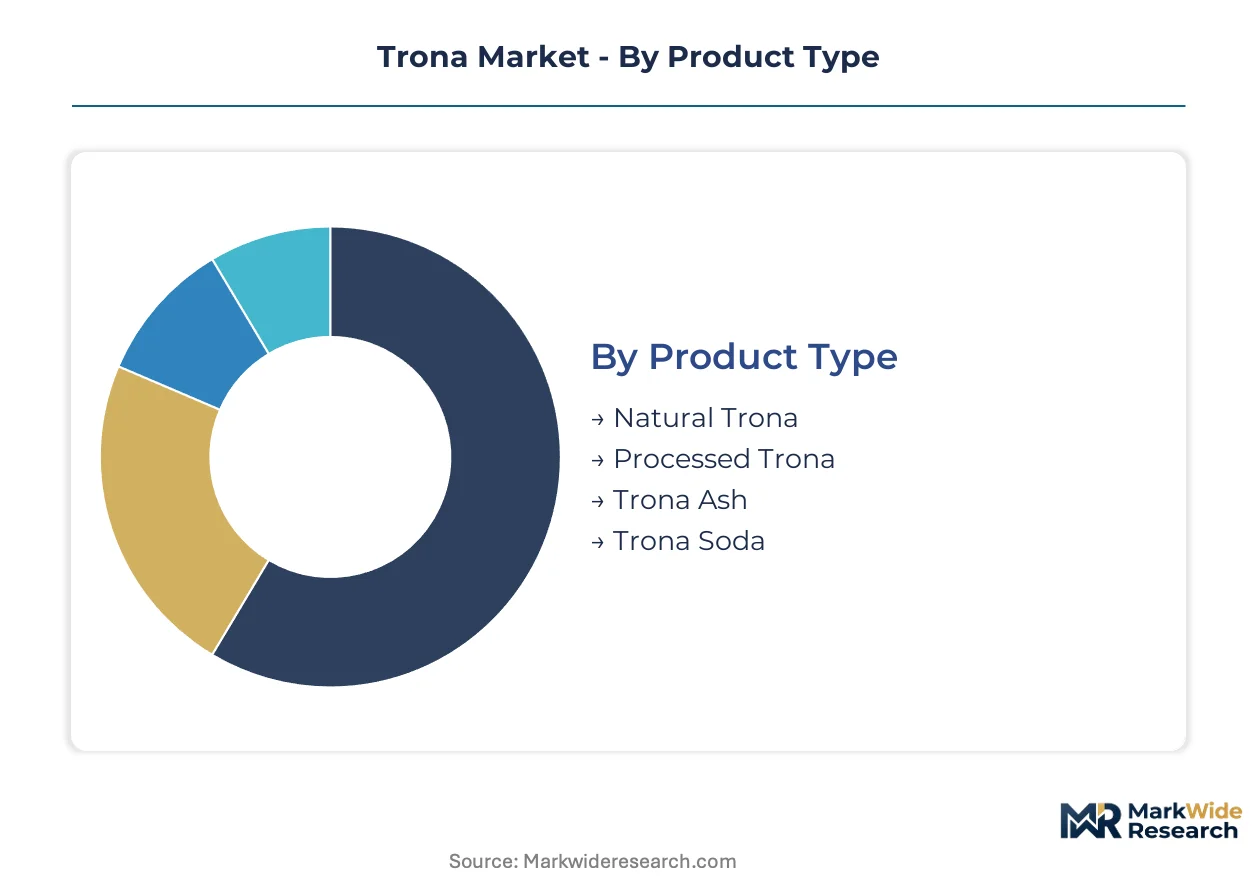
Trona procurement patterns diverge sharply across product purity tiers and end-use specifications. Glass manufacturers impose strict impurity ceilings while chemical processors optimize for dissolution kinetics. Form selection and channel strategy further fragment the supply landscape.
Product Type:
Standardization dominates commodity grades while premium segments demand bespoke calcination protocols and impurity profiling.
- Natural Trona:Raw sesquicarbonate ore mined from evaporite deposits, typically exceeding 90% mineral purity in Green River Basin deposits. Chinese flat-glass manufacturers are expanding procurement of high-grade natural feedstock as domestic architectural glass capacity scales, though Wyoming EPA permit tightening constrains extraction expansion timelines.
- Processed Trona:Calcined and refined material meeting dense soda ash specifications for industrial chemical synthesis. Specialty glassmakers in South Korea and Japan are adopting ultra-low-iron processed grades for optical and display glass applications, compressing procurement cycles and tightening quality tolerances.
- Trona Ash:Direct calcination product serving regional detergent and pulp bleaching markets.
- Trona Soda:Refined sodium carbonate derivative for chemical reagent and food-grade applications.
Most installed capacity flows through Processed Trona. Expansion is steepest in Natural Trona as Asian glassmakers integrate Wyoming feedstock into supply chains.
End Use:
Volume concentration sits with mature industrial consumers while emerging battery chemical applications reshape margin structures.
- Glass Manufacturing:Primary consumption segment where trona-derived soda ash reduces silica melting temperatures by approximately 300°C versus raw batch processing. Chinese and Indian architectural and automotive glass producers are scaling trona procurement as flat-glass capacity expands across Jiangsu, Gujarat, and Maharashtra industrial corridors.
- Chemical Production:Lithium carbonate precursor synthesis and detergent intermediate manufacturing. Chinese cathode material producers in Sichuan and Jiangsu provinces are negotiating direct offtake agreements with Wyoming miners for low-magnesium trona inputs, displacing merchant chemical distribution in battery supply chains.
- Water Treatment:pH adjustment and softening applications in municipal and industrial systems.
- Pulp & Paper:Bleaching and chemical recovery processes in integrated mill operations.
Glass Manufacturing commands the dominant capacity share. Chemical Production is climbing the fastest as battery material integration accelerates.
Form:
Dissolution speed requirements separate industrial bulk buyers from specialty chemical processors.
- Powder:Fine-ground material with accelerated dissolution kinetics dominating chemical reactor feedstock procurement. Glass batching operations across Asia-Pacific prefer powder form for homogeneous silica fusion, though dust control investments add processing facility capital requirements.
- Flake:Thin crystalline layers with controlled surface area for water treatment and gradual-release applications. European municipal water utilities are specifying flake grades for automated dosing systems, creating procurement premiums over bulk powder alternatives.
- Granule:Intermediate particle size for general industrial applications with moderate dissolution requirements.
- Crystals:Large-format crystalline structure for laboratory reagent and specialty synthesis where purity certification matters.
Powder moves the largest volume tonnage. Flake is gaining share fastest as water treatment automation spreads.
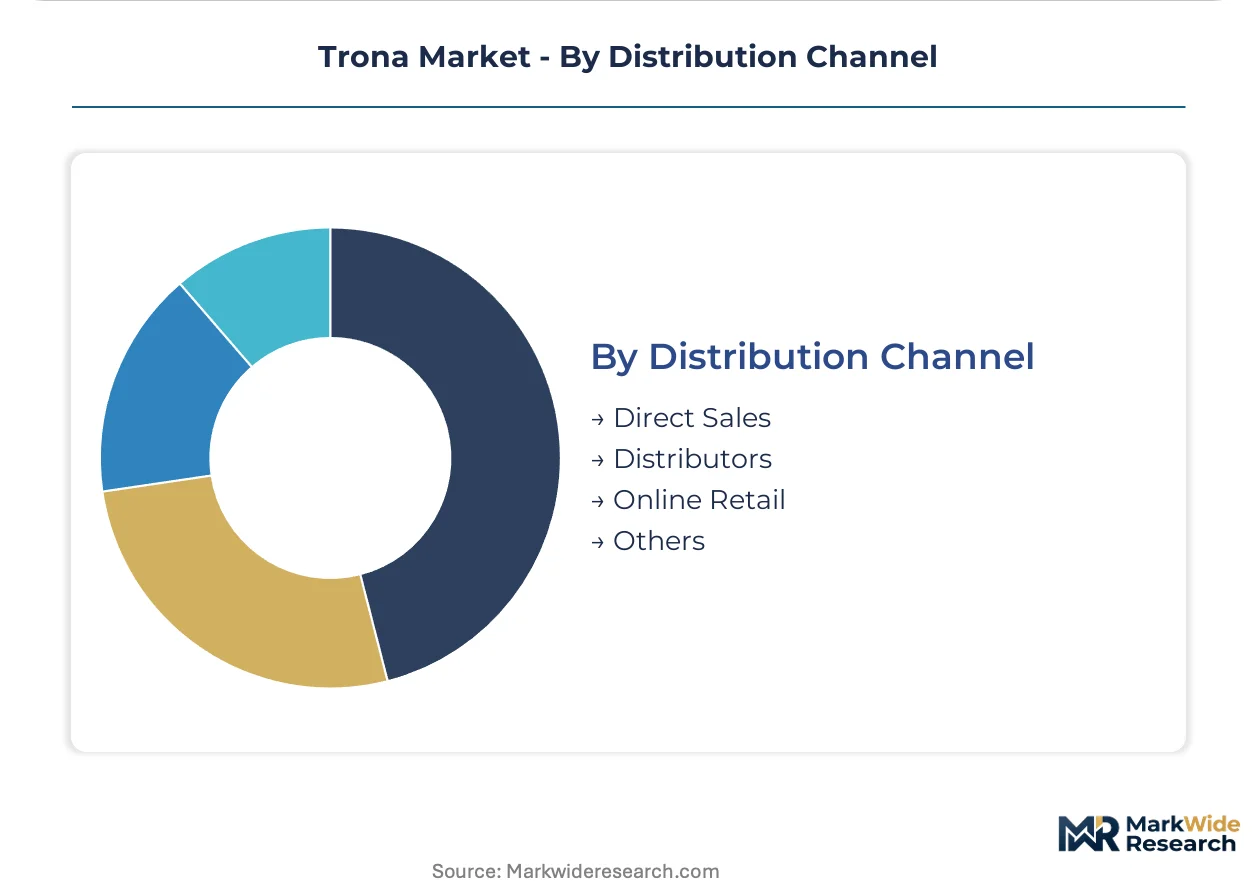
Distribution Channel:
Contract structure varies with buyer scale and specification complexity.
- Direct Sales:Long-term offtake agreements between miners and large-volume consumers. Chinese lithium carbonate refiners are consolidating procurement through direct Wyoming contracts, bypassing merchant intermediaries to secure low-magnesium specification guarantees.
- Distributors:Regional stockholding intermediaries serving mid-scale chemical and detergent formulators. Indian domestic formulators rely on distributor networks for trona-derived dense soda ash as local glass and chemical industries scale beyond import-direct volumes.
- Online Retail:Digital platforms for small-lot reagent and laboratory-grade procurement.
- Others:Cooperative purchasing arrangements and integrated supply chain partnerships.
Direct Sales handles the majority of tonnage. Distributors are expanding most quickly as regional chemical clusters mature outside traditional consumption centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized mining engineers and sesquicarbonate process chemists cluster around the Green River Basin in Wyoming, anchoring North American trona expertise. Turkish geologists and plant operators dominate European supply chains through Beypazari deposits. Chinese process engineers concentrate in Jiangsu and Sichuan provinces, driving Asia-Pacific capacity expansion.
United States
Flat-glass manufacturers in Ohio and Indiana source dense soda ash from Wyoming trona calcination. The EPA and Wyoming Department of Environmental Quality tightened groundwater protection standards and surface mining permits in 2023. Green River Basin operations face extended retrofit timelines for rotary kiln emissions controls.
China
Architectural glass producers in Jiangsu province and lithium carbonate refiners in Sichuan province scale trona-derived feedstock procurement. The Ministry of Ecology and Environment enforces dual carbon goals that favor lower-emission natural soda ash over coal-fired synthetic routes. Xuzhou and Yibin industrial clusters consolidate direct offtake agreements with Wyoming miners.
Turkey
Detergent formulators and regional glassmakers across Southeast Europe source Beypazari basin trona. ECHA REACH authorization requirements for synthetic soda ash byproducts create regulatory preference for naturally-derived alternatives. Ankara province mining operations expand solution extraction capacity to serve EU pre-registered supply chain pathways.
India
Domestic glass manufacturers in Gujarat and Maharashtra substitute imported synthetic ash with trona-derived dense grades. The Bureau of Indian Standards certifies soda ash purity grades for detergent and chemical applications. Mundra and Hazira port clusters handle rising import volumes from Wyoming and Turkish origins.
Germany
Specialty chemical processors and water treatment operators procure ultra-low-iron dense soda ash for automated dosing systems. The EU Carbon Border Adjustment Mechanism creates tariff advantages for low-carbon-intensity natural trona imports. North Rhine-Westphalia chemical parks evaluate Wyoming direct contracts against Solvay-process alternatives.
Trona Market Key Industry Players
Top-tier vendors anchor integrated mining-refining complexes, while mid-scale operators concentrate on regional distribution and specialty grade customization. The structure consolidates around reserve access and calcination scale rather than technology differentiation. Three archetypes dominate: Wyoming-based integrated miners with captive reserves, European synthetic process specialists, and Turkish natural deposit operators serving regional markets. Capacity expansion and direct offtake contracting with battery chemical producers represent the dominant competitive moves reshaping procurement relationships.
Within the integrated mining tier, Genesis Alkali and Ciner Resources Corporation occupy positions exemplifying Green River Basin concentration and vertical control over dense soda ash output. Solvay represents the synthetic process archetype competing through European manufacturing proximity and REACH-registered supply chains. These three entities anchor the competitive structure without exhaustively mapping the vendor landscape.
| Leading Market Players |
|---|
| FMC Corporation |
| WE Soda Ltd. |
| OCI Company Ltd. |
| ANSAC |
| Tata Chemicals Ltd. |
| Genesis Alkali |
| Ciner Resources Corporation |
| Solvay |
| Searles Valley Minerals |
| Others |
Cost & Logistics Intelligence
Advanced solution mining with selective dissolution is compressing production cost spreads between premium and standard trona grades while simultaneously concentrating supply leverage among Wyoming operators with proven reserve access. This technology shift tightens the cost gap between dense soda ash specifications and natural ore outputs, reshaping how glass manufacturers and battery chemical producers negotiate long-term offtake terms.
Pricing Analysis
Contract-based long-term offtake dominates trona procurement, with pricing stratifying across premium ultra-low-iron grades, standard dense soda ash, and unprocessed natural ore. Price differentiation hinges on impurity certification thresholds and volume scale commitments, with Chinese lithium carbonate refiners showing least price sensitivity due to specification rigidity for battery precursor synthesis. Cost compression in commodity natural ore is intensifying because Turkish and Kenyan deposit operators are expanding solution extraction capacity, pressuring Wyoming spot pricing for standard-grade material.
Supply Chain Analysis
Single-source vulnerability sits with Wyoming's Green River Basin, where over 90 percent of US trona reserves concentrate extraction economics and reserve access timelines. Supply draws from Wyoming, Turkey, and Kenya, with raw material dependencies anchoring in natural gas for calcination energy, mining equipment fleets, and specialized sesquicarbonate process chemicals. Tariff exposure runs through the EU Carbon Border Adjustment Mechanism, which advantages low-carbon-intensity Wyoming trona over coal-fired synthetic alternatives. Distribution runs through direct sales contracts for large-volume glass and battery chemical consumers, with regional distributors serving mid-scale detergent and water treatment formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Trona procurement functions as a geographic-arbitrage play between Wyoming's low-carbon extraction economics and European regulatory preference for naturally-derived soda ash under REACH and CBAM frameworks. The cost differential between US natural gas-fired calcination and European coal-based synthetic production creates sustained margin capture opportunities for reserve-anchored operators.
For Market Incumbents: Acquire solution mining technology licenses and proven reserve blocks in the Green River Basin to preempt Turkish and Kenyan capacity expansion. Defensive consolidation should prioritize captive control over low-magnesium ore zones critical for lithium carbonate precursor supply, as Chinese cathode material producers are displacing merchant chemical distribution with direct Wyoming contracts. Process engineer scarcity in sesquicarbonate calcination represents the priority capability gap to close through targeted technical recruitment. For New Entrants and Emerging Players: Capture Indian detergent sector expansion as domestic formulators substitute imported synthetic ash with trona-derived dense grades, with Gujarat and Maharashtra industrial corridors offering the most penetrable geographic entry point. Specialty water treatment flake grades for European municipal automation systems present a second white-space target with premium pricing tolerance. A go-to-market angle anchored in REACH-registered supply chain pathways and ultra-low-iron certification bypasses incumbent volume advantages. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale Turkish operators with Beypazari basin reserves and pre-registered EU supply chain access, relative to fully integrated Wyoming majors. Long-term viability across the projection horizon hinges on carbon intensity differentials persisting under border adjustment mechanisms, with natural trona maintaining cost advantage over synthetic routes. The signal to watch is Chinese Ministry of Ecology and Environment enforcement of dual carbon goals accelerating substitution away from coal-fired domestic soda ash production.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Solution Mining Technology | Wyoming operators deploying selective dissolution reduce surface disturbance costs and improve ore grade recovery versus mechanical extraction. |
| Long-term Supply Agreement with Battery Chemical Producers | Direct offtake contracts with Jiangsu and Sichuan lithium carbonate refiners displace merchant distribution and lock in low-magnesium specification premiums. |
| Green Manufacturing Transition in Calcination Operations | Rotary kiln emissions retrofits satisfy Wyoming Department of Environmental Quality permit tightening and preserve reserve access timelines. |
| Joint Venture with Turkish Reserve Operators | Beypazari basin partnerships extend EU pre-registered supply chain pathways and diversify geographic concentration risk from Green River Basin. |
| Capacity Expansion in Ultra-Low-Iron Dense Soda Ash | South Korean and Japanese specialty glassmakers are compressing procurement cycles for optical and display glass applications. |
Research Approach
Direct dialogue with trona mine operations managers, dense soda ash procurement leads at flat-glass manufacturers, lithium carbonate refinery technical directors, and Wyoming state regulator officials grounded qualitative assessment in operational reality. Secondary validation drew from USGS mineral commodity summaries, Wyoming Department of Environmental Quality permit filings, Turkish Mining Ministry production statistics, and Chinese customs trade data for soda ash imports. Bottom-up and top-down triangulation cross-checked reserve estimates against end-use consumption patterns across glass, chemical, and battery supply chain applications.
Bottom-up modeling built from individual mine production capacities, ore grade profiles, and calcination yield assumptions, while top-down analysis anchored in end-use industry consumption benchmarks for glass manufacturing and lithium carbonate precursor synthesis. Segmentation dimensions included product purity tier, end-use application, form specification, and regional production hub. CAGRs were derived from demand elasticity modeling against flat-glass capacity expansion trajectories and battery cathode material production scaling across the analysis window.
EPA permit timeline delays, natural gas price volatility spikes, and synthetic soda ash process cost breakthroughs are the dominant revision risks that could compress or extend natural trona demand growth. Forecasts reflect assumptions about carbon border mechanism enforcement intensity and Chinese domestic synthetic capacity rationalization under environmental compliance pressure. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Hydrochloric Acid Electrolysis Market
Bulk Chemicals
Sodium Hydrosulfide Market
Bulk Chemicals
Bulk Chemical Packaging Market
Bulk Chemicals
Mercaptan Market
Bulk Chemicals
Glucaric Acid Market
Bulk Chemicals
Global Ethylene Market
Bulk Chemicals
Oman Sodium Hydroxide Market
Bulk Chemicals
Tributyl Citrate Market
Bulk Chemicals
Carbon Black Market
Bulk Chemicals
Potassium Hydrogen Sulfite Market
Bulk Chemicals
North America Lime Market
Bulk Chemicals
Global Ground and Precipitated Calcium Carbonate Market
Bulk Chemicals
Magnesium Acetate Market
Bulk Chemicals
Sheet Molding and Bulk Molding Compounds Market
Bulk Chemicals
North America Caustic Potash Market
Bulk Chemicals
Potassium Sulphate Market