
 Rocket Propellant Chemicals Market | 2026-2036
Rocket Propellant Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Rocket Propellant Chemicals Market Analytics
A shift from single-source government contracts to multi-source commercial procurement is pivoting how prime contractors secure ammonium perchlorate and hydrazine derivatives. Northrop Grumman leverages long-standing relationships with defense agencies to sustain solid propellant orders. SpaceX anchors commercial demand through vertical integration of Merlin engine production. Lockheed Martin competes on large-diameter solid rocket motor contracts for strategic missile programs.
Rocket propellant chemicals comprise energetic formulations—oxidizers such as ammonium perchlorate, fuels including hydrazine and RP-1, and additives that control burn rates and storage stability—manufactured through batch crystallization, blending, and casting processes to produce thrust for launch vehicles and missiles. Solid propellants dominate defense applications due to simplicity and storability, while liquid propellants lead commercial launch activity where throttle control and reusability matter. Additives command premium margins as specialized burn-rate modifiers and stabilizers become critical for precision-guided systems and extended mission profiles.
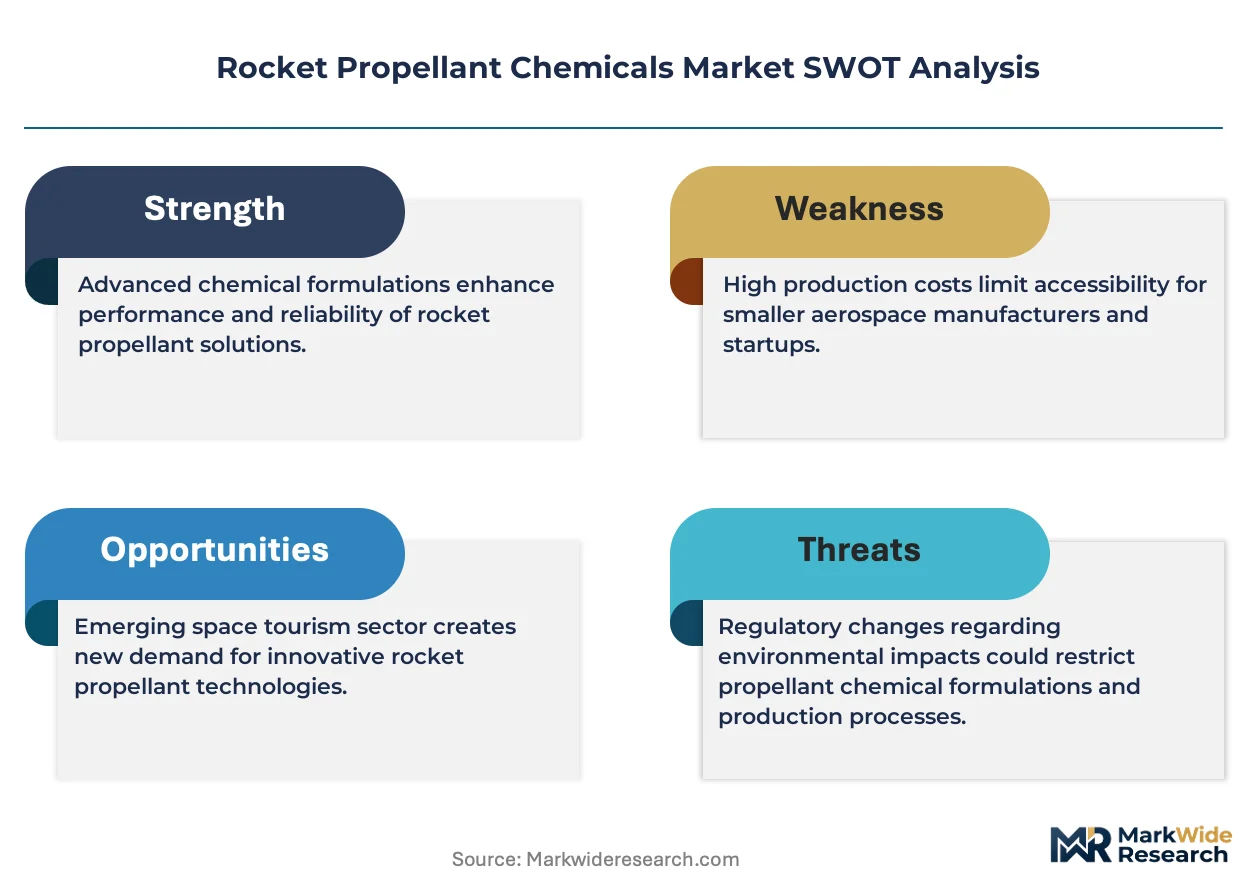
FAA launch licensing requirements and EPA National Emission Standards for Hazardous Air Pollutants constrain domestic manufacturing capacity and shape facility siting decisions. REACH registration obligations in Europe limit hydrazine derivative imports, redirecting supply chain investments toward compliant production nodes. Stakeholders must monitor how dual-use export control revisions affect cross-border transfers of ammonium perchlorate and related precursor chemicals.
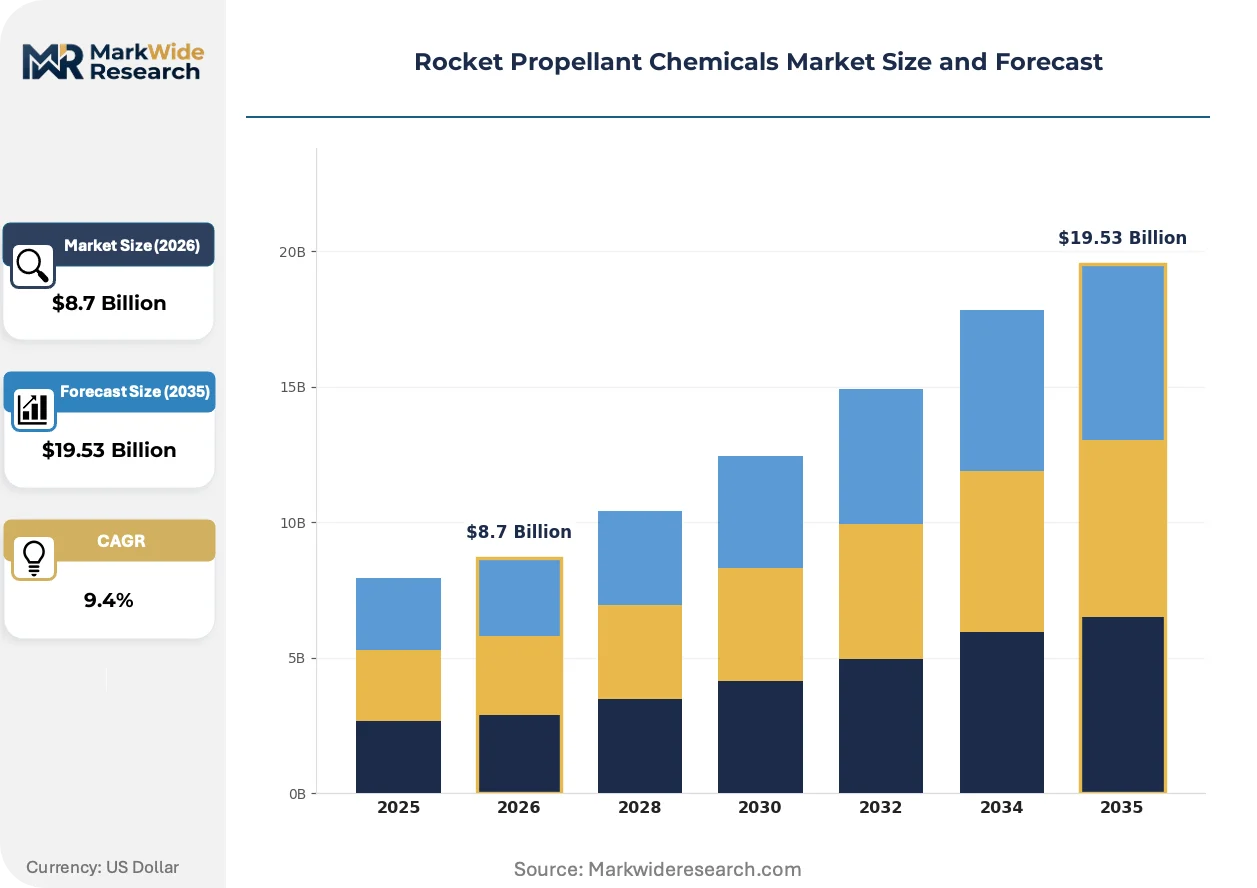
Market Dynamics
Defense procurement consolidation and commercial launch cadence acceleration are compressing supplier lead times while EPA hazardous air pollutant enforcement tightens manufacturing siting constraints for ammonium perchlorate producers.
Growth Catalysts
- NASA Artemis program:Sustained government contracts for lunar mission architectures are pulling forward demand for high-performance solid propellant formulations and storable liquid oxidizers.
- REACH registration obligations:European chemical compliance requirements are redirecting hydrazine derivative investments toward domestic production nodes with certified handling infrastructure.
- Throttleable liquid systems:Reusable engine architectures favor precision-controlled burn profiles that solid propellants cannot deliver, expanding addressable demand for cryogenic and hypergolic formulations.
Market Restraints
- Ammonium perchlorate supply concentration:Domestic production clusters in the western United States face EPA National Emission Standards enforcement that constrains capacity expansion timelines.
- Hydrazine toxicity handling costs:Specialized containment infrastructure and worker protection protocols inflate operational expenditures above commodity chemical benchmarks.
- Solid propellant inflexibility:Fixed burn profiles limit mission adaptability for responsive space and precision-strike applications where throttle control delivers tactical advantage.
Strategic Opportunities
- Green propellant transition:AF-M315E and LMP-103S alternatives to hydrazine unlock reduced handling costs and streamlined launch licensing through FAA streamlined safety approvals.
- India launch market emergence:ISRO commercial arm NSIL is expanding procurement of storable propellants for PSLV and GSLV missions, creating new supply chain entry points.
- Additive manufacturing integration:3D-printed fuel grain geometries enable rapid prototyping of custom burn-rate profiles for tactical missile programs.
Industry Challenges
- Propellant chemist talent pipeline:University programs in energetic materials synthesis have contracted, narrowing the specialist labor pool for formulation development.
- Casting facility qualification timelines:New solid rocket motor production lines require 18-24 month FAA and DOD certification cycles before operational clearance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rocket Propellant Chemicals Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Propellants, Solid Propellants, Hybrid Propellants, Composite Propellants Application: Aerospace, Defense, Space Exploration, Satellite Launch Component: Oxidizers, Fuels, Additives, Stabilizers Industry Vertical: Aerospace OEMs, Government Agencies, Research Institutions, Private Enterprises |
| Companies Covered | L3Harris Technologies, Northrop Grumman, SpaceX, Aerojet Rocketdyne, Lockheed Martin, Boeing, Safran, Mitsubishi Heavy Industries, China Aerospace Science and Technology Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rocket Propellant Chemicals Market Evolving Landscape
Propulsion architecture choices are bifurcating between reusable liquid systems for commercial launch and advanced solid formulations for responsive defense missions, with regulatory chemistry constraints shaping both pathways.
Metal-hydride fuel additives are integrating into aluminized solid propellant formulations to enhance specific impulse without sacrificing storage stability. Tactical missile primes are qualifying these modified grains for extended-range precision strike. The structural consequence is that traditional ammonium perchlorate-aluminum baseline formulations are facing performance ceilings in next-generation competitive bids.
EPA National Emission Standards for Hazardous Air Pollutants are tightening volatile organic compound thresholds at perchlorate manufacturing facilities. This regulatory pressure is forcing capital deployment toward closed-loop crystallization and solvent recovery systems. Western United States production sites are responding with facility consolidation rather than greenfield expansion to amortize compliance costs across existing throughput.
Launch service procurement is consolidating around multi-mission block buy contracts that bundle propellant supply with vehicle integration. Satellite constellation operators are displacing single-launch spot purchasing with five-year propellant supply agreements tied to ride-share manifests. This pattern is most visible in United States commercial spaceports where SpaceX and United Launch Alliance compete for National Security Space Launch program awards.
Rocket Propellant Chemicals Market Segmentation
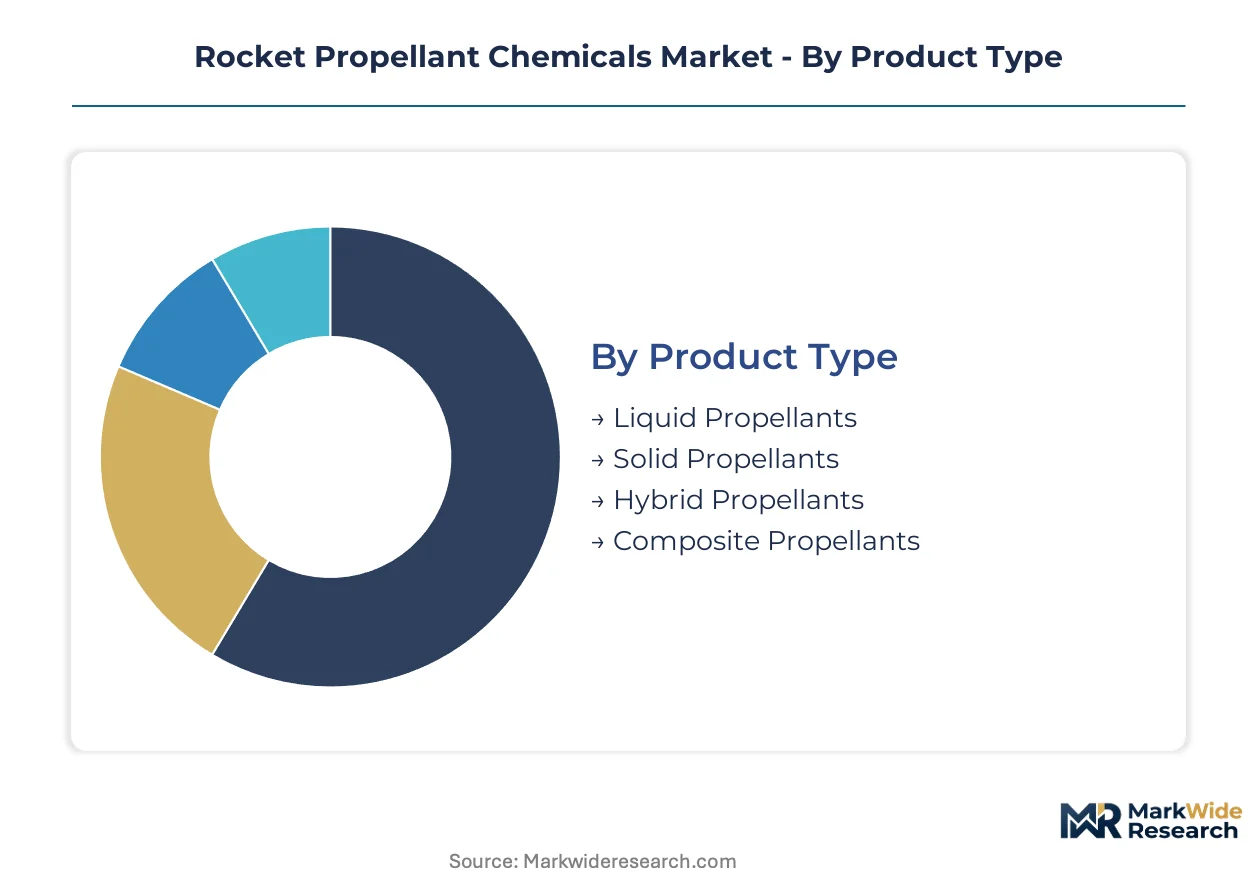
Propellant chemistry segmentation reveals how formulation choices lock in supply chain dependencies and regulatory exposure. Buyers optimize across thrust requirements, storage constraints, and handling infrastructure investments.
Product Type:
Defense primes prioritize storability and launch readiness; commercial operators trade simplicity for throttle control and reusability.
- Liquid Propellants:Cryogenic and storable formulations including RP-1, liquid oxygen, and hypergolic combinations enable precise thrust modulation. SpaceX Merlin engine production in the United States anchors demand for RP-1 and liquid oxygen combinations, with reusable architectures requiring refined purity specifications that constrain supplier qualification.
- Solid Propellants:Ammonium perchlorate composite formulations deliver immediate launch readiness without cryogenic infrastructure. Northrop Grumman strategic missile programs in the United States sustain procurement of large-diameter solid rocket motors where fixed burn profiles match mission requirements.
- Hybrid Propellants:Combines solid fuel grains with liquid or gaseous oxidizers for throttle capability without full cryogenic complexity.
- Composite Propellants:Advanced formulations incorporating metal hydrides and nanoscale additives for specific impulse enhancement.
Volume sits with solid propellants for defense backlog; growth tilts toward liquid propellants for commercial reusability.
Application:
Mission profiles determine whether storability or precision control dominates procurement criteria.
- Aerospace:Crewed vehicle programs require human-rated propellant handling protocols and redundant supply chains. NASA Artemis lunar architecture contracts in the United States specify storable hypergolic formulations for in-space propulsion modules.
- Defense:Responsive launch and precision strike missions demand instant readiness without cryogenic conditioning. Tactical missile programs across multiple defense agencies prioritize solid propellant reliability for extended-range engagements.
- Space Exploration:Interplanetary missions favor high-energy cryogenic combinations for maximum delta-V efficiency.
- Satellite Launch:Constellation deployment economics favor reusable liquid systems with rapid turnaround cycles.
Defense applications concentrate procurement volume; satellite launch climbs fastest on constellation deployment schedules.
Component:
Specialized chemical handling infrastructure separates commodity suppliers from qualified propellant providers.
- Oxidizers:Ammonium perchlorate production clusters in the western United States face EPA National Emission Standards enforcement that limits capacity expansion. Domestic crystallization facilities serve solid propellant demand while REACH obligations redirect European hydrazine derivative investments toward compliant production nodes.
- Fuels:Hydrazine and RP-1 specifications vary by engine architecture and reusability requirements. SpaceX vertical integration of Merlin engine production in the United States includes captive refining of RP-1 to exacting purity standards.
- Additives:Burn-rate modifiers and stabilizers command premium margins for precision-guided systems.
- Stabilizers:Long-term storage formulations require specialized chemistries for extended mission profiles.
Additive margins exceed commodity fuels; oxidizer supply tightens under environmental enforcement.
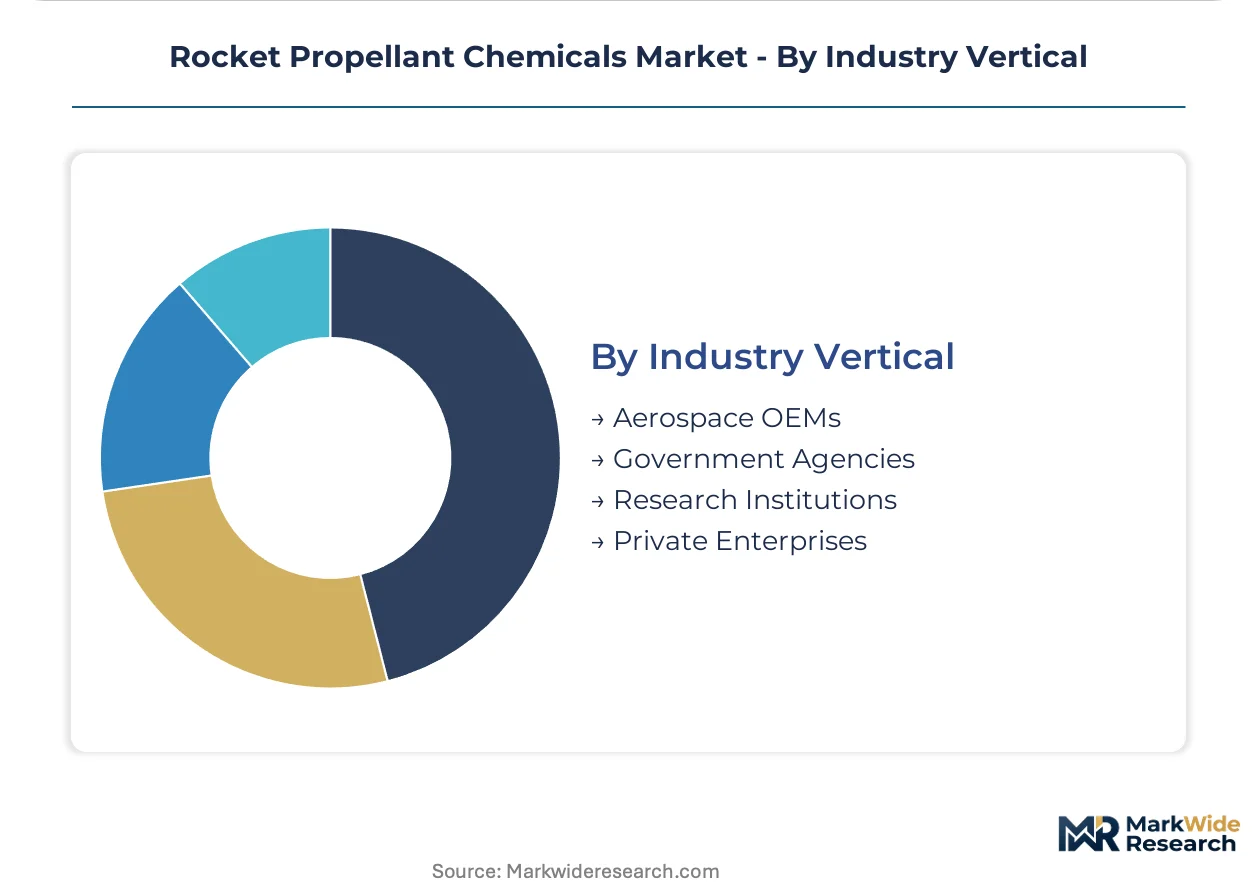
Industry Vertical:
Contracting mechanisms range from cost-plus government awards to fixed-price commercial procurement with multi-year supply commitments.
- Aerospace OEMs:Prime contractors bundle propellant supply with vehicle integration under multi-mission block buy structures. United Launch Alliance and SpaceX compete for National Security Space Launch program awards in the United States with divergent propulsion architectures.
- Government Agencies:NASA and defense procurement offices sustain long-term supply agreements for strategic reserve requirements. Artemis program contracts in the United States pull forward demand for high-performance formulations with certified handling chains.
- Research Institutions:University and national laboratory programs drive qualification of green propellant alternatives.
- Private Enterprises:Emerging launch providers seek ride-share compatible propellant specifications.
Government agencies anchor procurement volume; private enterprises expand fastest on venture-backed launch development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ammonium perchlorate crystallization clusters in the western United States anchor global oxidizer supply chains. Defense procurement contracts and commercial launch licensing requirements concentrate propellant manufacturing in jurisdictions with established hazardous materials infrastructure.
United States
NASA Artemis program contracts and SpaceX Starship development pull demand for high-performance solid and storable liquid formulations. EPA National Emission Standards for Hazardous Air Pollutants constrain ammonium perchlorate capacity expansion in western states. Utah and Nevada production sites consolidate operations to amortize compliance investments across existing throughput.
China
Long March launch cadence and military missile modernization sustain procurement of composite solid propellants. NMPA and MIIT oversight of energetic materials production shapes facility licensing and export control protocols. Sichuan and Shaanxi provinces host state-owned chemical enterprises serving China Aerospace Science and Technology Corporation requirements.
France
ArianeGroup launch service contracts and Safran propulsion programs drive demand for cryogenic and hypergolic formulations. ECHA REACH obligations redirect hydrazine derivative investments toward compliant production nodes with certified handling infrastructure. The Paris-Saclay cluster coordinates research into green propellant alternatives for next-generation launch systems.
India
ISRO commercial arm NSIL expands procurement of storable propellants for PSLV and GSLV missions. BIS certification requirements and DGFT export controls govern cross-border transfers of ammonium perchlorate precursors. Andhra Pradesh and Kerala host propellant processing facilities supporting domestic launch vehicle production.
Japan
Mitsubishi Heavy Industries H3 rocket development and defense missile programs sustain demand for solid and liquid propellant chemicals. METI industrial safety standards and PMDA chemical handling protocols shape manufacturing facility siting. Nagoya and Tanegashima clusters integrate propellant supply with launch site operations.
Rocket Propellant Chemicals Market Competitive Landscape
Long-term supply agreements dominate the current landscape as prime contractors secure qualified propellant sources amid tightening environmental enforcement. The vendor base concentrates around defense-anchored chemical processors and vertically integrated launch providers, with tiering between government-contracted specialists and commercial-scale operators. Strategic archetypes include captive in-house producers, multi-program defense suppliers, and emerging green propellant specialists. Competitive positioning hinges on casting facility qualification timelines and multi-mission block buy contract capture.
Within the defense-contractor tier, Northrop Grumman and Lockheed Martin represent established solid propellant procurement channels for strategic missile programs. SpaceX occupies a distinct position through backward integration into Merlin engine production and captive RP-1 refining. These three entities exemplify divergent competitive models: legacy defense relationships, commercial vertical integration, and reusable architecture scale economics.
| Leading Market Players |
|---|
| L3Harris Technologies |
| Northrop Grumman |
| SpaceX |
| Aerojet Rocketdyne |
| Lockheed Martin |
| Boeing |
| Safran |
| Mitsubishi Heavy Industries |
| China Aerospace Science and Technology Corporation |
| Others |
Value Network & Pricing Analysis
Multi-mission block buy procurement from satellite constellation operators is compressing supplier margins and forcing propellant manufacturers toward long-term contract structures that sacrifice spot-market premiums for volume certainty.
Pricing Analysis
Service bundling separates qualified propellant supply from commodity chemical sales, with casting facility certification and handling infrastructure included in premium tier offerings. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by EPA compliance grade, volume scale, and mission-critical certification. Cost compression in standard-grade ammonium perchlorate is intensifying because western United States production sites amortize EPA National Emission Standards investments across constrained throughput. Government agencies exhibit lowest price sensitivity due to strategic reserve requirements; emerging launch providers face highest sensitivity on venture-backed budgets.
Supply Chain Analysis
Reverse-logistics for solid rocket motor casting equipment and refurbishment of hypergolic handling infrastructure creates secondary supply flows that extend asset lifecycles and delay new capital deployment. Supply concentrates in the United States, China, and France, with ammonium perchlorate crystallization anchored in Utah and Nevada, composite propellant production in Sichuan and Shaanxi provinces, and ArianeGroup cryogenic sourcing through Paris-Saclay cluster. The chain draws from chlorine feedstock, aluminum powder, and hydrazine precursor chemicals. Single-source vulnerability sits with western United States EPA-constrained oxidizer capacity. Distribution runs through defense prime contractor integration facilities and commercial spaceport logistics nodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA enforcement timelines and casting facility qualification bottlenecks are accelerating consolidation, eliminating undercapitalized propellant processors unable to fund closed-loop crystallization retrofits.
For Market Incumbents: Deepen backward integration into precursor chemical production to secure ammonium perchlorate supply against EPA capacity constraints. Lock in multi-mission block buy contracts with SpaceX and United Launch Alliance before qualification timelines widen competitive windows. Incumbents must fund 18-24 month FAA certification cycles for new casting lines to defend against emerging green propellant specialists. For New Entrants and Emerging Players: The premium-to-economy price gap in hydrazine alternatives offers entry points for AF-M315E and LMP-103S formulations with reduced handling costs. Target ISRO commercial procurement through NSIL for PSLV and GSLV missions as the most penetrable geography outside United States defense channels. Green propellant qualification partnerships with research institutions provide the fastest go-to-market angle. For Investors and Strategic Acquirers: The window for entry favors casting facility operators with existing EPA compliance infrastructure and multi-program defense relationships. Long-term viability rests on 5-10 year NASA Artemis and National Security Space Launch contract visibility. Watch FAA launch licensing cadence and green propellant FAA streamlined safety approval volumes as inflection indicators for technology transition timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Chemicals | Captive ammonium perchlorate supply insulates against EPA western United States capacity constraints. |
| Green Propellant Qualification Partnership | AF-M315E and LMP-103S certification unlocks reduced handling costs and streamlined FAA licensing. |
| Multi-Mission Block Buy Contract Capture | Five-year propellant supply agreements with SpaceX and United Launch Alliance anchor revenue visibility. |
| Casting Facility Consolidation | Facility consolidation in Utah and Nevada amortizes EPA National Emission Standards compliance investments. |
| India Supply Chain Entry Point | NSIL procurement relationships for PSLV and GSLV missions diversify geographic revenue exposure. |
Research Methodology
Multi-period observation of NASA contract awards, FAA launch licensing volumes, and EPA enforcement actions anchored the trend analysis, supplemented by interviews with propellant plant managers, defense procurement officers at Northrop Grumman and Lockheed Martin, distribution channel partners handling hazardous materials, and technical R&D directors in energetic materials synthesis. Secondary validation drew from SEC 10-K filings, FAA launch licensing databases, EPA National Emission Standards enforcement records, and customs trade data for ammonium perchlorate precursor chemicals. Bottom-up propellant volume modeling triangulated against top-down NASA and defense budget allocation analysis.
Segment-weighting across product type, application, component, and industry vertical dimensions shaped the analytical framework across the analysis window. Cryogenic versus storable liquid propellant splits, solid propellant defense backlog versus commercial growth tilts, and additive premium margin capture were modeled explicitly. CAGRs were derived from contract visibility timelines and launch cadence projections. Industry-specific forecast inputs included SpaceX Starship development milestones and Artemis program phase transitions.
Inputs from defense procurement databases and EPA enforcement records were available through the study window; gaps in emerging launch provider financial disclosures introduce uncertainty bands around private enterprise segment sizing. Forecasts reflect assumptions regarding FAA licensing throughput and green propellant qualification timelines. Practitioners should monitor EPA National Emission Standards enforcement intensity and REACH registration obligation expansion for early signals of supply chain restructuring.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Global Acetic Anhydride Market
Chemicals
Ferric Oxide Market
Chemicals
Triisopropanolamine (TIPA) Market
Chemicals
Calcium Hydroxide Market
Chemicals
SLS and LABSA Market
Chemicals
Diethylenetriamine (DETA) Market
Chemicals
Aerosol Insecticides Market
Chemicals
Europe Tertiary Amines Market
Chemicals
Paint Remover Market
Chemicals
Phosphorus Pentasulfide (P2S5) Market
Chemicals
Cetyl Stearyl Alcohol Market
Chemicals
North America Tartaric Acid Market
Chemicals
Sodium Phosphate Tribasic Market
Chemicals
Perchloric Acid Market
Chemicals
Acid Anhydrides Market
Chemicals
Allyl Chloride Market