
 Polyferric Sulfate Market | 2026-2036
Polyferric Sulfate Market Size, Share, and Industry Trends Forecast 2026-2036
Polyferric Sulfate Market Outlook
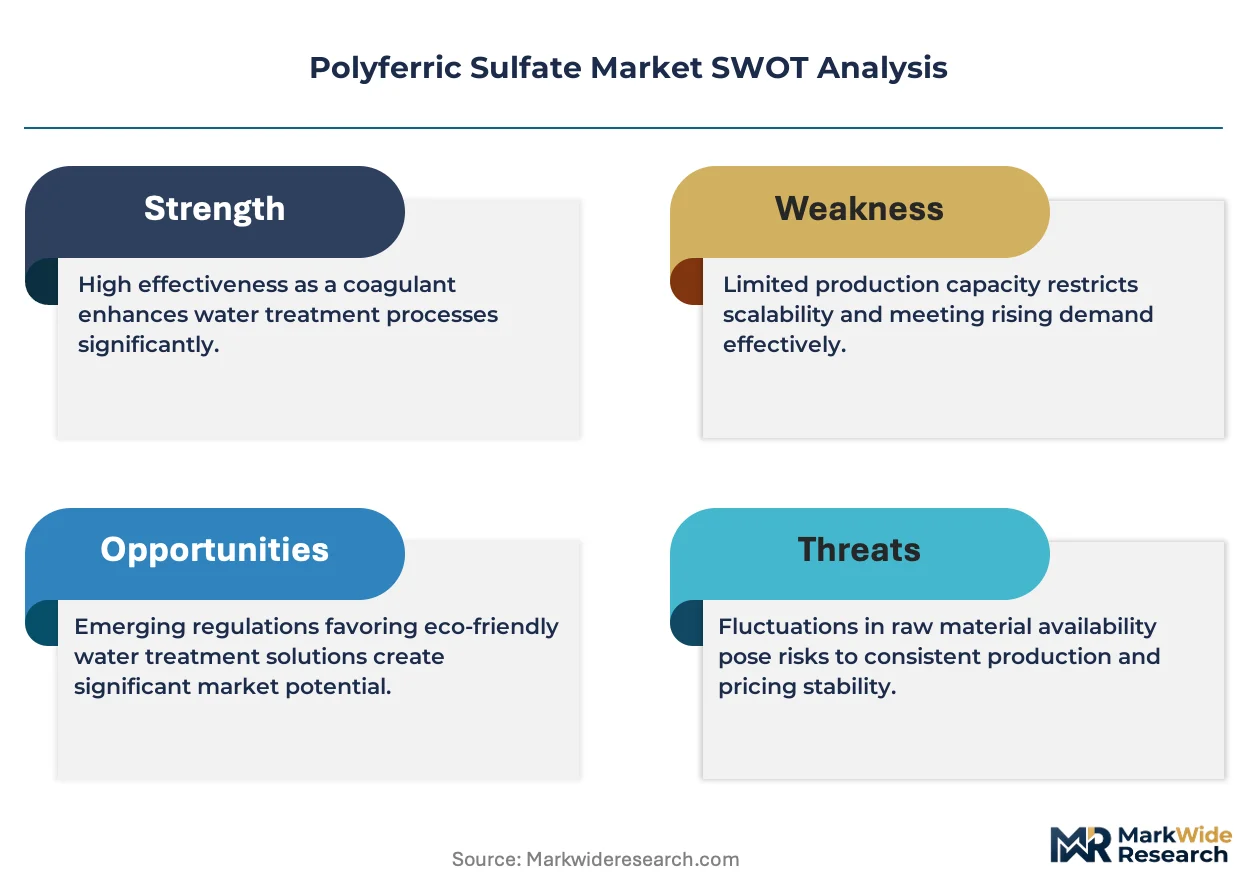
ISO 14001 environmental management certification is collapsing as a baseline qualifier for polyferric sulfate procurement contracts, forcing smaller regional suppliers out of municipal tenders. Kemira Oyj leverages its integrated ferric chloride-to-polyferric sulfate production chain across Nordic and Baltic water utilities. Pencco Inc. anchors North American supply through dedicated rail-served manufacturing in the Ohio River Valley. Chemtrade Logistics Inc. competes via bulk terminal distribution networks serving Great Lakes municipalities.
Polyferric sulfate is a pre-hydrolyzed inorganic coagulant with a typical iron content of 11-13% w/w and basicity ranging from 25-50%, manufactured through controlled oxidation of ferrous sulfate in sulfuric acid media to produce stable polymeric iron species for charge neutralization and sweep flocculation in water treatment. The coagulant product type dominates municipal procurement specifications due to lower dosing requirements versus conventional ferric salts, while wastewater treatment applications show the fastest structural expansion as industrial discharge limits tighten and on-site sludge minimization becomes a priority cost driver for chemical manufacturers. Mining companies represent a concentrated but price-sensitive end-user pool where logistics costs often exceed product value.
EPA National Pollutant Discharge Elimination System permits and China's MEE wastewater discharge standards are elevating ferric-based coagulant performance benchmarks for phosphorus removal and turbidity control across municipal and industrial outfalls. REACH registration requirements in Europe are raising documentation burdens for imported polyferric sulfate, favoring domestic producers with established substance dossiers. Stakeholders must monitor evolving per- and polyfluoroalkyl substances remediation regulations, as polyferric sulfate coagulation is being evaluated for precursor removal in advanced treatment trains.
Market Dynamics
China's MEE discharge standards for phosphorus and suspended solids are compressing product performance requirements across municipal procurement specifications, forcing coagulant suppliers to reformulate basicity profiles and iron speciation to meet tightening effluent limits.
Growth Catalysts
- Phosphorus removal mandates:China's MEE wastewater standards now require sub-0.5 mg/L total phosphorus at municipal outfalls, elevating polyferric sulfate dosing in tertiary treatment trains.
- Textile corridor expansion:Heavy metal-laden effluent from dyeing operations in China's Zhejiang and Jiangsu provinces drives chemical consumption at on-site pretreatment facilities.
- Sludge minimization economics:Electronics manufacturers in South Korea's Gyeonggi-do cluster prioritize polyferric sulfate for reduced sludge volume versus conventional alum.
Market Restraints
- Ferrous sulfate feedstock volatility:Steel pickling waste availability fluctuates with automotive production cycles, compressing margin predictability for non-integrated producers.
- Aluminum sulfate substitution:Mature alum supply chains in North American Great Lakes municipalities lock in incumbent pricing through long-term bulk terminal contracts.
- REACH documentation burdens:ECHA substance dossier requirements for imported polyferric sulfate extend EU market entry timelines by 18-24 months.
Strategic Opportunities
- PFAS precursor remediation:EPA NPDES permit holders are evaluating polyferric sulfate coagulation for per- and polyfluoroalkyl substances removal in advanced treatment trains.
- Rail-served manufacturing:Ohio River Valley production assets can capture Great Lakes municipal demand through bulk liquid terminal distribution networks.
- ISO 14001 procurement elevation:Environmental management certification is collapsing from competitive advantage to baseline tender requirement, creating qualification gaps for regional suppliers.
Industry Challenges
- Basicity control expertise:Polymerization reactor operation demands specialized chemical engineering talent scarce outside established ferric salt production regions.
- Legacy ferric chloride integration:Municipal utilities with existing chloride-based dosing infrastructure face capital friction switching to sulfate chemistry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyferric Sulfate Market |
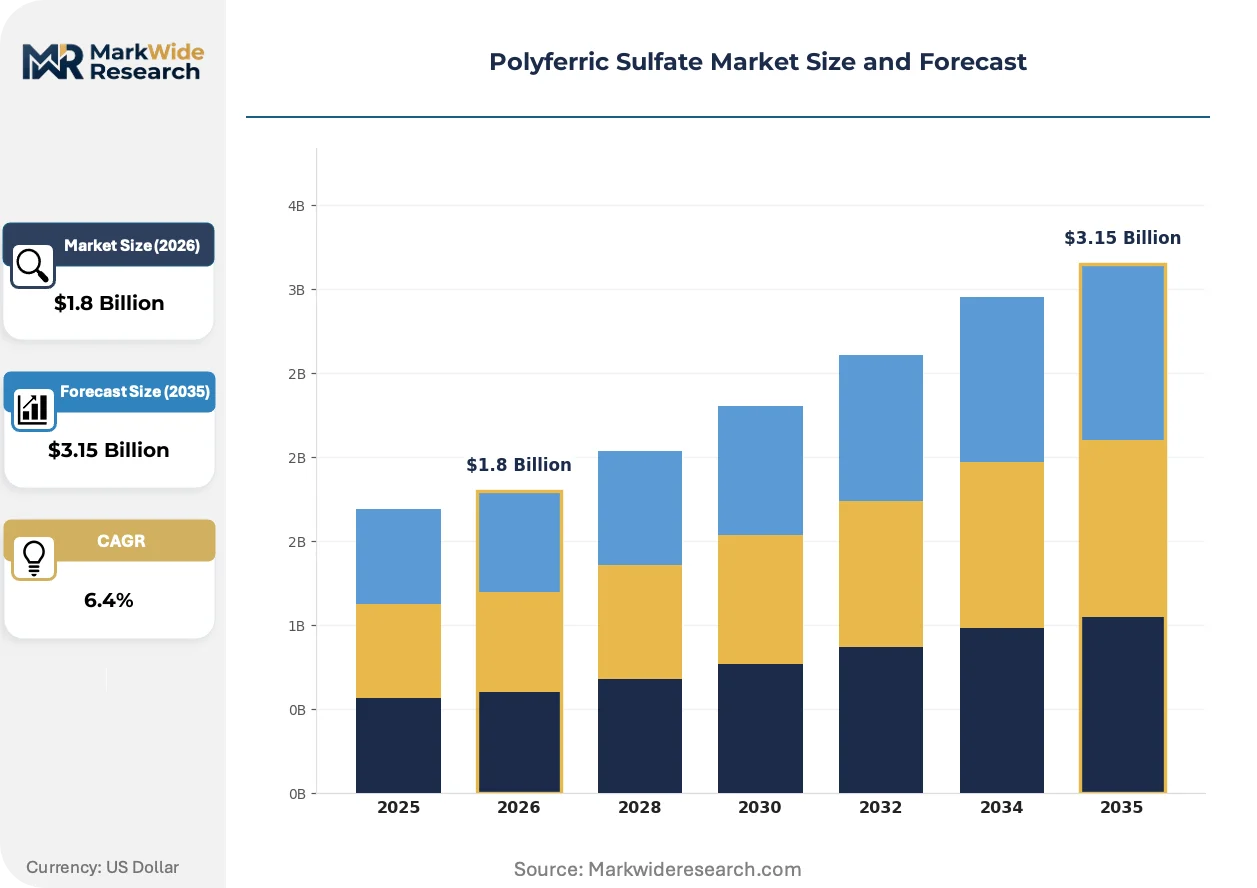
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coagulant, Flocculant, Purification Agent, Additive Application: Water Treatment, Wastewater Treatment, Industrial Processing, Mining End User: Municipalities, Chemical Manufacturers, Mining Companies, Pharmaceutical Industry Distribution Channel: Direct Sales, Online Retail, Distributors, Resellers |
| Companies Covered | Kemira Oyj, Pencco Inc., Chemtrade Logistics Inc., Clinty Chemicals, Henan Aierfuke Chemicals Co. Ltd., Hunan Yide Chemical Co. Ltd., Lubon Industry Co. Ltd., Altivia Chemicals LLC, Airedale Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyferric Sulfate Market Strategic Shifts
Pre-hydrolyzed coagulant chemistry is reshaping competitive positioning as buyers prioritize dosing efficiency and sludge volume reduction over unit product cost in total cost-of-ownership calculations.
High-basicity polyferric sulfate formulations are supplanting conventional ferric chloride in Nordic municipal tenders. Kemira Oyj's integrated production chain leverages existing ferric chloride assets to manufacture 40-50% basicity products for Baltic water utilities. The shift is compressing chloride supplier margins while rewarding sulfuric acid-integrated producers with captive feedstock access.
REACH registration requirements in Europe are elevating documentation burdens for imported coagulants. ECHA substance dossier mandates now require chronic ecotoxicity data and polymer characterization that domestic EU producers have already compiled. The friction is favoring established European ferric salt manufacturers with complete registration portfolios.
Specification-driven procurement is consolidating around ISO 14001 environmental management certification as a baseline tender qualifier. Municipal buyers in China's Yangtze River Delta now embed certification requirements directly into technical specifications, disqualifying uncertified regional suppliers from wastewater treatment plant chemical supply contracts.
Polyferric Sulfate Market Segmentation
Polyferric sulfate procurement channels diverge sharply by segment, with bulk liquid terminals serving municipal water utilities while packaged formulations flow through chemical distributors to industrial accounts. Understanding these pathway distinctions shapes go-to-market economics and margin capture for suppliers.
Product Type:
Channel economics vary dramatically across product forms, with liquid coagulants commanding dedicated bulk logistics and dry formulations enabling distributor networks.
- Coagulant:Pre-hydrolyzed liquid formulations with 11-13% iron content and 25-50% basicity dominate municipal procurement through rail-served bulk terminals. Zhejiang textile corridor utilities specify these grades for heavy metal precipitation in dyeing effluent.
- Flocculant:Higher molecular weight polymeric variants with enhanced sweep flocculation kinetics concentrate in electronics manufacturing clusters. South Korea's Gyeonggi-do semiconductor fabs prioritize these for reduced sludge volume versus conventional alum.
- Purification Agent:Specialized grades for potable water treatment flow through certified distributor networks to smaller municipal systems lacking bulk unloading infrastructure.
- Additive:Blended formulations incorporating polyferric sulfate as a performance component move through chemical compounders serving niche industrial applications.
By volume, Coagulant leads. By expansion trajectory, Flocculant is climbing the fastest.
Application:
Cost tier stratification separates commodity municipal contracts from premium industrial specifications requiring customized basicity profiles.
- Water Treatment:Potable water applications demand NSF/ANSI 60 certification and consistent iron speciation for turbidity control. Great Lakes municipalities source through established bulk terminal networks with incumbent pricing leverage.
- Wastewater Treatment:China's MEE phosphorus discharge mandates below 0.5 mg/L total phosphorus elevate dosing in tertiary treatment trains. Yangtze River Delta utilities now embed ISO 14001 certification requirements directly into technical specifications.
- Industrial Processing:On-site pretreatment at electronics and textile facilities requires flexible delivery schedules and technical service support, favoring regional distributors over bulk terminals.
- Mining:Remote site logistics often exceed product value, compressing margins and favoring suppliers with backward integration into sulfuric acid and ferrous sulfate feedstocks.
By revenue concentration, Water Treatment holds the largest share. By regulatory tailwinds, Wastewater Treatment is gaining share fastest.
End User:
Customer type determines contract structure, with municipalities locking in multi-year supply agreements while industrial buyers prioritize spot purchasing flexibility.
- Municipalities:Public water and wastewater utilities drive volume through formal tender processes with technical specifications, certification requirements, and performance guarantees. Baltic water utilities are shifting from ferric chloride to high-basicity polyferric sulfate formulations.
- Chemical Manufacturers:Formulators and compounders purchase intermediate grades for blending into specialized water treatment products, requiring consistent quality and documentation for downstream regulatory compliance.
- Mining Companies:Concentrated but price-sensitive demand centers on acid mine drainage treatment, with procurement decisions heavily influenced by total delivered cost including remote logistics.
- Pharmaceutical Industry:Stringent purity requirements and validation documentation favor suppliers with established pharmaceutical water treatment credentials and dedicated quality management systems.
By contract value, Municipalities dominate. By margin expansion, Pharmaceutical Industry specifications command premium pricing.
Distribution Channel:
Supply concentration in East Asian production corridors shapes channel viability for different geographic markets.
- Direct Sales:Bulk liquid terminals and dedicated rail cars serve high-volume municipal and industrial accounts with integrated logistics, capturing margin through vertical control of transportation and storage.
- Online Retail:Packaged dry formulations and smaller volume liquid containers reach small water systems and industrial facilities through digital procurement platforms with technical documentation access.
- Distributors:Regional chemical distributors provide local inventory, technical service, and credit terms to mid-sized industrial accounts lacking direct supplier relationships.
- Resellers:Independent agents and trading companies facilitate cross-border transactions, particularly for REACH-registered product entry into European markets where documentation burdens favor established import channels.
By tonnage moved, Direct Sales leads. By geographic reach extension, Distributors are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Municipal wastewater utilities in China's Yangtze River Delta and textile manufacturers in Zhejiang province concentrate procurement volumes. Steel pickling waste availability in the US Rust Belt and electronics fabrication in South Korea's Gyeonggi-do cluster complete the demand map.
China
Textile dyeing operations in Zhejiang and Jiangsu provinces generate heavy metal-laden effluent requiring on-site pretreatment. MEE discharge standards now mandate sub-0.5 mg/L total phosphorus at municipal outfalls. Yangtze River Delta utilities embed ISO 14001 certification directly into chemical supply tenders.
United States
Great Lakes municipalities source through established bulk terminal networks with incumbent pricing leverage. EPA NPDES permits elevate ferric-based coagulant performance benchmarks for phosphorus removal. Ohio River Valley production assets capture demand via rail-served manufacturing and liquid terminal distribution.
South Korea
Electronics manufacturers in Gyeonggi-do prioritize polyferric sulfate for reduced sludge volume versus conventional alum. Semiconductor fabs drive specification-grade procurement with flexible delivery requirements. The Seoul Capital Area concentrates advanced treatment train adoption for industrial discharge compliance.
Germany
REACH registration requirements raise documentation burdens for imported coagulants, favoring domestic producers with complete substance dossiers. ECHA mandates chronic ecotoxicity data and polymer characterization extending market entry timelines. Industrial water treatment facilities in North Rhine-Westphalia specify certified distributor channels.
Finland
Nordic water utilities shift from ferric chloride to high-basicity polyferric sulfate formulations. Baltic municipal tenders reward sulfuric acid-integrated producers with captive feedstock access. Kemira Oyj leverages integrated production chains across regional water utility contracts.
Polyferric Sulfate Market Competitive Environment
Player mix skews toward integrated chemical conglomerates with backward control over ferrous sulfate feedstocks. The vendor base separates into three tiers: multinational water treatment specialists with rail-served manufacturing assets, regional compounders serving industrial distributor networks, and commodity traders dependent on spot steel pickling waste supply. Consolidation pressures favor producers with captive sulfuric acid integration and established REACH dossiers. Capacity expansion in the Ohio River Valley and strategic partnerships for PFAS remediation evaluation represent dominant competitive vectors.
Among Nordic-integrated producers, Kemira Oyj exemplifies the sulfuric acid-captive archetype with existing ferric chloride asset leverage. Pencco Inc. anchors North American supply through dedicated rail-served manufacturing infrastructure. Chemtrade Logistics Inc. occupies a position in bulk terminal distribution networks serving Great Lakes municipalities. These three represent distinct strategic postures: feedstock integration, logistics verticalization, and channel concentration respectively.
| Leading Market Players |
|---|
| Kemira Oyj |
| Pencco Inc. |
| Chemtrade Logistics Inc. |
| Clinty Chemicals |
| Henan Aierfuke Chemicals Co. Ltd. |
| Hunan Yide Chemical Co. Ltd. |
| Lubon Industry Co. Ltd. |
| Altivia Chemicals LLC |
| Airedale Chemical |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake agreements with sulfuric acid indexation lock in feedstock access and price visibility for polyferric sulfate producers serving Yangtze River Delta municipal utilities. These contracts insulate integrated manufacturers from ferrous sulfate volatility while compressing margin predictability for non-integrated compounders dependent on spot steel pickling waste.
Pricing Analysis
Cost-plus contracts with sulfuric acid feedstock indexation dominate municipal procurement, anchoring price stability for integrated producers. Three-tier pricing structure separates NSF/ANSI 60 certified potable water grades from industrial wastewater specifications and uncertified commodity tiers. Cost compression in the commodity tier is intensifying because aluminum sulfate substitution pressure from incumbent Great Lakes suppliers locks in bulk terminal pricing. Mining companies exhibit the highest price sensitivity, where remote logistics often exceed product value, while pharmaceutical water treatment specifications command the lowest sensitivity due to validation documentation requirements.
Supply Chain Analysis
China and Finland anchor global polyferric sulfate production, with Zhejiang province concentrating textile corridor supply and Nordic integrated producers serving Baltic municipal utilities. Manufacturing draws from steel pickling waste, sulfuric acid, and specialized polymerization reactor equipment. Single-source vulnerability in ferrous sulfate feedstock creates exposure to automotive production cycle fluctuations. Distribution runs through rail-served bulk liquid terminals for high-volume municipal accounts and regional chemical distributors for mid-sized industrial facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service contracts for basicity optimization and dosing system calibration are expanding faster than commodity coagulant sales, creating recurring revenue layers that outperform hardware margins. This service-attach dynamic repositions chemical supply relationships from transactional procurement to performance-based partnerships.
For Market Incumbents: Compound ISO 14001 certification advantages into municipal tender qualification moats before regional suppliers close documentation gaps. Defend margin position by adding captive sulfuric acid capacity at Ohio River Valley assets, neutralizing feedstock volatility that threatens non-integrated competitors. Prioritize PFAS remediation evaluation partnerships with EPA NPDES permit holders to anchor specification-grade positioning ahead of regulatory finalization. For New Entrants and Emerging Players: Lead with REACH-registered product entry into German industrial water treatment facilities, where ECHA documentation burdens extend incumbent timelines. Target South Korea's Gyeonggi-do electronics cluster for flocculant-grade specifications, where semiconductor fabs prioritize sludge volume reduction over unit cost. Establish distributor relationships with certified channels in North Rhine-Westphalia rather than competing directly for bulk municipal terminals. For Investors and Strategic Acquirers: Sulfuric acid-integrated regional producers with incomplete REACH portfolios represent the most compelling acquisition archetype for European market entry. Monitor EPA NPDES permit renewal cycles as the critical inflection signal, as tightening phosphorus limits accelerate ferric chloride displacement and expand addressable market for high-basicity formulations. Long-term viability hinges on backward integration depth and regulatory dossier completeness rather than volume scale alone.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sulfuric Acid | Captive feedstock access neutralizes steel pickling waste volatility for Nordic and Baltic producers. |
| REACH Registration Completion | ECHA substance dossiers extend competitive moats against imported coagulants in German industrial markets. |
| Rail-Served Capacity Expansion | Ohio River Valley liquid terminal networks capture Great Lakes municipal demand from incumbent alum suppliers. |
| PFAS Remediation Evaluation Partnerships | EPA NPDES permit holder pilots position polyferric sulfate in advanced treatment train specifications. |
| ISO 14001 Certification Investment | Baseline tender requirements in China's Yangtze River Delta disqualify uncertified regional competitors. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with water utility procurement managers, chemical plant operations directors, and ferric salt technical specialists, combined with secondary validation against MEE discharge standards documentation, EPA NPDES permit filings, and ECHA REACH registration databases. Bottom-up volume estimates from regional production capacity and top-down demand triangulation from municipal tender awards were cross-referenced to establish market sizing boundaries.
Across the analysis window, forecasts model product type segmentation by basicity tier and iron speciation, application segmentation by discharge limit stringency, and end-user segmentation by contract structure maturity. CAGRs derive from regression analysis of historical municipal chemical procurement volumes against regulatory tightening timelines, with specific inputs including textile corridor expansion rates in Zhejiang and semiconductor fab capacity additions in Gyeonggi-do.
Forecasts assume regulatory continuity in China's MEE phosphorus standards and EPA NPDES permit benchmarks; material policy shifts would require re-modeling. Forecasts reflect assumptions about steel pickling waste availability and sulfuric acid pricing stability. Recalibration cycles align with material shifts in discharge standard enforcement intensity and REACH registration completion timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Formic Acid Market
Bulk Chemicals
Natural Thickener Market
Bulk Chemicals
Global Linear Alpha Olefins Market
Bulk Chemicals
Global Sodium Hydrosulfite Market
Bulk Chemicals
Palmitic Acid Market
Bulk Chemicals
Global Levulinic Acid Market
Bulk Chemicals
Foundry Coke Market
Bulk Chemicals
Sheet Molding and Bulk Molding Compounds Market
Bulk Chemicals
Sulfur Market
Bulk Chemicals
Bromacil Market
Bulk Chemicals
Acrylamide Market
Bulk Chemicals
Global Ground and Precipitated Calcium Carbonate Market
Bulk Chemicals
Formate Brine Market
Bulk Chemicals
Global Quinine Sulphate Market
Bulk Chemicals
N-Heptane Market
Bulk Chemicals
Europe Hydrogen Bromide Market