
 Pressure Filter Market | 2026-2036
Pressure Filter Market Size, Share, and Industry Trends Forecast 2026-2036
Pressure Filter Market Analytics
Shortages of certified welding technicians and filtration process engineers is redrawing competitive boundaries across the pressure filter supply base. Parker Hannifin Corp leverages its vertically integrated pneumatic and hydraulic divisions to bundle filtration with motion control systems. Eaton Corporation anchors its position through captive distribution serving power generation and aerospace rebuild programs. Alfa Laval AB specializes in hygienic designs that command premium positioning within European dairy and pharmaceutical processing.
A pressure filter is a mechanical separation device that uses differential pressure to force fluid through a porous medium, typically operating at pressures from 0.5 to 15 bar depending on cake formation requirements and solids loading. The equipment separates suspended particulates from liquids or gases to protect downstream equipment, recover valuable solids, or achieve regulatory discharge standards. Leaf filters and disc filters dominate the installed base in mining tailings and chemical processing where high solids volumes demand automated cake discharge. Bag filters represent the fastest-expanding product category in pharmaceutical sterile filtration, driven by single-use adoption and elimination of clean-in-place validation burdens. Stainless steel construction retains the largest material share in food and beverage applications where surface finish standards and thermal cycling resistance justify higher first costs against plastic alternatives.
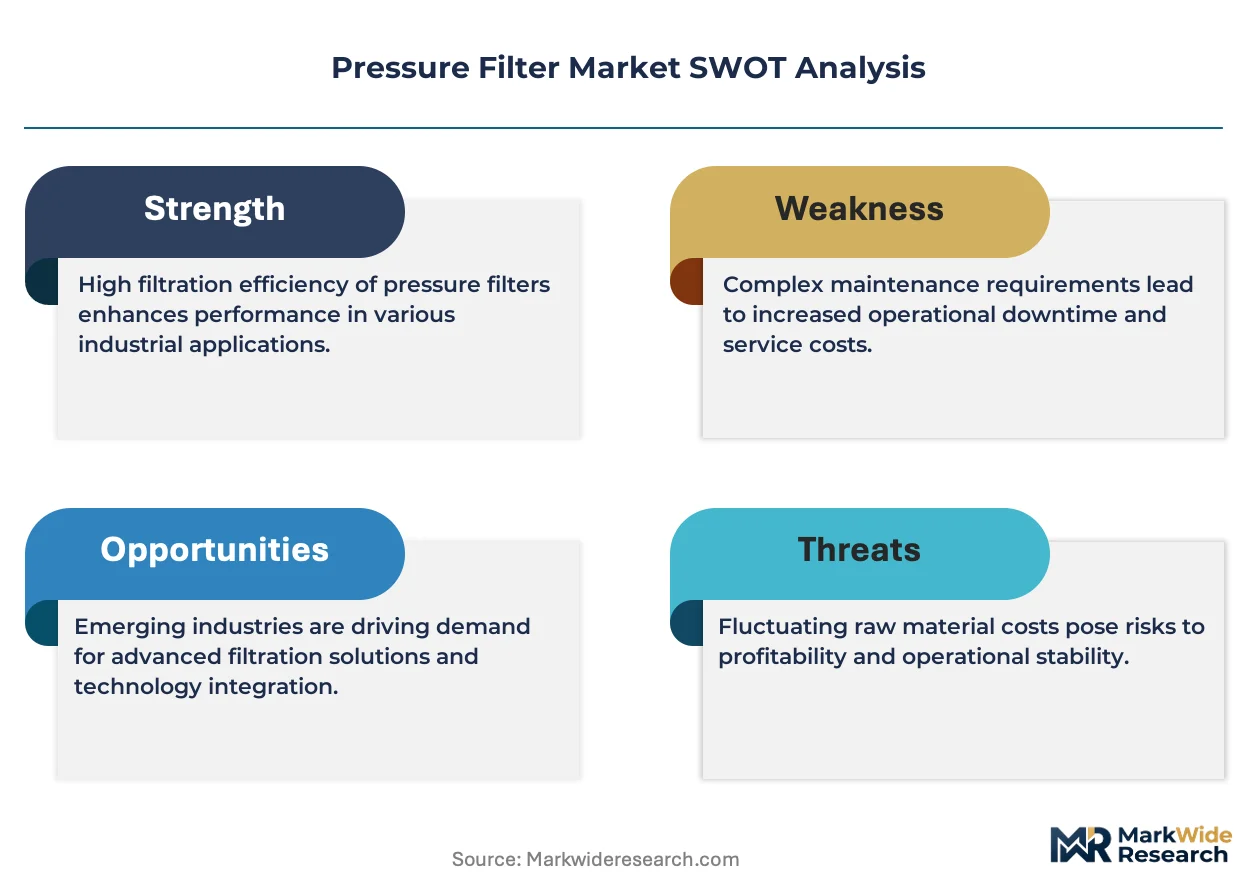
EPA effluent limitation guidelines under the Clean Water Act mandate tertiary filtration upgrades at municipal wastewater facilities, directly expanding replacement demand for tube and disc configurations. REACH substance restrictions in Europe are shifting material specifications away from certain polymer coatings toward ceramic and composite media in chemical process applications. FDA cGMP requirements for pharmaceutical manufacturing continue tightening validation protocols for filter integrity testing and extractables documentation. Stakeholders must weigh capital deployment between incremental automation of existing pressure filter assets versus full replacement with membrane-integrated hybrid systems that stricter discharge standards will eventually require.
Market Dynamics
EPA effluent limitation guidelines under the Clean Water Act are forcing tertiary filtration upgrades across municipal wastewater infrastructure, compressing replacement cycles and tilting procurement toward automated backwashing configurations.
Growth Catalysts
- Clean Water Act mandates:EPA effluent limitation guidelines require tertiary filtration at municipal wastewater facilities, directly expanding replacement demand for tube and disc filter configurations across legacy installations.
- Rhine-Ruhr industrial corridor:Germany's manufacturing concentration around chemical processing and metalworking generates sustained demand for high-pressure leaf filters in tailings and slurry applications.
- Single-use pharmaceutical adoption:Bag filters eliminate clean-in-place validation burdens, accelerating procurement in sterile drug manufacturing where FDA cGMP requirements tighten documentation protocols.
Market Restraints
- Certified welding technician shortages:Specialized fabrication skills for pressure vessel construction concentrate in aging workforce pools, extending lead times for stainless steel filter housing delivery.
- Polymer coating restrictions:REACH substance limitations in Europe shift material specifications toward ceramic and composite media, raising unit costs against conventional coated steel alternatives.
- Membrane hybrid substitution:Integrated membrane-press systems threaten standalone pressure filter demand as discharge standards tighten toward ultrafiltration-grade effluent quality.
Strategic Opportunities
- Indian pharmaceutical manufacturing:CDSCO regulatory alignment with FDA standards creates upgrade demand for validated bag filtration systems in active pharmaceutical ingredient production.
- Power generation rebuild programs:Captive distribution channels serving aerospace and turbine maintenance open aftermarket penetration for cartridge and disc filter replacement cycles.
- Motion control bundling:Pneumatic and hydraulic system integration enables packaged offerings combining filtration with valve actuation and process automation.
Industry Challenges
- Filtration process engineer scarcity:Deep expertise in cake formation dynamics and media selection concentrates among retiring specialists, constraining system optimization for high-solids mining applications.
- Validation timeline compression:FDA extractables documentation and integrity testing protocols extend qualification periods for pharmaceutical sterile filtration deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pressure Filter Market |
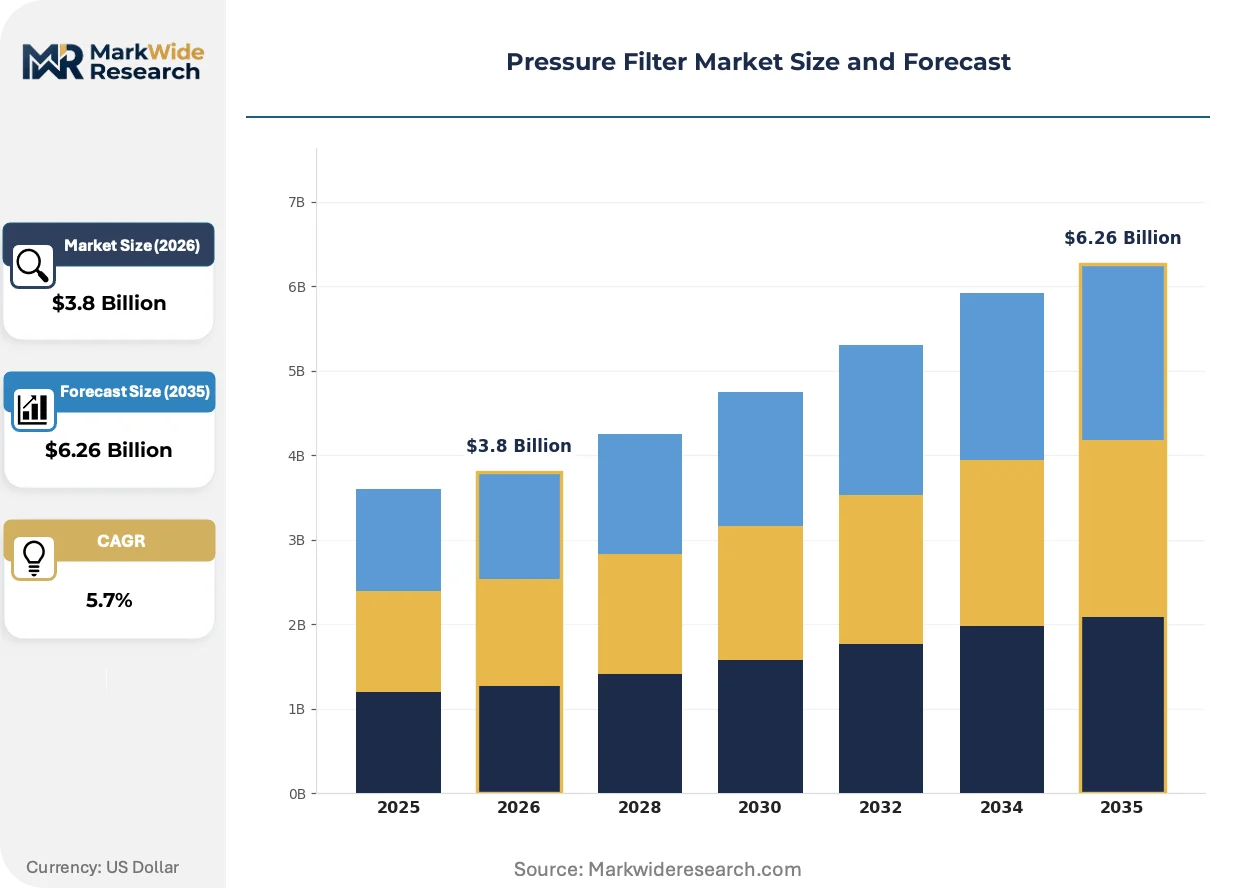
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disc Filters, Leaf Filters, Tube Filters, Bag Filters End User: Municipal, Chemical, Pharmaceutical, Food & Beverage Material: Stainless Steel, Plastic, Ceramic, Composite Application: Water Treatment, Oil Recovery, Mining, Wastewater Management |
| Companies Covered | Parker Hannifin Corp, Eaton Corporation, Alfa Laval AB, Andritz AG, FLSmidth and Co. AS, Evoqua Water Technologies LLC, Donaldson Company, Inc., Pall Corporation, Filtration Group Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pressure Filter Market Evolving Landscape
Automation architectures and material substitutions are compressing the gap between conventional pressure filtration and membrane-grade performance, reshaping how operators balance capital efficiency against regulatory compliance.
Ceramic membrane elements are supplanting traditional polymer-coated metal screens in chemical process applications where thermal cycling and aggressive pH environments degrade conventional media. Specialty chemical manufacturers in Germany's industrial cluster are piloting these configurations for catalyst recovery and solvent filtration. The shift is compressing maintenance intervals while raising initial capital requirements, favoring operators with centralized engineering capabilities.
REACH substance restrictions are eliminating certain fluoropolymer coatings from food-contact and pharmaceutical applications, redirecting specification toward uncoated stainless steel and sintered metal fiber alternatives. ECHA's evolving candidate list forces reformulation of sealing materials and surface treatments across European-installed equipment. Process engineers in dairy and beverage applications are responding with accelerated validation protocols for alternative surface finishes.
Equipment-as-service contracting is displacing traditional capital purchase models in municipal water treatment, particularly for automated backwashing systems where performance guarantees align contractor incentives with operational uptime. North American utilities are consolidating vendor relationships around outcome-based agreements covering media replacement and preventive maintenance. The model concentrates procurement authority among regional water authorities with consolidated balance sheets.
Pressure Filter Market Segmentation
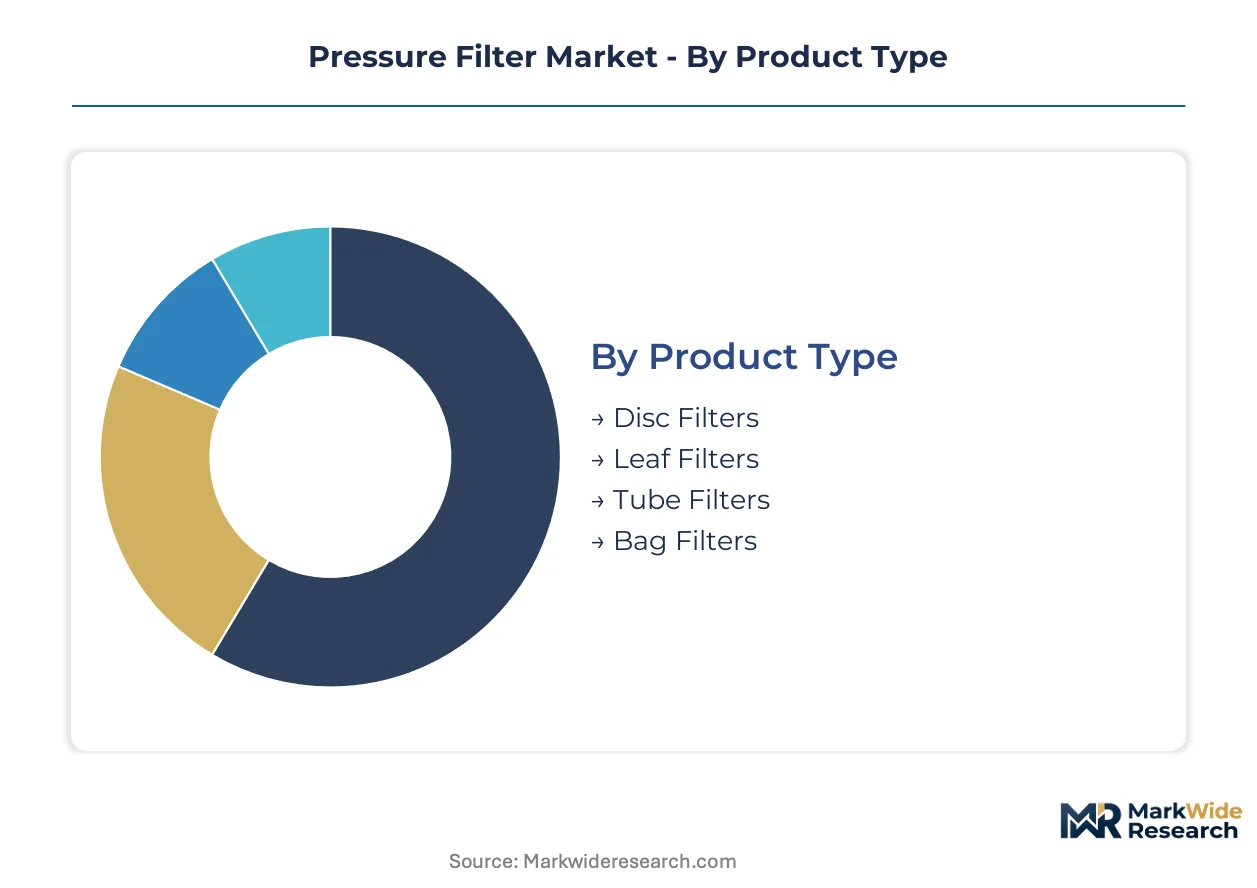
Pressure filter procurement patterns diverge sharply across product architectures, with membrane hybrid systems threatening established configurations in high-purity applications. Material specifications and end-use validation requirements create distinct competitive arenas where technical compliance, not price alone, determines vendor selection.
Product Type:
Membrane-integrated hybrid systems exert substitution pressure most acutely on tube and disc configurations in municipal tertiary treatment, forcing incumbents to automate cake discharge or cede share.
- Bag Filters:Single-use polypropylene or nylon mesh configurations eliminate clean-in-place validation. FDA cGMP documentation burdens in pharmaceutical sterile processing accelerate procurement, particularly for active pharmaceutical ingredient production.
- Leaf Filters:Horizontal or vertical plate assemblies handle high-solids slurries through automated cake discharge mechanisms. Germany's Rhine-Ruhr chemical corridor sustains demand for high-pressure variants in catalyst recovery and tailings dewatering.
- Disc Filters:Rotating cloth or metal screen discs provide continuous filtration with low operating head. Mining tailings applications in Australia favor these for large-volume dewatering with minimal operator intervention.
- Tube Filters:Cylindrical element configurations suit polishing applications with moderate solids loading. Power generation condensate polishing in the US maintains steady replacement cycles through captive distribution channels.
Leaf filters anchor the volume base in heavy industrial slurry processing while bag filters gain share at the steepest rate in pharmaceutical sterile applications.
End User:
Capital deployment intensity varies by sector, with municipal utilities consolidating procurement authority around equipment-as-service models while pharmaceutical manufacturers absorb extended validation timelines.
- Pharmaceutical:Sterile filtration demands extractables documentation and integrity testing protocols per FDA cGMP. Single-use bag adoption eliminates steam-in-place infrastructure, compressing facility qualification periods.
- Municipal:EPA effluent limitation guidelines mandate tertiary filtration upgrades across wastewater infrastructure. North American utilities are expanding automated backwashing procurement through performance-based contracting.
- Chemical:Aggressive pH environments and thermal cycling degrade conventional polymer coatings. REACH substance restrictions redirect specifications toward ceramic and uncoated stainless steel alternatives.
- Food & Beverage:Surface finish standards and thermal cycling resistance justify stainless steel first costs. Dairy processing in Europe accelerates validation protocols for alternative surface treatments as ECHA restricts fluoropolymer coatings.
Municipal utilities anchor the volume base through infrastructure replacement cycles while pharmaceutical applications gain share at the steepest rate on single-use technology adoption.
Material:
Regulatory chemistry restrictions in Europe compress the viable material set, elevating ceramic and composite alternatives against legacy coated metal configurations.
- Stainless Steel:Austenitic grades with controlled sulfur content deliver surface finishes below Ra 0.8 micrometers for hygienic applications. Food and beverage thermal cycling requirements sustain premium positioning against plastic alternatives.
- Ceramic:Alumina and silicon carbide elements withstand aggressive pH and thermal shock in chemical process applications. Germany's specialty chemical manufacturers pilot these for catalyst recovery where polymer degradation previously limited media life.
- Composite:Carbon fiber reinforced polymer housings reduce weight in mobile mining equipment. High-pressure ratings challenge conventional steel in remote tailings dewatering installations.
- Plastic:Polypropylene and PVDF housings serve corrosive chemical environments at lower capital cost. REACH candidate list restrictions on certain polymer formulations constrain European specification.
Stainless steel anchors the volume base across food and hygienic applications while ceramic gains share at the steepest rate in chemical process substitution.
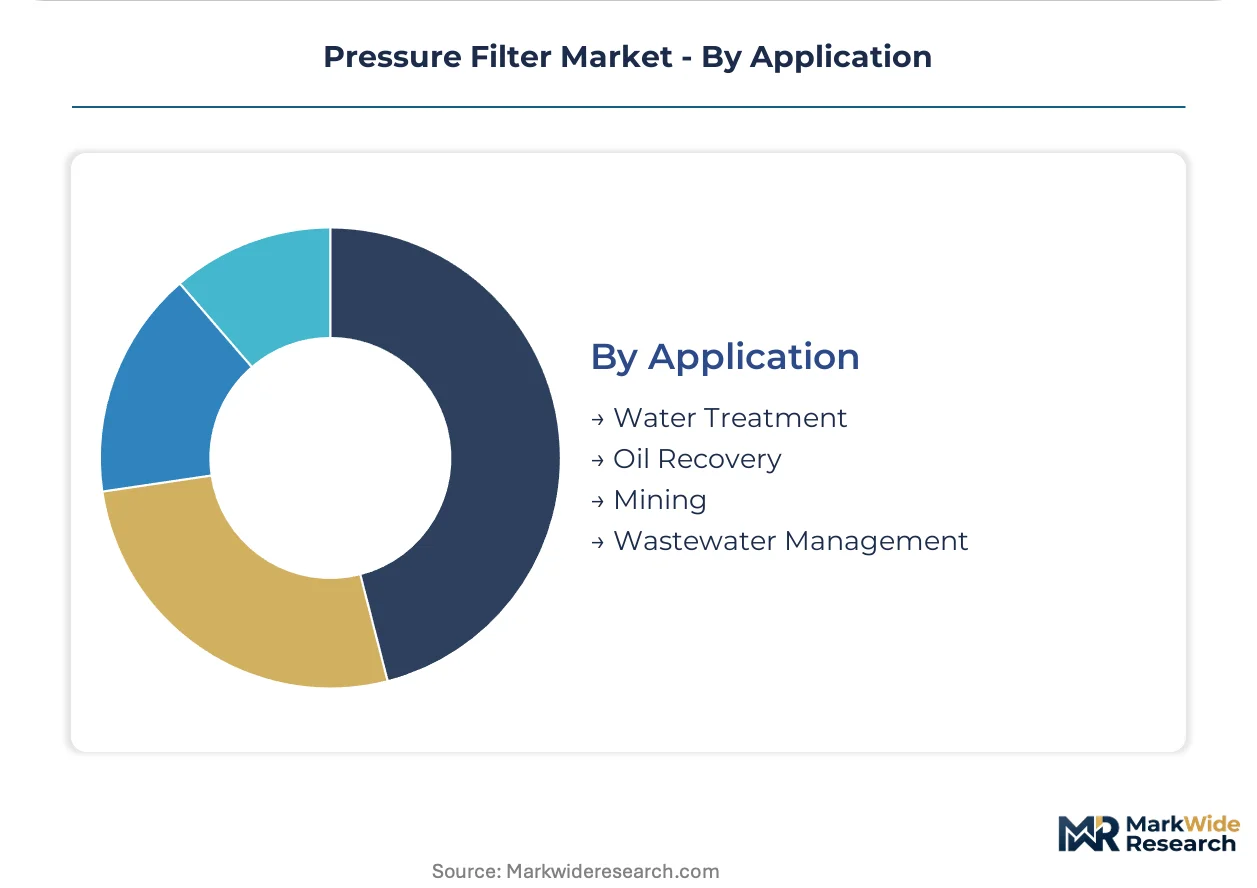
Application:
Discharge standard tightening creates tiered performance requirements, with water treatment and wastewater management facing the steepest compliance escalation.
- Water Treatment:Municipal drinking water and industrial process water polishing demand consistent effluent quality. Automated backwashing systems reduce operator burden in North American utility consolidation.
- Wastewater Management:EPA tertiary filtration mandates compress replacement cycles for legacy tube and disc installations. Equipment-as-service contracting aligns contractor incentives with operational uptime guarantees.
- Mining:Tailings dewatering and process water recovery handle high-solids volumes with automated cake discharge. Filtration process engineer scarcity constrains system optimization for high-throughput operations.
- Oil Recovery:Produced water treatment and refinery process streams require corrosion-resistant materials. Ceramic and composite media expand service intervals in sour service environments.
Water treatment anchors the volume base through municipal infrastructure scale while wastewater management gains share at the steepest rate on regulatory compliance upgrades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA effluent limitation guidelines are compressing replacement cycles across United States municipal infrastructure. Utilities in Germany's Rhine-Ruhr corridor face REACH substance restrictions on polymer coatings. India's CDSCO regulatory alignment with FDA standards is accelerating pharmaceutical filtration upgrades.
United States
Municipal water treatment utilities are expanding automated backwashing procurement to meet Clean Water Act tertiary filtration mandates. EPA guidelines force upgrades across legacy tube and disc installations. Power generation rebuild programs in the Midwest sustain captive distribution channels for cartridge replacement cycles.
Germany
Specialty chemical manufacturers pilot ceramic membrane elements for catalyst recovery where thermal cycling degrades conventional media. ECHA's evolving candidate list eliminates certain fluoropolymer coatings from food-contact applications. The Rhine-Ruhr manufacturing corridor concentrates demand for high-pressure leaf filters in metalworking and chemical processing.
India
Active pharmaceutical ingredient producers absorb validated bag filtration systems as CDSCO standards tighten. The country's national pharmaceutical regulator drives alignment with FDA cGMP documentation protocols. Maharashtra and Gujarat pharmaceutical clusters are compressing facility qualification periods through single-use adoption.
China
Mining tailings operations demand automated cake discharge for high-solids dewatering amid filtration process engineer scarcity. The Ministry of Ecology and Environment tightens discharge standards for industrial wastewater. Shandong Peninsula chemical processors are shifting specifications toward ceramic alternatives under dual carbon goals.
Australia
Large-volume tailings dewatering favors disc filter configurations with minimal operator intervention. The national environmental regulator enforces water recovery mandates at remote mining installations. Western Australia iron ore operations sustain demand for composite-housed mobile filtration equipment.
Pressure Filter Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the pressure filter supply base. Vertically integrated conglomerates bundle filtration with adjacent motion control and fluid power systems. Specialized hygienic fabricators command premium positioning through surface finish capabilities and validation documentation. Competitive moves concentrate on backward integration into ceramic media production and outcome-based contracting for municipal infrastructure.
Among diversified industrial conglomerates, Parker Hannifin Corp and Eaton Corporation occupy positions spanning pneumatic, hydraulic, and filtration system integration. Alfa Laval AB exemplifies the hygienic specialist archetype through European dairy and pharmaceutical positioning. These three anchors represent distinct strategic vectors: bundled automation, captive distribution channels, and premium hygienic compliance respectively.
| Leading Market Players |
|---|
| Parker Hannifin Corp |
| Eaton Corporation |
| Alfa Laval AB |
| Andritz AG |
| FLSmidth and Co. AS |
| Evoqua Water Technologies LLC |
| Donaldson Company, Inc. |
| Pall Corporation |
| Filtration Group Corporation |
| Others |
Value Network & Pricing Analysis
Ceramic membrane substitution for polymer-coated metal screens is redrawing supply geography toward Germany's specialty chemical manufacturers while compressing pricing premiums previously commanded by conventional media. REACH substance restrictions on fluoropolymer coatings simultaneously elevate ceramic unit costs and eliminate lower-priced alternatives, forcing buyers toward consolidated supply sources with captive media production.
Pricing Analysis
Price spreads between German-engineered ceramic systems and Asian-manufactured polymer-coated units exceed forty percent on equivalent throughput ratings. Three-tier pricing structure across hygienic-certified, industrial-standard, and economy-grade configurations segments buyer pools by validation burden. Cost compression in municipal procurement channels intensifies as equipment-as-service contracting transfers capital risk to vendors. Pharmaceutical sterile filtration buyers exhibit lowest price sensitivity given FDA cGMP documentation requirements that lock in validated suppliers.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes extend lead times for stainless steel filter housings sourced from Chinese fabrication clusters. Manufacturing gravity centers on Germany, China, and India for finished equipment, with ceramic media drawing from Japanese and German powder metallurgy specialists. Supply chain risk concentrates in single-source dependency for certified welding technicians in pressure vessel construction. Distribution runs through captive service networks for power generation rebuild programs and regional water authority consolidations for municipal infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pressure filter incumbents face membrane-integrated hybrid substitution that threatens standalone equipment demand as discharge standards tighten toward ultrafiltration-grade effluent quality.
For Market Incumbents: Consolidate backward integration into ceramic media production to capture margin pools escaping to Japanese and German powder suppliers. Anchor captive distribution channels serving power generation rebuild programs against erosion by motion-control bundling competitors. Priority rests on automated cake discharge R&D to defend tube and disc configurations from membrane hybrid displacement. For New Entrants and Emerging Players: Anchor in Indian pharmaceutical manufacturing clusters where CDSCO-FDA alignment compresses qualification timelines for validated bag filtration systems. Target Maharashtra and Gujarat API producers adopting single-use elimination of clean-in-place infrastructure. Go-to-market leverage sits with equipment-as-service contracting expertise transferred from water treatment utility consolidation experience. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed hygienic specialists holding European dairy and pharmaceutical surface finish capabilities. Five-to-ten year viability hinges on REACH regulatory chemistry adaptation and ceramic media scale-up. Signal to monitor: ECHA candidate list expansion accelerating fluoropolymer coating obsolescence beyond current food-contact restrictions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Media | Captures margin pools escaping to Japanese powder metallurgy specialists under REACH coating restrictions. |
| Equipment-as-Service Contracting | Aligns vendor incentives with municipal utility uptime guarantees in North American consolidation. |
| Automated Cake Discharge R&D | Defends tube and disc configurations against membrane hybrid substitution in tertiary treatment. |
| Single-Use Bag Validation Investment | Compresses pharmaceutical facility qualification periods under FDA cGMP documentation protocols. |
| Captive Distribution Channel Expansion | Secures power generation and aerospace rebuild program replacement cycles against bundled competitors. |
Research Methodology
Initial hypotheses were tested against primary input from municipal water utility procurement directors, pharmaceutical manufacturing engineers, chemical process plant managers, and filtration aftermarket service heads, then refined through secondary validation against EPA effluent limitation guidelines, ECHA REACH candidate list updates, FDA cGMP documentation protocols, and customs trade data on ceramic media imports. Bottom-up equipment shipment tallies triangulated against top-down municipal infrastructure investment forecasts.
Variance decomposition across product type, end-use sector, material specification, and geographic regulatory cluster shaped the analytical framework over the projection horizon. CAGRs derived from regression against historical replacement cycle compression and regulatory mandate implementation timelines. Industry-specific inputs included welding technician workforce demographics and ceramic membrane pilot adoption rates in Germany's Rhine-Ruhr corridor.
Underlying assumptions cover stable EPA enforcement intensity and ECHA substance restriction expansion velocity, with deviation risk concentrated in membrane hybrid cost-performance breakthroughs accelerating substitution timelines. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Hazardous Chemicals Packaging Market
Industrial Chemicals
Trimethylolpropane (TMP) Market
Industrial Chemicals
Singapore Sealants Market
Industrial Chemicals
Global Aerosol Propellant Market
Industrial Chemicals
Potassium Acetate Market
Industrial Chemicals
North America Biocides Market
Industrial Chemicals
Biochemicals Control Market
Industrial Chemicals
Global Refrigerants Market
Industrial Chemicals
Hydrogen Sulfide Scavengers Market
Industrial Chemicals
Isononanol (INA) Market
Industrial Chemicals
Middle East and Africa Non-Phthalate Plasticizers Market
Industrial Chemicals
Cockroach Gel Baits Market
Industrial Chemicals
Europe Biocides Market
Industrial Chemicals
Acetylene Market
Industrial Chemicals
Global N-MDEA Market
Industrial Chemicals
Foam Market