
 Global Battery Technology Market | 2026-2036
Global Battery Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Global Battery Technology Market Analysis
The performance gap between premium energy-density cells and commodity-grade storage packs is realigning procurement strategies across automotive and grid-scale buyers. CATL leverages its integrated lithium refining and cathode production to dominate volume supply contracts for mass-market electric vehicles. LG Energy Solution differentiates through high-nickel chemistry leadership and dedicated joint ventures with premium automotive OEMs. Samsung SDI anchors its position in cylindrical formats for power tools and premium consumer electronics where cycle stability commands price premiums.
Battery technology encompasses electrochemical energy storage systems comprising cathode, anode, electrolyte, and separator materials engineered to reversible redox reactions with specified voltage windows, energy densities, and cycle-life thresholds. These systems store and discharge electrical energy for motive, stationary, and portable power applications across industrial and consumer contexts. Lithium-ion chemistry occupies the dominant margin pool given its scale economies and established recycling infrastructure, while solid-state technology represents the fastest-advancing segment as manufacturers resolve ceramic-electrolyte manufacturing yields. Flow batteries compete in long-duration renewable energy storage where discharge duration requirements exceed lithium-ion cost-effectiveness thresholds.
China's MIIT enforces GB standards for cell safety and recycling traceability, while the EU Battery Regulation mandates carbon-footprint declarations and recycled-content minimums that reshape supply-chain sourcing for European-bound production. The US IRA production tax credits for domestic cell and module manufacturing are redirecting capital-location decisions across the supplier base. Stakeholders must monitor regulatory divergence on chemistry restrictions, recycling mandates, and local-content thresholds as these frameworks harden into definitive compliance costs rather than transitional incentives.
Market Dynamics
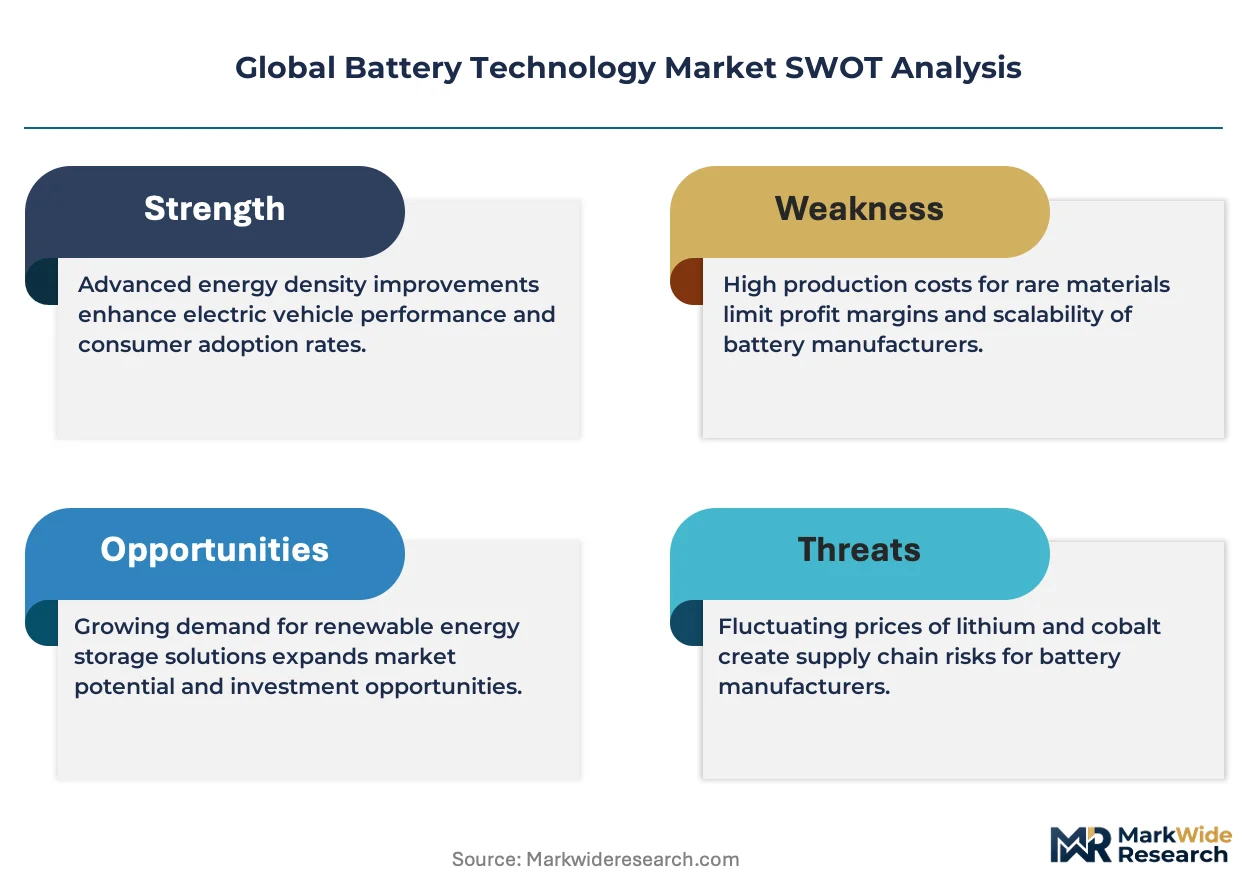
Fleet electrification mandates across major economies are compressing development cycles and forcing chemistry choices years ahead of technical maturity, locking supply chains into high-volume commitments before next-generation formats achieve manufacturing yields.
Growth Catalysts
- US IRA Production Tax Credits:Domestic cell and module manufacturing incentives are redirecting capital-location decisions across the supplier base, accelerating localized supply chain buildouts.
- Silicon-Anode Integration:Higher energy density anode materials are extending vehicle range thresholds and reducing pack count requirements for equivalent performance.
- China:GB standards enforcement for cell safety and recycling traceability is standardizing quality baselines and enabling scaled secondary material recovery.
Market Restraints
- Lithium Price Volatility:Spodumene and brine concentrate cost swings transmit directly into cell bill-of-materials, compressing margin visibility for long-dated supply contracts.
- Technical Limitation:Ceramic-electrolyte manufacturing yields remain below commercial thresholds, delaying solid-state volume timelines.
- Substitution Threat:Sodium-ion chemistry is capturing two-wheeler and stationary storage applications where energy density requirements permit lower-cost alternatives.
Strategic Opportunities
- India:PLI scheme incentives for advanced chemistry cell manufacturing are attracting first-mover investments before domestic demand matures.
- Long-Duration Storage:Vanadium and iron-chromium flow batteries are penetrating renewable energy storage where discharge duration exceeds lithium-ion cost-effectiveness thresholds.
- EU Battery Regulation:Carbon-footprint declarations and recycled-content minimums are creating compliance-driven demand for traceable, low-carbon supply chains.
Industry Challenges
- Electrolyte Formulation Talent:Scarcity of experienced solid-state ceramic processing engineers is constraining pilot-to-production scaling timelines.
- Gigafactory Capex Intensity:Dry electrode coating and formation equipment requirements demand multi-billion-dollar commitments before revenue generation.
- Standardization Delays:Divergent cell format specifications across automotive OEMs prevent module-level interchangeability and fragment tooling investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Battery Technology Market |
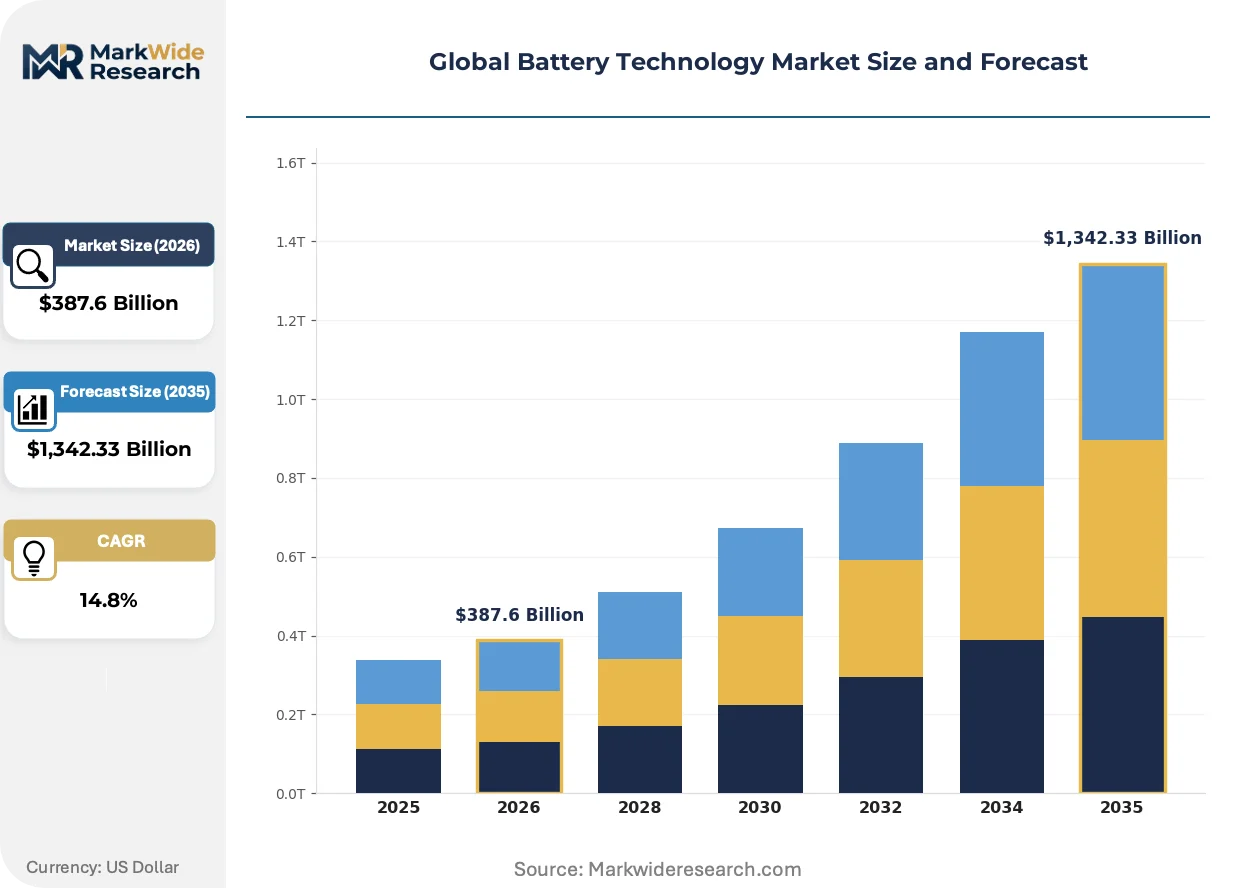
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $1,342.33 Billion |
| CAGR (2026 – 2036) | 14.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-ion, Nickel-cadmium, Lead-acid, Flow Batteries Application: Electric Vehicles, Consumer Electronics, Renewable Energy Storage, Industrial Equipment End User: Automotive OEMs, Telecom Companies, Electronics Manufacturers, Utility Providers Technology: Solid-state, Hybrid, Smart Battery Systems, Battery Management Systems |
| Companies Covered | CATL, LG Energy Solution, Panasonic Holdings Corporation, BYD, Samsung SDI, SK Innovation, GS Yuasa Corporation, EVE Energy Co., Ltd., Solid Power, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Battery Technology Market Emerging Trajectories
Solid-state chemistry breakthroughs are compressing the performance gap between laboratory demonstrations and manufacturing viability, while regulatory frameworks harden compliance requirements faster than supply chains can adapt.
Silicon-anode composites are rewriting the energy density ceiling for lithium-ion systems. Automotive OEMs are qualifying these materials for 2026-2027 model year platforms, accepting cycle-life tradeoffs for range extension. This chemistry shift is compressing cobalt and nickel loading requirements per vehicle, altering upstream metal offtake structures.
The EU Battery Regulation mandates carbon-footprint declarations and recycled-content minimums for European-bound production. Industrial consequence includes forced supply-chain reconfiguration toward traceable, low-carbon lithium sources and certified recycling streams. High-nickel cathode producers are most affected, accelerating partnerships with European recycling operators to secure compliant secondary material flows.
Fleet procurement departments are consolidating cell supply contracts around performance-guarantee structures rather than unit pricing. Direct OEM-battery maker partnerships are displacing tiered distributor networks in automotive and heavy-duty segments. Germany and the United States exhibit this pattern most visibly, where electrification mandates have centralized buying authority within sustainability and engineering functions.
Global Battery Technology Market Segmentation
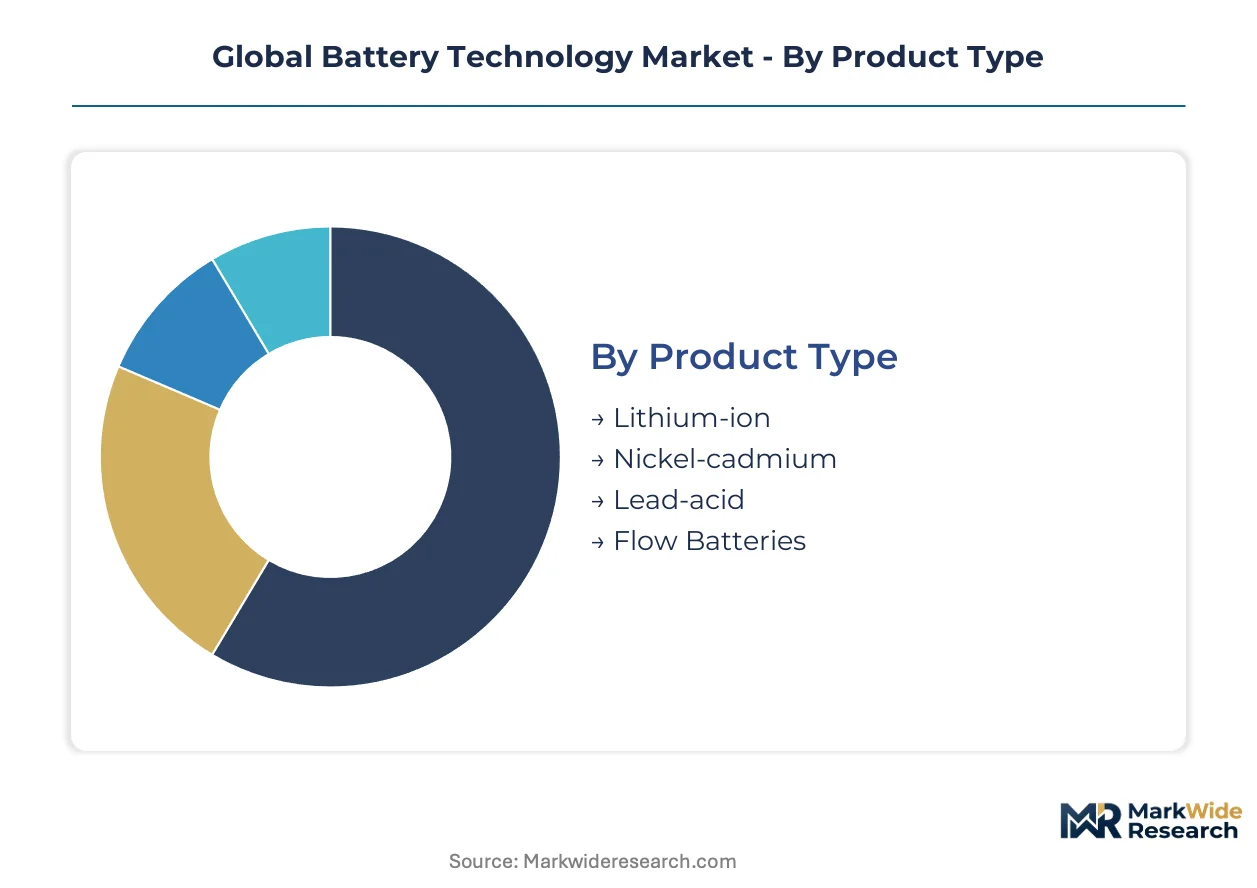
Battery technology markets fragment across electrochemical systems, end-use applications, and integration architectures. Procurement strategies diverge sharply between automotive volume contracts and industrial specialty orders. Technology choices made today lock supply chains into decade-long manufacturing commitments.
Product Type:
Supply concentration tilts dramatically toward lithium-ion, with cathode active material refiners and cell assemblers clustering in East Asian manufacturing corridors.
- Lithium-ion:Dominant electrochemistry utilizing intercalation compounds at cathode and graphite or silicon composites at anode. Electric vehicle manufacturers in Germany, China, and the United States now specify cell formats years ahead of delivery, compressing supplier qualification windows and locking cathode chemistry commitments.
- Flow Batteries:Redox-active species stored in external electrolyte tanks enable independent scaling of power and energy capacity. Utility providers in Australia and California deploy vanadium systems for 8-12 hour discharge durations where lithium-ion degradation economics fail.
- Lead-acid:Mature flooded and valve-regulated designs serve telecom backup power and starter-lighting-ignition functions where cost sensitivity outweighs energy density requirements.
- Nickel-cadmium:Aircraft and rail applications retain this chemistry for extreme temperature tolerance and mechanical durability despite cadmium toxicity restrictions under EU REACH.
Today's leader: Lithium-ion. Tomorrow's challenger: Flow Batteries.
Application:
Cost tier differentiation separates premium automotive packs from commodity stationary installations, with cell grading and warranty structures tracking this divide.
- Electric Vehicles:Traction battery packs integrate thermal management, structural enclosures, and battery management electronics. Fleet electrification mandates in California, the United Kingdom, and Norway force OEMs into multi-gigawatt-hour supply contracts before next-generation solid-state formats achieve manufacturing yields.
- Renewable Energy Storage:Grid-scale installations buffer intermittency from wind and solar generation. China's State Grid and Germany's transmission operators specify 4-hour duration systems for frequency regulation, driving lithium iron phosphate chemistry dominance in this segment.
- Consumer Electronics:Cylindrical and pouch formats power smartphones, laptops, and wearables where volumetric energy density commands price premiums.
- Industrial Equipment:Forklifts, mining vehicles, and port machinery convert from lead-acid to lithium-ion for opportunity charging and reduced maintenance downtime.
Electric Vehicles anchor current revenue concentration. Renewable Energy Storage offers the steepest expansion trajectory as capacity markets remunerate duration.
End User:
Volume concentration among automotive OEMs creates procurement power asymmetries that reshape supplier margin structures.
- Automotive OEMs:Direct cell supply contracts now displace tiered distributor networks. Volkswagen, Tesla, and BYD negotiate performance-guarantee structures covering cycle life, degradation curves, and thermal runaway liability.
- Utility Providers:Battery energy storage system procurement emphasizes availability guarantees and long-term service agreements over upfront capital cost.
- Electronics Manufacturers:Consumer device brands qualify multiple cell vendors per product line to mitigate supply disruption risk.
- Telecom Companies:Tower operators standardize on lithium-ion backup systems to reduce diesel generator runtime and fuel logistics costs in India and Southeast Asia.
Automotive OEMs currently dictate cell format roadmaps. Utility Providers are gaining procurement sophistication fastest as storage becomes core grid infrastructure.
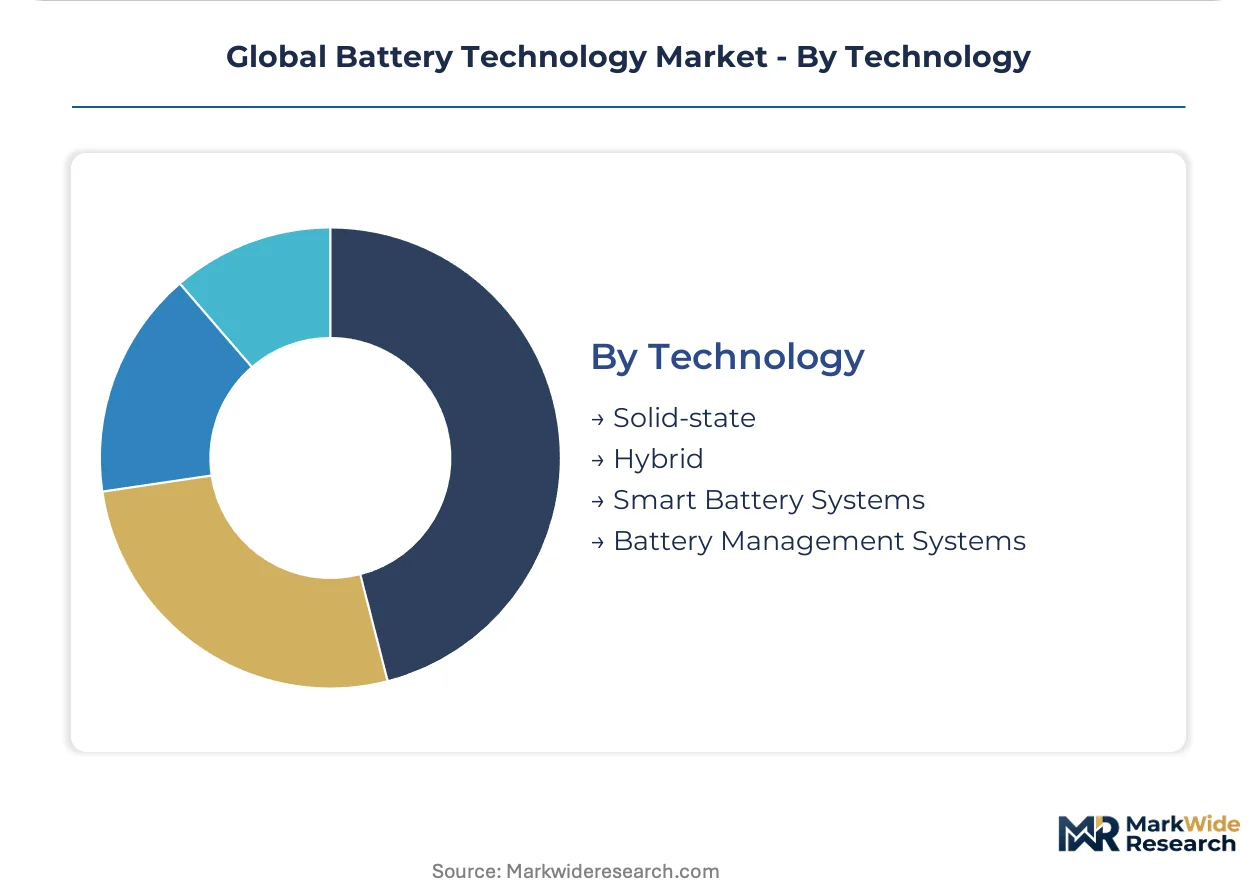
Technology:
Integration depth separates component suppliers from system architects, with value capture shifting toward battery management intelligence and thermal engineering.
- Solid-state:Ceramic or sulfide electrolytes replace flammable liquid electrolytes, enabling lithium-metal anodes with theoretical energy density doubling current lithium-ion. Toyota and QuantumScape target automotive qualification timelines contingent on manufacturing yield breakthroughs.
- Battery Management Systems:Cell-level voltage and temperature monitoring, state-of-charge estimation algorithms, and contactor control electronics differentiate pack performance and safety. Silicon Valley and Tel Aviv software specialists compete with automotive Tier-1 suppliers for this embedded systems layer.
- Smart Battery Systems:Communication-enabled packs report health status to cloud platforms, enabling predictive maintenance and second-life routing.
- Hybrid:Dual-chemistry architectures combine power-optimized and energy-optimized cells within single installations.
Battery Management Systems dominate current value-added capture. Solid-state represents the most consequential technology transition risk for incumbent supply chains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized electrochemical engineers and ceramic processing talent cluster in East Asian manufacturing corridors and German industrial regions, anchoring cell production and next-generation solid-state development. These workforce concentrations determine where capital deploys and which regulatory frameworks shape operational compliance.
China
Electric vehicle fleet mandates and grid-scale storage procurement drive cell demand across multiple provinces. MIIT enforces GB standards for safety certification and recycling traceability that standardize quality baselines. The Yangtze River Delta hosts gigafactory clusters where CATL and BYD operate integrated cathode-to-cell facilities.
Germany
Premium automotive OEM electrification timelines compress supplier qualification windows for high-nickel chemistry packs. The EU Battery Regulation mandates carbon-footprint declarations and recycled-content minimums that reshape sourcing decisions. North Rhine-Westphalia and Lower Saxony concentrate cell manufacturing joint ventures between domestic OEMs and Asian suppliers.
United States
IRA production tax credits redirect capital-location decisions toward domestic cell and module manufacturing. FERC interconnection reforms and state-level storage mandates accelerate utility-scale procurement. The Great Lakes region and Texas attract gigafactory investments where SK Innovation and LG Energy Solution anchor localized supply chain buildouts.
South Korea
Cylindrical format dominance in power tools and premium consumer electronics sustains specialized cell demand. METI-aligned industrial policy supports materials science research consortia advancing silicon-anode integration. Seoul Capital Area and Busan-Ulsan corridor host Samsung SDI and SK Innovation facilities serving automotive and industrial segments.
Japan
Conservative automotive qualification standards prioritize cycle stability and thermal safety over energy density maximization. METI funding programs target solid-state manufacturing yield improvements through ceramic-electrolyte processing advances. Kansai region research clusters around Osaka and Kyoto maintain foundational materials science expertise for next-generation formats.
Global Battery Technology Market Vendor Landscape
Top-tier vendors anchor high-volume automotive supply contracts, while mid-tier specialists occupy industrial and consumer electronics niches. The supplier base stratifies around cathode chemistry expertise, integrated lithium refining capabilities, and cylindrical versus prismatic format specialization. Three archetypes dominate: integrated materials-to-cells conglomerates, technology-licensing pure-plays, and automotive-captive joint ventures. Competitive moves center on backward integration into lithium refining and formation equipment capacity expansion.
Within the integrated conglomerate tier, CATL and BYD exemplify upstream control over lithium refining and cathode active material production. LG Energy Solution occupies a position representing high-nickel chemistry leadership and premium automotive OEM partnerships. Samsung SDI anchors the cylindrical format specialization archetype where cycle stability commands price premiums in power tools and consumer electronics.
| Leading Market Players |
|---|
| CATL |
| LG Energy Solution |
| Panasonic Holdings Corporation |
| BYD |
| Samsung SDI |
| SK Innovation |
| GS Yuasa Corporation |
| EVE Energy Co., Ltd. |
| Solid Power |
| Others |
Supply Flow & Price Mechanics
Fleet procurement departments consolidating around performance-guarantee structures rather than unit pricing force suppliers to absorb technical risk and warranty costs, compressing margin visibility for long-dated supply contracts while rewarding integrated manufacturers with captive lithium refining and cathode production.
Pricing Analysis
Cell supply contracts bundle formation cycling, warranty coverage, and technical support into long-term offtake agreements rather than transactional spot purchases. Price differentiation tracks cathode chemistry grade and automotive OEM certification tier, with high-nickel cells commanding premiums over lithium iron phosphate alternatives. Cost compression in commodity-grade stationary storage intensifies as sodium-ion chemistry captures two-wheeler and grid-buffer applications. Automotive OEMs exhibit the lowest price sensitivity given electrification mandate deadlines, while utility providers negotiate hardest on upfront capital cost.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Los Angeles warehouse cathode active materials and electrolyte salts for just-in-time delivery to gigafactory formation lines. Manufacturing concentration centers on China, South Korea, and Japan, where integrated lithium refining and separator production cluster in Yangtze River Delta and Seoul Capital Area corridors. The supply chain rests on spodumene concentrate from Australia, cobalt hydroxide from the DRC, and synthetic graphite from China. Single-source vulnerability in ceramic-electrolyte precursor materials constrains solid-state pilot-to-production scaling. Distribution runs through direct OEM partnerships displacing tiered distributor networks in automotive and heavy-duty segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in battery technology hinges on silicon-anode integration reducing cobalt and nickel loading per vehicle, enabling premium-tier pricing for range-extended packs while commodity-grade lithium iron phosphate faces sodium-ion substitution pressure.
For Market Incumbents: Anchor high-volume automotive contracts through backward integration into lithium refining and cathode active material production, mirroring CATL and BYD's integrated model. Defend against solid-state disruption by accelerating ceramic-electrolyte manufacturing yield improvements through partnerships with Japanese materials science clusters. Prioritize capacity addition in the US Great Lakes region and Germany's North Rhine-Westphalia to capture IRA and EU Battery Regulation compliance premiums. For New Entrants and Emerging Players: Industrial equipment OEMs represent the most penetrable white-space target as forklifts, mining vehicles, and port machinery convert from lead-acid to lithium-ion for opportunity charging. India's PLI scheme for advanced chemistry cell manufacturing offers first-mover positioning before domestic electric vehicle demand matures. Pursue go-to-market angles through aftermarket service networks rather than direct automotive qualification given compressed supplier windows and multi-year OEM lock-in periods. For Investors and Strategic Acquirers: Asymmetric upside sits with solid-state technology pure-plays resolving ceramic-electrolyte manufacturing yields, contingent on Toyota and QuantumScape qualification timelines. Long-term viability over the projection horizon favors acquisition targets with captive lithium refining and certified recycling stream partnerships to meet EU Battery Regulation recycled-content minimums. Watch ceramic-electrolyte precursor material supply constraints as the inflection indicator for solid-state volume commercialization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lithium Refining | CATL and BYD's captive supply of spodumene concentrate secures margin control against price volatility. |
| Solid-State Manufacturing Yield Improvement | Toyota's ceramic-electrolyte processing advances determine next-generation format commercialization timelines. |
| EU Battery Regulation Compliance Partnership | High-nickel cathode producers partnering with European recyclers secure traceable secondary material flows. |
| Silicon-Anode Composite Qualification | Automotive OEMs accepting cycle-life tradeoffs for range extension rewrite energy density ceilings. |
| US IRA Production Tax Credit Capture | LG Energy Solution and SK Innovation's Great Lakes gigafactories redirect capital-location decisions. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with cell manufacturing executives, automotive OEM platform engineers, utility procurement officers, and cathode material R&D directors with secondary validation against MIIT GB standards filings, EU Battery Regulation implementation guidance, US IRA tax credit guidance documents, and SEC 10-K disclosures from listed battery manufacturers. Bottom-up cell production capacity modeling and top-down electric vehicle fleet penetration scenarios were triangulated against trade data from Chinese customs and Korean export statistics.
Segment-weighting approaches applied differential growth assumptions across lithium-ion, flow battery, and solid-state technology trajectories, with cathode chemistry splits, end-use application shares, and regional manufacturing capacity distributions modeled throughout the forecast period. CAGRs were derived from installed base growth, replacement cycle compression, and technology substitution curves. Forecast inputs included silicon-anode integration timelines, solid-state manufacturing yield improvement rates, and fleet electrification mandate compliance deadlines across California, the United Kingdom, and Norway.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ceramic-electrolyte manufacturing yield breakthroughs, lithium price volatility from spodumene and brine concentrate markets, and divergent regulatory frameworks on recycling mandates and local-content thresholds. Forecasts reflect documented assumptions around technology adoption curves and policy implementation fidelity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Infrastructure
Automatic Battery Manufacturing Equipment Market
Battery Infrastructure
India Electric Vehicle Battery Separator Market
Battery Infrastructure
Battery Production Machine Market
Battery Infrastructure
Smart Battery Swap Station Market
Battery Infrastructure
China Battery Manufacturing Equipment Market
Battery Infrastructure
EV Battery Sealant Market
Battery Infrastructure
Middle East and Africa Electric Vehicle Battery Separator Market
Battery Infrastructure
ASEAN Countries Electric Vehicle Battery Manufacturing Equipment Market
Battery Infrastructure
Battery Swap-Ready Pack Systems for Urban Fleets Market
Battery Infrastructure
North America Electric Vehicle Battery Electrolyte Market
Battery Infrastructure
China Electric Vehicle Battery Manufacturing Equipment Market
Battery Infrastructure
China Electric Vehicle Battery Separator Market
Battery Infrastructure
Electric Vehicle Battery Swapping Market
Battery Infrastructure
Global Battery Packaging Market
Battery Infrastructure
Europe Lithium Foil Market
Battery Infrastructure
South America Electric Vehicle Battery Separator Market