
 Diesel Fuel Water Separator Market | 2026-2036
Diesel Fuel Water Separator Market Size, Share, and Industry Trends Forecast 2026-2036
Diesel Fuel Water Separator Market Analytics
Advanced synthetic filter media is hardening as the dominant material platform, displacing traditional cellulose elements in high-duty marine and automotive applications. Cummins Filtration leverages captive engine OEM relationships to sustain pull-through demand for integrated separator systems. Donaldson Company anchors its position through aftermarket channel density across North American construction and agriculture fleets. MANN+HUMMEL Group competes on modular platform architectures that span automotive and industrial end uses with minimal re-tooling.
A diesel fuel water separator is a filtration device engineered to extract free and emulsified water from diesel fuel through coalescence, centrifugal force, or gravity differential, typically achieving water removal efficiency above 95 percent at rated flow conditions. Its primary industrial purpose is to protect high-pressure common-rail fuel injection systems from corrosion, cavitation, and injector failure caused by water contamination. Coalescing filters command the largest installed base due to proven reliability across variable fuel qualities, while centrifugal separators represent the fastest-growing technology category in marine and stationary power applications where continuous-duty operation justifies higher capital outlay. Onboard installation systems generate the densest margin pools in the automotive and marine segments, whereas stationary industrial systems exhibit slower replacement cycles but longer contract durations.
The United States Coast Guard enforces fuel system integrity standards for commercial vessels that directly mandate water separator certification under 46 CFR subchapter requirements. EPA nonroad diesel Tier 4 emission regulations tighten fuel cleanliness tolerances, forcing construction and agricultural equipment operators to upgrade separator specifications. China's MIIT implements GB standards for diesel fuel quality that cascade into aftermarket separator demand across commercial vehicle parc. Stakeholders must monitor regulatory divergence between marine MARPOL Annex VI enforcement zones and land-based emission regimes, as compliance gaps create product specification fragmentation that favors regionally adaptive suppliers over standardized global platforms.
Market Dynamics
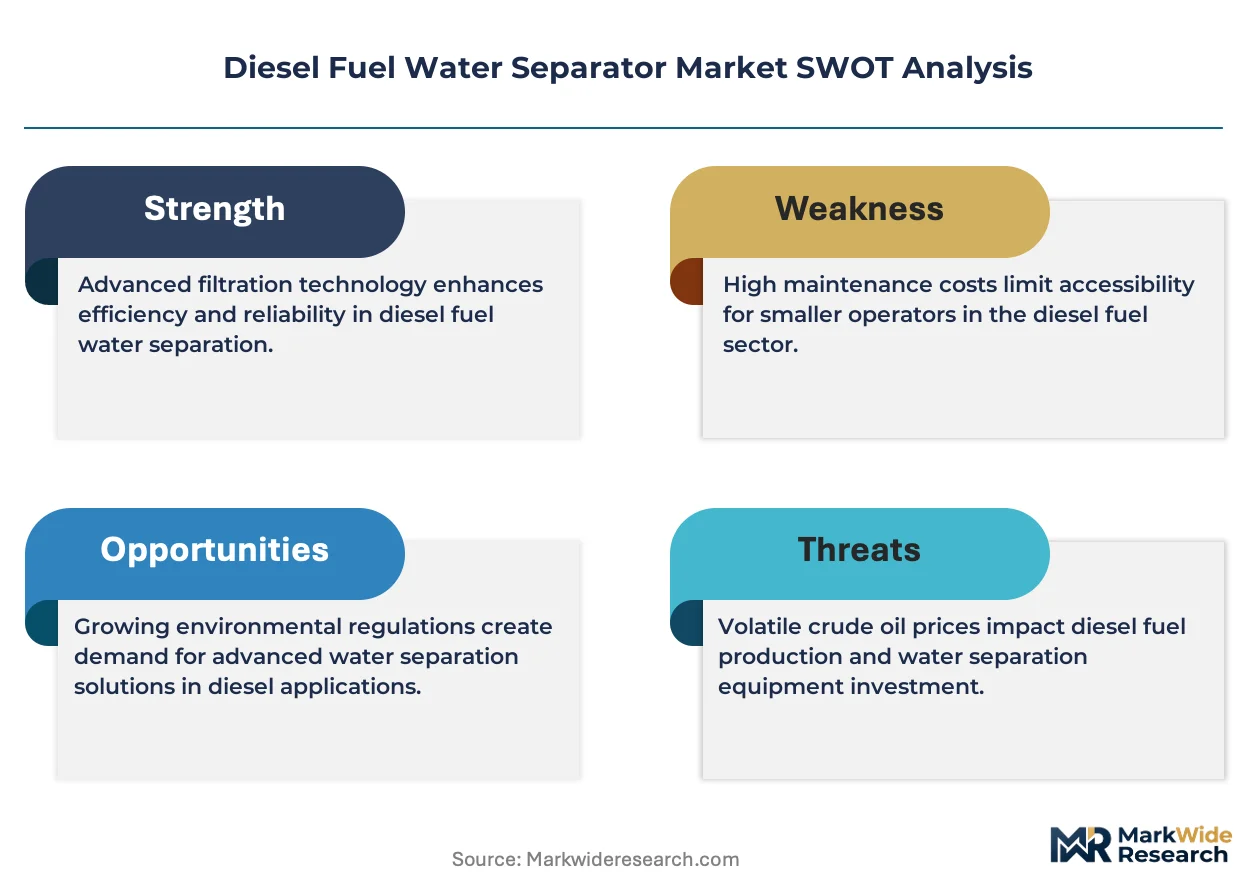
Synthetic filter media is absorbing capital and engineering talent at the expense of cellulose legacy platforms, compressing incumbent margins while rewarding material science investments. MARPOL Annex VI enforcement intensity in European and Asian port states is forcing fleet-wide retrofits that favor certified separator architectures over unbranded alternatives.
Growth Catalysts
- Marine MARPOL mandates:Port state control inspections in Hamburg, Singapore, and Long Beach are rejecting bunkered fuel with excessive water content, compelling vessel operators to install certified coalescing systems.
- High-pressure common-rail proliferation:Modern diesel injection systems operate at 2,000+ bar pressures where water-induced cavitation destroys injectors within hours, making separator redundancy non-negotiable.
- China's GB 19147 diesel quality standards:MIIT enforcement of particulate and water content limits is cascading into aftermarket demand across the country's commercial vehicle parc.
Market Restraints
- Specialized polymer supply concentration:Advanced coalescing media relies on fluoropolymer and glass fiber feedstocks concentrated among German and Japanese chemical suppliers, exposing filter manufacturers to input cost volatility.
- Centrifugal separator capex thresholds:Continuous-duty marine and power generation applications require capital outlays three to five times higher than coalescing cartridges, limiting adoption to large fleet operators.
- Regional certification fragmentation:Divergent USCG, EU MED, and China Classification Society approval timelines force suppliers to maintain parallel testing programs, inflating R&D overhead.
Strategic Opportunities
- Indian commercial vehicle aftermarket:BIS fuel quality enforcement remains patchy outside major metropolitan corridors, creating a whitespace for education-driven distributor partnerships.
- Remanufactured filter cores:Circular economy mandates under the EU Green Deal are opening regulatory space for refurbished coalescing elements with verified performance metrics.
- Digital condition monitoring integration:Water-in-fuel sensors paired with telematics platforms enable predictive maintenance contracts that shift revenue from product sales to subscription services.
Industry Challenges
- Coalescence engineering talent scarcity:The intersection of polymer chemistry, fluid dynamics, and filtration physics commands premium compensation, constraining mid-tier suppliers' R&D staffing.
- Legacy fuel system integration:Retrofit installations in aging marine and construction fleets require custom mounting adaptations that erode standardization economies.
- ISO 16332 test protocol compliance:Third-party certification to the water separation efficiency standard demands six-to-twelve-month validation cycles that delay product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diesel Fuel Water Separator Market |
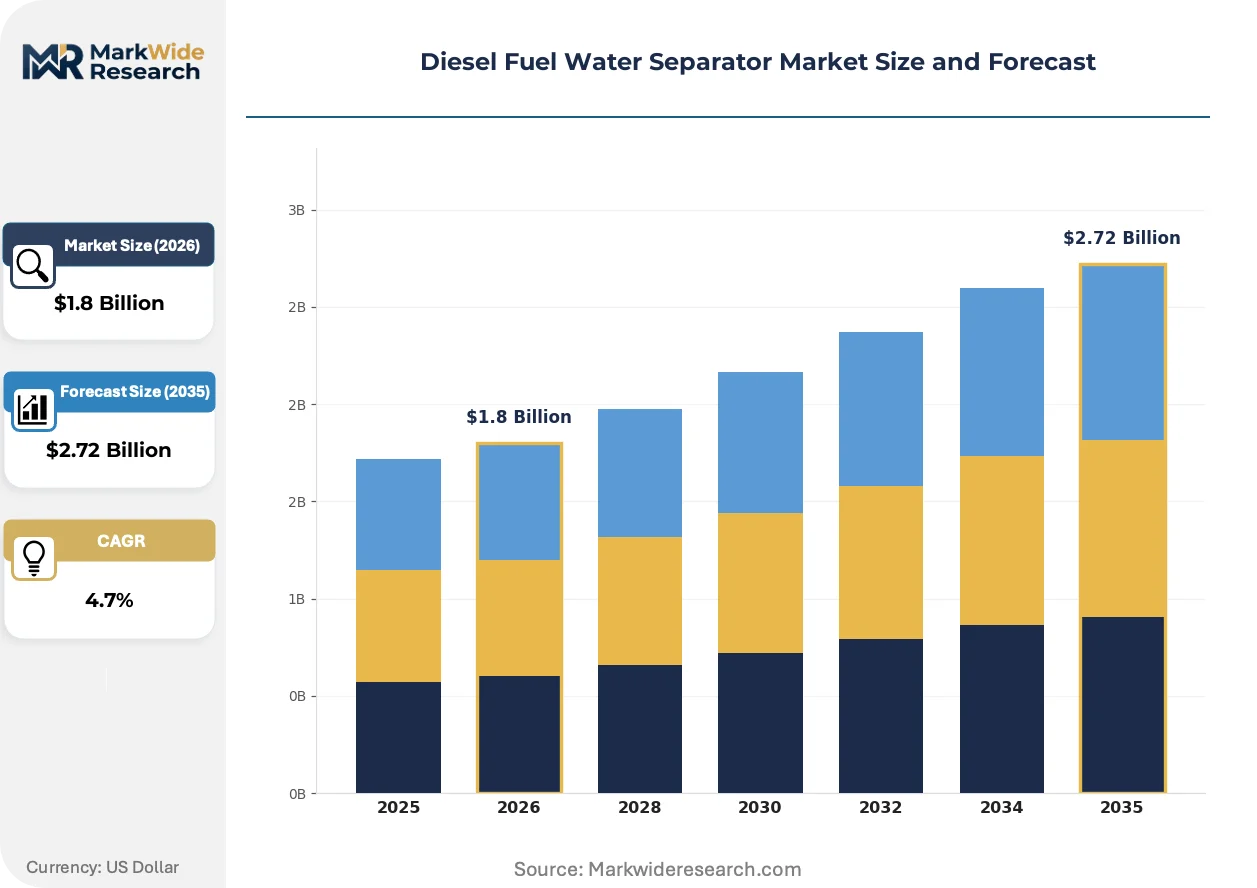
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coalescing Filters, Centrifugal Separators, Vacuum Separators, Gravity Separators Technology: Automatic, Manual, Hybrid, Pre-Filter Installation: Onboard Systems, Stationary Systems, Mobile Systems, Industrial Systems End User: Marine, Automotive, Industrial, Construction |
| Companies Covered | Parker Hannifin Corporation, Cummins Filtration, MANN+HUMMEL Group, Donaldson Company Inc., Robert Bosch GmbH, MAHLE GmbH, Denso Corporation, Alfa Laval, Pall Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diesel Fuel Water Separator Market Evolving Landscape
Material science breakthroughs and regulatory enforcement digitization are converging to redefine separator performance benchmarks and procurement patterns. The competitive frontier is shifting from static filtration efficiency toward dynamic, data-integrated fuel quality management.
Multilayer synthetic media incorporating nanofiber surface layers is absorbing the functional role previously served by depth-loading cellulose matrices. Off-highway construction equipment OEMs in Germany and the United States are specifying these architectures for Tier 4 final engines. The technology is absorbing service interval extension claims that now stretch to 1,500 operating hours, compressing aftermarket revenue per unit while locking in platform loyalty.
The EPA's nonroad diesel Tier 4 emission regulations have tightened fuel cleanliness tolerances to ISO 4406 18/16/13 levels, forcing separator specification upgrades across construction and agricultural equipment. Equipment lessors in the US Midwest are now rejecting rental returns with non-compliant filtration histories. The policy is reshaping fleet procurement toward integrated OEM-branded systems over aftermarket alternatives.
Marine operators are consolidating separator procurement under fleet-level framework agreements that bundle hardware, consumables, and sensor-based monitoring. Greek and Singaporean tanker owners have pioneered this model, displacing port-by-port spot purchasing. The shift concentrates supplier relationships among vertically integrated filtration specialists with global service networks.
Diesel Fuel Water Separator Market Segmentation
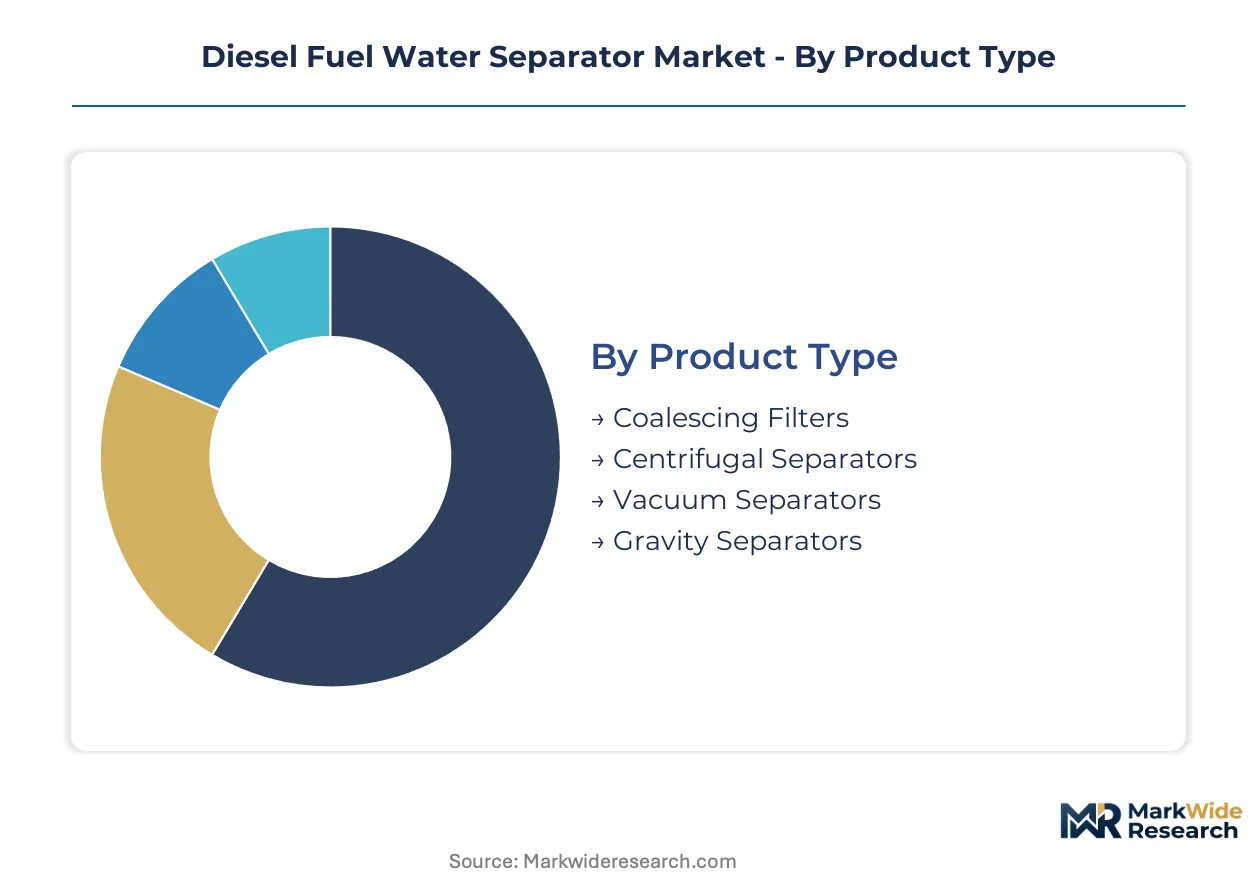
Segmentation in the diesel fuel water separator market reflects divergent buyer priorities across duty cycles, regulatory exposure, and maintenance capabilities. Procurement patterns split sharply between operators seeking lowest lifecycle cost versus those prioritizing compliance certification and uptime guarantees.
Product Type:
Buyers select filtration architecture based on fuel contamination severity, operating hours intensity, and capital recovery timelines.
- Coalescing Filters:Multilayer synthetic media stacks achieve 95%+ water removal efficiency through progressive droplet agglomeration. Marine operators in Hamburg, Singapore, and Long Beach specify these for MARPOL compliance under port state control scrutiny.
- Centrifugal Separators:Continuous rotational separation handles high-volume fuel streams without consumable media replacement. Stationary power generation installations in Germany absorb the steepest adoption trajectory despite three-to-five-fold capital premiums over cartridge systems.
- Vacuum Separators:Reduced-pressure boiling extraction targets emulsified water in cold-climate operations where coalescence efficiency degrades.
- Gravity Separators:Passive density differential settling serves low-throughput backup systems and emergency bypass configurations.
Coalescing filters lead on installed base scale; centrifugal separators lead on technology momentum.
Technology:
Automation intensity correlates directly with fleet size and labor cost structures, separating owner-operator preferences from institutional procurement.
- Automatic:Sensor-actuated drain valves and self-monitoring pressure differentials eliminate manual inspection intervals. US construction fleets under EPA Tier 4 enforcement specify these for warranty compliance on high-pressure common-rail engines.
- Manual:Operator-initiated drain cycles and visual bowl inspection suit low-utilization equipment where labor substitution outweighs downtime risk.
- Hybrid:Automated monitoring with manual override capability bridges cost-sensitive segments transitioning toward full automation.
- Pre-Filter:Coarse straining upstream of primary separation extends main element service life in high-particulate fuel environments.
Automatic systems dominate new equipment specification; hybrid configurations gain fastest in retrofit applications.
Installation:
Mounting configuration determines margin structure through replacement frequency, service contract attachment rates, and sensor integration potential.
- Onboard Systems:Engine-compartment or frame-rail integration in vehicles and vessels generates densest aftermarket revenue through high-turnover filter elements. Chinese commercial vehicle OEMs specify these for GB 19147 compliance.
- Stationary Systems:Fixed-base installations in power generation and marine bunkering exhibit extended replacement cycles but lock in multi-year consumables contracts.
- Mobile Systems:Skid-mounted or trailer configurations serve temporary fuel polishing at construction sites and emergency response operations.
- Industrial Systems:Bulk fuel storage tank farms and pipeline terminals deploy high-flow manifolded arrays with centralized monitoring.
Onboard installations concentrate revenue volume; stationary systems concentrate contract duration.
End User:
Regulatory enforcement intensity and equipment replacement velocity create divergent customer lifetime value profiles across verticals.
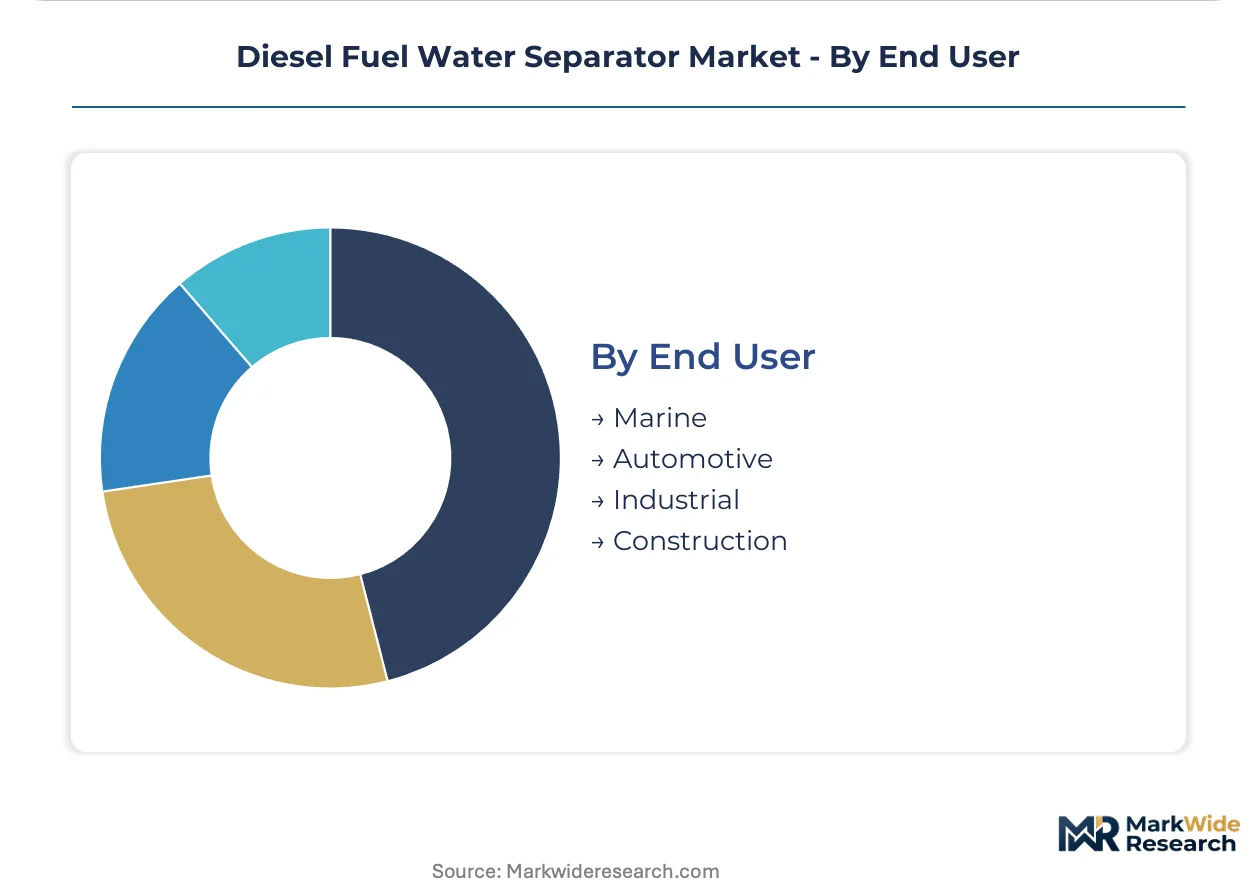
- Marine:IMO MARPOL Annex VI port state control drives fleet-wide retrofit demand. Greek and Singaporean tanker owners consolidate procurement under framework agreements bundling hardware, sensors, and predictive maintenance.
- Automotive:High-pressure common-rail proliferation at 2,000+ bar injection pressures makes separator redundancy mandatory. German and US commercial vehicle OEMs integrate certified systems at factory assembly.
- Industrial:Stationary diesel power generation and mining operations prioritize continuous-duty reliability over first cost.
- Construction:Equipment lessors in the US Midwest now reject rental returns with non-compliant filtration histories, reshaping fleet specification toward OEM-branded integrated systems.
Marine and automotive segments concentrate premium system demand; construction accelerates fastest on regulatory tightening.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Hamburg port cluster anchors global marine separator demand as vessel operators retrofit fleets to meet MARPOL fuel-quality mandates. Commercial fleet density and enforcement intensity intersect across Germany, China, and the United States.
United States
Construction equipment lessors in the Midwest reject rental returns with non-compliant filtration histories, forcing fleet-wide specification upgrades. EPA nonroad diesel Tier 4 regulations tighten fuel cleanliness tolerances to ISO 4406 18/16/13 levels. The US Coast Guard enforces 46 CFR subchapter requirements for commercial vessel fuel system integrity certification.
Germany
Off-highway OEMs specify multilayer synthetic media architectures for Tier 4 final engines, extending service intervals to 1,500 operating hours. KBA enforcement of EU MED certification timelines shapes product development cycles. Bavaria-based filtration specialists concentrate R&D talent for coalescence engineering at the polymer chemistry-fluid dynamics intersection.
China
MIIT implementation of GB 19147 diesel quality standards cascades into aftermarket demand across the commercial vehicle parc. Shanghai and Guangzhou port state control inspections reject bunkered fuel with excessive water content. Domestic OEMs integrate onboard separator systems at factory assembly for GB compliance.
Singapore
Tanker owners consolidate procurement under fleet-level framework agreements bundling hardware, consumables, and sensor-based monitoring. The Maritime and Port Authority enforces MARPOL Annex VI compliance through rigorous bunkering inspections. Greek and Singaporean fleet operators pioneer predictive maintenance contracts that shift revenue from product sales to subscription services.
India
BIS fuel quality enforcement remains patchy outside major metropolitan corridors, creating whitespace for education-driven distributor partnerships. Maharashtra and Gujarat commercial vehicle hubs absorb initial aftermarket penetration as awareness campaigns target fleet operators. The country's national standards body gradually extends certified separator specifications to secondary cities.
Diesel Fuel Water Separator Market Competitive Landscape
Global majors compete with regional champions across certification regimes and aftermarket channel density. The vendor base separates into integrated engine OEM affiliates, standalone filtration specialists, and diversified industrial conglomerates. Three strategic archetypes dominate: captive engine suppliers leveraging factory-fit relationships; aftermarket channel owners maximizing service contract attachment; and modular platform architects spanning multiple end-use verticals. Competitive moves concentrate on M&A for geographic footprint and strategic partnerships for sensor-telemetry integration.
Within the integrated OEM tier, Cummins Filtration exemplifies captive engine affiliate positioning through factory-fit pull-through demand. Donaldson Company anchors the aftermarket channel density archetype across North American construction and agriculture fleets. MANN+HUMMEL Group occupies the modular platform position, competing on architectures that span automotive and industrial end uses with minimal re-tooling.
| Leading Market Players |
|---|
| Parker Hannifin Corporation |
| Cummins Filtration |
| MANN+HUMMEL Group |
| Donaldson Company Inc. |
| Robert Bosch GmbH |
| MAHLE GmbH |
| Denso Corporation |
| Alfa Laval |
| Pall Corporation |
| Others |
Value Network & Pricing Analysis
Fluoropolymer resin indices from German and Japanese chemical suppliers cascade directly into tiered pricing structures for coalescing filter media, compressing margins on standard-grade cellulose alternatives while amplifying premiums on synthetic multilayer architectures certified to ISO 16332.
Pricing Analysis
Input-cost pass-through from specialized polymer feedstocks drives pricing stratification across premium, standard, and economy tiers. Premium synthetic media commands certification-grade margins for MARPOL-compliant marine applications, while economy cellulose cartridges face price erosion from Chinese aftermarket imports. Construction equipment lessors in the US Midwest exhibit acute price sensitivity on replacement cycles, whereas Greek tanker owners prioritize uptime guarantees over unit cost.
Supply Chain Analysis
Freight cost volatility on Asia-Europe routes strains inventory positioning for German and Chinese filter manufacturers serving marine retrofit demand. Fluoropolymer supply concentrates among Japanese and German chemical producers, while glass fiber media draws from US and Chinese sources. Single-source vulnerability in specialty polymer grades exposes manufacturers to input disruption. Distribution runs through OEM captive channels for factory-fit systems and independent aftermarket distributors for replacement elements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The diesel fuel water separator market has entered a late-cycle quality phase where synthetic media certification and sensor-integrated monitoring separate viable suppliers from commodity players, as MARPOL enforcement and Tier 4 engine proliferation shift procurement toward premium specifications.
For Market Incumbents: Acquire coalescence engineering talent pools in Bavaria and Stuttgart to defend against material science disruptors. Secure backward integration into fluoropolymer media production to offset Japanese chemical supplier pricing power. Anchor factory-fit relationships with Cummins and MANN+HUMMEL through exclusive sensor-telemetry development programs. For New Entrants and Emerging Players: The 40-60% price-point gap between premium ISO-certified systems and unbranded economy cartridges opens whitespace in Indian commercial vehicle aftermarket. Target Maharashtra and Gujarat fleet operators with education-driven distributor partnerships before BIS enforcement extends to secondary cities. Lead with hybrid automatic-manual systems to bridge cost-sensitive retrofit demand. For Investors and Strategic Acquirers: Asymmetric upside sits with modular platform architects spanning automotive and marine verticals with minimal re-tooling. Five-to-ten-year viability favors suppliers with captive sensor-telemetry integration and multi-regional certification capabilities. Monitor port state control rejection rates in Hamburg and Singapore as inflection indicators for fleet-wide retrofit acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-Telemetry Integration | Parker Hannifin and Donaldson are embedding water-in-fuel sensors to enable predictive maintenance subscriptions. |
| Backward Integration into Synthetic Media | MANN+HUMMEL and Cummins Filtration are securing captive fluoropolymer supply chains against Japanese chemical concentration. |
| Multi-Regional Certification Investment | Alfa Laval and Pall Corporation are parallel-tracking USCG, EU MED, and China Classification Society approvals to compress launch timelines. |
| Remanufactured Filter Core Development | Donaldson and MAHLE are piloting EU Green Deal-compliant refurbished coalescing elements with verified performance metrics. |
| Fleet-Level Framework Agreements | Greek and Singaporean tanker owners are consolidating procurement under bundled hardware-consumables-monitoring contracts. |
Research Methodology
Direct dialogue with marine chief engineers, automotive OEM procurement directors, aftermarket distribution managers, and filtration R&D heads grounded the qualitative foundation. Secondary validation drew from EPA Tier 4 regulatory filings, USCG 46 CFR subchapter documentation, China MIIT GB standard releases, and ISO 16332 test protocol records. Bottom-up equipment parc analysis and top-down market sizing were triangulated against trade data from German, Chinese, and US customs authorities.
Bottom-up modeling segmented the market by filtration architecture, automation intensity, installation configuration, and end-use vertical across the projection horizon. CAGRs were derived from equipment replacement velocity, regulatory enforcement timelines, and technology substitution curves. Marine fleet retrofit pipelines, commercial vehicle production forecasts, and stationary power generation capacity additions served as industry-specific demand inputs.
Caveats apply where MARPOL enforcement intensity, fluoropolymer supply disruptions, or centrifugal separator technology breakthroughs could materially shift the outlook. Forecasts reflect assumptions about regulatory adherence rates and synthetic media cost trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Pyrolysis Gas Market
Fuels
Coal Trading Market
Fuels
Bituminous Coal Market
Fuels
China LNG Market
Fuels
India Retail Fuel Market
Fuels
Singapore Bunker Fuel Market
Fuels
Global Methane Hydrate Market
Fuels
Europe Defense Aircraft Aviation Fuel Market
Fuels
Diesel Fuel Market
Fuels
United Kingdom Bunker Fuel Market
Fuels
Ethyl Tertiary Butyl Ether Market
Fuels
City Gas Distribution Market
Fuels
Global Fuel Ethanol Market
Fuels
Bunker Fuel Market
Fuels
Saudi Arabia Automotive Fuels Market
Fuels
China Bunker Fuel Market