
 Smart Battery Swap Station Market | 2026-2036
Smart Battery Swap Station Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Battery Swap Station Market Insights
China is rewriting deployment economics for battery swap infrastructure through state-backed standardization and subsidized pilot zones. Nio Power leverages its proprietary battery pack architecture to sustain network exclusivity across premium electric vehicle segments. Gogoro anchors urban two-wheeler density in Taipei and expanding Southeast Asian metros through subscription-based energy access. Contemporary Amperex Technology Co., Limited competes via open-platform battery designs that enable interoperability across multiple automaker networks.
Smart battery swap stations are automated electromechanical systems that exchange depleted traction battery packs for charged units within three to five minutes, utilizing robotic alignment mechanisms, thermal management interfaces, and cloud-connected inventory tracking to eliminate charging downtime for electric vehicles. Stationary systems dominate current installed base due to higher throughput capacity and grid integration potential, while modular designs represent the fastest-expanding configuration as operators seek scalable capex deployment matched to utilization curves. Fleet managers constitute the most concentrated end-user margin pool, given their predictable route patterns and volume commitments that amortize station infrastructure across guaranteed swap transactions.
China's MIIT enforces GB standards for battery dimensional interchangeability, while the EU AI Act and CE marking frameworks govern automated swap robotics and grid-connected energy assets in European deployments. These regulatory architectures shape product certification pathways, cross-border equipment sourcing, and software liability allocation for unmanned station operations. Stakeholders must monitor evolving interoperability mandates, as jurisdiction-specific battery form factors and communication protocols determine whether platform strategies require regional customization or can achieve transnational scale.
Market Dynamics
China's MIIT is compressing deployment timelines through mandatory GB standards for battery dimensional interchangeability, forcing operators to accelerate capex commitments before compliance deadlines lock in market structure.
Growth Catalysts
- Urban Logistics Density:E-commerce delivery corridors in Ho Chi Minh City and Jakarta generate sufficient transaction volume to amortize station infrastructure within eighteen months.
- Dual Carbon Mandates:China's dual carbon goals channel state subsidies toward swap-enabled fleet electrification, reducing operator payback periods.
- Robotic Alignment Systems:Vision-guided positioning technology cuts swap duration below 180 seconds, matching liquid fuel refueling throughput.
Market Restraints
- Lithium Price Volatility:Battery pack inventory represents sixty percent of station capex, exposing operators to cathode material cost swings.
- Proprietary Form Factor Lock-in:Nio Power's exclusive battery architecture prevents cross-network utilization, fragmenting addressable density.
- Grid Connection Queues:Distribution utility interconnection timelines in dense urban zones delay commercial launch by eight to fourteen months.
Strategic Opportunities
- India's PLI Scheme:Production-linked incentives for advanced chemistry cell manufacturing reduce battery procurement costs for swap station operators.
- Interoperability Protocols:Open-platform battery designs enable multi-OEM network participation, expanding utilization rates.
- Renewable Coupling:Solar-plus-storage configurations at swap hubs reduce grid dependency and peak demand charges.
Industry Challenges
- Thermal Management Certification:UL 9540A cell-to-pack fire safety testing extends product validation cycles by four to six months.
- Robotics Integration Complexity:Automated swap mechanisms require specialized electromechanical technicians scarce in secondary metro labor pools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Battery Swap Station Market |
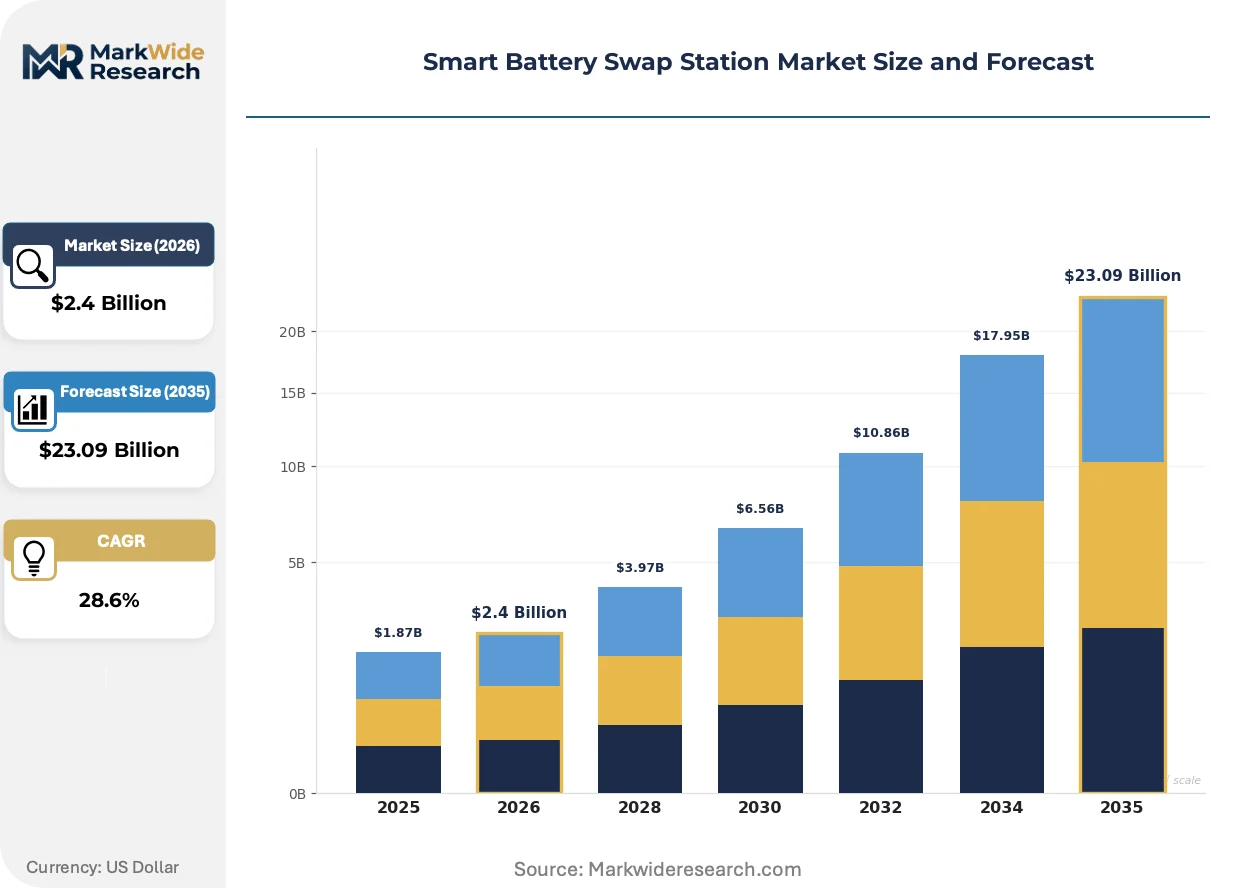
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $23.09 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stationary Systems, Mobile Units, Modular Designs, Intelligent Networked Stations Technology: Fast Charging, Wireless Communication, IoT Integration, Smart Monitoring End User: Electric Vehicle Operators, Fleet Managers, Public Transportation, Logistic Companies Installation: Urban Infrastructure, Highway Rest Stops, Commercial Facilities, Industrial Locations |
| Companies Covered | Nio Power, Gogoro, Ample, Contemporary Amperex Technology Co., Limited, Sun Mobility, BYD, Geely Automobile Holdings Limited, Aulton New Energy, Lifan Technology (Group) Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Battery Swap Station Market Trends and Innovations
Digital twin infrastructure is virtualizing station operations, compressing maintenance response times and enabling predictive battery health management across distributed networks.
Cloud-based battery management systems are virtualizing state-of-charge monitoring and thermal telemetry across swap station networks. Fleet operators in Shenzhen and Bangkok deploy these platforms to optimize pack rotation and predict degradation. The technology is virtualizing traditional asset tracking, shifting from physical inventory counts to real-time digital inventory.
The EU AI Act imposes conformity assessment requirements on automated swap robotics with decision-making autonomy. Station operators must document algorithmic transparency and risk mitigation for unmanned battery exchange sequences. European deployments face eighteen-month certification timelines versus six-month hardware-only approvals in Asian markets.
Subscription-based energy access is displacing per-swap transaction models among two-wheeler fleet managers. Gogoro's battery-as-a-service structure spreads capital burden across monthly payments, reducing upfront operator commitment. This procurement shift concentrates in Taipei, Jakarta, and Delhi where delivery fleet density justifies fixed-fee structures.
Smart Battery Swap Station Market Segmentation
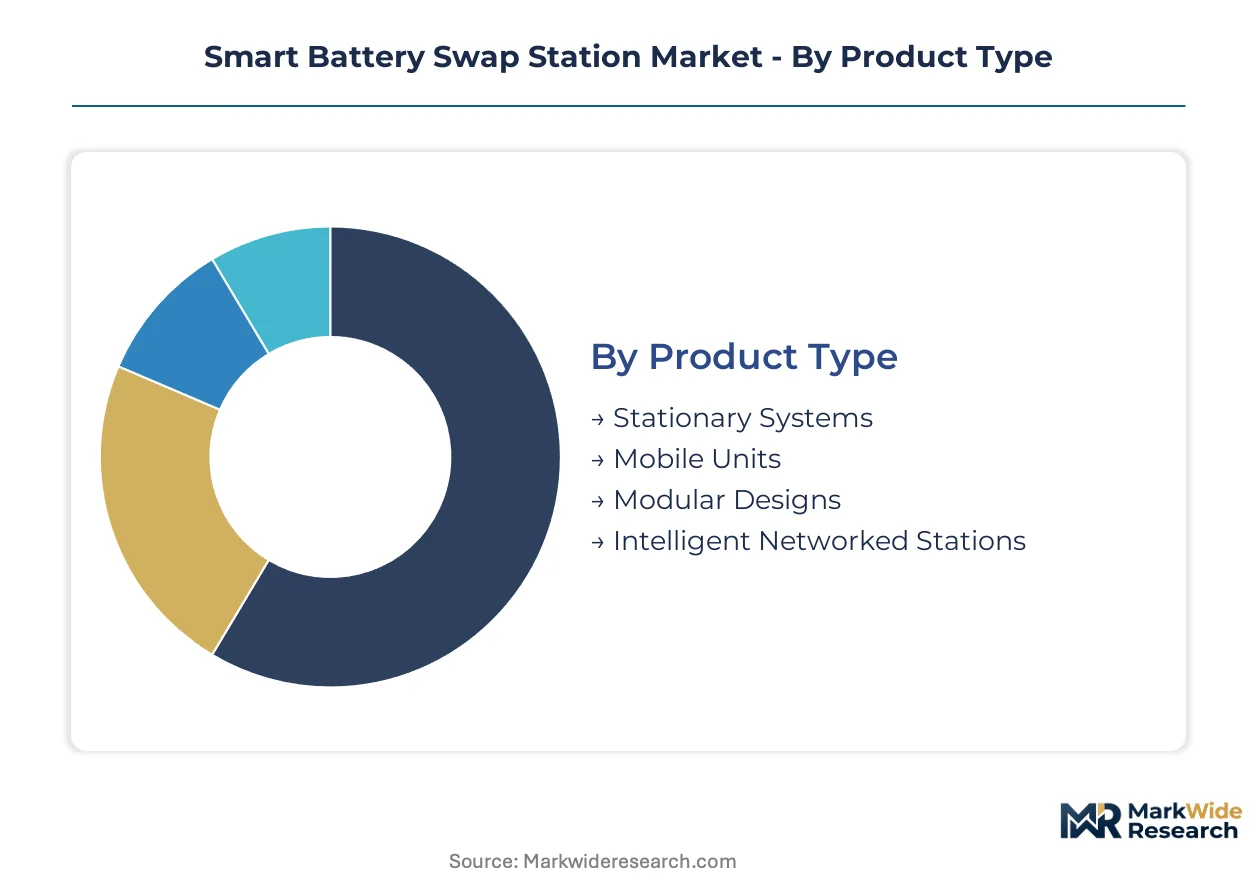
Segmentation in the Smart Battery Swap Station Market reveals how after-sales service intensity varies dramatically across deployment configurations. Technical complexity, utilization density, and maintenance cadence differ fundamentally between stationary hubs and mobile units, reshaping operator margin structures and vendor relationship economics.
Product Type:
After-sales service intensity peaks with stationary systems due to their electromechanical complexity and grid integration requirements, while modular designs minimize field technician dependency through plug-and-play component replacement.
- Stationary Systems:Fixed-location installations house robotic alignment mechanisms, thermal management interfaces, and cloud-connected inventory tracking for high-throughput operations. Demand concentrates in Shenzhen and Jakarta logistics corridors where delivery density justifies dedicated infrastructure and 24/7 technical support contracts.
- Modular Designs:Scalable capex deployment matches utilization curves through standardized battery vaults and interchangeable robotics modules. Ho Chi Minh City operators favor this configuration for phased rollout across dispersed urban zones, reducing stranded asset risk.
- Mobile Units:Truck-mounted or trailer-based systems serve temporary demand spikes and emergency fleet support with reduced installation lead times.
- Intelligent Networked Stations:Fully integrated hubs combine swap automation with renewable coupling and grid services for utility-facing revenue streams.
By volume, Stationary Systems leads. By growth pace, Modular Designs is climbing the fastest.
Technology:
Cost tier differentiation separates premium IoT-integrated platforms from baseline fast-charging configurations, with mid-tier wireless communication systems capturing fleet manager procurement.
- IoT Integration:Cloud-based battery management systems virtualize state-of-charge monitoring and thermal telemetry across distributed networks. Bangkok fleet operators deploy these platforms to optimize pack rotation and predict degradation, shifting from physical inventory counts to real-time digital inventory.
- Fast Charging:High-power electrical infrastructure enables sub-three-minute battery preparation cycles between swap transactions. China's MIIT-subsidized pilot zones mandate this capability as baseline compliance for state-funded deployments.
- Wireless Communication:Over-the-air firmware updates and remote diagnostics reduce on-site technician dispatches for software-related interventions.
- Smart Monitoring:Predictive analytics for battery health and station component wear enable condition-based maintenance scheduling.
By deployment base, Fast Charging dominates. By capability expansion, IoT Integration is gaining share fastest.
End User:
Customer type determines contract structure, with fleet managers demanding guaranteed service level agreements and public transportation authorities requiring redundant backup systems.
- Fleet Managers:Predictable route patterns and volume commitments amortize station infrastructure across guaranteed swap transactions, creating the most concentrated margin pool. Subscription-based energy access models spread capital burden across monthly payments, reducing upfront operator commitment in Taipei and Delhi.
- Logistic Companies:E-commerce delivery networks generate sufficient transaction volume to amortize station infrastructure within compressed payback periods across Southeast Asian urban corridors.
- Electric Vehicle Operators:Individual owner-operators drive sporadic demand patterns requiring flexible per-swap pricing rather than fixed-fee structures.
- Public Transportation:Municipal bus and taxi fleets require hardened redundancy and compliance with government procurement standards.
By revenue concentration, Fleet Managers leads. By contract innovation, Logistic Companies is expanding most quickly.
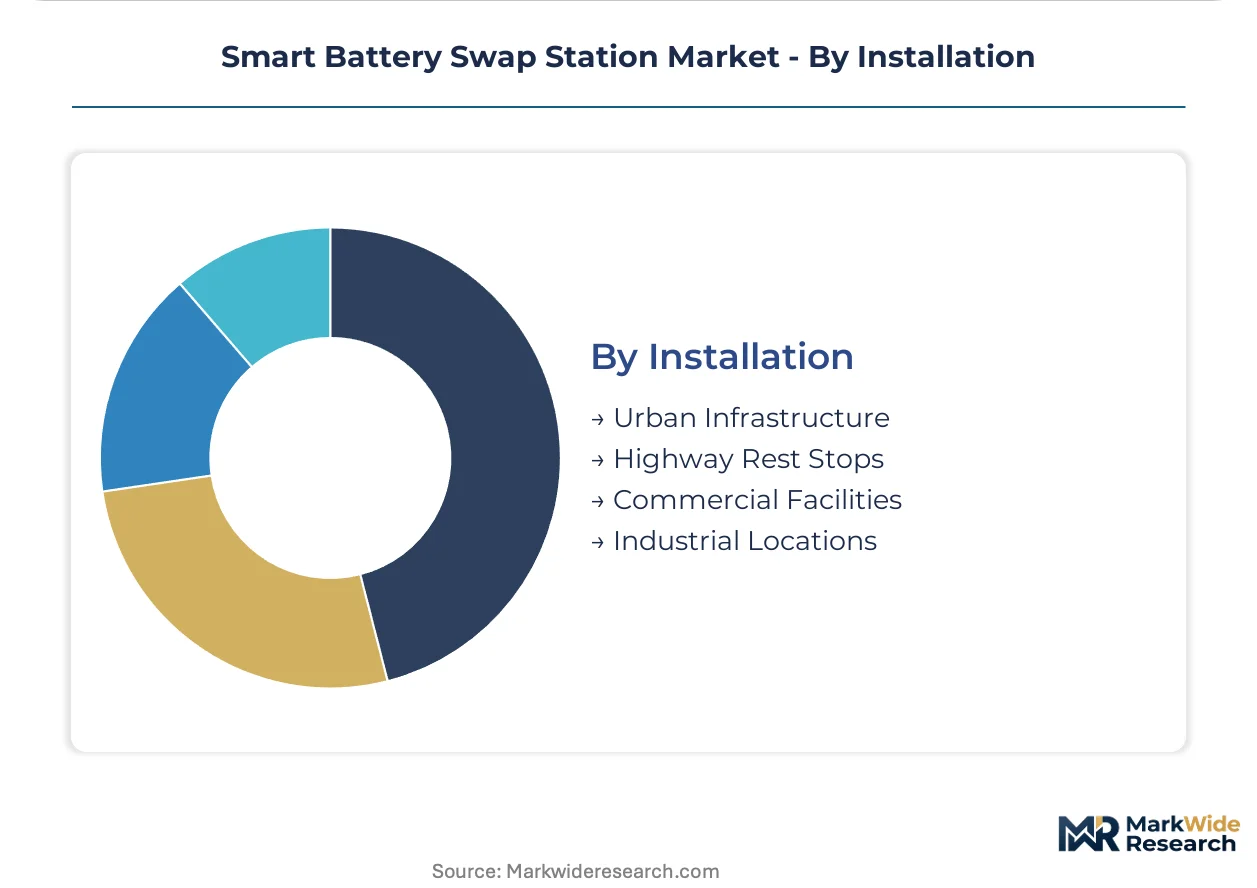
Installation:
Geography dictates grid interconnection complexity and regulatory approval timelines, with urban infrastructure facing the longest distribution utility queues.
- Urban Infrastructure:Dense metropolitan deployments face eight-to-fourteen-month grid connection delays but capture highest utilization rates. Distribution utility interconnection timelines in Jakarta and Ho Chi Minh City compress through streamlined permitting for dual carbon-aligned projects.
- Highway Rest Stops:Long-haul corridor positioning serves intercity electric truck and passenger vehicle segments with lower frequency but higher per-transaction revenue.
- Commercial Facilities:Retail parking integration and logistics hub co-location reduce land acquisition costs for private operators.
- Industrial Locations:Manufacturing plant and port-adjacent installations serve captive fleet demand with dedicated infrastructure.
By deployment count, Urban Infrastructure leads. By regulatory facilitation, Highway Rest Stops is advancing fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Swap station manufacturing clusters concentrate in China's industrial corridors, where MIIT standardization and state subsidy programs compress deployment timelines. European operators face extended certification cycles under the EU AI Act. Southeast Asian logistics hubs generate transaction density sufficient to amortize infrastructure within compressed payback windows.
China
MIIT-mandated GB standards for battery dimensional interchangeability force operators to accelerate capex commitments before compliance deadlines lock in market structure. The dual carbon goals channel state subsidies toward swap-enabled fleet electrification, reducing operator payback periods. Shenzhen and Beijing-Tianjin-Hebei logistics corridors concentrate stationary system deployments serving e-commerce delivery density.
United States
FAA and NHTSA regulatory frameworks govern automated robotics and vehicle-interfacing energy systems, creating multi-agency approval pathways for unmanned station operations. The IRA production tax credits indirectly support battery pack procurement cost structures for swap operators. California's zero-emission vehicle mandates drive pilot deployments across Los Angeles and San Francisco Bay Area urban logistics zones.
Germany
KBA vehicle type approval and CE marking frameworks extend hardware certification timelines for automated swap robotics with decision-making autonomy. The EU Green Deal carbon neutrality targets channel public procurement toward electrified municipal bus and taxi fleets. Bavaria and Baden-Württemberg automotive clusters host technology validation partnerships between station operators and OEM engineering centers.
India
BIS standards and the PLI scheme for advanced chemistry cell manufacturing reduce battery procurement costs for swap station operators seeking scale deployment. Central Electricity Authority grid interconnection guidelines shape urban infrastructure siting decisions. Delhi-NCR and Maharashtra logistics corridors concentrate modular design deployments serving last-mile delivery fleet electrification.
Vietnam
The country's national transport regulator streamlines permitting for dual carbon-aligned projects, compressing commercial launch timelines relative to neighboring jurisdictions. Ho Chi Minh City operators favor modular configurations for phased rollout across dispersed urban zones, reducing stranded asset risk. E-commerce delivery density in metropolitan corridors generates sufficient transaction volume to amortize station infrastructure within eighteen months.
Smart Battery Swap Station Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying battery packs, robotics modules, and thermal management interfaces. The vendor structure fragments across three strategic layers: proprietary network operators defending exclusive form factors, open-platform battery designers enabling multi-OEM interoperability, and modular station fabricators selling standardized vaults to regional operators. Dominant competitive moves include backward integration into battery cell supply and technology licensing partnerships that transfer swap automation IP across geographies.
Within the proprietary network tier, Nio Power and Gogoro exemplify closed-ecosystem strategies that lock utilization within branded vehicle fleets. Contemporary Amperex Technology Co., Limited occupies a position as an open-platform battery designer, supplying standardized packs to multiple automaker networks. Among China-based fabricators, Aulton New Energy and Lifan Technology (Group) Co., Ltd. represent modular station specialists serving state-subsidized pilot zones under MIIT standardization mandates.
| Leading Market Players |
|---|
| Nio Power |
| Gogoro |
| Ample |
| Contemporary Amperex Technology Co., Limited |
| Sun Mobility |
| BYD |
| Geely Automobile Holdings Limited |
| Aulton New Energy |
| Lifan Technology (Group) Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Shenzhen's manufacturing corridor anchors global battery pack production capacity, concentrating supply-side leverage among domestic fabricators who dictate downstream pricing terms to swap station operators across Southeast Asian deployment zones. This geographic clustering amplifies procurement negotiation dynamics for modular station components and thermal management systems.
Pricing Analysis
China's MIIT GB standards dictate the pricing tier structure across the swap station market, separating premium IoT-integrated configurations from baseline fast-charging installations through certification complexity and grid-interconnection capability. Three-tier pricing structure across premium, standard, and economy levels reflects after-sales service bundling and robotic alignment precision grades. Cost compression in economy-tier modular units is intensifying because India's PLI scheme for advanced chemistry cells expands battery procurement alternatives. Fleet managers exhibit the highest price sensitivity due to volume commitment pressures, while public transportation authorities accept premium tiers for redundancy guarantees.
Supply Chain Analysis
Extended payment terms from Chinese battery cell manufacturers and supply-chain finance facilities anchored in Shenzhen and Ningbo shape working capital requirements for station operators. Manufacturing concentration in China, South Korea, and Japan feeds the robotic alignment mechanisms and thermal management interfaces. Cathode material feedstock draws from Indonesian nickel and Chilean lithium processing. Single-source vulnerability persists for vision-guided positioning sensors. Distribution runs through OEM-authorized fabricators serving state-subsidized pilot zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity characterizes this market as subscription-based energy access models displace per-swap transactions, creating niche positioning for specialized software platforms and modular hardware fabricators.
For Market Incumbents: Harden network exclusivity through proprietary battery architecture patents before interoperability mandates erode form-factor lock-in advantages. Deepen backward integration into battery cell supply via partnerships with PLI scheme beneficiaries in India. Accelerate certification for UL 9540A thermal management compliance to extend product validation lead times against emerging competitors.
For New Entrants and Emerging Players: Establish a beachhead in Vietnam's Ho Chi Minh City logistics corridor where streamlined permitting for dual carbon-aligned projects compresses commercial launch timelines. Target modular design configurations for phased rollout across dispersed urban zones with lower stranded asset risk. Pursue white-label robotics module supply to regional operators lacking electromechanical fabrication capabilities.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors open-platform battery designers enabling multi-OEM interoperability as MIIT standardization mandates force proprietary networks toward compatibility. Long-term viability hinges on software-defined inventory management and predictive battery health analytics. Acquisition targets should demonstrate cloud-based fleet optimization platforms with demonstrated utilization in Bangkok or Jakarta deployment zones. The signal to watch is EU AI Act conformity assessment timeline compression for automated swap robotics.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Battery Cell Supply | PLI scheme qualification in India reduces procurement cost exposure for swap operators. |
| Interoperability Protocol Development | Open-platform designs enable multi-OEM network participation and expand utilization rates. |
| Digital Twin Infrastructure Deployment | Virtualized station operations compress maintenance response times across distributed networks. |
| Renewable Coupling Configuration | Solar-plus-storage at swap hubs reduces grid dependency and peak demand charges. |
| Robotics IP Licensing Partnership | Technology transfer agreements accelerate geographic expansion for automated swap mechanisms. |
Research Methodology
A spread of perspectives from swap station operators, fleet logistics managers, battery pack procurement leads, and robotics module fabricators converged on the working assumptions driving this analysis. Primary interviews with these stakeholders combined with secondary validation against MIIT policy filings, BIS standards documentation, EU AI Act regulatory texts, and customs trade data for electromechanical components. Bottom-up deployment modeling across urban infrastructure segments triangulated with top-down market sizing from state subsidy program disclosures.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, modeling segmentation dimensions including product type configuration, technology tier, end-user contract structure, and installation geography. CAGRs derived from fitted growth curves incorporating utilization rate trajectories, battery pack inventory turnover assumptions, and grid interconnection queue dynamics. Forecast inputs included lithium price volatility scenarios and robotic alignment system cost decline curves.
Stress conditions across cathode material cost swings, distribution utility interconnection delays, and EU AI Act certification timeline extensions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about fleet electrification commitment levels and state subsidy continuity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Infrastructure
ASEAN Countries Electric Vehicle Battery Separator Market
Battery Infrastructure
China Electric Vehicle Battery Manufacturing Equipment Market
Battery Infrastructure
China Battery Manufacturing Equipment Market
Battery Infrastructure
North America Electric Vehicle Battery Manufacturing Equipment Market
Battery Infrastructure
Battery Lug Market
Battery Infrastructure
Europe Electric Vehicle Battery Separator Market
Battery Infrastructure
New Energy Battery Structural Parts Market
Battery Infrastructure
India Electric Vehicle Battery Separator Market
Battery Infrastructure
South America Electric Vehicle Battery Manufacturing Equipment Market
Battery Infrastructure
Carbon Battery Bank Market
Battery Infrastructure
South America Electric Vehicle Battery Separator Market
Battery Infrastructure
EV Battery Sealant Market
Battery Infrastructure
Germany Electric Vehicle Battery Separator Market
Battery Infrastructure
Battery Tray Market
Battery Infrastructure
Battery-As-A-Service Market
Battery Infrastructure
Battery Raw Materials Market