
 South America Electric Vehicle Battery Separator Market | 2026-2036
South America Electric Vehicle Battery Separator Market Size, Share, and Industry Trends Forecast 2026-2036
South America Electric Vehicle Battery Separator Market Insights
OEM procurement power across South America is hardening as Brazilian and Argentine automakers consolidate supplier lists around fewer certified separator vendors. SK Innovation Co. Ltd leverages its integrated petrochemical base to supply coated films with shorter lead times. Mitsubishi Chemical Group Corporation anchors its position through high-heat-resistant polymer substrates tailored to tropical operating conditions. Entek Manufacturing LLC competes on dry-process manufacturing scale that reduces solvent dependency.
A battery separator is a microporous membrane placed between a lithium-ion battery's anode and cathode, typically manufactured from polyolefin substrates with pore sizes ranging from 0.03 to 0.1 microns to enable ion transport while preventing electrical short circuits. Its primary purpose is to maintain electrochemical stability and thermal shutdown safety during charge-discharge cycles across electric vehicle powertrains. Polymer separators occupy the dominant volume position due to mature extrusion and biaxial stretching infrastructure, though ceramic separators command margin premiums where thermal runaway protection exceeds baseline requirements. Ultrathin films represent the fastest-growing technology segment as cell manufacturers pursue energy density gains through stack-layer reduction.
Brazil's Inovação Verde framework and Argentina's national industrial standards body shape local content requirements and import certification pathways for separator materials. ANVISA oversight of industrial chemical imports adds compliance layers that favor suppliers with established local testing partnerships. Stakeholders must monitor how Chile's lithium royalty regulations and evolving Argentine battery supply chain incentives reshape regional sourcing economics.
Market Dynamics
OEM consolidation around certified separator suppliers is hardening procurement power across Brazil's southeastern manufacturing corridor, while ceramic coating adoption accelerates performance requirements beyond baseline polymer specifications.
Growth Catalysts
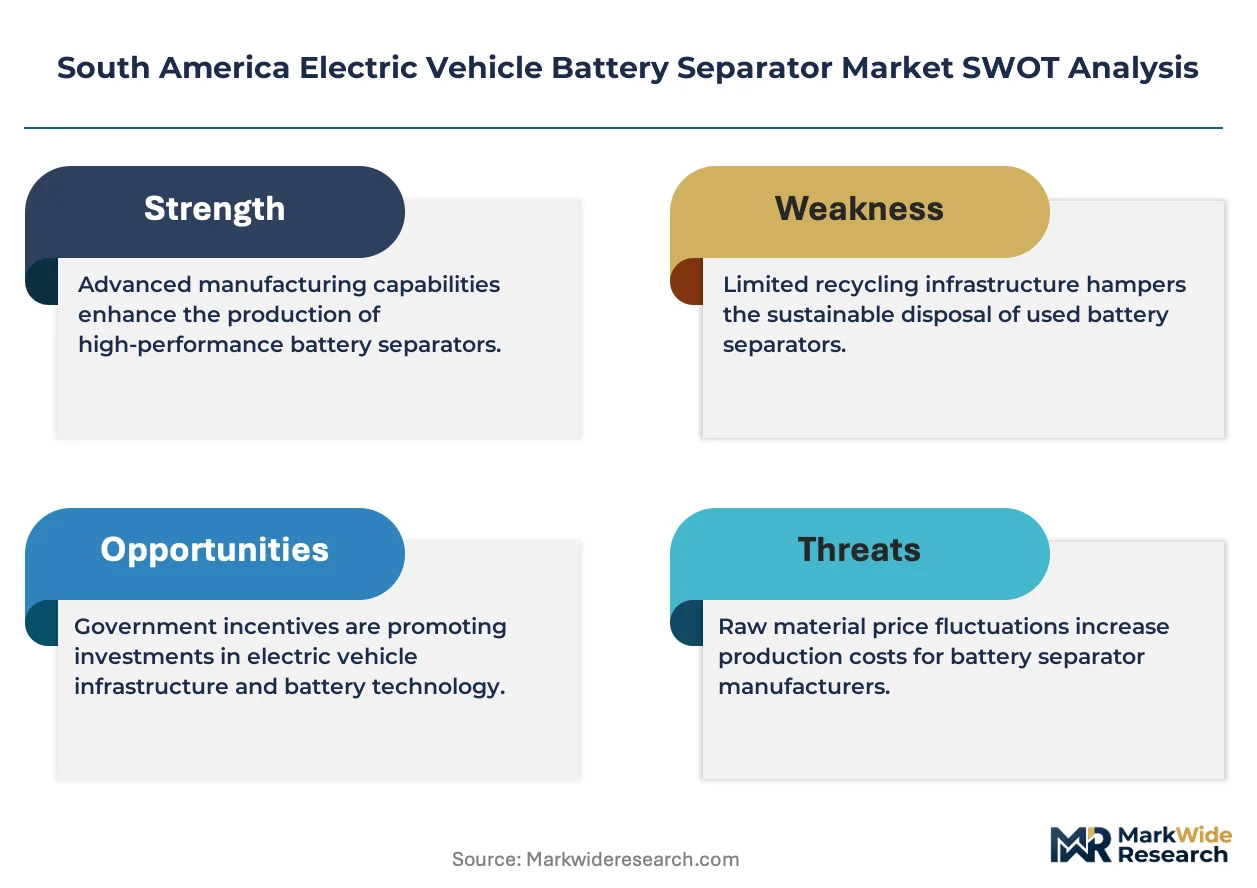
- Brazil's Inovação Verde program:Mandatory local content thresholds for EV components are pulling separator manufacturing investment toward São Paulo and Minas Gerais industrial zones.
- Ceramic coating techniques:Advances in alumina and silica deposition are enabling 150°C thermal shutdown performance that tropical operating conditions demand.
- Passenger EV fleet expansion:Brazilian and Chilean automakers are scaling lithium-ion cell production, concentrating separator demand in metropolitan São Paulo.
Market Restraints
- Polyolefin resin import dependency:Separator substrates rely on polyethylene and polypropylene feedstocks subject to petrochemical price volatility and currency fluctuation exposure.
- Single-source coating equipment concentration:Ceramic deposition machinery suppliers cluster in East Asia, creating 14-18 month lead time vulnerabilities for South American producers.
- ANVISA chemical import certification:Industrial chemical oversight adds 90-120 day testing cycles that delay new separator material introductions.
Strategic Opportunities
- Argentina's battery supply chain incentives:Provincial tax abatements in Córdoba and Buenos Aires provinces are attracting separator slitting and finishing operations.
- Chilean lithium royalty restructuring:Downstream processing credits are repositioning separator-cathode integration economics for Antofagasta-based cell manufacturers.
- Dry-process manufacturing adoption:Solvent-free extrusion methods are opening pathways for local producers to bypass wet-process chemical handling complexity.
Industry Challenges
- Polymer substrate thermal engineering talent scarcity:Biaxial stretching process optimization requires specialized polymer physicists in short supply across the region's materials science programs.
- Cell manufacturer qualification timelines:OEM separator validation protocols demand 18-24 month durability testing that compresses supplier cash conversion cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Electric Vehicle Battery Separator Market |
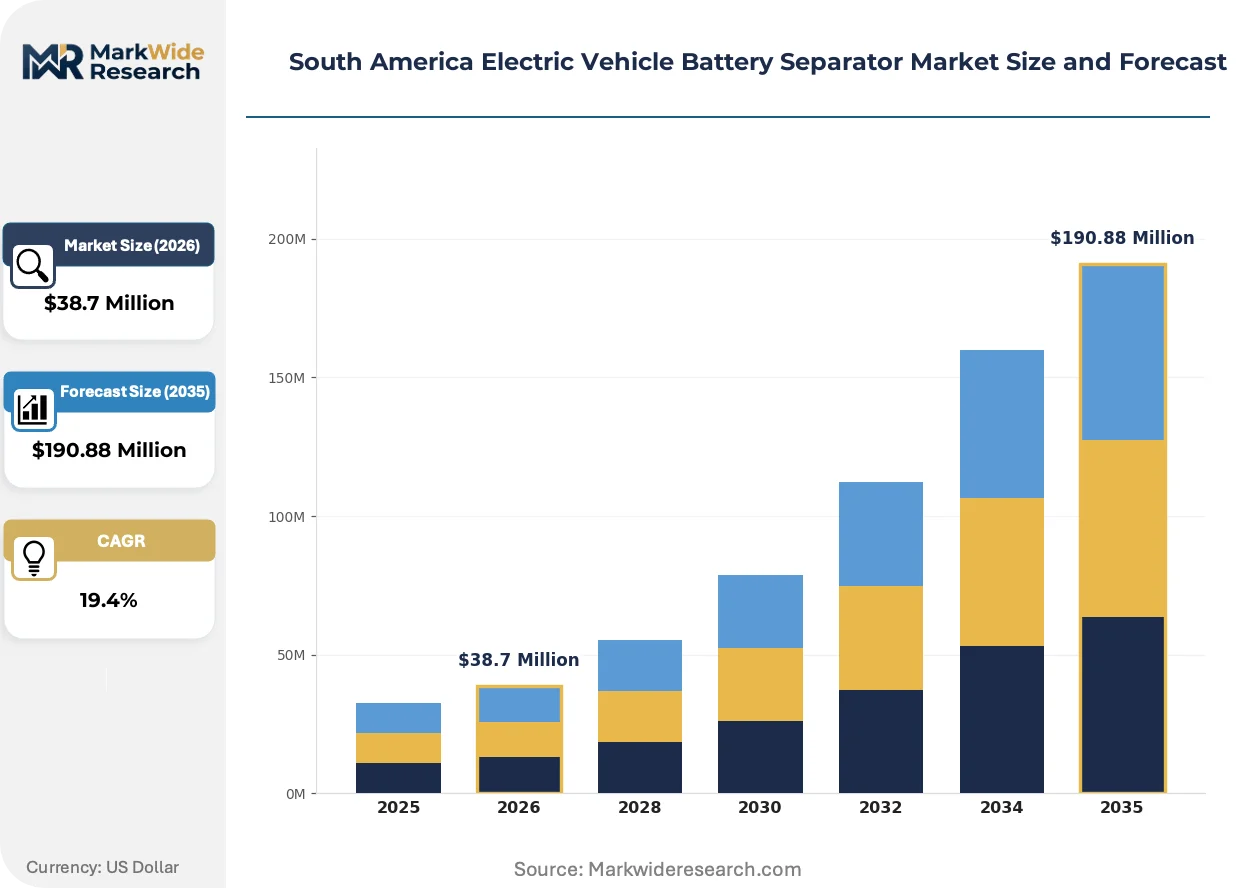
| Market Size in 2026 | $38.7 Million |
| Market Size in 2035 | $190.88 Million |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymer Separator, Ceramic Separator, Composite Separator, Non-Woven Separator End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Dealerships Technology: Ultrathin Films, Nanostructured Materials, Coating Techniques, Electrospinning Installation: Manufacturing Lines, Assembly Plants, Research Facilities, Pilot Production Systems |
| Companies Covered | SK Innovation Co. Ltd, Mitsubishi Chemical Group Corporation, Toray Industries Inc., Sumitomo Chemical Co. Ltd, Entek Manufacturing LLC, Asahi Kasei Corporation, SK IE Technology, W-SCOPE Corporation, UBE Corporation, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Electric Vehicle Battery Separator Market Trends and Innovations
Separator technology is bifurcating between ultrathin polymer films pursuing energy density gains and ceramic-hybrid architectures prioritizing thermal runaway containment. This divergence is reshaping capital allocation across South American manufacturing investments.
Ceramic-coated polyolefin separators are absorbing margin premiums previously captured by uncoated films. Brazilian cell manufacturers are specifying 3-5 micron ceramic layers for tropical climate battery packs. This specification shift is compressing commodity polymer separator pricing power while elevating coating equipment utilization rates.
Brazil's Inovação Verde framework is tightening local content verification for imported separator materials. ANVISA oversight of industrial chemical imports now requires pre-shipment testing at certified Brazilian laboratories. Separator suppliers without established local testing partnerships face extended customs clearance cycles that disadvantage just-in-time supply arrangements.
Fleet procurement contracts are consolidating separator specifications around fewer qualified vendors. Argentine and Chilean automakers are adopting Brazilian OEM qualification standards to simplify cross-border supply chain management. This standardization is concentrating separator purchasing volume with suppliers holding multi-country certification status, particularly visible in São Paulo state contract awards.
South America Electric Vehicle Battery Separator Market Segmentation
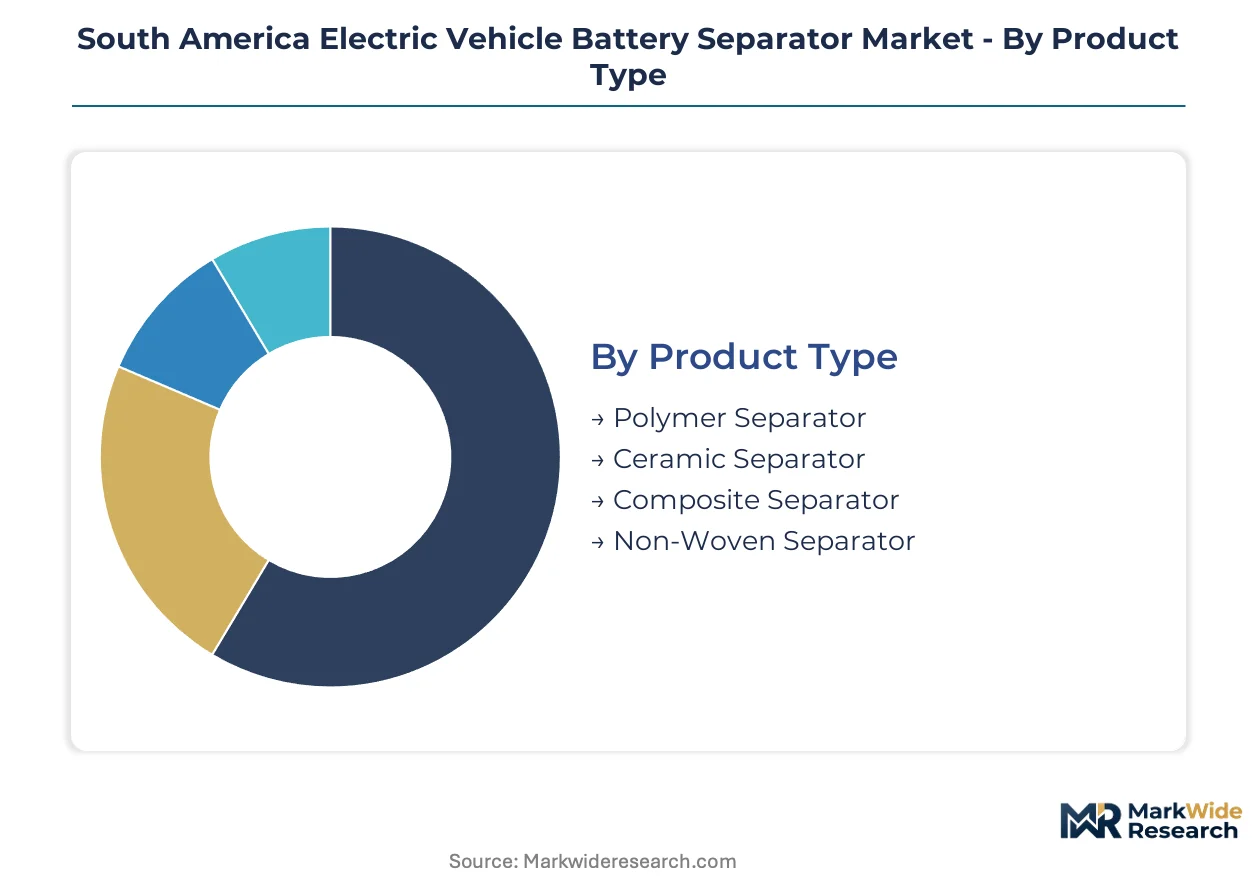
Battery separator procurement across South America stratifies sharply by technical specification and supply chain position. Segment selection determines capital deployment intensity, qualification timelines, and exposure to Brazil's Inovação Verde local content mandates.
Product Type:
Capital intensity varies dramatically across substrate technologies, with ceramic coating lines demanding 3-4x the upfront investment of conventional polymer extrusion systems.
- Polymer Separator:Manufactured from polyethylene and polypropylene substrates through biaxial stretching processes, these microporous films dominate installed capacity across São Paulo's manufacturing corridor. Brazilian OEMs specify 12-25 micron thickness grades for baseline passenger EV applications where cost optimization outweighs thermal performance premiums.
- Ceramic Separator:Alumina and silica deposition layers on polyolefin bases deliver 150°C thermal shutdown protection that tropical operating conditions require. Argentine and Chilean cell manufacturers are consolidating procurement around 3-5 micron ceramic specifications, absorbing margin premiums that uncoated films cannot command.
- Composite Separator:Hybrid architectures blending polymer flexibility with ceramic thermal resistance occupy intermediate price positioning. Demand concentrates in Córdoba province pilot production facilities testing next-generation cell formats.
- Non-Woven Separator:Electrospun fiber matrices offer alternative ion transport pathways with reduced dendrite penetration risk. ANVISA certification pathways for novel substrate chemistries remain underdeveloped, delaying commercial scale-up.
Most installed capacity flows through Polymer Separator lines. Expansion is steepest in Ceramic Separator coating operations.
End User:
Procurement authority concentrates upstream as Brazilian automakers consolidate qualified vendor lists and push specification standardization across their supply bases.
- OEMs:Direct separator procurement by BYD, CAOA Chery, and Stellantis operations in Minas Gerais and São Paulo states concentrates volume with certified suppliers holding multi-country validation status. These manufacturers specify thermal performance thresholds and mandate local content verification.
- Tier-1 Suppliers:Cell packagers and module integrators purchase separators under OEM-directed supply agreements. Argentine battery assembly operations in Buenos Aires province source through Tier-1 intermediaries to simplify cross-border logistics.
- Aftermarket Providers:Replacement separator demand remains negligible given lithium-ion cell sealed architectures and warranty restrictions on pack disassembly.
- Dealerships:No meaningful separator procurement occurs at retail level; battery service operations route replacement demand upstream to authorized service centers.
Volume aggregates at OEMs. Procurement flexibility is greatest among Tier-1 Suppliers.
Technology:
Process maturity determines which manufacturing approaches attract South American capital given scarce polymer engineering talent and ANVISA chemical handling oversight.
- Ultrathin Films:Sub-10 micron polymer substrates enable stack-layer reduction that lifts cell energy density. Brazilian manufacturers are piloting 5-8 micron specifications for premium EV platforms, though biaxial stretching yield rates lag East Asian benchmarks.
- Nanostructured Materials:Pore architecture engineering through controlled phase separation offers tunable ion transport pathways. Research facilities in Chile's Antofagasta region are evaluating nanostructured separators for lithium-rich cathode integration.
- Coating Techniques:Alumina and silica deposition methods dominate ceramic separator production. Equipment suppliers cluster in East Asia, creating 14-18 month lead time vulnerabilities for South American producers seeking to expand coating capacity.
- Electrospinning:Solvent-free fiber formation enables non-woven separator architectures with reduced environmental compliance burden. Dry-process adoption is climbing fastest among local producers seeking to bypass wet-process chemical handling complexity.
Coating Techniques absorb the majority of capital investment. Electrospinning is gaining share fastest among new entrants.
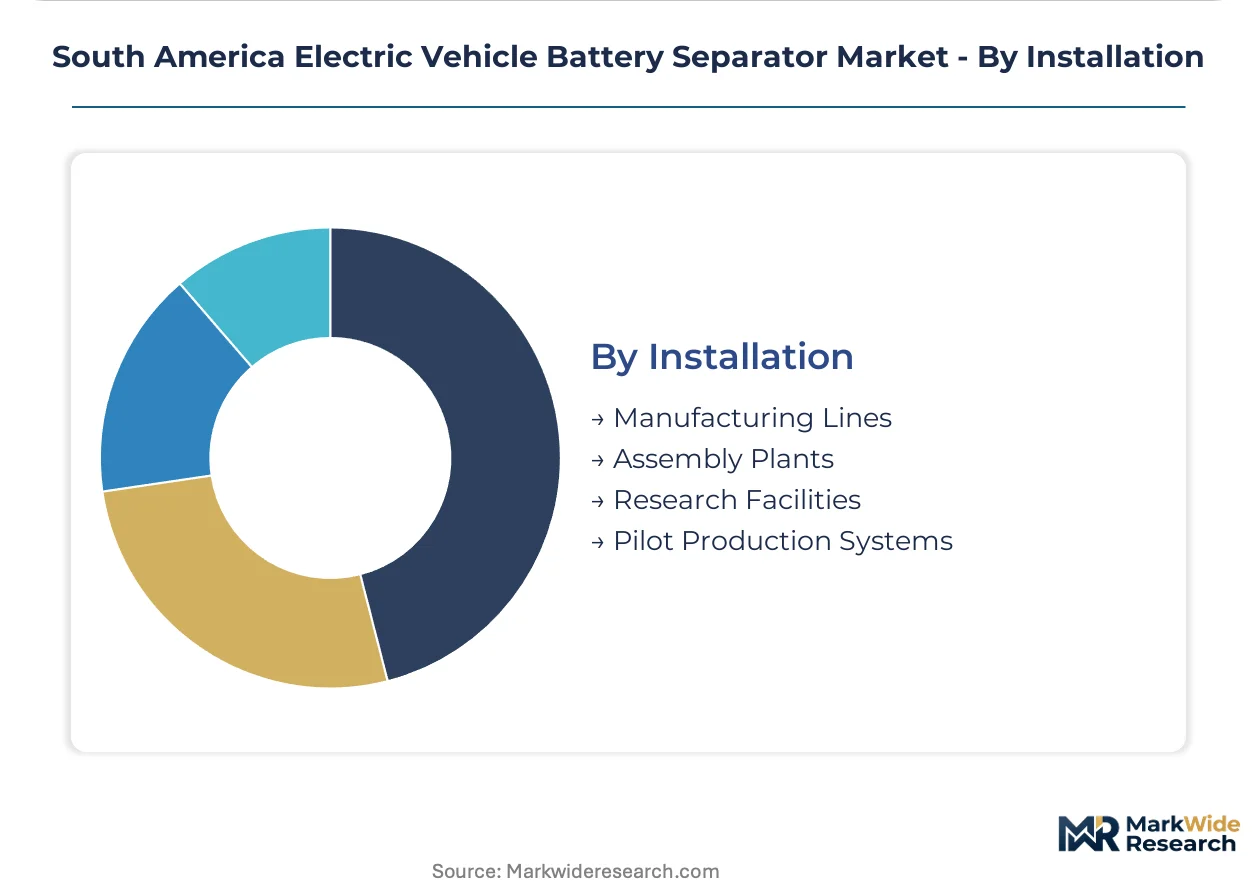
Installation:
Facility type determines separator qualification protocols, batch traceability requirements, and integration with downstream cell formation equipment.
- Manufacturing Lines:High-volume extrusion and coating operations in São Paulo state supply separator rolls to multiple cell producers. These lines require ISO 9001 and IATF 16949 certification that Brazilian OEMs mandate for qualified supplier status.
- Assembly Plants:Separator slitting and finishing operations in Córdoba and Buenos Aires provinces perform final dimensional conditioning before cell integration. Provincial tax abatements are attracting these mid-stream investments.
- Research Facilities:University and national laboratory programs in Campinas and Santiago evaluate novel substrate chemistries. ANVISA pre-shipment testing partnerships are essential for translating research prototypes into importable materials.
- Pilot Production Systems:Small-scale coating and stretching lines validate process parameters before commercial scale-up. Chilean lithium royalty restructuring is repositioning pilot investment economics for Antofagasta-based developers.
Manufacturing Lines carry the heaviest capital burden. Pilot Production Systems are multiplying fastest as new entrants test market entry.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil commands separator procurement volume while Argentina builds finishing capacity through provincial incentives. Chile leverages lithium proximity to attract pilot coating investments. The three markets operate under divergent regulatory timelines and industrial policy frameworks.
Brazil
Passenger EV production at Stellantis and BYD facilities in Minas Gerais pulls separator demand toward São Paulo's manufacturing corridor. ANVISA's Inovação Verde program mandates local content verification that extends customs clearance for imported ceramic coating materials. Ceramic deposition lines are concentrating in São Bernardo do Campo industrial parks to satisfy OEM qualification standards.
Argentina
Battery assembly operations in Buenos Aires province source separators through Tier-1 intermediaries to manage cross-border logistics complexity. Provincial tax abatements in Córdoba are attracting slitting and finishing investments from regional producers. Córdoba's pilot production facilities are testing composite separator architectures for next-generation cell formats.
Chile
Lithium royalty restructuring is repositioning downstream processing economics for Antofagasta-based cell manufacturers seeking separator-cathode integration. Research facilities in Santiago evaluate nanostructured separators for lithium-rich cathode chemistries. Antofagasta's pilot coating lines validate process parameters before commercial scale-up commitments.
Colombia
Emerging EV assembly operations in Bogotá metropolitan zone generate nascent separator demand through aftermarket channel development. National industrial standards bodies are drafting import certification pathways for separator materials. Medellín's polymer research institutes are evaluating dry-process manufacturing methods to reduce chemical handling compliance burdens.
South America Electric Vehicle Battery Separator Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across South America's separator procurement tiers. Market structure hardens around qualified vendor lists as Brazilian OEMs consolidate certification requirements. Three archetypes dominate: integrated petrochemical suppliers leveraging feedstock proximity, coating equipment operators commanding capital-intensive ceramic deposition, and dry-process specialists reducing solvent dependency. Capacity expansion and strategic partnerships represent the dominant competitive vectors as producers seek to shorten 14-18 month equipment lead times.
Within the integrated petrochemical tier, SK Innovation Co. Ltd and Mitsubishi Chemical Group Corporation exemplify suppliers anchoring positions through upstream material control. Entek Manufacturing LLC occupies a specialist position representing dry-process manufacturing scale. These three companies illustrate how geographic origin and corporate structure map onto competitive archetypes: Korean and Japanese conglomerates versus US-based manufacturing specialists.
| Leading Market Players |
|---|
| SK Innovation Co. Ltd |
| Mitsubishi Chemical Group Corporation |
| Toray Industries Inc. |
| Sumitomo Chemical Co. Ltd |
| Entek Manufacturing LLC |
| Asahi Kasei Corporation |
| SK IE Technology |
| W-SCOPE Corporation |
| UBE Corporation |
| Others |
Pricing and Supply Chain Analysis
Polymer physicist scarcity across São Paulo's materials science programs widens labor-cost spreads between ceramic-coated premium tiers and commodity polymer baselines. ANVISA certification delays compress margins for importers while rewarding local dry-process specialists with faster customs clearance.
Pricing Analysis
Capacity additions in Brazil's southeastern manufacturing corridor are reshaping price floors for uncoated polymer separators. Three-tier pricing structure across premium ceramic-coated, standard polymer, and economy-grade specifications stratifies procurement by thermal performance requirements. Cost compression in commodity polymer tiers intensifies as Brazilian OEMs consolidate qualified vendor lists. Tier-1 suppliers exhibit highest price sensitivity due to pass-through contract structures, while OEM direct procurement absorbs premium tier premiums for tropical climate specifications.
Supply Chain Analysis
Freight cost exposure from East Asian coating equipment suppliers extends lead time vulnerabilities for South American producers seeking ceramic deposition capacity. Raw material flows draw from South Korean and Japanese petrochemical bases for polyolefin substrates, Chinese alumina and silica feedstocks for ceramic layers, and Chilean lithium proximity for cathode-integrated separator development. Single-source equipment concentration in East Asia creates tariff exposure for capital goods imports. Distribution runs through São Paulo state manufacturing lines supplying Tier-1 cell packagers across Brazil, Argentina, and Chile.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's Inovação Verde program compounds separator demand through mandatory local content thresholds, creating regulatory-driven procurement expansion across the southeastern manufacturing corridor.
For Market Incumbents: Anchor market position through backward integration into polyolefin substrate production and ANVISA-certified local testing partnerships. Ceramic coating equipment lead time vulnerabilities threaten supply security for unintegrated suppliers. Defensive consolidation around dry-process manufacturing scale reduces solvent dependency and accelerates customs clearance cycles. For New Entrants and Emerging Players: Argentina's battery supply chain incentives in Córdoba and Buenos Aires provinces open a window for slitting and finishing operations targeting cross-border Tier-1 procurement. The most penetrable segment lies in composite separator pilot production for next-generation cell formats. A go-to-market angle emphasizing electrospinning solvent-free architectures bypasses wet-process chemical handling complexity that burdens established competitors. For Investors and Strategic Acquirers: Integrated petrochemical conglomerates are the most active acquirer in this space, seeking coating technology capabilities to complement upstream material positions. Long-term viability hinges on separator-cathode integration economics as cell manufacturers consolidate supply tiers. The signal to watch is Chilean lithium royalty restructuring momentum as a downstream processing credit inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Coating Capacity Expansion | East Asian equipment procurement addresses 150°C thermal shutdown specifications mandated by Brazilian OEMs. |
| Dry-Process Manufacturing Scale-Up | Solvent-free extrusion methods bypass ANVISA chemical import certification cycles for faster market entry. |
| ANVISA Testing Partnership Establishment | Pre-shipment validation at certified Brazilian laboratories compresses customs clearance from 90-120 days. |
| Provincial Incentive Zone Establishment | Córdoba and Buenos Aires tax abatements attract separator finishing operations near Argentine cell assembly. |
| Lithium-Cathode Integration Investment | Antofagasta pilot coating lines leverage Chilean royalty restructuring for downstream processing economics. |
Research Methodology
Direct dialogue with OEM procurement directors, Tier-1 cell packager operations managers, ANVISA regulatory affairs specialists, and ceramic coating equipment distributors grounded qualitative findings in operational reality. Secondary validation drew from Brazilian customs records, ANVISA import certification databases, SEC filings of listed petrochemical suppliers, and IHS Markit vehicle production data. Bottom-up and top-down triangulation reconciled separator roll volume estimates with cell production capacity announcements across the analysis window.
Top-down modeling anchored aggregate market sizing to passenger EV fleet projections, while bottom-up segmentation tracked ceramic versus polymer substrate procurement patterns by OEM qualification status. Modeled dimensions span product type, end-user tier, coating technology maturity, and regional production cluster. CAGRs were derived from fitted growth curves calibrated to Inovação Verde implementation timelines and OEM capacity expansion announcements. Forecast inputs include polyolefin resin price volatility indices and ceramic deposition equipment order backlogs.
Revisions become necessary when ANVISA regulatory timelines shift, Chilean lithium royalty structures materialize differently than anticipated, or East Asian equipment lead times extend beyond current planning assumptions. Forecasts reflect documented assumptions about local content threshold enforcement intensity and OEM qualification standard harmonization across Brazil, Argentina, and Chile. A model refresh is warranted upon material change in ceramic separator specification adoption rates among tropical climate battery pack designs.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Infrastructure
EV Battery Sealant Market
Battery Infrastructure
Carbon Battery Bank Market
Battery Infrastructure
Battery Enclosure Market
Battery Infrastructure
China Electric Vehicle Battery Manufacturing Equipment Market
Battery Infrastructure
France Electric Vehicle Battery Manufacturing Equipment Market
Battery Infrastructure
China Electric Vehicle Battery Separator Market
Battery Infrastructure
North America Electric Vehicle Battery Separator Market
Battery Infrastructure
Automatic Battery Manufacturing Equipment Market
Battery Infrastructure
Canada Electric Vehicle Battery Separator Market
Battery Infrastructure
Global Automotive 48 Volt Battery System Market
Battery Infrastructure
Germany Electric Vehicle Battery Manufacturing Equipment Market
Battery Infrastructure
Electric Vehicle Battery Swapping Market
Battery Infrastructure
Global Battery Packaging Market
Battery Infrastructure
South America Electric Vehicle Battery Manufacturing Equipment Market
Battery Infrastructure
Battery Swap-Ready Pack Systems for Urban Fleets Market
Battery Infrastructure
New Energy Battery Structural Parts Market