

High-Power Battery Cyclers for Fast-Charging Protocol Validation Market Size, Share, and Industry Trends Forecast 2026-2036
High-Power Battery Cyclers for Fast-Charging Protocol Validation Market Insights
The EU Battery Regulation is pivoting the cost-of-entry calculus for cycler vendors by mandating carbon-footprint disclosure and recycled-content thresholds across cell supply chains. Digatron leverages its European installed base to sustain service contracts with German automotive test labs. Keysight Technologies anchors its position through precision measurement IP that spans RF and power-electronics domains. Chroma ATE competes on manufacturing scale in Taiwan and mainland China, where it dominates regional procurement cycles for EV battery validation.
High-power battery cyclers for fast-charging protocol validation are precision power-electronics instruments that apply controlled current-voltage profiles up to multiple kiloamperes to stress-test lithium-ion cells under extreme charge rates, primarily to certify thermal stability and cycle-life degradation before production release. Rack-mounted cyclers occupy the core infrastructure layer at tier-one battery manufacturers due to channel density and thermal management integration, while regenerative cycling technology captures the fastest expansion as facilities prioritize energy recovery to offset electricity costs from repeated 4C-6C stress protocols. Multi-channel systems concentrate margin pools in R&D contracts where parallel test matrices reduce time-to-certification for new cell chemistries.
FDA oversight applies where cyclers validate medical-device battery packs, while EPA energy-efficiency standards shape regenerative-system design specifications in the US market; ECE R100 and UN 38.3 transport-safety protocols drive European and Asian test-lab procurement cycles. China's GB/T standards and MIIT certification requirements create a parallel compliance track that favors domestic equipment sourcing. Stakeholders must monitor whether solid-state and sodium-ion chemistries demand fundamentally different current-pulse architectures than existing silicon-carbide inverter platforms can deliver.
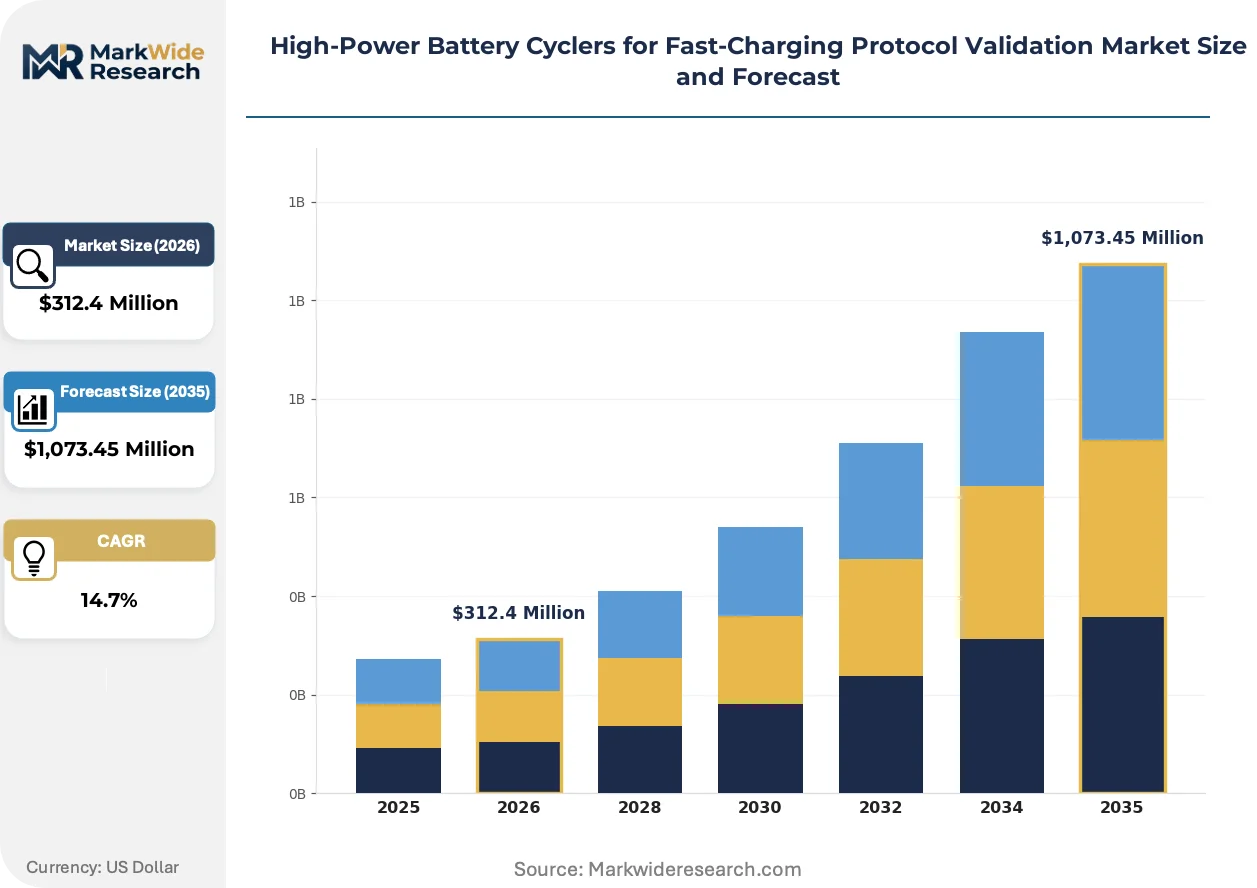
Market Dynamics
The 800V platform transition across automotive OEMs is compressing validation timelines, forcing test-lab operators to parallelize cell-stress protocols across multi-channel cycler arrays while regenerative energy recovery becomes non-negotiable for electricity cost containment.
Growth Catalysts
- ECE R100 thermal-runaway mandates:German automotive test labs must certify cell-level safety under revised European protocols, expanding installed cycler capacity at Stuttgart-area facilities.
- Silicon-carbide inverter architectures:Wide-bandgap semiconductors enable 6C pulse profiles that legacy IGBT platforms cannot sustain, opening replacement cycles for precision power-electronics infrastructure.
- Gigafactory corridors:Cell production buildouts around Incheon and Ningbo require parallel validation infrastructure, concentrating equipment procurement in battery manufacturing zones.
Market Restraints
- Copper and rare-earth magnet cost volatility:Regenerative cyclers depend on permanent-magnet synchronous machines, exposing vendors to neodymium supply disruptions from concentrated Chinese processing.
- Calibration labor scarcity:Precision current-sensor calibration requires specialized technicians, creating bottlenecks at test-lab scale-up phases.
- UN 38.3 transport-certification backlog:Cell shipment approval delays extend validation timelines, freezing cycler utilization rates at third-party labs.
Strategic Opportunities
- Sodium-ion chemistry qualification:Emerging cell formulations demand modified pulse architectures, creating white space for cycler vendors with programmable current-profile flexibility.
- GB/T standard harmonization:China's domestic fast-charging certification track favors equipment sourcing from regional suppliers with MIIT-recognized calibration chains.
- Second-life battery validation:Grid-storage repurposing applications require degraded-cell cycling protocols, opening aftermarket service contracts beyond OEM supply chains.
Industry Challenges
- Power-electronics firmware integration:Cyclers must synchronize with laboratory information management systems, creating interoperability friction at multi-vendor test facilities.
- Thermal-management commissioning:Liquid-cooled channel arrays require facility-level HVAC coordination, extending deployment timelines at greenfield sites.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High-Power Battery Cyclers for Fast-Charging Protocol Validation Market Trends and Innovations
Regenerative energy recovery is rewriting capital-expense calculations for high-throughput test labs, while solid-state cell roadmaps and AI-driven protocol optimization are forcing hardware-software co-development cycles across the vendor base.
Regenerative cycling architectures with active front-end inverters are overtaking passive resistive-load systems in new installations. Tier-one battery manufacturers in South Korea and Germany now specify energy recovery rates above 90 percent for 4C-6C stress protocols. This shift is compressing total-cost-of-ownership metrics and disqualifying vendors without grid-tie synchronization capabilities.
EU Battery Regulation carbon-footprint disclosure rules are mandating lifecycle documentation across cell supply chains. Test-lab operators must now attribute electricity consumption per validation cycle to specific cell batches, altering cycler procurement specifications toward granular energy monitoring. German automotive OEMs are embedding these requirements into equipment RFPs ahead of 2027 compliance deadlines.
Service-contract unbundling is fragmenting vendor-customer relationships in European test-lab markets. Equipment buyers now separate hardware procurement from calibration and firmware-update subscriptions, pressuring incumbent vendors with bundled legacy pricing. This pattern is most visible in Stuttgart and Munich, where independent metrology houses are capturing aftermarket service margins from OEM-captive labs.
High-Power Battery Cyclers for Fast-Charging Protocol Validation Market Segmentation
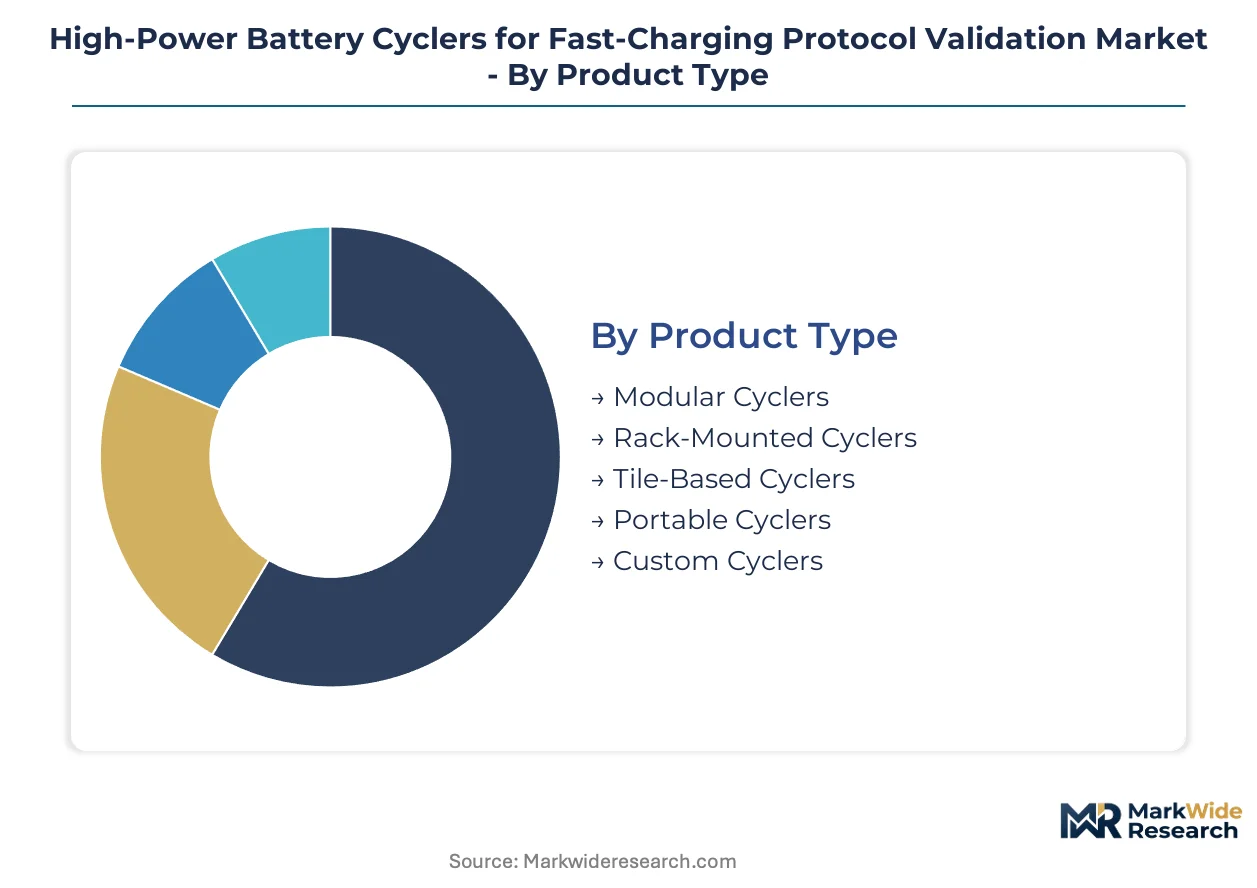
Segmentation in high-power battery cyclers reveals how validation infrastructure fragments across deployment scales and technical architectures. Equipment buyers prioritize channel density, energy recovery efficiency, or mobility depending on whether they operate gigafactory test floors, R&D laboratories, or field-service operations.
Product Type:
Standardization dominates at high-volume deployment tiers while customization concentrates in specialized validation environments requiring non-standard channel configurations or thermal integration.
- Rack-Mounted Cyclers:These systems integrate 50-200 channels per cabinet with centralized liquid cooling and grid-tie regenerative inverters. Tier-one battery manufacturers in Stuttgart and Incheon specify rack-mounted architectures for parallel 800V cell validation under ECE R100 protocols.
- Modular Cyclers:Hot-swappable channel cards enable capacity expansion without facility shutdowns. This architecture appeals to contract test labs in Ningbo managing fluctuating validation backlogs from multiple OEM clients.
- Tile-Based Cyclers:Distributed power electronics reduce single-point failure risk across large arrays.
- Portable Cyclers:Mobile units support field validation and supplier audit programs.
- Custom Cyclers:Engineered-to-order systems address unique thermal or mechanical integration constraints.
Leading the category by volume: Rack-Mounted Cyclers. Growing fastest: Modular Cyclers.
Technology:
Cost tier stratification separates capital-intensive regenerative architectures from entry-level resistive-load systems, with pulse-precision capabilities commanding premium positioning.
- Regenerative Cycling:Active front-end inverters return 90%+ of discharge energy to the grid, slashing electricity costs during repeated 6C stress protocols. South Korean battery makers now mandate regenerative specifications in all new cycler procurements.
- Multi-Channel Systems:Parallel test matrices compress certification timelines for new cell chemistries. Research laboratories in Germany deploy these systems to validate sodium-ion formulations against multiple protocol variants simultaneously.
- Pulse Charging:Precision current-pulse architectures enable silicon-carbide inverter validation.
- Constant Current:Baseline technology for standardized cycle-life testing.
- Step-Down Charging:Simplified architectures for consumer electronics validation.
Highest margin concentration: Regenerative Cycling. Steepest expansion trajectory: Multi-Channel Systems.
Application:
Application-driven segmentation tracks how validation intensity varies with cell energy density, safety-criticality, and regulatory exposure across end-use categories.
- Electric Vehicle Battery Testing:800V platform validation demands 4C-6C charge-rate stress testing with thermal-runaway detection. This application consumes the majority of installed high-power cycler capacity in Germany, South Korea, and China.
- Grid Storage Assessment:Second-life battery repurposing requires degraded-cell cycling protocols that differ from fresh-cell validation. Test labs in Ningbo are expanding capacity for grid-storage certification under China's dual carbon policy framework.
- Consumer Electronics Validation:Lower-power requirements with emphasis on compact form factors.
- Aerospace Power Systems:Extreme temperature cycling and vibration-hardened specifications.
- Marine Energy Devices:Salt-corrosion resistance and sealed-thermal-management requirements.
Dominant revenue pool: Electric Vehicle Battery Testing. Fastest-climbing segment: Grid Storage Assessment.
End User:
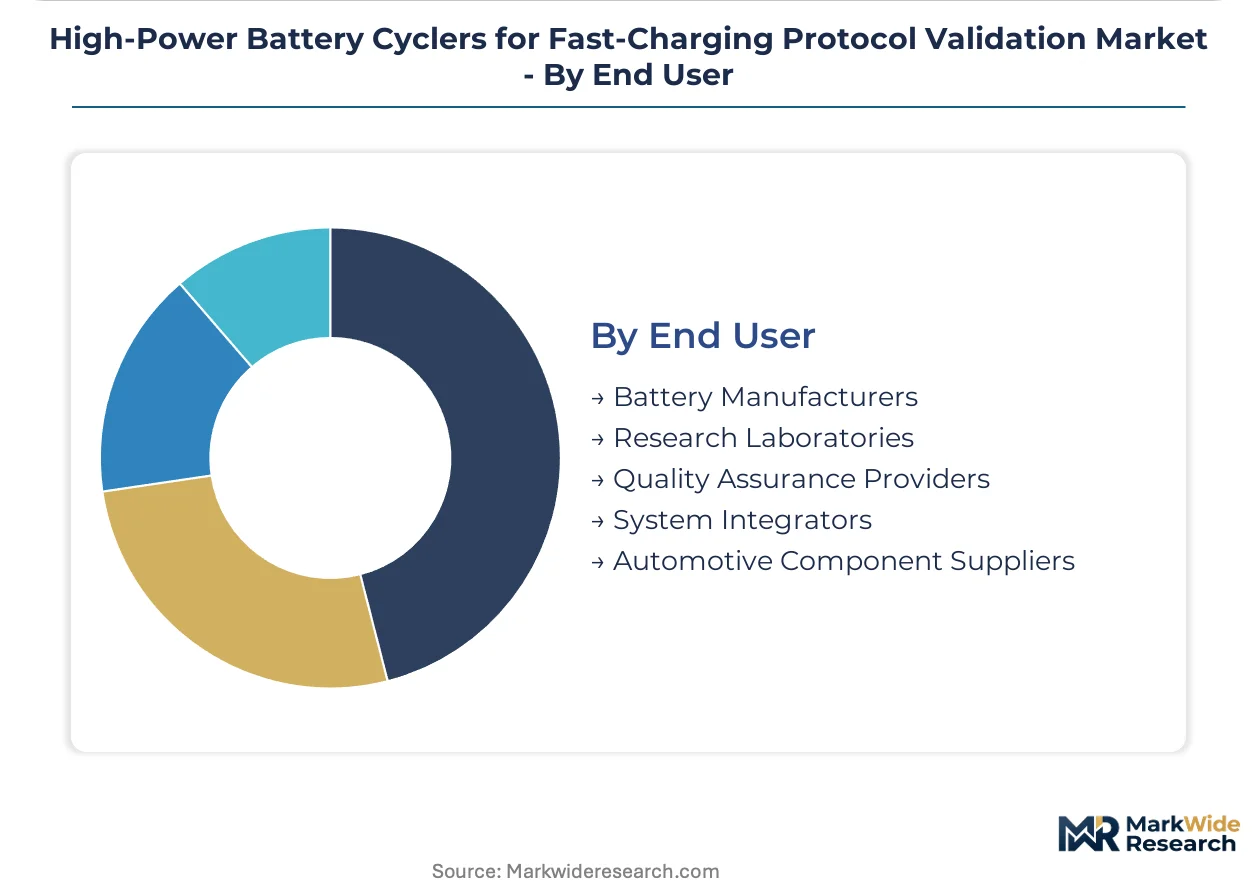
Customer-type segmentation distinguishes captive validation operations from third-party service providers, with procurement authority and technical specification control varying sharply across buyer categories.
- Battery Manufacturers:Gigafactory operators maintain in-house test floors for production-release validation. These buyers specify rack-mounted regenerative systems with direct LIMS integration and MIIT-recognized calibration chains.
- Research Laboratories:Academic and government labs prioritize programmable current-profile flexibility over throughput. German automotive OEMs fund external R&D contracts requiring multi-channel cycler access for pre-competitive cell chemistry screening.
- Quality Assurance Providers:Independent test labs compete on certification speed and protocol breadth.
- System Integrators:Turnkey validation facility contractors bundle cycler procurement with thermal and software infrastructure.
- Automotive Component Suppliers:Tier-two vendors validating pack-level integration.
Largest installed base: Battery Manufacturers. Fastest-growing procurement authority: Research Laboratories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Ningbo Economic and Technological Development Zone concentrates cycler procurement alongside CATL and BYD gigafactory buildouts. Germany's Stuttgart region anchors European validation infrastructure for 800V automotive platforms. South Korea's Incheon Free Economic Zone drives parallel test-lab expansion.
Germany
ECE R100 thermal-runaway mandates compel automotive OEMs to expand cell-level certification capacity. KBA enforcement of revised European protocols forces equipment upgrades at captive test labs. Stuttgart-area facilities now specify rack-mounted regenerative systems with direct LIMS integration for production-release validation.
China
GB/T fast-charging standards and MIIT certification requirements create a parallel compliance track favoring domestic equipment sourcing. Dual carbon policy frameworks mandate granular energy monitoring per validation cycle. Ningbo battery manufacturing corridors require parallel validation infrastructure as gigafactory output scales.
South Korea
MFDS-aligned safety protocols for automotive cell certification drive test-lab capacity expansion. Silicon-carbide inverter validation demands 6C pulse profiles that stress legacy infrastructure. Incheon Free Economic Zone concentrates procurement cycles where battery makers mandate regenerative specifications above 90 percent energy recovery.
United States
EPA energy-efficiency standards shape regenerative-system design specifications for domestic test facilities. NHTSA battery safety research programs fund external validation contracts at national laboratories. Michigan and California automotive clusters anchor cycler deployment for 800V platform development.
Japan
METI-funded solid-state battery initiatives demand modified pulse architectures for next-generation chemistry validation. JIS standards for industrial power electronics influence cycler specification templates. Nagoya-area automotive suppliers maintain captive test floors for tier-two pack integration certification.
High-Power Battery Cyclers for Fast-Charging Protocol Validation Market Competitive Landscape
German producers anchor one tier; Taiwanese specialists hold manufacturing scale advantages in Asia-Pacific procurement cycles. The vendor base separates into consolidated precision-measurement houses and regional fabrication specialists. Three archetypes dominate: European service-contract incumbents, Asian manufacturing-scale suppliers, and precision-instrument multinationals. Competitive moves concentrate on geographic expansion through local calibration chains and portfolio diversification into sodium-ion validation protocols.
Within the European service-contract tier, Digatron leverages its regional installed base to sustain relationships with automotive test labs. Keysight Technologies exemplifies the precision-measurement multinational archetype, spanning RF and power-electronics domains. Chroma ATE occupies a position among Asia-Pacific manufacturing-scale suppliers, anchoring regional procurement cycles through Taiwan and mainland China presence.
| Leading Market Players |
|---|
| Digatron |
| Keysight Technologies |
| NH Research |
| Chroma ATE |
| Arbin Instruments |
| AVL |
| PEC |
| MACCOR |
| Neware Technology |
| Others |
Pricing and Supply Chain Analysis
The EU Battery Regulation's carbon-footprint disclosure mandates gate qualified supply and premium-tier pricing access, forcing cycler vendors to document lifecycle electricity consumption per validation cycle while tier-one battery manufacturers embed these requirements into equipment RFPs ahead of compliance deadlines.
Pricing Analysis
Short lead-time premiums now separate urgent procurement from standard-cycle orders as German automotive OEMs compress 800V platform validation timelines. Three-tier pricing structure across premium, standard, and economy levels stratifies by energy recovery efficiency and MIIT-recognized calibration chain certification. Cost compression in economy-tier rack-mounted systems is intensifying because Taiwanese manufacturing-scale suppliers leverage regional component sourcing. Contract test labs in Ningbo exhibit highest price sensitivity due to fluctuating validation backlogs, while captive gigafactory test floors in Stuttgart prioritize specification compliance over unit cost.
Supply Chain Analysis
Dual-sourcing requirements for silicon-carbide power modules and precision current sensors now dominate procurement protocols at tier-one battery manufacturers. Manufacturing concentrates in China, Taiwan, and Germany, with final assembly drawing from neodymium permanent-magnet supply chains anchored in Chinese rare-earth processing zones. Copper busbar and liquid-cooling manifold dependencies create single-source vulnerability for regenerative inverter architectures. Distribution runs through direct OEM relationships and system integrator channels serving greenfield test-lab construction projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where the EU Battery Regulation creates a barrier-to-entry moat for vendors capable of documenting granular energy monitoring and recycled-content thresholds across cell supply chains.
For Market Incumbents: To counter silicon-carbide inverter platform displacement of legacy IGBT architectures, Digatron and Keysight Technologies must deepen backward integration into precision current-sensor manufacturing and expand calibration service contracts beyond hardware bundling. Capacity addition in South Korea's Incheon Free Economic Zone captures regenerative cycler demand from battery makers mandating above-90-percent energy recovery specifications. For New Entrants and Emerging Players: The 40-percent price-point gap between premium German regenerative systems and economy-tier Chinese rack-mounted units opens white space for modular cycler architectures with hot-swappable channel cards. Sodium-ion chemistry qualification protocols represent the most penetrable application segment, with programmable current-profile flexibility as the decisive go-to-market angle against incumbent firmware rigidity. For Investors and Strategic Acquirers: MFDS-aligned safety protocol revisions in South Korea are the leading indicator that automotive cell certification capacity expansion will accelerate across Asia-Pacific test-lab infrastructure. Long-term viability over the next decade hinges on vendor positioning against solid-state battery roadmaps requiring modified pulse architectures. Acquisition targets should display software-defined cycler platforms with AI-driven protocol optimization capabilities. Watch for GB/T standard harmonization announcements as the inflection signal for domestic Chinese equipment sourcing preferences.| Strategic Initiative | Industry Significance |
|---|---|
| Regenerative Energy Recovery Retrofit | Captures 90-percent-plus discharge energy return to offset electricity costs from repeated 6C stress protocols at Stuttgart-area facilities. |
| MIIT-Recognized Calibration Chain Investment | Unlocks procurement access to Ningbo gigafactory corridors where domestic certification requirements favor regional equipment sourcing. |
| Sodium-Ion Validation Protocol Development | Addresses emerging cell chemistry demand for modified pulse architectures that stress-test thermal stability under non-lithium ion transport mechanisms. |
| LIMS Integration Firmware Expansion | Resolves interoperability friction at multi-vendor test facilities where laboratory information management system synchronization is becoming mandatory. |
| Second-Life Battery Service Contract Launch | Opens aftermarket revenue streams beyond OEM supply chains as grid-storage repurposing applications require degraded-cell cycling protocols. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, combining primary interviews with test-lab operations directors, battery manufacturer procurement leads, power-electronics R&D engineers, and aftermarket service managers with validation from ECE R100 implementation documents, MIIT certification registries, and KBA enforcement bulletins. Bottom-up equipment shipment tracking and top-down gigafactory capital expenditure triangulation established market sizing boundaries.
Data-stream reconciliation across product type, technology architecture, application intensity, and end-user procurement authority dimensions drove the analytical framework over the projection horizon. CAGRs were derived from segment-level growth trajectory modeling incorporating silicon-carbide inverter adoption curves, regenerative energy recovery specification penetration, and sodium-ion chemistry qualification timelines as industry-specific forecast inputs.
Inputs from German automotive OEMs and South Korean battery makers were available through the study window; gaps in Chinese domestic supplier shipment disclosures introduce uncertainty bands around Ningbo corridor equipment procurement estimates. Deviation in GB/T standard harmonization timelines or EU Battery Regulation enforcement schedules would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.