
 Electric Vehicle Battery Swapping Market | 2026-2036
Electric Vehicle Battery Swapping Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle Battery Swapping Market Intelligence
A shortage of certified battery technicians and station automation engineers is redrawing competitive boundaries across the swapping ecosystem. NIO sustains its lead through captive battery manufacturing and proprietary station architecture in China's premium passenger segment. Gogoro dominates Taiwan's two-wheeler swapping density while extending its network licensing model into India and Indonesia. CATL leverages its cell-to-pack cost position to supply modular battery formats to third-party swapping operators.
Electric vehicle battery swapping denotes a system where depleted battery packs are exchanged for fully charged units at dedicated stations, typically completing the process in under five minutes through automated mechanical alignment and thermal management verification. The primary purpose is to eliminate charging downtime for commercial and passenger electric vehicles operating on continuous duty cycles. Swapping stations and automated systems currently absorb the majority of capital deployment, though subscription service models are generating the most predictable recurring revenue streams. Fleet operators represent the most structurally attractive end-user segment due to high utilization rates and centralized vehicle management.
China's MIIT enforces standardized battery dimensions and communication protocols under GB/T specifications, directly determining which vehicle-platform combinations qualify for swapping infrastructure subsidies. India's BIS and CEA are developing interoperability standards and grid-connection codes for battery-as-a-service operators, shaping how station networks secure power supply agreements and consumer safety certifications. In Europe, the EU Battery Regulation and CE marking requirements are defining product lifecycle traceability obligations that will constrain market entry for non-compliant battery suppliers. Stakeholders must track which regulatory jurisdictions move first on mandating open swapping architectures versus permitting proprietary ecosystems.
Market Dynamics
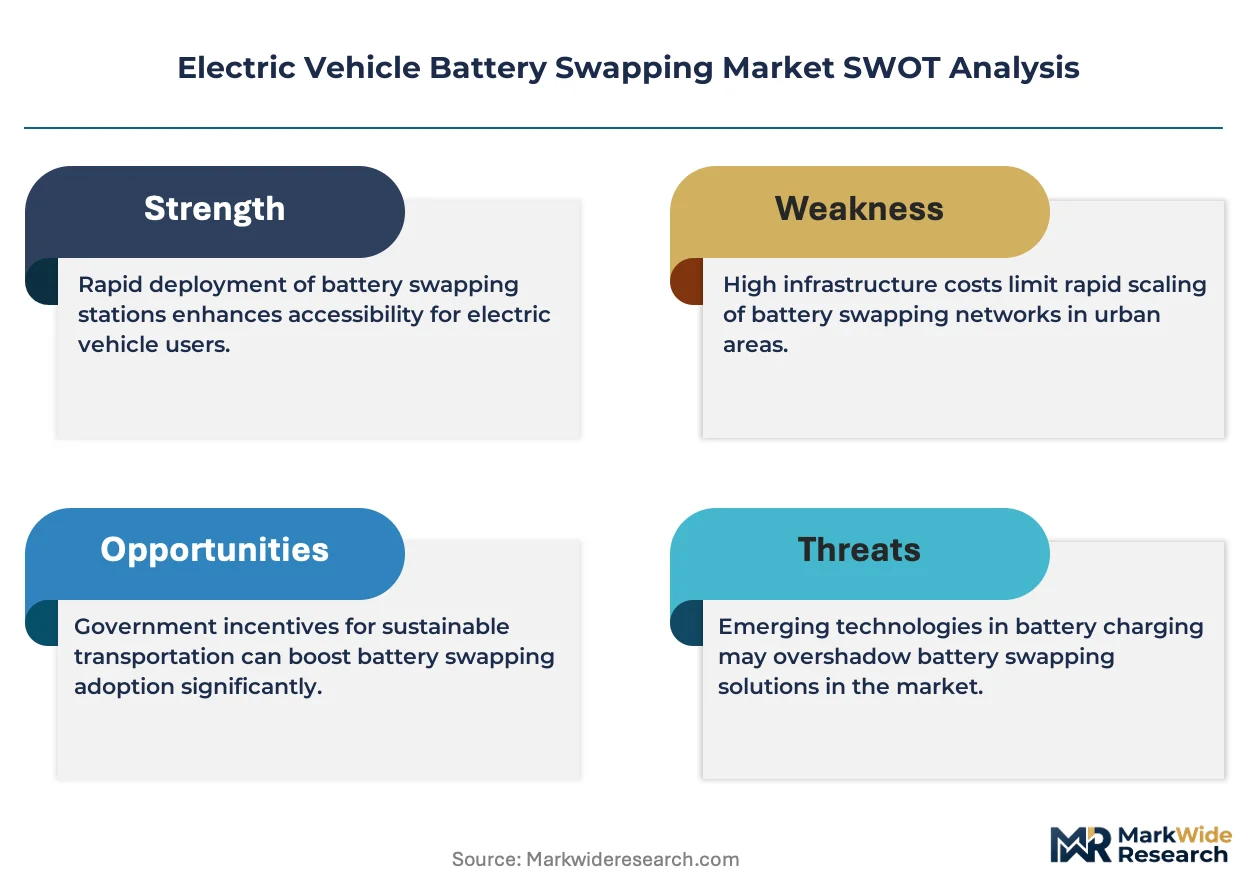
The shortage of certified battery technicians and station automation engineers is redrawing competitive boundaries across the swapping ecosystem, forcing operators to secure talent pipelines before scaling infrastructure.
Growth Catalysts
- China's dual carbon goals:NEV mandates and GB/T standardization under MIIT are accelerating station deployment timelines and creating subsidy-qualified vehicle-platform combinations.
- Last-mile delivery fleets:Logistics operators with continuous duty cycles demand sub-five-minute energy replenishment, driving predictable subscription revenue models.
- Modular cell-to-pack architectures:Standardized battery formats are reducing per-unit costs and enabling third-party operator network expansion.
Market Restraints
- Lithium and nickel price volatility:Raw material cost swings compress battery procurement margins for swapping operators locked into fixed subscription pricing.
- Proprietary station concentration:Captive architectures from dominant equipment suppliers limit interoperability and raise switching costs for fleet customers.
- Grid connection approval delays:India's CEA certification timelines for high-capacity charging infrastructure extend station commissioning by six to eighteen months.
Strategic Opportunities
- Indonesia's two-wheeler density:Licensing network models from established operators can penetrate Southeast Asia's largest motorcycle market with minimal greenfield capex.
- Battery-as-a-service tax incentives:India's PLI scheme for advanced chemistry cell manufacturing reduces input costs for domestic swapping operators.
- Automated thermal management convergence:Integration of predictive battery health monitoring with station robotics is cutting per-swap labor to near-zero.
Industry Challenges
- Certified automation engineer scarcity:Station deployment outpaces vocational training output, inflating salaries for robotic alignment specialists.
- Multi-standard battery inventory complexity:Operators serving mixed fleets must stock incompatible pack formats, raising working capital requirements.
- Legacy fleet integration friction:Retrofitting existing electric vehicles with swap-compatible chassis designs requires OEM cooperation that remains sporadic.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle Battery Swapping Market |
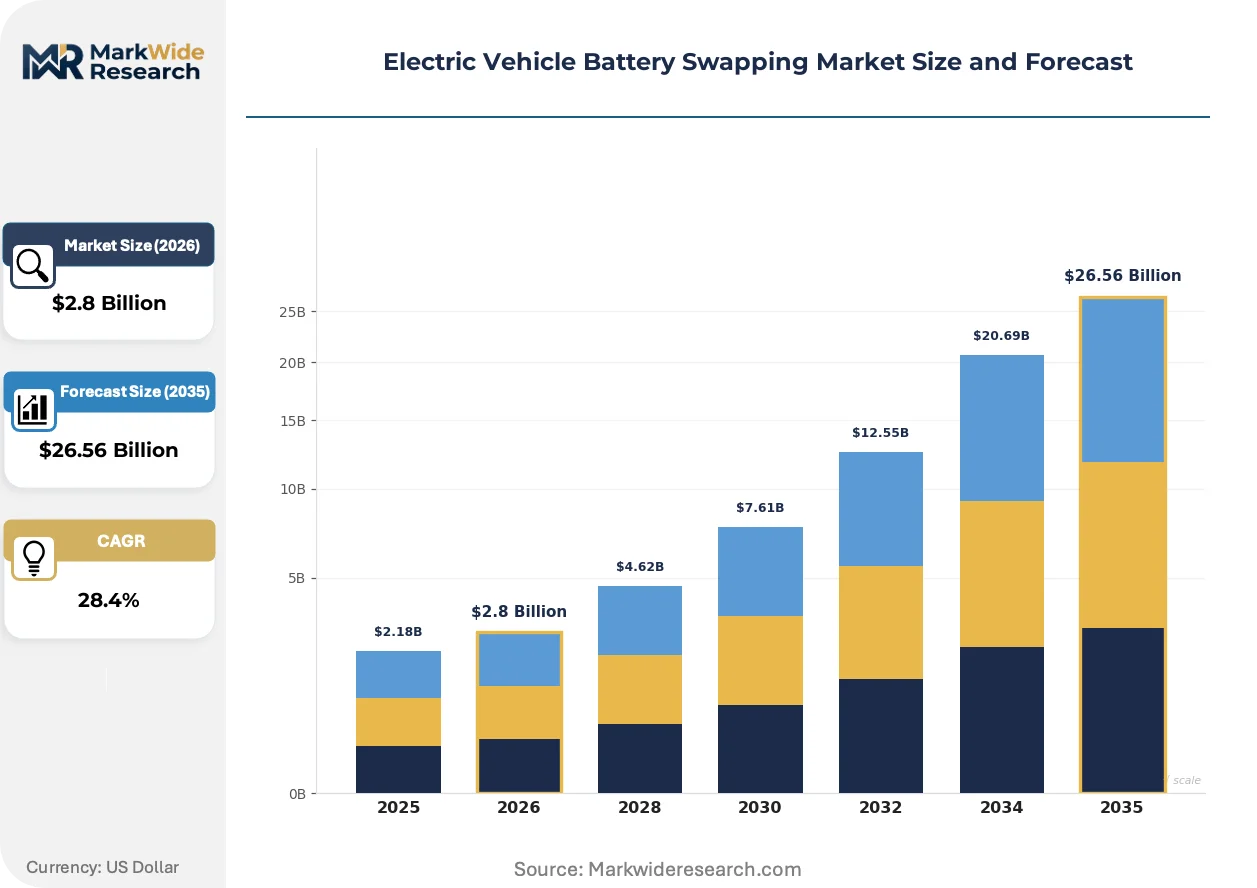
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $26.56 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Swapping Stations, Modular Batteries, Automated Systems, Smart Charging End User: Fleet Operators, Ride-Sharing Services, Public Transport, Individual Consumers Service Type: Subscription, Pay-Per-Swap, Membership, On-Demand Services Battery Type: Lithium-Ion, Solid-State, Lead-Acid, Nickel-Metal Hydride |
| Companies Covered | NIO, Gogoro, CATL, Ample, Sun Mobility, Battery Smart, Aulton New Energy, BAIC, KYMCO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle Battery Swapping Market Strategic Shifts & Innovations
Automated mechanical alignment systems are compressing swap times below three minutes while predictive battery health algorithms are shifting maintenance from reactive to preemptive models.
Robotic battery handling systems with machine-vision-guided alignment are displacing semi-automated station designs that required manual operator oversight. Fleet operators in Delhi and Bangalore are specifying fully automated stations in new procurement contracts. This displacement is compressing station opex and enabling twenty-four-hour unmanned operations.
The EU Battery Regulation's lifecycle traceability mandates are forcing non-compliant cell suppliers to exit European swapping networks. CE marking requirements now cover battery management system firmware and thermal runaway containment protocols. Modular pack suppliers are redesigning product architectures to satisfy digital passport obligations ahead of enforcement deadlines.
Fleet procurement teams are consolidating vendor relationships around operators offering integrated vehicle-battery-station subscriptions. Single-source contracting is replacing fragmented procurement of vehicles from OEMs, batteries from cell makers, and charging from utilities. This concentration is most visible among logistics operators in Hyderabad running centralized three-wheeler delivery pools.
Electric Vehicle Battery Swapping Market Segmentation
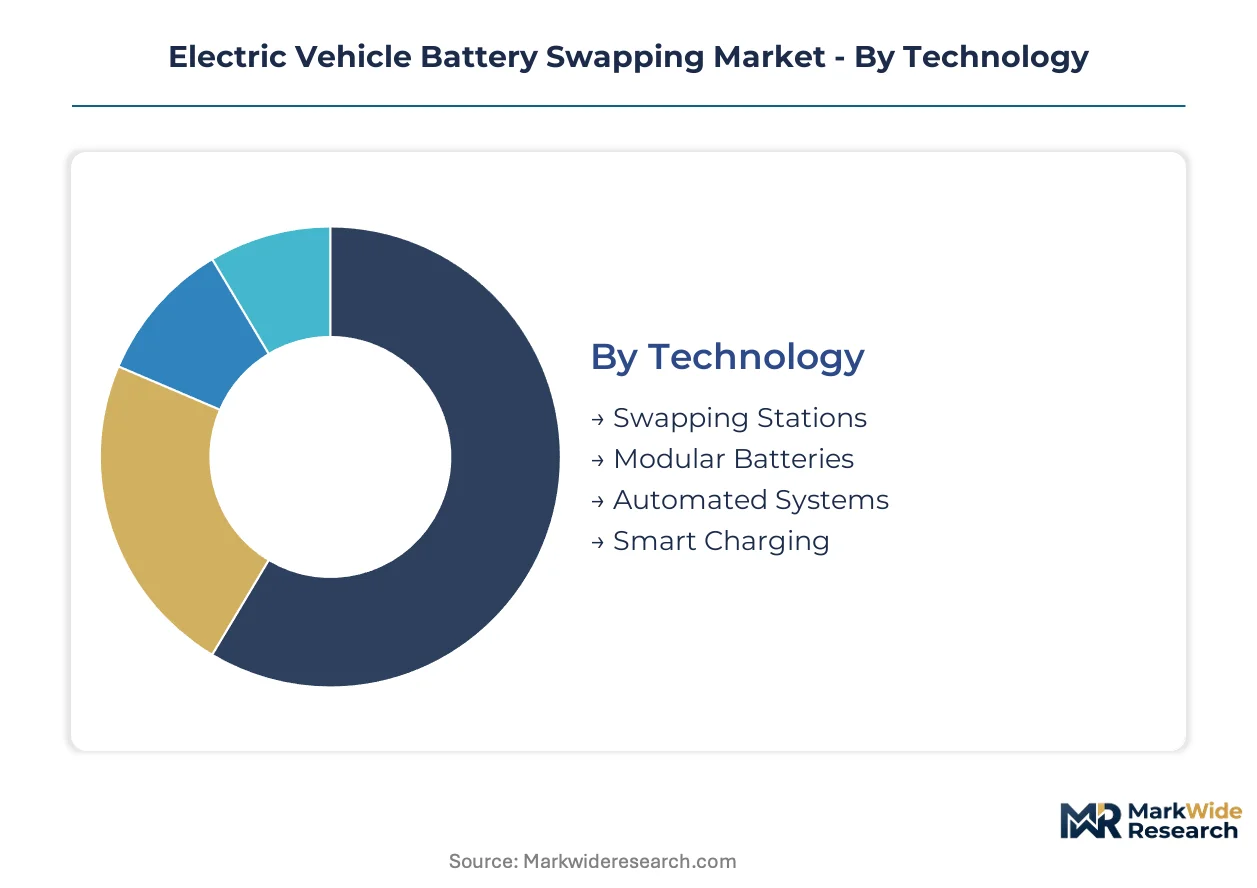
Segmentation in battery swapping markets determines capital allocation efficiency and technology roadmaps. Each dimension reveals distinct margin structures, regulatory exposure, and customer lifetime value profiles that shape operator strategy.
Technology:
Swapping stations face substitution pressure from ultra-fast charging corridors targeting passenger vehicles, while automated systems defend their position through irreplaceable sub-three-minute cycle times for commercial fleets.
- Swapping Stations:Fixed infrastructure housing robotic battery retrieval, thermal conditioning bays, and inventory management systems. Demand concentrates across Delhi, Bangalore, and Hyderabad where three-wheeler delivery fleets require 24-hour unmanned operations and grid-connection codes from India's CEA extend commissioning timelines.
- Automated Systems:Machine-vision-guided alignment mechanisms with predictive health verification. Logistics operators in China's premium passenger segment specify these for continuous duty cycles under MIIT's GB/T standardization, which determines subsidy qualification.
- Modular Batteries:Cell-to-pack architectures enabling third-party network expansion through standardized dimensions.
- Smart Charging:Grid-integrated power management with demand-response capabilities for station load balancing.
Swapping stations anchor the volume base while automated systems gain share at the steepest rate.
End User:
Cost tier differentiation separates fleet procurement teams seeking integrated vehicle-battery-station subscriptions from fragmented consumer purchasing patterns.
- Fleet Operators:Centralized vehicle management with predictable utilization rates and subscription revenue models. Last-mile delivery operators across logistics networks in India specify sub-five-minute energy replenishment, driving the most structurally attractive segment for operator margins.
- Ride-Sharing Services:High-frequency duty cycles with standardized vehicle platforms enabling battery pool efficiency. Taiwan's two-wheeler density supports network licensing models penetrating Southeast Asian markets.
- Public Transport:Municipal procurement with extended contract horizons and grid-scale power agreements.
- Individual Consumers:Fragmented demand with higher customer acquisition costs and intermittent utilization patterns.
Fleet operators anchor the volume base while ride-sharing services expand most quickly.
Service Type:
Application maturity varies from predictable recurring revenue in subscription models to transactional volatility in on-demand access.
- Subscription:Fixed monthly fees covering unlimited swaps with battery health guarantees. India's PLI scheme for advanced chemistry cell manufacturing reduces input costs for domestic operators offering these plans.
- Membership:Tiered access with priority station rights and discounted per-swap rates for registered users.
- Pay-Per-Swap:Transactional pricing without commitment, attracting intermittent users with higher per-unit margins.
- On-Demand Services:Mobile swapping units or emergency battery delivery for stranded vehicles.
Subscription models anchor the volume base while membership tiers climb the fastest.
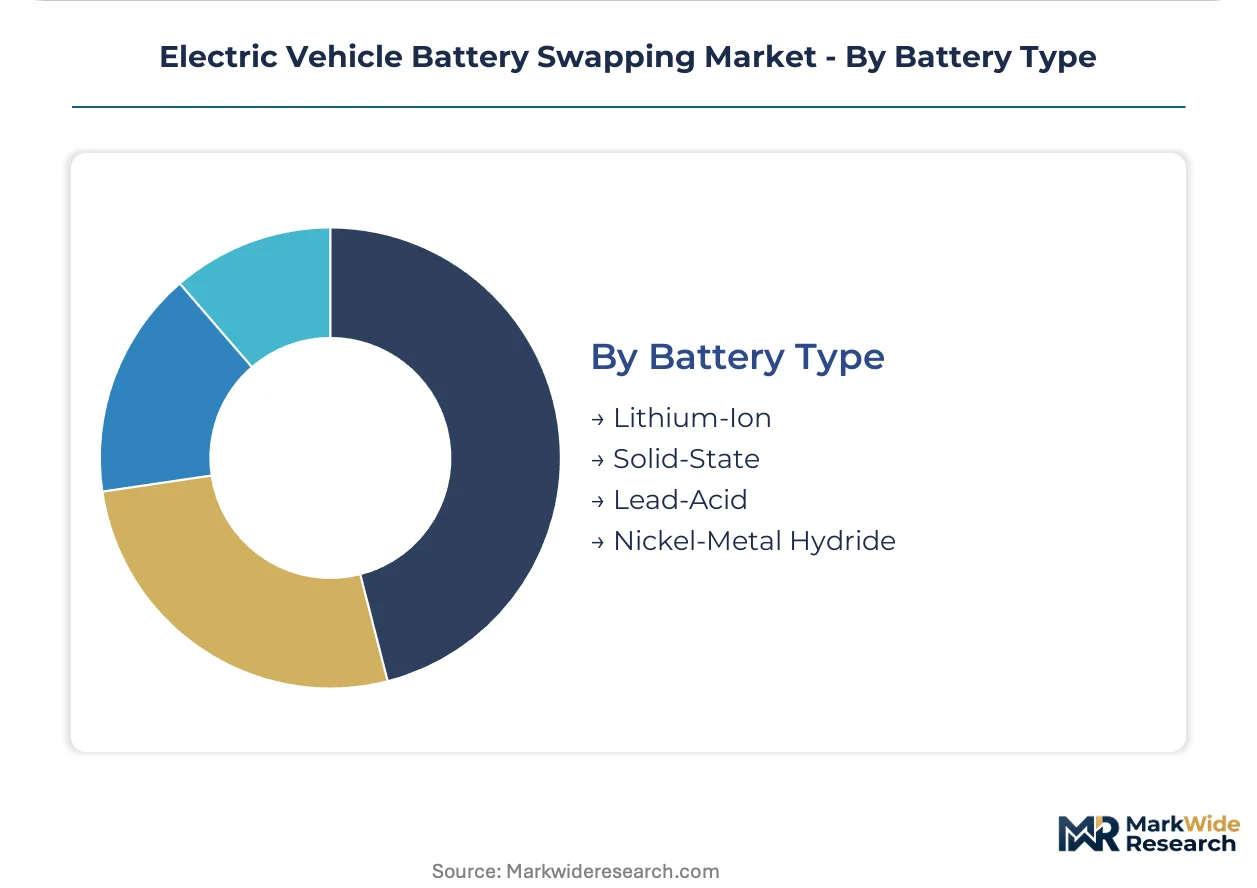
Battery Type:
Supply concentration in lithium-ion cell production shapes working capital requirements and raw material exposure across chemistry alternatives.
- Lithium-Ion:Dominant chemistry with established recycling infrastructure and cell-to-pack cost optimization. Price volatility in lithium and nickel compresses procurement margins for operators locked into fixed subscription pricing.
- Solid-State:Emerging architecture with higher energy density and reduced thermal runaway risk. The EU Battery Regulation's digital passport obligations are forcing redesigns ahead of enforcement deadlines.
- Nickel-Metal Hydride:Legacy chemistry in declining deployment for cost-sensitive applications.
- Lead-Acid:Minimal penetration limited to retrofitted low-speed vehicle conversions.
Lithium-ion anchors the volume base while solid-state gains share at the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China deploys battery swapping predominantly for premium passenger vehicles under state-mandated standardization, while India concentrates on two-wheeler and three-wheeler commercial fleets in dense urban corridors. This consumption-mix differential shapes divergent infrastructure economics and regulatory frameworks across major markets.
China
MIIT's GB/T specifications determine subsidy eligibility for vehicle-platform combinations, concentrating station deployment in the Yangtze River Delta and Pearl River Delta manufacturing belts. The dual carbon goals accelerate NEV mandate compliance timelines. Shanghai and Shenzhen host the densest swapping networks serving ride-hailing and premium passenger segments.
India
Last-mile delivery operators in Delhi, Bangalore, and Hyderabad drive three-wheeler swapping demand through centralized fleet procurement. BIS and CEA develop interoperability standards and grid-connection codes that shape power supply agreements. The PLI scheme for advanced chemistry cell manufacturing reduces input costs for domestic battery-as-a-service operators.
Taiwan
Two-wheeler density supports the highest per-capita swapping station penetration globally, with network licensing models now extending into Southeast Asian markets. Gogoro's proprietary ecosystem dominates urban corridors in Taipei and Kaohsiung. METI-referenced technical standards influence regional interoperability discussions.
Indonesia
Motorcycle fleet operators in Jakarta and Surabaya represent the largest unpenetrated two-wheeler market for licensed swapping network expansion. The national government's electric vehicle roadmap prioritizes battery-as-a-service models to circumvent grid infrastructure constraints. Minimal greenfield capex requirements attract foreign operator licensing agreements.
Germany
Commercial logistics operators in Bavaria and North Rhine-Westphalia pilot swapping for heavy-duty electric trucks on fixed distribution routes. The EU Battery Regulation's digital passport obligations constrain non-compliant cell suppliers from European network participation. KBA certification timelines for automated station systems extend market entry for foreign equipment vendors.
Electric Vehicle Battery Swapping Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with captive battery manufacturers and proprietary station architects commanding premium positioning against modular component suppliers. The market structure rewards backward integration into cell production and forward control over subscription service models. Three archetypes dominate: captive ecosystem operators with in-house battery manufacturing, network licensing platforms extending proven architectures into new geographies, and cell-to-pack suppliers enabling third-party operator scale. Competitive moves concentrate on strategic partnerships with fleet operators and technology licensing to reduce greenfield infrastructure risk.
Within the captive ecosystem tier, NIO and Gogoro exemplify divergent geographic specializations—NIO anchors premium passenger deployment in China while Gogoro occupies dense two-wheeler network positioning in Taiwan and licensed expansion markets. CATL represents the modular supply archetype, leveraging cell-to-pack cost positions to supply standardized battery formats without direct station operation exposure. These three companies illustrate how vertical integration depth separates premium-tier competitors from component-dependent challengers.
| Leading Market Players |
|---|
| NIO |
| Gogoro |
| CATL |
| Ample |
| Sun Mobility |
| Battery Smart |
| Aulton New Energy |
| BAIC |
| KYMCO |
| Others |
Cost & Logistics Intelligence
Station network scale economies in China's Yangtze River Delta manufacturing belt compress per-swap operating costs below the viability threshold for smaller regional operators, concentrating pricing power among vertically integrated players while forcing modular suppliers to compete on cell-to-pack cost positions alone.
Pricing Analysis
Long-term subscription contracts dominate fleet procurement, with logistics operators in Delhi and Hyderabad locking in fixed monthly fees for unlimited swaps. Price differentiation stems from automation tier and BIS certification status, with fully robotic stations commanding premiums over semi-automated alternatives. Cost compression in the pay-per-swap tier is intensifying because raw material volatility in lithium and nickel squeezes margins for operators without captive cell supply. Individual consumers exhibit the highest price sensitivity, while fleet procurement teams prioritize total cost of ownership over per-swap rates.
Supply Chain Analysis
Strategic stockpiling of lithium carbonate and nickel sulfate dominates operator inventory strategy, with China's CATL, South Korea's LG Energy Solution, and Japan's Panasonic anchoring cell supply. The supply chain draws from Chilean lithium brine operations, Indonesian nickel processing, and Australian spodumene concentrates. Single-source vulnerability in automated alignment robotics creates procurement risk for station equipment. Distribution runs through integrated vehicle-battery-station subscription bundles rather than fragmented component sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics in battery swapping are approaching an inflection as China's MIIT mandates open interoperability standards under GB/T specifications, collapsing the proprietary ecosystem premiums that previously sustained captive operators.
For Market Incumbents: Consolidate control over captive battery manufacturing and proprietary station architecture to defend against modular suppliers eroding margins through standardized cell-to-pack formats. Expand automated thermal management capabilities to cut per-swap labor costs toward zero. Secure certification pipelines for automation engineers before station deployment outpaces vocational training output in India and Southeast Asia. For New Entrants and Emerging Players: Differentiate on interoperability-first network design that complies with emerging BIS and CEA standards in India, where three-wheeler fleet procurement remains fragmented across incompatible pack formats. Target Jakarta and Surabaya motorcycle fleet operators through licensing agreements with established Taiwanese network platforms. Pursue battery-as-a-service tax incentives under India's PLI scheme for advanced chemistry cell manufacturing to offset greenfield capex requirements. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors operators with backward integration into cell production and forward control over subscription revenue streams rather than pure-play station equipment vendors. Long-term viability hinges on securing fleet procurement relationships with centralized vehicle management and predictable utilization rates. Watch for India's CEA grid-connection approval timelines as the signal indicating whether station network expansion can match fleet operator deployment schedules.| Strategic Initiative | Industry Significance |
|---|---|
| GB/T Standardization Compliance | MIIT certification determines subsidy eligibility for vehicle-platform combinations in China's premium passenger segment. |
| Automated Thermal Management Integration | Predictive battery health algorithms shift maintenance from reactive to preemptive models across Delhi logistics networks. |
| Network Licensing Expansion | Taiwanese operators leverage proven two-wheeler density models to penetrate Indonesia's motorcycle market with minimal capex. |
| PLI Scheme Utilization | India's advanced chemistry cell manufacturing incentives reduce input costs for domestic battery-as-a-service operators. |
| Interoperability Architecture Development | BIS and CEA standards shape power supply agreements and consumer safety certifications for open network participation. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with swapping station operators, fleet procurement managers, and automation systems engineers; and secondary validation through MIIT GB/T specification documents, BIS interoperability draft standards, CEA grid-connection codes, and customs data on lithium-ion cell imports. Bottom-up triangulation across station deployment counts and top-down reconciliation against fleet operator subscription disclosures anchored volume estimates.
Across the modeling period, projections incorporate technology segmentation by automation tier, service type by contract structure, battery chemistry by cell format, and end-user concentration by fleet centralization. CAGRs derive from logistic curve fitting to station penetration rates and battery inventory turnover assumptions. Forecast inputs include raw material price indices for lithium carbonate and nickel sulfate, plus CEA certification timeline distributions for high-capacity charging infrastructure.
Material uncertainties — regulatory acceleration of open swapping architectures, commodity price volatility compressing subscription margins, and grid-connection approval delays extending station commissioning — sit outside the modeled envelope. Forecasts reflect assumptions about standardization timeline adherence and fleet procurement consolidation trajectories. Revision becomes warranted when interoperability mandate adoption crosses thresholds that collapse proprietary ecosystem premiums.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Infrastructure
Battery-As-A-Service Market
Battery Infrastructure
Global Automotive 48 Volt Battery System Market
Battery Infrastructure
Battery Raw Materials Market
Battery Infrastructure
Italy Electric Vehicle Battery Separator Market
Battery Infrastructure
Asia Pacific Electric Vehicle Battery Separator Market
Battery Infrastructure
Europe Lithium Foil Market
Battery Infrastructure
United States Electric Vehicle Battery Separator Market
Battery Infrastructure
China Electric Vehicle Battery Electrolyte Market
Battery Infrastructure
China Battery Manufacturing Equipment Market
Battery Infrastructure
Substation Battery Market
Battery Infrastructure
United Kingdom Electric Vehicle Battery Separator Market
Battery Infrastructure
New Energy Battery Structural Parts Market
Battery Infrastructure
Battery Enclosure Market
Battery Infrastructure
North America Electric Vehicle Battery Manufacturing Equipment Market
Battery Infrastructure
EV Battery Sealant Market
Battery Infrastructure
ASEAN Countries Electric Vehicle Battery Separator Market