
 Global Battery Packaging Market | 2026-2036
Global Battery Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Global Battery Packaging Market Intelligence
The mandatory adoption of UN 38.3-certified packaging for lithium battery transport is collapsing the market's previous tiered structure based on general-purpose versus high-safety containers. This shift creates opportunities for specialized providers. Nefab Group leverages its expertise in engineered packaging to serve complex electric vehicle battery module logistics. Meanwhile, DuPont specializes in high-performance polymers and materials that enhance thermal management and impact resistance for battery enclosures.
Battery packaging encompasses engineered enclosures and materials designed to contain and protect cells, modules, and packs from short circuits, thermal runaway, and physical damage. These solutions often incorporate fire-retardant plastics and non-conductive cushioning to ensure safe handling and transport. While foil pouches dominate the consumer electronics application, rigid plastic cases and custom-engineered containers are essential for the larger formats used in electric vehicles. The electric vehicles segment represents the fastest-growing application area.
Global regulations, including the UN Manual of Tests and Criteria and specific enforcement by the US DOT and Europe's ADR framework, dictate stringent testing for battery packaging. These rules mandate performance standards for shock, vibration, and thermal stress, directly shaping product design and material selection. Consequently, material suppliers and converters must navigate the trade-off between higher-performance, fire-retardant materials and the push for lightweight, cost-effective solutions for mass-market applications.
Market Dynamics
The mandatory global adoption of UN 38.3 transportation safety standards for lithium-ion batteries is the central force reshaping the market. This regulatory pressure collapses distinctions between general-purpose and high-safety containers, compelling a universal shift toward certified, engineered solutions.
Growth Catalysts
- Electric Vehicle Production:The rapid expansion of electric vehicle manufacturing, especially within gigafactory clusters in China and the United States, creates sustained, high-volume demand for custom-engineered packaging for large-format battery modules and packs.
- Stricter Transport Regulations:Enforcement of the UN Manual of Tests and Criteria by authorities like the US DOT and through Europe's ADR framework mandates performance-tested packaging, driving adoption of higher-value, certified products.
- Circular Economy Initiatives:The emerging battery recycling and second-life market requires new categories of robust, reusable packaging designed for reverse logistics, creating a new demand stream for specialized containers.
Market Restraints
- Material Cost Volatility:Fluctuations in the price of essential high-performance materials, such as fire-retardant polymers and specialized aluminum alloys, create margin pressure and pricing instability for packaging converters.
- Weight-to-Protection Trade-off:A persistent technical conflict exists between the need for robust, impact-resistant packaging to meet safety rules and the demand for lightweight solutions to reduce shipping costs and optimize vehicle efficiency.
- Supply Chain Concentration:The market for UN-certified packaging solutions is concentrated among a finite number of specialized suppliers with the requisite testing and engineering capabilities, creating potential supply bottlenecks.
Strategic Opportunities
- Packaging for Battery Recycling:A significant opportunity exists in developing standardized, durable containers for the safe collection and transport of end-of-life EV batteries to recycling facilities, an underserved but growing logistics segment.
- Sustainable Material Development:Material science firms can gain share by commercializing bio-based or high-recycled-content polymers that meet stringent fire retardancy and impact standards while satisfying automotive OEM sustainability mandates.
- Localized Supply for New Gigafactories:Establishing packaging fabrication and certification facilities near new battery manufacturing hubs in North America and Eastern Europe presents an opportunity to serve localized demand and reduce logistics costs.
Industry Challenges
- Complex Certification Pathways:The time-consuming and costly process of achieving UN 38.3 and other regional certifications for new packaging designs acts as a barrier to entry and can delay product introductions for suppliers.
- Lack of Pack Design Standardization:The proliferation of bespoke battery pack and module designs across different automotive OEMs inhibits the development of scalable, modular packaging, increasing engineering overhead for each new vehicle program.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Battery Packaging Market |
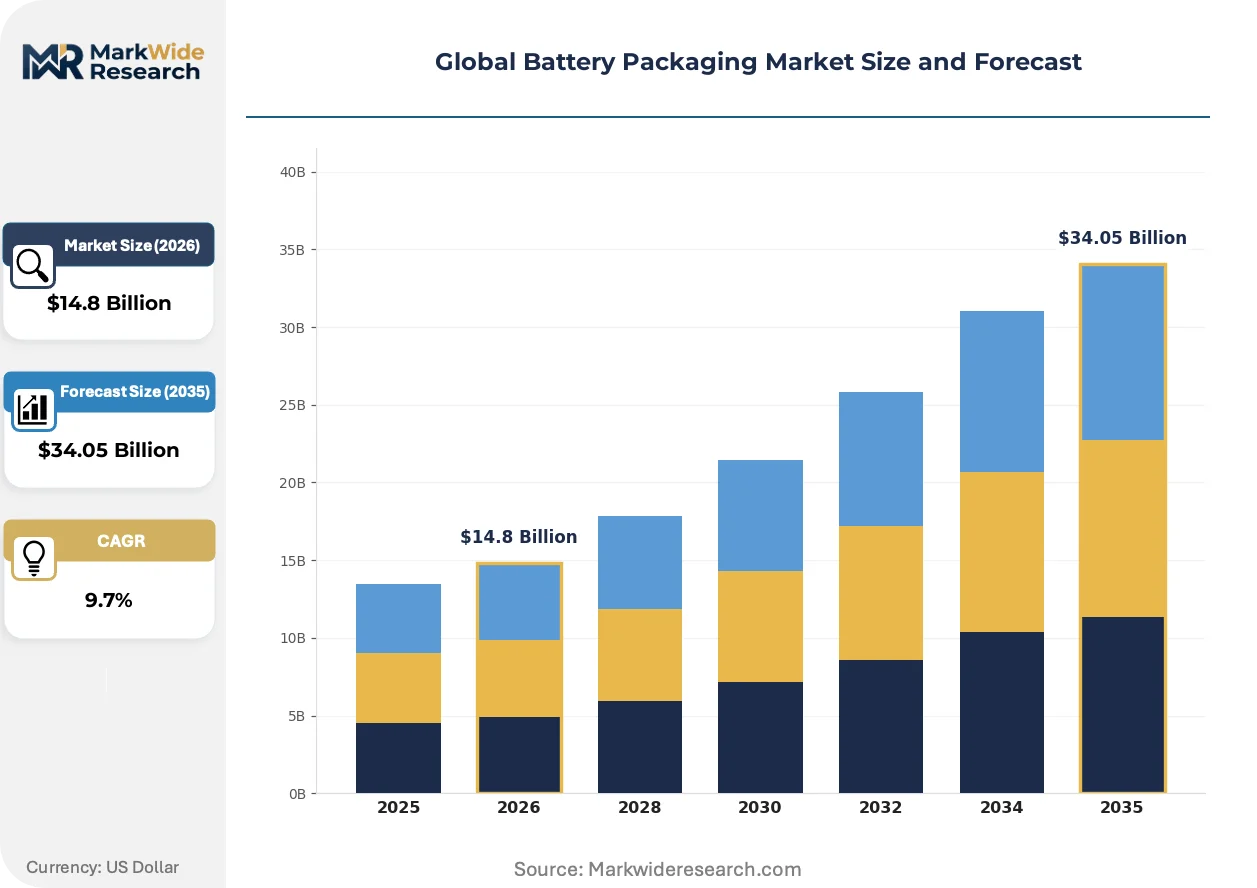
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $34.05 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foil Pouches, Plastic Cases, Metal Cans, Paperboard Boxes Material: Polypropylene, Aluminum, PET, PVC, HDPE, Cellulose Application: Electric Vehicles, Consumer Electronics, Industrial Equipment, Energy Storage Systems End User: OEMs, Aftermarket Suppliers, Tier-1 Manufacturers, Vehicle Assemblers |
| Companies Covered | Nefab Group, Wellplast AB, Toppan Inc., Amcor Rigid Plastics USA, Inc., C.L. Smith, 3M, DuPont, Trinseo, Covestro AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Battery Packaging Market Strategic Shifts & Innovations
Material science and regulatory pressures are converging to redefine battery packaging from a simple container into an engineered safety system. This evolution prioritizes thermal management, impact resistance, and end-of-life considerations over basic containment, influencing design from the polymer level up.
Intelligent packaging incorporating embedded sensors for thermal and impact monitoring provides real-time data on battery condition during transport. Logistics providers handling high-value prototype and pre-production EV batteries are the primary adopters of this technology. The advent of these systems is bifurcating the market into standard certified containers for bulk transport and premium, data-rich solutions for critical, high-risk shipments.
Europe's proposed Battery Regulation is directly influencing packaging design by emphasizing circular economy principles. The regulation introduces mandates for recycled content and easier disassembly, compelling a shift toward enclosures that facilitate automated removal and sorting of cells. Automotive OEMs and their suppliers operating in the EU are most affected, redesigning packaging to account for end-of-life processing.
A definitive shift toward reusable and collapsible packaging systems is gaining momentum, driven by cost-reduction programs and sustainability goals at major battery manufacturers. This model disrupts the traditional supply of single-use disposable packaging, creating demand for durable, multi-use containers supported by reverse logistics services. This trend is most visible within closed-loop supply chains connecting gigafactories to automotive assembly lines in China and Europe.
Global Battery Packaging Market Segmentation
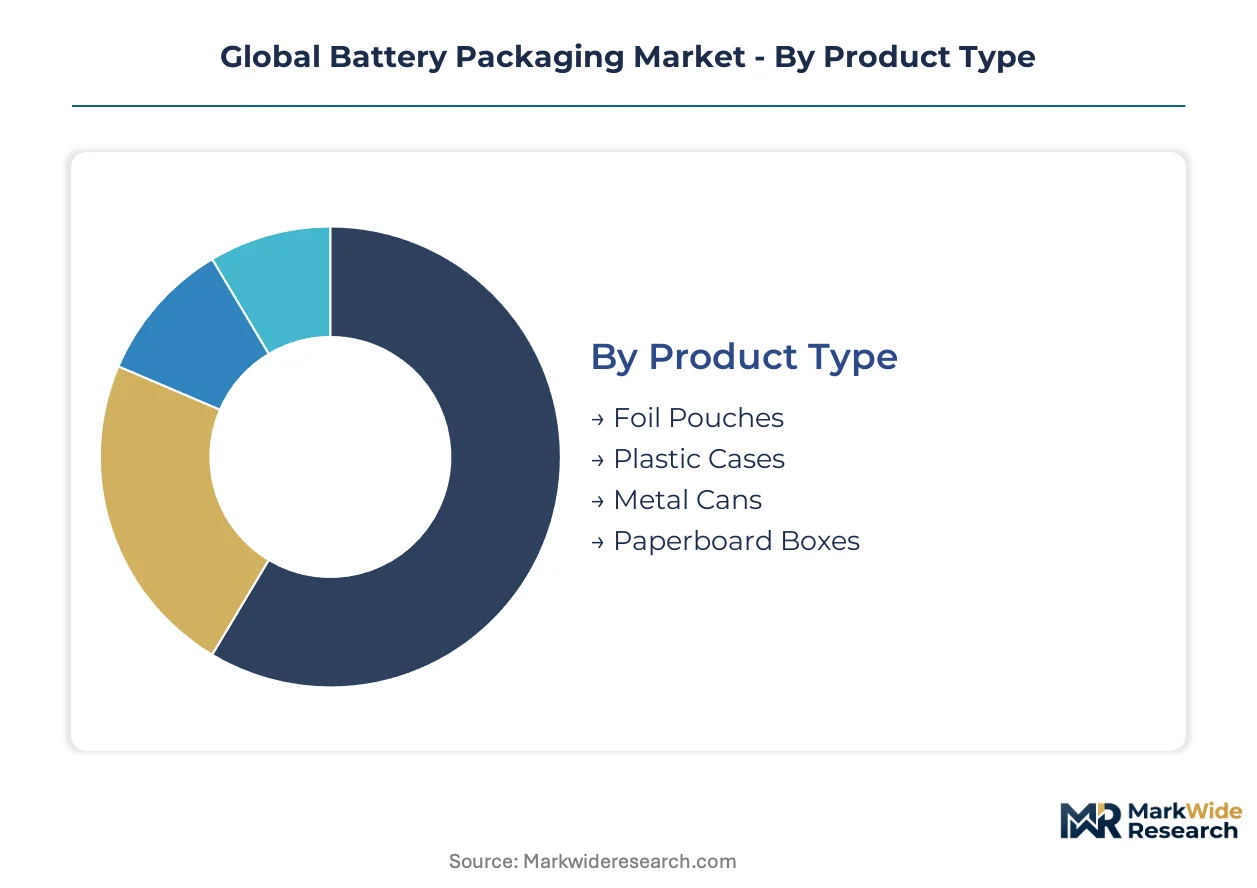
Understanding the segmentation of the global battery packaging market reveals how diverse applications and regulatory mandates shape product development and material selection. This granular view helps identify areas of concentrated demand and specific technological requirements. Market dynamics are particularly influenced by the stringent safety standards for lithium-ion battery transport.
Product Type:
Margin pools in product type segmentation are concentrated in custom-engineered solutions for large-format batteries, driven by electric vehicle demand.
- Plastic Cases:These rigid enclosures provide robust protection against impact and vibration, often incorporating fire-retardant additives for enhanced safety. Demand for plastic cases is particularly strong in the electric vehicle sector, where they protect high-voltage battery modules during transport and assembly in China and Europe.
- Metal Cans:Constructed from aluminum or steel, metal cans offer superior thermal management and impact resistance, crucial for high-energy density battery packs. These durable containers are essential for shipping prototype and pre-production electric vehicle batteries to assembly plants in Germany and the United States.
- Foil Pouches:Lightweight and flexible, foil pouches are primarily used for smaller, prismatic cells in consumer electronics applications.
- Paperboard Boxes:Economical and recyclable, these are suitable for low-risk, smaller format batteries or as secondary packaging for less hazardous cells.
Plastic Cases holds installed capacity. Metal Cans is rotating up the share rankings.
Material:
Cost tiers for battery packaging materials reflect performance requirements and raw material availability, influencing overall packaging economics.
- Aluminum:Valued for its high strength-to-weight ratio and excellent thermal conductivity, aluminum is a premium material for critical battery enclosures requiring superior thermal management. Its use is expanding in high-performance electric vehicle battery packs, particularly in manufacturing hubs across Asia and North America.
- Polypropylene:A versatile and cost-effective polymer, polypropylene offers good impact resistance and can be formulated with fire-retardant properties for various battery packaging applications. It sees significant use in rigid plastic cases for both consumer electronics and smaller electric vehicle modules, especially in cost-sensitive markets.
- PET:Polyethylene terephthalate is a lightweight plastic often used for blister packaging or protective films around smaller battery cells.
- PVC:Polyvinyl chloride provides good chemical resistance and is used for insulation and protective wraps in certain battery configurations.
- HDPE:High-density polyethylene offers durability and moisture resistance, making it suitable for reusable transport containers.
- Cellulose:Derived from plant fibers, cellulose-based materials are increasingly explored for sustainable and lightweight packaging solutions, particularly for smaller batteries.
Material innovation is critical for balancing safety and cost.
Application:
Volume requirements dictate the scale and automation needed for packaging solutions across diverse applications, from individual cells to large battery packs.
- Electric Vehicles:This segment demands highly engineered, UN 38.3 certified packaging for large-format battery modules and complete packs, focusing on thermal management and impact protection. The rapid expansion of gigafactories in China and the United States drives substantial demand for specialized EV battery packaging.
- Energy Storage Systems:Packaging for grid-scale and residential energy storage systems requires robust, durable enclosures capable of protecting large battery units over extended periods. These systems, critical for renewable energy integration, necessitate secure transport solutions to installation sites globally.
- Consumer Electronics:Packaging for consumer electronics batteries emphasizes compact design, cost-efficiency, and protection against minor impacts for devices like smartphones and laptops.
- Industrial Equipment:This application includes packaging for batteries used in forklifts, robotics, and other heavy machinery, requiring sturdy and often reusable containers.
The fastest-growing trajectory for packaging demand is in new energy sectors.
End User:
Supply concentration among end users influences procurement strategies and long-term partnership development within the battery packaging ecosystem.
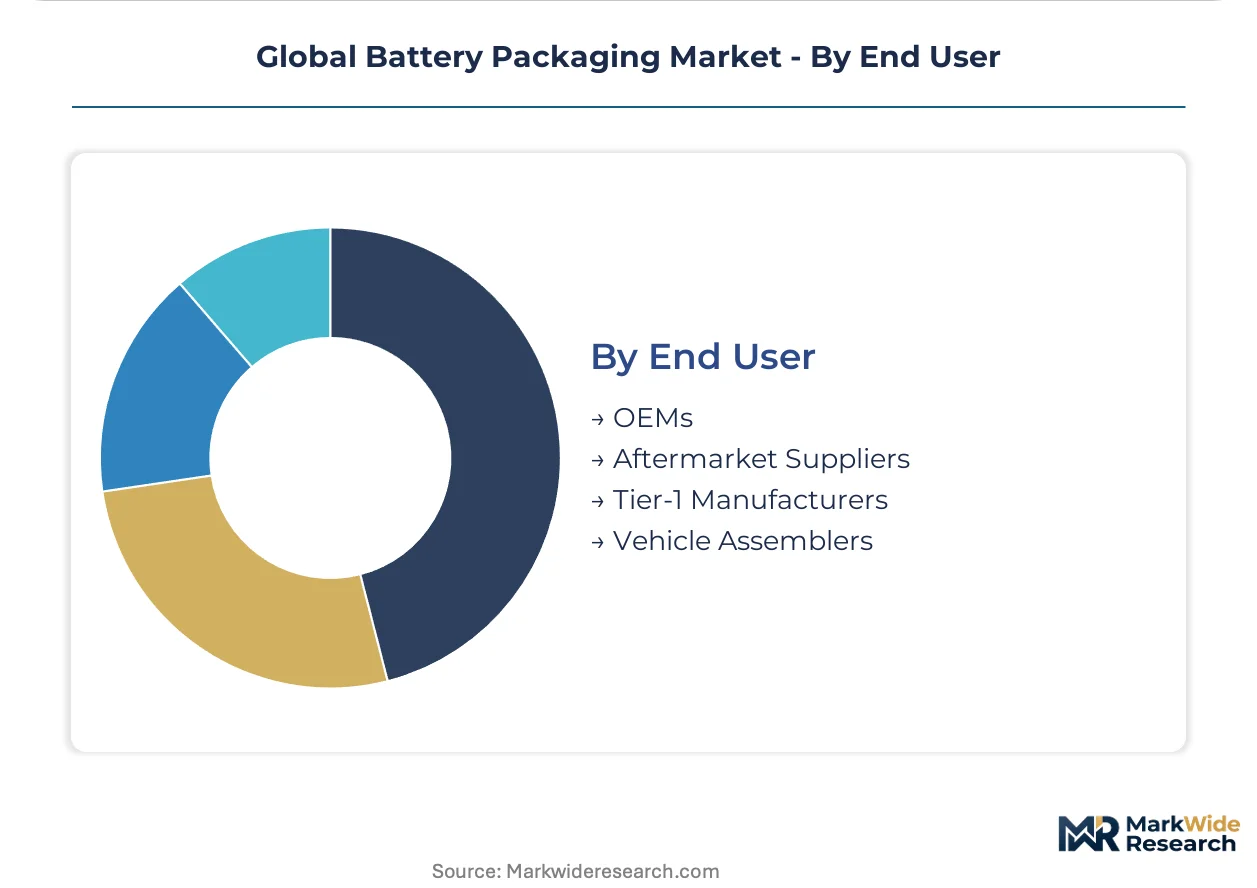
- OEMs:Original Equipment Manufacturers, particularly in the automotive sector, directly procure highly specialized and often custom-designed packaging solutions for their specific battery pack configurations. Automotive OEMs in Germany and Japan are key drivers for advanced packaging development.
- Tier-1 Manufacturers:These suppliers, often producing battery modules or complete packs for OEMs, require packaging that integrates seamlessly into their production and logistics chains. Tier-1 battery producers in South Korea and the United States are significant purchasers of certified packaging.
- Aftermarket Suppliers:This segment includes companies providing replacement batteries or components, requiring packaging for individual cells or smaller battery units.
- Vehicle Assemblers:While often receiving pre-packaged battery modules, assemblers may require specific internal packaging or handling solutions for their production lines.
Direct engagement with manufacturers shapes product development and delivery schedules.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global battery packaging market exhibits significant supply-side concentration, particularly in regions with established battery manufacturing ecosystems. This concentration is heavily influenced by the rapid expansion of electric vehicle production and stringent transportation safety standards. Key geographic areas are developing specialized capabilities to meet this localized demand for certified packaging solutions.
China
China's rapid expansion of electric vehicle production and battery gigafactories drives immense demand for specialized packaging. The country's dual carbon goals and GB standards mandate high-performance, certified solutions for safe transport. Major battery manufacturing hubs like the Yangtze River Delta region are experiencing localized surges in packaging fabrication to support these operations.
United States
The United States sees strong demand from domestic electric vehicle manufacturing and large-scale energy storage system deployments. US DOT enforcement of UN 38.3 standards ensures rigorous performance requirements for battery packaging. New gigafactory clusters across southern states are attracting packaging suppliers to establish local production capabilities.
Germany
German automotive OEMs contribute significantly to demand for engineered battery packaging for their vehicle assembly lines. Europe's ADR framework and the upcoming EU Battery Regulation shape design requirements for safety and circularity. Automotive supply chain hubs in Bavaria and North Rhine-Westphalia are adapting packaging solutions for end-of-life processing.
South Korea
South Korea's leading Tier-1 battery manufacturers create substantial demand for advanced packaging solutions supporting global exports. METI and PMDA standards influence the design and certification of high-performance battery containers. Major battery production facilities in the Seoul Capital Area and Busan-Ulsan drive innovation in packaging materials and logistics.
Japan
Japan's established automotive industry and ongoing R&D in advanced battery technologies generate demand for specialized protective packaging. JIS standards and METI guidelines ensure strict adherence to safety protocols for battery transport. The Kanto region, a major manufacturing hub, sees continuous development of innovative packaging for new battery formats.
Global Battery Packaging Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the global battery packaging market. The market structure exhibits a tiered consolidation, with a few specialized engineering firms dominating the high-performance end and a broader base of material converters and general packaging suppliers. Strategic archetypes include custom solution providers for EV batteries, material science innovators developing fire-retardant polymers, and high-volume commodity producers for consumer electronics. Dominant competitive moves involve strategic partnerships for integrated logistics solutions and continuous portfolio diversification into new battery formats and recycling applications.
Specialists in engineered solutions include Nefab Group, which leverages its expertise for complex electric vehicle battery module logistics. DuPont, a materials science firm, exemplifies innovation in high-performance polymers that enhance thermal management and impact resistance for battery enclosures. Germany-based Covestro AG also operates within this segment, providing advanced material formulations for robust and safe battery packaging applications. These firms represent key players shaping the market's technological trajectory and driving material advancements for critical safety and performance requirements across diverse battery applications.
| Leading Market Players |
|---|
| Nefab Group |
| Wellplast AB |
| Toppan Inc. |
| Amcor Rigid Plastics USA, Inc. |
| C.L. Smith |
| 3M |
| DuPont |
| Trinseo |
| Covestro AG |
Cost & Logistics Intelligence
A 6-month lead time for UN 38.3 certified custom battery packaging directly influences supply chain shape and grants pricing power to specialized manufacturers. This market demands robust, performance-tested solutions for safe battery transport. Supply concentration among a few capable vendors creates bottlenecks for automotive OEMs and Tier-1 suppliers.
Pricing Analysis
UN 38.3 standards dictate the pricing tier structure for battery packaging, compelling a shift towards higher-value, certified solutions. Contract-based, project-specific pricing dominates for custom-engineered EV battery solutions. Differentiation stems from certification level, material performance (e.g., fire retardancy), and customization for specific battery pack designs. Material cost volatility, especially for specialized polymers and alloys, creates margin pressure. Automotive OEMs are less price-sensitive for mission-critical EV battery packaging, while consumer electronics applications prioritize cost-efficiency.
Supply Chain Analysis
Constrained availability of specialized containers for high-energy battery transport drives inbound logistics costs. Supply for high-performance battery packaging concentrates in China, South Korea, and Germany, reflecting established battery manufacturing ecosystems. The market relies on specialized fire-retardant polymers and lightweight aluminum alloys as key inputs. A structural risk involves the finite number of certified suppliers capable of meeting stringent regulatory demands. Distribution primarily runs directly to battery gigafactories and automotive assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a high-growth disruption, driven by the mandatory adoption of UN 38.3 transportation safety standards for lithium-ion batteries across global logistics networks.
For Market Incumbents: Shield existing market share by investing in rapid certification processes for new battery chemistries and pack designs. Expand localized production capabilities near emerging gigafactory clusters in North America to mitigate logistics risks. Develop sustainable, reusable packaging solutions to counter the threat of single-use product obsolescence mandated by circular economy initiatives. Focus R&D on advanced thermal management materials.
For New Entrants and Emerging Players: The underserved segment of robust, reusable packaging for battery recycling offers a significant service-layer gap. Target this reverse logistics segment by offering standardized, durable containers compliant with future EU Battery Regulation mandates. Commercialize bio-based or high-recycled-content polymers that meet stringent safety standards. A go-to-market angle involves partnering with battery recycling facilities to streamline collection and transport.
For Investors and Strategic Acquirers: Long-term, this sits as a critical infrastructure play because battery packaging is essential for the safe, compliant, and efficient deployment of electric vehicles and energy storage systems. Acquisition targets should include specialized engineering firms with proprietary certification expertise or material science companies developing next-generation fire-retardant plastics. A signal to watch is the rate of standardization in battery pack designs, which would enable more scalable packaging solutions.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Localized Production | Reduces logistics costs and lead times for regional gigafactories in the United States. |
| Invest in Sustainable Material R&D | Addresses automotive OEM sustainability mandates and prepares for future recycled content regulations. |
| Develop Reverse Logistics Solutions | Captures new demand from the emerging battery recycling and second-life markets. |
| Pursue Strategic Partnerships | Integrates specialized packaging expertise with battery manufacturers and logistics providers. |
| Enhance Certification Capabilities | Ensures compliance with evolving UN 38.3 and regional transportation safety standards. |
Research Approach
Desk research of industry reports, regulatory filings, and academic journals preceded structured interviews with automotive OEM procurement leads, battery module engineers, packaging logistics managers, and material science R&D directors. This approach combined primary insights with secondary validation, ensuring a comprehensive understanding of market dynamics. Bottom-up and top-down triangulation methods were employed to cross-verify data and derive robust market estimations, encompassing both volume and value metrics.
Variance decomposition informed the analytical framework across the projection horizon, isolating the impact of key drivers, restraints, and opportunities. The model integrated segmentation dimensions including product type, material, application, end user, and regional manufacturing capacity. Compound annual growth rates were derived from historical trends and forward-looking projections, incorporating inputs such as EV production forecasts and battery gigafactory build-out schedules.
Forecasts assume regulatory continuity in UN, US DOT, Europe's ADR framework, and China's GB standards; material policy shifts would require re-modeling. These projections reflect underlying assumptions regarding technological advancements and market adoption rates. Unforeseen changes in battery chemistry or geopolitical trade restrictions impacting material supply represent key risk factors. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Infrastructure
North America Electric Vehicle Battery Electrolyte Market
Battery Infrastructure
United States Battery Manufacturing Equipment Market
Battery Infrastructure
Battery Lug Market
Battery Infrastructure
EV Battery Sealant Market
Battery Infrastructure
France Electric Vehicle Battery Separator Market
Battery Infrastructure
Automotive Battery Plate Market
Battery Infrastructure
Electric Vehicle Battery Swapping Market
Battery Infrastructure
United States Electric Vehicle Battery Separator Market
Battery Infrastructure
Italy Electric Vehicle Battery Separator Market
Battery Infrastructure
Global Automotive 48 Volt Battery System Market
Battery Infrastructure
Battery Enclosure Market
Battery Infrastructure
France Electric Vehicle Battery Manufacturing Equipment Market
Battery Infrastructure
China Electric Vehicle Battery Manufacturing Equipment Market
Battery Infrastructure
Germany Electric Vehicle Battery Manufacturing Equipment Market
Battery Infrastructure
New Energy Battery Structural Parts Market
Battery Infrastructure
China Electric Vehicle Battery Electrolyte Market