
 ASEAN Countries Electric Vehicle Battery Manufacturing Equipment Market | 2026-2036
ASEAN Countries Electric Vehicle Battery Manufacturing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
ASEAN Countries Electric Vehicle Battery Manufacturing Equipment Market Insights
Thai electrode coating facilities is realigning capacity to serve CATL-affiliated cell plants in the Eastern Economic Corridor. ABB Ltd. leverages its robotics integration heritage to dominate assembly line automation for pouch and prismatic formats. Schuler AG sustains competitive position through its mechanical press expertise adapted to Asian cathode compaction specifications. WONIK PNE CO., LTD. anchors regional formation and aging system supply with localized service networks in Thailand and Vietnam.
ASEAN Countries Electric Vehicle Battery Manufacturing Equipment encompasses machinery for electrode slurry mixing, calendaring, cell stacking, electrolyte filling, and electrochemical formation testing, operating at precision tolerances below 10 micrometers for thickness uniformity and moisture-controlled environments below 100 ppm to prevent lithium degradation. Coating Systems and Testing Equipment segments attract disproportionate capital allocation as cell makers pursue higher energy density cathodes and 100% inline defect detection. Lithium-Ion technology equipment occupies the dominant revenue share, though Solid-State pilot line investments are accelerating in Singapore and Malaysian research corridors.
Thailand's Board of Investment coordinates with the country's national automotive regulator to mandate local content thresholds for EV supply chain equipment, while Indonesia's mineral downstreaming policies enforced by the investment ministry redirect nickel processing profits into battery plant machinery procurement. Singapore's Enterprise Singapore and Malaysia's MIDA both administer clean technology manufacturing grants that lower capital barriers for equipment installation. Stakeholders must monitor which ASEAN member state secures the next integrated gigafactory commitment, as this will dictate regional equipment vendor qualification priorities and service infrastructure placement for the coming decade.
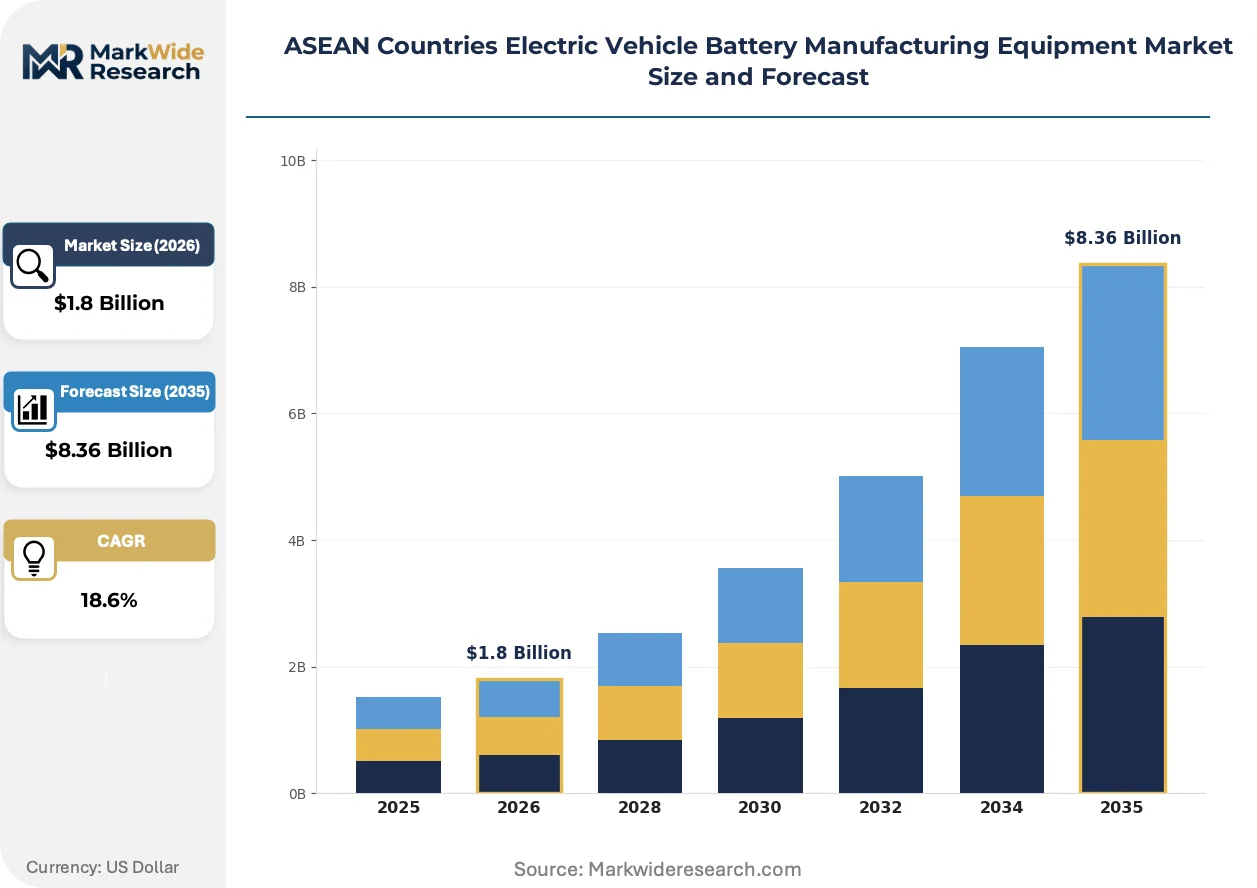
Market Dynamics
Indonesia's nickel downstreaming mandates and Thailand's Board of Investment incentive schemes are redirecting capital flows from raw mineral export toward localized electrode coating and formation equipment manufacturing, compressing lead times for ASEAN-based cell producers.
Growth Catalysts
- Thailand's BOI Incentive Schemes:Tax holidays and import duty exemptions for machinery procurement are accelerating domestic equipment vendor qualification in the Eastern Economic Corridor.
- Indonesia's Mineral Downstreaming Policies:Investment ministry enforcement of nickel processing localization is channeling smelter profits into battery plant machinery procurement.
- CATL-Affiliated Cell Plant Expansion:Chinese battery makers are qualifying Thai equipment vendors for electrode coating lines, creating spillover demand for precision calendaring systems.
Market Restraints
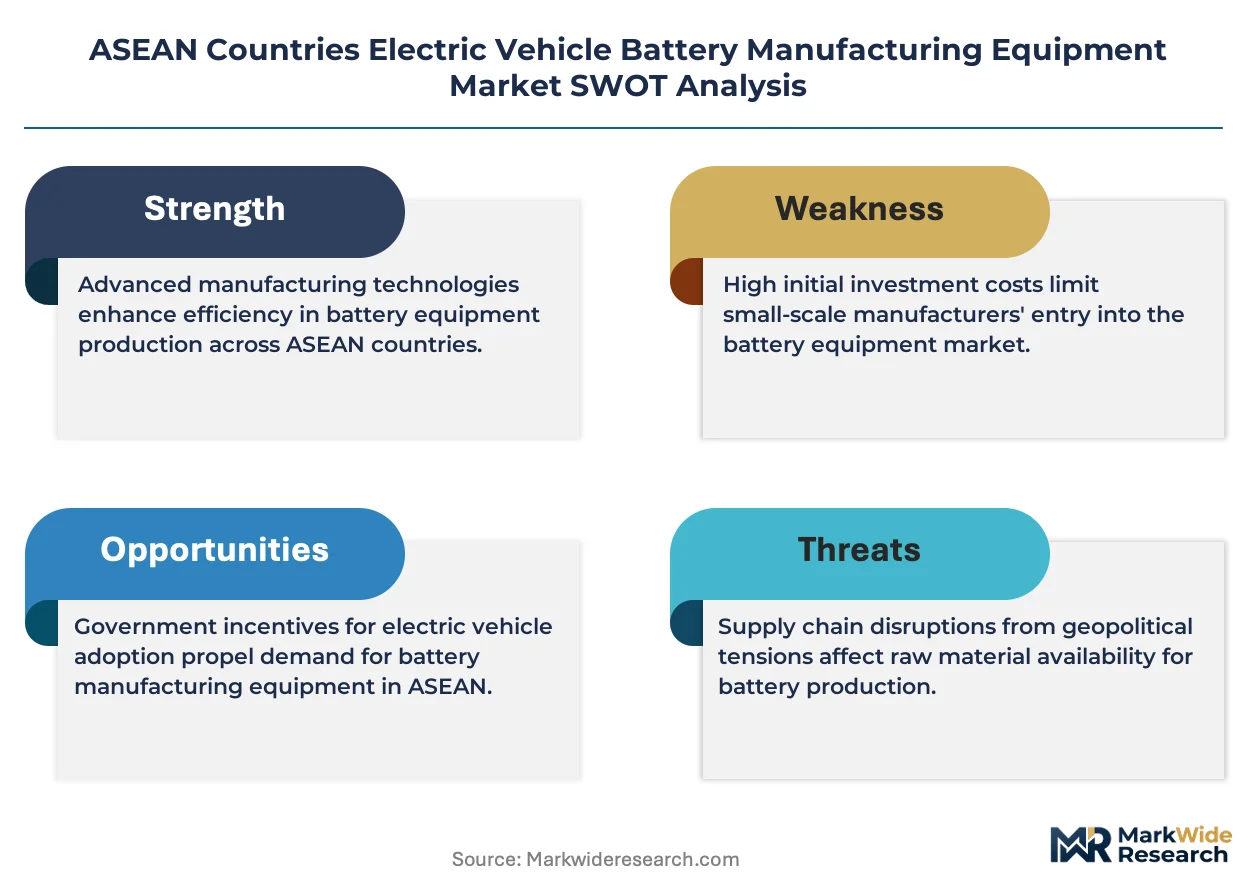
- High-Precision Component Import Dependence:Laser cutting heads and precision motion controllers remain concentrated with German and Japanese suppliers, exposing ASEAN integrators to yen and euro volatility.
- Moisture-Control Infrastructure Costs:Dry room construction for sub-100 ppm environments requires specialized HVAC and dehumidification systems that inflate facility capex by 40-60% versus standard cleanrooms.
- Solid-State Pilot Line Uncertainty:Singapore and Malaysian research corridors are accelerating solid-state investments, but commercial-scale equipment specifications remain undefined, freezing mid-tier vendor R&D commitments.
Strategic Opportunities
- Vietnam's Emerging Formation Equipment Demand:LG Energy Solution supplier networks are establishing localized service hubs around VinFast's Haiphong operations, creating first-mover advantage for aging system specialists.
- Singapore's Clean Technology Manufacturing Grants:Enterprise Singapore funding is lowering capital barriers for solid-state electrolyte deposition equipment trials in research corridors.
- Malaysia's MIDA Equipment Financing:Soft loans for precision coating line installation are attracting Korean equipment makers to Penang and Kulim industrial zones.
Industry Challenges
- Electrochemical Process Engineering Talent Scarcity:Formation and aging protocol optimization requires specialized expertise that local universities have not yet scaled to match gigafactory construction timelines.
- Inline Defection Detection Certification Delays:100% optical inspection systems for electrode coating must pass automotive OEM validation cycles that extend 18-24 months, delaying revenue recognition for equipment vendors.
- Legacy Lead-Acid Equipment Repurposing Friction:Southeast Asian battery machinery incumbents face technical debt from acid-based production lines ill-suited to lithium-ion dry room and slurry handling requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ASEAN Countries Electric Vehicle Battery Manufacturing Equipment Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Assembly Machines, Testing Equipment, Coating Systems, Extruders Technology: Lithium-Ion, Solid-State, Nickel-Cobalt-Manganese, Lead-Acid End User: OEMs, Tier Suppliers, Aftermarket Providers, Research Institutions Application: Passenger Vehicles, Commercial Vehicles, Buses, Two-Wheelers |
| Companies Covered | ABB Ltd., Sovema Group, WONIK PNE CO., LTD., Yokogawa India Ltd., Daiichi Jitsugyo Thailand Co Ltd, Schuler AG, Mitsubishi Heavy Industries, Ltd., HLI Green Power, Hitachi Ltd, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ASEAN Countries Electric Vehicle Battery Manufacturing Equipment Market Trends and Innovations
Equipment specifications across ASEAN cell plants are converging on higher energy density cathode formats and fully automated inline quality verification, compressing vendor qualification windows and favoring integrators with regional service infrastructure.
Dry electrode coating technology is absorbing capital allocation from traditional solvent-based slurry systems in Thai and Indonesian pilot lines. CATL-affiliated plants in the Eastern Economic Corridor are piloting binder-free electrode deposition to eliminate toxic NMP solvent recovery infrastructure. This process simplification is absorbing maintenance overhead and reducing facility footprint requirements for new market entrants.
Malaysia's MIDA and Singapore's Enterprise Singapore have synchronized grant disbursement timelines with equipment installation milestones, accelerating clean technology manufacturing adoption. This policy coordination is compressing vendor selection cycles and forcing equipment suppliers to pre-qualify financing structures before technical bids. Korean and Japanese formation system specialists are responding by establishing localized leasing subsidiaries in Penang and Jurong.
Automotive OEMs are consolidating equipment procurement authority at regional headquarters in Bangkok and Singapore, displacing distributed plant-level purchasing. Tier-1 cell makers must now present unified technical specifications across Thai, Indonesian, and Vietnamese operations to secure volume pricing. This centralization is visible in CATL and LG Energy Solution supplier programs, where equipment vendors face single-point qualification for multi-country deployment.
ASEAN Countries Electric Vehicle Battery Manufacturing Equipment Market Segmentation
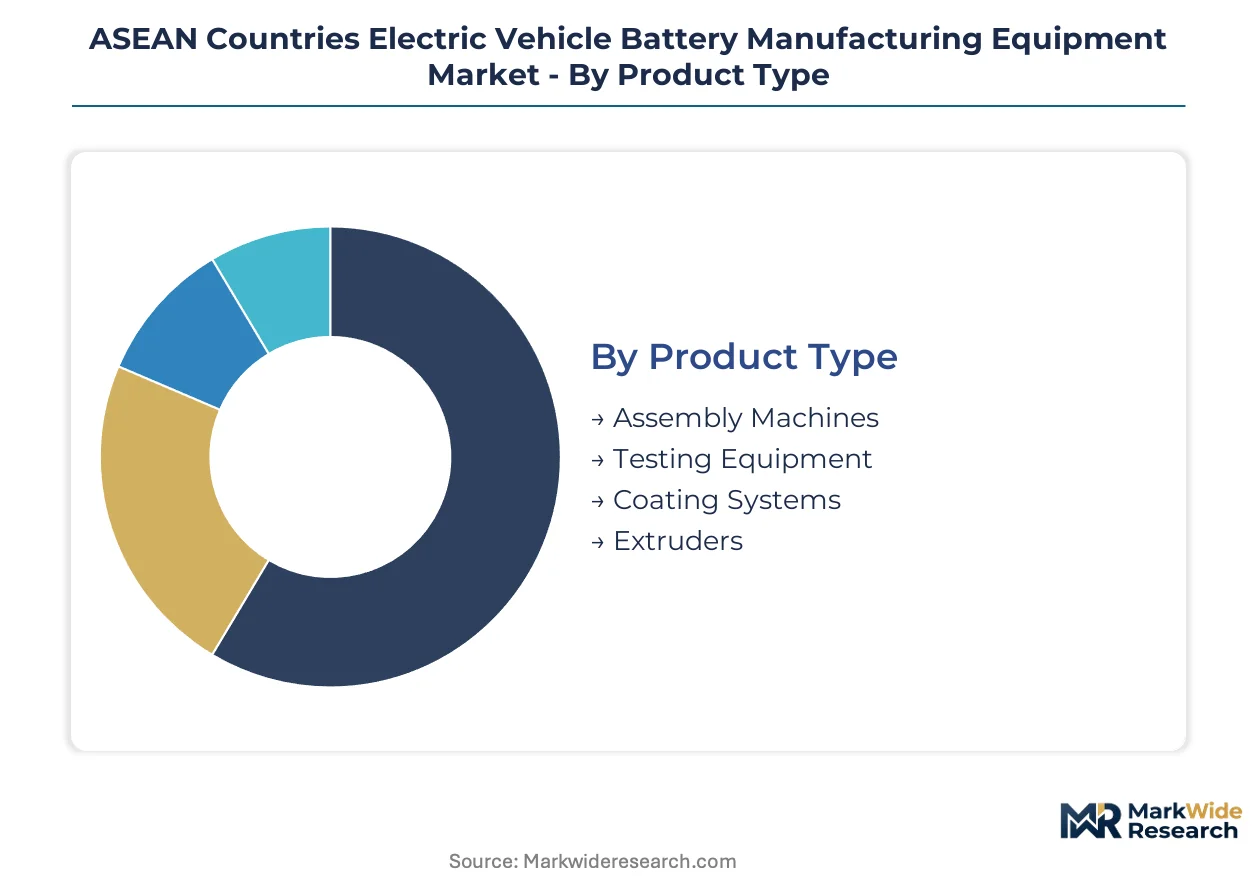
Equipment procurement patterns across Thailand, Indonesia, and Vietnam diverge sharply by product sophistication and technology maturity. Understanding these splits reveals where capital allocation concentrates and which vendor capabilities command premium positioning.
Product Type:
Supply concentration for high-precision subsystems determines competitive positioning among equipment integrators.
- Assembly Machines:Robotic stacking and tab welding systems operate at sub-10-micron tolerances for prismatic cell formats. Demand clusters in Thailand's Eastern Economic Corridor where CATL-affiliated plants are qualifying domestic vendors for pouch and prismatic line integration.
- Testing Equipment:Electrochemical formation and aging systems require 100% inline defect detection protocols with 18-24 month automotive OEM validation cycles. Indonesian nickel downstreaming mandates are channeling smelter profits into localized formation line procurement.
- Coating Systems:Electrode slurry deposition and calendaring equipment dominates capex allocation for cathode production.
- Extruders:Separator film and electrolyte handling machinery serves dry room environments below 100 ppm moisture.
Coating Systems absorbs the bulk of installed capacity; Testing Equipment is expanding most quickly.
Technology:
Cost tier separation between mature and emerging chemistries dictates facility retrofit requirements and vendor qualification timelines.
- Lithium-Ion:NCM and LFP electrode manufacturing equipment occupies dominant revenue share with established supply chains for solvent-based slurry systems. Thai and Indonesian gigafactories are scaling wet coating lines while piloting dry electrode alternatives to eliminate NMP recovery infrastructure.
- Solid-State:Electrolyte deposition and sulfide handling equipment remains in pilot phase with undefined commercial specifications. Singapore's Enterprise Singapore grants are funding research corridor trials, though mid-tier vendors have frozen R&D commitments pending scale-up clarity.
- Nickel-Cobalt-Manganese:High-nickel cathode compaction presses require adapted mechanical specifications for Asian material standards.
- Lead-Acid:Legacy equipment faces repurposing friction as Southeast Asian incumbents confront technical debt from acid-based production lines ill-suited to lithium-ion dry room requirements.
Lithium-Ion commands the majority of operational footprint; Solid-State is climbing the fastest despite specification uncertainty.
End User:
Customer type determines procurement authority centralization and service infrastructure placement requirements.
- OEMs:Automotive manufacturers are consolidating equipment procurement authority at regional headquarters in Bangkok and Singapore, displacing distributed plant-level purchasing. Tier-1 cell makers must present unified technical specifications across Thai, Indonesian, and Vietnamese operations.
- Tier Suppliers:Battery cell specialists like CATL and LG Energy Solution affiliates drive qualification programs for multi-country equipment deployment with single-point vendor approval.
- Aftermarket Providers:Service and refurbishment equipment demand concentrates around established manufacturing clusters.
- Research Institutions:Pilot line equipment procurement in Singapore and Malaysian corridors focuses on solid-state electrolyte deposition trials.
OEMs absorb the bulk of installed capacity; Tier Suppliers are gaining share fastest through supplier network localization.
Application:
Volume scale and margin structure vary significantly across vehicle categories, shaping equipment specification priorities.
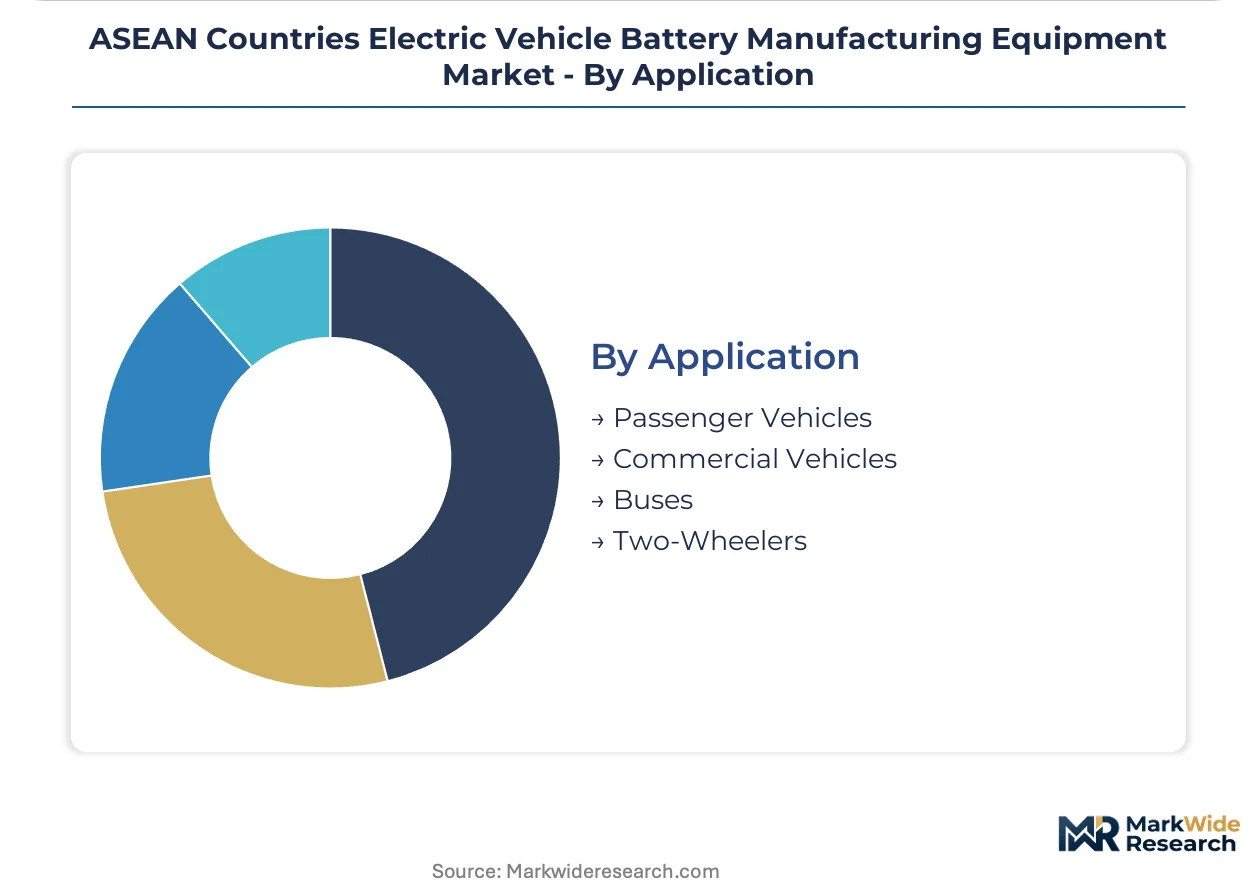
- Passenger Vehicles:High-energy density pouch and prismatic cell lines require precision coating and formation systems. Thailand's Board of Investment incentive schemes are accelerating domestic vendor qualification for electrode coating capacity serving regional EV platforms.
- Commercial Vehicles:Heavy-duty battery pack assembly demands robust module welding and thermal management integration. Indonesian mineral downstreaming policies are redirecting nickel processing profits into commercial vehicle battery plant machinery.
- Buses:Large-format cell stacking equipment serves public transit electrification programs.
- Two-Wheelers:Compact cylindrical cell production lines target Southeast Asia's dominant motorcycle markets with lower precision tolerance requirements.
Passenger Vehicles represents the dominant application; Commercial Vehicles is expanding most quickly on logistics fleet electrification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia's nickel belt anchors regional equipment demand as downstreaming mandates redirect smelter profits toward battery plant machinery. Thailand's Eastern Economic Corridor and Vietnam's northern industrial zones absorb the bulk of formation and coating system procurement.
Thailand
CATL-affiliated cell plants drive electrode coating line qualification in the Eastern Economic Corridor. Thailand's Board of Investment coordinates tax holidays and import duty exemptions with the national automotive regulator's local content thresholds. Rayong and Chonburi provinces host domestic vendor certification programs for precision calendaring equipment serving regional EV platforms.
Indonesia
Nickel downstreaming mandates channel smelter profits into battery plant machinery procurement across Sulawesi and Halmahera. The investment ministry enforces mineral processing localization requirements that redirect capital from raw export to electrode formation equipment. Morowali Industrial Park anchors cathode compaction press installations adapted to Asian material specifications.
Vietnam
LG Energy Solution supplier networks establish localized service hubs around VinFast's Haiphong operations. The country's industrial zones attract aging system specialists seeking first-mover positioning in formation equipment demand. Bac Ninh and Hai Duong provinces concentrate module welding and thermal management integration capacity for commercial vehicle battery packs.
Singapore
Enterprise Singapore administers clean technology manufacturing grants that lower capital barriers for solid-state electrolyte deposition equipment trials. Research corridors in Jurong and one-north host pilot line investments with undefined commercial specifications freezing mid-tier vendor R&D commitments. The city-state's funding synchronization compresses vendor selection cycles for equipment installation milestones.
Malaysia
MIDA soft loans for precision coating line installation attract Korean equipment makers to Penang and Kulim industrial zones. The country's grant disbursement timelines align with equipment installation milestones, forcing suppliers to pre-qualify financing structures before technical bids. Kulim Hi-Tech Park anchors cathode production capacity with moisture-controlled environments below 100 ppm.
ASEAN Countries Electric Vehicle Battery Manufacturing Equipment Market Competitive Landscape
Global majors compete with regional champions across automation integration and precision subsystem supply. The vendor base stratifies between robotics integrators with regional service infrastructure and specialized formation system providers with localized maintenance networks. Two archetypes dominate: European-Japanese precision equipment specialists and Korean-Chinese automation integrators. Competitive moves center on supplier network localization and dry room environment certification partnerships.
Within the precision automation tier, ABB Ltd. and Schuler AG exemplify European-Japanese heritage in assembly line robotics and mechanical press systems. WONIK PNE CO., LTD. anchors the formation equipment archetype with Korean manufacturing lineage. These three occupy positions spanning robotic integration, cathode compaction, and electrochemical aging systems respectively. Mitsubishi Heavy Industries, Ltd. and Hitachi Ltd represent diversified industrial conglomerates with equipment manufacturing divisions. Sovema Group and HLI Green Power sit within specialist battery machinery segments. Yokogawa India Ltd. and Daiichi Jitsugyo Thailand Co Ltd illustrate regional distribution and integration channels for precision subsystems.
| Leading Market Players |
|---|
| ABB Ltd. |
| Sovema Group |
| WONIK PNE CO., LTD. |
| Yokogawa India Ltd. |
| Daiichi Jitsugyo Thailand Co Ltd |
| Schuler AG |
| Mitsubishi Heavy Industries, Ltd. |
| HLI Green Power |
| Hitachi Ltd |
| Others |
Pricing and Supply Chain Analysis
LME nickel price volatility cascades through ASEAN battery equipment markets, compressing margins for electrode coating system integrators while amplifying pricing power for formation equipment vendors with captive service networks in Thailand and Indonesia.
Pricing Analysis
Service bundling distinguishes vendor tiers: premium integrators wrap multi-year maintenance contracts and dry room certification into project pricing, while economy suppliers unbundle these for transactional hardware-only deals. Three-tier pricing structure across premium, standard, and economy levels reflects automation sophistication and regional service density. Price differentiation hinges on precision tolerance guarantees and localized spare parts availability. Cost compression in standard-tier assembly equipment is intensifying because Korean and Chinese vendors are qualifying Thai distributors for direct sales. Tier suppliers with multi-country deployment contracts exhibit lowest price sensitivity; standalone research institutions show highest.
Supply Chain Analysis
Workforce scarcity in precision electrochemical engineering across Rayong, Chonburi, and Bac Ninh provinces is forcing equipment vendors to pre-train local technicians before installation handover. Component supply concentrates in Germany and Japan for laser cutting heads and motion controllers, with South Korea and China feeding automation subsystems. Raw material dependencies span high-grade aluminum for dry room construction, rare-earth magnets for servo motors, and fluoropolymer coatings for corrosion resistance. Single-source vulnerability in precision optical inspection modules exposes integrators to 18-24 month lead time volatility. Distribution runs through Bangkok and Singapore regional headquarters with centralized procurement authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ASEAN battery equipment markets are consolidating around vendors with integrated service infrastructure, as automotive OEM validation cycles and dry room certification requirements squeeze out pure-play hardware suppliers lacking regional maintenance networks.
For Market Incumbents: Acquire localized service technician training assets in Thailand's Eastern Economic Corridor and Vietnam's northern industrial zones. CATL and LG Energy Solution supplier program consolidation threatens mid-tier integrators lacking multi-country deployment credentials. Defensive positioning requires backward integration into precision subsystem refurbishment capabilities and captive spare parts warehousing in Penang and Jurong. For New Entrants and Emerging Players: Thailand's Board of Investment tax holidays and import duty exemptions for machinery procurement open a window for Korean and Japanese formation system specialists to establish localized leasing subsidiaries. White-space targets include solid-state pilot line equipment trials in Singapore research corridors and aftermarket refurbishment services for legacy lead-acid machinery conversions. Go-to-market positioning should emphasize dry room environment certification partnerships with established HVAC integrators. For Investors and Strategic Acquirers: Distressed-cycle entries favor precision automation vendors with existing automotive OEM qualification credentials and underutilized regional service infrastructure in Malaysia and Indonesia. Long-term viability centers on vendors capable of spanning both lithium-ion gigafactory scale-up and solid-state pilot line transitions. Watch for inflection signals in Indonesian nickel downstreaming enforcement intensity and Thai local content threshold adjustments.| Strategic Initiative | Industry Significance |
|---|---|
| Regional Service Hub Establishment | Localized maintenance networks in Thailand and Vietnam compress response times for formation system downtime. |
| Dry Room Certification Partnership | HVAC integrator alliances in Malaysia and Singapore accelerate facility commissioning for cathode production lines. |
| Precision Subsystem Backward Integration | In-house production of laser cutting heads reduces exposure to German and Japanese supplier lead time volatility. |
| Multi-Country Supplier Program Qualification | Single-point vendor approval across CATL and LG Energy Solution networks unlocks volume pricing leverage. |
| Solid-State Pilot Line Equipment Trials | Enterprise Singapore grant alignment positions vendors for undefined commercial specification scale-up. |
Research Methodology
Independent corroboration across equipment vendor technical documentation, national investment board procurement records, and automotive OEM supplier qualification protocols underwrites the qualitative findings. Primary interviews with plant engineering directors at Thai and Indonesian gigafactories, procurement leads at CATL-affiliated operations, dry room HVAC specialists, and formation system maintenance heads combined with secondary validation from customs trade data, Board of Investment incentive disclosures, and SEC filings from listed equipment manufacturers. Bottom-up installed capacity estimates and top-down capital expenditure projections were triangulated for segment-level sizing.
Comparable historical reference periods anchored the projection framework, with growth trajectories calibrated to prior technology manufacturing equipment adoption curves across the analysis window. Segmentation modeling spanned product type, technology maturity, end-user procurement authority, and application-specific precision requirements. CAGRs were derived from equipment shipment value aggregation and facility capex pipeline tracking. Forecast inputs incorporated nickel price volatility transmission effects and local content threshold enforcement timelines.
The model assumes a particular technology adoption path; alternative pathways for solid-state commercialization would alter the outlook. Forecasts reflect assumptions about Indonesian downstreaming policy continuity and Thai BOI incentive renewal. Material deviation in automotive OEM validation cycle duration or precision component import restriction severity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Infrastructure
France Electric Vehicle Battery Separator Market
Battery Infrastructure
Solar Containers Market
Battery Infrastructure
Carbon Battery Bank Market
Battery Infrastructure
Europe Electric Vehicle Battery Separator Market
Battery Infrastructure
ASEAN Countries Electric Vehicle Battery Separator Market
Battery Infrastructure
Europe Lithium Foil Market
Battery Infrastructure
Germany Electric Vehicle Battery Separator Market
Battery Infrastructure
India Electric Vehicle Battery Separator Market
Battery Infrastructure
Global Automotive 48 Volt Battery System Market
Battery Infrastructure
Global Battery Technology Market
Battery Infrastructure
North America Electric Vehicle Battery Manufacturing Equipment Market
Battery Infrastructure
France Electric Vehicle Battery Manufacturing Equipment Market
Battery Infrastructure
Middle East and Africa Electric Vehicle Battery Separator Market
Battery Infrastructure
China Electric Vehicle Battery Separator Market
Battery Infrastructure
New Energy Battery Structural Parts Market
Battery Infrastructure
Battery Maintenance Service Market