
 India Electric Vehicle Battery Separator Market | 2026-2036
India Electric Vehicle Battery Separator Market Size, Share, and Industry Trends Forecast 2026-2036
India Electric Vehicle Battery Separator Market Insights
Multi-source procurement of wet-process polyolefin membranes is consolidating as domestic cell manufacturers scale beyond pilot volumes. Toray Industries anchors Japanese supply relationships through its high-tensile polyethylene film technology. SK Innovation competes on ceramic coating integration for prismatic cell formats. Asahi Kasei specializes in trilayer shutdown separators that sustain thermal runaway protection under Indian ambient conditions.
An electric vehicle battery separator is a microporous membrane, typically 12–30 micrometers thick, positioned between anode and cathode to enable ion transport while preventing electrical shorting; its porosity, typically 40–60%, directly governs cell discharge rates and cycle life in lithium-ion configurations. Ceramic coated polyethylene separators lead the product type landscape due to their superior wettability with carbonate electrolytes and dimensional stability above 130°C. Solid-state technology represents the fastest-growing technology segment as Indian research institutions prototype sulfide and oxide ceramic electrolytes that eliminate conventional separator dependence. Battery Manufacturers occupy the most concentrated end user channel, locking in multi-year supply contracts that control pricing and specification roadmaps.
BIS certification requirements for cell component imports, coupled with PLI scheme domestic value-add mandates from the Ministry of Heavy Industries, are redirecting separator qualification programs toward local coating and slitting operations. CDSCO oversight of battery materials for electric bus deployments adds a secondary compliance layer for public transport tenders. Stakeholders must monitor BIS standard evolution for solid-state interfaces and decide between licensing foreign coating technology or funding indigenous microporous stretching capabilities before contract structures freeze for the next platform cycle.
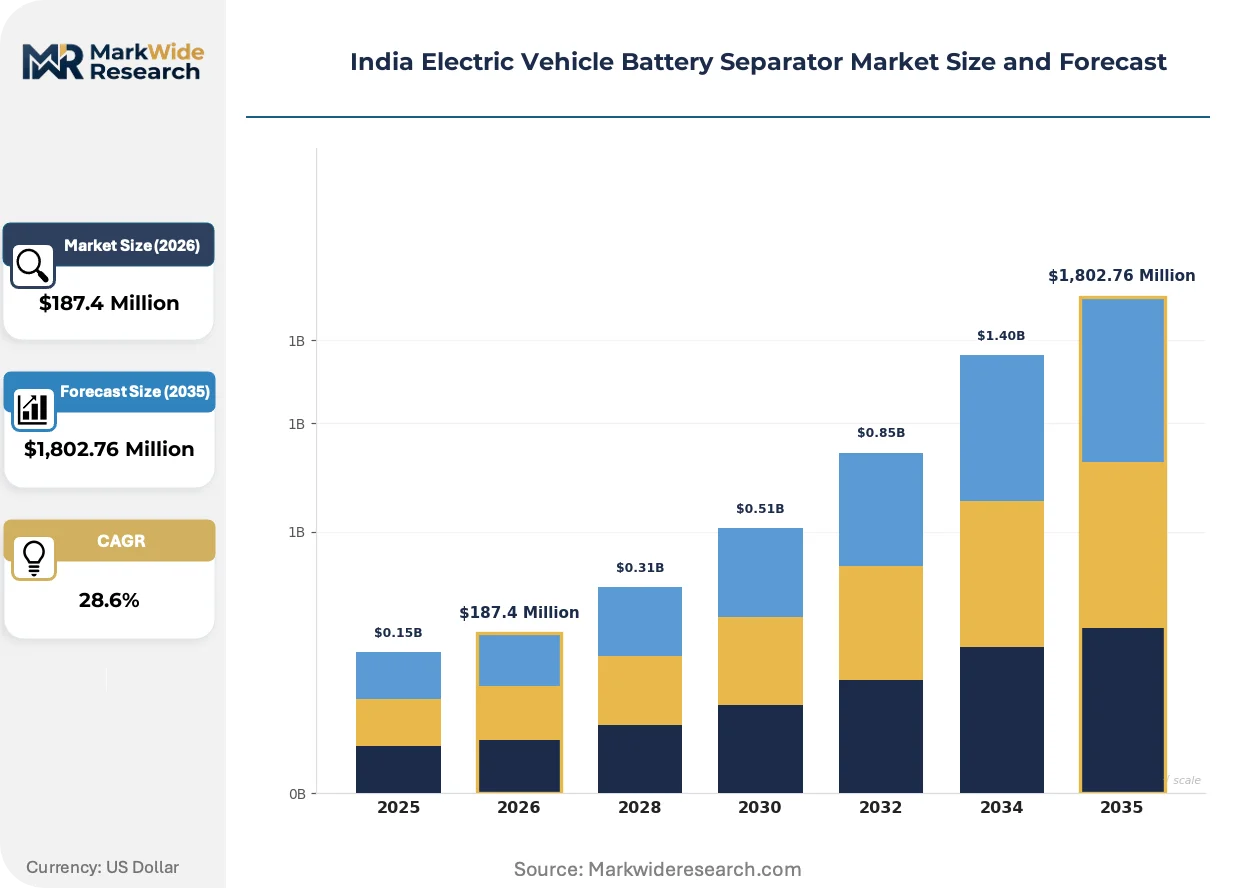
Market Dynamics
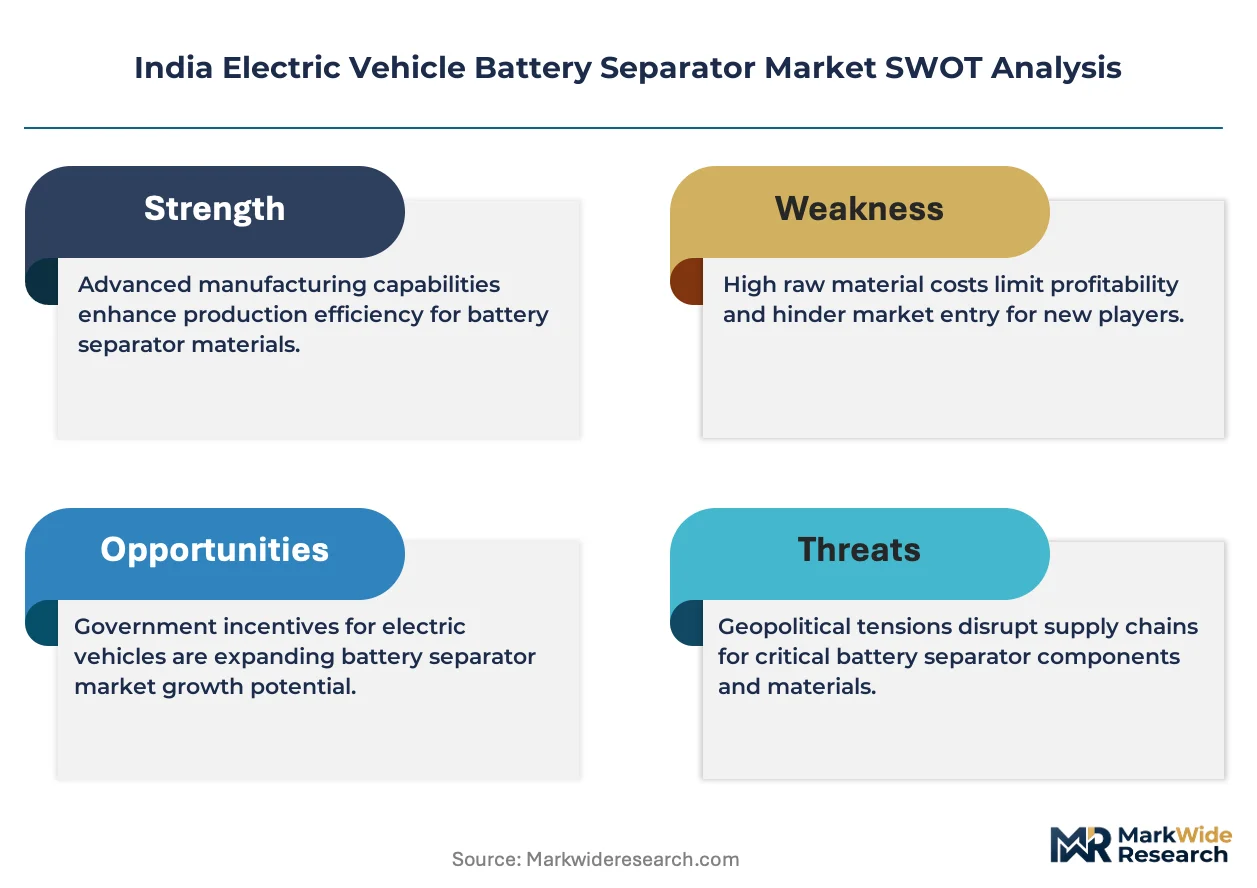
Domestic cell manufacturers are scaling wet-process polyolefin membrane volumes beyond pilot thresholds, forcing separator procurement into multi-year contract structures that lock specification roadmaps before local coating capabilities mature.
Growth Catalysts
- PLI scheme domestic value-add mandates:Ministry of Heavy Industries requirements redirect qualification programs toward indigenous slitting and ceramic coating operations.
- Passenger vehicle electrification:Tamil Nadu and Gujarat manufacturing corridors are accelerating separator procurement volumes as OEMs localize cell production.
- Ceramic coated polyethylene:Superior wettability with carbonate electrolytes and dimensional stability above 130°C is displacing uncoated alternatives in prismatic cell formats.
Market Restraints
- High-purity resin import dependence:Polyethylene feedstock concentrates around Asian petrochemical suppliers, exposing margins to freight and currency volatility.
- BIS certification timelines:Cell component import requirements create 12-18 month qualification windows that delay platform launches.
- Solid-state substitution threat:Sulfide and oxide ceramic electrolyte prototypes at Indian research institutions could eliminate conventional separator demand by the late 2030s.
Strategic Opportunities
- Pune-Aurangabad OEM belt:Supply agreement concentration around domestic electric bus and passenger vehicle programs offers captive offtake channels.
- CDSCO electric bus compliance layer:Public transport tender requirements create differentiated qualification pathways for separator suppliers with battery material safety documentation.
- Solid-state interface standards:Early participation in BIS evolution for ceramic electrolyte bonding protocols positions suppliers for next-platform contracts.
Industry Challenges
- Microporous stretching equipment scarcity:Indigenous biaxial stretching capability gaps force reliance on licensed Japanese or Korean process technology.
- Electrolyte compatibility testing bandwidth:Cell manufacturer qualification queues stretch 8-14 months as domestic production scales.
- Coating formulation IP fragmentation:Ceramic binder patents held by separate Japanese and Korean licensors complicate royalty stacking for local producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Electric Vehicle Battery Separator Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $1,802.76 Million |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ceramic Coated, Polyethylene, Polypropylene, Glass Fiber End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Battery Manufacturers Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Buses Technology: Li-ion, Solid-State, Lead-Acid, Nickel-Metal Hydride |
| Companies Covered | Toray Industries, Inc., Entek International LLC, Sumitomo Chemical Co., Ltd., UBE Industries, Ltd., Freudenberg SE, Mitsubishi Chemical Group Corporation, SK Innovation Co., Ltd., Celgard LLC, Asahi Kasei Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Electric Vehicle Battery Separator Market Trends and Innovations
Separator technology is bifurcating between incremental improvements in polyolefin substrates and disruptive ceramic electrolyte architectures that could obsolete conventional membranes entirely.
Ceramic coating integration is modularizing around prismatic cell formats as domestic manufacturers seek thermal runaway protection without redesigning electrode stacks. Battery Manufacturers in the Pune-Aurangabad belt are adopting trilayer shutdown configurations at 18-24 month refresh cycles. This architecture is modularizing supply relationships by decoupling substrate sourcing from coating qualification.
BIS standard evolution for solid-state interfaces is compressing development timelines as the Bureau of Indian Standards accelerates draft releases ahead of commercial cell launches. Domestic coating operations must now pre-qualify ceramic binder formulations against unreleased specifications. The Tamil Nadu manufacturing corridor faces the steepest compliance ramp as its cell producers target 2027-2028 platform deadlines.
Long-term supply contracts are displacing spot procurement as Battery Manufacturers seek volume guarantees through the PLI scheme window. Tier-1 cell producers now require 5-7 year offtake commitments with fixed pricing ladders. This concentration is most visible in Gujarat, where OEM supply agreements bundle separator procurement with electrode and electrolyte sourcing.
India Electric Vehicle Battery Separator Market Segmentation
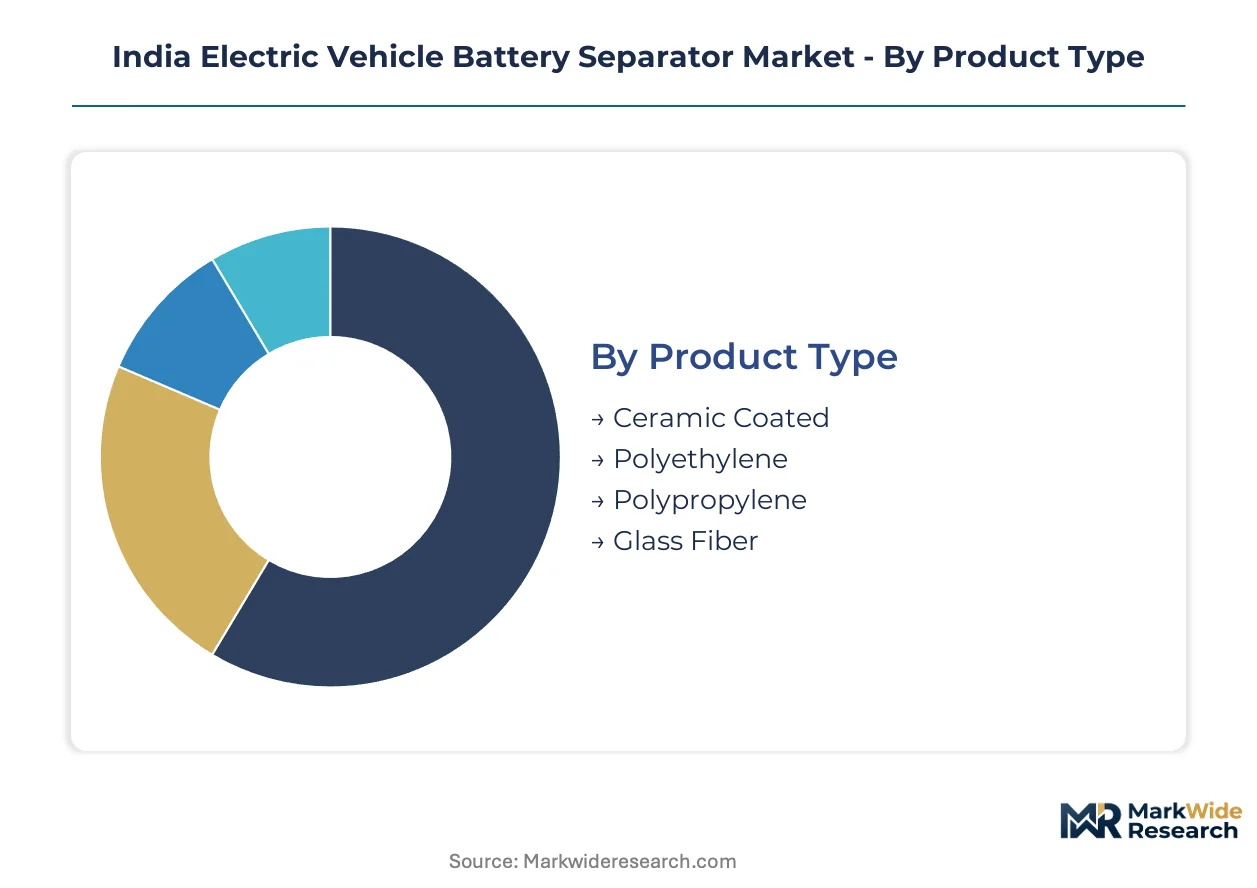
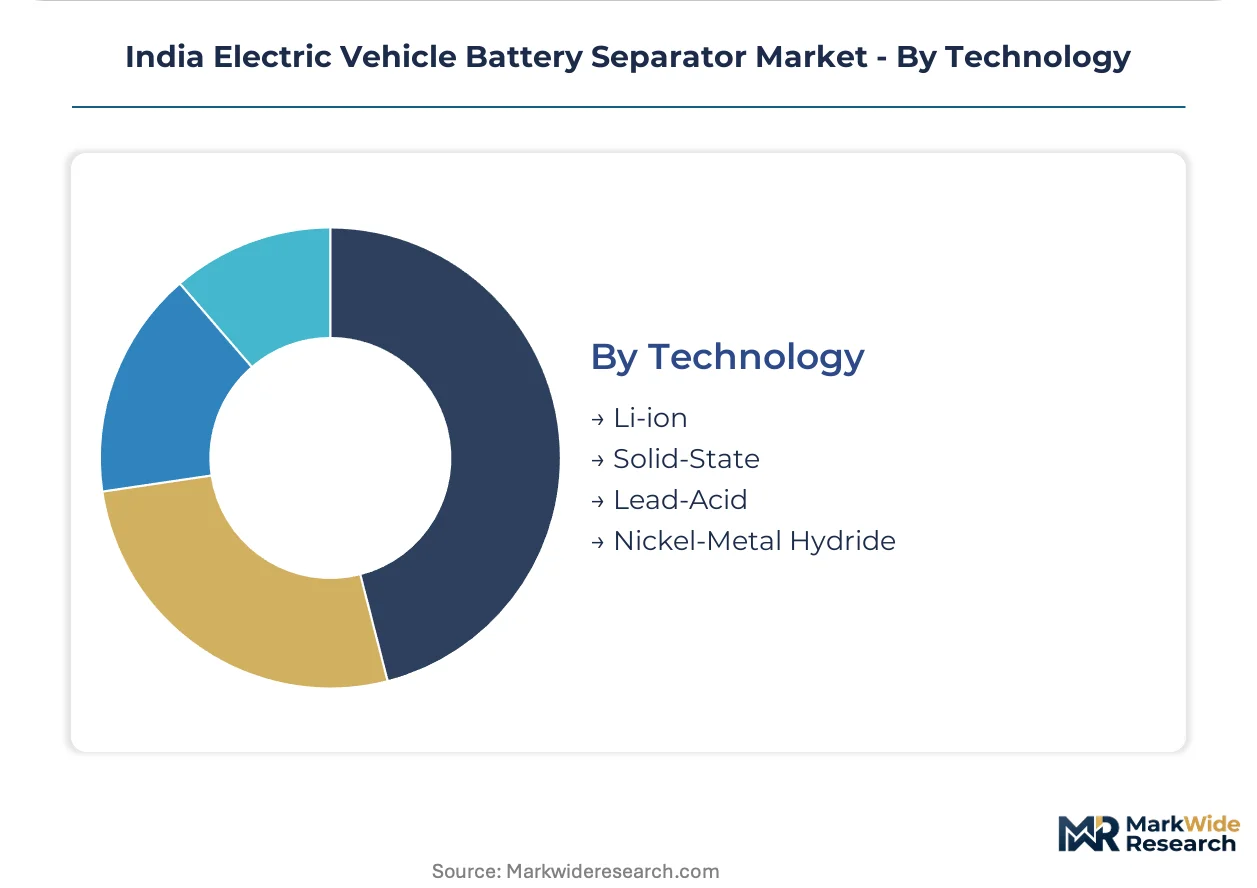
Separator procurement patterns in India fragment across cell chemistry roadmaps, vehicle platform specifications, and PLI scheme compliance tiers. Each segmentation dimension carries distinct qualification requirements and margin structures that reshape supplier positioning across Tamil Nadu and Gujarat manufacturing corridors.
Product Type:
Supply concentration for microporous substrates tilts toward ceramic coating capabilities as domestic cell manufacturers scale beyond pilot volumes.
- Ceramic Coated:Polyethylene substrates receive alumina or boehmite ceramic layers that sustain dimensional stability above 130°C under Indian ambient thermal stress. Pune-Aurangabad OEM supply agreements concentrate procurement for prismatic cell formats requiring thermal runaway protection.
- Polyethylene:Wet-process biaxially stretched membranes dominate current procurement volumes with 12-30 micrometer thickness ranges and 40-60% porosity specifications. Tamil Nadu manufacturing corridors anchor import substitution programs for high-tensile film grades.
- Polypropylene:Dry-process membranes offer cost advantages for cylindrical cell configurations with lower thermal tolerance requirements. Gujarat cell producers qualify uncoated alternatives for entry-tier passenger vehicle platforms.
- Glass Fiber:High-temperature stability substrates serve niche applications in electric bus battery packs requiring extreme thermal endurance. CDSCO compliance documentation creates differentiated qualification pathways for public transport tenders.
Today's leader: Ceramic Coated. Tomorrow's challenger: Polyethylene as indigenous stretching capabilities mature.
End User:
Procurement authority concentrates with entities controlling multi-year offtake contract structures and PLI scheme qualification timelines.
- Battery Manufacturers:Tier-1 cell producers lock 5-7 year supply agreements with fixed pricing ladders through the PLI scheme window. These entities govern specification roadmaps and ceramic coating qualification protocols across Pune-Aurangabad and Gujarat corridors.
- OEMs:Passenger vehicle assemblers increasingly bundle separator procurement with electrode and electrolyte sourcing under integrated platform contracts. Tamil Nadu manufacturing clusters see direct OEM engagement as cell localization accelerates.
- Vehicle Assemblers:Commercial vehicle and two-wheeler producers rely on tier-2 cell supplier relationships with shorter contract cycles and spot procurement flexibility.
- Aftermarket Providers:Replacement cell producers source through distributor channels with limited specification control and price-sensitive procurement patterns.
Contract authority flows toward Battery Manufacturers. Volume growth shifts toward OEMs as backward integration into cell production spreads.
Application:
Platform thermal requirements and BIS certification timelines segment demand across vehicle categories with divergent safety margins.
- Passenger Vehicles:Prismatic cell formats with ceramic coated separators dominate as OEMs localize production for compact SUV and sedan platforms. Gujarat and Tamil Nadu manufacturing corridors anchor procurement concentration for this segment.
- Buses:Electric public transport deployments trigger CDSCO oversight requirements that create compliance-heavy qualification pathways. Pune-Aurangabad belt suppliers with battery material safety documentation capture differentiated tender access.
- Commercial Vehicles:Light and medium-duty truck applications favor cost-optimized polyethylene configurations with moderate thermal tolerance specifications.
- Two-Wheelers:High-volume, low-margin procurement for scooter and motorcycle batteries prioritizes polypropylene substrates with rapid qualification cycles.
Revenue concentration sits with Passenger Vehicles. Regulatory differentiation favors Buses for margin expansion.
Technology:
Cell chemistry roadmaps determine separator dependence intensity and long-term substitution risk across the forecast window.
- Li-ion:Lithium-ion configurations with carbonate electrolytes sustain ceramic coated polyethylene demand through prismatic and cylindrical formats. Current procurement volumes concentrate with NMC and LFP cell chemistries qualifying under BIS standards.
- Solid-State:Sulfide and oxide ceramic electrolyte prototypes at Indian research institutions threaten conventional separator obsolescence by eliminating microporous membrane requirements. Early BIS standard evolution for solid-state interfaces compresses supplier development timelines.
- Lead-Acid:Mature technology with minimal separator innovation serves aftermarket replacement cycles and entry-tier two-wheeler applications.
- Nickel-Metal Hydride:Declining chemistry presence in hybrid vehicle programs retains limited procurement for legacy platform support.
Li-ion commands current procurement. Solid-State represents the steepest expansion trajectory as indigenous electrolyte research advances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Tamil Nadu manufacturing corridor anchors separator procurement concentration as domestic cell producers scale wet-process polyolefin volumes beyond pilot thresholds. Gujarat and Maharashtra manufacturing belts follow with accelerating OEM supply agreement activity.
Tamil Nadu
Cell localization programs for compact SUV and sedan platforms drive separator demand from Chennai and Sriperumbudur industrial zones. BIS certification timelines for cell component imports compress qualification windows to 12-18 months. The Sriperumbudur-Oragadam belt hosts OEM supply agreements bundling separator procurement with electrode sourcing.
Gujarat
Passenger vehicle electrification and prismatic cell format adoption concentrate procurement around Sanand and Halol manufacturing nodes. PLI scheme domestic value-add mandates redirect qualification programs toward indigenous slitting operations. The Sanand-Vithalapur corridor anchors multi-year offtake contracts with fixed pricing ladders through 2030.
Maharashtra
The Pune-Aurangabad belt concentrates ceramic coated separator demand for electric bus and passenger vehicle programs requiring CDSCO compliance documentation. Public transport tenders create differentiated qualification pathways for suppliers with battery material safety documentation. Chakan and Talegaon industrial areas host tier-1 cell producer coating qualification protocols.
Karnataka
Two-wheeler battery pack localization drives polypropylene substrate demand with rapid qualification cycles for scooter and motorcycle applications. The state's electric mobility policies accelerate separator procurement from Bengaluru and Hosur manufacturing clusters. Electronics City and Jigani industrial zones concentrate distributor channel relationships for aftermarket cell producers.
Haryana
Commercial vehicle electrification programs for light and medium-duty trucks favor cost-optimized polyethylene configurations. The Manesar-Bawal industrial corridor hosts entry-tier passenger vehicle platform cell sourcing with moderate thermal tolerance specifications. PLI scheme incentives attract coating operation investments for prismatic cell supply to northern OEM assembly plants.
India Electric Vehicle Battery Separator Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue ceramic coating specialization and indigenous substrate stretching capabilities. The supplier base concentrates around Japanese and Korean technology licensors with domestic coating operations forming a secondary tier. Three archetypes dominate: resin-to-film integrated producers, licensed coating specialists, and research-backed solid-state electrolyte developers. Capacity expansion and strategic technology licensing represent the dominant competitive moves as qualification timelines compress.
Among Japanese fabricators, Toray Industries, Inc. and Asahi Kasei Corporation anchor the premium substrate tier with established polyethylene film supply relationships. Sumitomo Chemical Co., Ltd. occupies a position exemplifying the licensed technology archetype for domestic coating operations. SK Innovation Co., Ltd. represents Korean competitive positioning on ceramic coating integration for prismatic cell formats.
| Leading Market Players |
|---|
| Toray Industries, Inc. |
| Entek International LLC |
| Sumitomo Chemical Co., Ltd. |
| UBE Industries, Ltd. |
| Freudenberg SE |
| Mitsubishi Chemical Group Corporation |
| SK Innovation Co., Ltd. |
| Celgard LLC |
| Asahi Kasei Corporation |
| Others |
Pricing and Supply Chain Analysis
Multi-year offtake commitments from Battery Manufacturers under the PLI scheme are compressing pricing flexibility and forcing supply chains to absorb resin cost volatility through fixed-price ladder structures.
Pricing Analysis
Input-cost pass-through from high-purity polyethylene resin imports anchors contract pricing structures. Three-tier pricing stratifies across ceramic-coated premium grades, standard wet-process polyethylene, and dry-process polypropylene economy tiers. Pricing pressure stems from BIS certification delays that extend qualification timelines and strain working capital. Battery Manufacturers exhibit lowest price sensitivity due to PLI scheme margin protection, while aftermarket providers face acute cost compression.
Supply Chain Analysis
Regional distribution centers in Chennai, Sanand, and Pune operate hub-and-spoke patterns feeding Tamil Nadu and Gujarat manufacturing corridors. Supply concentrates in Japan, South Korea, and China for biaxial stretching equipment and ceramic binder formulations. Raw material dependencies include ultra-high molecular weight polyethylene resin, alumina nanopowders, and proprietary coating solvents. Single-source vulnerability in licensed Japanese process technology creates qualification bottlenecks. Distribution runs through tier-1 cell producer warehouses with direct-to-plant delivery schedules.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India Electric Vehicle Battery Separator Market functions as a regulatory compounder where BIS certification timelines and PLI scheme domestic value-add mandates continuously reshape procurement authority and supplier viability.
For Market Incumbents: Cement supply relationships through 5-7 year offtake contracts before indigenous stretching capabilities mature. Lock in ceramic coating IP licensing with Japanese and Korean patent holders to preempt royalty stacking. Expand slitting and coating capacity in Gujarat and Tamil Nadu corridors to capture PLI scheme localization premiums. For New Entrants and Emerging Players: Tier-2 commercial vehicle battery suppliers represent an underserved buyer archetype with shorter qualification cycles and spot procurement flexibility. Target Haryana and Karnataka two-wheeler pack assemblers seeking polypropylene alternatives with rapid BIS pathways. Pursue CDSCO compliance documentation as a differentiated entry wedge for electric bus tenders in the Pune-Aurangabad belt. For Investors and Strategic Acquirers: Asymmetric upside sits with licensed coating specialists holding BIS pre-qualification status and established cell manufacturer relationships. Solid-state electrolyte research institutions threaten conventional separator demand by the late 2030s, compressing the viable holding period. Monitor BIS draft releases for solid-state interface standards as the inflection signal for next-platform contract positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Coating Capacity Expansion | Captures PLI scheme domestic value-add mandates in Gujarat and Tamil Nadu corridors. |
| Backward Integration into Resin Sourcing | Reduces exposure to Asian petrochemical supplier currency and freight volatility. |
| BIS Certification Pre-Qualification | Compresses 12-18 month import timelines for cell component qualification programs. |
| Long-Term Supply Agreement | Locks specification roadmaps and volume guarantees through Battery Manufacturer consolidation. |
| Solid-State Interface R&D Partnership | Positions for next-platform contracts as BIS accelerates ceramic electrolyte standards. |
Research Methodology
Coverage spans Tamil Nadu, Gujarat, Maharashtra, Karnataka, and Haryana, with primary inputs from each manufacturing corridor triangulated against secondary validation. Interviews with cell manufacturer procurement directors, OEM platform engineers, ceramic coating equipment suppliers, and BIS certification consultants informed demand-side assumptions. Secondary sources include Ministry of Heavy Industries PLI scheme disclosures, BIS standard draft releases, CDSCO electric bus tender documentation, and customs trade data for polyethylene resin imports. Bottom-up cell production forecasts and top-down vehicle electrification targets were reconciled through iterative triangulation.
Granularity-level modeling deployed cell chemistry roadmaps, vehicle platform specifications, and PLI scheme compliance tiers as core segmentation dimensions. CAGRs were derived from production volume build-ups across prismatic, cylindrical, and pouch cell formats, with electrolyte compatibility timelines and BIS certification velocity as industry-specific forecast inputs. Passenger vehicle localization rates and electric bus deployment schedules anchored the projection horizon.
Inputs from BIS and CDSCO regulatory filings were available through the study window; gaps in solid-state electrolyte commercialization timelines introduce uncertainty bands for technology substitution scenarios. Forecasts reflect documented assumptions around PLI scheme extension and resin import tariff stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Infrastructure
Carbon Battery Bank Market
Battery Infrastructure
Asia Pacific Electric Vehicle Battery Separator Market
Battery Infrastructure
Battery Enclosure Market
Battery Infrastructure
ASEAN Countries Electric Vehicle Battery Separator Market
Battery Infrastructure
Global Automotive 48 Volt Battery System Market
Battery Infrastructure
North America Electric Vehicle Battery Electrolyte Market
Battery Infrastructure
Canada Electric Vehicle Battery Separator Market
Battery Infrastructure
Global Battery Packaging Market
Battery Infrastructure
Battery Tray Market
Battery Infrastructure
North America Electric Vehicle Battery Manufacturing Equipment Market
Battery Infrastructure
Global Battery Technology Market
Battery Infrastructure
Germany Electric Vehicle Battery Manufacturing Equipment Market
Battery Infrastructure
France Electric Vehicle Battery Materials Market
Battery Infrastructure
France Electric Vehicle Battery Manufacturing Equipment Market
Battery Infrastructure
China Battery Manufacturing Equipment Market
Battery Infrastructure
Battery Production Machine Market