
 Canada Electric Vehicle Battery Separator Market | 2026-2036
Canada Electric Vehicle Battery Separator Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Electric Vehicle Battery Separator Market Insights
Project finance tied to clean-technology tax credits is reshaping competitive entry in the Canada electric vehicle battery separator space. Asahi Kasei Corporation leverages its polyolefin expertise to anchor supply relationships with North American cell manufacturers. SK Innovation Co., Ltd. sustains R&D intensity in ceramic-coated separators for high-nickel chemistries. ENTEK International LLC specializes in dry-process membrane production, occupying a defensible niche against wet-process competitors.
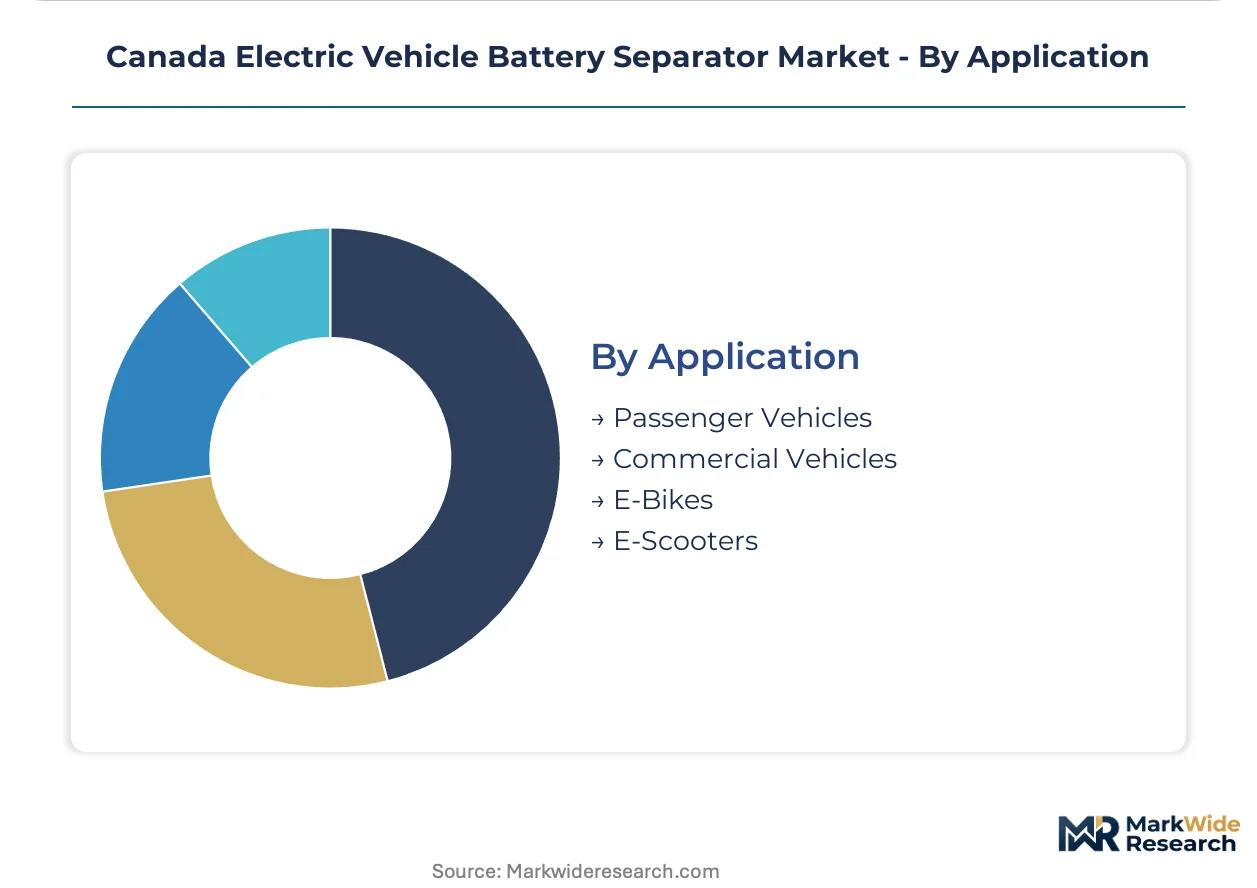
An electric vehicle battery separator is a microporous membrane, typically 25 to 40 microns thick, positioned between cathode and anode to prevent electrical shorting while permitting lithium-ion transport. Polyethylene separators dominate the product-type landscape due to their shutdown safety mechanism at elevated temperatures. Composite separators represent the fastest-growing category as Canadian OEMs demand thermal stability for next-generation battery packs. Passenger vehicles command the largest application share, though commercial vehicle procurement is expanding fastest among end-use segments.
Health Canada and Transport Canada jointly enforce battery safety standards that directly influence separator material selection and testing protocols. Environment and Climate Change Canada regulations on perfluorinated compounds are forcing membrane manufacturers to reformulate wet-process chemistries. Stakeholders must monitor how evolving federal zero-emission vehicle mandates reshape qualification timelines and domestic content requirements.
Market Dynamics
Transport Canada's zero-emission vehicle mandates are compressing qualification timelines for battery separator suppliers, forcing rapid domestic content alignment while Ontario's automotive corridor absorbs the bulk of procurement volume.
Growth Catalysts
- Clean-technology tax credits:Project finance tied to federal incentives is lowering capital barriers for separator manufacturing facilities in Ontario and Quebec.
- High-nickel cathode chemistries:Canadian OEMs are specifying ceramic-coated separators to manage thermal runaway risks in next-generation battery packs.
- Dry-process membrane adoption:Manufacturers are pivoting from wet-process chemistries to avoid Environment and Climate Change Canada restrictions on perfluorinated compounds.
Market Restraints
- Polyolefin feedstock volatility:Price swings in polyethylene resin directly compress separator margins and destabilize contract pricing.
- Asian supply concentration:Overreliance on East Asian coating equipment and ceramic powder suppliers exposes Canadian producers to shipping disruptions.
- Wet-process regulatory friction:Health Canada's evolving environmental guidelines are forcing costly reformulation of legacy solvent-based production lines.
Strategic Opportunities
- Quebec battery valley expansion:Provincial critical mineral processing investments are creating captive feedstock advantages for separator producers locating near cathode active material plants.
- Commercial vehicle electrification:Heavy-duty truck and bus OEMs are specifying thicker composite separators with enhanced puncture resistance for demanding duty cycles.
- Recyclable separator development:Federal sustainable technology funding is accelerating R&D into monomaterial membranes compatible with closed-loop battery recycling infrastructure.
Industry Challenges
- Electrochemical engineering talent scarcity:Canadian universities produce insufficient specialists in separator pore architecture design and ionic conductivity optimization.
- Cell manufacturer qualification timelines:OEM validation protocols for new separator formulations extend 18-24 months, delaying revenue recognition for domestic entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Electric Vehicle Battery Separator Market |
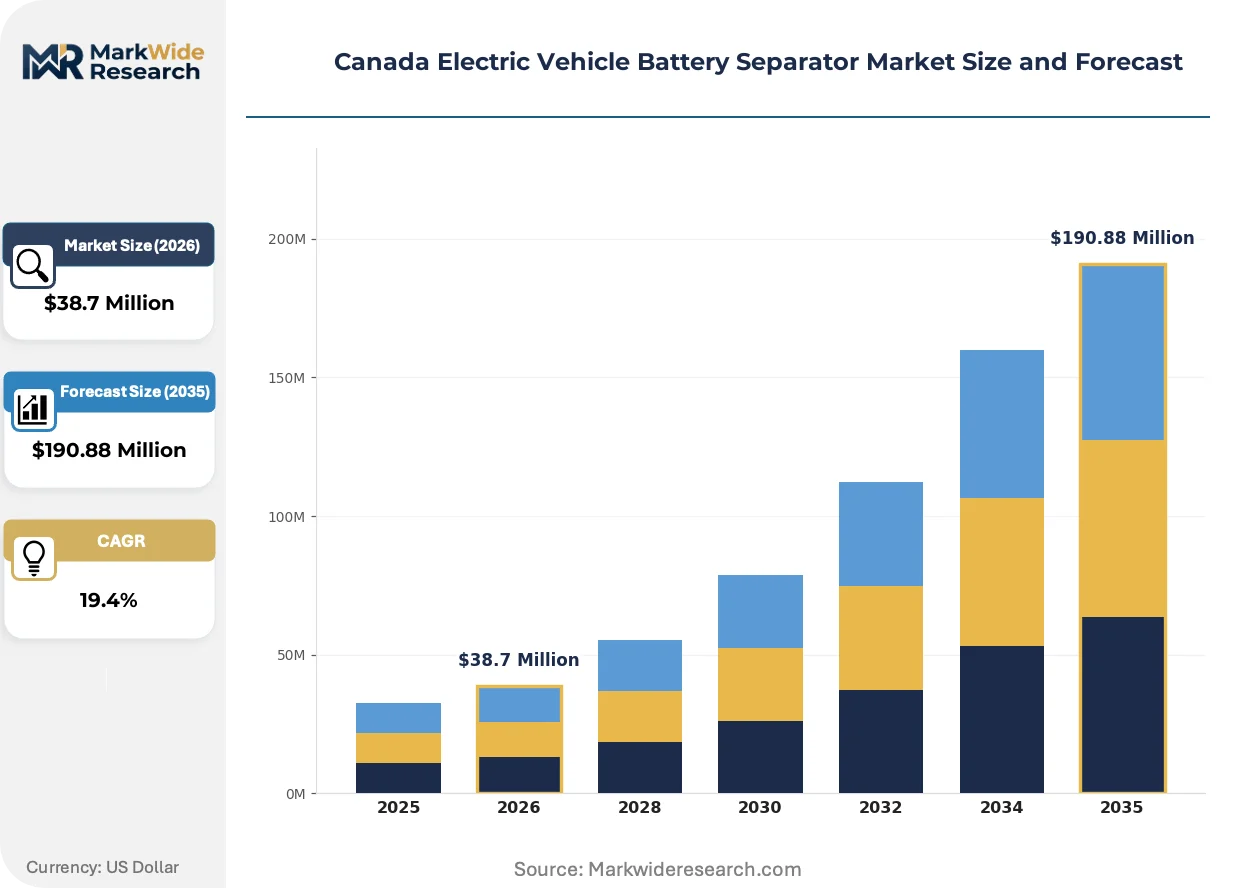
| Market Size in 2026 | $38.7 Million |
| Market Size in 2035 | $190.88 Million |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, Composite, Glass Fiber Thickness: 25 Micron, 30 Micron, 40 Micron, 50 Micron End User: OEMs, Aftermarket Providers, Fleet Operators, Charging Infrastructure Application: Passenger Vehicles, Commercial Vehicles, E-Bikes, E-Scooters |
| Companies Covered | Asahi Kasei Corporation, SK Innovation Co., Ltd., Toray Industries, W-Scope Corporation, SEMCORP Co., Ltd., Sumitomo Chemical Co., Ltd., UBE Corporation, Freudenberg Performance Materials, ENTEK International LLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Electric Vehicle Battery Separator Market Trends and Innovations
Dry-process membrane manufacturing is collapsing the traditional wet-process dominance in Canadian separator supply chains, while regulatory pressure on perfluorinated compounds accelerates material reformulation across the value chain.
Ceramic-coated polyethylene separators are collapsing the thermal safety gap between conventional polyolefins and high-cost polyimide alternatives. Canadian OEMs assembling high-nickel battery packs are adopting these hybrid membranes at accelerating rates. The technology is collapsing the premium pricing tier for thermal runaway protection, forcing pure-play ceramic suppliers to defend value through thickness reduction and ionic conductivity gains.
Environment and Climate Change Canada restrictions on perfluorinated compounds in industrial processes are forcing wet-process separator manufacturers to eliminate fluorinated surfactants from their coating chemistries. This regulatory compression is triggering capital-intensive solvent recovery system upgrades across Ontario production facilities. The policy is reshaping competitive positioning toward dry-process specialists with inherently lower environmental compliance burdens.
Cell manufacturer consolidation in Ontario is compressing supplier negotiation leverage and accelerating long-term offtake contracting. Tier-one battery producers are locking in separator volume commitments five to seven years forward, displacing spot-market procurement. This behavioral shift is most visible in the Windsor-Toronto corridor, where Stellantis and LG Energy Solution joint venture scale is dictating qualification standards for the entire provincial supply base.
Canada Electric Vehicle Battery Separator Market Segmentation
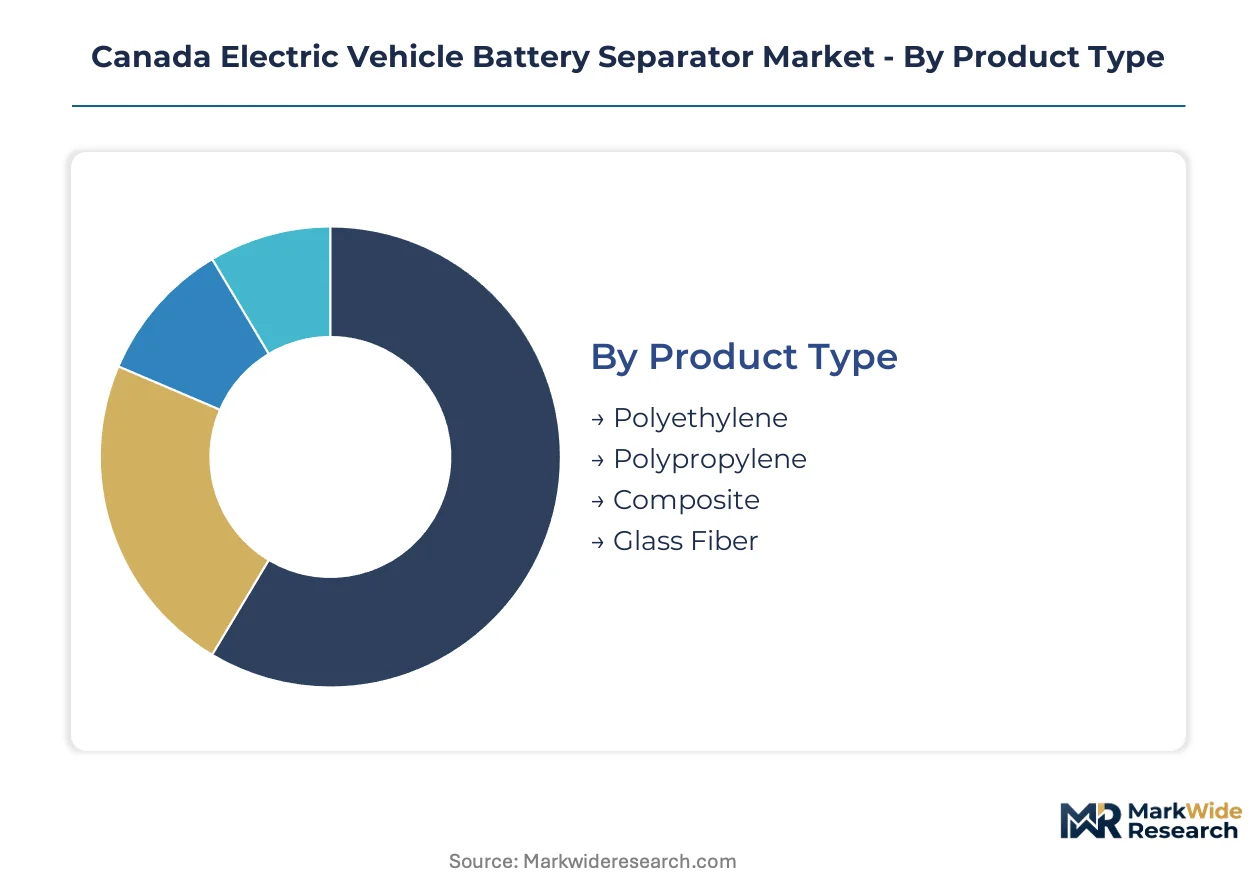
Separator selection in the Canada electric vehicle battery separator market hinges on thermal runaway thresholds, cell format constraints, and OEM qualification protocols. Procurement cycles vary dramatically across product types and end-use applications, with passenger vehicle programs moving fastest and commercial vehicle validation extending timelines.
Product Type:
Polyethylene separators turn inventory fastest due to standardized OEM specifications, while composite formulations linger in extended validation cycles for next-generation chemistries.
- Polyethylene:A microporous polyolefin membrane with a thermal shutdown mechanism that activates between 130°C and 140°C. Ontario's automotive corridor absorbs the bulk of procurement volume as Stellantis and LG Energy Solution joint venture operations specify this baseline chemistry for cost-sensitive cell formats.
- Composite:Hybrid constructions combining polyolefin substrates with ceramic coatings for enhanced thermal stability. Canadian OEMs assembling high-nickel battery packs are adopting these membranes at accelerating rates to manage thermal runaway risks in demanding duty cycles.
- Polypropylene:Higher melting point than polyethylene variants, suited to elevated-temperature operating environments. Fleet operators in Alberta's cold-climate corridors favor this chemistry for commercial vehicle battery packs.
- Glass Fiber:Inorganic nonwoven matrices offering extreme thermal resistance and electrolyte wettability. Niche applications in heavy-duty bus electrification programs around Vancouver and Montreal.
Polyethylene dominates installed base. Composite is where expansion concentrates.
Thickness:
Cost tiers stratify sharply across thickness specifications, with thinner membranes commanding premium positioning for energy-dense cell designs.
- 25 Micron:Ultra-thin membranes maximizing volumetric energy density for premium passenger vehicle segments. Quebec battery valley cathode active material plants are driving specification alignment toward this thickness class.
- 30 Micron:Balanced mechanical strength and ionic conductivity for mainstream cell production. Ontario separator producers maintain highest throughput on this specification.
- 40 Micron:Reinforced puncture resistance for commercial vehicle and heavy-duty applications. Windsor-Toronto corridor OEMs specify this thickness for truck and bus battery packs.
- 50 Micron:Maximum mechanical durability for extreme duty cycles and secondary-use stationary storage. Emerging demand from Alberta oilfield electrification retrofits.
30 micron commands current production volume. 25 micron is climbing the fastest as energy density targets tighten.
End User:
Customer type determines contract structure, with OEMs locking in long-term offtake and fleet operators driving spot-market flexibility.
- OEMs:Tier-one battery producers with five-to-seven-year volume commitments and stringent qualification protocols. Stellantis, Ford, and GM operations in Ontario dictate separator standards for the entire provincial supply base.
- Fleet Operators:Municipal transit authorities and logistics companies specifying thicker composite separators for demanding duty cycles. Vancouver's TransLink and Toronto's TTC are accelerating procurement for electric bus conversions.
- Aftermarket Providers:Replacement separator demand tied to battery refurbishment and second-life applications. Quebec's emerging recycling infrastructure is creating captive feedstock advantages.
- Charging Infrastructure:Stationary storage battery separators for grid-buffering installations. Hydro-Québec utility-scale projects are driving specification toward 40-50 micron thickness classes.
OEMs dominate installed base. Fleet operators are gaining share fastest as commercial electrification accelerates.
Application:
Application maturity spreads across passenger vehicle dominance and emerging commercial vehicle intensity.
- Passenger Vehicles:High-volume production programs with standardized separator specifications. Ontario's automotive corridor concentrates procurement for Stellantis, Ford, and GM electric vehicle assembly.
- Commercial Vehicles:Heavy-duty truck and bus applications demanding enhanced puncture resistance and thermal stability. Alberta and British Columbia fleet electrification mandates are expanding procurement fastest.
- E-Bikes:Cost-optimized separator specifications for micromobility battery packs. Montreal and Vancouver urban delivery fleets are driving regional demand concentration.
- E-Scooters:Thin-format separators for compact lithium-ion cell designs. Seasonal demand patterns tied to Toronto and Vancouver shared mobility deployments.
Passenger vehicles dominate installed base. Commercial vehicles represent the steepest expansion trajectory as zero-emission mandates tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada's separator trade balance tilts toward import dependency, with domestic production concentrated in Ontario while Quebec and British Columbia absorb specialized imports for distinct battery chemistries.
Ontario
Stellantis-LG Energy Solution joint venture operations in Windsor drive polyethylene separator procurement at industrial scale. Transport Canada zero-emission vehicle mandates compress supplier qualification timelines for corridor manufacturers. The Windsor-Toronto automotive corridor concentrates domestic separator demand as cell production scales toward 2030 targets.
Quebec
Critical mineral processing investments around Bécancour create captive feedstock advantages for cathode active material plants specifying ultra-thin 25-micron membranes. Environment and Climate Change Canada perfluorinated compound restrictions force wet-process reformulation at local coating facilities. The Quebec battery valley attracts separator producers seeking proximity to nickel and lithium refining infrastructure.
Alberta
Cold-climate fleet operators favor polypropylene separators for commercial vehicle battery packs operating in sub-zero conditions. Provincial electrification mandates for oilfield equipment drive demand for 50-micron reinforced membranes in stationary storage retrofits. Calgary-Edmonton logistics corridors concentrate heavy-duty truck electrification programs with extended validation cycles.
British Columbia
TransLink and municipal transit authorities accelerate ceramic-coated composite procurement for electric bus conversions across the Lower Mainland. Health Canada battery safety standards influence separator testing protocols at Vancouver-area validation labs. The province's hydroelectric grid supports utility-scale storage projects specifying thicker glass fiber separators for grid-buffering installations.
Atlantic Canada
Regional port infrastructure development targets European battery supply chain integration, positioning Halifax for separator import logistics. Federal sustainable technology funding flows toward recyclable membrane R&D at Atlantic universities. New Brunswick's emerging battery recycling infrastructure creates secondary demand for monomaterial separator refurbishment.
Canada Electric Vehicle Battery Separator Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in the separator value chain, with cell manufacturers consolidating supplier leverage through long-term offtake contracting. The Canadian market exhibits tiered concentration, with global polyolefin specialists holding established positions and dry-process niche players defending margin through regulatory compliance advantages. Three archetypes dominate: Asian membrane conglomerates with integrated coating capabilities, European materials specialists with automotive qualification heritage, and North American process innovators exploiting environmental regulatory shifts. Competitive dynamics center on capacity expansion near Ontario cell plants and technology licensing agreements for ceramic-coating intellectual property.
Among Japanese industrial conglomerates, Asahi Kasei Corporation and Toray Industries exemplify the integrated membrane-coating archetype with established North American supply relationships. Sumitomo Chemical Co., Ltd. and UBE Corporation occupy positions within the polyolefin substrate tier, representing scale-driven production capabilities. SK Innovation Co., Ltd. anchors the Korean specialist contingent, while ENTEK International LLC exemplifies the North American dry-process niche. These entities collectively represent the competitive spectrum from commodity polyethylene supply to differentiated ceramic-coated formulations serving high-nickel cathode requirements.
| Leading Market Players |
|---|
| Asahi Kasei Corporation |
| SK Innovation Co., Ltd. |
| Toray Industries |
| W-Scope Corporation |
| SEMCORP Co., Ltd. |
| Sumitomo Chemical Co., Ltd. |
| UBE Corporation |
| Freudenberg Performance Materials |
| ENTEK International LLC |
| Others |
Pricing and Supply Chain Analysis
Ontario separator production capacity running at 85 percent utilization is compressing spot-market availability while forcing long-term contract premiums upward for non-anchored buyers. Transport Canada zero-emission vehicle mandates are accelerating qualification timelines, tightening the window for price negotiation before volume commitments lock in.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across the Canada electric vehicle battery separator market. Pricing stratifies across premium ceramic-coated, standard polyethylene, and economy-grade polypropylene tiers based on thermal performance certification and volume scale commitments. Cost compression in standard polyethylene tiers is intensifying because polyolefin feedstock volatility destabilizes margin structures. Fleet operators exhibit highest price sensitivity due to thinner margin profiles, while Stellantis-LG joint venture operations command least sensitivity through captive volume guarantees.
Supply Chain Analysis
Export controls on advanced coating equipment from Japan and South Korea are constraining Canadian producers' access to ceramic deposition technology. Raw material flows draw from Chinese polyethylene resin suppliers, Japanese ceramic powder specialists, and Korean coating equipment manufacturers. Single-source vulnerability concentrates in East Asian ceramic powder supply, exposing Ontario production lines to shipping disruption cascades. Distribution runs through direct OEM integration with Windsor-Toronto corridor cell plants, bypassing traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cell manufacturer consolidation around Stellantis-LG Energy Solution operations in Ontario is shifting procurement leverage decisively toward buyers, fragmenting supplier negotiation power across the domestic separator base.
For Market Incumbents: Build regulatory compliance moats around dry-process manufacturing capabilities to defend against wet-process reformulation costs triggered by Environment and Climate Change Canada perfluorinated compound restrictions. Secure backward integration into Quebec critical mineral processing corridors to anchor feedstock cost advantages against Asian ceramic powder volatility. Expand coating capacity within Ontario's automotive corridor to maintain qualification proximity with consolidating cell manufacturers. For New Entrants and Emerging Players: Alberta's cold-climate commercial vehicle segment offers underpenetrated white-space for polypropylene separator specialists targeting heavy-duty fleet electrification. Atlantic Canada's emerging battery recycling infrastructure presents secondary demand capture opportunities for monomaterial membrane developers. Establish technical validation partnerships with Hydro-Québec utility-scale storage projects to bypass lengthy OEM qualification timelines. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among dry-process specialists with environmental regulatory compliance advantages over wet-process competitors. Five-to-ten-year viability hinges on ceramic-coating intellectual property positioning for high-nickel cathode chemistries. Monitor Transport Canada zero-emission vehicle mandate acceleration as inflection indicator for separator qualification volume spikes.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Ontario corridor proximity to Stellantis-LG operations reduces logistics costs and qualification friction. |
| Backward Integration | Quebec critical mineral processing investments create captive ceramic powder supply for composite separator production. |
| Green Manufacturing Transition | Dry-process adoption eliminates Environment and Climate Change Canada perfluorinated compound compliance burdens. |
| Long-term Supply Agreement | Five-to-seven-year offtake contracts with Ontario OEMs lock in volume against Asian import volatility. |
| Joint Venture | Technology licensing partnerships with Korean ceramic-coating specialists accelerate high-nickel separator qualification. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade data, and OEM procurement disclosures across the Canada electric vehicle battery separator market. Primary interviews engaged separator plant managers, Tier 1 battery procurement leads, Transport Canada regulatory affairs officers, and Quebec critical mineral processing executives. Secondary validation drew from Environment and Climate Change Canada chemical restriction notices, Ontario automotive production databases, and Health Canada battery safety standard documentation. Bottom-up capacity modeling triangulated against top-down OEM demand projections.
Forecast inputs span product type segmentation across polyethylene, composite, and polypropylene chemistries; thickness specifications from 25 to 50 micron; and end-user categories distinguishing OEM, fleet operator, and aftermarket demand. Vehicle class segmentation separates passenger vehicle procurement patterns from commercial vehicle electrification intensity. CAGRs were derived through regression analysis of historical capacity expansion against mandate-driven demand inflections. Cell manufacturer consolidation timelines and ceramic-coating technology diffusion curves informed trajectory calibration across the projection horizon.
Practitioners should monitor Transport Canada mandate acceleration, Environment and Climate Change Canada regulatory expansion, and Asian ceramic powder supply disruption for early signals of forecast revision. Material shifts in federal zero-emission vehicle incentive structures or perfluorinated compound restriction enforcement would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Infrastructure
Advance Battery Technologies Market
Battery Infrastructure
France Electric Vehicle Battery Manufacturing Equipment Market
Battery Infrastructure
EV Battery Sealant Market
Battery Infrastructure
Battery Swap-Ready Pack Systems for Urban Fleets Market
Battery Infrastructure
New Energy Battery Structural Parts Market
Battery Infrastructure
Battery Lug Market
Battery Infrastructure
France Electric Vehicle Battery Materials Market
Battery Infrastructure
South America Electric Vehicle Battery Manufacturing Equipment Market
Battery Infrastructure
Battery-As-A-Service Market
Battery Infrastructure
Battery Production Machine Market
Battery Infrastructure
North America Electric Vehicle Battery Electrolyte Market
Battery Infrastructure
Battery Enclosure Market
Battery Infrastructure
Lithium-Ion Battery Housing Cases Market
Battery Infrastructure
Carbon Battery Bank Market
Battery Infrastructure
Germany Electric Vehicle Battery Separator Market
Battery Infrastructure
Electric Vehicle Battery Swapping Market