

EV Battery Passport Market Size, Share, and Industry Trends Forecast 2026-2036
EV Battery Passport Market Insights
Subscription-based traceability software is expanding the addressable market for EV battery passport vendors beyond one-time licensing into recurring revenue pools. Circulor leverages blockchain architecture to anchor its position in upstream mineral tracking for European automakers. SAP competes through enterprise ERP integration that extends passport data into existing supply chain workflows. OPTEL GROUP specializes in pharmaceutical serialization technology that it navigates into battery lifecycle compliance applications.
An EV battery passport is a digital record system that encodes technical specifications including cell chemistry, state of health, carbon footprint, and chain-of-custody data across a battery's full lifecycle. Its primary commercial purpose is to enable regulatory compliance, secondary use qualification, and recycling value recovery. Blockchain-enabled passport architectures occupy the premium tier where margin pools concentrate due to immutability requirements for conflict-mineral verification. Cloud-based deployments represent the fastest-scaling segment as mid-tier battery manufacturers prioritize cost efficiency over decentralized infrastructure. Original Equipment Manufacturers constitute the dominant end-user category because they bear direct liability under extended producer responsibility frameworks.
The EU Battery Regulation mandates digital passports enforced by national market surveillance authorities across Germany, France, and Poland, creating immediate compliance demand for platforms serving European manufacturing. China's MIIT implements GB standards for battery traceability that require domestic and foreign producers to integrate with state-approved data repositories. The United States lacks federal passport mandates but California's SB 1215 and emerging SEC climate disclosure rules are forcing OEMs to adopt voluntary passport architectures. Stakeholders must decide whether to build proprietary passport stacks or embed third-party platforms before regulatory fragmentation hardens into irreversible procurement specifications.
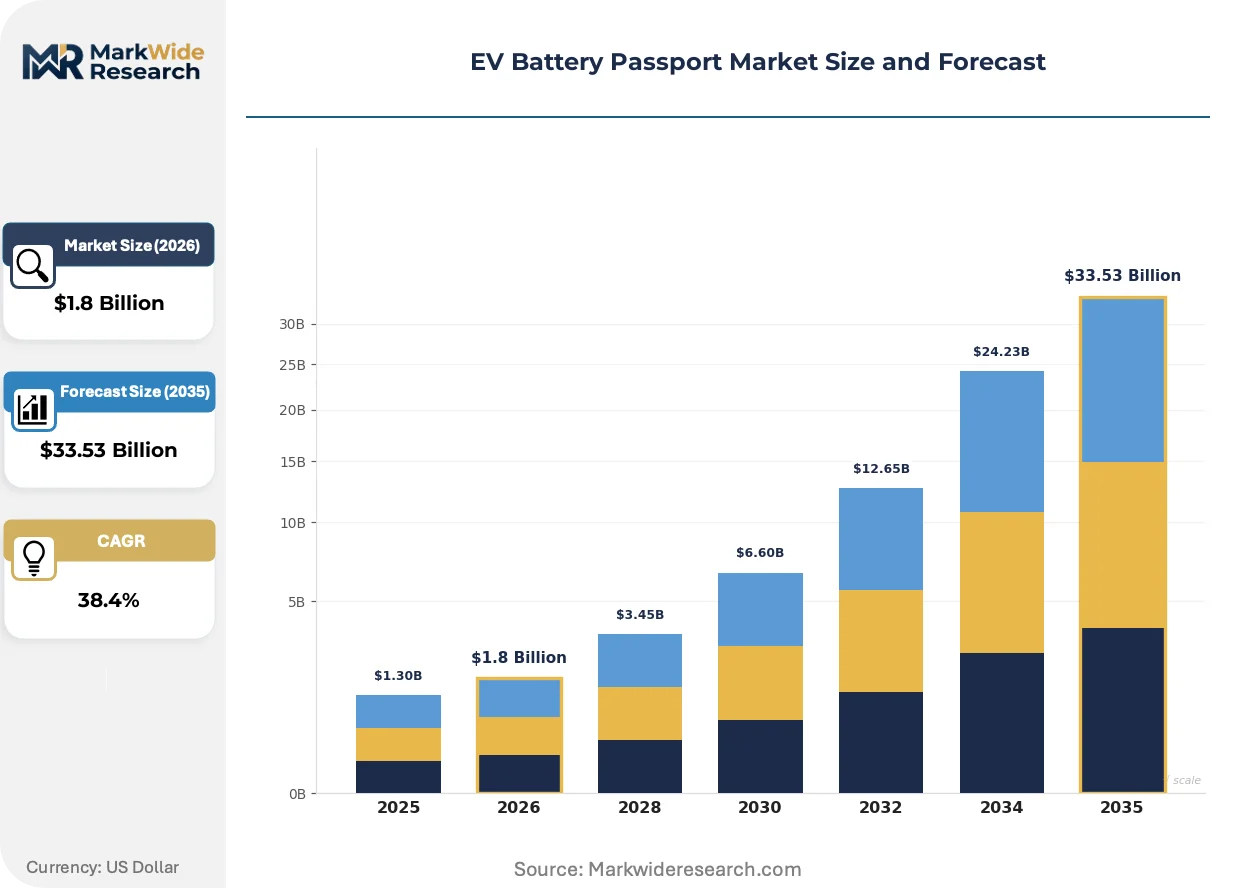
Market Dynamics
The EU Battery Regulation's digital passport mandate is compressing procurement timelines for automotive OEMs, forcing immediate platform selection decisions before 2027 enforcement deadlines harden vendor lock-in.
Growth Catalysts
- Extended Producer Responsibility:Automotive OEMs face direct liability for battery end-of-life management under EU frameworks, creating captive demand for passport systems that automate compliance documentation.
- Blockchain Immutability:Conflict-mineral verification requirements for cobalt, lithium, and nickel sourcing are pulling battery manufacturers toward distributed ledger architectures that satisfy downstream audit demands.
- Secondary Use Markets:Stationary energy storage operators require standardized state-of-health data to qualify retired EV batteries, expanding passport utility beyond regulatory compliance into asset valuation.
Market Restraints
- Interoperability Fragmentation:Divergent data standards between China's GB protocols and EU Battery Regulation specifications force dual-platform investments for multinational battery producers.
- Upstream Concentration:Critical mineral refining concentrates in Chinese processing facilities, creating single-point-of-failure risks for passport chain-of-custody verification.
- Legacy ERP Integration Costs:Mid-tier battery manufacturers face prohibitive customization expenses when embedding passport modules into decades-old manufacturing execution systems.
Strategic Opportunities
- Recycling Certification Services:EU-approved recycling facilities can monetize passport-verified material recovery certificates that command premiums from OEMs seeking closed-loop supply claims.
- AI-Powered Predictive Analytics:Machine learning models trained on aggregated passport degradation data enable battery residual value forecasting for financial leasing products.
- US State-Level Mandates:California's SB 1215 and emerging SEC climate disclosure rules are creating voluntary adoption pathways ahead of potential federal harmonization.
Industry Challenges
- Cross-Border Data Sovereignty:EU GDPR restrictions on battery performance data transfer conflict with China's data localization requirements for MIIT-registered repositories.
- Skills Shortage in Distributed Systems:Blockchain architecture expertise remains scarce among industrial software vendors serving automotive supply chains.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EV Battery Passport Market Trends and Innovations
Cloud-native passport deployments are compressing time-to-compliance for mid-tier manufacturers while blockchain architectures capture premium margins from conflict-mineral verification requirements.
Cloud-based Software-as-a-Service passport platforms are overtaking on-premise installations among European battery cell producers seeking rapid EU Battery Regulation compliance without capital-intensive infrastructure buildouts. Mid-tier manufacturers in Poland and Hungary are adopting these deployments to meet 2027 deadlines. The shift is compressing vendor selection cycles and favoring providers with pre-configured regulatory templates over customizable enterprise solutions.
REACH-compliant material disclosure requirements are expanding passport data fields to include full substance composition beyond the cell chemistry summaries originally contemplated. Battery producers must now document additive concentrations and binder materials across the electrode manufacturing process. European OEM procurement teams are responding by embedding passport data validation gates into supplier qualification workflows.
Subscription-based traceability contracts are displacing perpetual licensing arrangements as automakers seek operational expenditure alignment with compliance cost volatility. Tier 1 battery suppliers in Germany and South Korea are negotiating multi-year platform commitments that bundle software access with regulatory update services. The model is most visible among OEMs with diversified global manufacturing footprints requiring continuous standard harmonization.
EV Battery Passport Market Segmentation
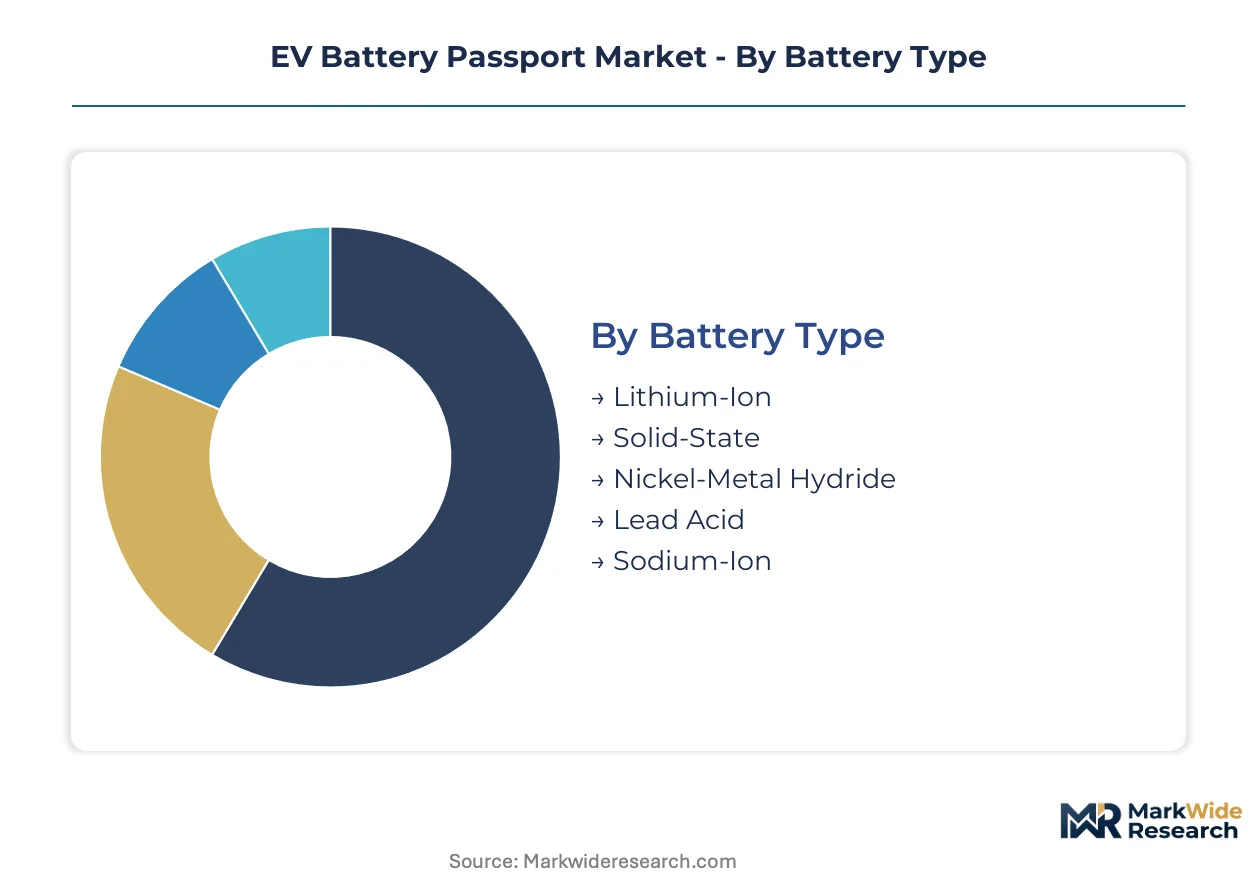
Segmentation in the EV battery passport market determines integration architecture and procurement economics. Battery chemistry dictates data field complexity, while deployment technology shapes margin structures and compliance timelines across OEM supply chains.
Battery Type:
Integration depth varies sharply by electrochemistry, with high-nickel formulations requiring granular mineral provenance tracking versus simpler legacy systems.
- Lithium-Ion:Dominant chemistry encompassing NMC, LFP, and NCA variants with distinct passport data requirements for cathode composition disclosure. European OEM procurement teams in Germany and Poland prioritize NMC passports for premium EV platforms, while Chinese manufacturers favor LFP documentation for cost-optimized commercial vehicles.
- Solid-State:Emerging ceramic-electrolyte architectures with simplified thermal management profiles but complex manufacturing-step documentation needs. Japanese automotive consortiums led by Toyota and Nissan are piloting proprietary passport schemas for sulfide-based cells ahead of commercial scale-up.
- Nickel-Metal Hydride:Mature hybrid-electric vehicle chemistry with established recycling infrastructure requiring minimal passport enhancement beyond existing producer responsibility frameworks.
- Lead Acid:Stationary and starter battery applications with basic material disclosure requirements under REACH compliance, rarely triggering advanced passport investments.
- Sodium-Ion:Abundant-material alternative gaining traction in Chinese grid-storage deployments where mineral conflict risks are negligible, reducing blockchain verification premiums.
Lithium-Ion leads volumes today; Solid-State is gaining share fastest.
Technology:
Deployment models stratify by immutability requirements and capital intensity, with cloud architectures compressing time-to-compliance for mid-tier producers.
- Blockchain:Distributed ledger architectures anchoring conflict-mineral verification through cryptographic chain-of-custody records. European OEMs sourcing DRC cobalt via German trading houses mandate blockchain passports to satisfy downstream audit requirements from regulators including ECHA.
- Cloud-Based:SaaS platforms with API-native integration into existing ERP systems, dominating Polish and Hungarian battery cell producer procurement for 2027 EU Battery Regulation deadlines.
- IoT Enabled:Sensor-embedded passports capturing real-time state-of-health telemetry for secondary-use qualification in stationary storage applications.
- AI Integrated:Machine learning modules predicting degradation trajectories to optimize residual value calculations for battery leasing products.
- Data Analytics:Aggregation engines processing passport datasets across supplier tiers to identify carbon footprint optimization opportunities.
Blockchain commands premium pricing; Cloud-Based deployments are expanding most quickly.
Application:
End-use segmentation determines regulatory exposure and data retention periods, with mobility applications facing stricter extended producer responsibility than stationary assets.
- Electric Passenger Vehicles:Premium OEM platforms with comprehensive passport mandates under EU Battery Regulation including carbon footprint declarations and recycled content quotas. German automotive procurement departments are embedding passport validation gates into cell supplier contracts.
- Commercial Electric Vehicles:Heavy-duty buses and trucks with accelerated degradation profiles requiring enhanced state-of-health tracking for residual value recovery.
- Electric Two-Wheelers:High-volume Asian markets with simplified passport requirements under China's MIIT GB standards, prioritizing basic traceability over granular material disclosure.
- Grid Storage:Stationary applications leveraging retired EV batteries where standardized health data enables secondary-use qualification.
- Remote Power Systems:Off-grid installations with minimal regulatory oversight, typically bypassing passport investments unless OEM supply chain integration mandates compliance.
Electric Passenger Vehicles dominates revenue concentration; Grid Storage is climbing the fastest.
End User:
Customer type shapes platform customization depth, with OEMs demanding enterprise-grade integration versus recyclers prioritizing material recovery certification workflows.
- Original Equipment Manufacturers:Primary liability holders under extended producer responsibility frameworks requiring end-to-end supply chain visibility. Volkswagen, BMW, and Mercedes-Benz procurement teams are consolidating vendor relationships around platforms with pre-configured EU Battery Regulation templates.
- Battery Remanufacturers:Secondary-market operators requiring standardized state-of-health data to qualify cells for automotive reuse or stationary redeployment.
- Recycling Facilities:EU-approved operators monetizing passport-verified material recovery certificates that command premiums from OEMs seeking closed-loop supply claims.
- Fleet Operators:Commercial vehicle managers leveraging passport data to optimize battery swap timing and residual value realization.
- Energy Storage Providers:Utility-scale and commercial installers sourcing retired EV batteries where passport health records reduce due diligence costs.
Original Equipment Manufacturers anchors demand today; Recycling Facilities is expanding most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive procurement departments are embedding passport validation gates into cell supplier contracts faster than China's state-mandated MIIT repository integrations, revealing divergent compliance acceleration patterns between regulatory-driven and state-directed economies.
Germany
Volkswagen, BMW, and Mercedes-Benz procurement teams are consolidating vendor relationships around platforms with pre-configured EU Battery Regulation templates. The KBA enforces digital passport mandates with 2027 deadlines, compressing platform selection cycles. Battery cell producers in Lower Saxony and Baden-Württemberg are adopting cloud-native deployments to meet enforcement timelines.
China
Domestic EV manufacturers and foreign joint ventures must integrate with MIIT-approved data repositories under GB standards for battery traceability. The Ministry of Industry and Information Technology mandates real-time production data uploads. Yangtze River Delta cell producers in Jiangsu and Zhejiang are scaling passport platforms to satisfy both domestic compliance and EU export requirements.
United States
California's SB 1215 and emerging SEC climate disclosure rules are forcing OEMs to adopt voluntary passport architectures ahead of potential federal harmonization. The EPA and NHTSA lack direct passport mandates but coordinate with state-level frameworks. Michigan and California automotive clusters are piloting blockchain-verified mineral tracking for cobalt and lithium supply chains.
Poland
Mid-tier battery cell producers are adopting cloud-based SaaS platforms to meet 2027 EU Battery Regulation deadlines without capital-intensive infrastructure buildouts. The Polish market surveillance authority enforces digital passport compliance under delegated EU authority. Manufacturing facilities in Silesia and Lower Silesia are compressing vendor selection cycles around pre-configured regulatory templates.
South Korea
LG Energy Solution and Samsung SDI procurement teams are negotiating multi-year platform commitments that bundle software access with regulatory update services. The Ministry of Trade, Industry and Energy aligns domestic standards with EU Battery Regulation specifications. Battery producers in Gyeonggi Province and Chungcheong Province are embedding passport data validation gates into electrode manufacturing workflows.
EV Battery Passport Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with blockchain architects commanding premium pricing for conflict-mineral verification while cloud-native platforms capture volume among mid-tier producers. The vendor base concentrates around three strategic archetypes: ERP-integrated enterprise suites, mineral-tracking blockchain specialists, and serialization-technology crossovers from pharmaceutical compliance. M&A activity targets regulatory template libraries, and strategic partnerships concentrate on API-native ERP integration capabilities.
Within the blockchain-native tier, Circulor and Minespider occupy positions anchored in upstream mineral provenance verification for European automakers sourcing DRC cobalt. SAP represents the ERP-integrated archetype, extending passport data into existing supply chain workflows through enterprise system compatibility. OPTEL GROUP exemplifies the serialization-technology crossover pattern, navigating pharmaceutical track-and-trace expertise into battery lifecycle compliance applications.
| Leading Market Players |
|---|
| Circulor |
| Minespider |
| AVL |
| Siemens |
| SAP |
| Everledger |
| RCS Global |
| OPTEL GROUP |
| IOTA |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up SaaS specialists now control platform provisioning across European battery manufacturing, tightening pricing discipline through subscription bundling while compressing procurement cycles for OEM compliance teams facing KBA enforcement timelines.
Pricing Analysis
Capacity additions in Poland and Hungary are reshaping price floors for cloud-native passport deployments as mid-tier manufacturers prioritize operational expenditure models over capital-intensive blockchain infrastructure. Three-tier pricing structure across premium blockchain, standard cloud-SaaS, and economy API-gateway levels dominates vendor negotiations, with certification grade under EU Battery Regulation specifications driving differentiation. Cost compression in the economy tier is intensifying because Polish cell producers are consolidating around pre-configured regulatory templates. Tier 1 German OEMs exhibit least price sensitivity due to direct liability exposure, while Asian export-oriented manufacturers demonstrate highest elasticity.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Volkswagen, BMW, and Mercedes-Benz procurement teams, bypassing distributor markups for enterprise-grade platform deployments. Geographic supply concentrates in Germany, China, and South Korea, with software development anchored in European regulatory technology clusters and cloud infrastructure drawing from Irish and Frankfurt data center hubs. Raw material dependencies span cobalt from DRC trading houses, lithium carbonate from Chilean and Australian refiners, and nickel from Indonesian processing facilities. Single-source vulnerability in Chinese critical mineral refining creates chain-of-custody verification bottlenecks for blockchain passport architectures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
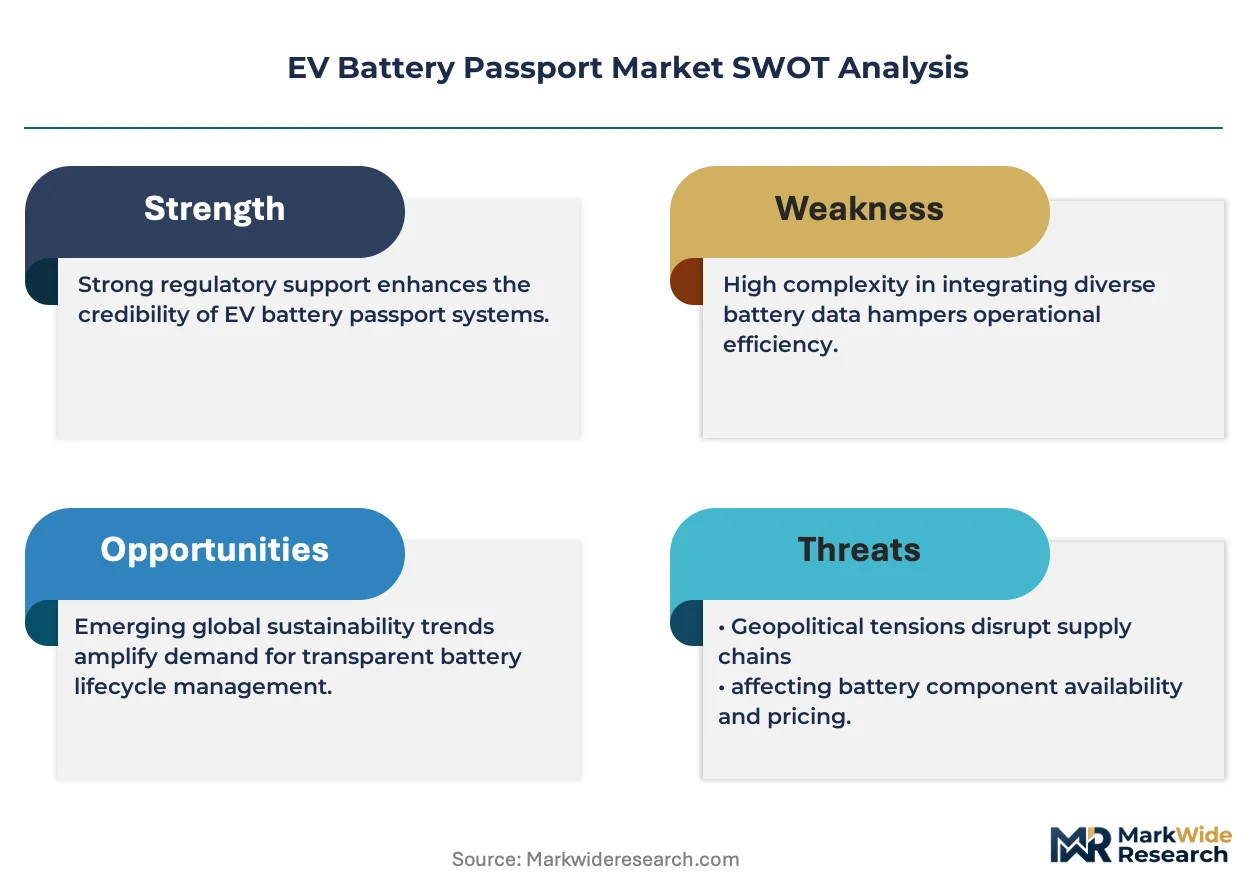
Analyst Recommendations
EV battery passport platforms function as stable compounders where regulatory mandate expansion across EU member states generates predictable recurring revenue pools insulated from cyclical automotive production volatility.
For Market Incumbents: Anticipate margin compression from cloud-native entrants by deepening ERP integration moats and pre-empting regulatory template expansion into REACH substance disclosure requirements. Prioritize certification investment for ECHA-aligned conflict-mineral verification to defend against blockchain specialists encroaching on upstream provenance tracking. Channel control through multi-year OEM procurement contracts remains the critical defensive lever against SaaS displacement. For New Entrants and Emerging Players: AI-powered predictive analytics modules offer a technology-first wedge into residual value forecasting for battery leasing products, an application layer incumbents have underdeveloped. Target Polish and Hungarian mid-tier cell producers as the most penetrable geography, where compressed 2027 compliance timelines favor rapid-deployment SaaS over enterprise customization. Lead with API-native integration capabilities to bypass legacy ERP replacement cycles. For Investors and Strategic Acquirers: Valuations sit cheapest among pharmaceutical serialization crossovers possessing regulatory template libraries but lacking battery-specific domain expertise, creating platform extension opportunities. Long-term viability centers on regulatory fragmentation persistence between EU Battery Regulation and China's MIIT GB standards, which sustains dual-platform demand. Watch for ECHA guidance on recycled content quota verification as the inflection signal for recycling certification service monetization.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Template Library Expansion | Pre-configured EU Battery Regulation modules accelerate Polish and Hungarian OEM procurement decisions. |
| Blockchain-Cloud Hybrid Architecture | Combines immutable mineral provenance with cost-efficient SaaS delivery for tiered buyer segmentation. |
| ERP Native Integration Partnership | SAP-compatible API layers embed passport data into existing Volkswagen and BMW supply chain workflows. |
| Recycling Certification Service Launch | EU-approved facilities monetize passport-verified recovery certificates for closed-loop supply claims. |
| AI Residual Value Module Development | Machine learning degradation models enable battery leasing product expansion into stationary storage. |
Research Methodology
Bottom-up OEM procurement modeling reconciled against top-down platform vendor tracking forms the analytical core, combining primary interviews with automotive compliance officers, battery cell producer IT directors, and recycling facility operations managers against secondary validation from ECHA guidance documents, KBA enforcement protocols, and MIIT GB standard filings. Trade data from German Federal Statistical Office and Polish Central Statistical Office anchored regional demand calibration. Top-down triangulation against cloud infrastructure deployment disclosures and ERP partnership announcements verified vendor market positioning.
Input-output matrices mapped passport data field requirements across lithium-ion, solid-state, and sodium-ion chemistries against deployment technology stacks and end-user liability exposure. Segmentation dimensions spanned battery chemistry complexity, immutability architecture, application regulatory intensity, and OEM tier integration depth. CAGRs derived from installed base expansion curves weighted by enforcement timeline proximity and compliance cost pass-through elasticity. Forecast inputs incorporated EU Battery Regulation delegated act progression and China's dual carbon policy trajectory.
The model holds under sustained regulatory fragmentation between EU and Chinese data sovereignty requirements; deviation in bilateral standard harmonization would shift vendor competitive positioning. Forecasts incorporate assumptions around KBA enforcement rigor and MIIT repository integration mandates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.