
 Global Abrasion Resistant Coatings Market | 2026-2036
Global Abrasion Resistant Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Global Abrasion Resistant Coatings Market Intelligence
Aftermarket service revenue is reconfiguring margin capture across the value chain. PPG Industries, Inc. leverages its automotive refinish heritage to extend protective coating service contracts into heavy machinery fleets. Akzo Nobel N.V. anchors European marine maintenance through specialized application networks in Rotterdam and Hamburg. BASF SE competes on formulation chemistry, sustaining premium positioning in ceramic-epoxy hybrid systems for oilfield equipment.
Abrasion resistant coatings are polymer or ceramic-based surface treatments engineered to withstand mechanical wear, typically achieving hardness values exceeding 5H pencil hardness and bond strengths above 20 MPa on prepared steel substrates; they protect capital-intensive equipment from erosive degradation in abrasive process environments. Epoxy formulations occupy the largest volume share due to their cost-performance balance in mining and manufacturing tool protection, while ceramic coatings represent the fastest-expanding technology segment as thermal spray application methods advance deposition efficiency for aerospace turbine components. Polyurethane systems dominate marine vessel applications where flexibility and UV resistance offset higher material costs.
The US EPA enforces volatile organic compound emission limits under NESHAP standards that compel coating reformulation toward waterborne and high-solids technologies, while REACH registration requirements in Europe restrict hazardous substance content in imported formulations. China's MEE implements GB standards for industrial coating emissions that reshape local manufacturing compliance costs. ISO 12944 corrosion protection standards govern international project specifications, creating certification barriers for non-compliant suppliers. Stakeholders must monitor regulatory divergence between jurisdictions to optimize formulation portfolios and avoid market access friction.
Market Dynamics
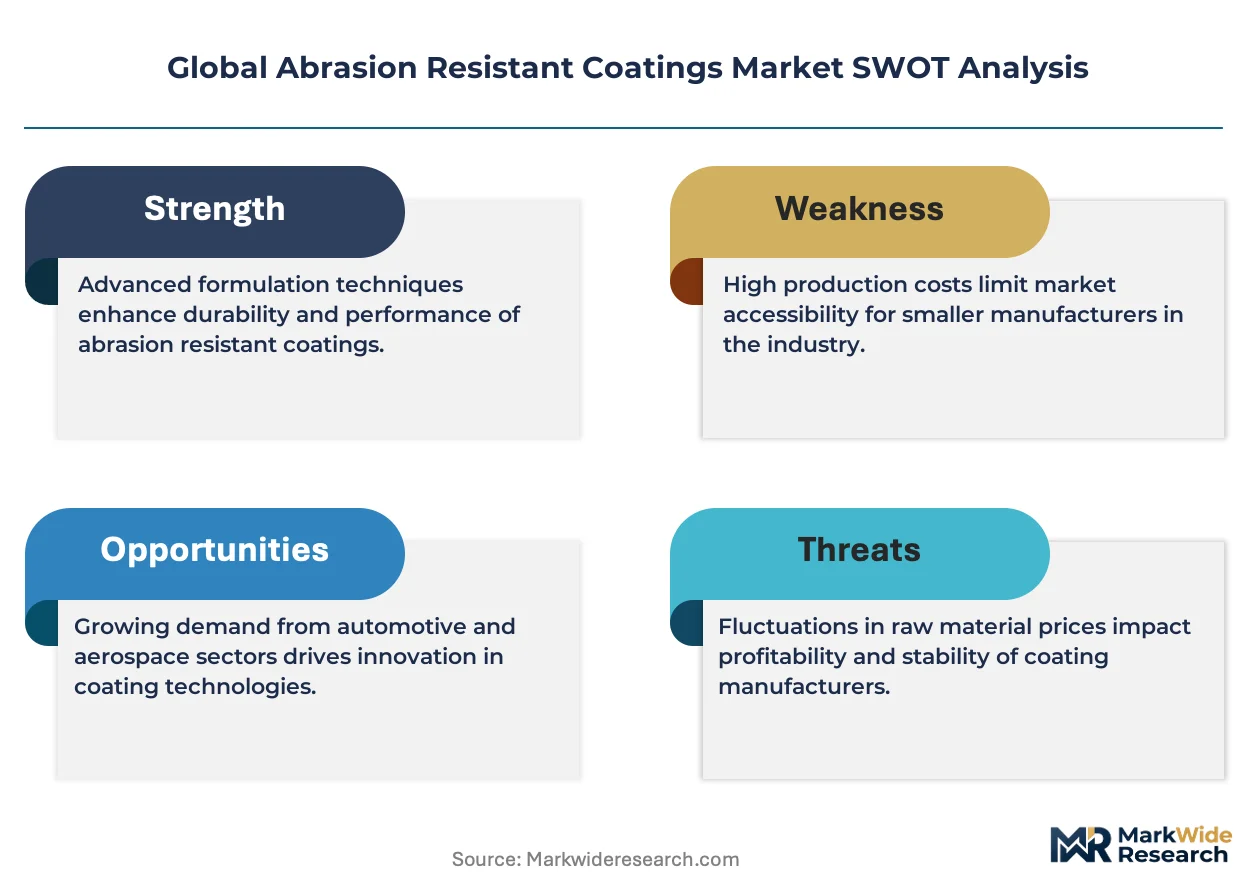
Coating formulation chemistry is pivoting under dual pressure from EPA volatile organic compound limits and REACH substance restrictions, forcing manufacturers to rebuild supply chains around waterborne and high-solids alternatives while maintaining performance thresholds.
Growth Catalysts
- Oil and Gas Asset Life Extension:Equipment operators in the Permian Basin and North Sea are expanding protective coating procurement to defer capital replacement cycles on drilling hardware and pipeline infrastructure.
- REACH Compliance Deadlines:ECHA registration requirements for hazardous substance content are accelerating reformulation investment among European suppliers seeking continued market access.
- Thermal Spray Deposition Efficiency:Aerospace turbine manufacturers are adopting advanced plasma spray systems that reduce ceramic coating application time and material waste.
Market Restraints
- Epoxy Resin Price Volatility:Petrochemical feedstock fluctuations create margin compression for coating manufacturers dependent on bisphenol-A derived formulations.
- Application Equipment Concentration:Thermal spray system supply concentrates among a limited set of German and Swiss equipment builders, creating procurement bottlenecks.
- Ceramic-Bond Technical Limitations:Coefficient of thermal expansion mismatches between ceramic topcoats and steel substrates limit performance in rapid thermal cycling environments.
Strategic Opportunities
- Indian Manufacturing Infrastructure:BIS certification requirements for industrial protective coatings are creating first-mover advantages for compliant foreign suppliers as domestic steel and cement capacity expands.
- Marine Hull Flexible Ceramic Hybrids:Shipyards in Rotterdam and Singapore are trialing polyurethane-ceramic composite systems that combine impact resistance with elastomeric deformation tolerance.
- China Dual Carbon Policy Alignment:MEE emissions standards for industrial coating operations are incentivizing low-VOC formulation adoption among state-owned steel and power generation asset owners.
Industry Challenges
- Certified Applicator Pipeline Shortages:ISO 12944 compliance auditing requires trained inspection personnel that remain scarce in emerging industrial clusters.
- Legacy Equipment Surface Preparation:Existing plant assets with degraded substrate conditions demand costly abrasive blasting before high-performance coating adhesion can be achieved.
- Multi-Jurisdiction Formulation Registration:Divergent VOC limits across EPA, REACH, and GB standard regimes force product line fragmentation and inventory complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Abrasion Resistant Coatings Market |
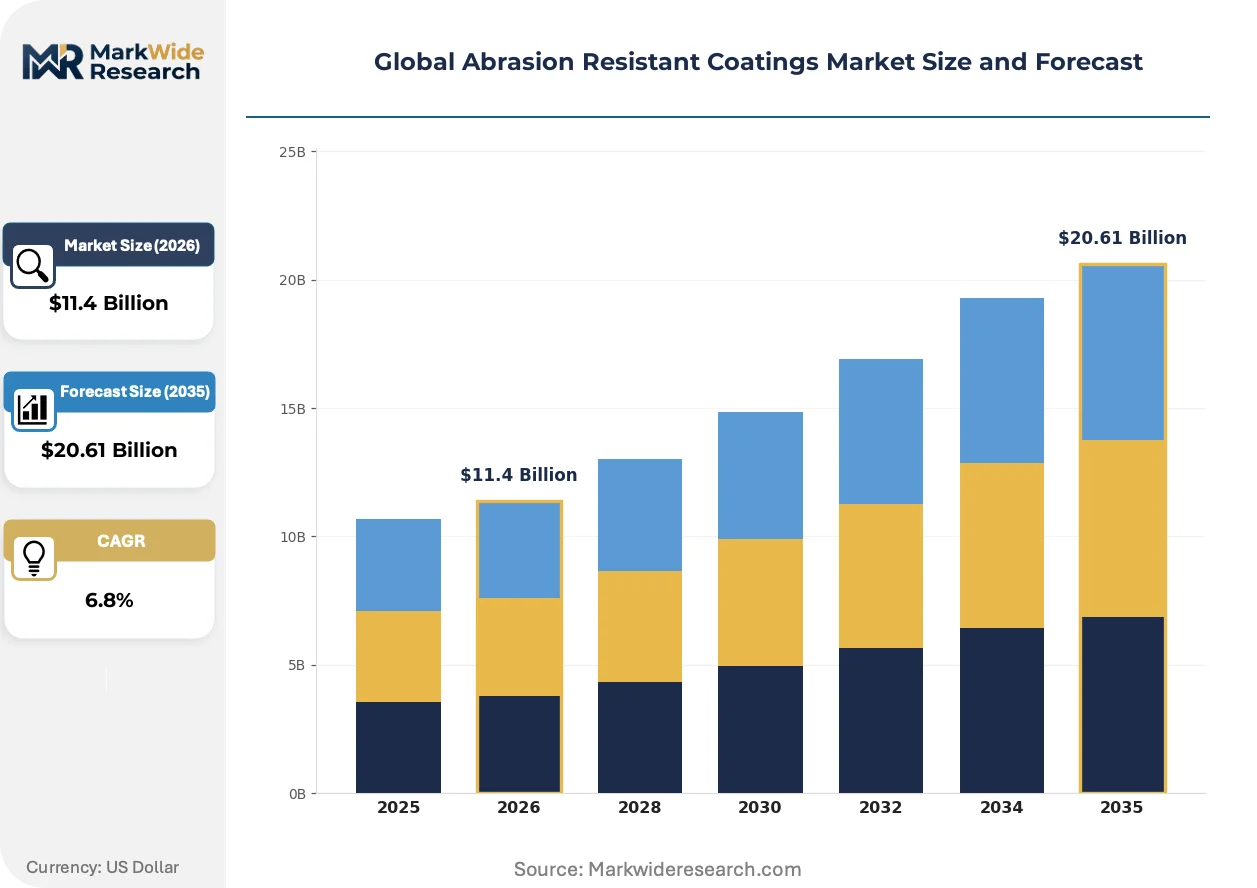
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $20.61 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Polyurethane, Ceramic, Acrylic, Fluoropolymer Application: Oil & Gas Equipment, Mining Machinery, Manufacturing Tools, Aerospace Components, Marine Vessels Technology: Thermal Spray, Electrostatic Spray, Brush Coating, Dip Coating, Roll Coating End User Industry: Energy Sector, Construction Equipment, Defense Systems, Transportation Fleet, Heavy Machinery |
| Companies Covered | RPM International Inc., Hempel A/S, PPG Industries, Inc., Axalta Coating Systems Ltd., Jotun A/S, Akzo Nobel N.V., BASF SE, Nippon Paint Holdings Co., Ltd., The Sherwin-Williams Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Abrasion Resistant Coatings Market Strategic Shifts & Innovations
Application technology and regulatory compliance frameworks are compressing traditional coating lifecycle economics while opening new performance tiers for specialized end-uses.
Nano-engineered ceramic matrix composites are achieving hardness values exceeding conventional tungsten carbide while reducing deposition temperature requirements. Aerospace maintenance facilities are adopting these materials for hot section component repair. The technology is rendering obsolete thermal barrier coating systems that required extended furnace cycles and substrate heat treatment.
EPA NESHAP standards for hazardous air pollutants from coating operations are mandating capture and control technology installation at fabrication facilities. Metal fabrication shops serving construction and agricultural equipment sectors are absorbing capital costs for enclosed spray booths and regenerative thermal oxidizers. Small and mid-tier job shops in the US Midwest are consolidating or exiting as compliance thresholds tighten.
Asset owners are unbundling coating specification from application service procurement, creating direct relationships with formulation suppliers while competitively tendering labor. Mining operators in Western Australia and Chile are issuing performance-based coating warranties that shift technical risk to applicators. This restructuring concentrates margin with chemistry owners and commoditizes installation labor across mature industrial markets.
Global Abrasion Resistant Coatings Market Segmentation
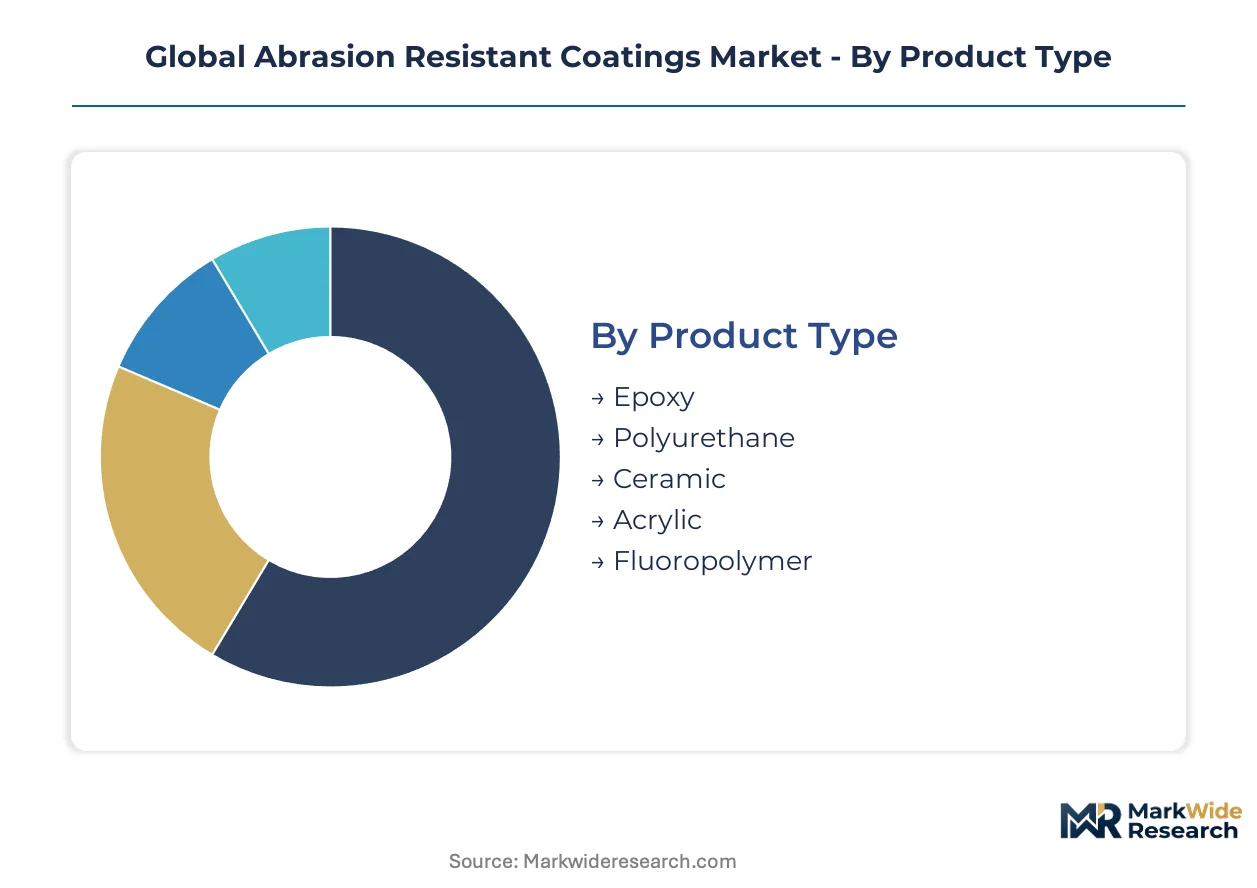
Segmentation in abrasion resistant coatings reveals distinct service intensity patterns. Aftermarket maintenance contracts vary dramatically by formulation chemistry and application method, reshaping how manufacturers capture lifetime value from installed base protection.
Product Type:
Service contract attachment rates diverge sharply across formulation families, with ceramic systems commanding premium field support while commodity epoxies compete on spot purchase economics.
- Epoxy:Bisphenol-A derived thermoset formulations achieve 5H pencil hardness with bond strengths exceeding 20 MPa on prepared steel. Mining operators in Western Australia and Chile specify these systems for dragline and shovel protection, though volatile resin pricing compresses applicator margins on fixed-price maintenance contracts.
- Ceramic:Tungsten carbide and chromium oxide matrix composites deposited via plasma spray achieve hardness values exceeding conventional cermets. Aerospace turbine manufacturers in the US and Germany are adopting these for hot section component repair, displacing thermal barrier coatings that required extended furnace cycles.
- Polyurethane:Elastomeric systems dominate marine hull applications where flexibility and UV resistance offset higher material costs against extended recoating intervals.
- Acrylic:Waterborne formulations serve light manufacturing tool protection where EPA NESHAP compliance drives VOC reduction without thermal spray infrastructure investment.
- Fluoropolymer:PTFE and PVDF based systems protect chemical processing equipment in aggressive pH environments where release properties reduce fouling downtime.
Epoxy holds the largest share; momentum sits with ceramic as deposition efficiency advances.
Application:
Capital equipment replacement cycles determine coating specification intensity, with infrastructure operators extending asset life through protective surface treatments rather than hardware substitution.
- Oil & Gas Equipment:Drill pipe, Christmas trees, and subsea manifolds in the Permian Basin and North Sea require corrosion-erosion resistant systems that defer capital replacement cycles on billion-dollar field developments.
- Mining Machinery:Dragline buckets, haul truck beds, and grinding mill liners in Western Australian iron ore and Chilean copper operations absorb the most severe mechanical abrasion, driving specification toward ultra-hard ceramic overlays.
- Manufacturing Tools:Stamping dies, injection molds, and cutting implements in German and Japanese precision manufacturing clusters demand thin-film coatings that preserve dimensional tolerances.
- Aerospace Components:Turbine blades, combustor liners, and afterburner components require thermal barrier and abradable seal coatings that withstand gas path temperatures exceeding 1000°C.
- Marine Vessels:Ballast tanks, cargo holds, and hull exteriors face combined corrosion and mechanical damage from cargo handling and ice impact in Rotterdam and Singapore shipyards.
Mining machinery absorbs the highest coating consumption per asset; aerospace components are climbing the fastest as MRO outsourcing expands.
Technology:
Application method selection locks in equipment capital requirements, spray booth compliance costs, and skilled labor dependencies that fragment competitive positioning across service tiers.
- Thermal Spray:Plasma and HVOF systems deposit ceramic and cermet coatings with porosity below 2% and bond strengths exceeding 70 MPa. German and Swiss equipment builders concentrate supply, creating procurement bottlenecks for job shops seeking ISO 14917 certification.
- Electrostatic Spray:Automated powder coating lines serve high-volume manufacturing tool protection with transfer efficiency exceeding 95% and near-zero overspray waste.
- Brush Coating:Field maintenance crews apply touch-up repairs on offshore platforms and remote mining sites where spray booth infrastructure is unavailable.
- Dip Coating:Small components including fasteners and valves receive uniform coverage through immersion in fluidized bed or liquid dispersion systems.
- Roll Coating:Continuous steel strip processing lines in automotive and appliance manufacturing apply thin-film pretreatments at line speeds exceeding 100 meters per minute.
Thermal spray commands premium pricing; electrostatic spray is expanding most quickly as automation reduces labor content.
End User Industry:
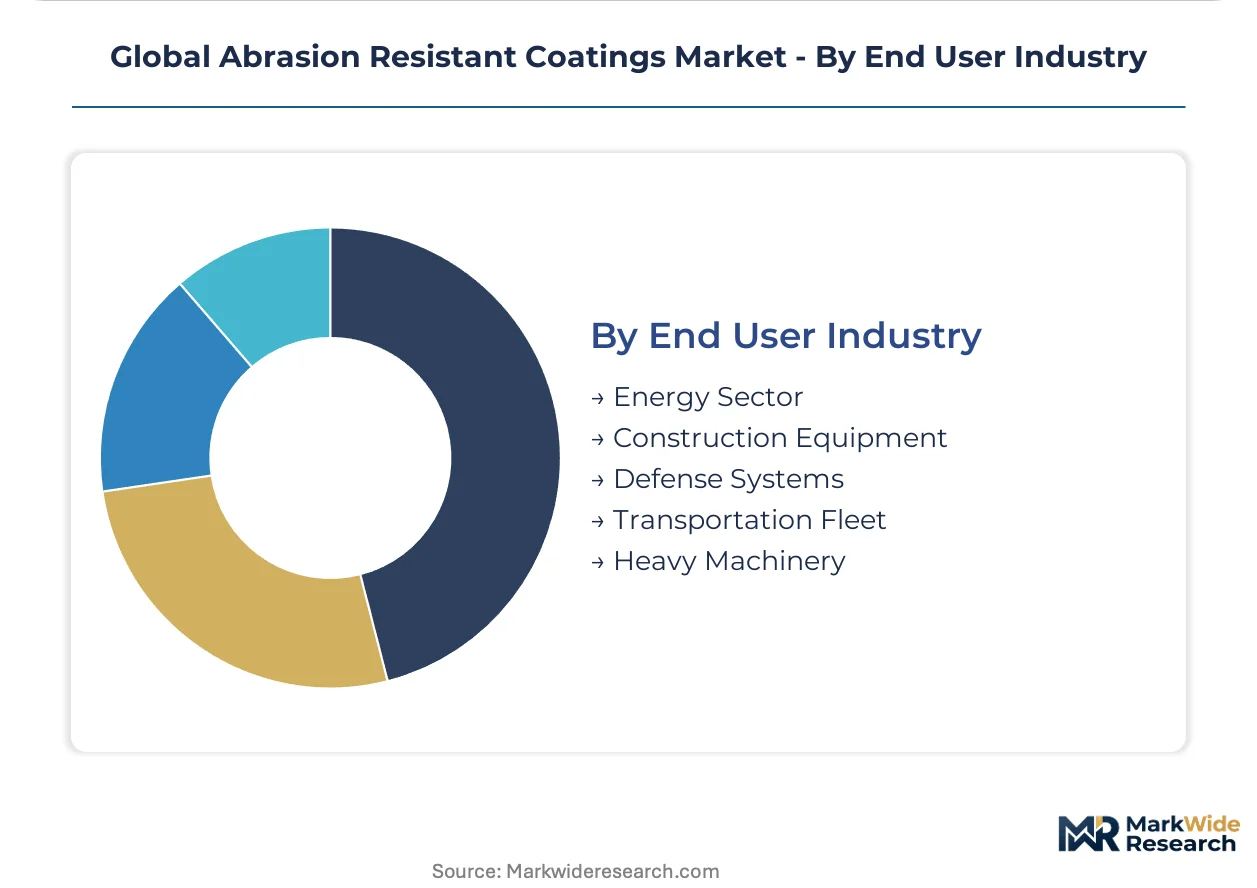
Procurement centralization varies by sector, with state-owned energy enterprises consolidating coating specification while fragmented construction equipment rental fleets defer to OEM factory applications.
- Energy Sector:State-owned oil companies in China and Saudi Arabia specify coating systems for drilling rigs, pipelines, and refining equipment through centralized technical standards that favor pre-qualified suppliers.
- Construction Equipment:Excavator buckets, bulldozer blades, and concrete mixer drums face abrasive soil and aggregate wear, with rental fleet operators increasingly outsourcing protective maintenance to specialized service networks.
- Defense Systems:Armored vehicle hulls, helicopter rotor hubs, and naval propulsion components require ITAR-compliant coating application facilities with restricted foreign access.
- Transportation Fleet:Rail car hopper interiors and truck trailer floors receive high-build epoxy systems that withstand bulk commodity abrasion during loading and unloading cycles.
- Heavy Machinery:Cement kilns, steel rolling mills, and paper machine dryers operate in combined high-temperature and abrasive environments that demand specialized ceramic-metallic formulations.
Energy sector procurement concentrates the largest contract value; heavy machinery is gaining share fastest as industrial infrastructure investment accelerates in India and China.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity fragments across geographies. Chinese state-owned steel mills negotiate on volume; German precision manufacturers prioritize performance certification over unit cost.
United States
Permian Basin drilling contractors specify corrosion-erosion coatings for Christmas trees and subsea manifolds. EPA NESHAP standards mandate capture technology at fabrication shops. Houston-Gulf Coast clusters concentrate thermal spray applicators serving offshore oilfield service companies.
China
State-owned steel and power generation asset owners procure low-VOC formulations under MEE emissions standards. GB compliance requirements reshape local manufacturing costs. Yangtze River Delta industrial zones drive ceramic coating adoption for cement kiln and rolling mill protection.
Germany
Aerospace turbine manufacturers in Munich-Stuttgart corridors specify plasma-deposited ceramic matrices for hot section repairs. REACH registration deadlines accelerate reformulation investment. Ruhr industrial belt maintenance networks specialize in ISO 12944-certified marine and infrastructure applications.
India
Domestic steel and cement capacity expansion creates protective coating procurement at BIS-certified specification tiers. Central Electricity Authority norms govern power plant asset protection standards. Gujarat and Maharashtra industrial corridors attract foreign suppliers establishing compliant distribution.
United Arab Emirates
Adnoc and offshore engineering contractors specify coating systems for sour gas field developments. Emirates Authority for Standardization and Metrology alignment with ISO corrosion protection frameworks governs project specifications. Dubai-Jebel Ali fabrication yards concentrate marine and energy sector application services.
Global Abrasion Resistant Coatings Market Key Industry Players
Capability concentration sits with formulation chemistry owners; scale advantage sits with diversified coatings conglomerates. The market structures around three tiers: global integrated suppliers with cross-sector formulation libraries, regional specialists anchoring marine or oilfield service networks, and application-focused job shops competing on labor rates. Strategic moves center on portfolio diversification into waterborne technologies and captive supply chain control over resin feedstocks.
Within the diversified multinational tier, PPG Industries, Inc. and Akzo Nobel N.V. occupy positions spanning automotive heritage into industrial protective segments. BASF SE exemplifies the chemical-origin archetype with upstream integration into epoxy and polyurethane building blocks. Hempel A/S and Jotun A/S represent marine-specialist positioning through Nordic coastal industrial heritage. These anchors illustrate how geographic origin and corporate structure shape competitive vectors without prescribing specific strategic actions.
| Leading Market Players |
|---|
| RPM International Inc. |
| Hempel A/S |
| PPG Industries, Inc. |
| Axalta Coating Systems Ltd. |
| Jotun A/S |
| Akzo Nobel N.V. |
| BASF SE |
| Nippon Paint Holdings Co., Ltd. |
| The Sherwin-Williams Company |
| Others |
Cost & Logistics Intelligence
The Ruhr industrial belt's thermal spray applicator clusters concentrate ceramic coating capacity for European aerospace and marine maintenance, translating equipment scarcity into premium pricing power for certified job shops serving ISO 12944-compliant infrastructure projects.
Pricing Analysis
Aftermarket service contracts drive lifetime value capture, with three-tier pricing structure across premium ceramic systems, standard epoxy formulations, and economy-grade polyurethane tiers. Price differentiation rests on ISO 14917 certification status and captive resin supply from backward-integrated chemical producers. Cost compression in commodity epoxy segments intensifies because bisphenol-A feedstock volatility squeezes fixed-price maintenance agreements. Mining operators in Western Australia exhibit highest price sensitivity on spot purchases, while German precision manufacturers prioritize certification grade over unit economics.
Supply Chain Analysis
Extended payment terms from German and Swiss thermal spray equipment builders strain job shop working capital, compressing cash conversion cycles for ceramic coating specialists. Supply concentrates in Germany, China, and the United States for plasma deposition systems, epoxy resin precursors, and tungsten carbide powder feedstocks. Raw material dependencies on petrochemical derivatives, rare earth stabilizers, and ceramic matrix precursors create tariff exposure from trade policy shifts. Distribution runs through regional applicator networks that combine formulation supply with certified installation labor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The abrasion resistant coatings market represents early-cycle expansion as thermal spray deposition efficiency advances displace legacy furnace-based thermal barrier systems, accelerating ceramic coating penetration into repair and maintenance workflows.
For Market Incumbents: Insulate formulation margins by deepening captive supply of bisphenol-A and polyurethane building blocks against resin price volatility. Secure ISO 12944 certification pipelines in Rotterdam and Hamburg marine service networks to lock out non-compliant entrants. Anchor position through exclusive service contracts with state-owned energy enterprises in China and Saudi Arabia that consolidate procurement under technical pre-qualification.
For New Entrants and Emerging Players: India's BIS-certified specification tiers offer first-mover advantage as domestic steel and cement capacity expansion outpaces qualified foreign supplier presence. Target Gujarat and Maharashtra industrial corridors with compliant distribution partnerships that satisfy Central Electricity Authority norms. Enter through performance-based coating warranties that shift technical risk to applicators, mirroring Western Australian mining operator procurement restructuring.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors ceramic matrix composite specialists with nano-engineered hardness exceeding conventional tungsten carbide. Long-term viability centers on formulation chemistry owners rather than commoditized installation labor across mature industrial markets. Watch thermal spray equipment utilization rates at German and Swiss builders as inflection signal for deposition efficiency adoption curves.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Epoxy Resins | Captive bisphenol-A supply insulates margins from petrochemical feedstock volatility at PPG and BASF scale. |
| Ceramic Spray Deposition Efficiency Investment | Advanced plasma systems reduce application time and material waste for aerospace turbine hot section repairs. |
| ISO 12944 Certification Pipeline Expansion | Trained inspection personnel scarcity in emerging clusters creates barrier to entry for non-compliant competitors. |
| Waterborne Formulation Portfolio Development | EPA NESHAP and REACH VOC compliance mandates reshape procurement toward low-emission alternatives. |
| Marine Service Network Consolidation | Rotterdam and Hamburg specialized application anchors capture aftermarket revenue from Nordic coastal industrial heritage. |
Research Approach
Cross-validation between primary interviews with plant engineers, OEM procurement teams, aftermarket service heads, and thermal spray applicators anchors the qualitative findings against secondary validation from SEC filings, customs and trade data, ACC and Cefic industry reports, and ISO certification registries. Bottom-up segment sizing triangulates against top-down macroeconomic indicators across the analysis window.
Calibration against historical capacity utilization, raw material price indices, and regulatory implementation timelines shapes the analytical framework. Segmentation dimensions span formulation chemistry, application method, end-use industry, and regional production hub clusters. CAGRs derive from installed base protection intensity, asset life extension demand, and technology substitution curves for ceramic deposition efficiency.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese state-owned chemical producers or accelerated REACH substance restrictions would shift outcomes. Macroeconomic deviation in industrial infrastructure investment, regulatory enforcement divergence across EPA, REACH, and GB standard regimes, or breakthroughs in cold spray deposition technology would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Hydrophilic Interior Glass Defogging Coatings Market
Coatings
Thailand Architectural Coatings Market
Coatings
Flexible Waterproof Coating Market
Coatings
United Kingdom Automotive OEM Coatings Market
Coatings
Topcoat Market
Coatings
Vinyl Surface Coatings Market
Coatings
Epoxy Powder Coatings Market
Coatings
US Protective Coatings Market
Coatings
Anti-Graffiti Coatings Market
Coatings
Perfluoroalkoxy (PFA) Coatings Market
Coatings
Global Nanocoatings Market
Coatings
North America Superhydrophobic Coating Market
Coatings
Antifouling Coatings Market
Coatings
Self-Cleaning Coatings Market
Coatings
Japan Architectural Coatings Market
Coatings
Africa Automotive Refinish Coatings Market