
 Phase Change Thermal Interface Materials Market | 2026-2036
Phase Change Thermal Interface Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Phase Change Thermal Interface Materials Market Analytics
China is reconfiguring supply capacity for phase change thermal interface materials through expanded polymer compounding infrastructure in Guangdong and Jiangsu provinces. Henkel AG & Co KGaA leverages its European formulation expertise to anchor premium segments in automotive power modules. Dow Inc competes through in-house paraffin and polymer science capabilities that sustain cost-advantaged PCM sheet production. Momentive Performance Materials Inc specializes in silicone-based thermal pad architectures for aerospace qualification tiers.
Phase change thermal interface materials are formulated substances that transition between solid and liquid states at engineered temperatures, typically paraffin waxes, salt hydrates, or fatty acid esters blended with thermally conductive fillers to achieve thermal conductivities ranging from 0.5 to 5 W/m·K; they function by filling microscopic air gaps between heat-generating components and dissipating surfaces to minimize thermal contact resistance. Organic PCM formulations dominate volume shipments due to cost scalability and chemical stability across consumer electronics cycles, while micronized PCM technology leads growth trajectories as miniaturized particles enable thinner bond-line control in smartphone and laptop architectures. Hydrogel PCM variants occupy niche margin pools in medical and wearable applications where biocompatibility requirements filter out petroleum-derived alternatives.
REACH registration requirements in Europe constrain raw material sourcing for formulations containing certain crystalline silicas or halogenated compounds, while EPA TSCA Section 5 premanufacture notifications govern new chemical introductions in the United States. China's GB standards for electronic product environmental protection, administered by SAMR, mandate restricted substance thresholds that phase change material suppliers must certify against for domestic market access. Stakeholders should monitor evolving thermal performance benchmarks from IEC standards committees and OEM qualification timelines as substrate geometries shrink below 100-micron tolerances.
Market Dynamics
Data center thermal density thresholds are forcing phase change material suppliers to reformulate for sub-100-micron bond-line tolerances while navigating divergent chemical safety regimes across production and consumption markets.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of high-GWP refrigerants in thermal management systems is redirecting R&D investment toward organic paraffin-based PCM formulations with negligible global warming potential.
- Server rack power densities:Hyperscale facilities deploying 100kW+ liquid-cooled racks require phase change materials that liquefy at 45-60°C to manage transient thermal spikes during AI training workloads.
- Guangdong polymer compounding:Expanded domestic blending capacity in southern China is reducing import dependency for thermally conductive fillers serving local electronics contract manufacturers.
Market Restraints
- Aluminum oxide price volatility:Primary filler costs swing with smelter energy tariffs, compressing gross margins for commodity-grade PCM sheet producers.
- REACH crystalline silica restrictions:ECHA registration requirements block certain traditional reinforcing powders from European formulations, forcing costly substitute qualification.
- Salt hydrate corrosion:Inorganic PCM variants degrade aluminum heat spreaders over 500+ thermal cycles, limiting deployment in automotive underhood applications.
Strategic Opportunities
- India PLI scheme:Production-linked incentives for semiconductor and electronics manufacturing are attracting PCM suppliers to establish local compounding operations ahead of domestic content requirements.
- Wearable biocompatibility:Hydrogel PCM formulations certified to ISO 10993 standards command 3-4x pricing multiples in continuous glucose monitor thermal buffering applications.
- AI-enabled thermal design:Convergence of computational fluid dynamics simulation with generative design is compressing OEM qualification cycles from 18 months to under 9 months for custom PCM geometries.
Industry Challenges
- Thin-film process engineering:Qualified technicians capable of calendering sub-200-micron PCM sheets with ±5% thickness tolerance remain concentrated in Japan and Germany.
- IEC thermal benchmark evolution:Pending standards committee revisions to contact resistance measurement protocols threaten to invalidate existing OEM qualification data.
- Legacy epoxy TIM displacement:Phase change materials must demonstrate total cost-of-ownership equivalence against entrenched silicone grease formulations in retrofit server maintenance contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Phase Change Thermal Interface Materials Market |
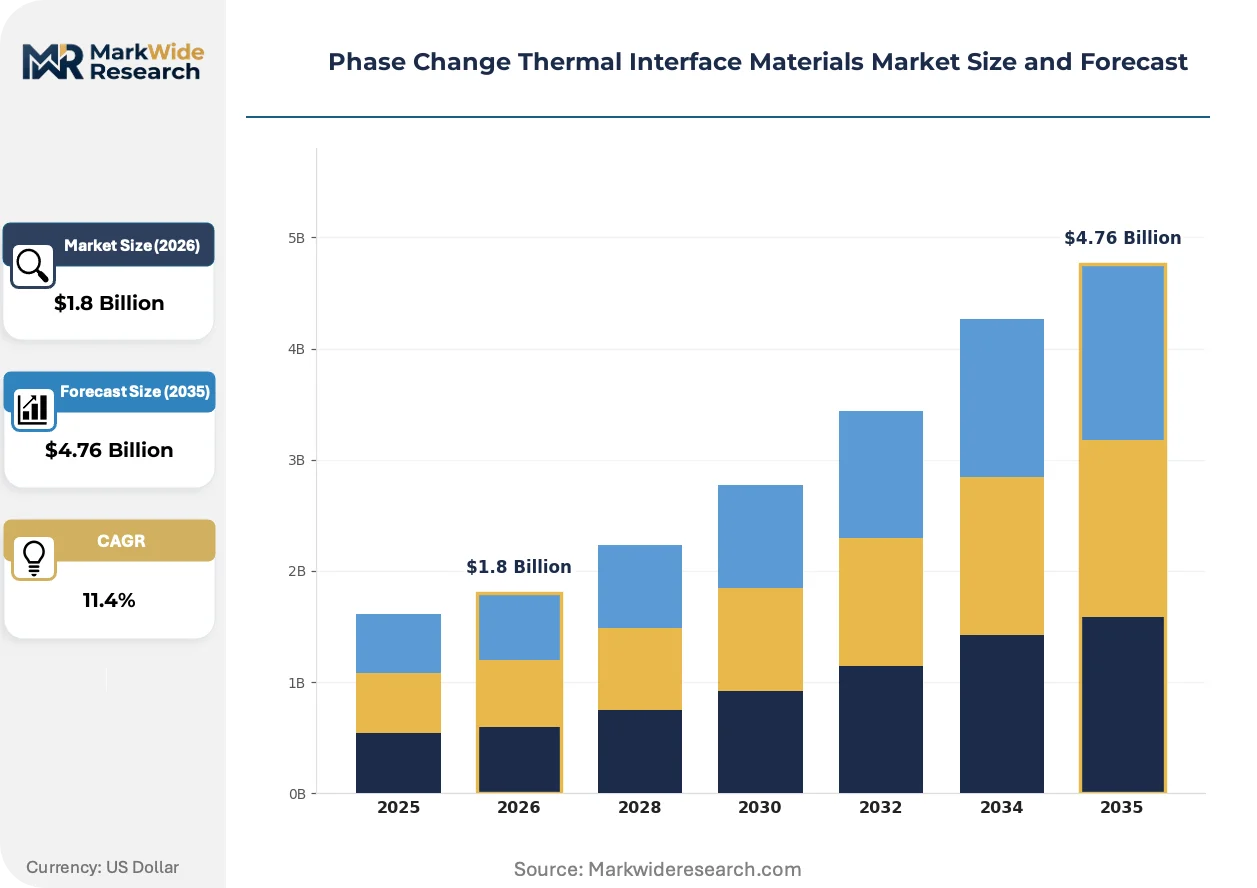
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PCM Sheets, Thermal Pads, Thermal Grease, Thermal Adhesives End User: Electronics, Automotive, Aerospace, Renewable Energy Application: Consumer Electronics, Power Electronics, LED Cooling, HVAC Technology: Micronized PCM, Hydrogel PCM, Organic PCM, Inorganic PCM |
| Companies Covered | Honeywell International Inc, 3M Company, Dow Inc, Henkel AG & Co KGaA, Momentive Performance Materials Inc, Laird Thermal Systems, Aavid Thermalloy LLC, Parker Hannifin Corp, Fujipoly America Corp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Phase Change Thermal Interface Materials Market Evolving Landscape
Micronization and digital integration are compressing form factors while regulatory chemistry constraints and procurement consolidation reshape supplier economics.
Micronized paraffin encapsulation is digitizing thermal interface control by enabling particle-size distributions below 50 microns that fill sub-10-micron surface asperities. Smartphone original equipment manufacturers in South Korea and Taiwan are qualifying these formulations for foldable device hinge thermal management. The technology is digitizing quality assurance through inline laser diffraction monitoring that replaces batch sampling with continuous particle-size verification.
The EU F-Gas Regulation amendment package is accelerating refrigerant-phaseout timelines that indirectly pressure thermal interface material selection in packaged cooling systems. Equipment manufacturers must now document lifecycle GWP contributions including auxiliary materials, prompting PCM suppliers to certify bio-based paraffin feedstocks through mass-balance accounting. Automotive power module producers serving European electric vehicle platforms are responding by dual-sourcing organic and inorganic formulations to hedge regulatory uncertainty.
Consolidated procurement through hyperscale data center operators is compressing supplier margins while demanding application engineering support. Direct contracting between cloud infrastructure divisions and PCM compounders is displacing traditional electronics distributor channels for volume thermal pad agreements. This concentration is most visible in northern Virginia and Frankfurt data center clusters where three operators account for majority phase change material procurement.
Phase Change Thermal Interface Materials Market Segmentation
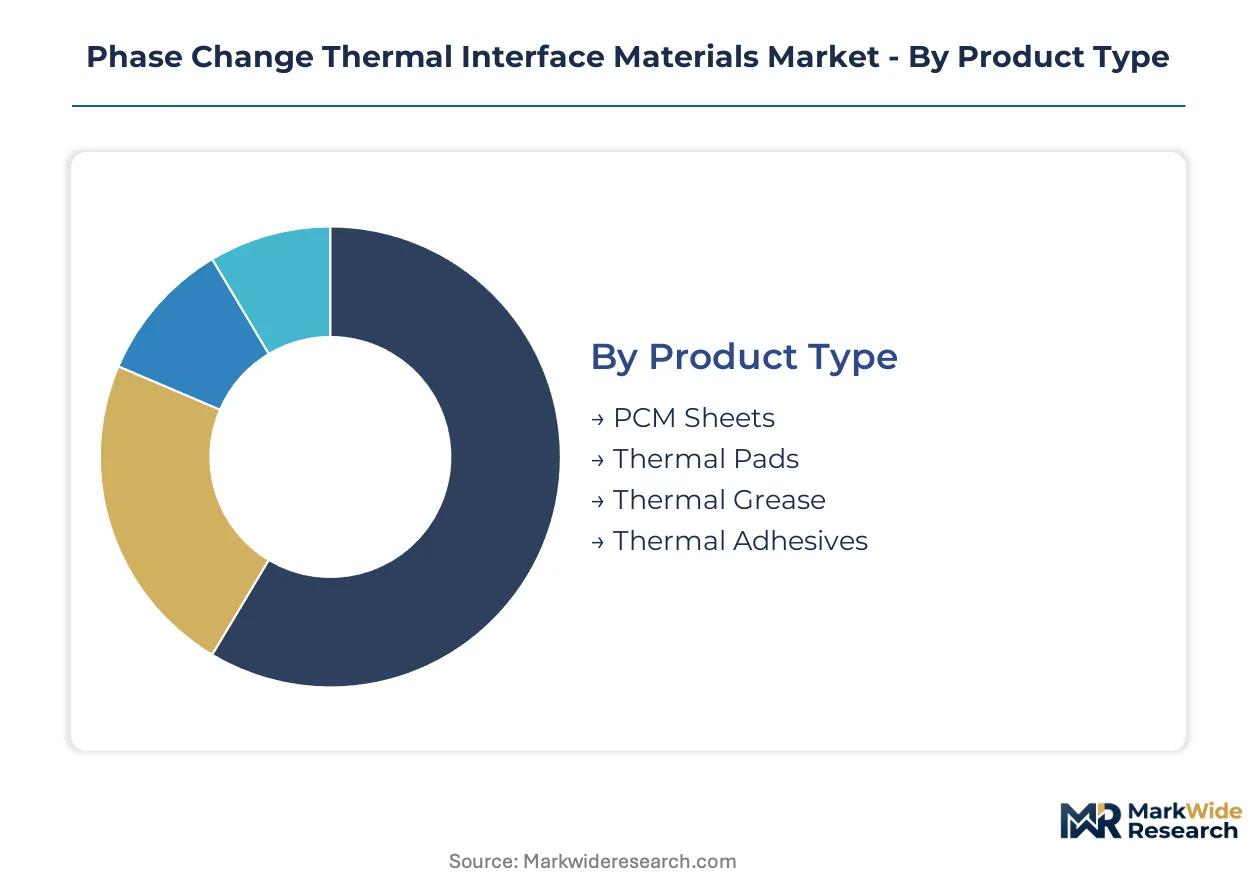
Phase change thermal interface materials serve divergent thermal management requirements across bond-line thicknesses, operating temperature ranges, and regulatory compliance tiers. Product configuration directly determines after-sales service intensity, with field-applied formulations demanding technical support networks that pre-cured sheets do not require.
Product Type:
After-sales service intensity varies sharply across product formats, with field-dispensed materials requiring application engineering support that factory-laminated sheets eliminate entirely.
- PCM Sheets:Pre-cured paraffin-polymer composites laminated to aluminum or polyimide carriers achieve bond-line thicknesses of 100-250 microns with ±10% uniformity. Data center operators in northern Virginia and Frankfurt clusters specify these formats for server CPU thermal interfaces to minimize installation variability. Factory-controlled curing eliminates field mixing errors but restricts conformability to complex geometries.
- Thermal Pads:Solid silicone or acrylic matrices loaded with boron nitride or aluminum oxide fillers maintain dimensional stability across -40°C to 150°C operational windows. Automotive power module manufacturers in Germany and South Korea favor these for IGBT thermal management where vibration resistance exceeds phase change wetting requirements. The segment carries lower technical support burdens due to straightforward compression-set installation protocols.
- Thermal Grease:Silicone or hydrocarbon carriers suspended with metallic oxide powders enable sub-50-micron bond-lines through screen or stencil dispensing.
- Thermal Adhesives:Reactive epoxy or acrylic formulations combining thermal conductivity with structural bonding eliminate mechanical clamping hardware.
By volume, PCM Sheets lead procurement in hyperscale data center contracts. By growth pace, Thermal Adhesives are ahead as electric vehicle power density requirements displace mechanical fasteners.
End User:
Cost tier stratification separates premium qualification pathways in aerospace from high-volume electronics procurement where per-unit material costs dominate supplier selection.
- Electronics:Smartphone original equipment manufacturers and laptop contract manufacturers in Taiwan and South Korea drive micronized PCM adoption for sub-100-micron hinge and chassis thermal interfaces. Foldable device architectures concentrate demand for materials maintaining performance across 200,000+ flex cycles. Consumer electronics procurement emphasizes unit economics over technical service intensity.
- Automotive:Electric vehicle battery pack and inverter thermal management specifications from European and Chinese original equipment manufacturers demand automotive-grade qualification data spanning 10-year service life projections. Underhood temperature extremes exceeding 125°C constrain organic PCM selection toward high-paraffin formulations with elevated phase-change temperatures. Supplier margins compress against silicone grease legacy formulations in retrofit maintenance channels.
- Aerospace:Satellite and avionics thermal control applications require outgassing certification per ASTM E595 and flame resistance per FAR 25.853.
- Renewable Energy:Photovoltaic inverter and wind turbine power converter thermal interfaces prioritize 20-year service life predictions.
Electronics commands the largest procurement volumes. Automotive exhibits the steepest expansion trajectory as electrification multiplies thermal interface count per vehicle platform.
Application:
Customer type concentration separates original equipment manufacturer specification control from aftermarket replacement demand where compatibility databases determine material selection.
- Consumer Electronics:Gaming laptop and smartphone original equipment manufacturers in China, Taiwan, and South Korea specify phase change materials for CPU and GPU thermal interfaces where aesthetic thinness constraints override absolute thermal performance. Gaming device thermal design power thresholds exceeding 150W concentrate demand for materials with 45-60°C phase transition windows that activate under sustained computational load.
- Power Electronics:Silicon carbide and gallium nitride device packaging for electric vehicle traction inverters and renewable energy converters requires thermal interface materials surviving 175°C junction temperatures. Module manufacturers in Germany and Japan qualify materials against IEC 60747 thermal cycling protocols. Technical support intensity peaks here as device thermal resistance directly impacts semiconductor reliability predictions.
- LED Cooling:High-brightness automotive headlamp and stadium lighting applications demand thermal interface materials with optical compatibility and UV resistance.
- HVAC:Packaged cooling system manufacturers specify phase change materials for heat exchanger interfaces where EU F-Gas Regulation lifecycle accounting now includes auxiliary material global warming potential contributions.
Power Electronics leads by revenue concentration. Consumer Electronics expands most quickly as foldable device form factors multiply thermal interface count per unit.
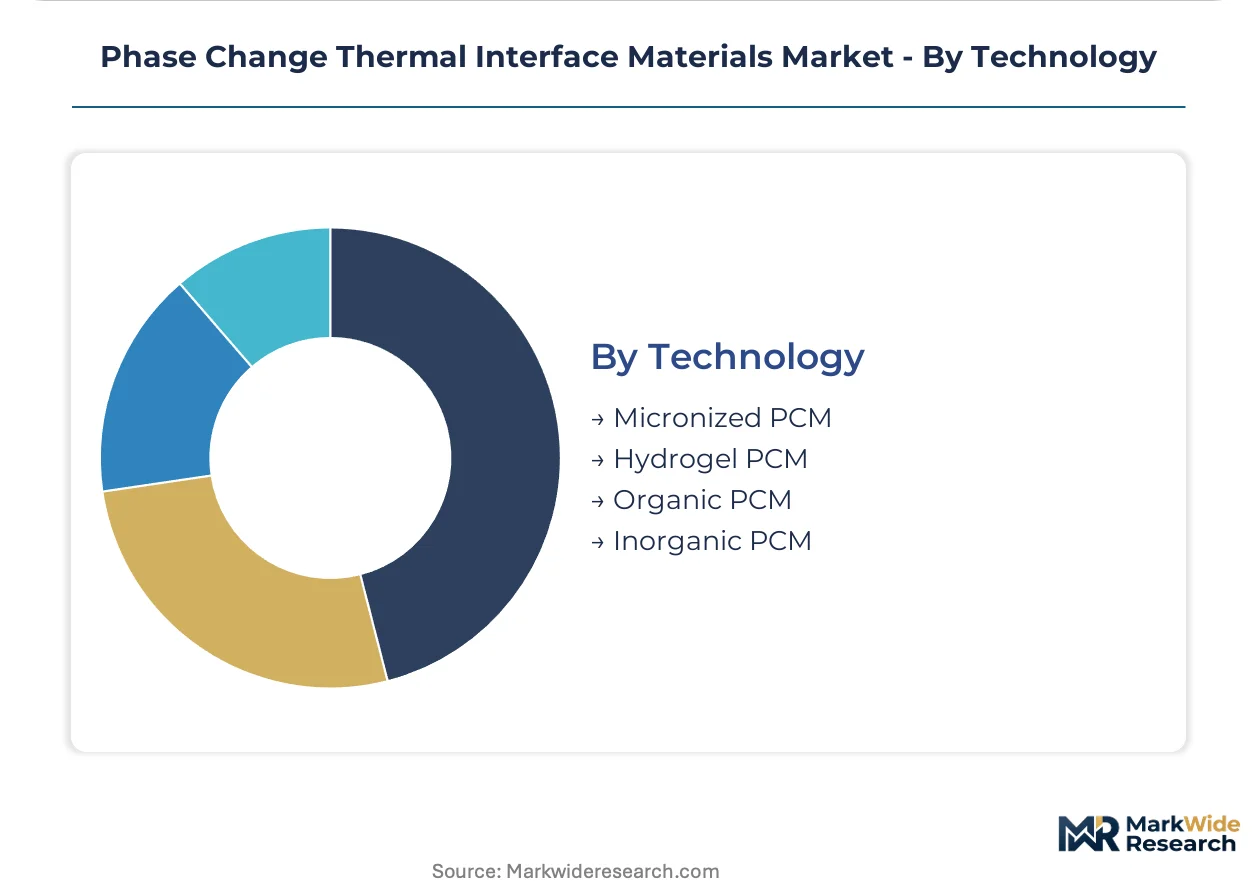
Technology:
Supply concentration for specialized raw materials—encapsulated paraffin microspheres, medical-grade hydrogel precursors—shapes competitive access across technology categories.
- Micronized PCM:Paraffin or salt hydrate cores encapsulated within polymer shells achieve particle sizes below 50 microns, enabling spray or inkjet deposition onto non-planar substrates. South Korean and Taiwanese smartphone manufacturers qualify these formulations for foldable hinge thermal management where conventional sheet formats fail. Inline laser diffraction quality systems replace batch sampling with continuous particle-size verification.
- Organic PCM:Paraffin waxes, fatty acid esters, and polyethylene glycols blended with thermally conductive fillers dominate volume shipments through cost scalability and chemical stability across consumer electronics replacement cycles. Guangdong and Jiangsu polymer compounding infrastructure expansion reduces import dependency for thermally conductive filler supply. The technology benefits from established feedstock supply chains and REACH-compliant formulation pathways.
- Hydrogel PCM:Cross-linked polyacrylamide or polysaccharide matrices with tunable water content achieve biocompatibility certification per ISO 10993 for wearable medical device applications.
- Inorganic PCM:Salt hydrates and metallic alloys deliver elevated thermal conductivity and phase-change enthalpy but introduce corrosion risks against aluminum heat spreaders.
Organic PCM leads procurement volumes across electronics and automotive applications. Micronized PCM gains share fastest as miniaturization requirements penetrate aerospace and medical device qualification tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's SAMR enforces GB standards that dictate restricted substance thresholds for domestic electronics production, anchoring regulatory gravity in the world's largest phase change material consumption zone. Data center buildouts in northern Virginia and Frankfurt cluster procurement decisions for hyperscale operators. Automotive electrification in Germany and battery manufacturing scale-up in South Korea concentrate qualification-intensive demand.
China
Guangdong and Jiangsu provinces are expanding polymer compounding infrastructure to reduce import dependency for thermally conductive fillers serving local contract manufacturers. SAMR-administered GB standards mandate restricted substance thresholds that suppliers must certify against for domestic market access. Shenzhen and Dongguan electronics clusters are qualifying micronized PCM formulations for foldable smartphone hinge thermal management.
United States
Hyperscale data center operators in northern Virginia are consolidating procurement through direct contracts with compounders, displacing traditional distributor channels for volume thermal pad agreements. EPA TSCA Section 5 premanufacture notifications govern new chemical introductions for phase change formulations. The Pacific Northwest semiconductor fabrication corridor is driving demand for sub-100-micron bond-line materials.
Germany
Automotive power module manufacturers are dual-sourcing organic and inorganic formulations to hedge EU F-Gas Regulation uncertainty on lifecycle GWP accounting. ECHA REACH registration requirements block certain crystalline silica reinforcing powders from European formulations, forcing costly substitute qualification. Baden-Württemberg and Bavaria host IGBT thermal management qualification centers serving European electric vehicle platforms.
South Korea
Smartphone original equipment manufacturers are qualifying micronized PCM formulations for foldable device architectures requiring 200,000+ flex cycle durability. The national standards body administers KATS certification aligned with IEC thermal performance benchmarks. Seoul and Suwon electronics corridors concentrate spray-deposition process engineering for sub-50-micron particle-size distributions.
India
Production-linked incentive schemes for semiconductor and electronics manufacturing are attracting phase change material suppliers to establish local compounding operations ahead of domestic content requirements. BIS certification mandates compliance with electronic product environmental protection standards. Karnataka and Tamil Nadu are emerging as contract manufacturing hubs where import substitution policies favor localized thermal interface material sourcing.
Phase Change Thermal Interface Materials Market Competitive Landscape
Capability concentration sits with European formulation specialists; scale advantage sits with integrated chemical conglomerates possessing captive paraffin supply. The vendor base stratifies across three tiers: diversified materials science conglomerates with in-house polymer capabilities, mid-size thermal management specialists focused on application engineering, and regional compounders serving geographically concentrated electronics manufacturing. Strategic moves center on backward integration into thermally conductive filler production and qualification data accumulation for automotive-grade longevity predictions.
Within the diversified conglomerate tier, Honeywell International Inc and 3M Company exemplify scale-driven positioning through materials science breadth and established qualification pathways with aerospace and defense contractors. Dow Inc and Henkel AG & Co KGaA occupy differentiated positions anchored in polymer formulation heritage and adhesive chemistry expertise respectively. Momentive Performance Materials Inc represents the specialist archetype, with silicone-based thermal pad architectures concentrated in qualification-intensive aerospace and industrial segments. These named entities collectively illustrate competitive positioning across capability depth versus manufacturing scale trade-offs.
| Leading Market Players |
|---|
| Honeywell International Inc |
| 3M Company |
| Dow Inc |
| Henkel AG & Co KGaA |
| Momentive Performance Materials Inc |
| Laird Thermal Systems |
| Aavid Thermalloy LLC |
| Parker Hannifin Corp |
| Fujipoly America Corp |
| Others |
Value Network & Pricing Analysis
Guangdong province's expanded polymer compounding infrastructure is compressing regional cost differentials while hyperscale data center procurement consolidation in northern Virginia and Frankfurt transfers pricing power downstream to volume buyers. Paraffin feedstock volatility and REACH-compliant formulation premiums create divergent margin structures across geographic supply bases.
Pricing Analysis
Price spreads between European REACH-certified formulations and Asian commodity-grade sheets run 40-60% depending on filler loading and phase-change temperature precision. Three-tier pricing structure across automotive-grade qualification, data center volume contracts, and consumer electronics spot procurement reflects certification investment recovery timelines. Cost compression in standard-grade PCM sheets is intensifying because Guangdong compounding capacity expansion feeds oversupply into Asian electronics contract manufacturing. Automotive power module buyers exhibit lowest price sensitivity due to decade-long reliability requirements and dual-sourcing qualification costs.
Supply Chain Analysis
Extended payment terms from hyperscale data center operators now stretch to 90-120 days, forcing compounders to access supply-chain finance facilities anchored by receivables from northern Virginia and Frankfurt procurement clusters. Manufacturing concentrates in China, Germany, and South Korea, with each hub serving distinct qualification tiers. Formulations draw from captive paraffin supply, boron nitride from Chinese ceramic processors, and aluminum oxide from smelter-linked distributors. Single-source vulnerability sits with sub-50-micron encapsulated paraffin microspheres where South Korean spray-deposition specialists dominate. Distribution runs through direct compounder-OEM contracts for volume thermal pads, with specialty distributors retaining medical and aerospace qualification pathways.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power has concentrated through hyperscale data center procurement consolidation, with three operators now controlling majority phase change material contracting in primary server clusters. This procurement density rewards suppliers with qualification data depth and punishes fragmented compounders lacking application engineering scale.
For Market Incumbents: Pre-empt margin erosion in standard-grade PCM sheets by anchoring backward integration into thermally conductive filler production in Guangdong or Jiangsu provinces. Accumulate automotive-grade IEC 60747 thermal cycling qualification data ahead of electric vehicle platform standardization. Defensive patent positioning around micronized encapsulation architectures blocks emerging entrants from foldable device hinge specifications. For New Entrants and Emerging Players: Pursue hydrogel PCM certification for ISO 10993-compliant wearable medical devices where biocompatibility requirements filter out petroleum-derived incumbents. India's PLI scheme for semiconductor manufacturing offers the most penetrable geographic entry point ahead of domestic content mandates. Lead with application engineering partnerships rather than price undercutting in qualification-intensive segments. For Investors and Strategic Acquirers: Long-term, this sits as a specialty-chemical-consolidation play because automotive electrification multiplies thermal interface count per vehicle while procurement concentration squeezes sub-scale compounders. Target mid-size European formulation specialists with captive REACH-compliant pathways and existing IGBT thermal management qualification data. Monitor EU F-Gas Regulation amendment timelines as inflection indicators for bio-based paraffin feedstock premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Filler Production | Captive boron nitride supply from Guangdong ceramic processors insulates margin against aluminum oxide volatility. |
| Automotive-Grade Qualification Investment | IEC 60747 thermal cycling data accumulation secures 10-year service life specifications from German EV platforms. |
| Biocompatibility Certification Pathway | ISO 10993 hydrogel PCM qualification opens 3-4x pricing multiples in continuous glucose monitor thermal buffering. |
| Direct Hyperscale Contracting | Eliminating distributor layers in northern Virginia and Frankfurt clusters captures procurement consolidation value. |
| Micronized Encapsulation Patent Positioning | Sub-50-micron particle-size distribution IP blocks competitor access to foldable smartphone hinge specifications. |
Research Methodology
Desk research of customs trade filings, SEC 10-K thermal management disclosures, and IEC standards committee documentation preceded structured interviews with data center procurement directors, automotive power module thermal engineers, polymer compounding plant managers, and electronics contract manufacturing sourcing leads. Primary intelligence on qualification timelines and reformulation costs was cross-validated against secondary trade flow analysis and bottom-up capacity assessments from Guangdong and Jiangsu province industrial registries. Top-down market sizing triangulated against OEM thermal interface spend disclosures.
Forecast assumptions held fixed the EU F-Gas Regulation amendment trajectory and hyperscale data center power density evolution while varying electric vehicle platform thermal interface count and foldable device penetration scenarios across the analysis window. Segmentation modeling incorporated product format, end-use industry, application thermal load, phase-change temperature tier, and regional regulatory cluster. CAGRs were derived from installed base thermal interface replacement cycles and new platform adoption curves, with semiconductor junction temperature roadmaps and AI training workload thermal profiles as demand-side inputs.
Macroeconomic conditions sit as an overlay; deviation in aluminum oxide energy input costs or EU carbon border adjustment implementation would shift the trajectory for European formulation competitiveness. Forecasts reflect documented assumptions on regulatory chemistry constraints and procurement consolidation velocity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insulation Materials
Asia-Pacific Tank Insulation Market
Insulation Materials
Global High Temperature Insulation Materials Market
Insulation Materials
Fireproofing Materials Market
Insulation Materials
Cold-Air Diffusion Market
Insulation Materials
Reflective Thermal Insulation Coatings Market
Insulation Materials
Global Fire Protection Materials Market
Insulation Materials
Active Insulation Market
Insulation Materials
Dielectric Materials Market
Insulation Materials
Global Tank Insulation Market
Insulation Materials
Fire Protective Materials Market
Insulation Materials
Technical Foam Market
Insulation Materials
Europe Phase Change Material Market
Insulation Materials
Wire Insulation and Jacketing Compounds Market
Insulation Materials
Beryllium Oxide Market
Insulation Materials
Japan Industrial Insulation Market
Insulation Materials
Thin Insulation Market