
 Global Mirror Coatings Market | 2026-2036
Global Mirror Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Global Mirror Coatings Market Foresight
REACH compliance is expanding the cost-of-entry calculus for mirror coating producers serving European architectural and automotive channels. Sherwin-Williams Company leverages its integrated coatings portfolio to navigate multi-jurisdictional chemical safety mandates. FENZI S.p.A. sustains leadership in silver-based formulations through captive supply relationships with flat glass processors. Arkema differentiates via fluoropolymer additives that reduce volatile organic compound emissions during mirror manufacturing.
Mirror coatings constitute thin-film metallic or dielectric layers deposited onto glass or polymer substrates to achieve specified reflectance values, typically exceeding 90% for visible wavelengths in architectural applications. Physical vapor deposition and sputtering dominate precision optical manufacturing due to sub-nanometer thickness control, while electroplating retains cost advantages in decorative mirror production. Silver mirror coatings anchor the value pool in solar energy applications where spectral selectivity determines thermal conversion efficiency. Aluminum mirror coatings lead automotive rearview segments owing to durability under thermal cycling and humidity exposure.
FDA oversight governs mirror coatings in medical optical instruments through biocompatibility and sterility standards, while EPA regulations constrain solvent-based coating processes in the United States. ECHA enforces REACH substance restrictions across European coating supply chains, directly limiting chromium and cadmium compound formulations. China's MEE implements dual carbon goals that pressure domestic coating plants to transition from thermal spray to lower-emission deposition technologies. Stakeholders must monitor evolving substance restriction lists and carbon border adjustment mechanisms to anticipate reformulation investments and regional sourcing shifts.
Market Dynamics
REACH substance restrictions and China's dual carbon goals are forcing simultaneous reformulation of silver-based mirror coatings and retooling of deposition equipment across European and Chinese manufacturing plants.
Growth Catalysts
- Concentrated solar power expansion:Solar energy developers in the United States and China are specifying high-reflectance silver coatings for thermal conversion efficiency. Procurement volumes from concentrated solar power installations are accelerating.
- REACH compliance differentiation:ECHA substance restrictions on chromium and cadmium compounds are creating competitive separation for coating producers with pre-certified low-heavy-metal formulations. Early compliance investments are capturing architectural specification wins.
- Physical vapor deposition advancement:Sub-nanometer thickness control in sputtering equipment is enabling precision optical manufacturers to achieve tighter reflectance tolerances. Medical instrument and laser system producers are qualifying these coatings for next-generation devices.
Market Restraints
- Silver price volatility:Fluctuations in precious metals markets directly compress margins for silver mirror coating producers serving solar and architectural segments. Hedging costs add operational complexity.
- Supply concentration in flat glass:Captive supply relationships between major glass processors and coating specialists limit independent coating producers' access to substrate supply in Germany and China.
- Fluoropolymer additive dependency:Arkema and limited alternative suppliers control low-VOC fluoropolymer formulations, creating input cost pressure for coating producers seeking EPA compliance in United States manufacturing.
Strategic Opportunities
- India precision optical underpenetration:Domestic manufacturing of medical and defense optical instruments in India remains dependent on imported coated substrates. Local coating capacity investment could capture BIS-certified supply contracts.
- EU carbon border adjustment positioning:The EU Green Deal's carbon border adjustment mechanism creates first-mover advantage for coating producers with verified low-emission deposition processes. Early certification investments will secure European architectural specification.
- Polymer substrate convergence:Dielectric coating compatibility with lightweight polymer substrates is converging with automotive weight reduction mandates. Rearview mirror and interior trim applications are expanding beyond traditional glass.
Industry Challenges
- Vacuum deposition technician scarcity:Physical vapor deposition and sputtering operations require specialized thin-film technicians with sub-nanometer process control expertise. Training pipelines lag equipment deployment timelines.
- Multi-jurisdictional certification complexity:Coating producers serving medical, automotive, and solar segments simultaneously must maintain FDA biocompatibility, NHTSA durability, and IEC solar standards. Audit cycles consume management bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Mirror Coatings Market |
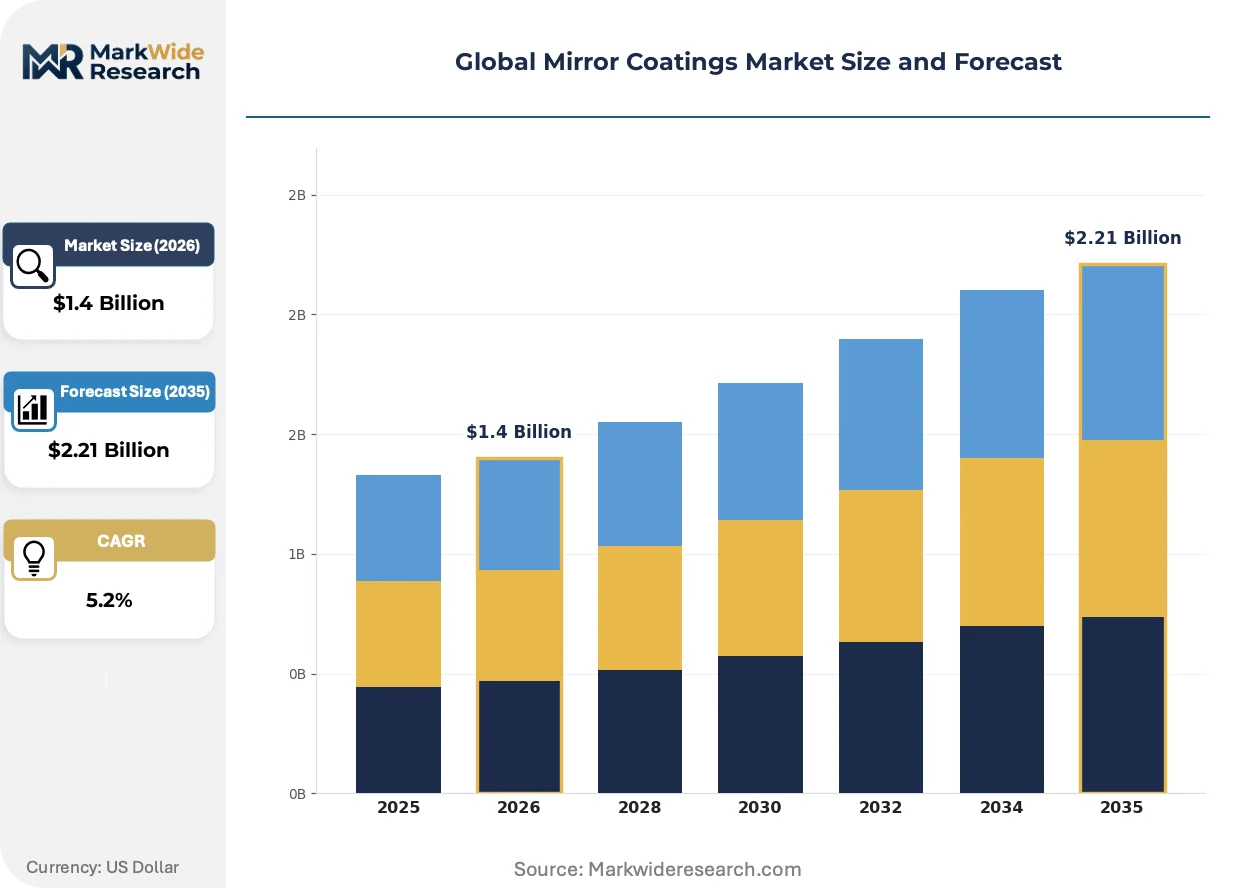
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.21 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Silver Mirror Coatings, Aluminum Mirror Coatings, Chromium Mirror Coatings, Gold Mirror Coatings, Copper Mirror Coatings Application: Architectural Glass, Automotive Rearview, Solar Panels, Optical Instruments, Decorative Mirrors Technology: Physical Vapor Deposition, Chemical Vapor Deposition, Electroplating, Sputtering, Thermal Spray End User: Architects, Automotive Suppliers, Solar Energy Firms, Optical Manufacturers, Interior Designers |
| Companies Covered | Sherwin-Williams Company, FENZI S.p.A., Arkema, JENOPTIK AG, AccuCoat Inc., CASIX, Inc., North America Coating Laboratories, Dynasil Corporation, Abrisa Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Mirror Coatings Market Shifts & Advancements
Deposition technology hybridization and regulatory chemistry constraints are compressing traditional process boundaries while opening specification opportunities for coating producers with advanced formulation capabilities.
Atomic layer deposition is converging with traditional sputtering in precision optical manufacturing to achieve angstrom-level thickness uniformity for laser mirror applications. Semiconductor equipment producers and scientific instrument manufacturers are piloting hybrid deposition lines. This convergence is enabling sub-wavelength surface roughness specifications that electroplating cannot achieve.
ECHA enforcement of REACH Annex XVII restrictions on chromium trioxide in mirror coatings is forcing European architectural producers to qualify alternative corrosion inhibitors. The industrial consequence is extended qualification timelines for new formulations with flat glass processors. Germany's flat glass coating plants are responding with captive testing facilities to compress certification cycles.
Buyer consolidation among concentrated solar power developers is compressing coating procurement from fragmented regional suppliers toward integrated mirror system providers. Tier-one solar EPCs in the United States and China are specifying complete heliostat assemblies rather than coated glass substrates. This disintermediation is visible most acutely in Nevada and Xinjiang solar manufacturing clusters.
Global Mirror Coatings Market Segmentation
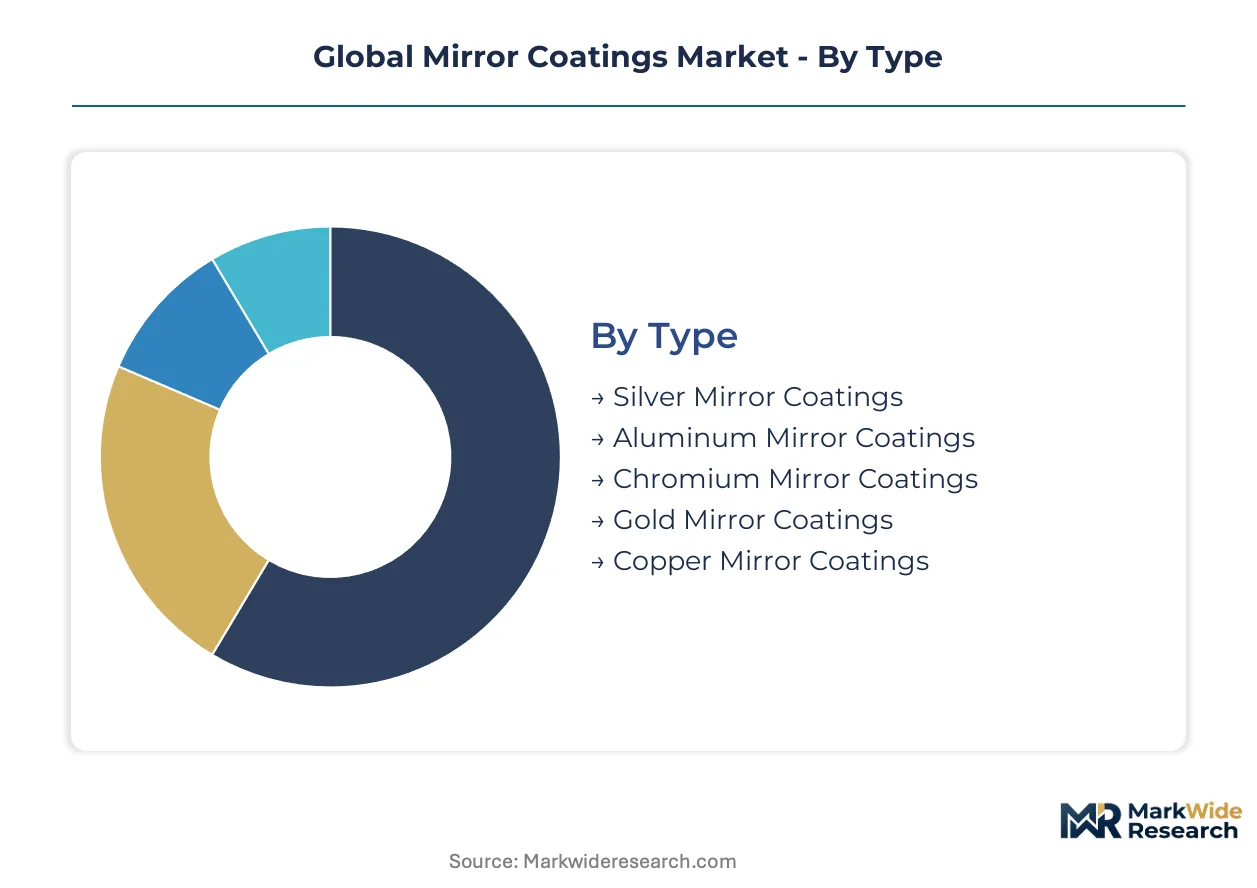
Mirror coatings demand fragments across metallic chemistries, deposition methods, and end-use specifications that each carry distinct margin profiles and regulatory exposure. Understanding these splits reveals where capital is concentrating and which technology transitions will reshape competitive positioning.
Type:
Silver formulations command premium pricing in high-reflectance applications while aluminum coatings anchor volume production in cost-sensitive automotive and architectural channels.
- Silver Mirror Coatings:These formulations deliver reflectance exceeding 95% across visible and infrared spectra through thin-film silver layers protected by dielectric overcoats. Concentrated solar power developers in the United States and China specify silver coatings for thermal conversion efficiency, though ECHA REACH substance restrictions on heavy metal content are forcing reformulation investments across European supply chains.
- Aluminum Mirror Coatings:Vacuum-deposited aluminum layers provide durable reflectance above 90% with superior thermal cycling resistance. Automotive rearview mirror producers in Germany and China favor aluminum for humidity tolerance, while architectural glass processors specify aluminum for cost-competitive facade applications where spectral selectivity requirements are less stringent.
- Chromium Mirror Coatings:Chromium layers offer hardness and abrasion resistance for industrial optical applications requiring mechanical durability.
- Gold Mirror Coatings:Gold formulations serve infrared laser systems and scientific instruments where oxidation resistance at elevated temperatures is critical.
- Copper Mirror Coatings:Copper layers function primarily as conductive underlayers in multi-stack dielectric mirror architectures.
Today's leader: Silver Mirror Coatings. Tomorrow's challenger: Aluminum Mirror Coatings.
Application:
Architectural glass and automotive rearview segments consume the majority of coating volume, while solar panel and precision optical applications drive technology advancement and margin expansion.
- Architectural Glass:Curtain wall and interior mirror applications demand consistent reflectance across large substrate areas with corrosion resistance for exterior exposure. Flat glass processors in Germany and China maintain captive coating operations to control specification compliance, while independent coating specialists compete on REACH-certified low-heavy-metal formulations for European commercial building projects.
- Solar Panels:Concentrated solar power installations require spectrally selective coatings that maximize solar flux reflection while minimizing thermal emittance. Solar energy firms in Nevada and Xinjiang are consolidating procurement toward integrated heliostat system providers, compressing margins for standalone coating producers.
- Automotive Rearview:Exterior mirror coatings must withstand thermal cycling, humidity exposure, and stone chip impact per NHTSA durability standards.
- Optical Instruments:Medical and scientific instruments demand sub-nanometer thickness control achievable only through physical vapor deposition.
- Decorative Mirrors:Furniture and interior design applications prioritize cost efficiency over spectral precision, favoring electroplating over vacuum deposition.
Architectural Glass currently dominates procurement volumes. Solar Panels are climbing the fastest as concentrated solar power capacity expands.
Technology:
Deposition method selection hinges on thickness precision requirements, substrate compatibility, and capital equipment availability rather than raw material costs alone.
- Physical Vapor Deposition:Thermal evaporation and electron-beam deposition achieve sub-nanometer thickness control for precision optical and laser mirror manufacturing. Medical instrument producers in the United States and Germany qualify PVD-coated substrates for FDA and CE-marked devices, while semiconductor equipment manufacturers specify PVD for EUV optical systems requiring atomic-scale surface roughness.
- Sputtering:Magnetron sputtering deposits dense, adherent films with excellent uniformity across large-area architectural glass. China's MEE dual carbon goals are pressuring domestic sputtering operations to transition from thermal spray toward lower-emission deposition configurations.
- Chemical Vapor Deposition:CVD enables conformal coating of complex geometries for specialized optical components.
- Electroplating:Wet chemical deposition retains cost advantages for decorative mirror production where thickness tolerance is measured in micrometers rather than nanometers.
- Thermal Spray:Flame and plasma spray techniques serve industrial mirror refurbishment with limited precision requirements.
Physical Vapor Deposition holds technology leadership. Sputtering is expanding most quickly in architectural and solar applications.
End User:
Customer type determines specification complexity, certification burden, and procurement consolidation patterns across the mirror coatings value chain.
- Solar Energy Firms:Concentrated solar power developers specify complete mirror systems rather than coated substrates, driving vertical integration among tier-one EPCs. Procurement consolidation in Nevada and Xinjiang manufacturing clusters favors coating producers with captive glass supply and in-house heliostat assembly capabilities.
- Optical Manufacturers:Medical and scientific instrument producers demand FDA biocompatibility and IEC laser safety certifications alongside sub-nanometer thickness tolerances. Multi-jurisdictional audit requirements consume supplier management bandwidth and favor coating specialists with dedicated quality systems.
- Automotive Suppliers:Tier-one mirror system integrators specify aluminum coatings with NHTSA-validated durability under thermal cycling and humidity exposure.
- Architects:Commercial building designers specify REACH-compliant coatings with verified low-heavy-metal content for European projects.
- Interior Designers:Residential and hospitality furniture producers prioritize cost and aesthetic consistency over spectral performance.
Solar Energy Firms currently concentrate procurement volume. Optical Manufacturers represent the steepest expansion trajectory as medical device and scientific instrument production scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thin-film technician pipelines in Germany, China, and the United States anchor the geographic distribution of precision coating capacity. These workforce concentrations determine where sub-nanometer process control expertise clusters and where deposition equipment investment flows.
Germany
Automotive rearview mirror producers in Baden-Württemberg and Bavaria drive aluminum coating demand for NHTSA-equivalent durability standards. KBA vehicle safety regulations intersect with ECHA REACH substance restrictions, forcing reformulation of chromium-containing corrosion inhibitors. Stuttgart's flat glass coating plants operate captive testing facilities to compress certification cycles for architectural specification.
China
Concentrated solar power developers in Xinjiang and Ningxia scale procurement of high-reflectance silver coatings for thermal conversion efficiency. MEE dual carbon goals pressure domestic sputtering operations to transition from thermal spray toward lower-emission deposition configurations. Yangtze River Delta coating plants consolidate heliostat assembly capabilities to serve tier-one solar EPCs.
United States
Medical instrument producers in Greater Boston and the Research Triangle demand FDA biocompatibility certification for PVD-coated substrates. EPA regulations constrain solvent-based coating processes, favoring fluoropolymer additive formulations. Nevada solar manufacturing clusters witness procurement consolidation toward integrated mirror system providers.
India
Domestic manufacturing of medical and defense optical instruments in Karnataka and Telangana remains dependent on imported coated substrates. BIS certification requirements create entry barriers for foreign coating specialists. Pune and Bengaluru precision optical clusters present local capacity investment opportunities for BIS-certified supply contracts.
Japan
Semiconductor equipment manufacturers in Kanto and Chubu specify EUV optical systems requiring atomic-scale surface roughness. METI industrial policy supports atomic layer deposition hybridization with traditional sputtering. Nagoya-area coating specialists pilot hybrid deposition lines for laser mirror applications.
Global Mirror Coatings Market Competitive Landscape
The competitive structure tilts toward integrated coatings portfolios with multi-jurisdictional chemical safety capabilities. Market position depends on captive supply relationships with flat glass processors and pre-certified low-heavy-metal formulations for European architectural channels. Two strategic archetypes dominate: diversified chemical conglomerates with broad coatings portfolios, and specialized thin-film deposition houses with precision optical expertise. Competitive moves concentrate on backward integration into substrate supply and technology licensing for hybrid deposition processes.
Among diversified chemical conglomerates, Sherwin-Williams Company and Arkema occupy positions defined by regulatory navigation capabilities and additive formulation expertise. FENZI S.p.A. exemplifies the specialized mirror coating archetype through its focus on silver-based formulations and flat glass processor relationships. These three companies represent distinct strategic postures: portfolio breadth versus deposition specialization versus substrate integration.
| Leading Market Players |
|---|
| Sherwin-Williams Company |
| FENZI S.p.A. |
| Arkema |
| JENOPTIK AG |
| AccuCoat Inc. |
| CASIX, Inc. |
| North America Coating Laboratories |
| Dynasil Corporation |
| Abrisa Technologies |
| Others |
Supply & Pricing Matrix
Tier-one solar EPCs in the United States and China dictate contract structures through consolidated heliostat procurement, compressing margin pools for standalone coating producers while rewarding integrated mirror system providers with captive glass supply and in-house assembly capabilities.
Pricing Analysis
Coated substrate sales separate from complete mirror system provision, with bundled heliostat assemblies commanding premium positioning over unbundled glass supply. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale, with REACH-compliant low-heavy-metal formulations capturing architectural specification premiums in Germany. Cost compression in silver-based formulations is intensifying because precious metals hedging expenses erode producer margins. Solar energy firms exhibit lowest price sensitivity due to thermal conversion efficiency requirements, while decorative mirror buyers prioritize unit economics over spectral performance.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Shanghai, and Detroit coordinate hub-and-spoke patterns for architectural glass and automotive mirror shipments. Manufacturing concentrates in Germany, China, and the United States, where thin-film technician pipelines anchor precision coating capacity. Production draws from silver ingot, aluminum pellet, and fluoropolymer additive feedstocks. Single-source vulnerability in low-VOC fluoropolymer formulations from Arkema and limited alternatives creates input cost pressure. Distribution runs through flat glass processor captive operations and independent coating specialist direct contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The mirror coatings market represents a late-cycle quality story as procurement consolidation among concentrated solar power developers shifts specification authority toward producers with verified sub-nanometer deposition control and multi-jurisdictional certification capabilities.
For Market Incumbents: Cement backward integration into flat glass substrate supply to defend against disintermediation by integrated heliostat system providers. Expand captive testing facilities in Germany to compress REACH reformulation certification cycles. Prioritize atomic layer deposition hybridization licensing to precision optical manufacturers in Japan and the United States.
For New Entrants and Emerging Players: Domestic medical instrument producers in India present the most penetrable buyer archetype, with BIS certification requirements creating defendable positioning against imports. Target defense optical manufacturing clusters in Karnataka and Telangana with localized PVD capacity. Qualify dielectric coating compatibility with lightweight polymer substrates to capture automotive interior trim specification.
For Investors and Strategic Acquirers: Diversified chemical conglomerates with broad coatings portfolios are the most active acquirers in this space, seeking deposition specialization to complement regulatory navigation capabilities. Focus on mid-cap thin-film houses with FDA biocompatibility pre-certification and established flat glass processor relationships. Watch EU carbon border adjustment mechanism implementation timing as inflection indicator for low-emission deposition process valuation premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Flat Glass Supply | Captive substrate access defends against procurement consolidation by tier-one solar EPCs in Nevada and Xinjiang. |
| REACH Pre-Certification Investment | Early compliance with ECHA substance restrictions captures architectural specification wins in Germany. |
| Atomic Layer Deposition Hybridization | Angstrom-level uniformity enables EUV optical system qualification with semiconductor equipment manufacturers in Japan. |
| Localized PVD Capacity in India | BIS-certified supply contracts reduce import dependency for medical and defense optical instrument producers. |
| Polymer Substrate Coating Qualification | Dielectric compatibility with lightweight materials captures automotive weight reduction mandates. |
Research Methodology
Coverage spans Germany, China, the United States, India, and Japan, with primary inputs from each market through structured interviews with thin-film deposition technicians, flat glass procurement directors, solar EPC specification engineers, medical device quality managers, and automotive tier-one mirror system integrators. Secondary validation incorporates ECHA REACH substance restriction databases, EPA solvent emission filings, MEE dual carbon policy disclosures, customs trade data for silver and aluminum coating inputs, and SEC 10-K coatings segment disclosures. Bottom-up capacity and demand modeling triangulates against top-down industry association aggregates.
Rate-of-change decomposition separates volume drivers from value mix shifts across the projection horizon. Segmentation dimensions include metallic chemistry tier, deposition technology precision class, end-use application specification intensity, and regional regulatory cluster. CAGRs derive from installed base growth, replacement cycle analysis, and technology substitution curves. Forecast inputs incorporate solar capacity buildout pipelines in Xinjiang and Nevada, precision optical instrument production scaling in Greater Boston and Stuttgart, and REACH Annex XVII enforcement timelines.
Underlying measurement precision varies by segment; solar panel and precision optical applications carry tighter precision than decorative mirror categories due to specification documentation density. Forecasts reflect documented assumptions regarding silver price volatility, fluoropolymer additive supply continuity, and technician training pipeline expansion. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Marking Coatings Market
Coatings
Germany Automotive OEM Coatings Market
Coatings
United Kingdom Automotive OEM Coatings Market
Coatings
Wood Preservative Coatings Market
Coatings
Japan Protective Coatings Market
Coatings
Coating Binders Market
Coatings
Anti-Graffiti Coatings Market
Coatings
Australia Industrial Coatings Market
Coatings
Water-Based Alkyd Coatings Market
Coatings
Mexico Protective Coatings Market
Coatings
Spain Automotive OEM Coatings Market
Coatings
Global Anti-Smudge Coatings Market
Coatings
Global Polytetrafluoroethylene (PTFE) Coatings Market
Coatings
Dispersion Coating Market
Coatings
Global Fire-Resistant Coating Market
Coatings
Thailand Architectural Coatings Market