
 Hard Coating Market | 2026-2036
Hard Coating Market Size, Share, and Industry Trends Forecast 2026-2036
Hard Coating Market Intelligence
A shift from single-source supplier relationships to multi-source procurement strategies is broadening the competitive landscape for hard coating services. OC Oerlikon Management AG leverages its extensive technology portfolio across both PVD and CVD processes, giving it significant scale. Sulzer Ltd specializes in thermal spray applications for demanding industrial environments like power generation. Carl Zeiss dominates the optical lens coating segment with its high-performance anti-reflective and scratch-resistant solutions.
Hard coatings are thin-film materials, often just a few microns thick, deposited onto a substrate to enhance its surface properties. Applied via processes like Physical Vapor Deposition (PVD) or Chemical Vapor Deposition (CVD), their primary purpose is to increase hardness, wear resistance, and lubricity. Physical Vapor Deposition represents the largest product type segment, valued for its process control and wide material compatibility. Demand from cutting tools and automotive components applications is driving growth for high-performance technologies like Diamond-Like Carbon coatings.
The European Union's REACH regulation impacts the chemical composition of coatings, restricting the use of certain hazardous substances. In the United States, the EPA enforces standards on volatile organic compound (VOC) emissions, influencing the adoption of environmentally compliant deposition technologies. Suppliers must now balance the technical demand for higher performance and durability against increasing regulatory pressures for sustainable, non-toxic coating materials.
Market Dynamics
The central force shaping the hard coating market is the tension between escalating performance demands from end-users and tightening environmental regulations, which restricts material choices and deposition processes. This dynamic compels innovation toward materials that offer enhanced durability while complying with stricter chemical and emissions standards.
Growth Catalysts
- Advanced Materials:The development of Diamond-Like Carbon (DLC) coatings enhances wear resistance and lubricity, driving adoption in precision cutting tools and high-performance engine components.
- Automotive Electrification:Demand from the electric vehicle sector for durable, low-friction coatings on bearings and gears to extend range and component life is a significant pull.
- Biocompatibility Needs:Stringent medical device regulations in the United States and Europe fuel demand for inert, biocompatible coatings for surgical instruments and implants, creating a high-value niche.
Market Restraints
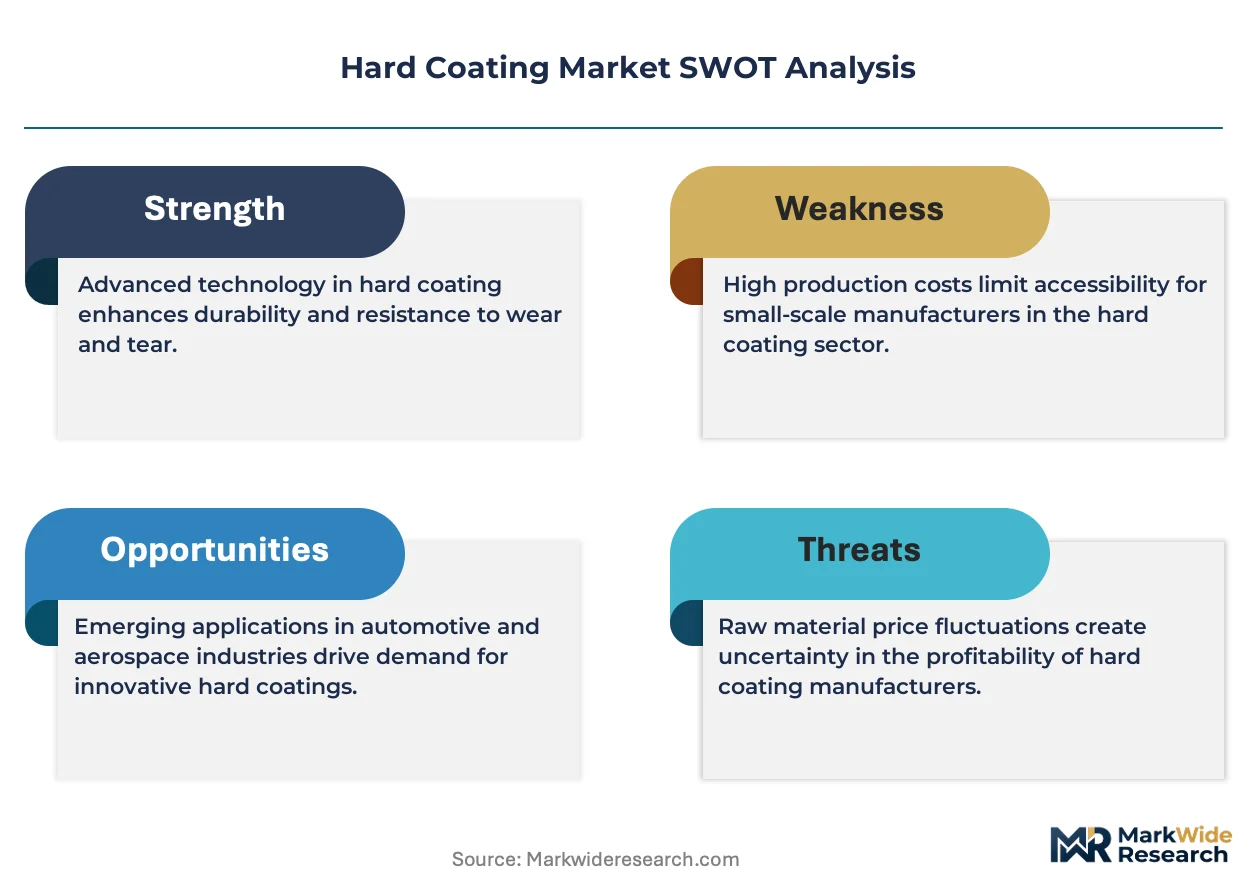
- Input Cost Volatility:The high and fluctuating costs of key raw materials like titanium, tungsten, and cobalt create significant price pressure and margin uncertainty for coating providers.
- Regulatory Compliance:The EU's REACH regulation restricts specific substances like hexavalent chromium, forcing costly reformulation and process requalification for established coating services.
- Geometric Complexity:Achieving uniform coating deposition on components with intricate 3D geometries remains a major technical hurdle, limiting application in certain high-precision parts.
Strategic Opportunities
- Renewable Energy Sector:Developing anti-corrosion and wear-resistant coatings for wind turbine gearboxes and geothermal drilling components presents a significant new application frontier.
- Southeast Asia Expansion:The growing industrial base in countries like Vietnam and Thailand offers an underpenetrated market for establishing localized, high-volume coating service centers.
- Smart Surfaces:Integrating sensor elements into hard coatings to enable real-time monitoring of wear and stress creates opportunities for predictive maintenance service models.
Industry Challenges
- Skilled Labor Scarcity:A persistent shortage of technicians with expertise in operating and maintaining complex PVD and CVD deposition equipment constrains production capacity and quality control.
- High Capital Investment:The substantial capital expenditure required for acquiring and installing advanced coating systems acts as a major barrier to entry for new competitors and smaller firms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hard Coating Market |
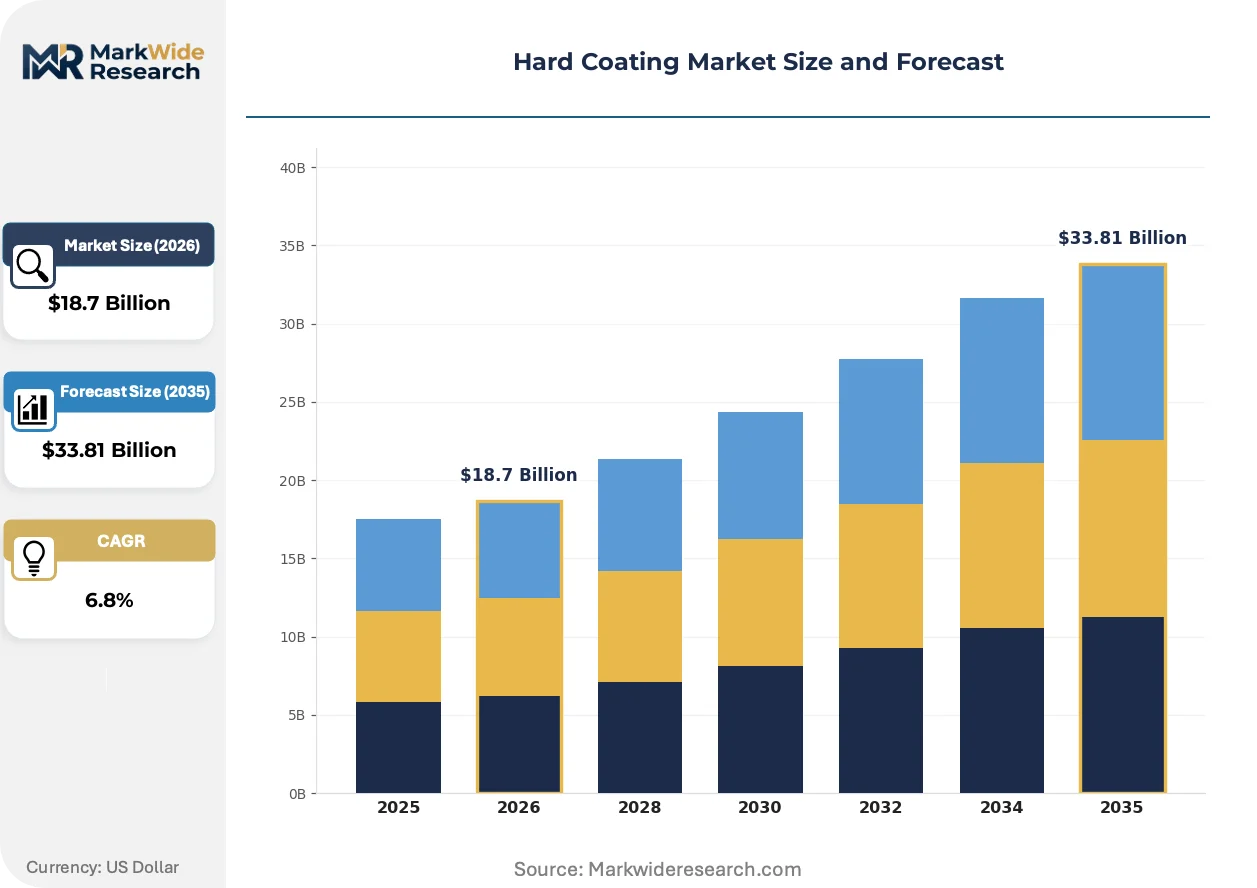
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Physical Vapor Deposition, Chemical Vapor Deposition, Plasma Spraying, Sol-Gel Coating, Thermal Spray, Electroplating Application: Cutting Tools, Optical Lenses, Automotive Components, Aerospace Parts, Electronics Casings, Wear-Resistant Surfaces End User Industry: Tool Manufacturers, Semiconductor Fabricators, Aircraft Assemblers, Consumer Electronics Makers, Machinery Producers, Medical Device Producers Technology: Nanocoating, Diamond-Like Carbon, Ceramic Coating, Metallic Coating, Polymer Coating, Composite Coating |
| Companies Covered | Carl Zeiss, ASB Industries, OC Oerlikon Management AG, Gencoa Ltd, Duralar Technologies, Momentive, SDC Technologies Inc., Sulzer Ltd, Cemecon AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hard Coating Market Strategic Shifts & Innovations
The market’s evolution is defined by the integration of multi-functional properties into environmentally sound coating platforms. This forces innovation that simultaneously addresses durability requirements from industrial applications and sustainability mandates from regulators, pushing development of novel materials and processes.
High-entropy alloy (HEA) coatings offer superior hardness and thermal stability over conventional materials. The aerospace sector is leading adoption for turbine blades, with use accelerating in heavy industry. This technology is unifying previously separate attributes like high-temperature oxidation resistance and extreme hardness into a single layer.
Regulatory pressure from the US Environmental Protection Agency (EPA) enforces strict limits on Volatile Organic Compound (VOC) emissions. This is accelerating the shift from solvent-based processes to compliant technologies like PVD and CVD. The automotive refinishing segment is most affected, prioritizing water-based systems to meet mandates.
Original equipment manufacturers are diversifying their supplier base for coating services to mitigate supply chain risks. This shift moves away from exclusive contracts toward a flexible procurement model involving multiple specialist vendors. The trend is most visible within Germany’s automotive sector and the US aerospace manufacturing ecosystem.
Hard Coating Market Segmentation
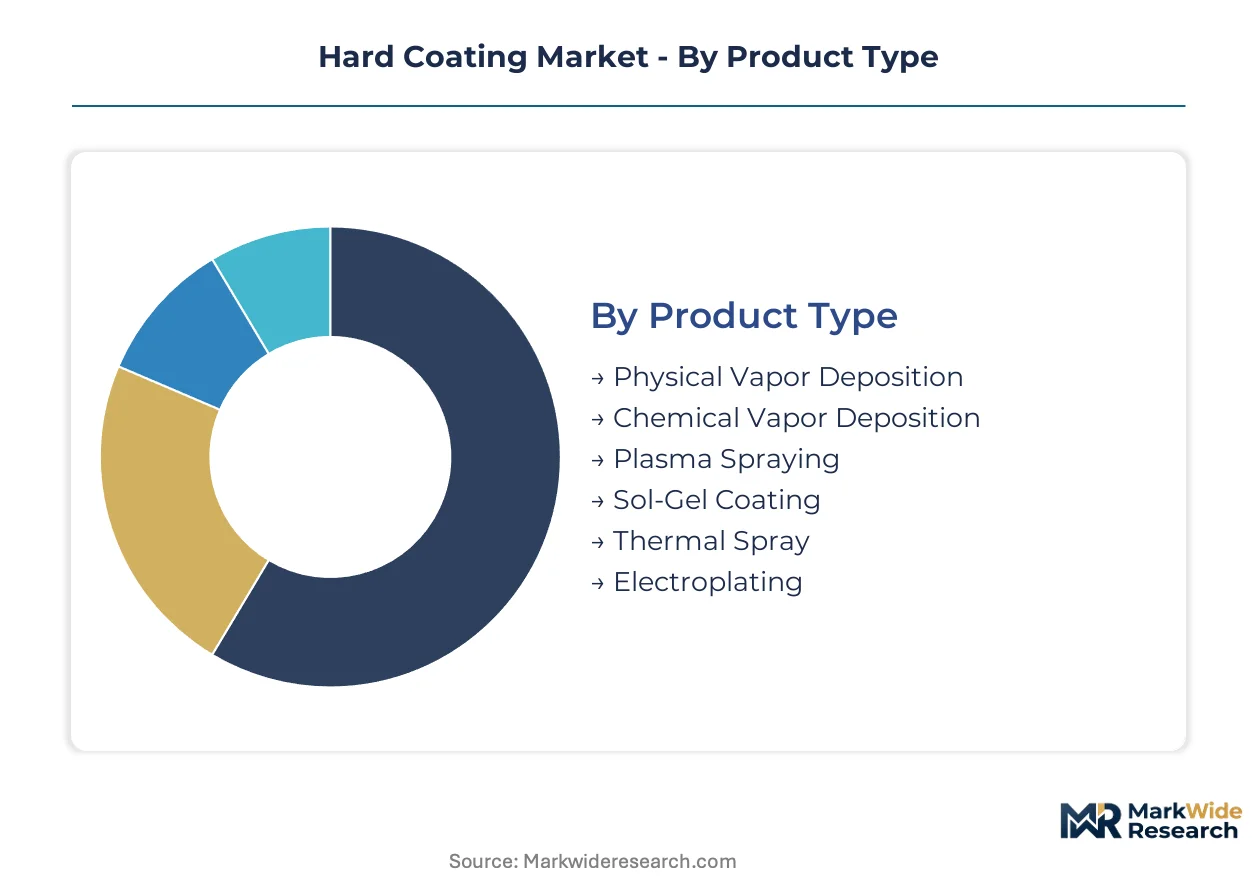
Hard coating market segmentation reveals how diverse surface enhancement needs drive material and process choices. Understanding these distinctions helps stakeholders identify key demand pockets and tailor high-performance solutions. This granular view highlights where innovation in durability and environmental compliance is most critical.
Product Type:
The selection of a hard coating product type hinges on the specific performance requirements and substrate material compatibility demanded by end-users.
- Physical Vapor Deposition:This process deposits thin films by vaporizing a solid material in a vacuum and condensing it onto a substrate. PVD offers excellent adhesion and wide material compatibility, making it suitable for precision cutting tools. Demand concentrates in advanced manufacturing hubs like Germany, driven by the need for enhanced tool life.
- Chemical Vapor Deposition:CVD applies coatings through chemical reactions of gaseous precursors on a heated substrate surface, forming highly conformal and dense layers. This method excels in achieving superior hardness and wear resistance for components in high-temperature environments. Automotive component manufacturers increasingly adopt CVD for engine parts requiring extreme durability.
- Plasma Spraying:This technique uses a high-velocity plasma jet to melt and spray coating materials onto surfaces, providing thick, wear-resistant layers for industrial components.
- Sol-Gel Coating:Sol-gel methods involve wet chemical processes to create thin ceramic or glass-like films at lower temperatures, often for optical or corrosion protection applications.
- Thermal Spray:Thermal spray processes deposit metallic or ceramic coatings for wear, corrosion, and thermal barrier applications in demanding industrial settings.
- Electroplating:Electroplating uses an electric current to deposit a thin, adherent metal layer onto a conductive object, enhancing surface properties and aesthetics.
Volume sits with Physical Vapor Deposition; growth tilts toward Chemical Vapor Deposition due to increasing performance demands.
Application:
Specific application requirements dictate the choice of hard coating, influencing properties like friction, hardness, and chemical inertness.
- Cutting Tools:Hard coatings significantly extend the lifespan and improve the performance of drills, milling cutters, and inserts by reducing friction and wear during machining. The manufacturing sector's continuous drive for efficiency and precision fuels demand for these enhanced tools.
- Automotive Components:Coatings on engine parts, gears, and bearings reduce friction, improve fuel efficiency, and extend component life, especially in electric vehicles. The shift towards electrification intensifies demand for low-friction, durable coatings in this sector.
- Optical Lenses:Coatings enhance light transmission, reduce reflection, and provide scratch resistance for various optical devices, including those from Carl Zeiss.
- Aerospace Parts:High-performance coatings protect critical aerospace components from extreme temperatures, wear, and corrosion, ensuring operational safety and longevity.
- Electronics Casings:Hard coatings offer scratch and impact resistance for consumer electronics, improving device durability and aesthetic appeal.
- Wear-Resistant Surfaces:General industrial applications utilize hard coatings to protect machinery, molds, and dies from abrasive and erosive wear, minimizing downtime.
The market exhibits strong demand from Cutting Tools, with Automotive Components showing the steepest expansion trajectory.
End User Industry:
Each end-user industry presents unique demands for hard coatings, driven by their specific product performance and regulatory requirements.
- Tool Manufacturers:These firms require advanced coatings for their cutting, forming, and molding tools to boost productivity and extend tool life. The competitive landscape for tool performance directly correlates with coating innovation.
- Medical Device Producers:The medical sector demands inert and biocompatible hard coatings for surgical instruments, implants, and diagnostic equipment. Stringent regulations in the United States and Europe drive a high-value niche for specialized coating solutions.
- Semiconductor Fabricators:Hard coatings protect critical equipment and components in semiconductor manufacturing from wear and chemical attack, ensuring process purity.
- Aircraft Assemblers:Aerospace manufacturers rely on coatings to enhance the durability and operational efficiency of components exposed to harsh flight conditions.
- Consumer Electronics Makers:These manufacturers use coatings for scratch resistance and aesthetic enhancement on device surfaces, meeting consumer expectations for durability.
- Machinery Producers:Industrial machinery benefits from hard coatings that reduce friction and extend the service life of moving parts, minimizing maintenance costs.
Demand is primarily driven by Tool Manufacturers, while Medical Device Producers is gaining share fastest.
Technology:
Technological advancements define the capabilities of hard coatings, with innovations focusing on multi-functional properties and environmental compliance.
- Diamond-Like Carbon:DLC coatings are amorphous carbon films exhibiting properties similar to natural diamond, offering exceptional hardness, low friction, and wear resistance. This technology is crucial for high-performance engine components and precision cutting tools.
- Nanocoating:This category encompasses coatings with nanoscale structures, providing superior surface properties like enhanced hardness, corrosion resistance, and self-cleaning capabilities. Nanocoatings find increasing utility in aerospace and medical applications.
- Ceramic Coating:Ceramic coatings, often based on oxides, nitrides, or carbides, provide high hardness, thermal stability, and chemical inertness for demanding industrial environments.
- Metallic Coating:Metallic coatings, applied through various deposition methods, enhance conductivity, corrosion resistance, and aesthetic appeal for a range of components.
- Polymer Coating:Polymer-based hard coatings offer flexibility, chemical resistance, and specific functional properties, often used in conjunction with other materials.
- Composite Coating:Composite coatings combine different materials, such as metals and ceramics, to achieve synergistic properties like improved toughness and wear performance.
The market's core relies on Ceramic Coating, but Diamond-Like Carbon is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The availability of key raw materials like titanium and tungsten across diverse geographies influences the hard coating market's regional dynamics. Localized manufacturing capabilities and stringent environmental regulations further shape demand and supply patterns. Key industrial centers globally demonstrate unique requirements for surface enhancement technologies.
Germany
Advanced manufacturing and automotive components drive significant demand for high-performance hard coatings in Germany. The European Union's REACH regulation heavily influences material selection, restricting certain hazardous substances. Major industrial clusters in Baden-Württemberg, particularly around Stuttgart, concentrate on automotive and machinery production requiring durable surface solutions.
United States
The aerospace and medical device sectors are critical demand drivers for specialized hard coatings in the United States. The EPA enforces strict standards on volatile organic compound (VOC) emissions, pushing adoption of compliant deposition technologies. Manufacturing hubs in Michigan and California lead in automotive and aerospace component production, respectively.
China
Rapid industrial expansion and a large automotive manufacturing base fuel demand for wear-resistant and low-friction coatings across China. National GB standards and dual carbon goals influence material choices and process sustainability. The Yangtze River Delta region, including Shanghai and Suzhou, represents a major hub for electronics and general manufacturing.
Japan
Precision cutting tools and optical lenses represent core application areas for hard coatings in Japan. The Ministry of Economy, Trade and Industry (METI) promotes advanced material research and development through various initiatives. The Kanto region, encompassing Tokyo, hosts numerous high-tech manufacturers and automotive suppliers.
Vietnam
Growing foreign direct investment in manufacturing, particularly in electronics and automotive assembly, creates an emerging market for hard coating services in Vietnam. The government's national environmental protection laws guide local industrial practices. Industrial parks around Ho Chi Minh City are expanding, attracting high-volume production facilities.
Hard Coating Market Key Industry Players
Strategic partnerships and multi-sourcing strategies dominate the current landscape, broadening the competitive field for hard coating services. The market structure features large, integrated technology providers alongside specialized niche players. Key archetypes include global solution providers, thermal spray specialists, and optical coating leaders. Capacity expansion and portfolio diversification are common competitive moves among established firms.
Within the global solution provider archetype, OC Oerlikon Management AG leverages an extensive technology portfolio across both PVD and CVD processes. Sulzer Ltd exemplifies a specialist provider, concentrating on thermal spray applications for demanding industrial environments like power generation. Carl Zeiss, a German-based company, anchors the optical lens coating segment with its high-performance anti-reflective and scratch-resistant solutions, demonstrating strong niche leadership.
| Leading Market Players |
|---|
| Carl Zeiss |
| ASB Industries |
| OC Oerlikon Management AG |
| Gencoa Ltd |
| Duralar Technologies |
| Momentive |
| SDC Technologies Inc. |
| Sulzer Ltd |
| Cemecon AG |
| Others |
Cost & Logistics Intelligence
The performance-grade divergence between advanced Diamond-Like Carbon (DLC) coatings and more commodity Physical Vapor Deposition (PVD) services manifests in both pricing power and supply chain complexity. This bifurcation shapes market dynamics, influencing procurement strategies and raw material dependencies across the industry.
Pricing Analysis
Warranty and service bundling often differentiate premium hard coating offerings, particularly for critical aerospace and medical device applications. Pricing models vary from contract-based long-term offtake for specialized services to per-unit transactional for standard PVD coatings. Price differentiation drivers include the customization level required for intricate geometries and the specific certification level needed for biocompatible medical implants. Cost compression in standard PVD coatings is intensifying due to volatility in raw material prices like titanium and tungsten. Tool manufacturers exhibit higher price sensitivity for high-volume standard tools, while Medical Device Producers are least sensitive due to stringent performance and regulatory requirements.
Supply Chain Analysis
Regional distribution centers and hub-and-spoke patterns characterize the hard coating service delivery, often co-located with major industrial clusters. Geographic supply concentration for advanced services sits within Germany's automotive sector, the United States' aerospace and medical device industries, and China's expanding manufacturing base. The industry relies on key raw materials such as titanium, tungsten, and cobalt. Commodity price volatility for these essential inputs presents a significant structural supply chain risk. Localized, high-volume coating service centers in emerging industrial regions like Vietnam represent the dominant downstream distribution model.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hard coating market is a cost-of-compliance story, with the European Union's REACH regulation creating a barrier-to-entry moat for compliant players. This necessitates strategic adjustments across the value chain to maintain competitiveness and capture new opportunities.
For Market Incumbents: Cement market leadership through strategic acquisitions of specialized coating firms with advanced DLC or High-Entropy Alloy (HEA) capabilities. Invest heavily in R&D for environmentally compliant deposition technologies to counter margin pressure from tightening EPA and REACH regulations. Focus on capacity addition in high-growth regions like Southeast Asia to mitigate supply chain risks and expand market reach. Diversify technology portfolios to offer multi-functional coatings that combine wear resistance with smart surface features.
For New Entrants and Emerging Players: Capture high-value niches by specializing in biocompatible coatings for medical devices, particularly in the United States and Europe, where regulatory barriers create defensible positions. Target underpenetrated industrial markets like Vietnam, offering localized, high-volume coating service centers for electronics and automotive assembly. A compelling go-to-market angle involves offering integrated smart surface solutions with real-time wear monitoring for predictive maintenance applications.
For Investors and Strategic Acquirers: Re-rating potential sits with technology-driven specialists given the demand for advanced DLC and HEA coatings in high-performance applications. Long-term viability over a 5-10 year window favors firms with strong intellectual property in sustainable coating materials and processes. Acquisition targets should include innovators in smart surfaces and environmentally compliant deposition technologies that address regulatory pressures. A signal to watch is the acceleration of automotive electrification, driving demand for specialized low-friction coatings on components.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Expands coating facilities in Germany to meet automotive and precision tool demand. |
| Green Manufacturing Transition | Adopts EPA-compliant PVD/CVD processes to meet evolving VOC emission standards. |
| Joint Venture | Forms partnerships for DLC coating development in high-performance engine components. |
| Product Launch | Introduces high-entropy alloy coatings for aerospace turbine blades, enhancing durability. |
| Geographic Expansion | Establishes service centers in Vietnam to capitalize on growing industrial manufacturing. |
Research Approach
Independent corroboration across industry reports, company filings, and academic journals underwrites the qualitative findings. Primary interviews involved R&D directors, procurement leads at tool manufacturers, and regulatory affairs specialists in medical devices to gather granular insights. Secondary data sources included EPA environmental compliance reports, METI technology roadmaps, and trade association statistics. Bottom-up analysis of segment revenue complemented top-down validation of market sizing.
Comparable historical periods anchored the forecast window, projecting market evolution over the analysis window. Segmentation dimensions modeled included product type, application, end-user industry, and coating technology. Compound Annual Growth Rates were derived from historical trends and projected demand drivers, such as automotive electrification and regulatory shifts. Key forecast inputs included raw material price trends and industrial production indices.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to geopolitical events and unforeseen technological breakthroughs. All forecasts reflect assumptions documented regarding regulatory stability and economic growth. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Acrylic Protective Coating Market
Coatings
Corrosion Protection Coating Market
Coatings
Functional Coil Coating Market
Coatings
Asia-Pacific Epoxy Powder Coatings Market
Coatings
China Marine Coatings Market
Coatings
Soft Touch Polyurethane Coatings Market
Coatings
Global Antiviral Coatings Market
Coatings
Camouflage Coatings Market
Coatings
US Protective Coatings Market
Coatings
Marine Nanocoating Market
Coatings
Global Conformal Coatings Market
Coatings
Canada Automotive OEM Coatings Market
Coatings
Global UV-Cured Coatings Market
Coatings
Conductive Polymer Coatings Market
Coatings
Global Radiation Cured Coatings Market
Coatings
Water-Based Alkyd Coatings Market