
 Europe Waterborne Polyurethane Coatings Market | 2026-2036
Europe Waterborne Polyurethane Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Waterborne Polyurethane Coatings Market Foresight
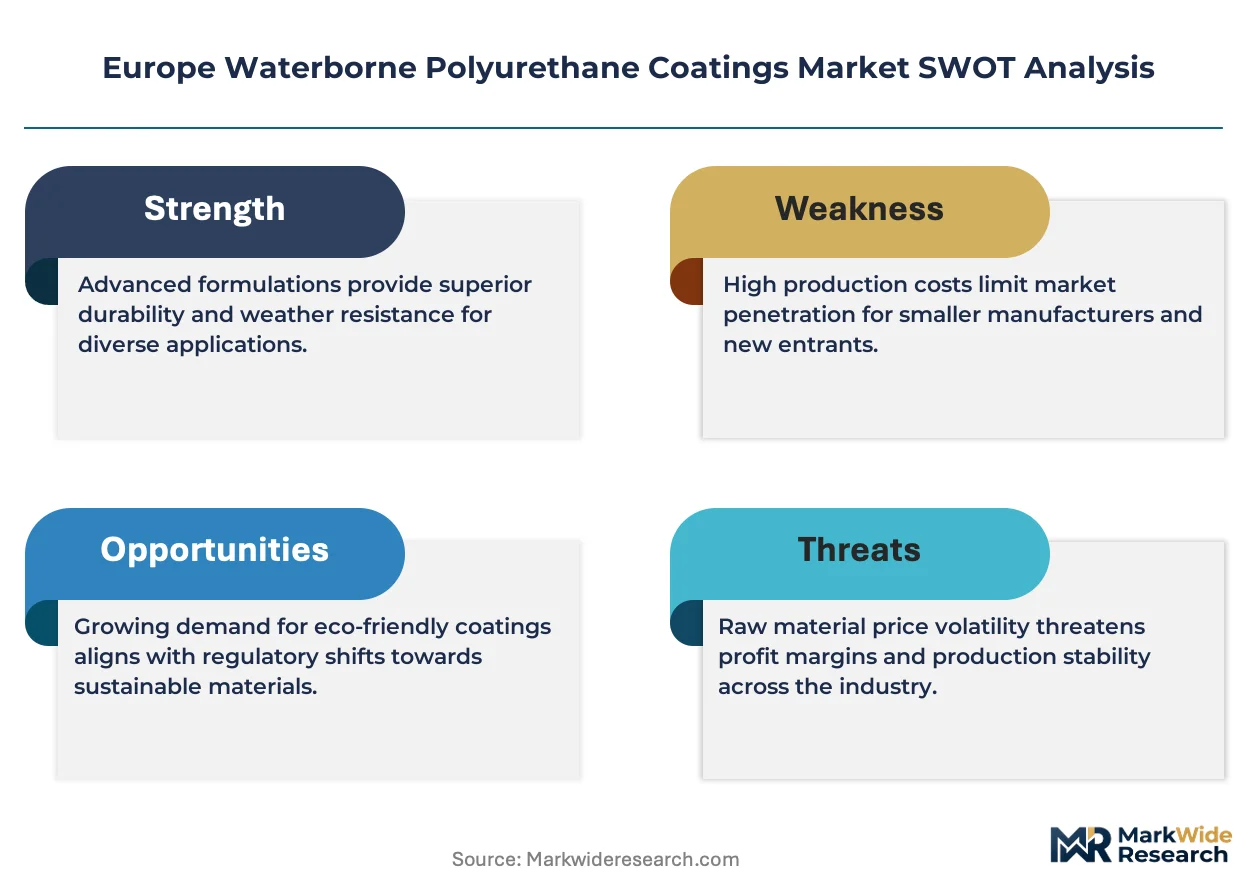
A capital-intensity divergence between integrated resin producers and formulation specialists is rotating competitive advantage toward backward-integrated players with captive polymer supply. BASF SE leverages its Ludwigshafen chemical complex to control raw material flows and stabilize margins. PPG Industries Inc anchors its position through automotive refinish relationships with German OEMs. Akzo Nobel NV differentiates via marine and protective coatings expertise at its Felling and Hengelo facilities.
Waterborne polyurethane coatings are aqueous dispersions of polyurethane polymers, typically 30-50% solids by weight, that cure through moisture evaporation and chemical crosslinking to form durable, flexible films. They serve primarily as low-emission alternatives to solvent-borne systems in applications demanding abrasion resistance and aesthetic finish. Aliphatic formulations command premium positioning in automotive exterior clearcoats where UV stability and color retention justify higher formulation costs. Spray coating technology dominates factory-applied segments, while roller application occupies the mid-tier flooring and furniture refinishing markets where equipment simplicity reduces capital barriers for contractors.
REACH registration requirements and the EU F-Gas Regulation constrain volatile organic compound content, forcing reformulation investments across the value chain. ECHA substance evaluation processes extend compliance timelines for new resin chemistries, creating regulatory moats for incumbents with established dossiers. Germany's Federal Environment Agency enforces stricter state-level VOC thresholds in Baden-Württemberg and Bavaria, fragmenting product registration requirements. Stakeholders must monitor the EU Green Deal's evolving chemical sustainability criteria and assess whether bio-based polyol feedstocks can satisfy performance specifications without triggering novel substance re-registration.
Market Dynamics
REACH substance evaluation timelines and Germany's stricter state-level VOC thresholds in Baden-Württemberg and Bavaria are fragmenting product registration requirements. This regulatory divergence forces manufacturers to maintain parallel formulation portfolios, raising compliance costs while creating defensive moats for incumbents with established dossiers.
Growth Catalysts
- EU Green Deal chemical sustainability criteria:The framework mandates solvent-phase substitution across industrial coatings, accelerating demand for aqueous polyurethane dispersions in automotive OEM clearcoat applications.
- Automotive refinish sector concentration in Germany:German OEM relationships drive specification lock-in for low-VOC coating systems, creating pull-through effects for waterborne polyurethane across the supplier base.
- Aliphatic formulation UV stability:Premium exterior automotive applications favor these chemistries for color retention, justifying higher formulation costs and expanding addressable market in luxury vehicle segments.
Market Restraints
- Petrochemical polyol price volatility:Crude oil-linked feedstock costs compress margins for non-integrated formulators lacking captive resin supply.
- ECHA dossier maintenance burden:Extended compliance timelines for novel resin chemistries delay new entrant market access and freeze innovation pipelines.
- Solvent-borne epoxy substitution in heavy-duty marine:Superior salt-spray resistance in protective coatings segments limits waterborne polyurethane penetration in North Sea offshore infrastructure.
Strategic Opportunities
- Spain furniture manufacturing acceleration:Barcelona and Valencia production clusters show underpenetrated uptake for roller-applied waterborne finishes on medium-density fiberboard substrates.
- CE marking harmonization with bio-based polyol integration:Renewable feedstock formulations that satisfy performance specifications without triggering novel substance re-registration unlock premium positioning.
- Digital color-matching platform convergence:Cloud-based spectrophotometry linked to automated dispensing systems reduces contractor capital barriers in Italian refinishing markets.
Industry Challenges
- Crosslinking chemistry skill scarcity:Formulation chemists with expertise in moisture-cure and two-component waterborne systems command wage premiums that strain mid-tier producer staffing.
- Legacy spray booth retrofit capex:Conversion from solvent-borne to waterborne-compatible humidity-controlled application environments requires capital outlays that delay contractor adoption cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Waterborne Polyurethane Coatings Market |
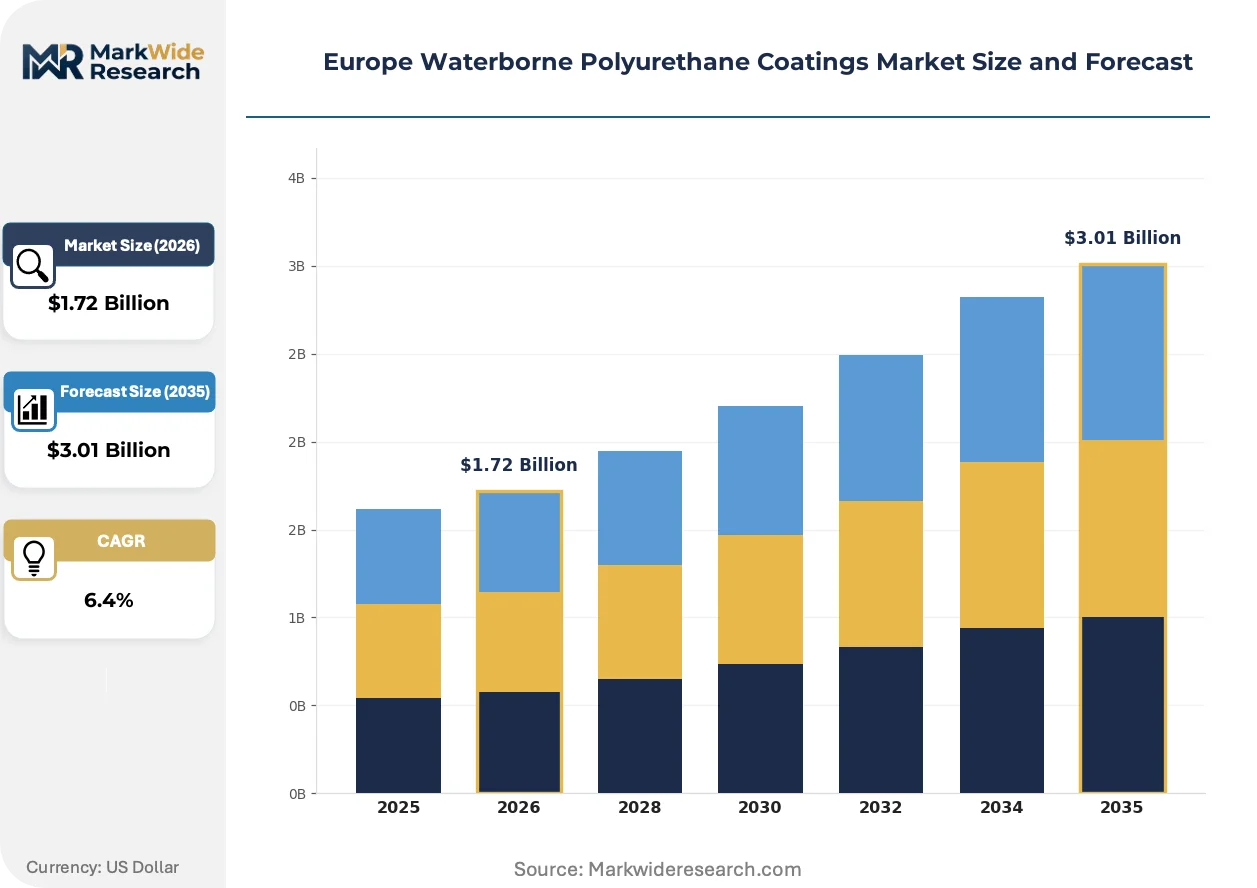
| Market Size in 2026 | $1.72 Billion |
| Market Size in 2035 | $3.01 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aliphatic, Aromatic, Hybrid, Elastomeric Application: Automotive, Furniture, Flooring, Construction End User: Manufacturers, Contractors, OEMs, Distributors Technology: Conventional, Spray Coating, Roller Application, Electrostatic |
| Companies Covered | Akzo Nobel NV, Jotun, BASF SE, Hempel, RPM International Inc, The Sherwin-Williams Company, Axalta Coating Systems, IVM Chemicals SRL, PPG Industries Inc, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Waterborne Polyurethane Coatings Market Shifts & Advancements
Polyurethane dispersion chemistry is fragmenting into performance-optimized and cost-optimized formulation branches. This technical divergence reflects diverging buyer requirements across automotive OEM, furniture, and industrial maintenance segments.
Self-crosslinking waterborne polyurethane technology is bifurcating the factory-applied coatings segment. These systems eliminate external crosslinker addition while maintaining film hardness and chemical resistance. Automotive exterior clearcoat specifications in Germany and France are adopting these chemistries at accelerated rates. The technology is bifurcating competitive advantage toward resin producers with proprietary polymer architecture IP, compressing formulation-only specialists into commodity positioning.
REACH authorization processes are tightening scrutiny on isocyanate-based curing agents. Industrial users face expanded worker exposure documentation requirements and substitution planning obligations. Automotive refinish shops in Bavaria and Baden-Württemberg are responding by accelerating conversion to blocked isocyanate and carbodiimide crosslinking alternatives ahead of enforcement phase-in.
Buyer specification consolidation among German automotive OEMs is compressing supplier diversity in coating procurement. Tier-1 applicators now face consolidated technical approval processes that favor multi-site qualified resin suppliers. Tier-2 Italian and Spanish furniture manufacturers are experiencing parallel specification migration as export-oriented producers align with German retail buyer standards.
Europe Waterborne Polyurethane Coatings Market Segmentation
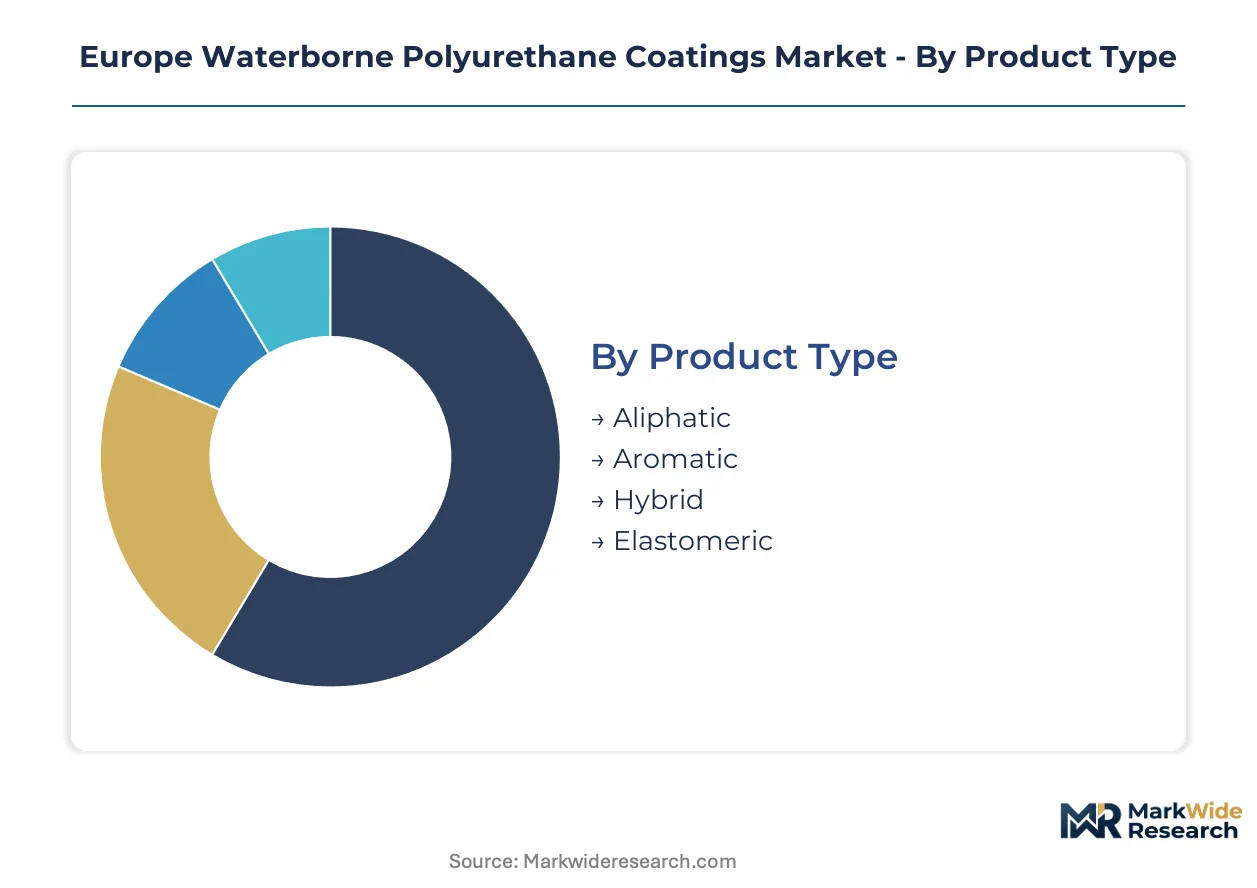
Waterborne polyurethane coatings fragment across four distinct classification axes. Each dimension carries regulatory, technical, and commercial implications that reshape procurement patterns and supplier positioning across European industrial corridors.
Product Type:
REACH substance evaluation timelines and the EU F-Gas Regulation create divergent compliance burdens across resin chemistries, fragmenting formulation portfolios and registration costs.
- Aliphatic:UV-stable isocyanate-based polymers with superior color retention and gloss durability. German automotive OEM clearcoat specifications in Stuttgart and Munich drive concentrated demand, though premium feedstock costs strain non-integrated formulator margins.
- Aromatic:Cost-optimized toluene diisocyanate-based systems offering abrasion resistance at lower formulation expense. Industrial maintenance applications in Poland and Czech Republic absorb volume where UV exposure is limited and cost sensitivity dominates procurement.
- Hybrid:Acrylic-polyurethane copolymers balancing hardness and flexibility for mid-tier furniture finishing.
- Elastomeric:High-elongation films for crack-bridging flooring systems in commercial renovation.
Established volume favors Aromatic; emerging adoption favors Aliphatic.
Application:
End-use concentration rotates around automotive specification lock-in versus dispersed contractor-driven demand.
- Automotive:Exterior clearcoat and refinish systems demanding aliphatic UV stability and controlled film build. Bavaria and Baden-Württemberg enforce stricter VOC thresholds than EU baseline, forcing dedicated product registrations and humidity-controlled spray booth investments.
- Furniture:Roller-applied finishes on medium-density fiberboard in Barcelona and Valencia production clusters. Italian export-oriented manufacturers align with German retail buyer standards, consolidating specification migration.
- Flooring:Commercial and residential surface protection with elastomeric crack-bridging requirements.
- Construction:Protective and decorative coatings for infrastructure and building envelopes.
Specification consolidation concentrates margin in Automotive; geographic expansion drives Furniture.
End User:
Procurement authority separates formulation-agnostic volume buyers from technically integrated specification setters.
- Manufacturers:Factory-applied coating operations with captive application lines and process control. German industrial corridor producers leverage scale to negotiate multi-year resin supply agreements.
- OEMs:Automotive and equipment original equipment manufacturers with locked technical approval processes. Tier-1 applicators face consolidated qualification requirements favoring multi-site qualified suppliers.
- Contractors:Field application specialists with equipment retrofit constraints and skill scarcity pressures.
- Distributors:Inventory-carrying intermediaries serving fragmented regional demand.
Technical integration favors OEMs; volume scale favors Manufacturers.
Technology:
Capital intensity and application environment dictate equipment selection and crosslinking chemistry compatibility.
- Spray Coating:Atomized application with controlled humidity and temperature parameters. German automotive OEM facilities require humidity-controlled booth retrofits that delay contractor conversion cycles and concentrate factory-applied volume.
- Roller Application:Simplified equipment reducing capital barriers for Italian and Spanish furniture refinishing contractors. Mid-tier flooring segments absorb volume where film thickness tolerance permits manual application.
- Conventional:Brush and dip methods for small-batch industrial maintenance.
- Electrostatic:Charged particle deposition for complex geometry metal finishing.
Factory automation favors Spray Coating; contractor accessibility favors Roller Application.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Poland and the Czech Republic exhibit acute price sensitivity for aromatic formulations, while German automotive OEMs absorb substantial premiums for aliphatic UV-stable systems. This demand-elasticity contrast shapes supplier pricing power and regional margin structures across the continent.
Germany
Automotive OEM clearcoat specifications in Stuttgart and Munich drive concentrated demand for aliphatic waterborne polyurethane systems. REACH registration requirements and stricter Bavarian state-level VOC thresholds fragment product registration obligations. The Ludwigshafen chemical complex anchors backward-integrated resin production, stabilizing raw material flows for formulators serving Baden-Württemberg automotive clusters.
France
Luxury automotive exterior applications favor premium aliphatic chemistries for color retention and gloss durability. The EU Green Deal chemical sustainability criteria accelerate solvent-phase substitution mandates across industrial coating operations. Production clusters in the Grand Est and Hauts-de-France regions absorb volume for furniture finishing and automotive refinish segments.
Italy
Export-oriented furniture manufacturers in Lombardy and Veneto align formulation specifications with German retail buyer standards, consolidating technical migration toward waterborne systems. CE marking harmonization pressures drive compliance investments across medium-density fiberboard finishing operations. Roller-applied waterborne polyurethane adoption accelerates in Brianza furniture production corridors.
Spain
Barcelona and Valencia furniture manufacturing clusters show underpenetrated uptake for roller-applied waterborne finishes, presenting expansion opportunities for mid-tier formulators. Cost-optimized aromatic systems dominate procurement where UV exposure remains limited. Spanish producers face accelerating specification migration as export channels deepen into Northern European retail networks.
Poland
Industrial maintenance applications absorb volume for aromatic toluene diisocyanate-based systems where cost sensitivity dominates procurement decisions. ECHA substance evaluation processes extend compliance timelines, creating defensive advantages for incumbents with established dossiers. Warsaw and Kraków industrial corridors concentrate demand for protective coatings in manufacturing infrastructure.
Europe Waterborne Polyurethane Coatings Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with backward-integrated resin producers commanding margin stability through captive polymer supply. Formulation specialists without in-house resin production face compressed margins during petrochemical feedstock volatility. Two strategic archetypes dominate: integrated chemical conglomerates controlling upstream polymer architecture, and coating specialists leveraging deep application expertise in automotive or marine segments. Competitive moves concentrate on strategic partnerships for bio-based feedstock development and geographic expansion into underpenetrated furniture manufacturing clusters.
Among integrated chemical conglomerates, BASF SE anchors the premium tier through its Ludwigshafen complex operations, while PPG Industries Inc occupies a position exemplifying automotive refinish specialization. Akzo Nobel NV represents the marine and protective coatings archetype with established facility networks. These three entities illustrate the competitive divergence between upstream-controlled and application-anchored positioning strategies.
| Leading Market Players |
|---|
| Akzo Nobel NV |
| Jotun |
| BASF SE |
| Hempel |
| RPM International Inc |
| The Sherwin-Williams Company |
| Axalta Coating Systems |
| IVM Chemicals SRL |
| PPG Industries Inc |
| Others |
Supply & Pricing Matrix
REACH registration dossiers gate both supplier qualification and price tiering simultaneously, forcing non-integrated formulators to absorb premium compliance costs while integrated resin producers capture margin through captive polymer architectures. German automotive OEMs in Stuttgart and Munich absorb substantial aliphatic formulation premiums, whereas Polish industrial maintenance buyers drive aromatic system procurement on cost sensitivity alone.
Pricing Analysis
After-sales technical service and extended formulation support contracts drive lifetime value for waterborne polyurethane suppliers. Three-tier pricing structure across premium aliphatic, standard hybrid, and economy aromatic levels separates German automotive clearcoat specifications from Polish industrial maintenance volumes. Cost compression in mid-tier furniture finishing is intensifying because Spanish and Italian contractors lack humidity-controlled spray booth infrastructure. German OEMs exhibit least price sensitivity; Polish protective coatings buyers demonstrate highest elasticity.
Supply Chain Analysis
Isocyanate feedstock concentration in the Ludwigshafen-Rotterdam-Antwerp chemical corridor underwrites European resin supply security. Germany, Belgium, and the Netherlands anchor polyol production; Spain and Italy concentrate downstream formulation for furniture applications. Supply chain risk centers on petrochemical price volatility tethered to crude oil benchmarks. Distribution runs through regional chemical distributors serving fragmented contractor networks in Southern Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. Established REACH dossiers create decade-long barriers against novel resin chemistry entrants.
For Market Incumbents: Compound backward integration advantages by securing captive polyol supply agreements with Ludwigshafen and Antwerp chemical complex operators. Expand humidity-controlled spray booth financing programs for Italian and Spanish contractor networks to accelerate conversion cycles. ECHA substance evaluation timeline extensions threaten new entrant pipeline access; defend through dossier maintenance investments and blocked isocyanate crosslinking R&D. For New Entrants and Emerging Players: Anchor in Spain's Barcelona and Valencia furniture manufacturing clusters where roller-applied waterborne finishes show underpenetrated uptake. Target mid-tier MDF substrate finishing with cost-optimized aromatic formulations bypassing German automotive specification complexity. Pursue digital color-matching platform partnerships to reduce contractor capital barriers and accelerate specification migration. For Investors and Strategic Acquirers: REACH authorization phase-in for isocyanate-based curing agents reshapes the acquisition landscape toward blocked isocyanate and carbodiimide technology holders. Five-to-ten year viability favors backward-integrated resin producers with established automotive OEM qualification. Target acquisition archetype: mid-cap formulators with proprietary self-crosslinking polymer IP and existing Bavarian spray booth infrastructure relationships. Signal to monitor: German Federal Environment Agency state-level VOC threshold harmonization momentum.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyol Production | Ludwigshafen complex operators stabilize margin against petrochemical volatility. |
| Self-Crosslinking Polymer R&D Investment | Proprietary IP compresses formulation-only competitors into commodity positioning. |
| Spray Booth Financing Partnerships | Italian contractor networks overcome retrofit capex barriers to waterborne conversion. |
| Bio-Based Polyol Feedstock Development | CE marking harmonization unlocks premium positioning without novel substance re-registration. |
| Digital Color-Matching Platform Deployment | Cloud-based spectrophotometry reduces capital barriers in Spanish refinishing markets. |
Research Methodology
Initial hypotheses were tested against primary input from coating formulation chemists, automotive OEM procurement directors, furniture manufacturing plant managers, and regional chemical distributors, then refined through secondary validation. Sources included ECHA substance evaluation databases, Cefic industry statistics, German Federal Environment Agency VOC enforcement records, and customs trade flow data. Bottom-up resin production estimates triangulated against top-down coatings consumption models.
Variance decomposition across product type, application segment, end-user procurement authority, and technology deployment mode structured the analytical framework. CAGRs derived from segment-level volume projections and value-per-unit assumptions across the analysis window. Forecast inputs incorporated REACH compliance timeline assumptions and automotive OEM specification lock-in persistence rates.
Material uncertainties — ECHA authorization scope expansion, EU Green Deal chemical sustainability criteria evolution, and petrochemical feedstock price shocks — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory enforcement consistency and substitution technology performance parity. Revision becomes warranted when blocked isocyanate crosslinking adoption crosses German automotive refinish threshold penetration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
France Protective Coatings Market
Coatings
Antifouling Coatings Market
Coatings
Asia-Pacific Anti-Friction Coatings Market
Coatings
Saudi Arabia Floor Coatings Market
Coatings
US Industrial Coatings Market
Coatings
Thermal Insulation Coating Market
Coatings
Coating Thickness Gauge Market
Coatings
Sustained Release Coatings Market
Coatings
Trim Coatings Market
Coatings
Thermal Barrier Coatings Market
Coatings
Protective and Marine Coatings Market
Coatings
United States Automotive OEM Coatings Market
Coatings
Hull Coatings Market
Coatings
Powder Coating Booth Market
Coatings
South Africa Protective Coatings Market
Coatings
Polyester Coatings Market