
 Global Diamond Coatings Market | 2026-2036
Global Diamond Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Global Diamond Coatings Market Foresight
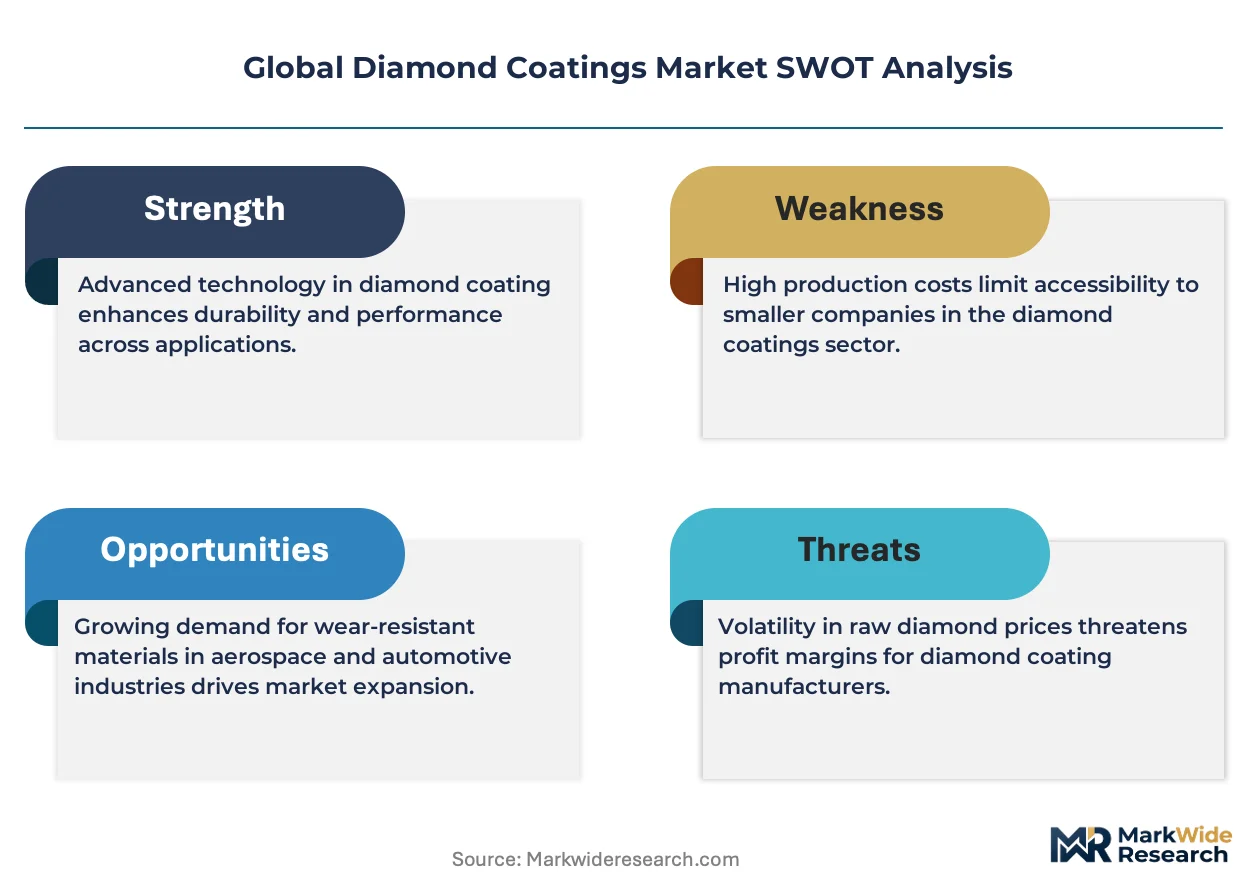
Asset-light leasing models for chemical vapor deposition reactors is rewriting competitive entry barriers for diamond coatings production. Element Six leverages captive synthetic diamond supply to anchor its coating operations across European precision engineering markets. Sumitomo Electric Industries Ltd. sustains technology leadership through in-house development of polycrystalline diamond substrates for cutting tool applications. NeoCoat SA specializes in nanocrystalline diamond films for optical components, occupying a defensible niche in photonics supply chains.
Diamond coatings are thin-film layers of synthetic diamond deposited onto substrates through chemical vapor deposition or physical vapor deposition, typically ranging from nanometers to micrometers in thickness, engineered to deliver extreme hardness, low friction coefficients, and superior thermal conductivity for industrial surfaces. Their primary commercial purpose centers on extending component lifespan in abrasive environments while enabling heat dissipation in semiconductor and aerospace systems. Polycrystalline diamond coatings dominate cutting tool applications due to established performance benchmarks and mature supply chains, while ultrananocrystalline diamond films represent the fastest-expanding category as biomedical and microelectromechanical system applications proliferate. Substrate material selection increasingly favors silicon and tungsten carbide, where thermal expansion matching and adhesion chemistry create the deepest margin pools for specialized deposition service providers.
FDA device regulations in the United States constrain diamond-coated surgical instrument introductions through biocompatibility validation requirements, while REACH compliance in Europe governs precursor chemical handling across CVD supply chains. China's GB standards and MIIT directives shape domestic manufacturing qualifications for diamond-coated electronics substrates, influencing export eligibility for multinational coating houses. Stakeholders must monitor evolving chemical hazard classifications under ECHA review cycles and assess dual-use export control implications for thermal management coatings in defense-adjacent aerospace programs.
Market Dynamics
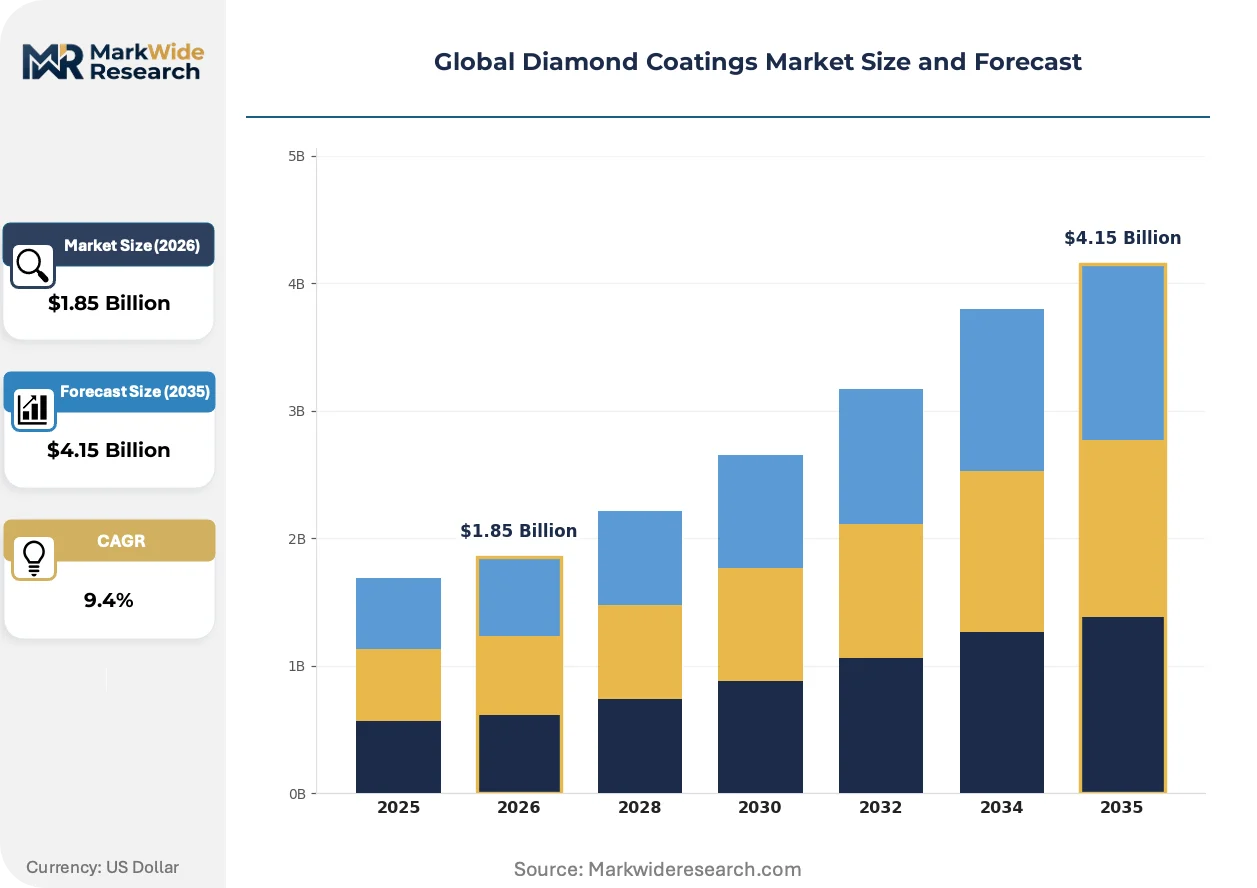
Chemical vapor deposition reactor leasing is compressing capital barriers for diamond coatings entrants, while precision engineering clusters in China, Japan, and Germany deepen captive demand for thermal management substrates.
Growth Catalysts
- MIIT electronics directives:China's domestic manufacturing qualifications for diamond-coated substrates are accelerating local CVD capacity expansion and export eligibility for multinational coating houses.
- Chip packaging thermal management:Semiconductor fabrication facilities are specifying polycrystalline diamond interposers to dissipate heat from high-density 3D architectures.
- Ultrananocrystalline film biomedical applications:Surgical instrument manufacturers are validating diamond-coated surfaces for extended wear resistance in orthopedic cutting tools.
Market Restraints
- Precursor chemical cost volatility:Methane and hydrogen feedstock pricing swings compress margin predictability for independent deposition service providers.
- European REACH compliance friction:ECHA hazard classification reviews for organometallic CVD precursors are extending chemical registration timelines and limiting formulation flexibility.
- Silicon carbide substrate substitution:Wide-bandgap semiconductor manufacturers are evaluating bare SiC thermal spreaders as lower-cost alternatives to diamond-coated solutions in moderate-power applications.
Strategic Opportunities
- India precision engineering underpenetration:Domestic machine tool builders in Pune and Bengaluru represent unserved demand for polycrystalline diamond-coated cutting inserts.
- EU Green Deal industrial decarbonization incentives:Carbon footprint reduction mandates for manufacturing processes are creating preference for diamond-coated tooling that extends component lifespan and reduces replacement frequency.
- Photonics nanocrystalline convergence:Optical component manufacturers are integrating diamond films with silicon photonics platforms for thermal stability in high-power laser systems.
Industry Challenges
- CVD reactor operator skill scarcity:Plasma diagnostics and precursor flow optimization expertise concentrates among veteran technicians in German and Japanese industrial clusters.
- FDA 510(k) biocompatibility timelines:Diamond-coated surgical instrument developers face extended validation cycles for endotoxin and cytotoxicity testing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Diamond Coatings Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $4.15 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Coating Type: Nanocrystalline Diamond, Single Crystal, Polycrystalline Diamond, Ultrananocrystalline Diamond Application: Cutting Tools, Wear-Resistant Parts, Optical Components, Thermal Management Devices Substrate Material: Silicon, Tungsten Carbide, Aluminum, Glass End User Industry: Electronics Manufacturing, Aerospace Engineering, Energy Production, Precision Engineering |
| Companies Covered | Crystallume Corporation, Sumitomo Electric Industries Ltd., Element Six, JCS Technologies Pte Ltd., Diamond Product Solutions, Sandvik AB, NeoCoat SA, SP3 Diamond Technologies, OC Oerlikon Management AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Diamond Coatings Market Shifts & Advancements
Deposition technology is hybridizing across thermal and plasma-enhanced methods, while regulatory frameworks in major manufacturing jurisdictions are tightening precursor chemical oversight.
Hot-filament chemical vapor deposition is hybridizing with microwave plasma enhancement to achieve lower-temperature deposition on thermally sensitive substrates. Medical device manufacturers are piloting these hybrid systems for polymer-based surgical instruments. The convergence is compressing equipment differentiation between mid-tier and premium reactor suppliers.
REACH authorization requirements for boron-containing CVD precursors are restricting formulation options for European coating houses. Deposition service providers are qualifying alternative dopant chemistries to maintain n-type diamond conductivity specifications. German precision engineering clusters are absorbing the compliance costs faster than Southern European independents.
Asset-light reactor leasing is displacing capital purchase models among Asian machine tool coating job shops. Taiwanese and South Korean cutting tool manufacturers are accessing CVD capacity through equipment-as-a-service contracts rather than owning deposition assets. The shift concentrates technical service revenue with European and Japanese reactor OEMs while fragmenting coating production geography.
Global Diamond Coatings Market Segmentation
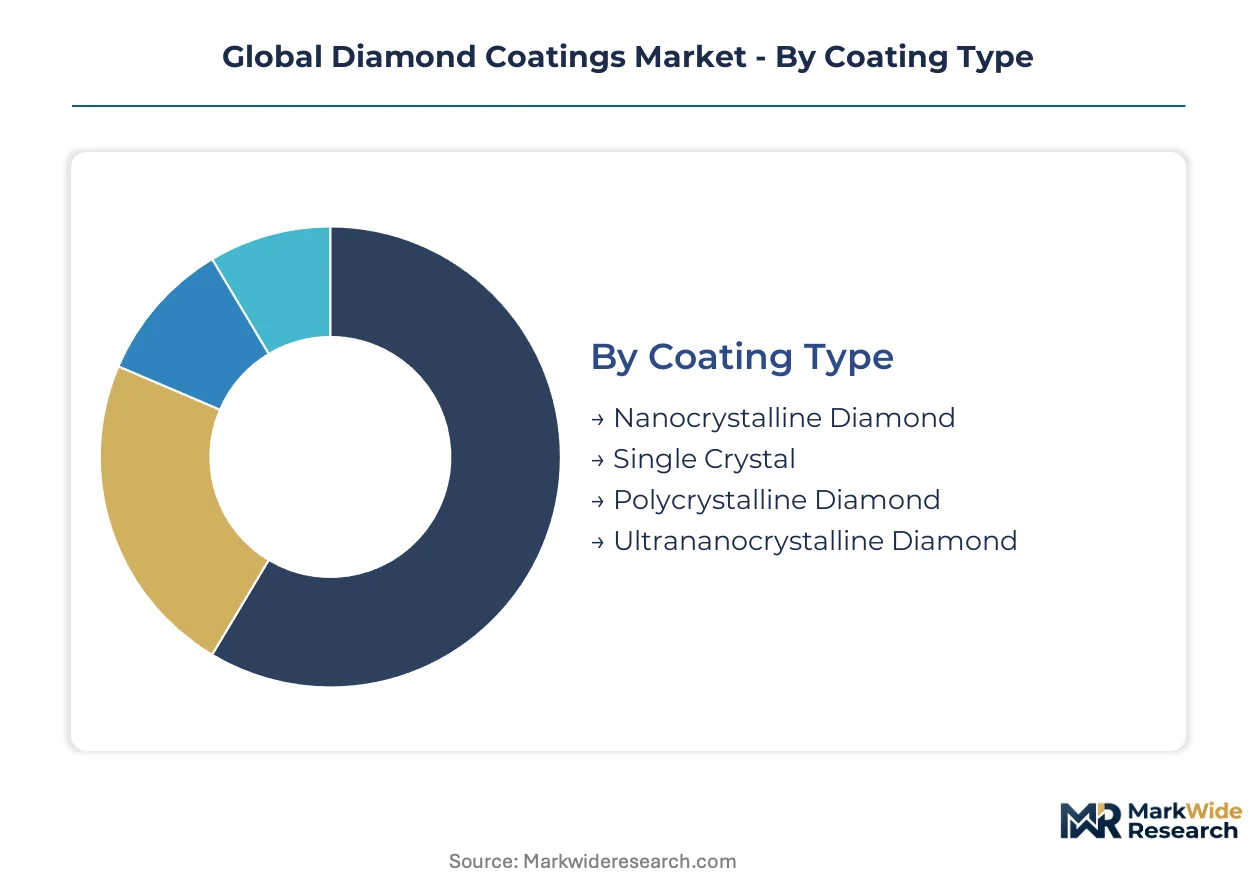
Diamond coatings segmentation reveals distinct margin architectures across deposition technologies and substrate pairings. Coating type determines thermal conductivity ceilings and surface roughness tolerances, while substrate selection dictates adhesion chemistry and expansion matching requirements.
Coating Type:
The use-case spectrum spans from optical clarity demands in photonics to extreme hardness requirements in abrasive machining environments.
- Polycrystalline Diamond:Aggregated diamond grains with grain boundaries enabling controlled surface textures for cutting tool interfaces. Demand concentrates in German and Japanese precision engineering clusters where polycrystalline diamond-coated inserts extend tool life in hardened steel machining. Established volume favors polycrystalline diamond; emerging adoption favors ultrananocrystalline diamond.
- Ultrananocrystalline Diamond:Grain sizes below 10 nanometers delivering exceptional surface smoothness for biomedical and MEMS applications. Surgical instrument manufacturers in the United States are validating these films for orthopedic cutting tools under FDA 510(k) pathways. This segment is climbing the fastest as microelectromechanical system fabrication expands.
- Nanocrystalline Diamond:Intermediate grain structures balancing hardness with optical transparency for photonics substrates.
- Single Crystal:Epitaxial diamond layers for quantum sensing and high-frequency electronics requiring minimal defect densities.
Cost tiers separate commodity cutting tool coatings from premium biomedical and quantum-grade depositions.
Application:
Application segmentation tracks thermal management intensity against mechanical wear exposure.
- Thermal Management Devices:Diamond interposers and heat spreaders dissipating heat from high-density 3D chip architectures. Semiconductor fabrication facilities in Taiwan and South Korea specify these for advanced packaging applications where thermal conductivity exceeds 1000 W/mK. Established volume favors cutting tools; emerging adoption favors thermal management devices.
- Cutting Tools:Polycrystalline diamond-coated inserts and end mills for non-ferrous metal and composite machining. Tungsten carbide substrate compatibility has matured supply chains across Chinese machine tool manufacturing.
- Wear-Resistant Parts:Seals, bearings, and nozzles operating in abrasive slurry environments.
- Optical Components:Diamond windows and lenses transmitting from ultraviolet through far-infrared spectra.
Customer type bifurcation separates high-volume automotive machining contracts from low-volume aerospace and medical device qualifications.
Substrate Material:
Substrate selection governs CVD process temperature windows and thermal expansion mismatch risks.
- Tungsten Carbide:Cemented carbide substrates with cobalt binder phases enabling strong diamond nucleation through carbide formation. Cutting tool manufacturers in China and Germany dominate procurement volumes for machining inserts. Established volume favors tungsten carbide; emerging adoption favors silicon.
- Silicon:Wafer-scale substrates for thermal management interposers and MEMS devices. Electronics manufacturing in Japan and South Korea drives specification tightening for 300mm wafer compatibility.
- Aluminum:Lightweight substrates requiring low-temperature deposition protocols to prevent melting.
- Glass:Transparent substrates for optical and photonic integration applications.
Margin concentration aligns with thermal expansion matching complexity and surface preparation requirements.
End User Industry:
End user segmentation reflects certification intensity and performance specification stringency.
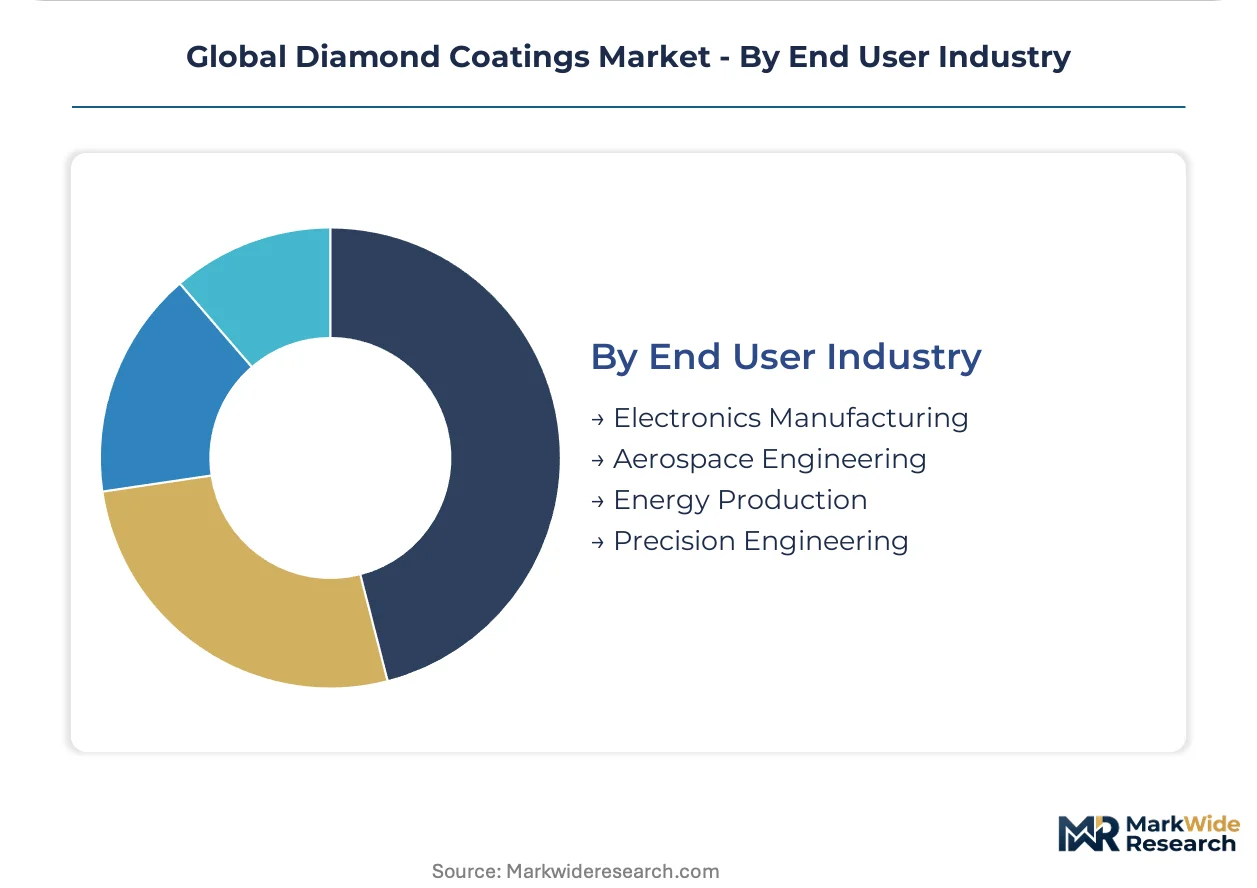
- Electronics Manufacturing:Semiconductor packaging, RF devices, and power electronics requiring thermal conductivity and electrical insulation. MIIT directives in China accelerate domestic qualification requirements for diamond-coated substrates. Established volume favors electronics manufacturing; emerging adoption favors aerospace engineering.
- Aerospace Engineering:Thermal protection systems and optical windows for hypersonic and space applications. Dual-use export controls in the United States and European Union constrain coating house eligibility for defense-adjacent programs.
- Precision Engineering:Machine tools, metrology equipment, and manufacturing instrumentation.
- Energy Production:Wear components for drilling, mining, and nuclear reactor environments.
Geographic supply concentration in East Asian electronics clusters contrasts with European precision engineering captive demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT electronics directives in China are accelerating domestic CVD capacity expansion and reshaping export eligibility criteria for multinational coating houses. Germany's precision engineering clusters absorb REACH compliance costs faster than Southern European independents. Japan and South Korea dominate thermal management substrate specifications for advanced semiconductor packaging.
China
Domestic manufacturing qualifications under GB standards and MIIT directives are driving CVD reactor deployment across Yangtze River Delta electronics corridors. The country's national standards regulator enforces substrate certification timelines that influence multinational coating house export strategies. Shenzhen and Shanghai industrial clusters concentrate thermal management interposer production for 3D chip architectures.
Germany
Precision engineering demand in Baden-Württemberg and Bavaria anchors polycrystalline diamond-coated cutting tool consumption. ECHA hazard classification reviews for organometallic CVD precursors extend chemical registration timelines. Stuttgart and Munich industrial corridors absorb compliance costs through captive synthetic diamond supply integration.
Japan
METI industrial policy supports domestic qualification requirements for diamond-coated substrates in RF device manufacturing. The country's national industrial regulator coordinates with semiconductor fabrication facilities to tighten 300mm wafer compatibility specifications. Tokyo and Osaka metropolitan areas concentrate plasma diagnostics expertise for CVD reactor optimization.
South Korea
Equipment-as-a-service contracts for CVD capacity are displacing capital purchase models among cutting tool coating job shops. MFDS medical device regulations influence biocompatibility validation pathways for orthopedic instrument developers. Busan-Ulsan and Seoul Capital Area clusters drive specification tightening for thermal management interposers in high-density packaging.
United States
FDA 510(k) biocompatibility timelines constrain diamond-coated surgical instrument introductions through endotoxin and cytotoxicity testing requirements. EPA oversight of precursor chemical emissions shapes CVD facility siting decisions. Greater Boston and Pacific Northwest precision engineering corridors concentrate MEMS fabrication demand for ultrananocrystalline diamond films.
Global Diamond Coatings Market Competitive Landscape
On the supply side, the industry is consolidating around captive synthetic diamond supply chains and specialized deposition service capabilities. Three strategic archetypes dominate: integrated synthetic diamond producers with downstream coating operations, independent CVD job shops accessing capacity through equipment leasing, and precision engineering specialists occupying defensible application niches. Competitive moves concentrate on backward integration into precursor chemical supply and geographic expansion through reactor deployment partnerships.
Within the integrated producer archetype, Element Six and Sumitomo Electric Industries Ltd. anchor European and Asian supply positions respectively. NeoCoat SA occupies a specialist position in nanocrystalline diamond films for photonics applications. These three entities exemplify divergent strategic postures: captive raw material control, in-house substrate development, and application-specific film engineering.
| Leading Market Players |
|---|
| Crystallume Corporation |
| Sumitomo Electric Industries Ltd. |
| Element Six |
| JCS Technologies Pte Ltd. |
| Diamond Product Solutions |
| Sandvik AB |
| NeoCoat SA |
| SP3 Diamond Technologies |
| OC Oerlikon Management AG |
| Others |
Supply & Pricing Matrix
German and Japanese reactor OEM concentration in plasma-enhanced CVD equipment anchors margin capture at the deposition service tier, while Asian job shop fragmentation compresses coating prices through equipment-as-a-service competition.
Pricing Analysis
Certification level creates the primary spread across diamond coatings, with FDA-grade biomedical films commanding premium multiples over industrial cutting tool grades. Three-tier pricing structure across premium quantum-grade, standard thermal management, and economy cutting tool levels stratifies the market. Cost compression in economy-tier polycrystalline diamond coatings is intensifying as Chinese machine tool builders internalize deposition capacity. Automotive machining contractors exhibit highest price sensitivity, while aerospace thermal management programs show lowest elasticity due to qualification switching costs.
Supply Chain Analysis
Tariff exposure between United States and China dominates supply chain risk planning for precursor chemical sourcing and reactor component procurement. Manufacturing concentrates in Germany, Japan, and China, with each hub specializing in distinct equipment tiers and coating service models. The supply chain draws from methane and hydrogen feedstock markets, synthetic diamond substrate suppliers, and plasma generator component manufacturers. Single-source vulnerability concentrates in microwave plasma source technology from Japanese suppliers. Distribution runs through precision engineering clusters rather than broad merchant channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward semiconductor fabrication facilities and precision engineering OEMs as these customers consolidate procurement volumes and internalize coating specifications.
For Market Incumbents: Entrench captive synthetic diamond supply positions through backward integration into methane cracking and substrate production. Sumitomo Electric's in-house polycrystalline diamond substrate development illustrates the defensive value of upstream control. Priority investment targets plasma diagnostics expertise concentration in Tokyo and Stuttgart industrial corridors to lock in operator skill scarcity. For New Entrants and Emerging Players: Establish a beachhead in India's unserved precision engineering market, specifically Pune and Bengaluru machine tool manufacturing clusters. Photonics nanocrystalline diamond films for silicon photonics integration represent the most penetrable premium segment. Go-to-market should leverage equipment-as-a-service partnerships with European reactor OEMs to bypass capital barriers. For Investors and Strategic Acquirers: Capital is best deployed toward deposition service providers with demonstrated FDA 510(k) pathway experience and established thermal management substrate qualifications. Long-term viability over the next decade hinges on positioning for quantum sensing and high-frequency electronics applications. Watch for MIIT directive acceleration in China as the signal for domestic capacity inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Supply | Methane cracking capacity secures margin control against hydrogen feedstock volatility. |
| FDA 510(k) Certification Investment | Biocompatibility validation opens orthopedic surgical instrument revenue pools. |
| Equipment-as-a-Service Deployment | Reactor leasing contracts fragment coating geography while concentrating service revenue. |
| Hybrid Deposition Technology Development | Hot-filament microwave convergence enables polymer substrate expansion for medical devices. |
| REACH Alternative Chemistry Qualification | Boron-free dopant pathways preserve European market access under ECHA reviews. |
Research Methodology
Cross-validation between CVD reactor operator interviews and semiconductor fabrication facility procurement data anchors the qualitative findings. Primary discussions with plasma diagnostics technicians, thermal management substrate specification engineers, cutting tool procurement managers, and medical device regulatory affairs leads combined with secondary review of MIIT directive filings, ECHA registration databases, FDA 510(k) submission logs, and SEC equipment manufacturer disclosures. Bottom-up coating volume estimates from deposition service providers triangulate against top-down semiconductor packaging demand forecasts.
Calibration against historical capacity deployment patterns and qualification timeline benchmarks shapes the analytical framework. Segmentation dimensions span coating type, substrate material pairing, end-use industry certification intensity, and regional regulatory cluster. CAGRs derive from equipment shipment trajectories and substrate specification evolution across the projection horizon. Industry-specific inputs include CVD reactor utilization rates and thermal conductivity specification tightening in advanced packaging.
Stress conditions across methane-hydrogen feedstock pricing spreads, REACH authorization timeline extensions, and FDA biocompatibility validation delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about equipment-as-a-service adoption velocity and domestic manufacturing qualification acceleration in China. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Global Optical Coating Market
Coatings
Global PET Film Coated Steel Coil Market
Coatings
Polysiloxane Coatings Market
Coatings
Electronic Protection Device (EPD) Coatings Market
Coatings
Fluoropolymer Coating Market
Coatings
Waterborne Wood Coatings Market
Coatings
Egyptian Protective Coatings Market
Coatings
China Marine Coatings Market
Coatings
Anti Soiling Coating Market
Coatings
Plastic-Coated Wires Market
Coatings
Anti-Microbial Powder Coatings Market
Coatings
Phosphate Conversion Coatings Market
Coatings
Mexico Floor Coatings Market
Coatings
US Industrial Coatings Market
Coatings
US Protective Coatings Market
Coatings
High Temperature Coatings Market