
 Asia-Pacific Floor Coatings Market | 2026-2036
Asia-Pacific Floor Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Floor Coatings Market Outlook
Modular coating kits combining primer, base coat, and topcoat in single purchase bundles is restructuring buyer procurement patterns across the Asia-Pacific floor coatings market. Sika AG leverages its integrated construction chemicals portfolio to anchor specification decisions in major infrastructure projects. PPG Industries Inc. competes through technology leadership in high-performance polyurethane systems for heavy-traffic environments. Asian Paints Ltd. dominates distribution density in India's tier-two and tier-three manufacturing hubs.
Asia-Pacific floor coatings comprise resin-based protective layers applied to concrete, wood, or metal substrates to resist abrasion, chemical attack, and moisture ingress, with epoxy systems typically achieving dry-film thickness of 250–500 microns in industrial settings. Their primary purpose spans factory floors, warehouse surfaces, healthcare corridors, and retail showrooms where durability and hygiene standards intersect. Epoxy formulations lead volume due to cost-performance ratios in manufacturing end uses, while water-based technology segments gain fastest traction as environmental compliance tightens across the region. UV-cured systems occupy premium niche positions where rapid return-to-service drives specification in retail and healthcare applications.
China's MEE enforces VOC emission ceilings that constrain solvent-based coating production, while India's BIS certification mandates performance testing for industrial floor applications. Japan's METI promotes low-carbon building material standards that favor high-solids and water-borne alternatives in public construction. Australia's TGA-equivalent building code authorities impose slip-resistance benchmarks for healthcare and education facilities. Stakeholders must monitor divergence between national chemical regulations and harmonized ISO performance standards when configuring regional product portfolios and manufacturing footprints.
Market Dynamics
China's MEE is tightening GB standards for volatile organic compound emissions, forcing solvent-based epoxy formulators toward water-borne and high-solids alternatives. This regulatory compression is restructuring raw material procurement and manufacturing footprints across the Asia-Pacific floor coatings supply base.
Growth Catalysts
- Industrial corridor expansion:India's western manufacturing belt from Mumbai to Gujarat is driving protective flooring installations as automotive and chemical processing capacity scales.
- Water-borne technology maturation:Advances in acrylic-epoxy hybrid dispersions are matching solvent-based performance at lower VOC outputs, accelerating specification in food processing and healthcare facilities.
- Japan's METI low-carbon building standards:Public construction mandates favor high-solids systems in government-funded infrastructure, creating preferential procurement pathways for compliant suppliers.
Market Restraints
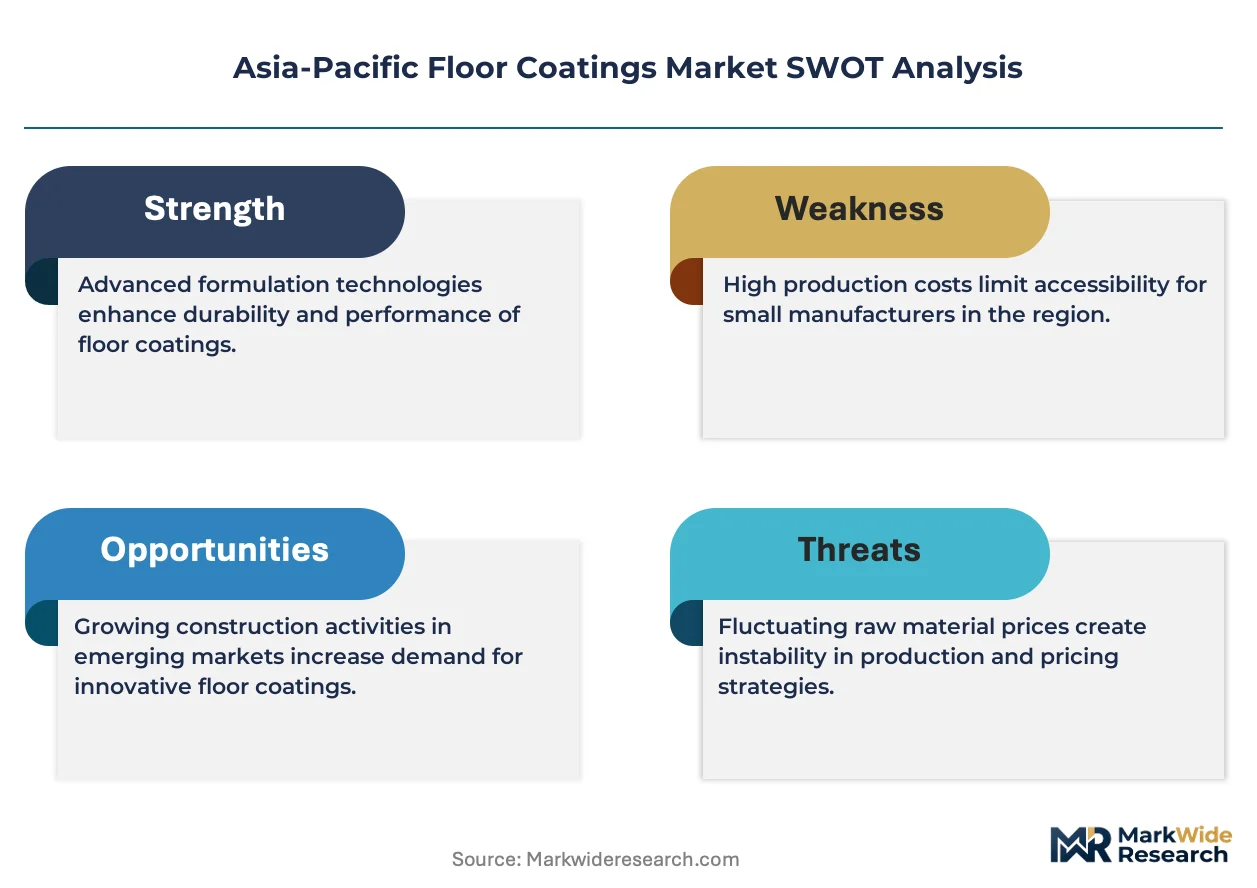
- Petrochemical feedstock volatility:Epoxy resin and isocyanate pricing fluctuates with naphtha and propylene dynamics, compressing margin predictability for formulators.
- Solvent-based capacity stranding:China's GB VOC ceilings threaten solvent-system investments in Shandong and Jiangsu provinces, creating asset write-down risk for non-adaptive producers.
- Concrete polishing substitution:Mechanical densification and diamond grinding systems displace thin-film coatings in warehouse and logistics applications where abrasion resistance is primary.
Strategic Opportunities
- Vietnam's northern industrial zones:Electronics manufacturing migration from China is creating greenfield flooring demand in Bac Ninh and Hai Phong provinces.
- UV-cured system penetration:Rapid return-to-service requirements in retail and healthcare are opening premium niches for photoinitiator-cured polyurethane-acrylates.
- Modular kit bundling:Specification engineers favor integrated primer-base-topcoat packages that reduce contractor procurement complexity and installation failure risk.
Industry Challenges
- Applicator certification gaps:Moisture tolerance testing and film thickness verification require skilled technicians that remain scarce in India's tier-three manufacturing hubs.
- Multi-standard compliance burdens:Divergence between China's GB standards, India's BIS certification, and Australia's slip-resistance benchmarks forces redundant product line configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Floor Coatings Market |
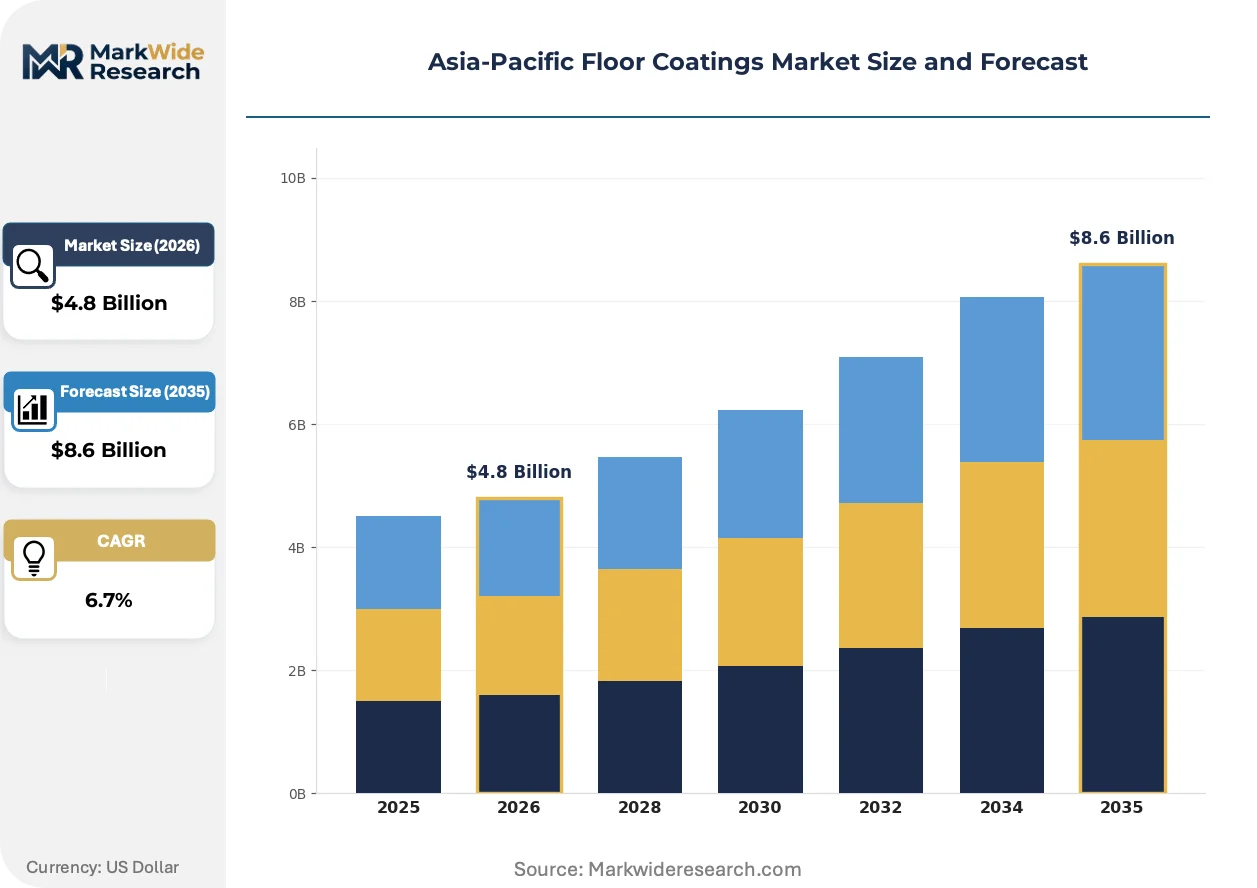
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Polyurethane, Acrylic, Polyester Application: Industrial, Commercial, Residential, Institutional Technology: Water-Based, Solvent-Based, High-Solids, UV-Cured End User: Manufacturing, Retail, Healthcare, Education |
| Companies Covered | Sika AG, The Sherwin-Williams Company, PPG Industries Inc., RPM International Inc., Akzo Nobel N.V., BASF SE, Jotun Group, Asian Paints Ltd., Nippon Paint Holdings Co., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Floor Coatings Market Strategic Shifts
Formulation chemistry and application protocols are converging around speed-to-service and environmental compliance. The competitive frontier has shifted from pure performance metrics to total installation economics and regulatory adaptability.
Hybrid water-borne epoxy-polyurethane systems are unifying the chemical resistance of epoxies with the flexibility and UV stability of polyurethanes in single-coat architectures. Automotive assembly plants in Thailand and Indonesia are specifying these hybrids for paint shop and battery manufacturing areas where thermal cycling and chemical exposure coexist. The technology is unifying what previously required separate base and topcoat applications, compressing labor costs and cure schedules.
Australia's building code authorities have imposed slip-resistance benchmarks for healthcare and education facilities that exceed generic ISO recommendations. Flooring contractors must now submit pendulum test certificates before final payment release, adding documentation overhead to project execution. Epoxy and polyurethane suppliers serving Australian institutional markets are reformulating with aluminum oxide and silicon carbide aggregates to meet the new traction thresholds.
Specification authority is migrating from general contractors to facility engineering departments that demand lifecycle cost documentation. Major warehousing operators in Singapore and South Korea now require year-five appearance and adhesion warranties backed by third-party inspection protocols. This accountability shift favors suppliers with in-house technical service teams capable of substrate moisture mapping and warranty claim administration.
Asia-Pacific Floor Coatings Market Segmentation
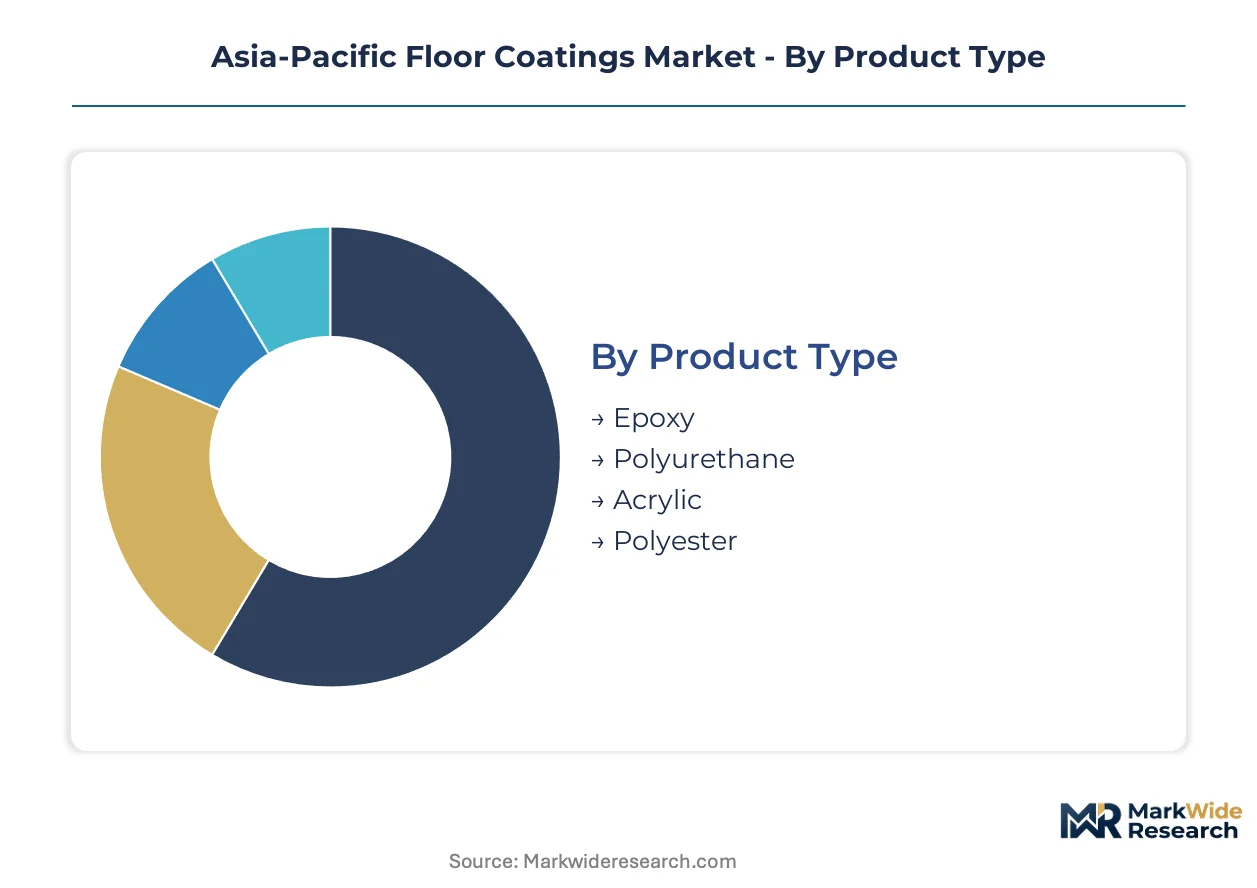
Floor coatings buyers across Asia-Pacific make specification decisions through layered filters: substrate compatibility, regulatory compliance, and lifecycle cost. Segmentation reveals where formulation chemistry, application environment, and procurement authority intersect to determine supplier positioning.
Product Type:
Cost-performance ratios dominate resin selection in manufacturing procurement, with durability thresholds and chemical resistance requirements driving tier-one specifications.
- Epoxy:Two-part thermosetting systems based on bisphenol-A or bisphenol-F resins deliver 250–500 micron dry-film thickness with superior chemical resistance. Demand concentrates in China's Shandong and Jiangsu manufacturing corridors where automotive and electronics assembly plants require abrasion-resistant flooring for heavy machinery zones. China's MEE VOC enforcement is pushing epoxy formulators toward water-borne hybrid variants to maintain specification eligibility in government-funded industrial parks.
- Polyurethane:Aliphatic and aromatic isocyanate-cured systems offer flexibility and UV stability that epoxies lack, making them preferred for topcoat applications in facilities with thermal cycling. India's western industrial belt from Mumbai to Gujarat specifies polyurethane topcoats for chemical processing plants where thermal shock resistance prevents film cracking. Formulators face margin pressure from propylene and MDI feedstock volatility.
- Acrylic:Water-borne acrylic dispersions serve cost-sensitive commercial applications with moderate durability requirements.
- Polyester:Unsaturated polyester systems occupy niche positions in rapid-cure industrial applications where styrene emission controls permit their use.
Volume sits with epoxy systems across manufacturing end uses; growth tilts toward polyurethane as hybrid formulations unify base-coat and topcoat functions.
Application:
Facility type determines performance specifications, warranty expectations, and contractor qualification requirements across the value chain.
- Industrial:Factory floors, warehouse surfaces, and logistics centers demand 5–10 year service life with resistance to forklift traffic, chemical spills, and moisture ingress. China's expanding semiconductor fabrication facilities in Hefei and Xi'an are driving specification of conductive epoxy systems with electrostatic discharge protection. Japan's METI low-carbon building standards favor high-solids industrial systems in public-private manufacturing partnerships.
- Commercial:Retail showrooms, hospitality spaces, and office environments prioritize aesthetics and rapid return-to-service over extreme durability. Australia's slip-resistance benchmarks for commercial spaces exceed ISO recommendations, forcing reformulation with aluminum oxide aggregates.
- Residential:Garage floors and basement sealants represent price-sensitive demand with DIY application prevalence.
- Institutional:Healthcare corridors and education facilities combine hygiene standards with heavy foot traffic resistance.
Industrial applications command premium pricing through specification complexity; commercial segments are expanding most quickly as retail construction accelerates in Vietnam and Indonesia.
Technology:
Environmental compliance timelines and cure-speed requirements are restructuring technology portfolios faster than performance differentiation alone.
- Water-Based:Acrylic-epoxy hybrid dispersions achieve VOC outputs below China's GB standards while matching solvent-based adhesion and chemical resistance. Food processing facilities in Thailand and Indonesia specify water-borne systems to meet HACCP hygiene protocols without extended ventilation periods. Technology maturation is closing the performance gap that previously restricted water-borne systems to light-duty applications.
- UV-Cured:Photoinitiator-activated polyurethane-acrylates cure in seconds under high-intensity UV lamps, enabling same-day return-to-service. Premium retail fit-outs in Singapore and Seoul specify UV systems for minimal revenue disruption during renovation cycles. Capital equipment requirements limit adoption to contractors with dedicated application infrastructure.
- Solvent-Based:Traditional epoxy and polyurethane systems face regulatory compression as China's MEE tightens emission ceilings.
- High-Solids:Reduced-solvent formulations balance compliance and application familiarity for contractors transitioning from solvent-based systems.
Water-based technology holds volume leadership in new specifications; UV-cured systems show the steepest expansion trajectory in premium commercial segments.
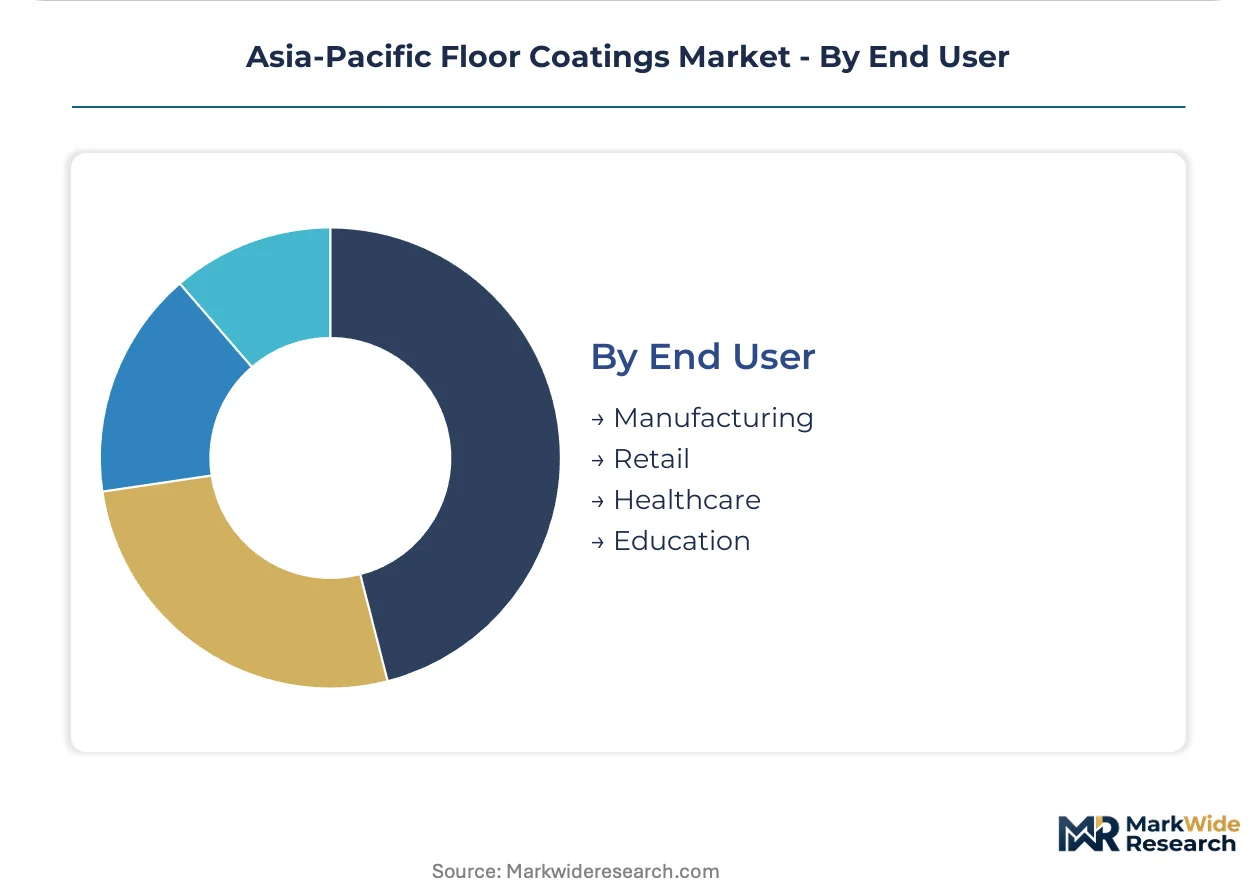
End User:
Procurement authority varies sharply across end users, from facilities engineering departments demanding lifecycle documentation to general contractors prioritizing first-cost minimization.
- Manufacturing:Automotive, electronics, and chemical processing plants require substrate-specific formulations with documented moisture tolerance and warranty-backed performance. Major warehousing operators in South Korea now mandate year-five adhesion testing with third-party inspection protocols. Specification engineers favor modular primer-base-topcoat packages that reduce installation failure risk.
- Healthcare:Hospital corridors, operating theaters, and pharmaceutical cleanrooms demand seamless, hygienic surfaces with chemical resistance to disinfectant protocols. Australia's TGA-equivalent building code authorities impose traction benchmarks that exceed generic standards.
- Retail:Fast-fashion and electronics retailers prioritize rapid installation cycles and visual uniformity across franchise locations.
- Education:School and university facilities balance durability requirements with public procurement budget constraints.
Manufacturing end users dominate value capture through specification complexity; healthcare segments are gaining share fastest as hospital construction expands in India's tier-two cities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Shandong and Jiangsu special economic zones concentrate solvent-based epoxy capacity now facing MEE emission ceiling enforcement, while India's western industrial corridor attracts automotive and chemical processing investment driving protective flooring demand.
China
Semiconductor fabrication facilities in Hefei and Xi'an drive specification of conductive epoxy systems with electrostatic discharge protection. MEE GB standards for VOC emissions are forcing formulators toward water-borne and high-solids alternatives. Shandong and Jiangsu manufacturing corridors face asset write-down risk for non-adaptive solvent-system producers.
India
Automotive assembly plants and chemical processing capacity scaling across Mumbai-Gujarat belt generate protective flooring installations. BIS certification mandates performance testing for industrial floor applications. Tier-two and tier-three manufacturing hubs in Maharashtra and Gujarat concentrate distribution density for domestic suppliers.
Japan
Public-private manufacturing partnerships favor high-solids systems under METI low-carbon building standards. Government-funded infrastructure creates preferential procurement pathways for compliant suppliers. Kanto and Kansai industrial zones specify advanced formulations for electronics and automotive facilities.
South Korea
Major warehousing operators mandate year-five adhesion testing with third-party inspection protocols. Seoul Capital Area logistics centers drive specification complexity through lifecycle cost documentation. Facility engineering departments in Busan-Ulsan manufacturing belt demand substrate moisture mapping services.
Australia
Building code authorities impose slip-resistance benchmarks for healthcare and education facilities exceeding ISO recommendations. Pendulum test certificates are now required before final payment release. Contractors serving Sydney and Melbourne institutional markets reformulate with aluminum oxide aggregates to meet traction thresholds.
Asia-Pacific Floor Coatings Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across formulation chemistry and application service capabilities. The market structure tilts toward consolidation among construction chemicals portfolios that anchor specification decisions in major infrastructure projects. Three archetypes dominate: integrated construction chemicals suppliers, high-performance coatings technology leaders, and regional distribution specialists. Competitive moves concentrate on modular kit bundling strategies and in-house technical service team deployment for warranty claim administration.
Among Swiss and Dutch diversified conglomerates, Sika AG and Akzo Nobel N.V. exemplify integrated construction chemicals portfolios that anchor specification decisions. PPG Industries Inc. represents North American technology leadership in high-performance systems. Asian Paints Ltd. occupies the regional distribution specialist position across India's tier-two and tier-three manufacturing hubs. These three anchors demonstrate how geographic coverage, technology depth, and channel density create distinct competitive positions.
| Leading Market Players |
|---|
| Sika AG |
| The Sherwin-Williams Company |
| PPG Industries Inc. |
| RPM International Inc. |
| Akzo Nobel N.V. |
| BASF SE |
| Jotun Group |
| Asian Paints Ltd. |
| Nippon Paint Holdings Co. |
| Others |
Value Chain & Pricing Dynamics
Epoxy resin and isocyanate feedstock costs cascade from naphtha and propylene volatility through formulation margins to tiered pricing structures downstream, with water-borne technology premiums compressing as environmental compliance deadlines approach across China's Shandong manufacturing belt.
Pricing Analysis
Margin tightening in solvent-based epoxy tiers traces to China's MEE GB VOC enforcement, which forces asset repositioning or write-downs. Three-tier pricing structure across premium, standard, and economy levels separates UV-cured rapid-return systems from high-solids compliance grades and conventional solvent formulations. Price differentiation hinges on certification grade against BIS or METI standards and volume scale in modular kit procurement. Food processing and healthcare buyers demonstrate lowest price sensitivity where HACCP and hygiene protocols dominate specification, while warehouse operators in logistics corridors show highest sensitivity to first-cost minimization.
Supply Chain Analysis
Single-source vulnerability sits with Chinese bisphenol-A resin production concentrated in Shandong and Jiangsu provinces, where MEE emission ceilings threaten capacity continuity. Raw material procurement draws from Saudi propylene derivatives, Korean MDI supply, and domestic Chinese epoxy intermediates. Tariff exposure on specialty isocyanates imported from Japan and Europe compounds margin pressure for polyurethane formulators. Distribution runs through construction chemicals distributors anchored in India's tier-two manufacturing hubs and direct specification relationships with facility engineering departments in South Korean warehousing operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific floor coatings function as a cost-of-compliance market where China's MEE GB VOC ceilings erect regulatory moats favoring water-borne and high-solids investments by incumbent suppliers.
For Market Incumbents: Lock in specification authority through in-house technical service teams capable of substrate moisture mapping and year-five warranty administration. Anchor procurement decisions with modular primer-base-topcoat bundling that reduces contractor installation failure risk. Solvent-based capacity stranding in Shandong and Jiangsu provinces threatens non-adaptive producers, while backward integration into acrylic-epoxy hybrid dispersions secures margin control. For New Entrants and Emerging Players: Begin with Vietnam's northern industrial zones in Bac Ninh and Hai Phong provinces, where electronics manufacturing migration from China creates greenfield flooring demand without entrenched supplier relationships. Target UV-cured system niches in premium retail fit-outs across Singapore and Seoul, where rapid return-to-service requirements justify capital equipment investment and technical service premiums. Pursue specification partnerships with facility engineering departments rather than general contractor channels to capture lifecycle cost documentation requirements. For Investors and Strategic Acquirers: BIS certification expansion beyond India's western corridor into Maharashtra and Gujarat tier-three hubs is the leading indicator that distribution density advantages will compound for compliant domestic suppliers. The five-to-ten year viability window favors acquisition of regional specialists with water-borne formulation capabilities and established applicator certification programs. Watch for METI low-carbon building standard adoption rates in Japanese public-private manufacturing partnerships as the signal for high-solids technology preference shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic-Epoxy Hybrid Resins | Captures margin from naphtha volatility while securing water-borne formulation supply against MEE enforcement. |
| Applicator Certification Program Expansion | Addresses moisture tolerance testing scarcity in India's tier-three manufacturing hubs to reduce installation failure rates. |
| Modular Kit Bundling with Third-Party Inspection Protocols | Aligns with South Korean warehousing operator demands for year-five adhesion documentation and warranty claim administration. |
| UV-Cured System Capital Equipment Deployment | Enables same-day return-to-service capture in Singapore and Seoul premium retail segments with dedicated contractor infrastructure. |
| Long-Term Supply Agreement with Electronics Manufacturing Tenants | Secures flooring specification in Vietnam's Bac Ninh and Hai Phong industrial zones before competitor entrenches. |
Study Parameters
Multi-period observation of formulation technology maturation, regulatory enforcement timelines, and procurement pattern shifts anchored the trend analysis, supplemented by interviews with plant engineers at automotive assembly facilities, procurement leads at chemical processing operators, distribution channel partners in India's western corridor, and technical R&D directors at construction chemicals suppliers. Secondary validation drew from China's MEE emission disclosure filings, India's BIS certification registries, Japan's METI low-carbon building material standards documentation, customs and trade data on epoxy resin and isocyanate flows, and SEC 10-K construction chemicals segment disclosures. Bottom-up project pipeline enumeration and top-down regional construction spend estimates were triangulated against formulation chemistry adoption curves.
Segment-weighting across product type, application environment, technology platform, and end-user procurement authority structured the analytical framework. Resin chemistry splits, facility-type demand distributions, and compliance-technology substitution rates were modeled across the projection horizon. CAGRs were derived from regression analysis of historical specification volumes against industrial construction permit data and manufacturing capacity expansion announcements. Feedstock price elasticity and regulatory deadline acceleration scenarios informed scenario-band outputs.
Petrochemical feedstock volatility, regulatory enforcement acceleration beyond published timelines, and concrete polishing substitution rates in warehouse applications are the dominant revision risks that could compress or expand addressable coating volumes. Forecasts reflect assumptions about technology performance convergence and contractor certification availability that may shift with training program investments. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Wood Preservative Coatings Market
Coatings
Japan Architectural Coatings Market
Coatings
Global Smart Coating Market
Coatings
Waterproof Coating Market
Coatings
US Antifouling Yacht Coatings Market
Coatings
Physical Vapor Deposition (PVD) Coatings Market
Coatings
North America Coil Coatings Market
Coatings
Chemical Resistant Coatings Market
Coatings
Cladding Coatings Market
Coatings
Fire Retardant Coatings Market
Coatings
North America Powder Coatings Market
Coatings
Russia Protective Coatings Market
Coatings
OEM Coatings Market
Coatings
Liquid-Applied Roof Coating Market
Coatings
Architectural Metal Coatings Market
Coatings
Africa Automotive Refinish Coatings Market