
 1-Hexene Based Polyethylene Market | 2026-2036
1-Hexene Based Polyethylene Market Size, Share, and Industry Trends Forecast 2026-2036
1-Hexene Based Polyethylene Market Insights
Performance-linked polymer subscriptions tied to melt-index guarantees is restructuring how resin contracts get priced and renewed. Chevron Phillips Chemical leverages its Cedar Bayou alpha-olefin integration to control feedstock costs across the Gulf Coast. Sinopec anchors domestic supply through its Ningbo and Tianjin complexes. Dow differentiates via its Elite enhanced polyethylene platform for demanding film applications.
1-Hexene based polyethylene denotes ethylene copolymers incorporating six-carbon alpha-olefin comonomer at 1-10 mole percent, produced via solution or gas-phase processes with densities spanning 0.890-0.940 g/cm³, serving primarily as puncture-resistant film and durable molded goods. Linear low-density polyethylene leads volume owing to stretch-wrap and heavy-duty sack demand, while ultra-low-density polyethylene captures expanding interest in soft-touch consumer goods where flexibility thresholds are rising. High-density polyethylene occupies mature infrastructure pipe and crate segments where margin compression is structural.
EPA emissions rules under the Clean Air Act constrain crackers in Texas and Louisiana, pushing operators toward lower-intensity catalyst systems. REACH registration requirements in Europe govern 1-hexene monomer imports and copolymer formulations for consumer contact applications. China's MEE enforces carbon-intensity benchmarks on new petrochemical capacity approvals. Stakeholders must weigh feedstock-advantaged positions against regulatory capital burdens as comonomer flexibility becomes a procurement priority.
Market Dynamics
Metallocene catalyst systems are displacing Ziegler-Natta platforms across new polyethylene capacity, compressing conversion costs while tightening comonomer flexibility requirements for resin producers.
Growth Catalysts
- Stretch-wrap film demand:E-commerce fulfillment centers in China and the United States are consuming linear low-density grades for pallet stabilization, pulling volume from conventional low-density alternatives.
- REACH registration clarity:ECHA's finalized monomer purity thresholds have streamlined 1-hexene import protocols for European compounders, reducing formulation approval timelines.
- Alpha-olefin integration:Gulf Coast crackers with captive hexene supply are capturing margin expansion unavailable to merchant-feed buyers in Northeast Asia.
Market Restraints
- Crude-alpha-olefin price linkage:Naphtha volatility transmits directly to 1-hexene contract pricing, compressing resin margins during upstream spikes.
- China coastal concentration:Zhejiang and Jiangsu provinces host over sixty percent of Asian derivative capacity, creating single-geography supply risk.
- Propylene-based polypropylene substitution:Random copolymer grades are capturing soft-touch packaging applications previously served by ultra-low-density polyethylene.
Strategic Opportunities
- India's packaging modernization:FSSAI-mandated food-contact compliance deadlines are accelerating converter upgrades toward certified metallocene grades.
- Automotive interior soft-touch surfaces:Dashboard and door-panel applications are specifying ultra-low-density polyethylene for haptic performance.
- Digital resin procurement platforms:Spot-market transparency tools are enabling mid-tier converters to optimize inventory against melt-index guarantee contracts.
Industry Challenges
- Metallocene catalyst sourcing:Limited qualified suppliers for single-site systems create procurement bottlenecks during capacity ramp-ups.
- Legacy equipment retrofit costs:Gas-phase reactor modifications for comonomer flexibility require capital commitments that strain regional compounder balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 1-Hexene Based Polyethylene Market |
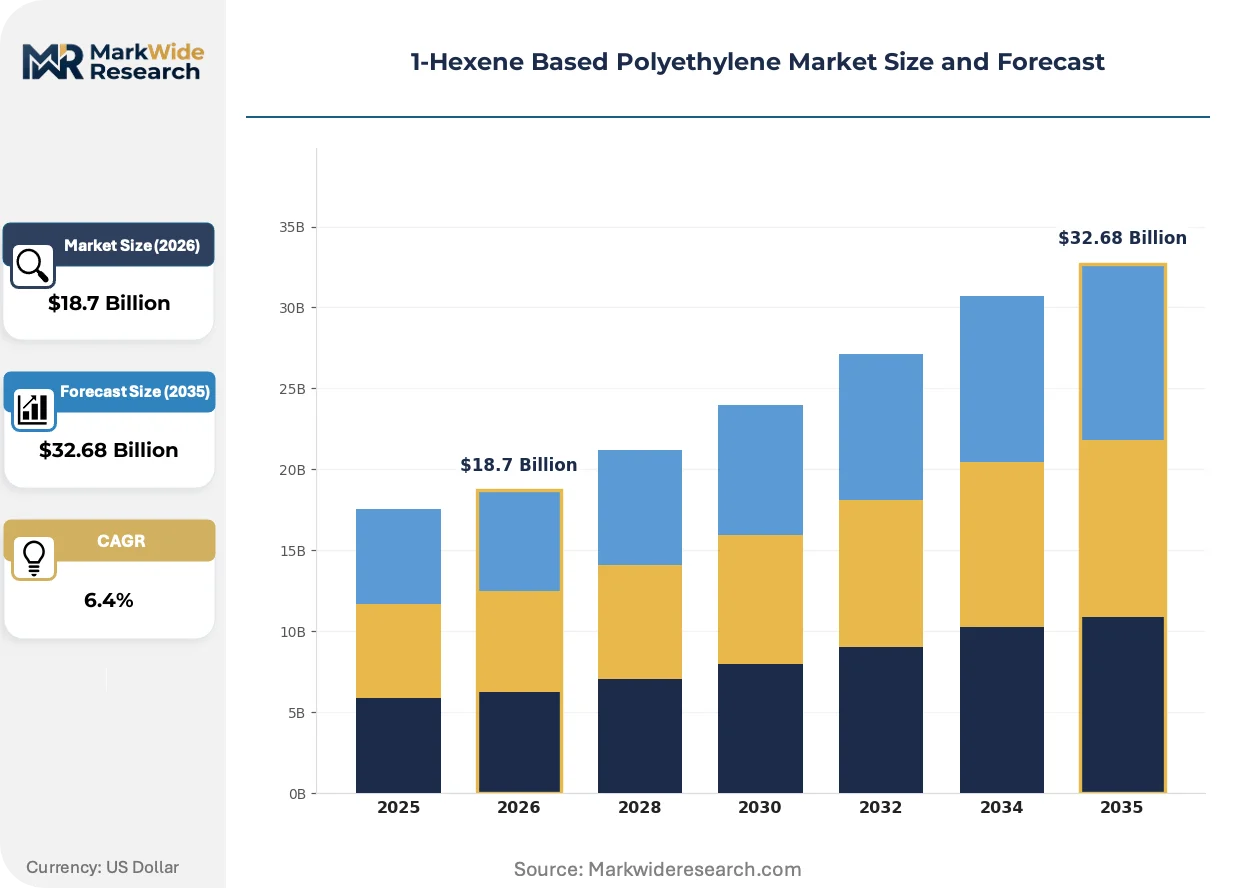
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Low-Density Polyethylene, High-Density Polyethylene, Linear Low-Density Polyethylene, Ultra-Low-Density Polyethylene End User: Packaging, Automotive, Consumer Goods, Construction Application: Film, Injection Molding, Blow Molding, Coatings Distribution Channel: Online Sales, Retail Stores, Distributors, Direct Sales |
| Companies Covered | Chevron Phillips Chemical, Hanwha, ExxonMobil, Sinopec, Mitsui Chemicals, Dow, Eastman, SABIC, LyondellBasell, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
1-Hexene Based Polyethylene Market Trends and Innovations
Digital process control and molecular architecture engineering are converging to enable property-specific resin design, moving polyethylene from commodity specification toward application-tailored performance grades.
Single-site metallocene catalyst technology is integrating advanced comonomer distribution control into solution-phase reactors. Film converters serving fresh-produce packaging are adopting these grades at accelerating rates. The technology is integrating precision property targeting that compresses development cycles for custom formulations.
EPA emissions enforcement under the Clean Air Act is tightening cracker operating permits in Texas and Louisiana. Operators face capital allocation toward emission control systems or catalyst intensity reductions. The regulatory pressure is concentrating new capacity investment in regions with lower carbon-intensity benchmarks.
Performance-guarantee contracts are replacing volume-based resin purchasing among major packaging converters. Melt-index consistency thresholds now determine contract renewal terms rather than spot-price differentials. This behavioral shift is most visible in China's coastal petrochemical clusters where integrated buyers possess laboratory verification capabilities.
1-Hexene Based Polyethylene Market Segmentation
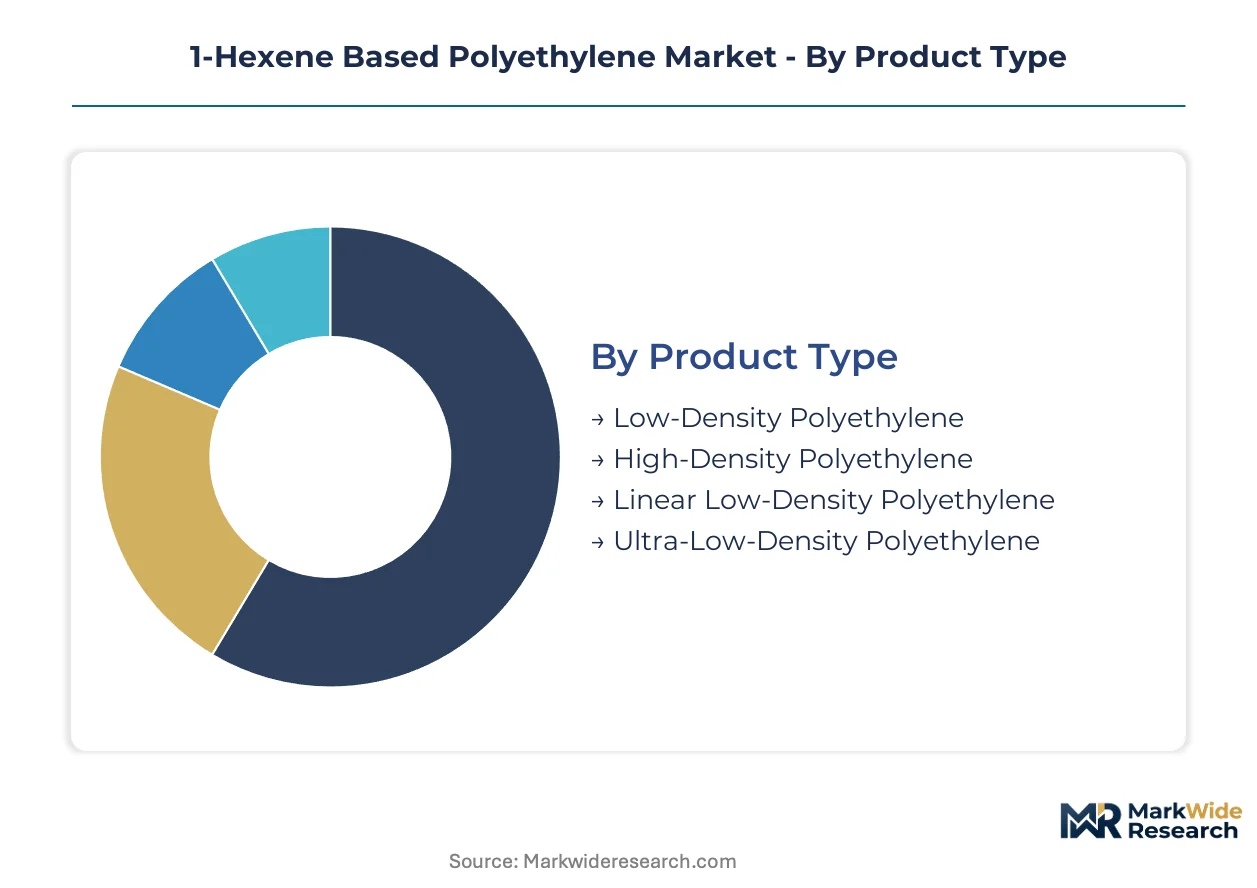
Comonomer flexibility requirements and catalyst technology choices fragment the 1-hexene based polyethylene landscape into distinct performance tiers. Each segment commands different margin structures and procurement protocols based on density specifications and end-use certification demands.
Product Type:
Supply concentration in metallocene-capable production lines favors certain density grades over legacy Ziegler-Natta output.
- Linear Low-Density Polyethylene:Ethylene-1-hexene copolymers at 0.915-0.925 g/cm³ density dominate stretch-wrap and heavy-duty sack applications. E-commerce fulfillment centers in China's coastal provinces pull volume from conventional low-density alternatives as pallet stabilization standards tighten.
- Ultra-Low-Density Polyethylene:Grades below 0.915 g/cm³ enable soft-touch haptic performance in premium consumer goods. Automotive interior specifications for dashboard and door-panel surfaces are expanding specification sheets at German OEMs.
- Low-Density Polyethylene:Conventional autoclave and tubular reactor output serves legacy film and coating applications where melt-index consistency matters less than price.
- High-Density Polyethylene:Mature infrastructure pipe and industrial crate segments face structural margin compression as propylene-based random copolymers capture adjacent applications.
Today's leader: Linear Low-Density Polyethylene. Tomorrow's challenger: Ultra-Low-Density Polyethylene.
End User:
Customer procurement sophistication determines contract structures across converter tiers.
- Packaging:Stretch-wrap demand from fulfillment centers and fresh-produce film converters anchors volume. FSSAI-mandated food-contact compliance in India is accelerating upgrades toward certified metallocene grades.
- Automotive:Interior soft-touch surfaces specify ultra-low-density grades for haptic performance. Tier-1 suppliers in Stuttgart and Detroit are qualifying new resin sources against OEM durability protocols.
- Consumer Goods:Personal care and household product packaging favors clarity and sealability in blow-molded bottles.
- Construction:Pipe and geomembrane applications demand long-term stress-crack resistance certification.
Packaging commands present volume leadership. Automotive interior applications are climbing the fastest.
Application:
Processing method compatibility dictates comonomer distribution requirements and catalyst selection.
- Film:Cast and blown film lines serving produce packaging and industrial wrap consume the majority of linear low-density output. Metallocene grades with narrow molecular weight distribution are displacing conventional resins at European converters.
- Injection Molding:Durable goods and crate manufacturing favor higher-density grades with stiffness thresholds.
- Blow Molding:Bottle and container applications balance impact resistance against parison sag control.
- Coatings:Extrusion coating for paper and board lamination requires specific melt-index ranges for adhesion performance.
Film extrusion maintains the steepest expansion trajectory. Injection molding faces substitution pressure from polypropylene in rigid packaging.
Distribution Channel:
Converter scale and technical service requirements split procurement patterns across channel types.
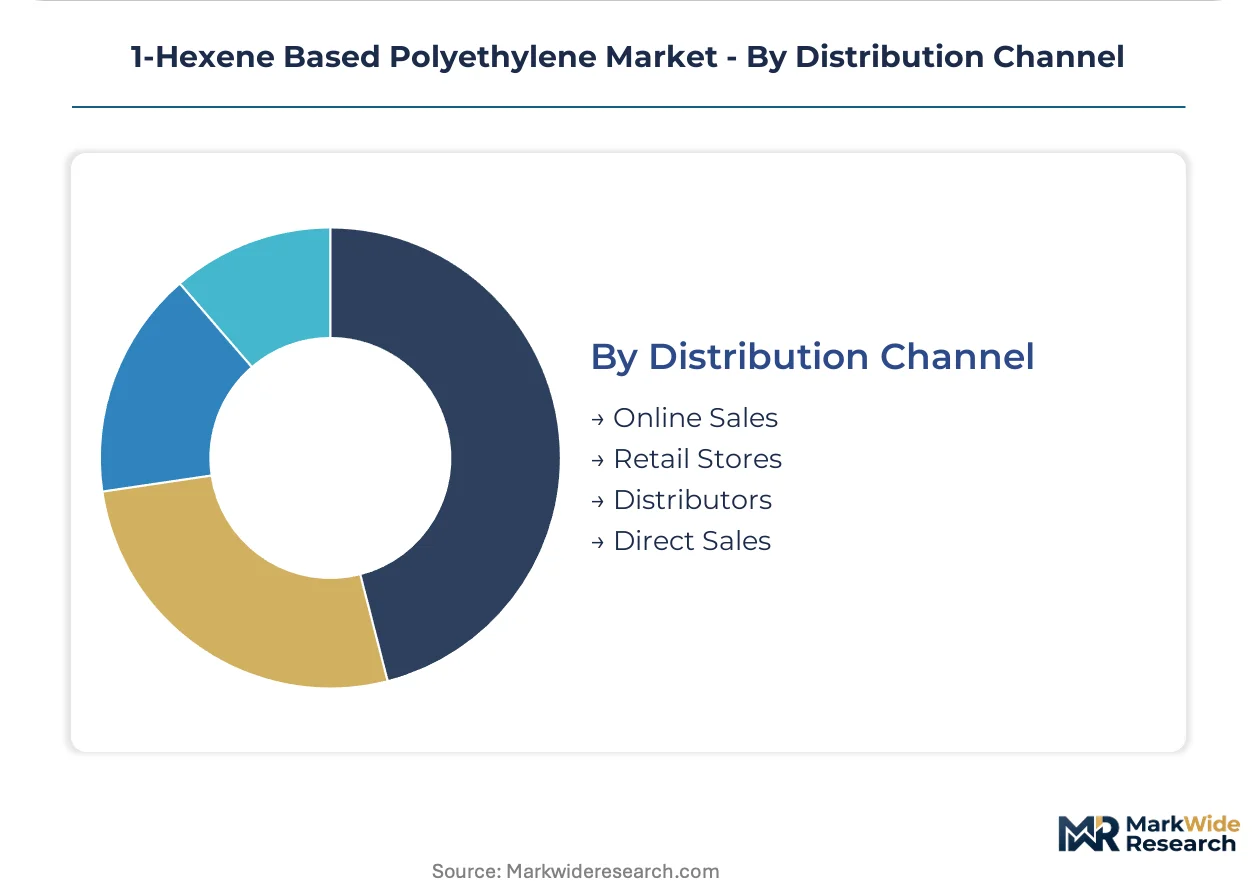
- Distributors:Regional stocking points serve mid-tier converters lacking laboratory verification capabilities. Inventory pooling reduces working capital burdens for compounders in India's packaging modernization push.
- Direct Sales:Integrated crackers and major resin producers contract directly with multinational packaging groups. Melt-index guarantee terms and performance-linked subscriptions dominate these relationships.
- Online Sales:Spot-market transparency tools enable small-batch procurement against volatile raw material positions.
- Retail Stores:Limited to specialty grades and small-volume technical compounds for R&D sampling.
Distributor relationships anchor current procurement volume. Direct sales channels are gaining share fastest as performance-guarantee contracts proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting polyethylene investment toward jurisdictions with lighter carbon-intensity benchmarks. Gulf Coast operators absorb EPA compliance costs while Asian producers face MEE-mandated efficiency thresholds. European compounders navigate REACH registration complexity that slows formulation approvals.
United States
Stretch-wrap demand from e-commerce fulfillment centers in Texas and Georgia consumes linear low-density grades. EPA emissions enforcement under the Clean Air Act constrains cracker operating permits in Texas and Louisiana. Cedar Bayou and Baytown petrochemical clusters anchor alpha-olefin integration strategies that control feedstock costs.
China
Coastal packaging converters in Zhejiang and Jiangsu provinces expand orders for metallocene-certified film grades. MEE carbon-intensity benchmarks govern new petrochemical capacity approvals with stringent efficiency floors. Ningbo and Tianjin complexes anchor domestic supply chains through integrated crackers feeding derivative units.
Germany
Automotive interior specifications from Stuttgart OEMs specify ultra-low-density polyethylene for dashboard haptic performance. ECHA finalized monomer purity thresholds under REACH that streamlined 1-hexene import protocols. Ruhr industrial corridor compounders qualify resin sources against durability protocols for Tier-1 suppliers.
Saudi Arabia
Construction pipe and geomembrane applications demand long-term stress-crack resistance certification for infrastructure projects. SAMR-aligned standards facilitate polymer exports toward Asian markets with harmonized testing regimes. Jubail petrochemical cluster leverages feedstock advantages from associated gas reserves.
India
FSSAI-mandated food-contact compliance deadlines accelerate converter upgrades toward certified metallocene grades. BIS certification requirements govern resin imports for consumer packaging applications. Maharashtra and Gujarat industrial corridors host mid-tier compounders adopting digital procurement platforms for inventory optimization.
1-Hexene Based Polyethylene Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments. Integrated petrochemical majors with captive alpha-olefin supply command margin structures unavailable to merchant-feed compounders. Three archetypes dominate: Gulf Coast crackers with backward integration into hexene production, Asian state-backed producers with coastal cluster density, and European specialists with REACH-compliant formulation expertise. Capacity expansion and catalyst technology licensing represent the dominant competitive vectors.
Among North American integrated producers, Chevron Phillips Chemical and Dow exemplify the captive-feedstock archetype through Gulf Coast alpha-olefin integration. Sinopec occupies a position within the state-backed coastal cluster model. These three anchors illustrate how geographic feedstock positioning and regulatory compliance capabilities determine competitive standing without requiring identical strategic postures.
| Leading Market Players |
|---|
| Chevron Phillips Chemical |
| Hanwha |
| ExxonMobil |
| Sinopec |
| Mitsui Chemicals |
| Dow |
| Eastman |
| SABIC |
| LyondellBasell |
| Others |
Pricing and Supply Chain Analysis
Metallocene-grade certification tiers bifurcate procurement economics, with melt-index guarantee contracts commanding premium positioning against spot-market Ziegler-Natta alternatives. This divergence manifests in direct sales channels anchoring integrated producer margins while distributor networks absorb working capital burdens for mid-tier compounders lacking laboratory verification capabilities.
Pricing Analysis
Distributor margin compression defines the channel layer, with stocking points pooling inventory for converters in India's packaging modernization corridor. Contract-based long-term offtake dominates multinational procurement, where volume scale and REACH registration status drive price differentiation. Cost compression in conventional low-density grades is intensifying because propylene-based random copolymers capture soft-touch applications. Merchant-feed compounders in Northeast Asia exhibit highest price sensitivity; Gulf Coast crackers with captive hexene supply show least.
Supply Chain Analysis
Alpha-olefin feedstock rests on Gulf Coast petrochemical clusters, Chinese coastal provinces, and Saudi associated gas reserves. Naphtha crackers, metallocene catalyst systems, and comonomer distribution equipment constitute critical input dependencies. Single-source vulnerability concentrates in qualified single-site catalyst suppliers during capacity ramp-ups. Distribution runs through direct sales channels for integrated buyers and regional distributor networks for mid-tier compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Quality specifications are hardening across stretch-wrap and automotive interior applications, elevating resin procurement toward performance-guaranteed metallocene grades. This demand-shift rewards producers with backward integration into alpha-olefin supply and laboratory certification capabilities.
For Market Incumbents: Extend catalyst technology licensing programs to compounders retrofitting gas-phase reactors for comonomer flexibility. Deepen captive hexene production at existing Gulf Coast crackers to defend margin position against merchant-feed buyers facing naphtha volatility. Prioritize FSSAI pre-certification for Indian distributor networks ahead of food-contact compliance deadlines.
For New Entrants and Emerging Players: Begin with automotive interior soft-touch specifications where German OEMs are qualifying new resin sources against durability protocols. India's packaging modernization corridor offers the most penetrable geography, with mid-tier compounders adopting digital procurement platforms. A technical service partnership with laboratory-equipped distributors enables market entry without capital-intensive reactor assets.
For Investors and Strategic Acquirers: Consolidation pressure builds where regional compounders lack backward integration into alpha-olefin supply and face stranded asset risk from metallocene displacement. Long-term viability favors producers with coastal cluster density and REACH-compliant formulation expertise. Watch catalyst system procurement bottlenecks during announced capacity ramp-ups as an inflection signal for margin compression timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alpha-Olefin Supply | Cedar Bayou and Baytown complexes demonstrate margin capture unavailable to merchant-feed buyers. |
| Metallocene Catalyst Technology Licensing | Single-site system suppliers enable compounder retrofit programs for comonomer flexibility. |
| Long-term Supply Agreement | Melt-index guarantee contracts with Chinese coastal converters lock volume against spot volatility. |
| Green Manufacturing Transition | Lower-intensity catalyst systems satisfy EPA emissions enforcement under the Clean Air Act. |
| Joint Venture | Ningbo and Tianjin complexes anchor Sinopec's domestic supply chain through integrated crackers. |
Research Methodology
Multiple input streams — plant manager interviews at Gulf Coast crackers, procurement lead discussions at European film converters, and technical R&D director consultations — were reconciled against customs and trade data, ACC and Cefic industry reports, and SEC 10-K filings from integrated producers. Bottom-up resin volume estimates from end-use application modeling were triangulated with top-down capacity assessments across named petrochemical clusters.
Data-stream reconciliation anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include density grade tier, end-use industry, catalyst technology type, and regional production hub. CAGRs were derived from elasticity-adjusted demand projections and announced capacity additions. Industry-specific forecast inputs incorporated MEE carbon-intensity benchmark trajectories and REACH registration timeline assumptions.
Caveats apply where naphtha price volatility, catalyst supply bottlenecks, or regulatory approval delays could materially shift the outlook. Forecasts reflect assumptions about e-commerce fulfillment center expansion rates and automotive interior specification adoption curves. A small set of named triggers — EPA enforcement intensity, FSSAI compliance deadline adherence, and German OEM qualification timelines — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Europe Polymer Emulsion Market
Polymers & Resins
Polyalkylene Glycols (Pags) Market
Polymers & Resins
Polyacrylic Acid Market
Polymers & Resins
Africa Polyether Ether Ketone (PEEK) Market
Polymers & Resins
Resin Glue Market
Polymers & Resins
Global Polybutene Market
Polymers & Resins
Polymer Antioxidants Market
Polymers & Resins
Polycide Market
Polymers & Resins
Marine-grade Polyurethane Market
Polymers & Resins
Polyamide 12 Market
Polymers & Resins
Cast Polymers Market
Polymers & Resins
Thermoplastic Polyamide Elastomer (TPE) Market
Polymers & Resins
Poly (1-Decene) Market
Polymers & Resins
Copolyesters Market
Polymers & Resins
France Engineering Plastics Market
Polymers & Resins
Global Liquid Crystal Polymer (LCP) Market