
 Global Polyphenylene Market | 2026-2036
Global Polyphenylene Market Size, Share, and Industry Trends Forecast 2026-2036
Global Polyphenylene Market Foresight
Specialized polymer engineering talent is redrawing competitive boundaries as formulation complexity rises. Toray Industries leverages its integrated resin-to-compound pipeline to dominate high-heat automotive grades. Solvay anchors European supply through backward integration into para-dichlorobenzene precursors. SABIC competes aggressively in the Middle East with advantaged feedstock access and expanding compounding capacity.
Polyphenylene denotes a class of aromatic thermoplastics characterized by repeating phenylene ring linkages, with glass transition temperatures ranging from 150°C to 220°C depending on substitution pattern and backbone chemistry. These polymers deliver dimensional stability, inherent flame resistance, and chemical inertness for electrical insulation, structural aerospace components, and corrosive process environments. Polyphenylene sulfide leads volume owing to its cost-performance balance in automotive sensor housings and connector bodies. Polyphenylene ether occupies premium margin pools in consumer electronics where dielectric properties and low moisture uptake command specification adherence. Molded parts capture growing share as OEMs seek to consolidate multi-piece metal assemblies into single polymer components.
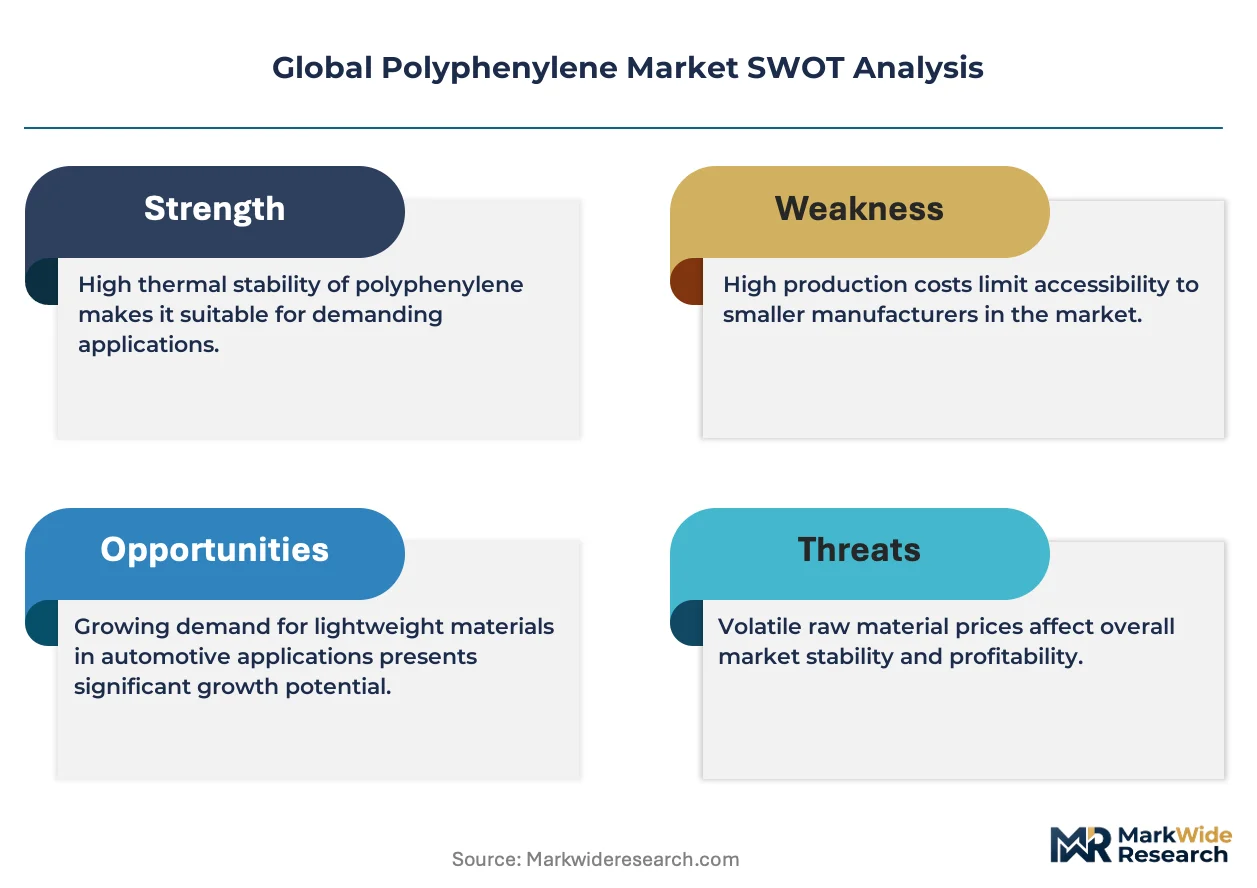
EPA regulations on per- and polyfluoroalkyl substances are forcing reformulation of legacy flame-retardant packages in US-sold compounds. REACH restrictions on halogenated additives in Europe redirect R&D toward phosphorus-based and inorganic synergist systems. China's SAMR enforces GB standards for electrical appliance safety that elevate tracking resistance requirements for connector materials. Buyers must monitor regulatory divergence across these jurisdictions to avoid stranded inventory and qualification delays.
Market Dynamics
Automotive electrification is compressing thermal management design cycles and forcing polymer suppliers to validate high-heat grades against accelerated OEM qualification timelines. This pressure is redrawing supplier-OEM relationships and concentrating procurement authority among integrated resin compounders.
Growth Catalysts
- REACH flame-retardant restrictions:European ECHA mandates on halogenated additives are redirecting formulation R&D toward phosphorus-based systems, expanding addressable demand for inherently fire-resistant polyphenylene backbones.
- EV battery module housings:Automotive OEMs specify polyphenylene sulfide for cell-to-pack structural components requiring 180°C continuous service temperature and electrolyte resistance.
- Japan's electronics corridors:METI-supported reshoring of semiconductor packaging substrate production is pulling high-purity polyphenylene ether into BT laminate replacement trials.
Market Restraints
- Para-dichlorobenzene supply concentration:Over sixty percent of merchant precursor capacity sits in China's Shandong and Jiangsu provinces, exposing compounders to export license volatility and freight cost spikes.
- PPS crystallization kinetics:Narrow processing windows require precision temperature control that legacy injection molding infrastructure cannot achieve without substantial retrofit investment.
- Polyetherimide substitution:SABIC's Ultem grades penetrate connector applications at 15-20 percent lower specific cost, pressuring PPS pricing in mid-tier automotive sensor housings.
Strategic Opportunities
- India's PLI scheme for electronics:Contract manufacturers expanding smartphone and laptop assembly in Tamil Nadu and Karnataka require localized supply of high-flow PPS grades for miniaturized connectors.
- US IRA clean energy manufacturing credits:Domestic content bonuses for solar inverters and EV chargers incentivize reshoring of polyphenylene compound production to Texas and South Carolina.
- Metal-to-polymer consolidation:HVAC and appliance OEMs are redesigning multi-piece brass valve assemblies into single-shot PPS components, opening white space in residential heat pump markets.
Industry Challenges
- Polymer rheology modeling expertise:The talent pool for predictive simulation of fiber-reinforced PPS flow in thin-wall geometries is concentrated among a handful of German and Japanese engineering consultancies, creating recruitment bottlenecks.
- UL 94 V-0 requalification timelines:EPA-driven reformulation of legacy flame-retardant packages requires 18-24 month recertification cycles that delay new compound introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Polyphenylene Market |
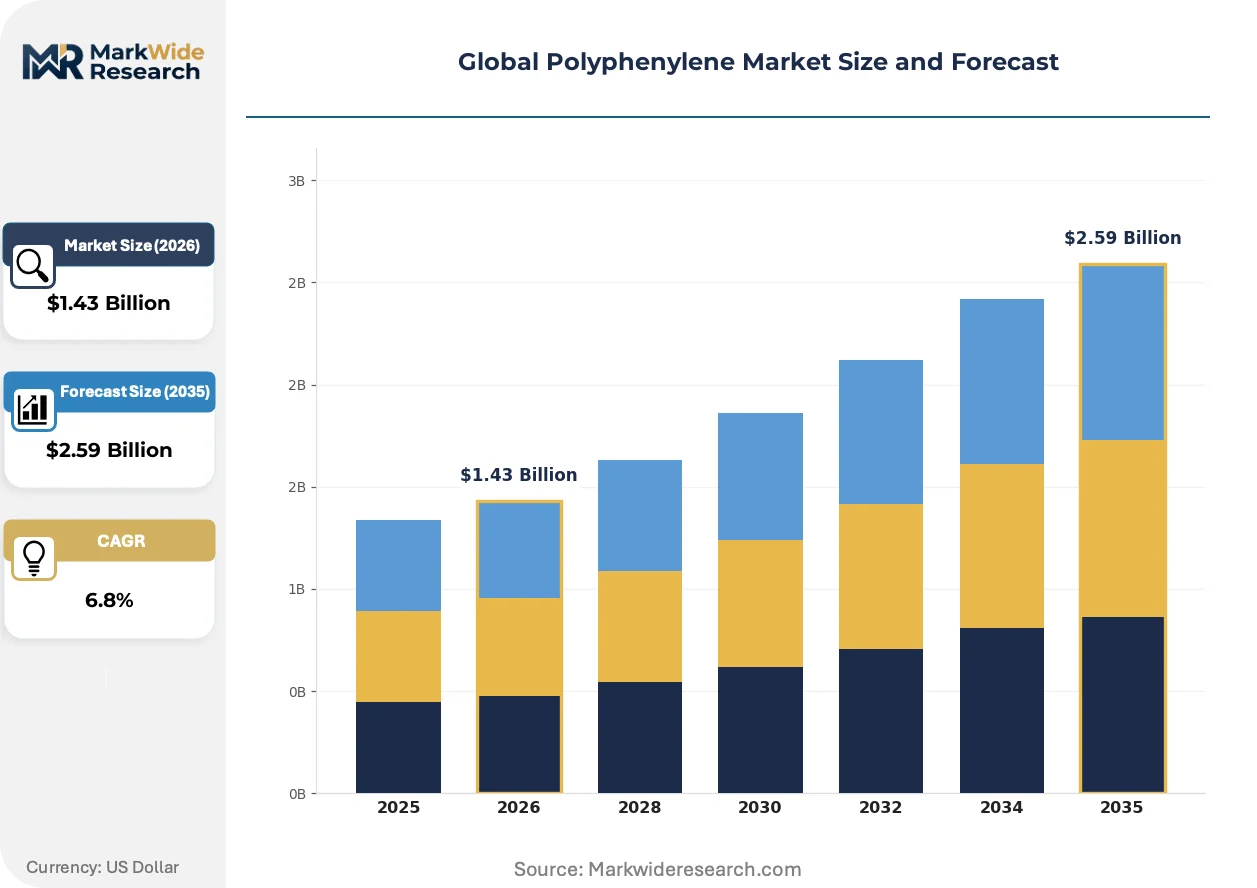
| Market Size in 2026 | $1.43 Billion |
| Market Size in 2035 | $2.59 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyphenylene Ether, Polyphenylene Sulfide, Polyphenylene Oxide, Polyphenylene Sulfide Copolymers Application: Electrical Components, Aerospace Parts, Consumer Electronics, Chemical Processing Equipment End User Industry: Automotive OEMs, Electronics Manufacturers, Chemical Producers, Aerospace Fabricators Form: Pellets, Powder, Films, Molded Parts |
| Companies Covered | Toray Industries, Solvay, DIC Corporation, Kureha Corporation, LG Chem, Celanese Corporation, SABIC, Ensinger, Tosoh Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Polyphenylene Market Shifts & Advancements
Material science convergence with digital manufacturing is collapsing traditional development cycles and enabling part complexity that was previously uneconomical at scale. These shifts are restructuring how specifications propagate from OEM engineering desks to resin compounders.
Long-fiber thermoplastic PPS compounds are miniaturizing automotive under-hood electrical connectors while maintaining creep resistance. Tier-1 suppliers in Germany and Japan are adopting these grades for 48V mild-hybrid architectures. The technology is compressing the number of separate components in power distribution units from twelve-piece assemblies to three integrated modules.
EPA regulations on per- and polyfluoroalkyl substances are forcing systematic reformulation of legacy flame-retardant packages in US-sold compounds. Compounders must validate phosphorus-nitrogen synergist systems without sacrificing tracking resistance or color stability. Electrical connector manufacturers serving appliance and industrial motor markets face the steepest requalification burdens.
Consolidated procurement desks at major automotive OEMs are compressing supplier qualification timelines from thirty-six months to eighteen months. Tier-2 compounders without captive resin production are losing access to platform engineering teams. This concentration is most visible in Germany's automotive belt where Volkswagen, BMW, and Mercedes-Benz have centralized polymer specification authority.
Global Polyphenylene Market Segmentation
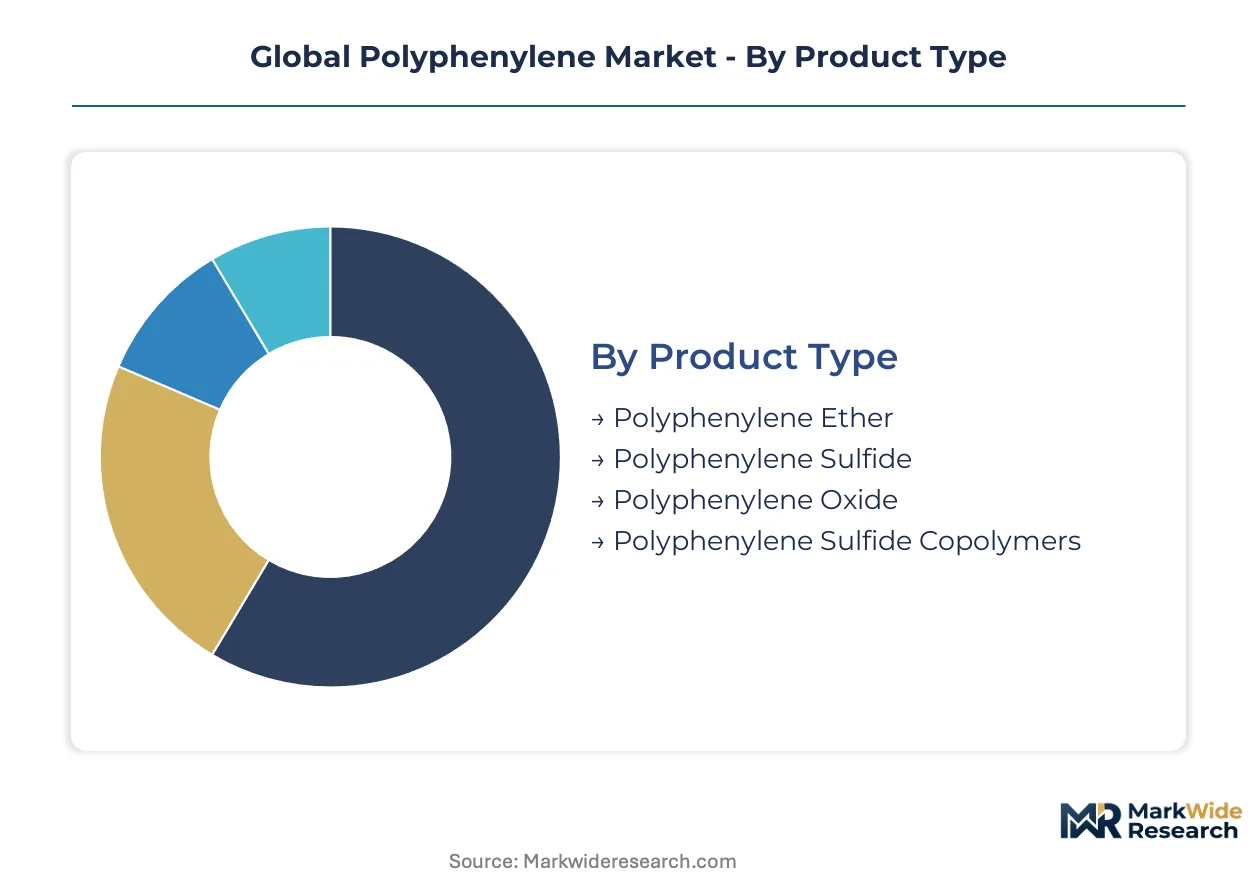
Polyphenylene chemistry varies dramatically across backbone structures, creating distinct specification tiers that flow through specialized distribution channels. Compounders and OEM procurement desks track these segments separately because thermal performance, flame resistance, and processing windows diverge significantly.
Product Type:
High-heat automotive grades move through resin compounders with captive polymerization capacity, while specialty electronics grades route through distributors serving semiconductor packaging substrate manufacturers.
- Polyphenylene Sulfide:Semi-crystalline thermoplastic with melting points near 285°C and excellent chemical resistance to automotive fluids. Demand concentrates in Germany's automotive belt for under-hood sensor housings and 48V mild-hybrid connector bodies, driven by OEM consolidation of multi-piece metal assemblies into single polymer components.
- Polyphenylene Ether:Amorphous polymer with low dielectric constant and minimal moisture absorption, suited to high-frequency electronics. Japan's electronics corridors pull this grade for BT laminate replacement trials in semiconductor packaging substrates, supported by METI-backed reshoring initiatives.
- Polyphenylene Oxide:High glass transition temperature variant offering dimensional stability in precision electrical insulation. Specified for industrial motor housings requiring long-term thermal aging resistance.
- Polyphenylene Sulfide Copolymers:Modified backbones engineered for improved melt flow in thin-wall geometries. Targeted at miniaturized automotive connectors where fiber-reinforced grades face processing constraints.
Polyphenylene sulfide dominates installed base. Polyphenylene ether is where expansion concentrates.
Application:
Application segments stratify by performance certification requirements and OEM qualification timelines, with automotive and aerospace demanding the longest validation cycles.
- Electrical Components:Connectors, relays, and circuit breakers requiring UL 94 V-0 flame ratings and tracking resistance. Germany's automotive OEMs specify these for high-voltage EV architectures.
- Consumer Electronics:Smartphone and laptop internal structural parts where dielectric properties and low moisture uptake command specification adherence. India's PLI scheme for electronics is pulling high-flow grades into Tamil Nadu assembly operations.
- Aerospace Parts:Interior structural components meeting FAA flammability standards with inherent flame resistance. Specified for cabin air handling units and electrical junction boxes.
- Chemical Processing Equipment:Pumps, valves, and filter housings exposed to corrosive process streams. Demand clusters along the US Gulf Coast chemical processing hub.
Electrical components anchor current volume. Consumer electronics is climbing the fastest as device miniaturization accelerates.
End User Industry:
End user concentration determines pricing power, with automotive OEMs consolidating procurement authority and compressing supplier qualification timelines.
- Automotive OEMs:Drive specifications for high-heat under-hood applications including battery module housings and power distribution units. Volkswagen, BMW, and Mercedes-Benz have centralized polymer specification authority in Germany.
- Electronics Manufacturers:Require high-purity grades with tight lot-to-lot consistency for semiconductor packaging and miniaturized connectors. Japan's reshoring initiatives are reshaping procurement patterns.
- Chemical Producers:Specify corrosion-resistant grades for process equipment in aggressive environments. Demand tracks capital expenditure cycles in specialty chemical production.
- Aerospace Fabricators:Source certified materials meeting stringent traceability and flammability requirements. Qualification timelines extend 24-36 months for new compound introductions.
Automotive OEMs command the largest specification footprint. Electronics manufacturers are gaining share fastest as semiconductor packaging substrate production reshores.
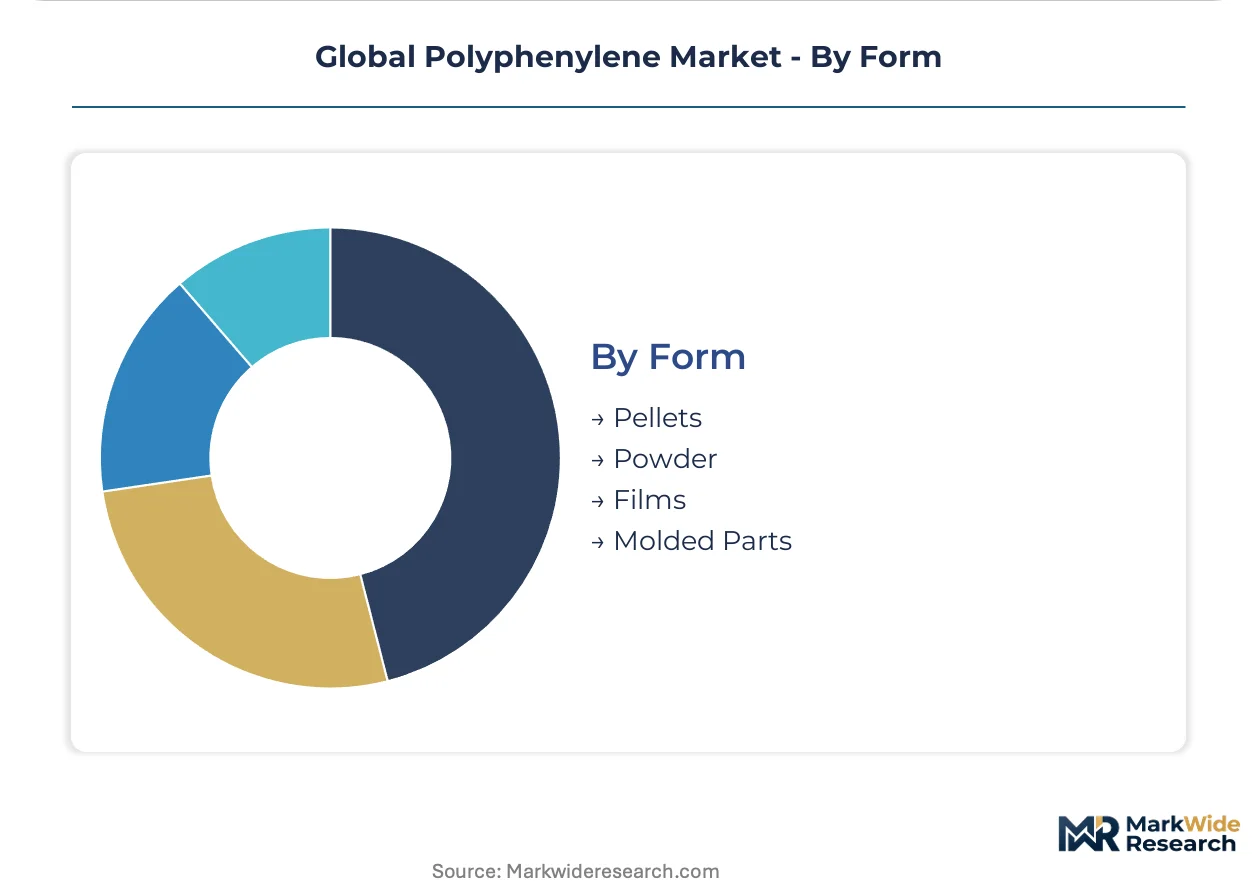
Form:
Form factor determines supply chain configuration, with pellets feeding compounders and injection molders while films route through specialized converters.
- Pellets:Standard feedstock for injection molding and extrusion operations. Automotive Tier-1 suppliers in Germany and Japan process fiber-reinforced pellet grades for connector miniaturization.
- Molded Parts:Finished components consolidating multi-piece assemblies into single-shot polymer solutions. HVAC and appliance OEMs are redesigning brass valve assemblies into PPS components for residential heat pump markets.
- Powder:Used in compression molding and coating applications requiring uniform particle size distribution. Serves specialty electrical insulation and friction components.
- Films:Thin-gauge extruded products for dielectric substrates and flexible circuit applications. Electronics packaging substrate trials in Japan are evaluating film-grade polyphenylene ether.
Pellets dominate current supply volumes. Molded parts are where value capture is expanding most quickly as metal-to-polymer consolidation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany's automotive belt while cost-sensitive procurement in China's chemical processing hubs compresses margins for standard-grade compounders. This asymmetry redistributes investment toward high-specification production in Western Europe and specialized electronics corridors in East Asia.
United States
EPA regulations on per- and polyfluoroalkyl substances are forcing systematic reformulation of legacy flame-retardant packages in US-sold compounds. The IRA clean energy manufacturing credits incentivize reshoring of polyphenylene compound production to Texas and South Carolina for solar inverters and EV chargers. Demand clusters along the US Gulf Coast chemical processing hub for corrosion-resistant grades in pumps and valves.
Germany
Volkswagen, BMW, and Mercedes-Benz have centralized polymer specification authority, compressing supplier qualification timelines from thirty-six months to eighteen months. REACH restrictions on halogenated additives redirect R&D toward phosphorus-based systems at compounders serving under-hood electrical components. The automotive belt spanning Bavaria and Baden-Württemberg anchors European demand for high-heat PPS grades in 48V mild-hybrid architectures.
China
SAMR enforces GB standards for electrical appliance safety that elevate tracking resistance requirements for connector materials. Over sixty percent of merchant para-dichlorobenzene precursor capacity sits in Shandong and Jiangsu provinces, exposing compounders to export license volatility. The Yangtze River Delta chemical processing corridor processes standard-grade PPS for domestic appliance and industrial motor markets.
Japan
METI-supported reshoring of semiconductor packaging substrate production pulls high-purity polyphenylene ether into BT laminate replacement trials. JIS standards govern material qualification for electronics-grade compounds with tight lot-to-lot consistency requirements. The Kanto and Kansai electronics manufacturing corridors concentrate demand for miniaturized connector applications.
India
The PLI scheme for electronics attracts contract manufacturers expanding smartphone and laptop assembly in Tamil Nadu and Karnataka. BIS certification requirements for electrical appliance safety create compliance thresholds for imported compound grades. Localized supply of high-flow PPS grades for miniaturized connectors remains underdeveloped, opening procurement opportunities for integrated resin compounders.
Global Polyphenylene Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Integrated resin compounders with captive polymerization capacity dominate high-margin automotive specifications, while merchant compounders compete on price in standard electrical applications. Two strategic archetypes define positioning: backward-integrated specialists controlling precursor supply, and scale-driven diversified chemical conglomerates leveraging feedstock access. Competitive moves concentrate on qualification timeline compression and geographic capacity expansion near OEM assembly clusters.
Among Japanese chemical conglomerates, Toray Industries and Tosoh Corporation exemplify the integrated resin-to-compound archetype with deep specialization in high-heat automotive and electronics grades. Solvay anchors European supply through upstream control over para-dichlorobenzene precursors, representing the backward-integrated model. SABIC occupies a position among Middle Eastern producers with advantaged feedstock economics and expanding compounding presence. These three players illustrate how geographic and structural positioning shapes competitive access to specification-driven procurement desks.
| Leading Market Players |
|---|
| Toray Industries |
| Solvay |
| DIC Corporation |
| Kureha Corporation |
| LG Chem |
| Celanese Corporation |
| SABIC |
| Ensinger |
| Tosoh Corporation |
| Others |
Supply & Pricing Matrix
Scale economies at integrated resin compounders with captive para-dichlorobenzene polymerization capacity establish price floors that merchant compounders cannot match without feedstock subsidies or tariff protection. This concentration of upstream scale in China's Shandong and Jiangsu provinces compresses margins for standard-grade PPS while amplifying premium capture for automotive-qualified grades in Germany and Japan.
Pricing Analysis
The configured-to-order premium for automotive-qualified PPS grades runs 40-60 percent above catalog pricing for standard electrical grades, with UL 94 V-0 recertification timelines and lot-to-lot consistency guarantees driving the spread. Price differentiation rests on qualification depth with Volkswagen-BMW-Mercedes procurement desks and backward integration into para-dichlorobenzene precursors. Cost compression in standard appliance-grade compounds is intensifying because SABIC's Ultem polyetherimide substitutes penetrate at 15-20 percent lower specific cost. Tier-2 automotive sensor housing buyers exhibit highest price sensitivity; aerospace fabricators with 24-36 month qualification cycles show least.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes and port congestion at Rotterdam and Hamburg inflate inbound logistics costs for European compounders sourcing Chinese para-dichlorobenzene. Supply concentrates in China, Germany, and Japan, with over sixty percent of merchant precursor capacity anchored in Shandong and Jiangsu provinces. Raw material dependencies rest on para-dichlorobenzene, sodium sulfide, and high-purity copper fiber for conductive grades. Single-source vulnerability from China's export license volatility for precursor chemicals threatens compounder inventory positions. Distribution runs through resin compounders with captive polymerization for automotive OEMs, specialty distributors for electronics grades, and direct mill relationships for chemical processing equipment fabricators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment around REACH flame-retardant restrictions and UL 94 V-0 recertification timelines creates structural barriers that compounder incumbents exploit against merchant competitors.
For Market Incumbents: Compound qualification timeline compression advantages by embedding technical service teams within Volkswagen, BMW, and Mercedes-Benz platform engineering desks before eighteen-month windows close. Deepen backward integration into para-dichlorobenzene precursors to defend margin position against SABIC's Ultem substitution threat in mid-tier automotive sensor housings.
For New Entrants and Emerging Players: Differentiate on localized compounding capacity in India's Tamil Nadu and Karnataka corridors, where PLI scheme electronics manufacturing lacks indigenous high-flow PPS supply. Target miniaturized connector applications for smartphone and laptop assembly with JIS-standard certification as the go-to-market angle, bypassing entrenched German automotive qualification queues.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated resin-to-compound specialists with captive para-dichlorobenzene polymerization and decade-long automotive platform lock-ins. Long-term viability over the next decade hinges on EPA-driven reformulation cycles that strand legacy flame-retardant compounders. Acquire backward-integrated Japanese or European specialists with METI or ECHA regulatory entrenchment. Watch for inflection when China's SAMR accelerates GB standard enforcement on tracking resistance, forcing importer recertification waves.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursors | Solvay's para-dichlorobenzene control anchors European supply security against Shandong export volatility. |
| Automotive Qualification Timeline Compression | Eighteen-month Volkswagen-BMW-Mercedes windows concentrate procurement authority among integrated compounders. |
| Phosphorus-Based Flame-Retardant Reformulation | EPA PFAS restrictions and REACH halogen bans redirect R&D toward inherently fire-resistant polyphenylene backbones. |
| Localized Compounding in India | Tamil Nadu and Karnataka electronics assembly under PLI scheme lacks indigenous high-flow PPS connector supply. |
| Long-Fiber Thermoplastic PPS Scale-Up | German Tier-1 suppliers adopt these grades for 48V mild-hybrid connector miniaturization. |
Research Methodology
Desk research of customs and trade flow databases, SEC and TSE corporate filings, and ECHA regulatory submission records preceded structured interviews with polymer plant managers, automotive Tier-1 procurement leads, electronics distributor channel partners, and technical R&D directors at resin compounders. Primary fieldwork with these stakeholders validated secondary estimates through bottom-up demand modeling and top-down supply capacity reconciliation.
Variance decomposition across product type, application, end-use industry, and regional production hub segmentation dimensions informed the analytical framework over the projection horizon. CAGRs were derived from installed base erosion rates, replacement demand cycles, and net new specification wins across automotive electrification and electronics reshoring trends. Model inputs incorporated para-dichlorobenzene capacity utilization rates, UL 94 V-0 recertification pipeline visibility, and METI-backed semiconductor packaging substrate trial timelines.
Material uncertainties — EPA PFAS enforcement intensity, China's para-dichlorobenzene export license volatility, and automotive OEM platform standardization decisions — sit outside the modeled envelope. Forecasts reflect assumptions around regulatory continuity and qualification timeline compression trajectories. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Polymer Memory Market
Polymers & Resins
Polytrimethylene Terephthalate Market
Polymers & Resins
Thermoplastic Edge Bands Market
Polymers & Resins
Global Polyphthalamide Market
Polymers & Resins
Fluorinated Ethylene Propylene (FEP) Market
Polymers & Resins
Canada Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
North America Epoxy Resins Market
Polymers & Resins
Polyester Polyol Market
Polymers & Resins
PE Resins Market
Polymers & Resins
Bisphenol a Market
Polymers & Resins
Non-Ionic Polyacrylamide Market
Polymers & Resins
Tie Layer Resin Market
Polymers & Resins
Basic Methacrylate Copolymer Market
Polymers & Resins
Polyethylene Naphthalate Market
Polymers & Resins
Photocure Resins Market
Polymers & Resins
Bismaleimide Monomer Market