
 Nylon-6 Market | 2026-2036
Nylon-6 Market Size, Share, and Industry Trends Forecast 2026-2036
Nylon-6 Market Outlook
Closed-loop chemical recycling is rewriting material economics for polyamide supply chains. BASF SE leverages its integrated caprolactam complexes in Ludwigshafen to sustain cost-advantaged virgin resin output. AdvanSix Inc. anchors North American supply through its Virginia-based integrated production, while Aquafil Group differentiates via ECONYL regeneration technology that competes on performance parity with fossil-based grades.
Nylon-6 is a semicrystalline polyamide synthesized via ring-opening polymerization of caprolactam, distinguished by a melting point near 220°C and excellent fatigue resistance for load-bearing components. Its primary purpose spans engineered plastics for automotive and industrial gear, plus textile filaments for carpet and apparel applications. Resins command the deepest margin pools in automotive under-the-hood and powertrain housings, while filaments retain volume leadership across textile end uses. Extrusion technology dominates processing for film and monofilament outputs, whereas injection molding concentrates value in precision automotive and electronics components.
REACH registration requirements in Europe and EPA industrial emissions standards in the United States constrain caprolactam plant expansions and elevate compliance capital intensity. China's GB standards and dual carbon goals under MEE oversight are pressuring domestic producers toward energy-efficient polymerization routes and bio-based feedstock pilots. Stakeholders must monitor regulatory divergence on recycled-content certification, as fragmented standards across jurisdictions threaten to segment tradable supply into incompatible quality tiers.
Market Dynamics
Chemical recycling infrastructure is collapsing the historical cost gap between virgin and regenerated caprolactam, forcing integrated producers to reconfigure asset deployment around feedstock flexibility rather than scale economics alone.
Growth Catalysts
- Automotive lightweighting mandates:NHTSA fuel economy standards and EU CO2 fleet targets are accelerating polymer substitution in engine covers, intake manifolds, and structural brackets where Nylon-6 competes with metal castings.
- REACH recycled-content quotas:ECHA registration requirements for closed-loop grades are creating certified demand pools that command supply priority from European compounders.
- China's caprolactam-to-fiber integration:Coastal Zhejiang and Jiangsu provinces host fully integrated complexes that compress conversion costs and anchor regional export competitiveness.
Market Restraints
- Benzene price volatility:Cyclohexane feedstock costs swing with crude oil and naphtha indices, compressing margin visibility for non-integrated polymerization operators.
- MEE environmental compliance:China's Ministry of Ecology and Environment enforcement of dual carbon goals is idling older, coal-heavy caprolactam capacity and tightening regional supply availability.
- Polypropylene substitution in automotive:Lower-density PP compounds reinforced with glass fiber are capturing non-structural under-hood applications where temperature tolerance permits.
Strategic Opportunities
- India automotive component localization:PLI scheme incentives for advanced chemistry cell and auto component manufacturing are pulling compounder investment toward Pune and Chennai industrial corridors.
- Textile-to-textile regeneration:Post-industrial carpet and fishing net collection networks in Southeast Asia are scaling feedstock supply for depolymerization units serving apparel brands.
- ISO 14001-driven procurement:Tier-1 automotive suppliers are embedding lifecycle assessment requirements into resin qualification protocols, favoring certified lower-carbon grades.
Industry Challenges
- Depolymerization technical talent scarcity:Caprolactam recovery from mixed polyamide waste streams demands specialized chemical engineering expertise that outpaces current vocational pipeline output.
- Multi-jurisdiction certification fragmentation:Divergent recycled-content verification protocols between ECHA, EPA, and emerging national standards are forcing producers to maintain parallel quality systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nylon-6 Market |
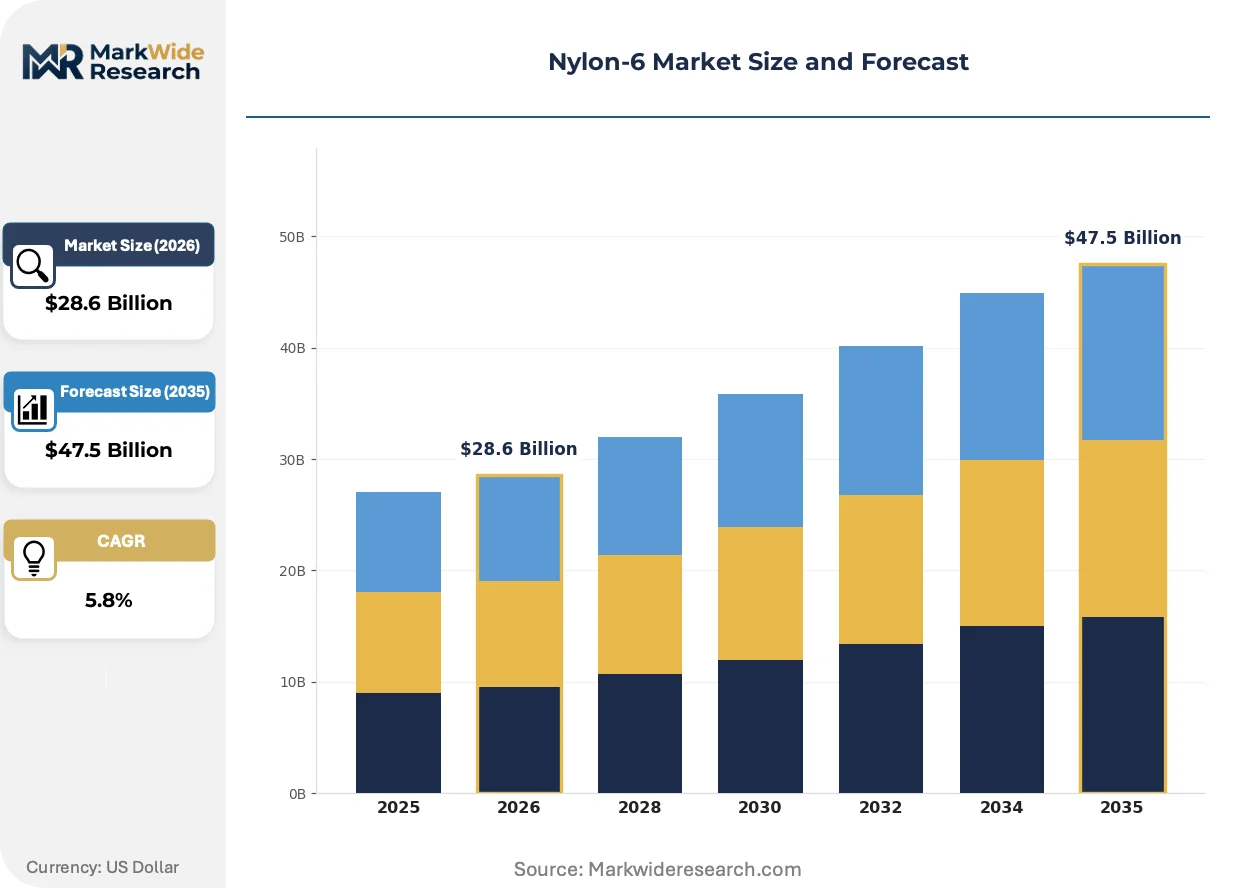
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $47.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Filaments, Fibers, Resins, Additives End User: Textiles, Automotive, Electronics, Consumer Goods Application: Ropes, Industrial Fabrics, Packaging Films, Coatings Technology: Injection Molding, Extrusion, Blow Molding, 3D Printing |
| Companies Covered | BASF SE, Toray Industries, Inc., Shenma Industrial Co., Ltd, Guangdong Xinhui Meida Nylon Co., Ltd., AdvanSix Inc., Arkema S.A., DuPont de Nemours Inc., DSM N.V., Aquafil Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nylon-6 Market Strategic Shifts
Feedstock circularity is overtaking virgin capacity expansion as the primary axis of competitive differentiation, with technology deployment patterns diverging sharply between integrated petrochemical complexes and specialized regeneration facilities.
Enzymatic hydrolysis of polyamide waste streams is collapsing the energy intensity differential between mechanical recycling and chemical regeneration. Automotive seating and airbag manufacturers in Germany and Japan are qualifying enzymatically processed chips for safety-critical applications. This technology is collapsing the historical performance penalty that relegated recycled grades to commodity textile uses.
EU Green Deal carbon border adjustment mechanisms are tightening embodied emissions accounting for imported resin. European compounders are now requesting supplier-specific polymerization carbon footprints as contract prerequisites. Automotive powertrain housing specifications in France and Italy are embedding these thresholds as technical disqualifiers.
Brand-led recycled-content commitments are compressing traditional spot-market procurement cycles. Apparel and carpet OEMs are negotiating multi-year offtake agreements directly with regeneration facilities, bypassing conventional distributor channels. This pattern is most visible in Italy's textile machinery cluster and China's Yangtze River Delta synthetic fiber belt.
Nylon-6 Market Segmentation
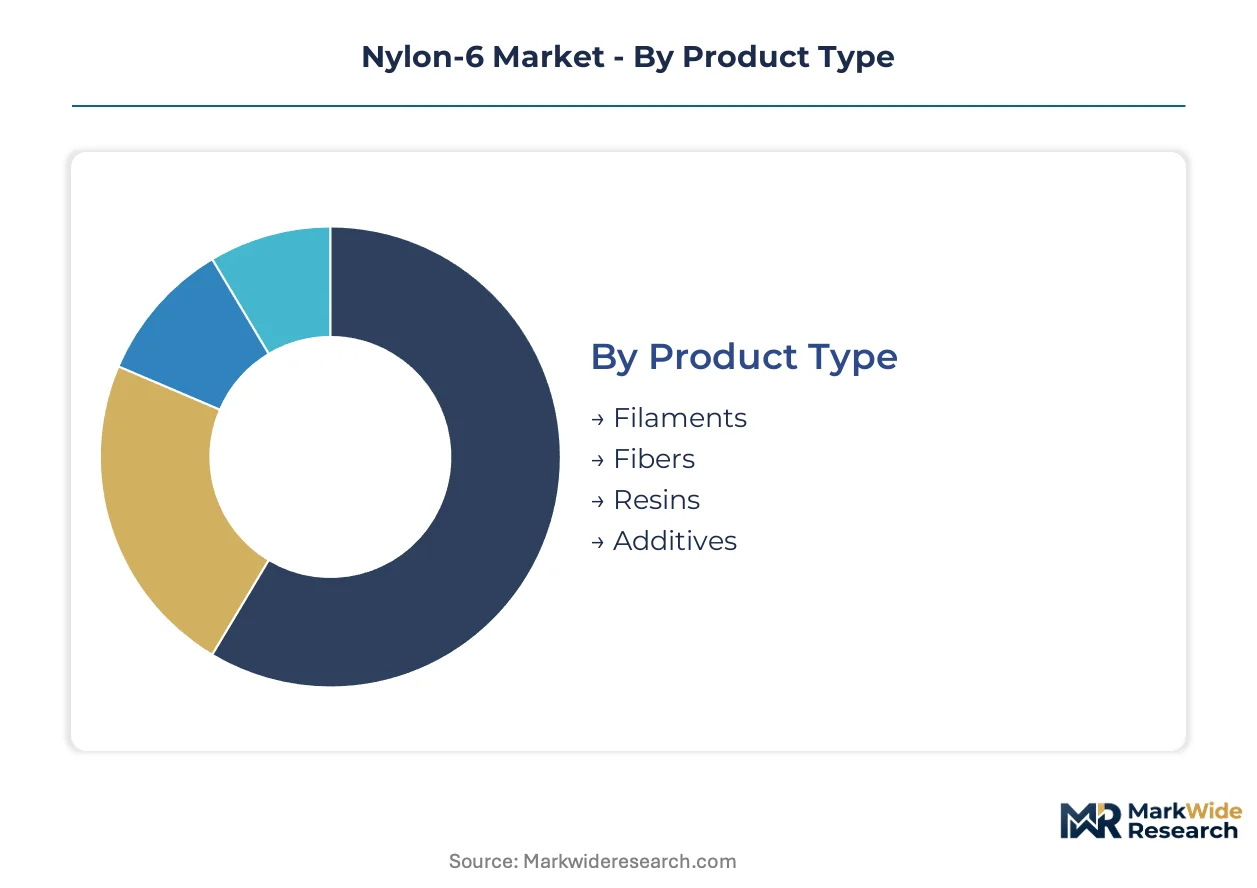
Nylon-6 demand fragments across distinct technical specifications and processing requirements. Each segment commands different margin structures and regulatory exposure, forcing suppliers to maintain parallel qualification tracks for automotive safety standards versus textile performance benchmarks.
Product Type:
Mature commodity grades dominate volume flows while specialty formulations capture technology premiums.
- Filaments:Continuous extruded strands with denier ranges from 20-2000, engineered for tensile strength and abrasion resistance. Carpet manufacturers in the United States and apparel weavers in Italy concentrate procurement around solution-dyed variants that eliminate downstream water processing. REACH registration requirements for colorant migration constrain supplier pools to certified compounders.
- Resins:Pelletized polymer grades with viscosity indices calibrated for injection molding or extrusion throughput. Automotive under-hood component specifications in Germany and Japan demand heat-stabilized formulations that withstand 150°C continuous operating temperatures. NHTSA fuel economy mandates are accelerating resin substitution for metal powertrain housings.
- Fibers:Staple and tow formats for nonwoven and spun yarn applications. Hygiene product manufacturers in Southeast Asia source super-absorbent surface layers from low-pilling staple grades.
- Additives:Nucleating agents, impact modifiers, and flame retardants compounded for performance enhancement. Electronics enclosure producers in Taiwan specify halogen-free flame retardant packages for connector housings.
Resins retain volume leadership; additives hold the steepest expansion curve.
End User:
Cost tier stratification separates specification-intensive industrial buyers from price-sensitive commodity offtakers.
- Automotive:Tier-1 suppliers qualify material lots against OEM-specific crash simulation databases and thermal aging protocols. Engine cover and intake manifold producers in Stuttgart and Detroit mandate lot traceability from caprolactam monomer through molded component. EU CO2 fleet targets are pulling polymer substitution rates higher in structural brackets.
- Textiles:Carpet mills and apparel manufacturers drive filament and fiber consumption through specification programs tied to recycled-content certifications. ECONYL regeneration technology from Aquafil Group supplies luxury fashion houses in Milan with performance parity to virgin grades.
- Electronics:Connector and cable tie manufacturers specify lubricated grades for automated assembly line feeding. Surface-mount device carriers in South Korea demand electrostatic discharge protection.
- Consumer Goods:Kitchen utensil and sporting equipment molders prioritize food-contact compliance and color consistency over mechanical performance extremes.
Textiles anchor total volume; automotive climbs the fastest on lightweighting mandates.
Application:
Volume concentration clusters in load-bearing industrial uses where fatigue resistance justifies material cost premiums over polypropylene alternatives.
- Industrial Fabrics:Woven and knitted constructions for conveyor belts, airbags, and tire cord. Safety-critical airbag fabric weavers in Japan enforce sub-3% elongation variance across production lots.
- Ropes:Braided and twisted constructions for marine mooring and arborist rigging. High-tenacity filament grades with UV stabilizers command specification lock-in from commercial fishing fleets in Norway.
- Packaging Films:Biaxially oriented and cast film for food barrier layers and industrial wrap. Oxygen transmission rate specifications from European food processors constrain resin selection to high-viscosity extrusion grades.
- Coatings:Powder and liquid formulations for wire insulation and metal corrosion protection. Electrical motor manufacturers in China specify thermal class F ratings for magnet wire enamels.
Industrial fabrics dominate value capture; ropes gain share fastest on marine safety regulation tightening.
Technology:
Processing method determines capital intensity and scrap rate economics, with injection molding commanding the tightest tolerance bands.
- Injection Molding:High-pressure cavity filling for complex geometries with wall thickness below 2mm. Automotive powertrain housing producers in Bavaria deploy sequential valve gating to eliminate weld lines in structural bosses. Mold flow simulation validation is mandatory for safety-critical component qualification.
- Extrusion:Continuous profile and sheet production with draw-down ratios calibrated for molecular orientation. Monofilament fishing line manufacturers in China run 24/7 operations with melt filtration systems that exclude gel particle defects.
- Blow Molding:Parison inflation for hollow containers and ducting. Fuel tank and air duct producers leverage coextrusion capabilities for multi-layer barrier constructions.
- 3D Printing:Fused filament fabrication and selective laser sintering for prototyping and low-volume end-use parts. Medical device developers in Massachusetts qualify implantable-grade powder lots against USP Class VI biocompatibility standards.
Injection molding retains volume leadership; 3D printing holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports caprolactam and Nylon-6 resin to Southeast Asian textile processors and European automotive compounders, while Germany ships engineering-grade compounds to Tier-1 suppliers across the EU and North America.
China
Integrated caprolactam-to-fiber complexes in Zhejiang and Jiangsu provinces drive export competitiveness through compressed conversion economics. MEE enforcement of dual carbon goals idles older coal-heavy capacity, tightening regional supply availability. Coastal synthetic fiber clusters around Shaoxing and Suzhou anchor regenerated filament production for apparel brands.
Germany
Automotive powertrain housing demand from Stuttgart and Munich OEMs pulls high-performance resin consumption. ECHA registration requirements for closed-loop grades create certified demand pools commanding supply priority. Ludwigshafen's integrated petrochemical complex sustains cost-advantaged virgin output for European compounders.
United States
NHTSA fuel economy standards accelerate polymer substitution in Detroit-serving engine covers and intake manifolds. EPA industrial emissions standards constrain greenfield caprolactam expansions, elevating compliance capital intensity. Virginia-based integrated production anchors North American supply security for automotive Tier-1s.
India
PLI scheme incentives for advanced chemistry cell and auto component manufacturing pull compounder investment toward Pune and Chennai corridors. BIS standards for automotive material qualification create technical entry barriers for unapproved imports. Maharashtra's industrial belt concentrates textile filament consumption for domestic apparel weaving.
Japan
METI carbon neutrality roadmaps pressure producers toward energy-efficient polymerization routes and bio-based feedstock pilots. JIS standards for safety-critical airbag fabrics enforce sub-3% elongation variance across production lots. Nagoya's automotive component cluster drives precision resin demand for hybrid powertrain housings.
Nylon-6 Market Competitive Environment
Channel-controlling players compete with product-specialist players across a consolidated upstream and fragmented downstream. Integrated petrochemical majors with captive caprolactam supply dominate virgin resin economics, while specialized regeneration facilities capture premium recycled-content contracts. Two archetypes prevail: backward-integrated chemical conglomerates and technology-differentiated circular material specialists. Competitive moves concentrate on feedstock flexibility investments and multi-jurisdiction certification maintenance.
Among Germany-based chemical conglomerates, BASF SE exemplifies the integrated archetype through its Ludwigshafen complex control. Toray Industries, Inc. represents Japanese diversified material science positioning across filament and resin segments. AdvanSix Inc. anchors North American supply as a Virginia-based integrated operator. Aquafil Group occupies the regeneration-specialist tier with its ECONYL technology platform serving luxury fashion procurement.
| Leading Market Players |
|---|
| BASF SE |
| Toray Industries, Inc. |
| Shenma Industrial Co., Ltd |
| Guangdong Xinhui Meida Nylon Co., Ltd. |
| AdvanSix Inc. |
| Arkema S.A. |
| DuPont de Nemours Inc. |
| DSM N.V. |
| Aquafil Group |
| Others |
Value Chain & Pricing Dynamics
Benzene price volatility cascading through cyclohexane feedstock costs determines both virgin-to-regenerated pricing spreads and the geographic shape of Nylon-6 supply chains. This commodity exposure compresses margin visibility for non-integrated polymerization operators while rewarding backward-integrated complexes with captive caprolactam supply.
Pricing Analysis
Virgin resin generation maintains a pricing premium over chemically regenerated grades, though enzymatic hydrolysis is collapsing this gap. Pricing stratifies across premium, standard, and economy tiers based on certification grade and volume scale, with REACH-registered recycled-content lots commanding supply priority. Cost compression in standard-grade filament is intensifying because China's MEE enforcement idles older coal-heavy capacity. Automotive Tier-1s demonstrate the least price sensitivity due to safety-critical qualification requirements, while apparel weavers in Southeast Asia exhibit acute sensitivity to resin cost swings.
Supply Chain Analysis
Contract manufacturing concentration in China's Zhejiang and Jiangsu provinces holds the majority of global caprolactam-to-fiber capacity. Supply draws from benzene, cyclohexane, and caprolactam monomer inputs sourced from integrated petrochemical complexes. Single-source vulnerability concentrates in Ludwigshafen-based virgin resin output for European compounders. Distribution runs through direct mill relationships for textile filaments and qualified distributor networks for automotive resins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as automotive lightweighting mandates accelerate polymer substitution rates beyond prior penetration ceilings. Chemical recycling infrastructure buildout and regulatory recycled-content quotas create durable tailwinds for qualified suppliers.
For Market Incumbents: Insulate margin position through backward integration into caprolactam feedstock and accelerated ECONYL-equivalent regeneration capacity. Polypropylene substitution in non-structural automotive applications threatens volume retention in commodity grades. Prioritize REACH and EU Green Deal certification maintenance to lock European compounder offtake. For New Entrants and Emerging Players: Build out textile-to-textile regeneration capabilities targeting post-industrial carpet and fishing net collection networks in Southeast Asia. India's PLI scheme corridors around Pune and Chennai offer the most penetrable geography for automotive compounder partnerships. Pursue direct mill relationships bypassing conventional distributor channels. For Investors and Strategic Acquirers: The market sits at a capacity-reconfiguration phase that favors technology-differentiated circular material specialists over commodity virgin resin operators. Long-term viability hinges on feedstock flexibility rather than scale economics alone. Target acquisition archetypes combine enzymatic hydrolysis technology with multi-jurisdiction certification infrastructure. Watch for MEE enforcement intensity in China as inflection signal for regional supply availability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Caprolactam | Ludwigshafen and Virginia complexes demonstrate cost-advantaged virgin output against spot feedstock purchasers. |
| Chemical Recycling Scale-Up | Enzymatic hydrolysis deployment collapses energy intensity differential with mechanical recycling for safety-critical applications. |
| Multi-Jurisdiction Certification Investment | Parallel ECHA, EPA, and emerging national quality systems prevent supply segmentation into incompatible tiers. |
| Long-Term Automotive Offtake Agreements | Direct contracts with Stuttgart and Detroit Tier-1s bypass spot-market volatility for powertrain housing resins. |
| Joint Venture in India PLI Corridors | Pune and Chennai localization captures PLI scheme incentives for advanced chemistry cell component manufacturing. |
Study Parameters
A standing panel of caprolactam plant managers, automotive Tier-1 procurement leads, textile mill technical directors, and chemical distribution channel partners provided ongoing calibration throughout the study period. Primary interview findings were cross-validated against secondary sources including customs and trade flow databases, ACC and Cefic industry reports, SEC 10-K filings from integrated producers, and MEE environmental enforcement disclosures. Bottom-up capacity and consumption estimates were triangulated with top-down macroeconomic elasticity models.
Scenario-bracketing across benzene price volatility bands, MEE enforcement intensity levels, and automotive lightweighting penetration rates framed the projection horizon. Segmentation dimensions modeled include product grade tier, end-use industry vertical, processing technology, and regional production hub clustering. CAGRs were derived from elasticity-adjusted volume forecasts incorporating named capacity additions and idling events. Industry-specific inputs encompassed REACH registration timelines, PLI scheme disbursement schedules, and ECONYL-equivalent technology deployment trajectories.
Stress conditions across crude oil index swings, Chinese environmental compliance enforcement, and polypropylene substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding technology adoption curves and regulatory implementation timelines. Specific risk factors that could revise projections include accelerated enzymatic hydrolysis cost reduction, fragmented recycled-content certification proliferation, and unexpected MEE capacity idling orders. Quarterly review of benzene-cyclohexane spreads, MEE inspection announcements, and automotive OEM polymer substitution announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Polystyrene and Expandable Polystyrene (EPS) Market
Polymers & Resins
Polymer Modifiers Market
Polymers & Resins
Modified Epoxy Resins Market
Polymers & Resins
Global Medical Superabsorbent Polymers Market
Polymers & Resins
Global Engineering Plastic Market
Polymers & Resins
Global Alkyd Resin Market
Polymers & Resins
Aromatic Ketone Polymer Market
Polymers & Resins
Global Microcellular Polyurethane Foam Market
Polymers & Resins
Synthetic Polymer Waxes Market
Polymers & Resins
Asia-Pacific Polyamide Market
Polymers & Resins
Super Absorbent Polymer Market
Polymers & Resins
Global Solid Masterbatches Market
Polymers & Resins
Global High Performance Polyethylene Market
Polymers & Resins
Europe Polyvinylpyrrolidone (PVP) Market
Polymers & Resins
Virgin Resin Market
Polymers & Resins
Dispersant Polymer Market