
 Synthetic Polymer Waxes Market | 2026-2036
Synthetic Polymer Waxes Market Size, Share, and Industry Trends Forecast 2026-2036
Synthetic Polymer Waxes Market Intelligence
Specialized polymer chemist availability is redrawing competitive boundaries across the synthetic polymer waxes value chain. BASF SE leverages its integrated Ludwigshafen complex to sustain captive feedstock advantages for high-purity polyethylene wax output. Clariant AG anchors its position through application-specific micronized wax grades tailored to coatings customers. Honeywell International Inc. differentiates via proprietary catalyst technology that narrows molecular weight distribution in its synthetic wax portfolio.
Synthetic polymer waxes comprise hydrocarbon-based materials engineered through Fischer-Tropsch synthesis, polyethylene polymerization, or polypropylene modification, typically exhibiting melting points between 100°C and 140°C and serving primarily as surface modifiers, lubricants, and processing aids across industrial formulations. Micronized waxes command premium positioning in coatings applications where particle size distribution below 15 micrometers determines gloss control and mar resistance. Emulsion waxes represent the fastest-expanding form category as waterborne formulation mandates intensify across architectural and industrial coatings segments. Solid waxes retain volume dominance in plastics compounding where direct melt incorporation remains the standard processing method.
EPA oversight of volatile organic compound emissions in US coatings applications directly constrains solvent-borne wax carrier formulations, redirecting R&D investment toward aqueous dispersion platforms. ECHA REACH registrations for polymer substances exceeding one tonne annually impose comprehensive toxicological dossier requirements that filter smaller compounders from European supply chains. China's MEE enforcement of dual carbon goals is tightening energy intensity benchmarks for Fischer-Tropsch wax production facilities in Ningxia and Inner Mongolia. Stakeholders must weigh regulatory compliance costs against regional manufacturing access when configuring their synthetic polymer wax sourcing matrices.
Market Dynamics
Automotive OEMs are consolidating coating specifications around scratch-resistant polymer wax formulations, forcing suppliers to retool R&D pipelines toward micronized grades that meet mar resistance thresholds below 15 micrometers.
Growth Catalysts
- Waterborne formulation mandates:EPA volatile organic compound limits in US coatings applications are redirecting solvent-borne wax investments toward aqueous dispersion platforms. Architectural coatings manufacturers are accelerating emulsion wax adoption to maintain market access.
- Fischer-Tropsch capacity expansion:China's plastics processing sector is absorbing rising domestic synthetic wax output as Ningxia and Inner Mongolia production facilities scale to serve compounding operations.
- REACH compliance premiums:ECHA registration requirements for polymer substances exceeding one tonne annually are filtering smaller compounders from European supply chains, concentrating volume with dossier-capable manufacturers.
Market Restraints
- Ethylene feedstock volatility:Polyethylene wax production margins compress when naphtha-cracker economics tighten, exposing non-integrated producers to input cost swings without captive ethylene supply.
- Fischer-Tropsch concentration risk:Synthetic wax output clusters in China's northwest energy corridor, creating single-geography exposure to MEE dual carbon enforcement and power rationing protocols.
- Natural wax substitution:Carnauba and beeswax alternatives compete in premium coatings segments where bio-based labeling commands shelf-space advantages at retail.
Strategic Opportunities
- Battery coating applications:Lithium-ion cell manufacturing is opening demand for ultra-pure synthetic waxes as separator lubricants and electrode binders in gigafactory supply chains.
- India PLI scheme alignment:Domestic plastics processing incentives are attracting wax formulation investments to serve automotive and packaging compounding clusters in Gujarat and Maharashtra.
- 3D printing filament lubrication:Fused deposition modeling feedstock producers are specifying micronized polymer waxes to reduce nozzle wear and improve layer adhesion in engineering-grade thermoplastics.
Industry Challenges
- Specialized polymer chemist scarcity:Formulation expertise at the intersection of Fischer-Tropsch catalysis and coatings application engineering commands salary premiums that mid-scale producers struggle to match.
- REACH dossier timelines:ECHA toxicological data requirements for new polymer substances extend registration cycles to 18-24 months, delaying product launches in European coatings markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Synthetic Polymer Waxes Market |
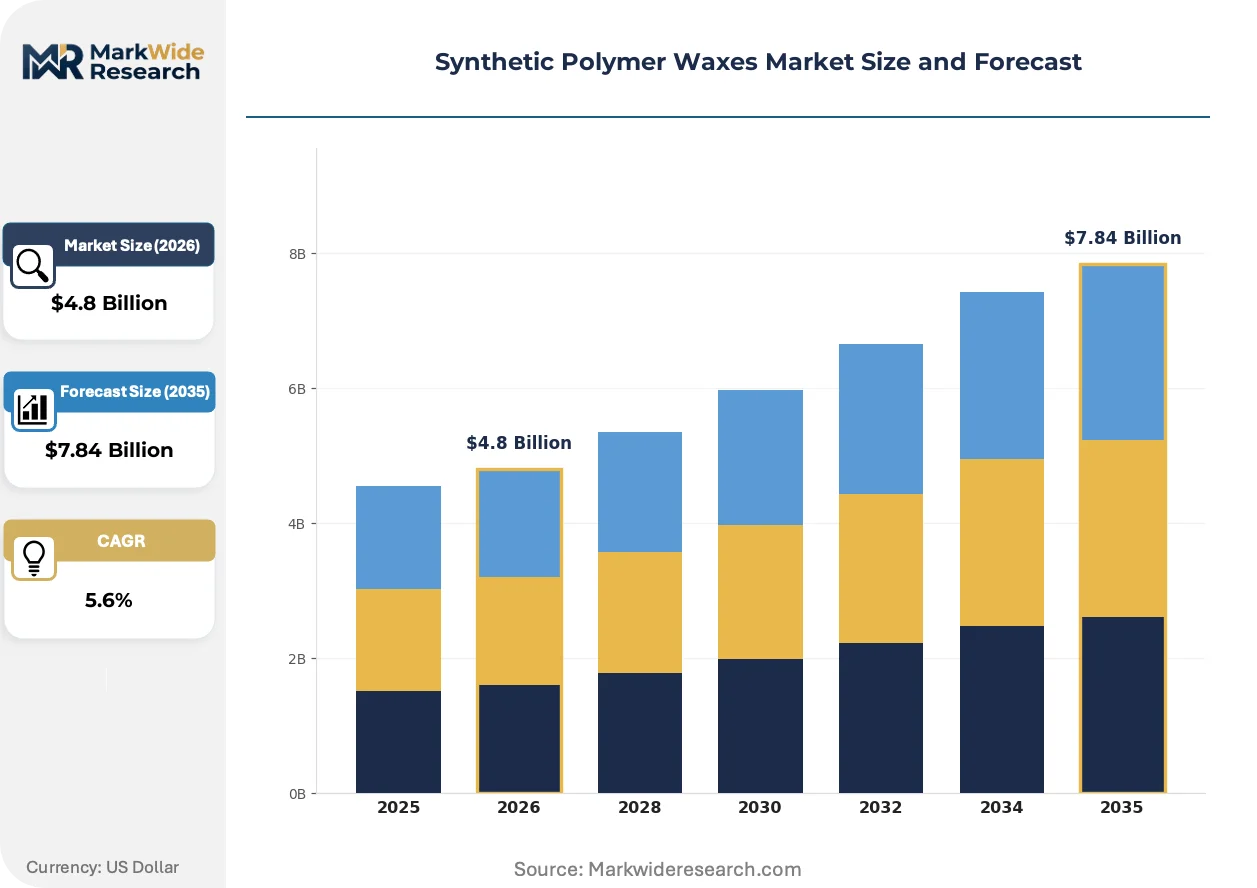
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.84 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Emulsion Waxes, Micronized Waxes, Dispersion Waxes, Solid Waxes Application: Coatings, Adhesives, Cosmetics, Plastics End User: Automotive, Food Packaging, Personal Care, Industrial Form: Granular, Powder, Liquid, Paste |
| Companies Covered | BASF SE, Clariant AG, Honeywell International Inc., Sasol Limited, ExxonMobil Corporation, Mitsui Chemicals, Inc., Eastman Chemical Company, Evonik Industries AG, SABIC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Synthetic Polymer Waxes Market Strategic Shifts & Innovations
Formulation chemistry is pivoting toward aqueous delivery systems as regulatory pressure on solvent carriers intensifies, while particle engineering advances unlock performance tiers previously reserved for petroleum-derived alternatives.
Metallocene-catalyzed polyethylene wax production is fragmenting molecular weight distribution control across the supplier base. Coatings formulators in automotive clearcoat applications are adopting narrow-distribution grades to achieve predictable gloss retention. This capability diffusion is compressing premium pricing power previously held by catalyst-technology leaders.
REACH Article 33 disclosure obligations for substances of very high concern are tightening supply chain documentation burdens across European coatings value chains. Downstream formulators now demand batch-level certification from wax suppliers to maintain CE marking compliance. Automotive OEMs in Germany and France are consolidating procurement around REACH-registered suppliers with established SCIP database protocols.
Specification consolidation among automotive tier-one coatings suppliers is concentrating volume with wax producers capable of lot-to-lot consistency at micronized particle sizes. Direct mill-base incorporation protocols are displacing traditional pre-dispersion steps, rewarding suppliers with in-house micronization capabilities. This pattern is most visible in US and German automotive coating supply chains where OEM mar resistance specifications have tightened since 2023.
Synthetic Polymer Waxes Market Segmentation
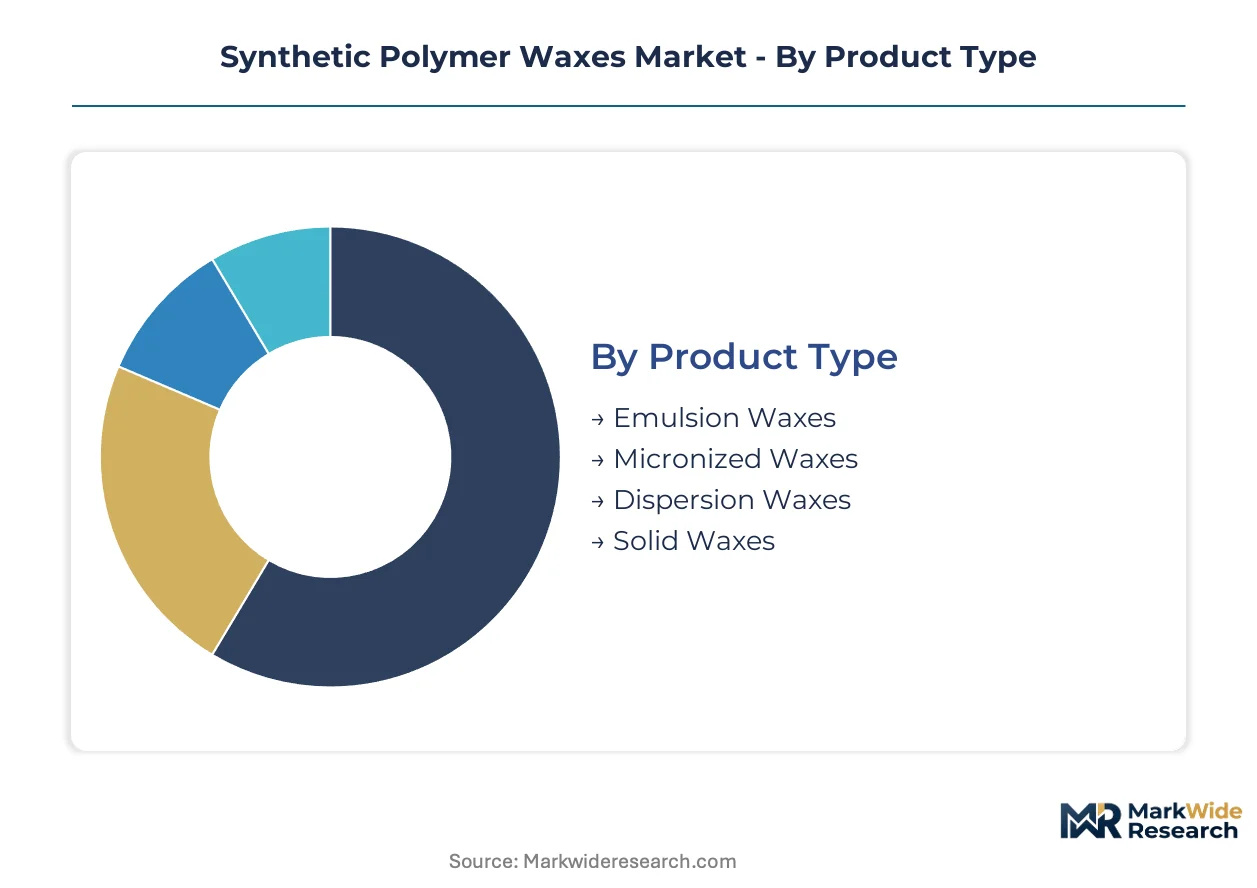
Synthetic polymer waxes serve distinct performance requirements across formulation chemistry. Segmentation reveals how product engineering, application specifications, and delivery forms create differentiated value pools for suppliers.
Product Type:
Emulsion waxes concentrate in domestic European and North American coatings production serving waterborne mandate compliance, while solid waxes dominate export flows to Asian plastics compounding hubs.
- Emulsion Waxes:Aqueous dispersions with particle sizes below 5 micrometers enable direct incorporation into waterborne architectural coatings. Demand clusters in Germany and US manufacturing corridors where EPA and ECHA solvent restrictions have eliminated solvent-borne alternatives in decorative paints.
- Micronized Waxes:Jet-milled powders with controlled distribution below 15 micrometers deliver mar resistance in automotive clearcoats. Premium positioning in German and Japanese OEM supply chains rewards suppliers with in-house micronization capabilities and batch-level certification protocols.
- Dispersion Waxes:Pre-dispersed liquid concentrates reduce milling steps for mid-scale coatings producers in India and Southeast Asia.
- Solid Waxes:Direct-melt grades in pellet and slab forms serve plastics compounding operations across China's Yangtze River Delta and Pearl River Delta manufacturing belts.
Solid waxes hold the largest share; momentum sits with emulsion waxes.
Application:
Cost tier differentiation separates specification-grade coatings from commodity plastics processing, with adhesive applications occupying a mid-tier value position.
- Coatings:Automotive OEM clearcoats, industrial maintenance paints, and architectural finishes specify narrow-distribution polymer waxes for gloss control and scratch resistance. German automotive tier-one suppliers enforce lot-to-lot consistency standards that filter smaller compounders from approved vendor lists.
- Plastics:Polyethylene and polypropylene compounding operations incorporate synthetic waxes as external lubricants and release agents. China's domestic plastics processing capacity expansion in Ningxia and Zhejiang provinces absorbs rising Fischer-Tropsch wax output from northwest production facilities.
- Adhesives:Hot-melt and pressure-sensitive formulations use synthetic waxes to adjust viscosity and set speed in packaging assembly operations.
- Cosmetics:Color cosmetic and skincare applications demand pharmaceutical-grade certification and low odor profiles for premium positioning.
Coatings commands premium pricing; plastics drives volume scale.
End User:
Customer type fragmentation separates specification-driven automotive procurement from price-sensitive industrial buyers, with food packaging emerging as a compliance-intensive growth vertical.
- Automotive:OEM clearcoat specifications consolidate around micronized grades meeting mar resistance thresholds below 15 micrometers. German and French automakers require REACH-registered suppliers with established SCIP database protocols for substances of very high concern documentation.
- Food Packaging:Migration limits under FDA and EFSA frameworks demand ultra-pure synthetic waxes for direct food contact applications. Suppliers with toxicological dossiers and positive regulatory listings capture specification premiums in North American and European flexible packaging markets.
- Personal Care:Cosmetic formulators prioritize sensory properties and INCI labeling compliance for premium skincare positioning.
- Industrial:General manufacturing applications emphasize unit cost optimization over performance specifications in metalworking and textile processing.
Automotive holds the largest share; food packaging shows steepest expansion trajectory.
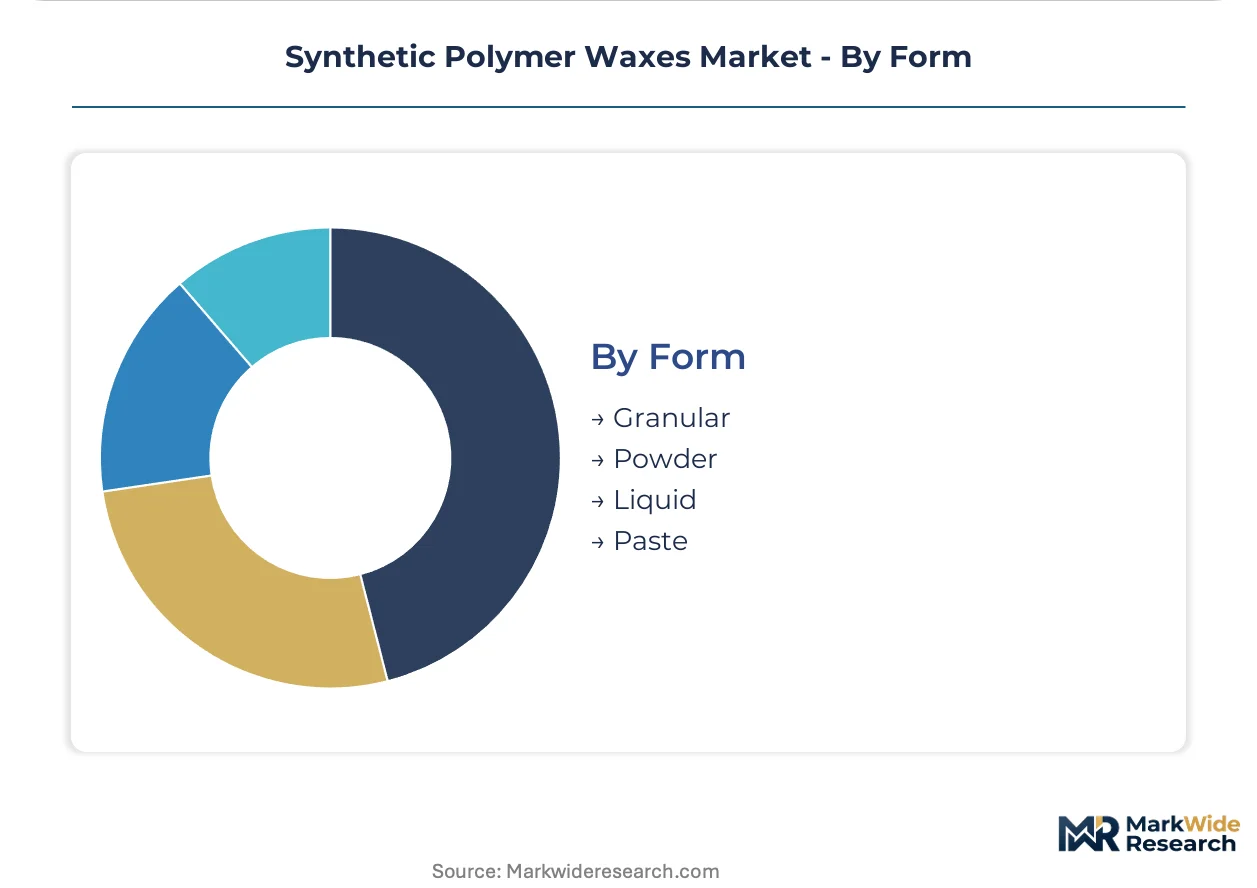
Form:
Supply concentration in powder micronization creates margin premiums, while liquid handling advantages expand addressable market among smaller formulators.
- Powder:Jet-milled and spray-dried grades serve coatings and plastics applications requiring precise particle size distribution. German and Japanese automotive coatings suppliers specify powder forms for direct mill-base incorporation protocols that displace pre-dispersion steps.
- Liquid:Pumpable dispersions and emulsions reduce handling complexity for waterborne coatings manufacturers in US and European architectural segments. Aqueous delivery systems align with EPA volatile organic compound limits and ECHA solvent reduction mandates.
- Granular:Free-flowing pellets facilitate automated feeding in high-volume plastics compounding operations.
- Paste:Semi-solid concentrates serve specialty adhesive and sealant formulations requiring controlled viscosity adjustment.
Powder holds the largest share; liquid gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. German automotive coatings buyers prioritize micronized grades for mar resistance, while Chinese plastics compounders absorb Fischer-Tropsch wax volumes in pellet form for direct melt incorporation.
United States
Architectural coatings manufacturers drive emulsion wax uptake as EPA volatile organic compound limits eliminate solvent-borne alternatives. The agency's 2024 coating rulemaking tightens permissible emissions in industrial maintenance applications. Manufacturing corridors in Ohio and Michigan concentrate waterborne formulation capacity serving domestic OEM supply chains.
Germany
Automotive tier-one suppliers enforce REACH-registered sourcing with SCIP database protocols for substances of very high concern documentation. ECHA registration requirements for polymer substances exceeding one tonne annually filter smaller compounders from approved vendor lists. The Ludwigshafen chemical complex anchors integrated polyethylene wax production serving coatings customers across the Rhine-Neckar metropolitan region.
China
Plastics processing capacity expansion in Ningxia and Inner Mongolia absorbs rising domestic Fischer-Tropsch wax output. MEE enforcement of dual carbon goals tightens energy intensity benchmarks for production facilities in the northwest energy corridor. Yangtze River Delta compounding clusters in Jiangsu and Zhejiang provinces standardize direct-melt incorporation protocols for solid wax grades.
India
Domestic automotive and packaging compounding incentives under the PLI scheme attract wax formulation investments to Gujarat and Maharashtra. BIS standards for polymer additives create compliance thresholds that favor organized manufacturers over informal suppliers. Mumbai-Pune industrial belt operations scale micronized wax handling for coatings applications serving tier-one automotive suppliers.
Japan
Cosmetic and precision electronics applications sustain demand for ultra-pure synthetic waxes with pharmaceutical-grade certification. METI chemical substance management frameworks impose reporting obligations on polymer importers exceeding specified volume thresholds. Osaka-Kobe manufacturing clusters specialize in narrow-distribution grades for automotive clearcoat specifications requiring predictable gloss retention.
Synthetic Polymer Waxes Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in the synthetic polymer waxes competitive structure. Integrated petrochemical majors leverage captive ethylene supply and Fischer-Tropsch synthesis capabilities to sustain cost positions in commodity grades. Specialist compounders differentiate through application-specific micronization and aqueous dispersion expertise. Capacity expansion in China's northwest energy corridor and strategic partnerships for battery coating applications represent the dominant competitive moves reshaping supply configurations.
Among Germany-based integrated chemical producers, BASF SE and Evonik Industries AG occupy positions reflecting backward integration into polymer feedstocks and catalyst technologies. Honeywell International Inc. exemplifies the specialty-tier archetype with proprietary process capabilities. These three entities anchor distinct competitive vectors: integrated petrochemical scale, application-engineered performance grades, and proprietary catalysis platforms.
| Leading Market Players |
|---|
| BASF SE |
| Clariant AG |
| Honeywell International Inc. |
| Sasol Limited |
| ExxonMobil Corporation |
| Mitsui Chemicals, Inc. |
| Eastman Chemical Company |
| Evonik Industries AG |
| SABIC |
| Others |
Cost & Logistics Intelligence
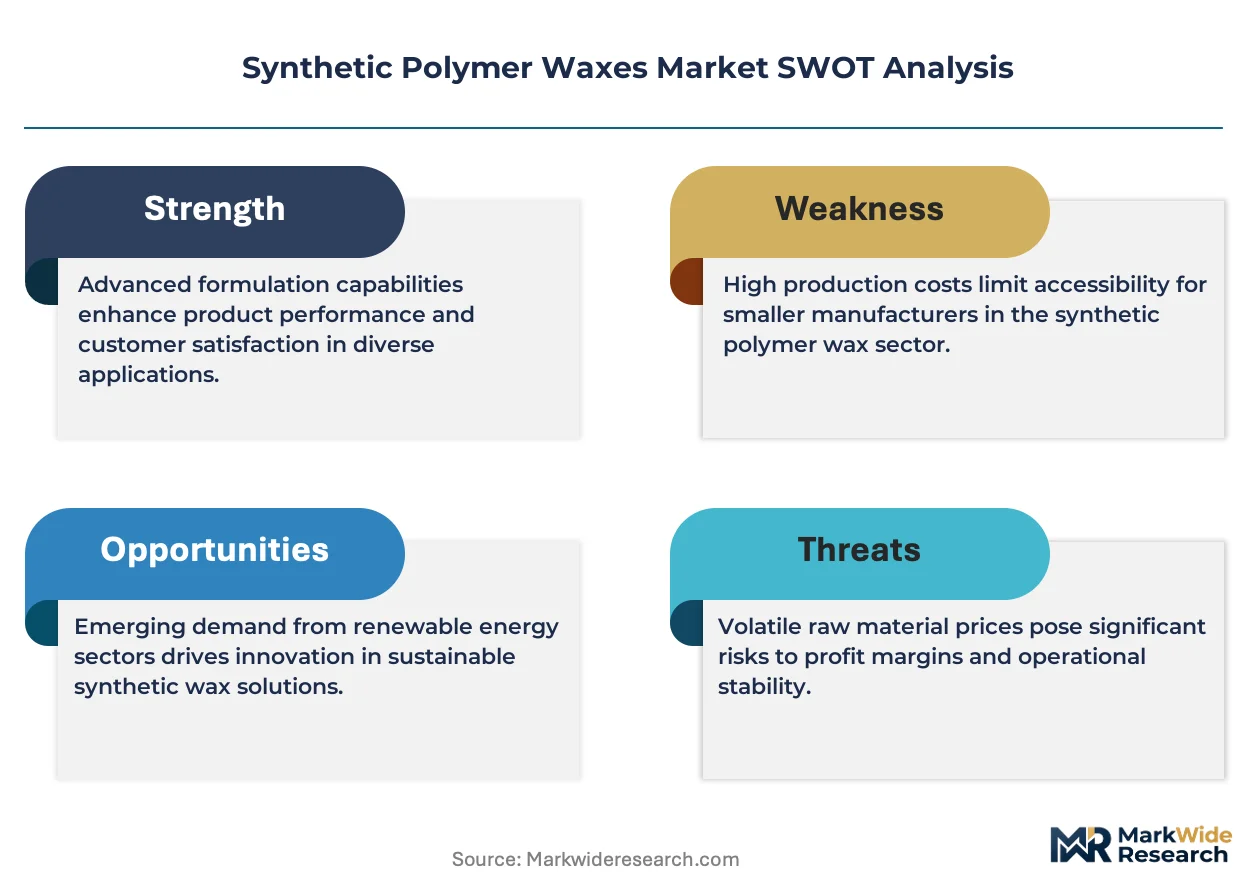
REACH registration requirements for polymer substances exceeding one tonne annually simultaneously gate supply qualification and stratify price tiers across European coatings value chains, concentrating volume premiums with dossier-capable manufacturers while filtering smaller compounders from approved vendor lists.
Pricing Analysis
Long-term offtake contracts dominate procurement between integrated Fischer-Tropsch producers and Chinese plastics compounders, while spot purchases persist for specialty micronized grades in automotive coatings. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and particle size distribution precision. Cost compression in commodity polyethylene waxes is intensifying because ethylene feedstock volatility squeezes non-integrated producers. Tier-one automotive OEMs exhibit lowest price sensitivity, prioritizing lot-to-lot consistency and REACH documentation over unit cost optimization.
Supply Chain Analysis
Ningxia-to-Inner Mongolia rail corridors constitute a chokepoint for Fischer-Tropsch wax flows serving Yangtze River Delta compounding clusters. Supply concentrates in China, Germany, and South Africa for synthetic wax manufacturing. Production draws from naphtha-cracker ethylene, natural gas feedstocks, and proprietary catalyst systems. Single-geography exposure to MEE dual carbon enforcement creates structural risk for northwest Chinese output. Distribution runs through direct mill-base supply relationships with automotive tier-one coatings suppliers and bulk pellet distribution to plastics compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Synthetic polymer waxes demand is recovering from cyclical trough conditions as automotive production schedules normalize and OEM coating specifications consolidate around scratch-resistant formulations.
For Market Incumbents: Shield margin positions by deepening captive ethylene supply integration at Ludwigshafen-scale complexes and accelerating REACH dossier investments to maintain European coatings market access against emerging Fischer-Tropsch competitors. Prioritize in-house micronization capability expansion to capture automotive OEM specification consolidation.
For New Entrants and Emerging Players: Differentiate on battery coating applications for lithium-ion separator lubricants, where ultra-purity requirements and gigafactory proximity create specification premiums insulated from commodity wax competition. Target India PLI-aligned plastics compounding clusters in Gujarat and Maharashtra with localized emulsion wax production.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across aqueous dispersion platforms as waterborne formulation mandates redirect R&D spend from solvent-borne infrastructure. Five-to-ten year viability favors specialists with proprietary catalyst technology and established SCIP database protocols. Watch MEE enforcement intensity in Ningxia and Inner Mongolia as inflection indicator for Chinese supply reliability.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethylene Supply | Captive naphtha-cracker output at Ludwigshafen insulates BASF from feedstock volatility squeezing non-integrated competitors. |
| Micronization Capacity Expansion | In-house jet-milling capabilities enable direct mill-base incorporation protocols demanded by German automotive tier-one suppliers. |
| REACH Dossier Investment | ECHA toxicological data completion filters smaller compounders from European coatings supply chains, concentrating premiums. |
| Battery Coating Application Development | Ultra-pure synthetic wax specifications for lithium-ion separator lubricants open demand outside traditional coatings and plastics segments. |
| India PLI Scheme Alignment | Domestic production incentives in Gujarat and Maharashtra attract formulation investments serving automotive and packaging compounding clusters. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with Fischer-Tropsch plant managers, coatings formulators at automotive tier-one suppliers, plastics compounding procurement leads, and ECHA regulatory affairs specialists; and secondary validation through customs trade data, ACC and Cefic industry reports, SEC 10-K filings, and REACH registration databases. Bottom-up segment sizing triangulated against top-down macroeconomic drivers.
Across the analysis window, forecasts reflect segment-level modeling across product type, application, end-user category, and regional production hub dimensions. CAGRs were derived from volume trajectory analysis incorporating automotive OEM production schedules, plastics processing capacity expansion in China, and waterborne formulation mandate compliance timelines in US and European coatings markets.
Material uncertainties — ethylene feedstock volatility, MEE dual carbon enforcement intensity, and REACH registration timeline extensions — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory stability and automotive production normalization. Practitioners should keep alternative scenarios live as Chinese energy intensity benchmarks and EPA coating rulemaking evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Green Polyols Market
Polymers & Resins
Super Absorbent Polymer Market
Polymers & Resins
Filled Fluoropolymer Market
Polymers & Resins
Global Barrier Resins Market
Polymers & Resins
Terpene Resins Market
Polymers & Resins
Polyethylene Terephthalate (PET) Resin Market
Polymers & Resins
Global Polymer Stabilizer Market
Polymers & Resins
North America Plastic Compounding Market
Polymers & Resins
Global Polyurethane Dispersions Market
Polymers & Resins
Global Polymerization Initiator Market
Polymers & Resins
United States Geopolymer Market
Polymers & Resins
Homopolymer Resins Market
Polymers & Resins
Bio-Based Polyvinyl Chloride Market
Polymers & Resins
Global Liquid Crystal Polymer (LCP) Market
Polymers & Resins
Polyamide-Imide (PAI) Market
Polymers & Resins
Global HBPA Epoxy Resin Market