
 Vinyl Acetate Ethylene Copolymer Powder Market | 2026-2036
Vinyl Acetate Ethylene Copolymer Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Vinyl Acetate Ethylene Copolymer Powder Market Intelligence
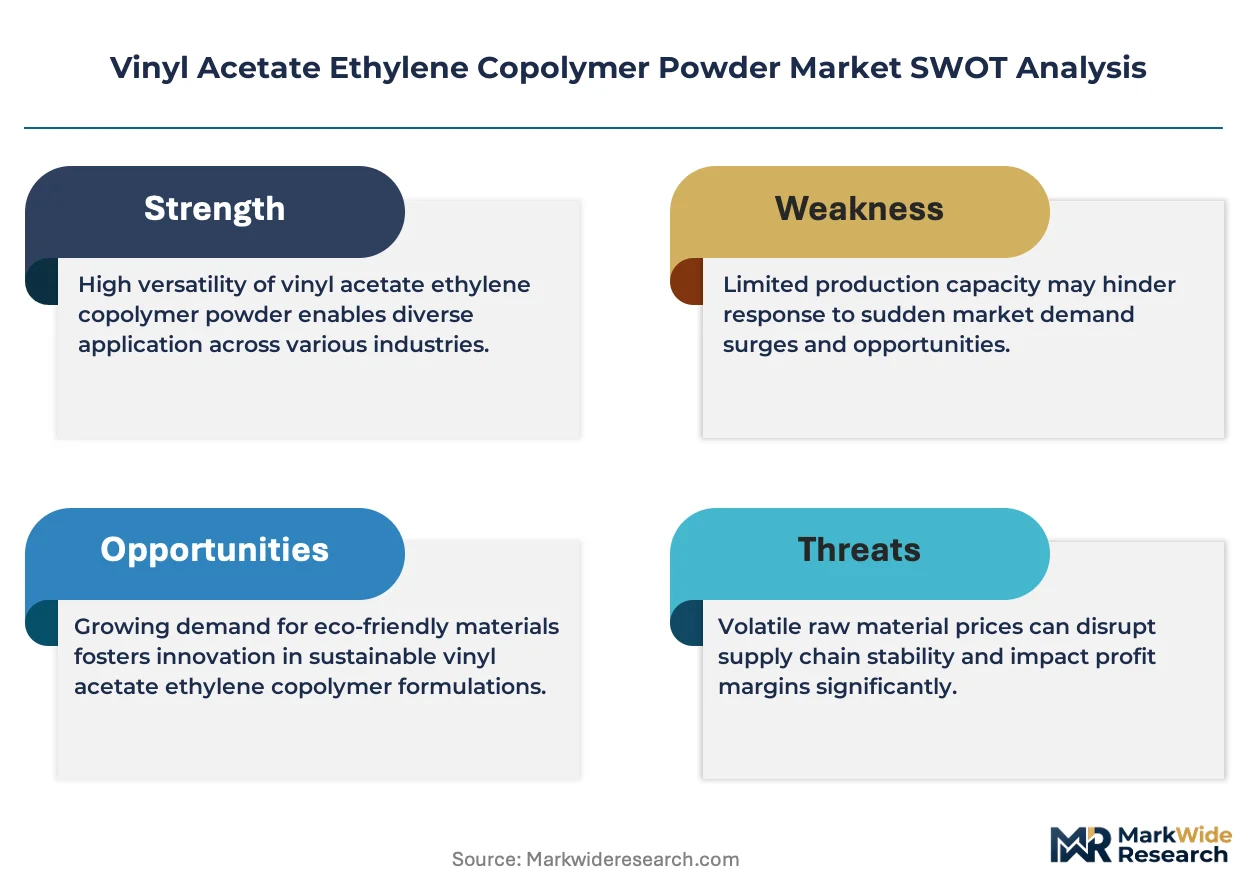
The gap between premium and commodity tiers is restructuring the competitive landscape for vinyl acetate ethylene copolymer powder. Wacker Chemie AG leverages its integrated ethylene-vinyl acetate supply chain to dominate high-purity grades for pharmaceutical packaging adhesives. Celanese Corporation anchors North American demand through specialized dispersions that meet FDA indirect food-contact standards. Dow competes on manufacturing scale, sustaining cost leadership across standard-grade construction applications in multiple geographies.
Vinyl acetate ethylene copolymer powder comprises a thermoplastic copolymer synthesized through emulsion polymerization, typically containing 60-95% vinyl acetate content with ethylene comonomer to enhance flexibility and alkali resistance. The material functions primarily as a redispersible polymer powder that improves adhesion, cohesion, and water retention when blended with cementitious or gypsum-based dry mortars. Standard grade products occupy the mature volume base in generic tile adhesives, while flexible grade formulations capture expanding margin pools in exterior insulation and finish systems. Fast-setting grades are accelerating in concrete repair applications where construction cycle compression drives substitution of traditional acrylic modifiers.
EPA regulations on volatile organic compound emissions from architectural coatings constrain solvent-based adhesive formulations, redirecting formulation investment toward VAE powder dispersions. REACH registration requirements and ECHA restrictions on residual monomer content enforce purity thresholds that filter smaller compounders from European supply chains. China's MEE enforcement of GB standards for indoor air quality in building materials creates parallel compliance burdens for imported and domestic products. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and misaligned certification investments.
Market Dynamics
Construction cycle compression across Asia-Pacific infrastructure projects is forcing specification upgrades from standard-grade to fast-setting VAE powders, tightening the window between application and occupancy while elevating performance requirements for tile adhesive and repair mortar formulations.
Growth Catalysts
- India's PLI scheme for construction chemicals:Domestic manufacturing incentives are accelerating captive VAE powder production for tile adhesive and waterproofing applications, reducing import dependency for infrastructure contractors.
- GB standards for low-VOC building materials:China's MEE enforcement is redirecting solvent-based adhesive formulation investment toward redispersible polymer powder dispersions in interior finishing systems.
- Exterior insulation and finish systems:Thermal retrofit mandates across European building stock are expanding flexible-grade VAE consumption in facade systems requiring crack resistance and weatherability.
Market Restraints
- Ethylene feedstock volatility:Crude-linked ethylene pricing swings compress margin stability for emulsion polymerization operations, particularly affecting non-integrated compounders without captive olefin supply.
- Residual monomer thresholds:ECHA restrictions under REACH registration enforce purity standards that filter smaller European compounders lacking analytical and purification infrastructure.
- Acrylic modifier substitution:Styrene-acrylic dispersions compete in premium concrete repair segments where ultra-rapid strength development overrides cost considerations.
Strategic Opportunities
- Pharmaceutical packaging adhesives:High-purity grades meeting FDA indirect food-contact standards command margin premiums in blister pack and sachet lamination applications.
- Carbon-cured dry mortar systems:VAE powders compatible with CO2-cured cement chemistries align with EU Green Deal decarbonization pathways for prefabricated construction elements.
- Direct contractor distribution:Bypassing traditional distributor networks through digital procurement platforms captures margin and specification control in mid-scale commercial construction.
Industry Challenges
- Formulation chemist scarcity:Expertise in cement-polymer compatibility testing and rheology modification is concentrating among legacy technical service teams approaching retirement.
- Multi-jurisdiction certification lag:Parallel REACH, FDA, and BIS registration timelines extend product launch cycles by 18-24 months for cross-border suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vinyl Acetate Ethylene Copolymer Powder Market |
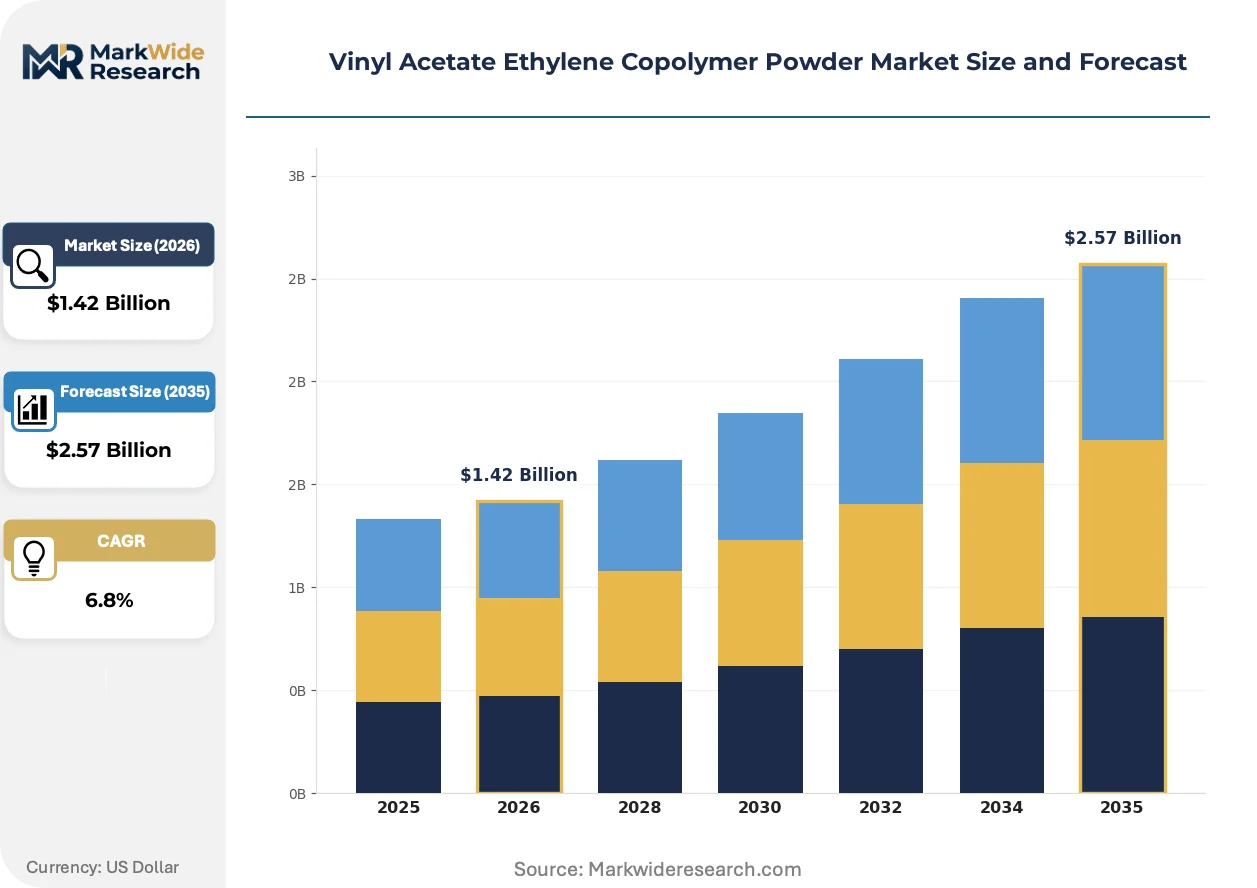
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Grade, High-Gloss Grade, Fast-Setting Grade, Flexible Grade, Heat-Resistant Grade Application: Adhesives, Textile Binders, Paper Coatings, Paints & Inks, Construction Materials End Use Industry: Packaging Manufacturers, Textile Producers, Coating Suppliers, Construction Contractors, Printing Companies Form: Fine Powder, Granules, Pellets, Flakes, Agglomerates |
| Companies Covered | Wacker Chemie AG, Celanese Corporation, Dow, BASF SE, Synthomer plc, Air Products and Chemicals, Inc., Akzo Nobel N.V., Shaanxi Xutai Technology Co., Ltd., Hexion Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vinyl Acetate Ethylene Copolymer Powder Market Strategic Shifts & Innovations
Formulation science is pivoting toward hybrid polymer architectures that merge VAE flexibility with specialized performance attributes, while regulatory enforcement tightens purity thresholds and procurement patterns fragment across project scale tiers.
Hybrid VAE-ethylene copolymer dispersions with silane crosslinking functionality are consolidating specification control in exterior facade systems requiring simultaneous water resistance and vapor permeability. Large-scale European thermal retrofit contractors specify these grades for multi-decade durability warranties. The technology is consolidating mid-tier suppliers lacking silane grafting capability into subordinate toll-manufacturing relationships.
REACH registration requirements and ECHA restrictions on residual vinyl acetate monomer are compressing the European supplier base toward integrated producers with in-house analytical and purification infrastructure. Compounders without captive ethylene-vinyl acetate supply chains face escalating compliance costs. Specialty adhesive formulators in Germany and France are consolidating procurement toward pre-certified raw material sources to de-risk registration timelines.
Specification authority is migrating from distributor sales networks toward project-level procurement teams armed with digital performance databases. Tier-one construction contractors in India and China now bypass traditional channel intermediaries for direct mill relationships on volume tile adhesive projects. This disintermediation is compressing distributor margins while rewarding manufacturers with localized technical service and just-in-time logistics infrastructure.
Vinyl Acetate Ethylene Copolymer Powder Market Segmentation
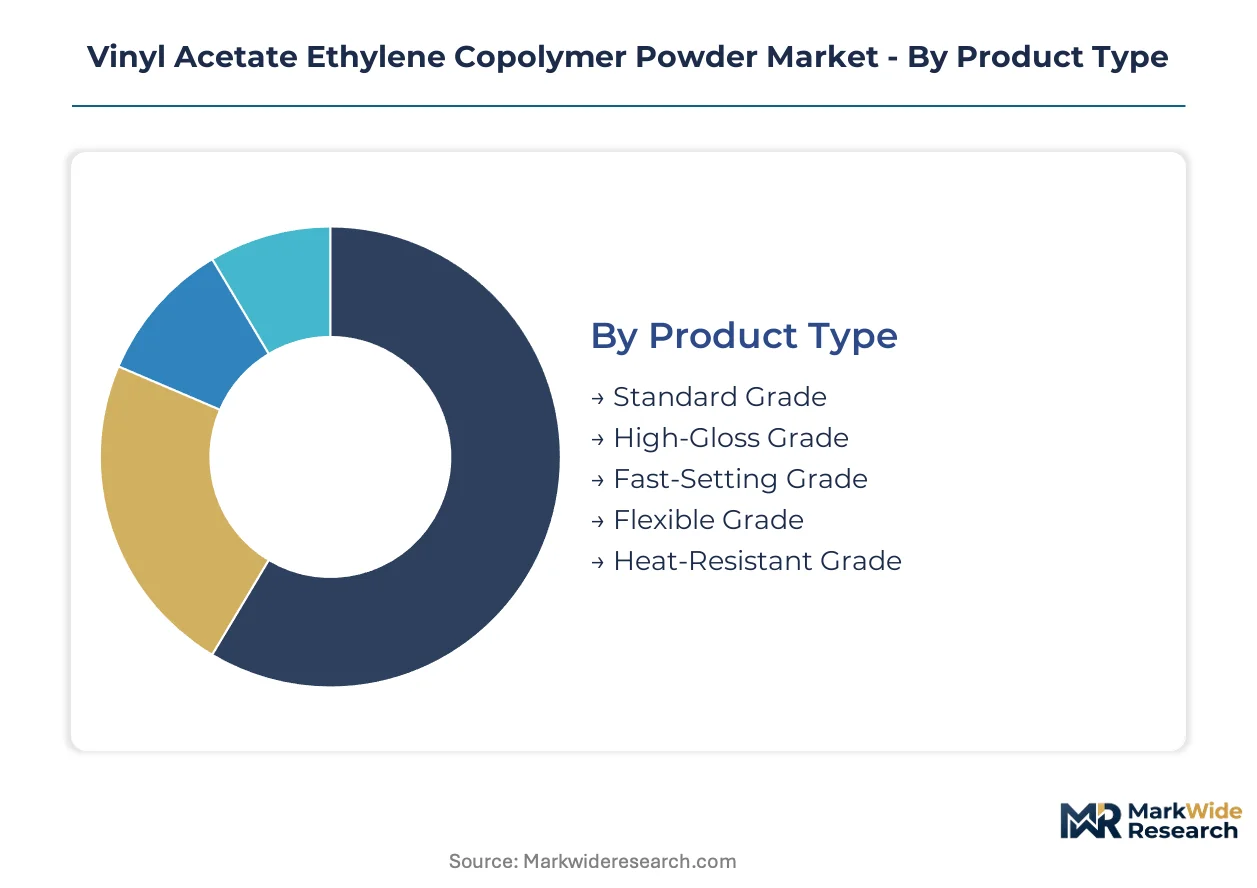
VAE powder specifications diverge sharply across construction timelines, packaging compliance tiers, and coating durability requirements. Buyers select grades based on cure speed mandates, VOC constraints, and substrate compatibility rather than unit cost alone.
Product Type:
Cost tier determines specification authority, with premium grades capturing margin in regulated applications while commodity volumes anchor construction scale.
- Standard Grade:Compositions with 60-75% vinyl acetate content serve generic tile adhesive and interior skim coat formulations where alkali resistance requirements remain moderate. Volume concentrates in India's infrastructure corridor projects under PLI-scheme procurement mandates, though margin compression from ethylene feedstock volatility constrains non-integrated suppliers.
- Flexible Grade:Ethylene-rich copolymers with enhanced elongation properties specify into exterior insulation and finish systems across European thermal retrofit mandates. Demand clusters in Germany and France where multi-decade durability warranties require silane-crosslinked hybrid architectures.
- High-Gloss Grade:Specialized dispersions for paper coating and decorative laminate applications where surface aesthetic specifications override cost considerations.
- Fast-Setting Grade:Accelerated cure chemistries for concrete repair and rapid-turnover commercial flooring where construction cycle compression eliminates standard-grade alternatives.
- Heat-Resistant Grade:Crosslinked formulations tolerating elevated temperatures in industrial adhesive and specialty packaging lamination.
Volume sits with Standard Grade; growth tilts toward Flexible Grade.
Application:
Application selection tracks end-use regulatory intensity, with construction and packaging commanding stricter certification thresholds than decorative coatings.
- Construction Materials:Redispersible polymer powders in cementitious dry mortars, tile adhesives, and waterproofing systems constitute the dominant consumption channel. India's MEE-aligned GB standard enforcement for low-VOC building materials redirects solvent-based formulation investment toward VAE dispersions in interior finishing systems.
- Adhesives:Pharmaceutical packaging and food-contact lamination applications specify high-purity grades meeting FDA indirect food-contact standards, commanding substantial margin premiums over construction grades.
- Textile Binders:Non-woven fabric binding and fabric finishing applications where wash durability and hand-feel specifications drive grade selection.
- Paper Coatings:Gloss enhancement and printability modification in specialty packaging and label stock.
- Paints & Inks:Pigment binding and film-forming in water-based architectural coatings constrained by EPA VOC emission regulations.
Construction Materials carries current volume; Adhesives is climbing the fastest on regulatory premium capture.
End Use Industry:
Customer type determines procurement pattern, with integrated packaging manufacturers demanding certified supply chains and construction contractors prioritizing logistics reliability.
- Construction Contractors:Tier-one infrastructure developers in India and China bypass traditional distributor networks for direct mill relationships on volume tile adhesive projects, compressing channel margins while rewarding localized technical service capability.
- Packaging Manufacturers:Blister pack and sachet laminators in regulated pharmaceutical markets specify pre-certified raw material sources to de-risk REACH and FDA registration timelines.
- Coating Suppliers:Water-based formulation houses serving architectural and industrial markets under EPA and MEE VOC constraints.
- Textile Producers:Non-woven and technical fabric manufacturers with durability and processing efficiency specifications.
- Printing Companies:Specialty ink formulators requiring pigment dispersion stability and substrate adhesion.
Construction Contractors dominate procurement scale; Packaging Manufacturers deliver steepest expansion trajectory on purity premium capture.
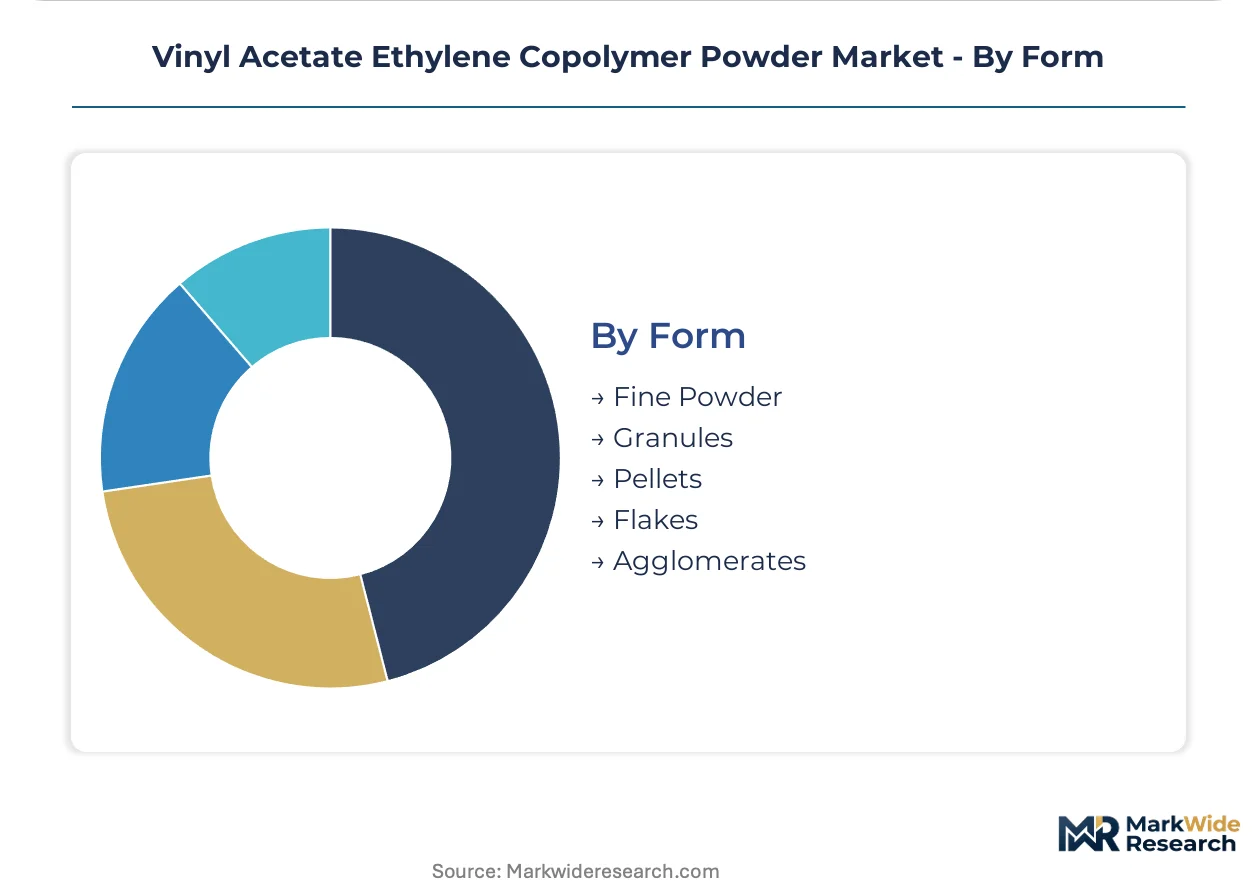
Form:
Physical form selection balances dissolution kinetics against dust exposure regulation and handling automation compatibility.
- Fine Powder:Particle sizes below 80 microns enable rapid redispersion in cementitious matrices, specifying into automated dry mortar blending operations where dust containment systems satisfy OSHA and REACH occupational exposure limits.
- Granules:Agglomerated particles reducing airborne dust during handling, preferred in manual mixing environments and regions with stringent workplace safety enforcement.
- Pellets:Densified forms for bulk handling systems in continuous production environments.
- Flakes:Intermediate morphology for specialty adhesive compounding with controlled dissolution profiles.
- Agglomerates:Engineered particle structures balancing flowability with redispersion speed in specific application equipment.
Fine Powder retains formulation share; Granules is gaining share fastest on occupational safety compliance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mumbai-Pune corridor anchors VAE powder procurement scale for India's infrastructure buildout, with construction chemical distributors clustering around the Nhava Sheva port logistics hub.
India
PLI scheme disbursements for construction chemicals accelerate captive VAE powder production in Gujarat and Maharashtra. BIS certification mandates for imported dry mortar additives tighten formulation compliance timelines. The Delhi-Mumbai Industrial Corridor concentrates demand from tier-one contractors sourcing directly from domestic mills.
China
MEE enforcement of GB standards for low-VOC building materials redirects solvent-based adhesive investment toward redispersible polymer powders. Dual carbon goals compress cement chemistry innovation cycles in prefabricated construction. The Yangtze River Delta houses the densest concentration of VAE emulsion polymerization capacity serving interior finishing systems.
Germany
EU Green Deal thermal retrofit mandates expand flexible-grade VAE consumption in multi-decade durability facade systems. REACH registration requirements filter smaller compounders lacking residual monomer purification infrastructure. The Rhine-Ruhr industrial region concentrates high-purity grade production for pharmaceutical packaging laminators.
United States
EPA VOC emission constraints on architectural coatings sustain water-based formulation investment in construction adhesives. FDA indirect food-contact standards command margin premiums for blister pack lamination applications. The Texas-Louisiana Gulf Coast corridor leverages integrated ethylene supply chains for cost-competitive standard-grade production.
Saudi Arabia
NEOM megaproject specifications drive demand for fast-setting grades in compressed construction cycles. The national standards body enforces low-emission building material protocols for interior air quality compliance. The Eastern Province industrial cities cluster imports high-purity grades for packaging converter operations serving GCC pharmaceutical markets.
Vinyl Acetate Ethylene Copolymer Powder Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the VAE powder value chain. Integrated petrochemical majors with captive ethylene-vinyl acetate supply chains dominate high-purity and flexible-grade segments, while toll manufacturers serve commodity construction volumes. Three strategic archetypes define competitive positioning: backward-integrated chemical conglomerates, specialized emulsion polymerization houses, and regional dry mortar compounders. Dominant competitive moves include capacity expansion in India and China to capture PLI-scheme and GB-standard compliance demand, plus technology licensing partnerships for silane-crosslinked hybrid architectures.
Among Germany-based chemical conglomerates, Wacker Chemie AG exemplifies the integrated archetype with upstream control over ethylene-vinyl acetate feedstocks. Celanese Corporation represents North American specialization in FDA-compliant dispersions for regulated packaging applications. Dow occupies the scale-driven position across standard-grade construction markets through manufacturing footprint breadth. These three anchors illustrate how geographic origin and corporate structure map to segment tier dominance.
| Leading Market Players |
|---|
| Wacker Chemie AG |
| Celanese Corporation |
| Dow |
| BASF SE |
| Synthomer plc |
| Air Products and Chemicals, Inc. |
| Akzo Nobel N.V. |
| Shaanxi Xutai Technology Co., Ltd. |
| Hexion Inc. |
| Others |
Cost & Logistics Intelligence
Silane-crosslinked hybrid VAE architectures are compressing the European supplier base toward integrated producers with captive analytical infrastructure, simultaneously elevating purity premiums and filtering non-integrated compounders from specification chains. This technological transition concentrates pricing power among backward-integrated chemical conglomerates while forcing toll manufacturers toward commodity construction volumes.
Pricing Analysis
Yield-based pricing anchored to mortar adhesion strength and cure speed specifications dominates flexible-grade and fast-setting segments, separating premium formulations from commodity construction powders. Price differentiation hinges on REACH residual monomer certification and FDA indirect food-contact compliance tiers. Cost compression in standard-grade tile adhesive powders intensifies from ethylene feedstock volatility and Indian PLI-scheme domestic production incentives. Small-scale dry mortar compounders exhibit highest price sensitivity; pharmaceutical packaging laminators accept substantial premiums for pre-certified supply chains.
Supply Chain Analysis
REACH and FDA qualification gating funnels procurement toward pre-certified raw material sources, compressing the European supplier base toward integrated producers with in-house purification infrastructure. Manufacturing concentrates in Germany, China, and India, with the Rhine-Ruhr corridor serving pharmaceutical packaging and the Yangtze River Delta anchoring interior finishing systems. Feedstock dependencies span crude-linked ethylene, vinyl acetate monomer, and specialized silane crosslinking agents. Single-source vulnerability runs through non-integrated compounders lacking captive olefin supply. Distribution runs through direct mill relationships for tier-one construction contractors and traditional chemical distributors for mid-scale compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around integrated producers with captive ethylene-vinyl acetate supply chains, as REACH registration costs and residual monomer purification requirements force smaller European compounders toward exit or toll-manufacturing subordination.
For Market Incumbents: Hedge margin erosion in standard-grade construction powders by expanding silane-crosslinked flexible-grade capacity for European thermal retrofit mandates. Prioritize backward integration into ethylene feedstocks to insulate against crude-linked volatility. Defend specification control through localized technical service teams in India's Delhi-Mumbai Industrial Corridor. For New Entrants and Emerging Players: Capture white-space in carbon-cured dry mortar systems compatible with EU Green Deal decarbonization pathways, where incumbent VAE suppliers lag in CO2-cured cement chemistry adaptation. Target India's PLI-scheme construction chemical procurement for domestic manufacturing partnerships. Lead with digital procurement platforms that bypass traditional distributor networks for direct contractor relationships. For Investors and Strategic Acquirers: Re-rating potential sits with mid-cap emulsion polymerization houses possessing silane grafting capability and pre-certified REACH registration, given ECHA enforcement tightening residual monomer thresholds. Long-term viability favors producers with dual-use pharmaceutical packaging and construction material certifications. Watch for inflection in Indian BIS import substitution mandates accelerating domestic capacity buildout.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethylene Feedstocks | Captive olefin supply insulates margin stability from crude-linked volatility affecting non-integrated compounders. |
| Silane Crosslinking Technology Licensing | Hybrid VAE-ethylene architectures consolidate specification control in European facade durability warranty markets. |
| Direct Contractor Distribution Platforms | Digital procurement bypasses traditional channels, capturing margin and specification authority in Indian infrastructure. |
| REACH Pre-Certification Investment | In-house analytical infrastructure filters smaller competitors from pharmaceutical packaging adhesive supply chains. |
| Carbon-Cured Cement Compatibility R&D | CO2-cured dry mortar alignment captures EU Green Deal prefabricated construction element demand. |
Research Approach
Independent corroboration across plant managers at emulsion polymerization facilities, procurement leads at downstream dry mortar compounders, distribution channel partners, and technical R&D directors at adhesive formulators underwrites the qualitative findings. Secondary validation draws from customs and trade data, Cefic industry reports, SEC 10-K chemical segment disclosures, and BIS certification registries. Bottom-up volume modeling triangulates against top-down ethylene-vinyl acetate feedstock demand estimates.
Comparable historical reference periods spanning construction cycle expansions and regulatory enforcement phases anchor the projection horizon across the analysis window. Segmentation dimensions include grade tier (standard, flexible, fast-setting), end-use industry (construction, packaging, coatings), physical form (fine powder, granules), and regional production hub. CAGRs derive from elasticity-adjusted demand curves incorporating ethylene feedstock cost trajectories and PLI-scheme capacity addition schedules.
The model holds under sustained REACH and FDA enforcement intensity; deviation in regulatory relaxation or feedstock cost collapse would shift competitive advantage toward non-integrated toll manufacturers. Forecasts reflect assumptions regarding construction spending trajectories and certification timeline rigidity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Polymer Resin Market
Polymers & Resins
Hybrid Polymer Market
Polymers & Resins
Soft PVC Sealing Strip Market
Polymers & Resins
Tie Layer Resin Market
Polymers & Resins
Polyolefin Wax Market
Polymers & Resins
Polysulfide Resin Market
Polymers & Resins
Styrene Acrylonitrile (SAN) Market
Polymers & Resins
Global Polybutene Market
Polymers & Resins
Silicone Resins Market
Polymers & Resins
Methacrylate Monomers Market
Polymers & Resins
Polycarbonate Resin Market
Polymers & Resins
Polyimides Market
Polymers & Resins
Basic Methacrylate Copolymer Market
Polymers & Resins
Polymers for Electric Vehicle (EV) Market
Polymers & Resins
Global Specialty Polystyrene Resin Market
Polymers & Resins
Hydrocarbon Resins Market