
 Oxygen Barrier Materials Market | 2026-2036
Oxygen Barrier Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Oxygen Barrier Materials Market Analytics
Capital-intensity divergence between integrated resin producers and downstream converters is rotating competitive advantage toward firms controlling polymer supply chains. Amcor leverages captive ethylene vinyl alcohol capacity across European extrusion lines. Kuraray Co., Ltd. anchors its position through proprietary polyvinyl alcohol resin synthesis. Toray Industries Inc. differentiates via biaxially oriented polyamide film leadership in Asian pharmaceutical packaging.
Oxygen barrier materials are engineered polymers and multilayer structures designed to limit oxygen transmission rates below 1 cc/m²/day under standard test conditions, preserving product integrity in sensitive applications. Co-extrusion technology dominates high-volume food packaging where ethylene vinyl alcohol cores deliver cost-efficient barrier performance. Lamination occupies premium pharmaceutical segments demanding hermetic seal integrity and pinhole-free construction. Coating approaches gain traction in electronics applications seeking thinner, lighter barrier solutions.
FDA food contact substance notifications govern material approval for US pharmaceutical and food packaging applications, while EU REACH restrictions on perfluorinated substances reshape coating chemistry development. EFSA migration limits for polyamide oligomers directly constrain formulation choices in European food contact applications. Stakeholders must monitor evolving extended producer responsibility frameworks as recyclability mandates intensify scrutiny of multilayer barrier structures.
Market Dynamics
EU REACH restrictions on perfluorinated substances and the Packaging and Packaging Waste Regulation are forcing material substitution across European flexible packaging, redirecting converter investment toward recyclable multilayer structures and bio-based barrier coatings.
Growth Catalysts
- Pharmaceutical shelf-life mandates:Tightened stability requirements for biologics and vaccines are expanding demand for hermetic blister packaging with sub-1 cc/m²/day oxygen transmission rates.
- German converter clustering:Flexible packaging production concentrates around Düsseldorf and Hamburg, creating localized supply efficiency and just-in-time delivery advantages for barrier film buyers.
- EFSA migration limits:Stricter polyamide oligomer thresholds in food contact applications are accelerating validation of alternative barrier polymers in European dairy and meat packaging.
Market Restraints
- Ethylene vinyl alcohol supply concentration:Captive resin production by integrated petrochemical majors limits independent converter access to EVOH grades, constraining capacity expansion for specialty barrier films.
- Multilayer recyclability friction:Current mechanical recycling infrastructure cannot process five-to-seven layer barrier structures, exposing converters to extended producer responsibility cost penalties under evolving EU frameworks.
- Bio-based barrier performance gaps:Cellulose nanofiber and polylactic acid alternatives exhibit moisture sensitivity and inferior oxygen barrier versus synthetic benchmarks, restricting adoption in high-humidity pharmaceutical applications.
Strategic Opportunities
- India pharmaceutical packaging:CDSCO enforcement of stability testing guidelines for temperature-sensitive generics is creating demand for barrier blister lidding among Mumbai and Hyderabad formulation clusters.
- Atomic layer deposition convergence:Integration of ALD aluminum oxide coatings with polymer substrates enables sub-micron barrier layers for flexible electronics and quantum dot displays.
- Deposit-return scheme alignment:EU member state implementation of packaging deposit systems rewards mono-material barrier designs with simplified sorting and higher recycling value capture.
Industry Challenges
- Co-extrusion die engineering scarcity:Specialized tooling design for nine-layer and eleven-layer barrier structures requires expertise concentrated among German and Austrian equipment manufacturers, creating talent bottlenecks for capacity scaling.
- Migration testing timeline compression:EFSA and FDA notification pathways for novel food contact substances extend eighteen to thirty-six months, delaying commercialization of bio-based barrier formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oxygen Barrier Materials Market |
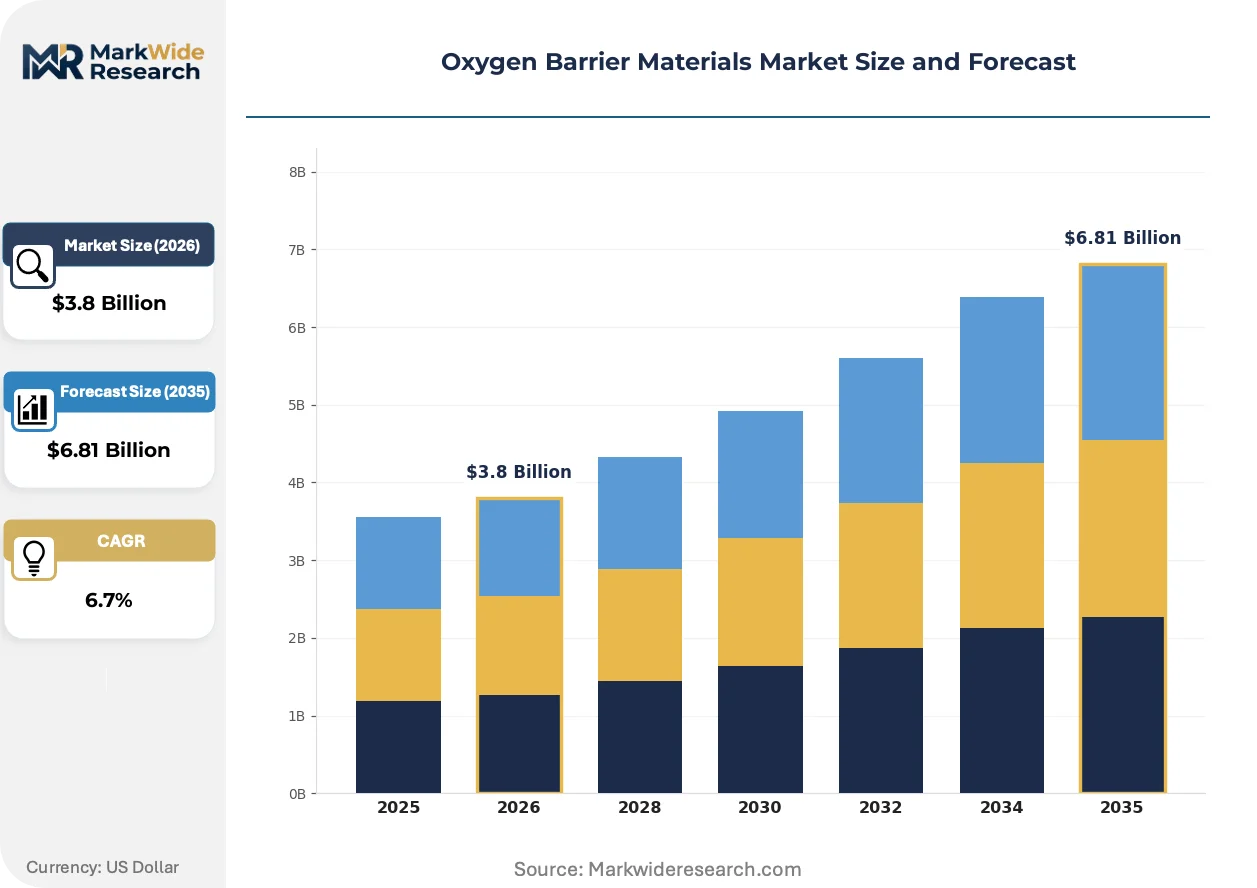
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polyamide, Ethylene Vinyl Alcohol, Polypropylene Application: Food Packaging, Pharmaceuticals, Electronics, Automotive End User: Food & Beverage, Healthcare, Consumer Electronics, Automotive Parts Technology: Co-extrusion, Lamination, Coating, Others |
| Companies Covered | Amcor, Berry Global Inc., Mondi, Sealed Air, Dupont Teijin Films, Kuraray Co., Ltd., Toppan Inc., Toray Industries Inc., Smurfit Westrock, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oxygen Barrier Materials Market Evolving Landscape
Barrier material innovation is pivoting from incremental polymer modification toward structural redesign of multilayer architectures and deposition technologies. Three converging developments are redefining performance benchmarks and manufacturing economics.
Plasma-enhanced chemical vapor deposition is decomposing the traditional trade-off between barrier performance and film thickness. Electronics manufacturers in South Korea and Japan are adopting PECVD silicon oxide coatings for foldable display encapsulation, achieving water vapor transmission rates below 10⁻⁶ g/m²/day at sub-micron thicknesses. This technology is decomposing incumbent aluminum foil laminates in premium consumer electronics packaging.
REACH restrictions on perfluorinated substances are eliminating C6 and C8 fluorochemicals from grease-resistant barrier coatings. Paperboard converters serving European food service markets are migrating to clay-based and bio-wax alternatives, accepting modest barrier degradation to maintain regulatory compliance. Dairy and ready-meal segments are absorbing the highest formulation switching costs.
Buyer consolidation among European retail private-label chains is compressing supplier qualification cycles. Lidl and Aldi Süd are unbundling technical specification development from incumbent film suppliers, engaging directly with resin producers for custom EVOH copolymer grades. This disintermediation is most pronounced in German discount retail meat and cheese packaging procurement.
Oxygen Barrier Materials Market Segmentation
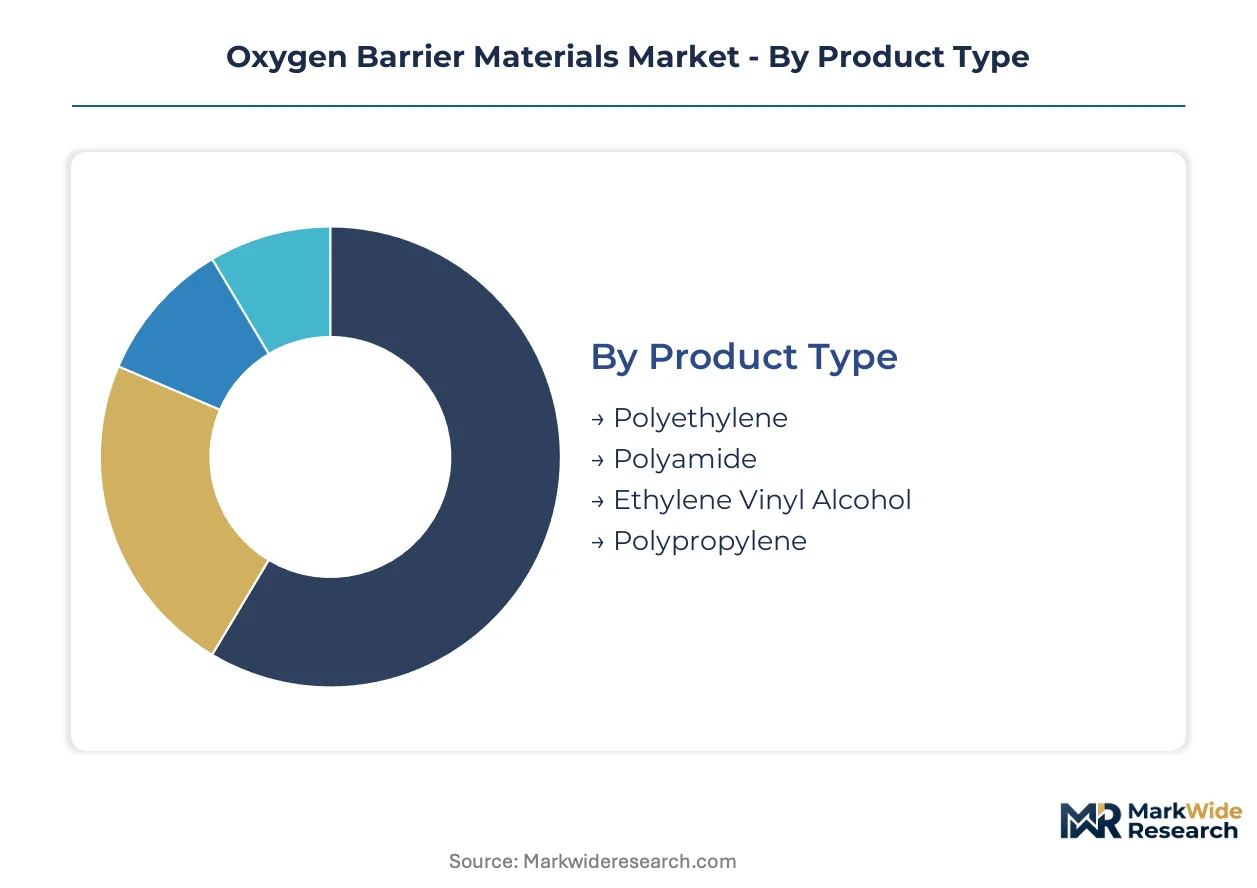
Oxygen barrier materials fragment across polymer chemistry, application performance requirements, and manufacturing technology. Each segmentation dimension reveals distinct margin structures and channel access patterns that shape supplier positioning.
Product Type:
Material selection flows through converter capabilities and end-use certification requirements, with resin producers capturing value upstream of film extrusion.
- Ethylene Vinyl Alcohol:Co-polymerized ethylene content tunes oxygen transmission from 0.5 to 3 cc/m²/day. German flexible packaging converters around Düsseldorf and Hamburg absorb the majority of European EVOH film supply for meat and cheese barrier applications.
- Polyamide:Biaxially oriented PA6 and PA6/6 grades deliver puncture resistance alongside barrier performance. Toray Industries anchors Asian pharmaceutical blister packaging demand through proprietary biaxial orientation lines in Japan and South Korea.
- Polyethylene:Metallocene-catalyzed linear low-density grades serve as sealant layers in multilayer structures rather than primary barriers. Cost positioning enables high-volume snack food packaging where moderate barrier suffices.
- Polypropylene:Oriented PP films with vapor-deposited aluminum oxide coatings address moisture-sensitive electronics packaging. South Korean display manufacturers specify these constructions for foldable device encapsulation.
By volume, Polyethylene leads. By growth pace, Ethylene Vinyl Alcohol is climbing the fastest.
Application:
End-use performance thresholds segment the market into food contact, pharmaceutical hermetic, and industrial precision categories with diverging certification burdens.
- Pharmaceuticals:Blister lidding and cold-form foil replacements demand sub-1 cc/m²/day oxygen transmission with hermetic seal integrity. CDSCO enforcement of stability guidelines in Mumbai and Hyderabad formulation clusters is expanding specification adoption.
- Food Packaging:Modified atmosphere packaging for red meat and cheese drives five-to-seven layer co-extruded structures. EU Packaging and Packaging Waste Regulation recyclability mandates are forcing material substitution toward mono-material barrier designs.
- Electronics:Quantum dot displays and flexible circuits require water vapor transmission below 10⁻⁶ g/m²/day. Plasma-enhanced chemical vapor deposition of silicon oxide is displacing aluminum foil laminates in premium South Korean consumer electronics.
- Automotive:Fuel system components and battery pack membranes specify heat-resistant barrier grades. Nylon-based constructions dominate under-hood applications where temperature cycling exceeds 120°C.
Food Packaging generates the highest absolute volume. Pharmaceuticals commands the steepest expansion trajectory.
End User:
Buyer concentration and qualification cycles vary sharply, with retail private-label consolidation compressing supplier selection timelines in European food segments.
- Food & Beverage:Dairy and ready-meal processors absorb the highest formulation switching costs as REACH restrictions eliminate C6 and C8 fluorochemicals from grease-resistant coatings. Clay-based and bio-wax alternatives trade barrier performance for regulatory compliance.
- Healthcare:Biologics and vaccine stability requirements tighten shelf-life mandates, expanding hermetic blister demand. EMA guidelines on container closure integrity drive specification toward pinhole-free constructions.
- Consumer Electronics:Foldable display manufacturers in Japan and South Korea specify sub-micron PECVD barrier layers. Atomic layer deposition convergence enables thinner, lighter encapsulation solutions.
- Automotive Parts:Electric vehicle battery pack venting membranes and fuel cell humidifier components require hydrolysis-resistant barrier grades. OEM qualification cycles extend 24-36 months.
Food & Beverage dominates current procurement volume. Healthcare shows the strongest forward momentum.
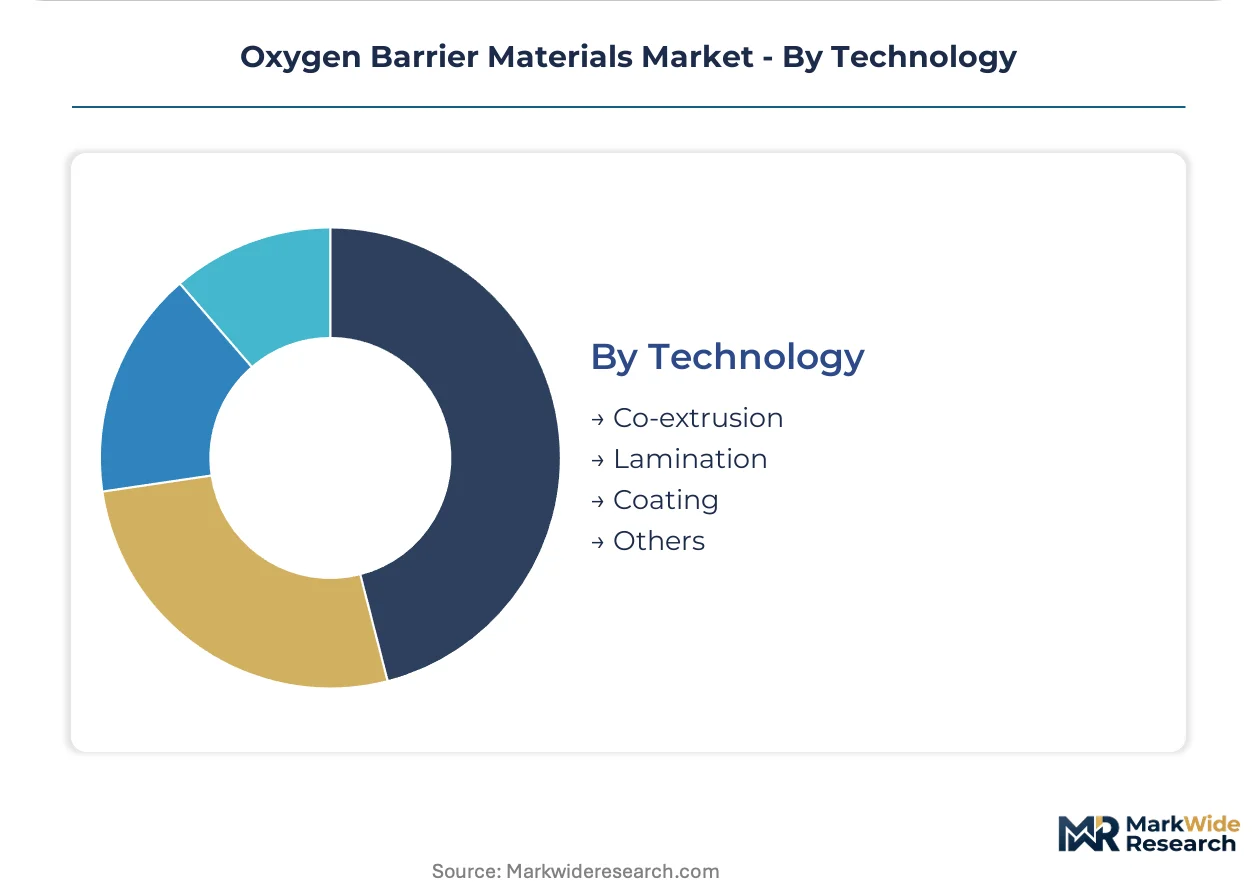
Technology:
Process selection locks in capital intensity and layer count capability, with equipment scarcity constraining capacity scaling for the most complex architectures.
- Co-extrusion:Nine-layer and eleven-layer die technology concentrates among German and Austrian equipment manufacturers. High-throughput lines serve commodity snack and meat packaging where cost efficiency outweighs premium performance.
- Lamination:Adhesive and extrusion lamination occupies pharmaceutical segments demanding hermetic seal integrity. Pinhole-free construction justifies higher unit economics against co-extruded alternatives.
- Coating:Atomic layer deposition and plasma-enhanced chemical vapor deposition enable sub-micron barrier layers for electronics. Thinner constructions reduce material intensity while achieving synthetic polymer performance.
- Others:Metallization and bio-based deposition approaches serve niche applications seeking decorative or sustainable differentiation. Performance gaps versus synthetic benchmarks restrict mainstream adoption.
Co-extrusion leads in installed capacity. Coating is gaining share fastest in value-added segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across oxygen barrier material procurement. European retail chains absorb premium pricing for recyclable multilayer compliance, while Asian pharmaceutical converters prioritize unit economics over sustainability premiums in generic drug packaging.
Germany
Flexible packaging converters cluster around Düsseldorf and Hamburg, driving concentrated demand for ethylene vinyl alcohol films in meat and cheese applications. ECHA REACH restrictions on perfluorinated substances force rapid coating chemistry substitution toward bio-wax alternatives. The Düsseldorf corridor hosts nine-layer co-extrusion capacity serving discount retail private-label chains.
United States
FDA food contact substance notifications govern pharmaceutical blister material approvals, extending qualification timelines for novel barrier polymers. Biologics manufacturers in Massachusetts and North Carolina tighten shelf-life specifications, expanding hermetic packaging demand. The FDA notification pathway creates eighteen-month commercialization delays for bio-based barrier entrants.
India
CDSCO enforcement of stability testing guidelines for temperature-sensitive generics accelerates barrier blister adoption in Mumbai and Hyderabad formulation clusters. The country's national pharmaceutical regulator mandates container closure integrity documentation for export-oriented facilities. Hyderabad's vaccine production corridor sources multilayer lidding films through direct resin producer relationships, bypassing traditional converter channels.
South Korea
Display manufacturers specify plasma-enhanced chemical vapor deposition barrier layers for foldable device encapsulation, achieving water vapor transmission below 10⁻⁶ g/m²/day. The Ministry of Trade, Industry and Energy supports domestic equipment fabrication for sub-micron coating systems. Seoul-based electronics packaging engineers collaborate directly with polymer substrate developers, compressing supplier qualification cycles.
Japan
Toray Industries anchors Asian pharmaceutical blister demand through proprietary biaxial orientation capacity. The Pharmaceuticals and Medical Devices Agency enforces container closure integrity guidelines that favor pinhole-free laminate constructions over co-extruded alternatives. Osaka-Kobe industrial corridor concentration enables just-in-time barrier film delivery to medical device manufacturers.
Oxygen Barrier Materials Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, creating a two-speed competitive structure. Integrated resin producers with captive ethylene vinyl alcohol capacity capture upstream margin pools, while downstream converters compete on die engineering and layer-count precision. Three archetypes dominate: petrochemical majors with backward polymer integration, specialized film extruders with proprietary co-extrusion tooling, and coating technology licensors serving electronics segments. Capacity expansion and strategic partnerships constitute the dominant competitive moves, as equipment scarcity constrains organic scaling.
Among Asia-Pacific materials specialists, Kuraray Co., Ltd. and Toray Industries Inc. occupy positions emphasizing proprietary resin synthesis and biaxial orientation leadership respectively. Amcor represents the integrated packaging conglomerate archetype with captive supply chain control across European extrusion networks. These three entities exemplify how geographic clustering around Düsseldorf, Osaka, and Melbourne shapes competitive positioning through proximity to converter demand and regulatory influence.
| Leading Market Players |
|---|
| Amcor |
| Berry Global Inc. |
| Mondi |
| Sealed Air |
| Dupont Teijin Films |
| Kuraray Co., Ltd. |
| Toppan Inc. |
| Toray Industries Inc. |
| Smurfit Westrock |
| Others |
Value Network & Pricing Analysis
FDA food contact substance notifications gate both supplier qualification timelines and price differentiation between certified and uncertified barrier material grades in pharmaceutical applications. EFSA migration limits for polyamide oligomers create parallel certification premiums in European food packaging, compressing margins for converters unable to secure compliant resin supply.
Pricing Analysis
After-sales technical service contracts and migration testing support packages drive lifetime value capture for resin producers serving pharmaceutical converters. Three-tier pricing structure across premium, standard, and economy levels separates FDA-notified EVOH grades from generic food-contact variants and commodity sealant layers. Price differentiation rests on certification tier and volume scale, with Mumbai formulation clusters absorbing premium lidding film costs for CDSCO-compliant exports. Pricing pressure stems from German discount retail chains unbundling specifications and engaging resin producers directly, bypassing converter markups. Healthcare buyers exhibit lowest price sensitivity due to stability mandate compliance requirements, while snack food processors prioritize unit economics over barrier performance.
Supply Chain Analysis
Just-in-time delivery preferences dominate German flexible packaging corridors around Düsseldorf and Hamburg, where converter clustering enables rapid response to retail private-label demand fluctuations. Geographic supply concentrates in Germany, Japan, and South Korea, with ethylene vinyl alcohol resin synthesis anchored in integrated petrochemical complexes near Osaka and Rotterdam. Raw material dependencies include ethylene feedstock, vinyl alcohol monomer, and metallocene catalyst systems. Single-source vulnerability from captive EVOH production by petrochemical majors constrains independent converter expansion. Distribution runs through converter networks with direct resin producer relationships increasingly displacing traditional film supplier channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges from regulatory divergence between FDA notification pathways and EU REACH restrictions, creating niche positions for regionally specialized barrier formulations. Pharmaceutical shelf-life mandates and electronics encapsulation demands are splintering the addressable market into performance-tiered segments.
For Market Incumbents: Secure captive ethylene vinyl alcohol capacity through backward integration or long-term offtake agreements with petrochemical majors to defend against resin supply concentration. Invest in nine-layer and eleven-layer co-extrusion die engineering capabilities, as equipment scarcity concentrates among German and Austrian manufacturers and locks out capacity scaling for competitors. Prioritize FDA notification pathway expertise to accelerate bio-based barrier commercialization and offset REACH-driven formulation switching costs in European dairy segments.
For New Entrants and Emerging Players: Anchor in Indian pharmaceutical packaging corridors around Mumbai and Hyderabad, where CDSCO enforcement of stability guidelines creates specification demand without incumbent converter lock-in. Target atomic layer deposition coating services for South Korean foldable display manufacturers, leveraging sub-micron barrier technology gaps versus established polymer film suppliers. Pursue direct resin producer partnerships to bypass traditional converter qualification cycles and compress time-to-revenue.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with underutilized barrier film assets in European extrusion networks. Long-term viability favors specialists with proprietary co-extrusion tooling and pharmaceutical certification portfolios over commodity converters exposed to retail pricing compression. Watch for EFSA polyamide oligomer threshold tightening as inflection signal for alternative barrier polymer validation demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into EVOH Resin | Captive supply secures margin pools as petrochemical majors restrict independent converter access to barrier grades. |
| Atomic Layer Deposition Capacity Buildout | Sub-micron coating systems address South Korean display manufacturer specifications for foldable device encapsulation. |
| FDA Notification Pathway Investment | Eighteen-month commercialization acceleration enables bio-based barrier entrants to outpace EFSA migration testing timelines. |
| Nine-Layer Co-Extrusion Tooling Acquisition | German and Austrian equipment manufacturer relationships unlock capacity scaling for complex multilayer meat and cheese packaging. |
| Direct Resin Producer Partnership | Bypassing traditional converter channels compresses supplier qualification cycles for Mumbai and Hyderabad pharmaceutical clusters. |
Research Methodology
Operator-level perspectives from extrusion line engineers, pharmaceutical packaging procurement managers, EVOH resin technical sales directors, and food converter plant managers anchored the qualitative base. These primary insights combined with secondary validation from FDA food contact substance notification databases, EFSA migration limit guidance documents, CDSCO stability testing circulars, and EU Packaging and Packaging Waste Regulation drafts. Bottom-up volume modeling across polymer chemistry tiers triangulated against top-down petrochemical capacity assessments.
Sensitivity analysis tested forecast robustness across alternative EVOH supply concentration scenarios and REACH restriction implementation timelines. Segmentation dimensions modeled include polymer chemistry type, application performance threshold, manufacturing technology capability, and regional regulatory cluster. CAGRs derived from regression analysis of historical price-volume relationships and forward capacity expansion announcements. Industry-specific inputs incorporated EFSA polyamide oligomer threshold evolution and CDSCO enforcement intensity for temperature-sensitive generics.
Decision-makers should treat outputs as directional under base assumptions of sustained pharmaceutical shelf-life tightening and EU recyclability mandate implementation; material deviation would warrant model refresh. Forecasts reflect documented assumptions regarding EVOH resin supply availability and coating chemistry substitution timelines. Revision becomes warranted when bio-based barrier performance gaps versus synthetic benchmarks narrow sufficiently to trigger pharmaceutical application adoption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Membrane Materials
Middle East and Africa Ceramic Membranes Market
Membrane Materials
Inorganic Ion Exchange Materials Market
Membrane Materials
Global Vapor Permeability Films Market
Membrane Materials
Vapor Barrier Films Market
Membrane Materials
Thermoplastic Polyolefin Membranes Market
Membrane Materials
Breather Membranes Market
Membrane Materials
Global Roofing Membranes Market
Membrane Materials
Membrane Bioreactor Market
Membrane Materials
Europe Gas Barrier Membrane Market
Membrane Materials
Global Breathable Membranes Market
Membrane Materials
Reverse Osmosis (RO) Membrane Market
Membrane Materials
Bitumen Waterproofing Membrane Market
Membrane Materials
Liquid Applied Membranes Market
Membrane Materials
TPO Roofing Membrane Market
Membrane Materials
North America Single-Ply Membrane Market
Membrane Materials
Global Track Etched Membrane Market