
 C9 Resin Market | 2026-2036
C9 Resin Market Size, Share, and Industry Trends Forecast 2026-2036
C9 Resin Market Analysis
Market Context
The capital-intensity divergence between integrated refiners and specialty chemical producers is rotating competitive advantage toward upstream-backed players. ExxonMobil Corporation leverages its Gulf Coast cracking capacity to secure low-cost C9 feedstock streams. Kolon Industries, Inc. anchors its position through backward integration into naphtha cracking at its Yeosu complex. Arakawa Chemical Industries, Ltd. differentiates via hydrogenated resin technology for premium adhesive grades.
Technical Definition and Segments
C9 aromatic hydrocarbon resins are thermoplastic polymers produced by catalytic polymerization of cracked petroleum distillates with softening points typically ranging from 100°C to 150°C, serving primarily as tackifiers and performance enhancers in adhesive and coating formulations. C9 Resins dominate volume throughput due to their cost-positioning in bulk hot-melt applications, while C9 Modified Resins command margin premiums through hydrogenation and esterification upgrades for odor-sensitive end uses. The Adhesives application segment leads absolute consumption, though Coatings is gaining share as waterborne alkyd systems reformulate with aromatic tackifiers.
Regulatory Outlook
EPA emissions standards for hazardous air pollutants from petroleum refining constrain US C9 resin production economics, while REACH registration requirements in Europe mandate extensive substance characterization for aromatic hydrocarbon imports. China's MEE enforces dual carbon compliance timelines that elevate operating costs for non-hydrogenated resin output. Stakeholders must monitor feedstock cost pass-through mechanics and regional carbon border adjustments to optimize manufacturing footprint decisions.
Market Dynamics
Feedstock cost pass-through mechanics and hydrogenation technology gaps are fragmenting competitive positioning between integrated refiners and specialty resin producers. The divergence in capital intensity favors upstream-backed players with captive naphtha cracking capacity.
Growth Catalysts
- Hot-melt adhesive demand:Packaging sector reformulation toward solvent-free bonding systems is pulling C9 resin volumes into flexible food packaging and e-commerce fulfillment applications.
- REACH registration completion:European aromatic hydrocarbon importers with full substance characterization dossiers now access premium adhesive formulations requiring full supply chain transparency.
- Yeosu-Ulsan corridor expansion:South Korea's petrochemical cluster is consolidating hydrogenation capacity for odor-sensitive resin grades serving electronics and hygiene adhesive markets.
Market Restraints
- Crude C9 feedstock volatility:Steam cracker operating rate fluctuations in East Asia create input cost instability for non-integrated resin producers without naphtha cracking assets.
- EPA hazardous air pollutant standards:US petroleum refining emissions controls elevate compliance costs for aromatic hydrocarbon distillation and catalytic polymerization operations.
- Rosin ester substitution:Bio-based tackifiers from pine derivatives are capturing share in pressure-sensitive adhesive segments where odor and color specifications permit.
Strategic Opportunities
- Waterborne alkyd coating reformulation:Coatings manufacturers in Germany and France are integrating aromatic tackifiers into low-VOC architectural paint systems to replace solvent-borne alternatives.
- India BIS standardization:Pending quality benchmarks for hot-melt adhesives in consumer goods packaging will formalize import specifications and create first-mover advantages for certified suppliers.
- Digital inventory platforms:Specialty chemical distributors are deploying AI-driven demand forecasting to reduce working capital requirements for mid-volume C9 resin buyers.
Industry Challenges
- Catalytic hydrogenation expertise scarcity:Limited pool of process engineers capable of operating partial hydrogenation units for premium resin grades constrains capacity expansion timelines.
- Dual carbon compliance integration:China's MEE emissions audits require real-time monitoring retrofits at existing polymerization facilities, compressing project completion windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | C9 Resin Market |
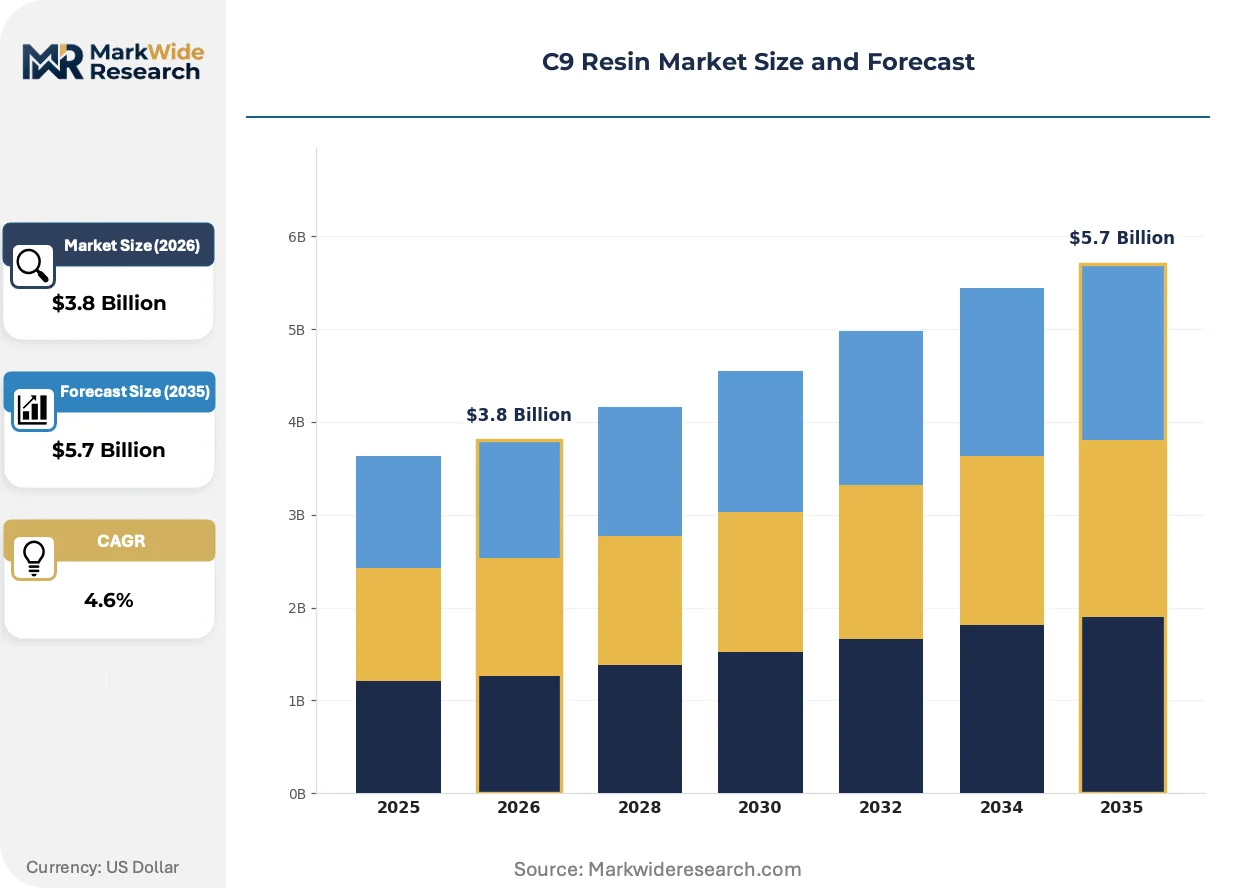
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: C9 Aromatic Hydrocarbons, C9 Resins, C9 Blends, C9 Modified Resins Application: Adhesives, Coatings, Sealants, Inks End User: Construction, Automotive, Electronics, Packaging Distribution Channel: Direct Sales, Distributors, Online Channels, Retail |
| Companies Covered | Eastman Chemical Company, ExxonMobil Corporation, Cray Valley, Kolon Industries, Inc., Arakawa Chemical Industries, Ltd., Neville Chemical Company, TotalEnergies, SABIC, ZEON Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
C9 Resin Market Emerging Trajectories
Partial hydrogenation protocols and waterborne formulation chemistry are decomposing the traditional premium-mass market boundary in aromatic tackifiers. These shifts favor producers with flexible catalytic platforms over fixed-asset commodity operators.
Partial hydrogenation technology is decomposing the odor-performance tradeoff that previously segmented C9 resin markets. Electronics and hygiene adhesive manufacturers in South Korea and Japan are adopting semi-hydrogenated grades at twice the rate of conventional aromatic resins. This capability compression is eroding the price premium commanded by fully hydrogenated hydrocarbon resins in non-food contact applications.
REACH substance characterization requirements for aromatic hydrocarbon imports are decomposing informal supply relationships between Asian producers and European formulators. ECHA compliance timelines now exceed eighteen months for new feedstock qualifications. Adhesive compounders in Germany and the Netherlands are consolidating supplier bases to reduce regulatory re-qualification burdens.
Specification-driven procurement is consolidating buyer power among multinational packaging converters. Tier-one hot-melt adhesive consumers are unbundling technical service from material supply, pressuring regional distributors to deliver formulation support without captive manufacturing. This disintermediation is most visible in the Benelux packaging corridor, where converters maintain direct supply agreements with Korean hydrogenated resin producers.
C9 Resin Market Segmentation
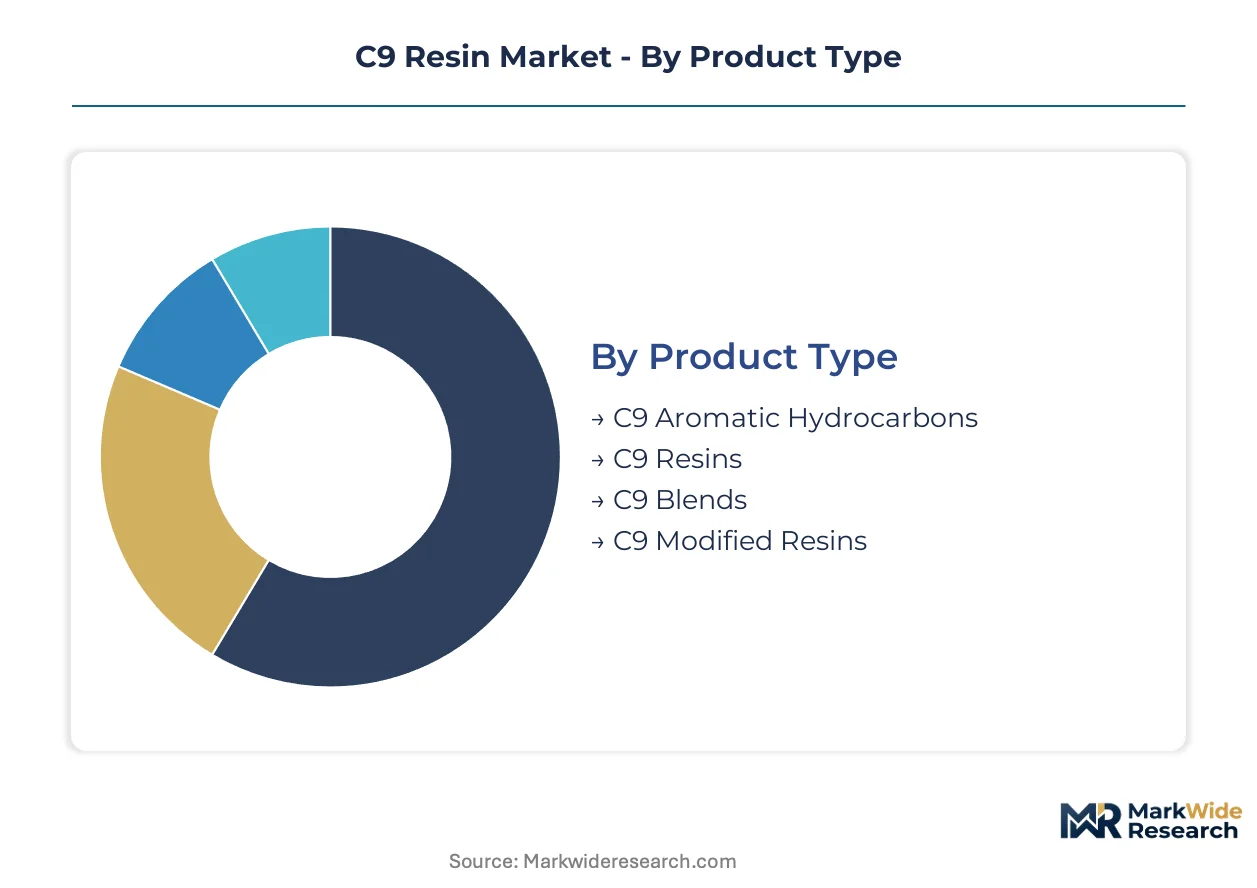
Segmentation in the C9 resin market tracks divergent margin structures across hydrogenation intensity, formulation chemistry, and buyer procurement sophistication. Product type and application splits reveal where integrated refiners extract returns versus where specialty producers command premiums.
Product Type:
Hydrogenation depth and catalytic upgrade intensity concentrate margin pools at opposite ends of this spectrum, with unmodified aromatic resins competing on feedstock access and modified grades on technical specification.
- C9 Aromatic Hydrocarbons:These cracked petroleum distillates serve as feedstock precursors rather than finished tackifiers, with value capture residing in naphtha cracking economics at Yeosu and Ulsan complexes. Korean integrated producers leverage captive steam cracker output to supply non-integrated resin manufacturers at cost-advantaged positions.
- C9 Resins:Standard catalytic polymerization yields thermoplastic polymers with softening points between 100°C and 150°C, dominating bulk hot-melt adhesive formulations where odor tolerance permits. Packaging converters in Germany and the Netherlands source these grades for flexible food packaging and e-commerce fulfillment applications.
- C9 Blends:Physical mixtures with aliphatic or rosin-based tackifiers balance cost and performance for mid-tier adhesive specifications.
- C9 Modified Resins:Hydrogenation and esterification upgrades deliver odor-sensitive grades for electronics and hygiene applications, with South Korean producers expanding partial hydrogenation capacity to serve Japanese electronics manufacturers.
The dominant share belongs to C9 Resins, while C9 Modified Resins is closing the gap fastest.
Application:
Formulation chemistry shifts—particularly waterborne alkyd system reformulation—are redistributing volume across solvent-borne replacement and traditional hot-melt channels.
- Adhesives:Hot-melt formulations in packaging and pressure-sensitive tapes consume the majority of aromatic tackifier volume, with specification unbundling separating technical service from material supply among Benelux converters. REACH-compliant supply chains now require eighteen-month qualification timelines, consolidating supplier relationships toward Korean hydrogenated resin producers.
- Coatinks:Waterborne alkyd architectural systems in France and Germany are integrating aromatic tackifiers to replace solvent-borne alternatives under low-VOC mandates.
- Sealants:Construction and automotive joint sealing applications demand specific softening point ranges for elastic recovery.
- Inks:Publication gravure and flexographic printing utilize aromatic resins for pigment wetting and gloss control.
Adhesives maintains volume leadership, though Coatings demonstrates the steepest expansion trajectory as regulatory pressure on solvent content intensifies.
End User:
Procurement sophistication varies sharply across these verticals, with multinational packaging converters consolidating supplier power while construction remains fragmented.
- Packaging:Tier-one hot-melt consumers unbundle technical service from material supply, pressuring regional distributors to deliver formulation support without captive manufacturing. India's pending BIS quality benchmarks for consumer goods packaging will formalize import specifications and create first-mover advantages for certified suppliers.
- Electronics:Japanese and Korean manufacturers of displays and semiconductors specify semi-hydrogenated grades at twice the rate of conventional aromatic resins, eroding price premiums previously commanded by fully hydrogenated alternatives.
- Construction:Sealant and waterproofing membrane applications drive steady demand for standard-grade resins with less specification intensity.
- Automotive:Interior bonding and NVH damping applications require odor-controlled formulations as OEMs tighten cabin air quality standards.
Packaging commands the largest volume position, while Electronics is gaining share fastest on hydrogenation upgrade demand.
Distribution Channel:
Channel selection reflects buyer scale and formulation complexity, with direct relationships consolidating among sophisticated compounders and distributors serving fragmented mid-volume accounts.
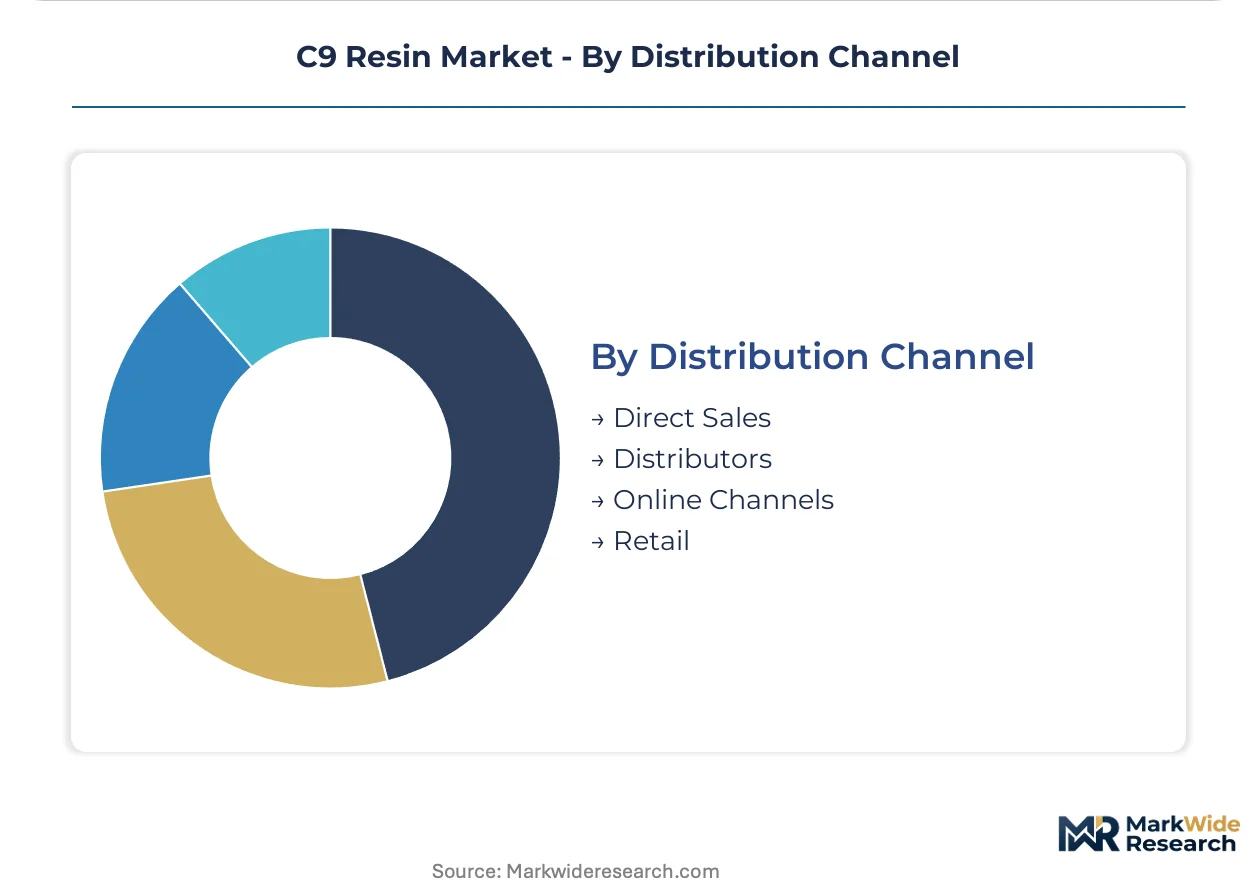
- Direct Sales:Multinational adhesive compounders and packaging converters in the Benelux corridor maintain direct agreements with Korean hydrogenated resin producers, bypassing distributor margins for volume commitments.
- Distributors:Specialty chemical distributors deploy AI-driven demand forecasting to reduce working capital requirements for mid-volume buyers without direct sourcing scale.
- Online Channels:Digital procurement platforms serve small-batch formulation laboratories and regional compounders seeking rapid qualification samples.
- Retail:Limited to maintenance-repair-operations segments and small construction applicators with minimal technical specification requirements.
Direct Sales holds the dominant position, while Distributors is expanding most quickly through digital inventory platform deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies, with East Asian manufacturers prioritizing hydrogenated grades for electronics while European buyers emphasize REACH-compliant supply chains for packaging adhesives. The United States maintains steady demand for standard aromatic resins in industrial applications despite emissions compliance costs. South Korea and Japan drive premium-grade adoption, whereas China and India concentrate on volume throughput for domestic packaging sectors.
China
Packaging converters in the Yangtze River Delta absorb the largest C9 resin volumes for flexible food packaging and e-commerce fulfillment applications. MEE dual carbon compliance timelines enforce real-time emissions monitoring retrofits at polymerization facilities, compressing project completion windows. The petrochemical corridor around Ningbo and Shanghai is consolidating hydrogenation capacity to serve odor-sensitive electronics manufacturers migrating from conventional aromatic grades.
South Korea
Electronics and hygiene adhesive manufacturers specify semi-hydrogenated C9 resins at twice the rate of conventional aromatic grades, eroding price premiums previously commanded by fully hydrogenated alternatives. Korean environmental regulations under the Ministry of Environment tighten volatile organic compound limits for adhesive formulations used in consumer goods. The Yeosu-Ulsan petrochemical cluster anchors backward integration into naphtha cracking, supplying captive feedstock streams for integrated resin producers.
Japan
Display and semiconductor manufacturers in the Kanto and Kansai regions specify odor-controlled tackifiers for cleanroom assembly operations. METI chemical substance management frameworks mandate extensive substance characterization for imported aromatic hydrocarbons, extending qualification timelines beyond eighteen months. The Nagoya-Tokyo industrial corridor concentrates procurement sophistication among tier-one electronics assemblers consolidating supplier relationships toward certified Korean hydrogenated resin producers.
Germany
Coatings manufacturers in Bavaria and North Rhine-Westphalia integrate aromatic tackifiers into waterborne alkyd architectural systems to replace solvent-borne alternatives under low-VOC mandates. REACH registration requirements enforce full supply chain transparency for aromatic hydrocarbon imports, consolidating supplier bases among adhesive compounders in the Benelux-German corridor. The Cologne-Düsseldorf chemical cluster concentrates formulation expertise for pressure-sensitive tape and label applications.
United States
Industrial adhesive compounders and packaging converters in the Gulf Coast and Midwest regions consume standard-grade C9 resins for bulk hot-melt applications where odor tolerance permits. EPA hazardous air pollutant standards elevate compliance costs for aromatic hydrocarbon distillation and catalytic polymerization operations. The Texas-Louisiana petrochemical corridor leverages integrated refinery-chemical complexes to secure low-cost feedstock streams for captive resin production.
C9 Resin Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in the C9 resin competitive structure. Upstream-backed players with captive naphtha cracking capacity command feedstock cost advantages over non-integrated resin manufacturers. Three archetypes dominate: integrated refiners leveraging Gulf Coast or Yeosu cracking assets, hydrogenation specialists serving electronics-grade specifications, and regional distributors deploying digital inventory platforms for mid-volume buyers. Capacity expansion in partial hydrogenation units and direct supply agreement consolidation represent the dominant competitive moves.
Within the integrated refiner archetype, ExxonMobil Corporation and SABIC exemplify upstream-backed positioning through captive feedstock access. Kolon Industries, Inc. occupies a distinctive position bridging integrated feedstock control with hydrogenation specialization for premium adhesive grades. Arakawa Chemical Industries, Ltd. anchors the hydrogenation-technology tier, representing the capability set required for odor-sensitive electronics and hygiene applications. Eastman Chemical Company and ZEON Corporation sit within the specialty resin producer segment, differentiated by formulation chemistry expertise rather than feedstock integration. The competitive dynamic compresses margins for standard aromatic grades while concentrating returns on semi-hydrogenated and fully hydrogenated product tiers.
| Leading Market Players |
|---|
| Eastman Chemical Company |
| ExxonMobil Corporation |
| Cray Valley |
| Kolon Industries, Inc. |
| Arakawa Chemical Industries, Ltd. |
| Neville Chemical Company |
| TotalEnergies |
| SABIC |
| ZEON Corporation |
| Others |
Supply Flow & Price Mechanics
Ninety-day feedstock qualification timelines at Korean hydrogenation units concentrate pricing power among Yeosu-Ulsan integrated producers while compressing margins for non-captive resin manufacturers dependent on spot naphtha purchases. This inventory-to-pricing linkage rewards backward integration into naphtha cracking and penalizes distributors without direct offtake agreements.
Pricing Analysis
Long-term offtake contracts dominate procurement between Korean integrated producers and Benelux packaging converters, insulating volume commitments from steam cracker rate volatility. Three-tier pricing structure across hydrogenated premium, standard aromatic, and economy unmodified grades reflects differentiation by odor specification and REACH certification status. Cost compression in standard aromatic tiers is intensifying because Chinese MEE emissions retrofits elevate operating expenses at non-integrated polymerization facilities. Mid-volume adhesive compounders exhibit highest price sensitivity, while Japanese electronics manufacturers prioritize specification compliance over unit cost.
Supply Chain Analysis
Inventory buffers at European distributors have compressed to three-to-four-week coverage as REACH re-qualification timelines extend supplier consolidation. Feedstock supply concentrates in South Korea, China, and Japan through naphtha cracking integration at Yeosu, Ningbo-Shanghai, and Kawasaki complexes. Catalytic hydrogenation catalysts and specialized process engineering talent constitute critical input dependencies. Single-source vulnerability runs through Korean partial hydrogenation capacity for electronics-grade specifications. Distribution runs through direct sales agreements between integrated producers and multinational packaging converters, with specialty distributors serving fragmented mid-volume accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specification fragmentation across odor grades, hydrogenation intensity, and REACH compliance tiers creates niche opportunities for focused entrants. Waterborne alkyd reformulation and hygiene adhesive demand are decomposing the traditional premium-mass boundary.
For Market Incumbents: Shield hydrogenation technology advantages by accelerating partial hydrogenation capacity additions at Yeosu-Ulsan complexes before Chinese MEE compliance timelines compress project windows. Secure captive naphtha cracking positions through upstream asset control or long-term feedstock offtakes to defend against crude C9 volatility. Invest in REACH substance characterization dossiers to consolidate European adhesive compounder relationships before eighteen-month qualification windows harden supplier lock-in. For New Entrants and Emerging Players: BIS certification fast-track for Indian hot-melt adhesive quality benchmarks represents the most penetrable regulatory entry point, with first-mover advantages accruing to suppliers completing certification before formal enforcement. Target waterborne alkyd coating reformulation in Germany and France where low-VOC mandates create specification gaps unmet by incumbent aromatic resin portfolios. Deploy digital inventory platforms with AI-driven demand forecasting to reduce working capital barriers for mid-volume buyers without direct sourcing scale. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because hydrogenation expertise scarcity and REACH compliance burdens are structurally advantaging integrated producers with captive feedstock and flexible catalytic platforms. Acquisition targets should prioritize Korean or Japanese specialty resin producers with partial hydrogenation capabilities and established electronics-grade qualification histories. Monitor Chinese MEE enforcement intensity as the critical inflection signal for capacity relocation decisions and margin compression timelines at non-compliant facilities.| Strategic Initiative | Industry Significance |
|---|---|
| Partial Hydrogenation Capacity Expansion | Korean producers at Yeosu-Ulsan complexes capture electronics-grade specification premiums before Chinese MEE retrofits compress completion windows. |
| REACH Substance Characterization Investment | Eighteen-month ECHA qualification timelines harden supplier relationships toward dossier-complete aromatic hydrocarbon importers in the Benelux corridor. |
| Backward Integration into Naphtha Cracking | Integrated refiners with Gulf Coast or Korean cracking assets secure cost-advantaged C9 feedstock streams against volatile spot market exposure. |
| Digital Inventory Platform Deployment | AI-driven demand forecasting reduces working capital requirements for mid-volume adhesive compounders without direct Korean producer relationships. |
| BIS Certification Pre-Positioning | First-mover certification for India's pending hot-melt adhesive quality benchmarks creates formalized import advantages before enforcement crystallizes. |
Methodological Framework
Operator-level perspectives from plant managers at naphtha cracking complexes, procurement leads at downstream adhesive compounders, distribution channel partners, and technical R&D directors anchored the qualitative base for this analysis. Primary fieldwork combined with secondary validation from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and ECHA registration databases established cross-source triangulation. Bottom-up volume modeling across hydrogenation grade tiers and top-down macro validation ensured convergence.
Sensitivity analysis around steam cracker operating rate assumptions and REACH compliance timeline scenarios framed the forecast uncertainty bands across the analysis window. Segmentation dimensions modeled include hydrogenation intensity grade, end-use application chemistry, regional production hub concentration, and buyer procurement sophistication tier. CAGRs derived from feedstock cost pass-through elasticity estimates and specification-driven demand shift projections incorporated waterborne alkyd penetration rates and electronics-grade hydrogenation adoption curves as industry-specific inputs.
Underlying assumptions cover sustained hot-melt adhesive demand in e-commerce packaging, MEE dual carbon enforcement intensity, and partial hydrogenation technology diffusion rates, with deviation risk concentrated in crude C9 feedstock volatility and rosin ester substitution acceleration in pressure-sensitive segments. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Global Polyphthalamide Market
Polymers & Resins
Epoxy Casting Potting Resin Market
Polymers & Resins
Polytrimethylene Terephthalate Market
Polymers & Resins
Thermoplastic Polyamide Elastomer (TPE) Market
Polymers & Resins
Middle East Engineering Plastics Market
Polymers & Resins
Methacrylate Monomers Market
Polymers & Resins
Polymer Memory Market
Polymers & Resins
Resorcinol Formaldehyde Resin Market
Polymers & Resins
Circular Polymers Market
Polymers & Resins
Global Bio Based Polyurethane Market
Polymers & Resins
Polyamide Precursors Market
Polymers & Resins
Orthophthalic Resins Market
Polymers & Resins
Global HBPA Epoxy Resin Market
Polymers & Resins
Polyether Amine Market
Polymers & Resins
Europe Polyvinyl Chloride (PVC) Market
Polymers & Resins
Polyamide-Imide (PAI) Market