
 Fire Resins Market | 2026-2036
Fire Resins Market Size, Share, and Industry Trends Forecast 2026-2036
Fire Resins Market Analytics
REACH is pivoting the European fire resins sector toward halogen-free formulations with stricter substance authorization protocols. Huntsman Corporation leverages its polyurethane technology leadership to serve aerospace laminates with low-smoke emission systems. BASF SE anchors its position through backward integration into phosphorus-based flame retardant precursors. Hexion Inc. specializes in phenolic resin chemistry for high-temperature composites where char formation determines survival ratings.
Fire resins are thermosetting polymers engineered with intumescent or char-forming additives to self-extinguish or resist flame propagation, typically achieving UL-94 V-0 ratings at thicknesses below three millimeters. Their primary purpose is to bind fiber reinforcements and fillers into structural composites that maintain load-bearing integrity during fire exposure. Phenolic resins command the highest temperature tolerance among product types but trade off processability, while epoxy resins capture premium margin pools in aerospace electrical insulation where outgassing specifications are tight. Construction applications dominate volume offtake driven by high-rise cladding regulations, though automotive under-the-hood applications are gaining fastest as OEMs reroute thermal management around battery packs.
FDA oversight of food-contact applications and EPA toxicity evaluations under TSCA constrain certain brominated chemistries in the US market, while REACH authorization and the EU F-Gas Regulation collectively push formulators toward phosphorus-nitrogen synergists. China's GB standards on building fire safety and SAMR product certification create parallel compliance tracks for exporters. Stakeholders must monitor regulatory divergence between halogen restriction timelines in Europe and slower phase-outs in other manufacturing jurisdictions to avoid stranded inventory or reformulation costs.
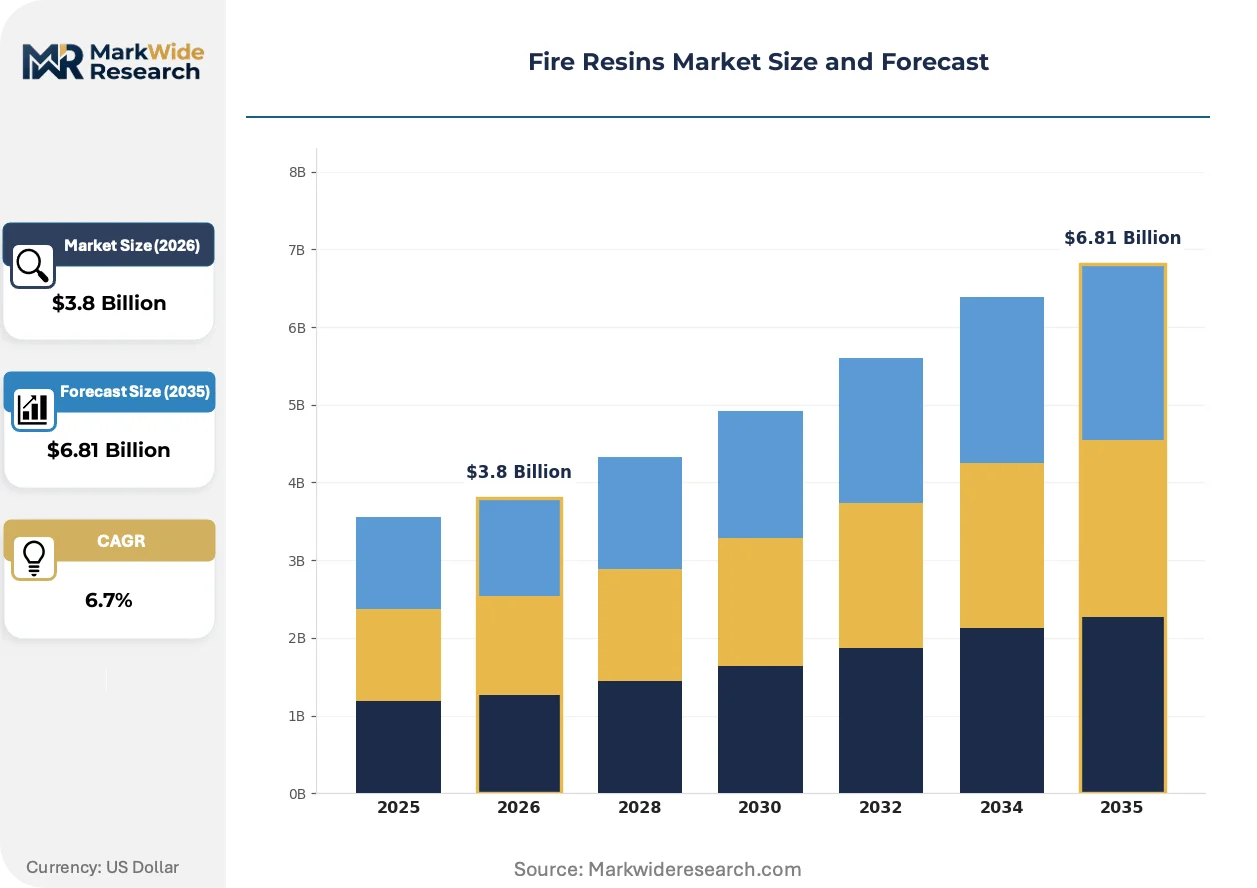
Market Dynamics
REACH substance authorization protocols are forcing a wholesale reformulation pivot across European supply chains, compelling producers to abandon legacy halogenated chemistries and rebuild additive portfolios around phosphorus-nitrogen synergists with shorter regulatory approval windows.
Growth Catalysts
- EU Green Deal embodied carbon rules:Chemical feedstock producers face tightening carbon accounting standards that favor bio-based resin precursors and low-emission curing processes in construction laminates.
- Automotive battery pack thermal management:OEMs rerouting high-voltage cabling and housing designs are specifying intumescent phenolic composites for under-the-hood fire containment systems.
- High-rise cladding mandates:Municipal building codes in Germany, France, and the UK now require UL-94 V-0 rated facade materials, pulling volume through certified resin channels.
Market Restraints
- Phosphorus feedstock concentration:Backward integration into phosphate rock processing is dominated by Chinese and Moroccan state-linked suppliers, creating price volatility exposure for European formulators.
- Phenolic resin processability trade-offs:High-temperature phenolics require extended cure cycles and specialized press equipment that constrains throughput in standard composite fabrication shops.
- Brominated chemistry phase-out friction:REACH authorization timelines for decabromodiphenyl ether are compressing faster than alternative flame retardant validation cycles, stranding some formulation pipelines.
Strategic Opportunities
- India building safety modernization:BIS adoption of GB-equivalent fire standards in commercial high-rises is opening import channels for halogen-free epoxy systems previously excluded by legacy specifications.
- Aerospace electrical insulation outgassing compliance:Tighter FAA and EASA smoke toxicity specifications are expanding addressable market for low-emission polyurethane laminates in cabin interior composites.
- Recyclable thermoset alternatives:Vitrimere chemistry and reversible crosslinking technologies are converging with fire performance requirements to enable circular material flows in automotive panels.
Industry Challenges
- Formulation chemist scarcity:The specialized knowledge required to balance intumescence, mechanical properties, and regulatory compliance across multiple jurisdictions is concentrating in a shrinking pool of experienced compounders.
- Multi-certification timeline compression:Simultaneous UL, EN, and GB standard testing for global product launches is extending qualification cycles and freezing R&D budgets in pre-commercial phases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fire Resins Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy Resins, Polyester Resins, Phenolic Resins, Polyurethane Resins Application: Construction, Automotive, Aerospace, Electrical End User: Manufacturers, Contractors, Distributors, Retailers Form: Liquid, Powder, Paste, Granular |
| Companies Covered | BASF SE, Huntsman Corporation, Hexion Inc., Ashland Global Holdings, LANXESS, Covestro AG, DuPont, SABIC, Scott Bader Company Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fire Resins Market Evolving Landscape
Formulation science is pivoting toward bio-based char formers and nano-additive dispersions that rewrite performance-cost trade-offs. Three developments are compressing competitive cycles and opening new specification categories.
Bio-derived phytic acid and lignin-based intumescent systems are expanding into construction panel applications where petrochemical feedstock disclosure requirements are hardening. German and Dutch builders are piloting these materials in public infrastructure tenders that mandate renewable content thresholds. The technology is compressing acceptance timelines for non-halogenated alternatives in cost-sensitive specification segments.
REACH authorization and the EU F-Gas Regulation are collectively tightening substance control protocols for flame retardant precursors. Formulators must now submit extended safety dossiers for phosphorus esters previously grandfathered under earlier annexes. Small and mid-scale compounders in Poland and the Czech Republic are consolidating testing resources to share regulatory compliance costs.
Certificate-driven procurement now dominates large construction and automotive programs, with buyers unbundling material supply from fabrication services to direct specification authority toward resin producers with pre-qualified regulatory packages. Tier-1 laminators in France and Italy are losing pricing leverage as OEMs contract directly with Huntsman and BASF for certified resin systems.
Fire Resins Market Segmentation
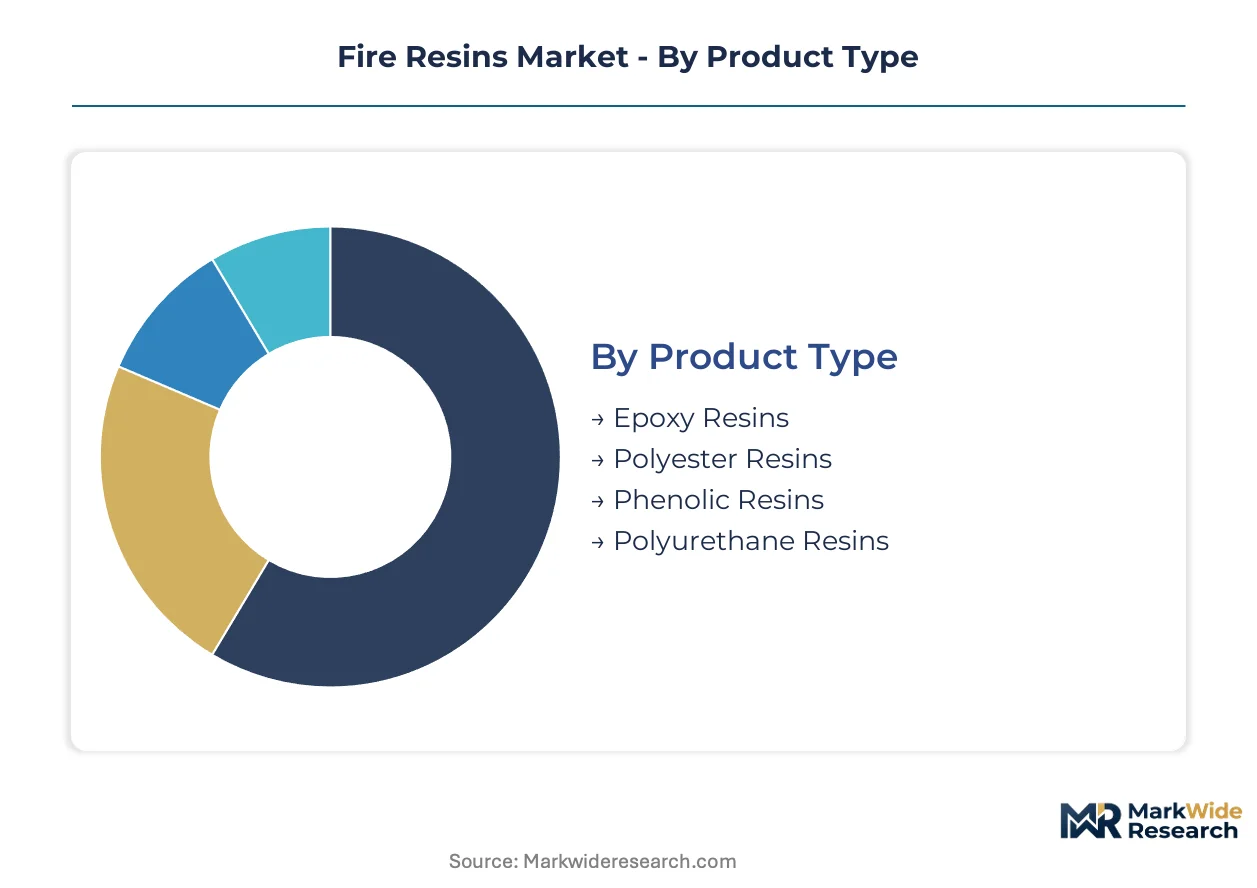
Fire resins segment along four critical dimensions that determine specification authority, margin capture, and regulatory compliance pathways. Product chemistry governs temperature tolerance and process economics. Application verticals impose divergent certification regimes. End-user channel structure dictates pricing leverage and technical service intensity.
Product Type:
Epoxy and phenolic resins split the market between premium-margin specification dominance and volume-driven construction offtake.
- Epoxy Resins:These thermosets achieve UL-94 V-0 ratings through phosphorus-nitrogen synergist integration while maintaining low outgassing profiles essential for aerospace electrical insulation. Demand concentrates in Germany's automotive cluster where OEMs specify them for battery pack housings facing EASA thermal runaway containment standards.
- Phenolic Resins:Char-forming chemistry delivers the highest temperature tolerance among commercial fire resins, enabling survival ratings in high-rise cladding applications. Builders in France and the UK now mandate these systems for facade composites under post-Grenfell regulatory frameworks, pulling volume through certified channels despite extended cure cycles.
- Polyester Resins:Cost-positioned formulations serve mass-market construction laminates where UL-94 V-0 compliance meets budget constraints.
- Polyurethane Resins:Low-smoke emission variants capture aerospace cabin interior specifications governed by FAA toxicity protocols.
Today's leader: Phenolic Resins. Tomorrow's challenger: Epoxy Resins.
Application:
Construction volume anchors the market while automotive and aerospace verticals capture disproportionate margin pools through certification complexity.
- Construction:High-rise cladding mandates across German, French, and UK municipal codes require UL-94 V-0 rated facade materials. This vertical absorbs the highest tonnage of phenolic and polyester systems, though price compression intensifies as certificate-driven procurement shifts specification authority upstream to resin producers.
- Automotive:OEMs rerouting thermal management around battery packs specify intumescent phenolic composites for under-the-hood fire containment. German automotive clusters drive fastest specification growth as manufacturers face EASA and KBA homologation requirements for electric vehicle platforms.
- Aerospace:Tighter FAA and EASA smoke toxicity specifications expand addressable market for low-emission polyurethane laminates in cabin interior composites.
- Electrical:Insulation applications demand epoxy systems with controlled outgassing profiles for high-voltage infrastructure.
Construction commands present volume. Automotive claims steepest expansion trajectory.
End User:
Channel structure determines who controls specification authority and captures technical service premiums.
- Manufacturers:Tier-1 composite fabricators and laminators purchase certified resin systems directly from producers like Huntsman and BASF, bypassing intermediaries as certificate-driven procurement consolidates buying power.
- Contractors:Construction firms source through approved distributor networks to meet project-specific UL and EN certification requirements for high-rise installations.
- Distributors:Regional chemical distributors maintain inventory positions for standard-grade polyester and epoxy formulations serving mid-market fabricators.
- Retailers:Limited role confined to small-volume maintenance and repair applications in non-structural fire protection.
Manufacturers tighten grip on specification. Distributors defend position in standard grades.
Form:
Physical form factor dictates processing equipment requirements and logistics economics across fabrication workflows.
- Liquid:Dominant format for epoxy and polyurethane systems enabling spray application and vacuum infusion in aerospace and automotive composites.
- Powder:Phenolic resins in powder form serve compression molding operations for electrical insulation components requiring precise charge weight control.
- Paste:Thixotropic formulations facilitate manual application in construction repair and retrofit scenarios.
- Granular:Solid phenolic novolacs feed automated metering systems for continuous panel production lines.
Liquid forms anchor premium applications. Powder formats defend position in electrical insulation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized formulation chemists cluster in Germany's industrial corridor and China's eastern manufacturing belt, anchoring regional capability centers that serve adjacent construction and automotive demand pools.
Germany
Automotive battery pack thermal management specifications from KBA and EASA drive intumescent phenolic composite demand. REACH authorization protocols force rapid halogen-free reformulation across supply chains. The Stuttgart-Munich corridor hosts BASF SE and LANXESS facilities serving OEMs with certified resin systems for electric vehicle platforms.
United States
High-rise cladding retrofit mandates in Chicago and New York pull phenolic resin volume through certified channels. EPA toxicity evaluations under TSCA constrain brominated chemistry deployment. The Gulf Coast petrochemical corridor maintains backward integration into phosphorus-based flame retardant precursors for construction laminates.
China
GB standards on building fire safety and SAMR product certification create compliance tracks for domestic and export markets. Dual carbon goals tighten embodied carbon accounting for chemical feedstocks. The Yangtze River Delta concentrates phenolic and epoxy production serving both local construction and European automotive export channels.
India
BIS adoption of GB-equivalent fire standards in commercial high-rises opens import channels for halogen-free epoxy systems. PLI scheme incentives for advanced materials support domestic formulation capacity buildup. The Gujarat-Maharashtra industrial corridor attracts Huntsman Corporation and Covestro AG technical service operations for building safety modernization.
France
Post-Grenfell regulatory frameworks mandate UL-94 V-0 rated facade materials for high-rise renovations. ECHA substance authorization timelines compress faster than alternative validation cycles. The Lyon-Toulouse aerospace cluster specifies low-emission polyurethane laminates for cabin interior composites under EASA smoke toxicity protocols.
Fire Resins Market Competitive Landscape
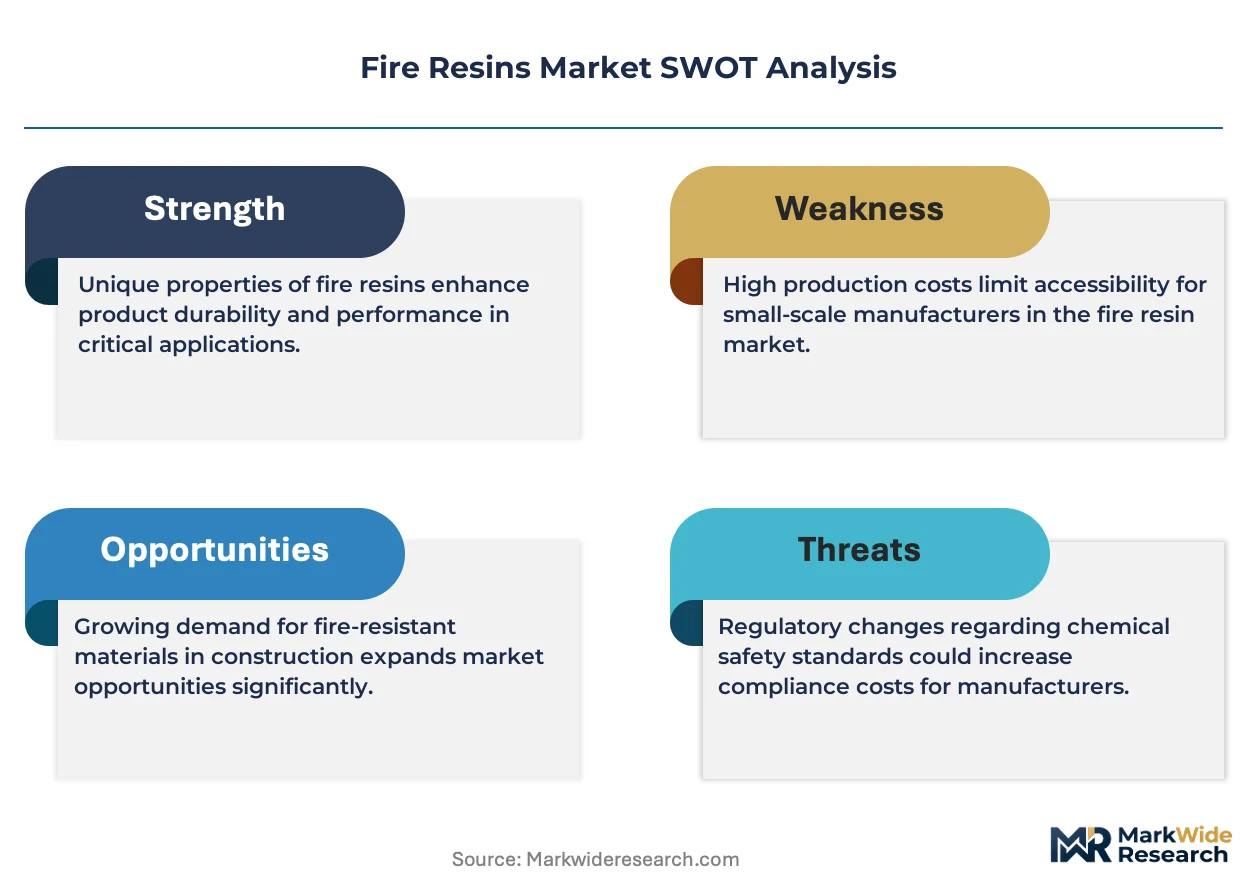
Diversified conglomerates compete with focused pure-play specialists across formulation tiers. The vendor base stratifies into three concentration levels: integrated chemical majors controlling phosphorus feedstock chains, mid-scale compounders sharing regulatory testing costs, and regional distributors defending standard-grade positions. Strategic moves center on backward integration into phosphate rock processing partnerships and certificate-driven procurement consolidation that shifts specification authority upstream.
Among German-based chemical majors, BASF SE anchors the integrated archetype through captive phosphorus-based flame retardant production, while LANXESS occupies a position within the specialty intermediates tier. Huntsman Corporation represents the polyurethane technology vector serving aerospace and automotive specifications. These three exemplify how geographic clustering around regulatory expertise and feedstock access determines competitive positioning.
| Leading Market Players |
|---|
| BASF SE |
| Huntsman Corporation |
| Hexion Inc. |
| Ashland Global Holdings |
| LANXESS |
| Covestro AG |
| DuPont |
| SABIC |
| Scott Bader Company Ltd. |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap compounders in Central Europe anchor supply discipline through generational capital patience, enabling them to absorb REACH compliance costs without margin collapse while larger conglomerates chase volume through aggressive unbundling of technical services.
Pricing Analysis
Certificate-driven procurement is unbundling material supply from fabrication services, compressing margins for Tier-1 laminators while rewarding resin producers with pre-qualified UL and EN packages. Three-tier pricing structure across premium certified, standard compliant, and economy unbranded tiers separates aerospace-specified epoxies from construction-grade polyesters. Cost compression in standard grades is intensifying because Chinese phosphate rock suppliers leverage state-linked pricing power. Contractors sourcing facade materials for German high-rises exhibit the sharpest price sensitivity, whereas OEMs specifying battery pack housings prioritize thermal runaway certification over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Moroccan and Chinese state-linked phosphate rock processors that feed phosphorus-based flame retardant precursors to European formulators. Manufacturing concentrates in Germany's industrial corridor, China's Yangtze River Delta, and the US Gulf Coast petrochemical belt. Feedstock dependencies include phosphate rock, phenol from cumene oxidation, and formaldehyde for phenolic resin synthesis. Tariff exposure on phosphorus ester imports from China threatens margin stability for mid-scale compounders. Distribution runs through certified direct channels for premium grades and regional chemical distributors for standard formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in halogen-free reformulation services where REACH compliance costs function as a moat against price-competitive imports from jurisdictions with slower regulatory phase-outs.
For Market Incumbents: Lock in specification authority by acquiring testing and certification capabilities that compress multi-standard validation timelines for global product launches. Backward integration into phosphorus-based flame retardant precursors defends against Moroccan and Chinese state-linked supply volatility. Threats from emerging bio-based char former specialists in Germany and the Netherlands demand accelerated R&D in lignin-derived intumescent systems to preempt specification shifts in public infrastructure tenders. For New Entrants and Emerging Players: Capture white-space in India's building safety modernization by importing halogen-free epoxy systems certified to BIS-adopted GB-equivalent standards ahead of domestic capacity buildup. The Gujarat-Maharashtra industrial corridor offers the most penetrable geography given PLI scheme incentives for advanced materials manufacturing. A technical service partnership with regional composite fabricators bypasses direct competition with established resin producers while building formulation credibility. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale Central European compounders sharing REACH compliance testing costs through industry consortia. Long-term viability across the analysis window hinges on regulatory divergence between European halogen restriction timelines and slower phase-outs elsewhere. The priority signal to watch is ECHA authorization timeline compression for phosphorus esters previously grandfathered under earlier annexes, which would accelerate consolidation pressure on undercapitalized formulators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphorus Precursors | Captive supply of phosphate-based flame retardants insulates BASF and LANXESS from Moroccan state-linked price volatility. |
| Multi-Certification Testing Consortium | Shared UL, EN, and GB validation costs enable Polish and Czech compounders to compete against integrated majors. |
| Bio-Based Char Former Pilot Programs | German and Dutch public infrastructure tenders with renewable content thresholds accelerate lignin-derived system acceptance. |
| Direct OEM Contracting Bypass | Huntsman and BASF specification authority consolidation squeezes Tier-1 French and Italian laminator margins. |
| India Technical Service Expansion | Huntsman Corporation and Covestro AG presence in Gujarat-Maharashtra captures BIS modernization import demand. |
Research Methodology
Bottom-up construction and automotive offtake modeling reconciled against top-down resin production capacity tracking forms the analytical core of this study. Primary interviews with plant managers at phenolic and epoxy facilities, procurement leads at German automotive OEMs, distribution channel partners serving French facade contractors, and technical R&D directors at phosphorus precursor operations informed demand and supply assumptions. Secondary validation drew from customs and trade data tracking phosphate rock and flame retardant precursor flows, Cefic sector reports on European chemical output, and SEC 10-K disclosures from listed resin producers. Triangulation across these sources anchored volume and value estimates.
Historical trendline analysis of phenolic and epoxy resin pricing against phosphate rock and phenol feedstock indices established baseline growth patterns across the projection horizon. Segmentation modeling covered product chemistry tier, application vertical, end-user channel structure, and physical form factor. CAGRs were derived from regression analysis of certified resin offtake against high-rise cladding mandate implementation timelines and electric vehicle platform homologation schedules. Industry-specific inputs included ECHA substance authorization pipeline status and KBA thermal runaway containment standard adoption curves.
REACH authorization timeline delays, phosphorus feedstock price spikes, and electric vehicle platform launch postponements are the dominant revision risks to the forecast framework. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Acrylic Styrene Acrylonitrile Resin Market
Polymers & Resins
Metallocene Polyolefin Market
Polymers & Resins
TPEE in Automotive Industry Market
Polymers & Resins
Biobased Polypropylene PP Size Market
Polymers & Resins
Closed Cell Polyurethane Foam Market
Polymers & Resins
Polystyrene and Expandable Polystyrene (EPS) Market
Polymers & Resins
Global Polyethyleneimine Market
Polymers & Resins
Bisphenol a Market
Polymers & Resins
Acrylic Resins Market
Polymers & Resins
Global Nylon Market
Polymers & Resins
Glycolide Polymers Market
Polymers & Resins
Polycide Market
Polymers & Resins
South America Thermoplastics Market
Polymers & Resins
Resin Glue Market
Polymers & Resins
Acrylonitrile Styrene Acrylate (ASA) Market
Polymers & Resins
Rosin Resin Market