
 Global Automotive Battery Sensor Market | 2026-2036
Global Automotive Battery Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Battery Sensor Market Intelligence
The ISO 26262 functional safety standard is unwinding the traditional supplier qualification process for automotive battery sensors. Compliance with this standard separates established automotive electronics suppliers from new entrants. Robert Bosch GmbH leverages its deep systems integration expertise across powertrain and battery management systems. Sensata Technologies Inc. specializes in high-reliability sensor components for harsh automotive environments, while NXP Semiconductors N.V. occupies a leading position in the market for secure in-vehicle network processors.
An automotive battery sensor is an electronic device that monitors a battery's voltage, current, and temperature. These components often utilize a shunt resistor for precise current measurement and transmit data over a CAN bus to the vehicle's control unit. The primary purpose is to feed real-time data to the Battery Management System for optimizing battery health and range. Current sensors and state-of-charge sensors are the leading product types, with their development directly tied to the expanding Electric Vehicles application segment.
Regulations such as the US EPA's emissions rules and the EU's Battery Regulation compel automakers to adopt advanced monitoring for performance and lifecycle tracking. China’s GB standards for EVs impose strict safety and data logging criteria, shaping sensor design for its domestic market. Consequently, procurement decisions for OEMs and Tier-1 suppliers will focus on the trade-offs between integrated multi-function sensor modules and discrete, specialized components.
Market Dynamics
The central dynamic shaping the automotive battery sensor market is the collision between explosive demand from electric vehicle production and the rigorous, time-consuming demands of functional safety compliance. This tension, particularly around standards like ISO 26262, creates a significant barrier to entry and solidifies the market position of established electronics suppliers with proven systems integration capabilities.
Growth Catalysts
- EV Policy Mandates:China's dual-credit policy and strict GB standards for battery safety compel domestic automakers to integrate advanced monitoring sensors, creating a massive, policy-sustained demand base.
- Higher Voltage Architectures:The automotive industry's progression towards 800V and higher voltage systems for premium EVs necessitates more sophisticated and resilient sensors for precise thermal and current management to ensure safety and performance.
- Regulatory Data Requirements:The EU Battery Regulation's digital battery passport provision requires granular lifecycle data, driving the adoption of intelligent sensors capable of logging and securely transmitting state-of-health information.
Market Restraints
- Component Price Volatility:Fluctuations in the cost of high-purity manganese for shunt resistors and specialized analog-to-digital converters (ADCs) create unpredictable cost pressures for sensor module manufacturers.
- Long-Term Measurement Drift:Sensors face challenges in maintaining accuracy over a vehicle's lifespan due to constant exposure to vibration, thermal cycling, and humidity, which can degrade performance and affect BMS calculations.
- Concentrated Semiconductor Supply:The supply of high-precision ADCs and microcontrollers essential for advanced battery sensors is concentrated among a few semiconductor firms, creating potential supply chain bottlenecks for Tier-1s.
Strategic Opportunities
- Commercial Vehicle Electrification:The expansion of battery sensors into electric buses, commercial trucks, and off-highway vehicles presents a significant opportunity, as these applications require robust, multi-sensor systems for larger battery packs.
- Wireless Sensor Integration:Developing sensors with integrated wireless communication protocols can eliminate complex wiring harnesses, reduce vehicle weight, and simplify battery pack assembly and serviceability for OEMs.
- Emerging Market Adoption:Government incentives in India and parts of Southeast Asia, such as production-linked incentive (PLI) schemes, are fostering local EV manufacturing, opening new geographic markets for sensor suppliers.
Industry Challenges
- Functional Safety Certification:Achieving ISO 26262 Automotive Safety Integrity Level (ASIL) compliance is a resource-intensive and lengthy process that can delay product launches and deter new suppliers from entering the market.
- System Integration Complexity:Ensuring flawless interoperability and communication between battery sensors, the Battery Management System (BMS), and the vehicle's ECU over CAN or LIN bus networks remains a persistent engineering challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Battery Sensor Market |
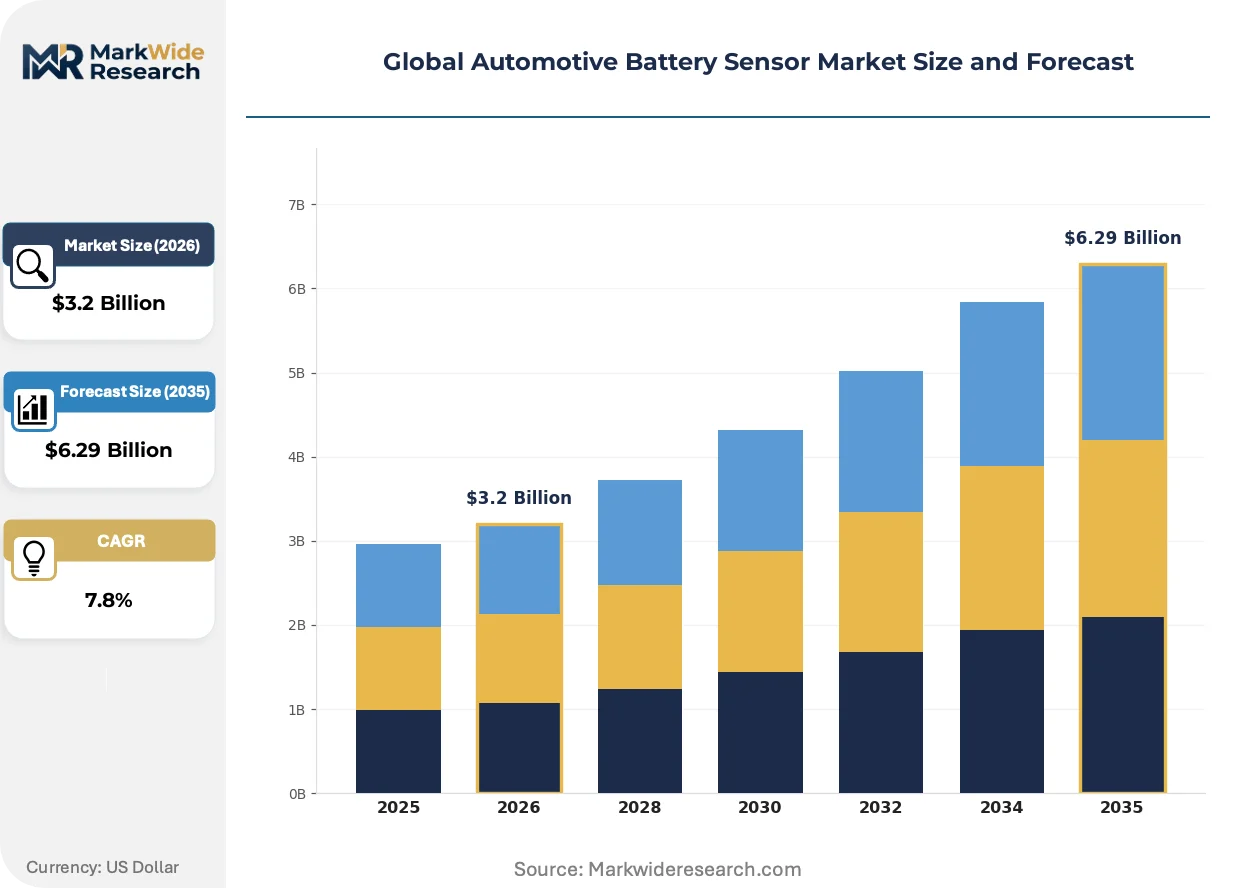
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $6.29 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Voltage Sensor, Temperature Sensor, Current Sensor, State-of-Charge Sensor Technology: CAN Bus, LIN Bus, Wireless, Resistive, Capacitive Application: Electric Vehicles, Hybrid Electric Vehicles, Commercial Vehicles, Two-wheelers End User: OEMs, Tier-1 Suppliers, Vehicle Assemblers, Aftermarket Providers |
| Companies Covered | Sensata Technologies Inc., NXP Semiconductors N.V., Robert Bosch GmbH, HELLA GmbH & Co. KGaA, Texas Instruments Incorporated, Continental AG, Infineon Technologies AG, Vishay Intertechnology Inc., Denso Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Battery Sensor Market Strategic Shifts & Innovations
The evolution of the automotive battery sensor is defined by a decisive shift toward on-board intelligence. This trend moves functionality from the central ECU to the sensor itself, enabling more sophisticated battery management algorithms that are critical for extending EV range and lifespan.
Intelligent battery sensors that incorporate a microcontroller and non-volatile memory are gaining prominence. These devices perform local data filtering, diagnostics, and state-of-charge calculations directly at the point of measurement. Major EV platforms and Tier-1 system integrators are rapidly adopting these smart modules. This on-sensor processing is supplanting the traditional architecture of sending raw analog signals to a central controller, which reduces network traffic and improves system resilience.
The EU's Battery Regulation is a significant policy driver compelling innovation in data security. This rule mandates a digital battery passport that tracks a battery's history from production to recycling. As a result, sensor development for the European market is now incorporating features for secure data logging and cryptographic authentication to ensure the integrity of the data supplied to these digital records, directly affecting component selection for automakers.
Automotive OEM buying behavior is evolving from sourcing discrete components to procuring pre-integrated and pre-validated sensing modules. This change in procurement favors suppliers capable of delivering a complete system that combines current, voltage, and temperature sensing with a single communication interface. This demand for turnkey solutions is particularly strong in North America and Europe, where complex vehicle platforms and compressed development timelines make system-level integration highly valuable.
Global Automotive Battery Sensor Market Segmentation
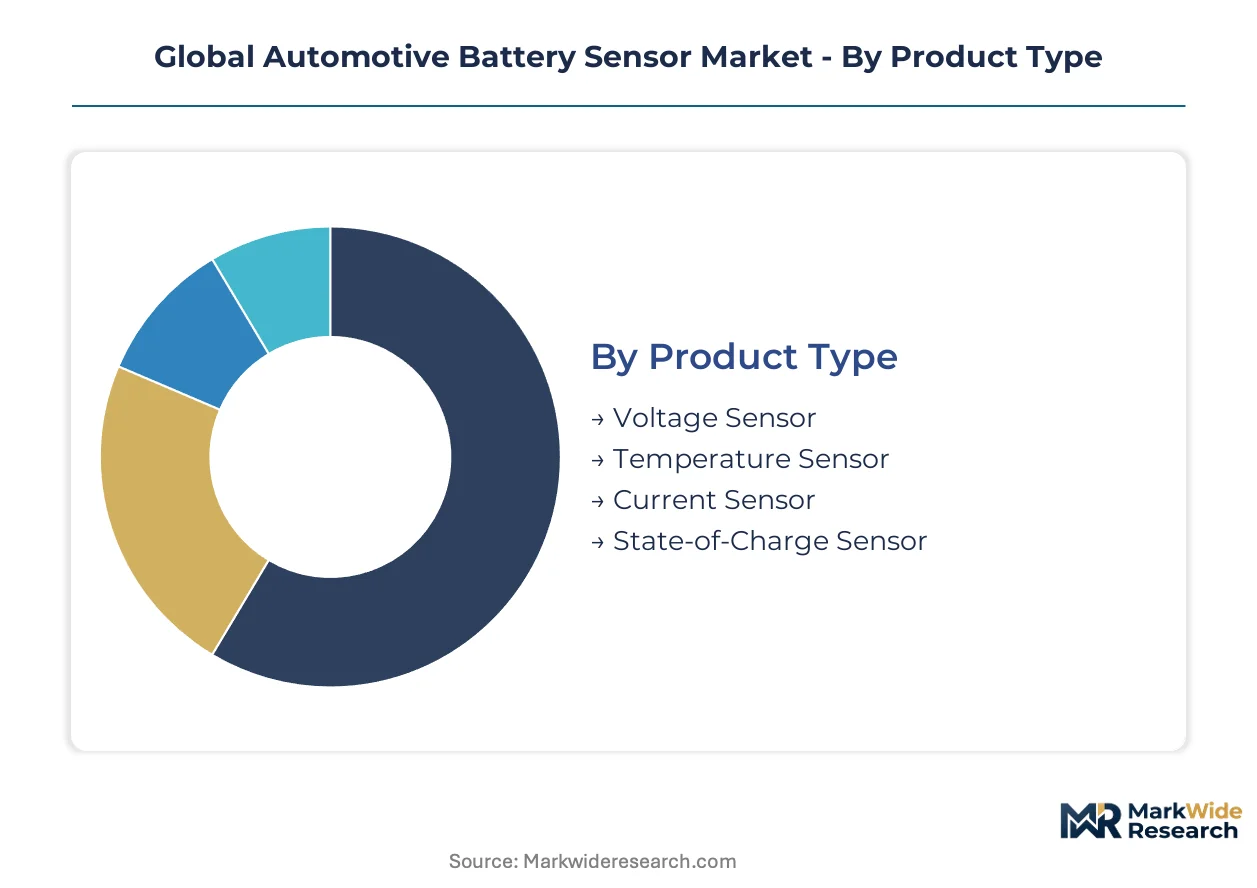
The automotive battery sensor market segmentation reflects the diverse technological requirements and application demands within the electric vehicle ecosystem. This analysis categorizes the market by crucial product types, underlying technologies, varied applications, and distinct end-user groups. Understanding these segments provides clarity on demand drivers and competitive dynamics.
Product Type:
Global demand for automotive battery sensors shows distinct regional preferences, with certain product types gaining traction in specific domestic markets due to local regulations and manufacturing priorities.
- Current Sensor:This device precisely measures the flow of electrical current within the battery pack, often utilizing a shunt resistor for high accuracy. Demand is particularly strong in China, where large-scale EV manufacturing and stringent GB standards drive the need for real-time current monitoring for battery safety.
- State-of-Charge Sensor:These intelligent sensors estimate the remaining energy in a battery, often incorporating microcontrollers for local data processing and non-volatile memory. The EU Battery Regulation's digital battery passport provision compels automakers to adopt these sensors for granular lifecycle data tracking across European markets.
- Voltage Sensor:These components monitor electrical potential difference across battery cells or the entire pack for cell balancing and stability.
- Temperature Sensor:Embedded within battery modules, these devices track thermal conditions to prevent overheating and optimize charging, vital in extreme climates.
Current Sensor holds the largest share; momentum sits with State-of-Charge Sensor.
Technology:
Different communication and sensing technologies are tailored to specific vehicle architectures and performance requirements, influencing their deployment across various automotive applications.
- CAN Bus:This Controller Area Network protocol provides a robust, standardized communication pathway for sensors to transmit data to the Battery Management System and other vehicle ECUs. Its established reliability and widespread adoption make it a foundational technology for complex system integration in premium automotive platforms.
- Wireless:Wireless sensor integration eliminates complex wiring harnesses within battery packs, reducing weight and simplifying assembly processes. This technology is gaining traction for its potential to enhance modularity and serviceability, particularly in new EV designs and commercial vehicle applications.
- LIN Bus:The Local Interconnect Network offers a cost-effective alternative for less critical sensor data in simpler battery monitoring tasks.
- Resistive:Resistive sensors detect changes in physical parameters by measuring electrical resistance, often used for basic temperature sensing.
- Capacitive:Capacitive sensors measure changes in capacitance to detect various physical quantities for specialized battery diagnostics.
Wireless technology exhibits the steepest expansion trajectory, while CAN Bus remains the prevalent standard for secure in-vehicle communication.
Application:
Regulatory mandates and evolving performance expectations significantly influence the type and sophistication of battery sensors required across various vehicle applications.
- Electric Vehicles:This segment represents the largest and fastest-growing application for automotive battery sensors, driven by global decarbonization targets and consumer demand for extended range. Sensors in EVs are critical for precise battery management, ensuring optimal performance and safety in high-voltage architectures.
- Commercial Vehicles:Electrification of buses, trucks, and off-highway machinery necessitates robust, multi-sensor systems to manage larger and more complex battery packs. These applications demand extreme reliability and precision for heavy-duty operational cycles and extended vehicle lifespans.
- Hybrid Electric Vehicles:Battery sensors in HEVs support efficient power management between engine and electric motor, optimizing fuel economy.
- Two-wheelers:The electric two-wheeler market in Asia, particularly India, requires compact, cost-effective battery monitoring for urban mobility.
Electric Vehicles dominate the market volume, with Commercial Vehicles experiencing particularly rapid growth due to fleet electrification.
End User:
The role of different end-user groups in the automotive supply chain dictates their specific procurement needs and demand for integrated battery sensor solutions.
- OEMs:Original Equipment Manufacturers directly procure advanced battery sensor modules for integration into their proprietary battery packs and vehicle platforms. Their procurement decisions heavily prioritize functional safety compliance, system integration capabilities, and long-term supply chain reliability.
- Tier-1 Suppliers:These companies act as system integrators, developing complete battery management systems and sensor modules for OEMs. They often source discrete sensor components and ASICs, adding value through software development and rigorous validation processes.
- Vehicle Assemblers:These entities integrate pre-assembled battery packs with sensors into the vehicle chassis, focusing on efficient installation and quality control.
- Aftermarket Providers:This segment supplies replacement sensors and diagnostic tools for maintenance and repair, emphasizing compatibility and availability.
OEMs represent the primary purchasing power, while Tier-1 Suppliers are increasingly crucial for delivering pre-validated, integrated sensor solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global expansion of electric vehicle charging infrastructure underwrites diverse regional growth in automotive battery sensors. This foundational network enables the proliferation of advanced battery technologies and their associated monitoring requirements. Demand patterns for sensor components vary significantly across key automotive manufacturing hubs.
China
China's extensive EV manufacturing infrastructure drives immense demand for automotive battery sensors. China’s GB standards for electric vehicles impose strict safety and data logging criteria, directly shaping sensor design. The Yangtze River Delta region, including cities like Shanghai, anchors significant EV production and battery pack assembly.
Germany
Germany's focus on premium electric vehicle production necessitates sophisticated battery sensors for high-voltage systems. The EU Battery Regulation's digital battery passport provision compels automakers to adopt advanced state-of-charge sensors. Bavaria, a hub for automotive R&D and manufacturing, sees concentrated development of integrated sensor modules.
United States
United States electric vehicle market expansion fuels demand for robust battery monitoring solutions. The US EPA's emissions rules and the Inflation Reduction Act incentivize domestic battery production and sensor integration. Michigan, particularly around Detroit, is transforming into a major hub for EV battery and sensor manufacturing.
Japan
Japan's strong position in hybrid electric vehicle production and advanced battery research sustains demand for precise sensors. JIS standards for automotive components ensure high reliability and quality for battery monitoring devices. Aichi Prefecture, centering on Nagoya, remains a critical region for automotive component suppliers and battery system integration.
India
India's rapid electric vehicle adoption, particularly in the two-wheeler segment, drives demand for cost-effective battery sensors. Government incentives like the PLI scheme foster local EV manufacturing, creating new market opportunities for sensor suppliers. Maharashtra, with its industrial cities like Pune, is emerging as a significant hub for EV component production.
Global Automotive Battery Sensor Market Key Industry Players
Listed leaders compete with private specialists across functional safety and systems integration capabilities within the automotive battery sensor market. This market exhibits a tiered structure, favoring established electronics suppliers due to rigorous ISO 26262 compliance requirements and the high cost of validation. Strategic archetypes include integrated system providers, high-reliability component specialists, and semiconductor firms focusing on secure in-vehicle processors. Companies pursue strategic partnerships and portfolio diversification to address complex OEM demands and expand their technological footprint across diverse vehicle platforms.
Within the integrated system provider archetype, Robert Bosch GmbH leverages its deep systems integration expertise across powertrain and battery management systems. This global entity's comprehensive approach addresses complex OEM requirements for functional safety and seamless integration. Sensata Technologies Inc. exemplifies a high-reliability component specialist, focusing on robust sensor components designed for harsh automotive environments. Their focus on durability and precision serves critical applications in battery packs. NXP Semiconductors N.V. anchors the secure in-vehicle network processor segment, providing essential semiconductor solutions for advanced battery monitoring and data integrity.
| Leading Market Players |
|---|
| Sensata Technologies Inc. |
| NXP Semiconductors N.V. |
| Robert Bosch GmbH |
| HELLA GmbH & Co. KGaA |
| Texas Instruments Incorporated |
| Continental AG |
| Infineon Technologies AG |
| Vishay Intertechnology Inc. |
| Denso Corporation |
Cost & Logistics Intelligence
Long-term capacity reservation contracts for high-precision analog-to-digital converters lock in both supply access and price visibility for Tier-1 automotive suppliers. This structure mitigates component price volatility and ensures consistent production.
Pricing Analysis
ISO 26262 ASIL certification creates the primary spread in automotive battery sensor pricing. Contract-based long-term offtake agreements dominate the market, reflecting the need for supply stability and system integration complexity. Pricing softness reflects increasing competition among sensor module manufacturers, particularly for standard components. OEMs exhibit lower price sensitivity for mission-critical, ASIL-D certified modules, while Tier-1 suppliers are more sensitive to the cost of discrete sensor components.
Supply Chain Analysis
Port congestion and container availability on trans-Pacific and Asia-Europe trade lanes impact inbound logistics costs for key sensor components. Geographic supply concentrates in China, South Korea, and Germany for specialized semiconductor fabrication, relying on high-purity manganese and advanced analog-to-digital converters. A structural risk arises from the concentrated semiconductor supply. Distribution primarily runs through direct sales to OEMs and Tier-1 suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive battery sensor market is undergoing a cyclical recovery, driven by accelerated electric vehicle production cycles globally. This rebound follows earlier supply chain disruptions and investment deferrals in the automotive sector.
For Market Incumbents: Secure long-term OEM contracts by deepening systems integration capabilities across powertrain and battery management systems. Invest proactively in advanced ASIL-D certification processes to maintain a competitive moat against new entrants offering specialized wireless sensor solutions. Continuous R&D in intelligent sensor modules with on-board processing extends product lifecycles and value propositions. This strategy reinforces market leadership against emerging low-cost competitors.
For New Entrants and Emerging Players: Differentiate on wireless sensor integration, eliminating complex wiring harnesses and simplifying battery pack assembly for OEMs. Target the rapidly expanding commercial vehicle electrification segment and emerging Asian markets like India. The electric two-wheeler market in India represents a highly penetrable segment requiring cost-effective, compact battery monitoring solutions. Focus on rapid prototyping and agile certification pathways to accelerate market entry.
For Investors and Strategic Acquirers: Specialized component manufacturers with unique IP in high-precision ADCs or functional safety software present attractive acquisition targets. The market offers sustained growth viability over the next decade, driven by global EV mandates and higher voltage architectures. Look for firms with proven ISO 26262 ASIL compliance records and strong OEM relationships. A key signal to watch is increasing consolidation among Tier-1 suppliers, indicating market maturity and value aggregation.
| Strategic Initiative | Industry Significance |
|---|---|
| Deepen Functional Safety Expertise | Elevates supplier status for critical ASIL-D certifications required by premium EV platforms. |
| Invest in Wireless Sensor Technology | Reduces vehicle weight and assembly complexity, appealing to OEMs for next-generation battery packs. |
| Expand Commercial Vehicle Offerings | Captures robust demand from fleet electrification, requiring durable multi-sensor systems. |
| Form Strategic OEM Partnerships | Secures long-term design-wins and integrates sensor development early into vehicle platforms. |
| Focus on Intelligent Sensor Modules | Shifts processing to the edge, improving data integrity and reducing BMS network load. |
Research Approach
A standing panel of OEM platform engineers, Tier-1 procurement leads, battery pack designers, and functional safety consultants provided ongoing calibration for primary data. This approach integrated insights from extensive interviews with secondary validation against automotive production databases, regulatory filings, and academic research. Bottom-up data aggregation and top-down market sizing ensured comprehensive coverage.
Quantitative outputs were validated for consistency against external benchmarks and industry growth projections across the analysis window. The analytical framework modeled segmentation across product type, technology, application, end-user, and voltage architecture. Compound annual growth rates were derived through regression analysis and scenario modeling. Key forecast inputs included global EV production forecasts and battery chemistry evolution trends.
The analysis sits within stated boundaries; outcomes outside sudden shifts in raw material supply or major regulatory changes would require recalibration. Forecasts reflect assumptions regarding technological advancements and market adoption rates. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Wheel Spindle Market
Vehicle Components
United Kingdom Vacuum Truck Market
Vehicle Components
Hooklift Trailer Market
Vehicle Components
Automotive Battery Terminals Market
Vehicle Components
Global Motorcycle Chain Sprocket Market
Vehicle Components
Automotive NVH Materials Market
Vehicle Components
Electric Wheelchair Market
Vehicle Components
Towing Equipment Market
Vehicle Components
Exhaust Gas Recirculation (EGR) Valve Market
Vehicle Components
Child Seats Market
Vehicle Components
Bicycle Brake Cable Market
Vehicle Components
Mobility Aids and Transportation Equipment Market
Vehicle Components
Vehicle Retarder Market
Vehicle Components
Electric Vehicles Component Market
Vehicle Components
Brake Hoses Market
Vehicle Components
UK Automotive Carbon Fiber Composites Market