
 South Africa Automotive Carbon Fiber Composites Market | 2026-2036
South Africa Automotive Carbon Fiber Composites Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Automotive Carbon Fiber Composites Market Analytics
Market Context
A capital-intensity divergence between upstream carbon fiber precursor producers and downstream automotive component fabricators is unwinding competitive dynamics across the South Africa Automotive Carbon Fiber Composites Market. Hexcel Corporation leverages its captive PAN precursor supply chain to dominate aerospace-grade fiber qualification pathways that automotive tier suppliers must navigate. SGL Carbon SE anchors its position through backward integration into polyacrylonitrile spinning and oxidation furnaces near European technical centers. Teijin Limited competes via differentiated thermoplastic unidirectional tape technologies that reduce cycle times for structural automotive parts.
Technical and Segment Dynamics
Automotive carbon fiber composites are fiber-reinforced polymer materials comprising continuous or chopped carbon filaments embedded in thermosetting epoxy or thermoplastic matrices, engineered to achieve specific stiffness-to-weight ratios exceeding 100 GPa per g/cm³ for structural load-bearing applications. Prepreg dominates current procurement volumes due to established autoclave processing infrastructure serving motorsport and limited-production luxury vehicle programs in South Africa. Thermoplastic manufacturing stages represent the fastest-expanding category as compression molding cycle times drop below three minutes, enabling cost structures compatible with commercial vehicle annual volumes. Structural components command the deepest margin pools because crashworthiness certification requirements and OEM liability exposure create qualification barriers that protect incumbent suppliers.
Regulatory Framework
South Africa's National Regulator for Compulsory Specifications enforces SANS automotive material standards that govern flammability, tensile strength retention, and recyclability claims for composite interior and structural applications. The Department of Trade, Industry and Competition administers the Automotive Production and Development Programme, which ties local content rebates to verified domestic manufacturing value-add in component assembly. Stakeholders must monitor evolving EU Carbon Border Adjustment Mechanism alignment pressures, as South African automotive exports to European assembly plants face embedded emissions scrutiny that favors low-carbon fiber precursor sourcing decisions.
Market Dynamics
The South Africa Automotive Carbon Fiber Composites Market is being reshaped by the collision between the Automotive Production and Development Programme's local content mandates and the technical complexity of qualifying imported precursor materials under EU Carbon Border Adjustment Mechanism alignment pressures. Domestic fabricators face compressed margins as they absorb certification costs while scaling thermoplastic processing capacity.
Growth Catalysts
- APDP rebate structures:The Automotive Production and Development Programme ties local content verification to manufacturing value-add thresholds, incentivizing domestic composite component assembly and resin transfer molding investments.
- Thermoplastic cycle time compression:Compression molding technologies achieving sub-three-minute cycles are unlocking cost structures compatible with commercial vehicle annual volumes beyond motorsport niche applications.
- Gauteng motorsport cluster:High-performance vehicle manufacturers in this province are expanding procurement of structural load-bearing components, creating qualification pathways that tier suppliers can leverage.
Market Restraints
- Precursor import dependency:Polyacrylonitrile fiber and oxidation furnace equipment concentrate in European and Asian supply bases, exposing South African fabricators to currency volatility and extended lead times.
- Autoclave infrastructure lock-in:Established prepreg processing equipment serving motorsport programs creates path dependency that slows thermoplastic capital redeployment despite superior unit economics.
- Steel-aluminum hybrid substitution:Advanced high-strength steel and aluminum-intensive vehicle architectures from OEM technical centers in Germany and Japan compete for lightweighting budgets in mass-market segments.
Strategic Opportunities
- Eastern Cape supplier park proximity:Component fabricators locating near OEM assembly plants in this province can capture logistics cost advantages and qualify for enhanced APDP localization credits.
- Thermoset-thermoplastic hybrid structures:Multi-material bonding technologies enabling localized overmolding of continuous fiber inserts with injection-molded thermoplastic complex geometries represent unexploited white space.
- Recyclability certification premiums:SANS standards evolution toward end-of-life material recovery verification creates first-mover positioning for suppliers investing in pyrolysis and solvolysis reclamation capabilities.
Industry Challenges
- Crashworthiness qualification timelines:Structural component approval for OEM liability exposure requires 18-24 month testing protocols that compress supplier cash conversion cycles and deter market entry.
- Polymer matrix formulation expertise scarcity:Formulation chemists capable of tuning epoxy and PEEK systems for South African temperature and humidity operating conditions command premium compensation that strains mid-cap fabricator payroll structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Automotive Carbon Fiber Composites Market |
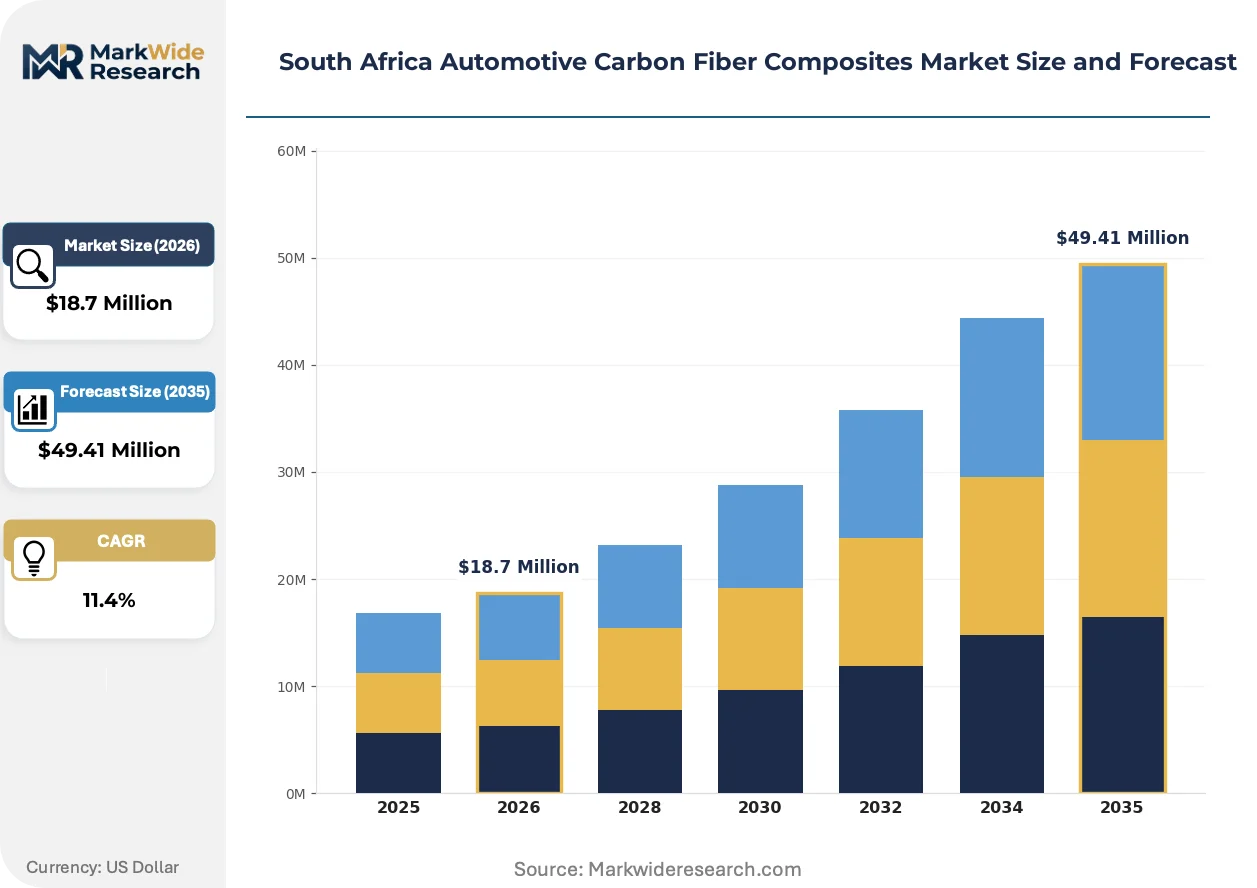
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $49.41 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prepreg, Sheet Molding Compound, Continuous Fiber, Woven Fabric Manufacturing Stage: Thermoplastic, Thermosetting, Hybrid, Injection Molding End User: Electric Vehicles, Commercial Vehicles, Luxury Vehicles, Sports Cars Application: Structural Components, Interior Parts, Exterior Panels, Chassis Components |
| Companies Covered | Hexcel Corporation, Mitsubishi Chemical Group Corporation, SGL Carbon SE, Teijin Limited, BFG International, Solvay SA, Magna International Inc., Nippon Sheet Glass Co. Ltd, Lanxess AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Automotive Carbon Fiber Composites Market Evolving Landscape
Manufacturing process economics and regulatory compliance requirements are forcing material-platform decisions earlier in vehicle development cycles. Three developments are compressing competitive windows for South African suppliers.
Thermoplastic unidirectional tape technologies are bifurcating the structural component supply base. Motorsport programs in Gauteng continue specifying autoclave-cured epoxy prepregs for maximum specific stiffness. Commercial vehicle tier suppliers are adopting carbon-PEEK and carbon-PA6 tapes for compression-molded battery enclosures and seat structures, collapsing the cost gap with aluminum at annual volumes above fifty thousand units.
SANS automotive material standards enforced by the National Regulator for Compulsory Specifications are tightening flammability and tensile strength retention thresholds for interior applications. Composite cabin trim suppliers must reformulate intumescent coatings and revalidate ignition resistance ratings. Upholstery and dashboard fabricators serving domestic OEM assembly programs are absorbing six-month recertification cycles to maintain component approval status.
Buyer concentration among Gauteng-based motorsport constructors and Eastern Cape OEM assembly plants is consolidating procurement authority. Tier-two fabricators are bypassing traditional composite distributors to negotiate direct precursor supply agreements with European PAN producers. This disintermediation compresses working capital requirements for qualified suppliers while marginalizing inventory-holding intermediaries without autoclave or press capacity.
South Africa Automotive Carbon Fiber Composites Market Segmentation
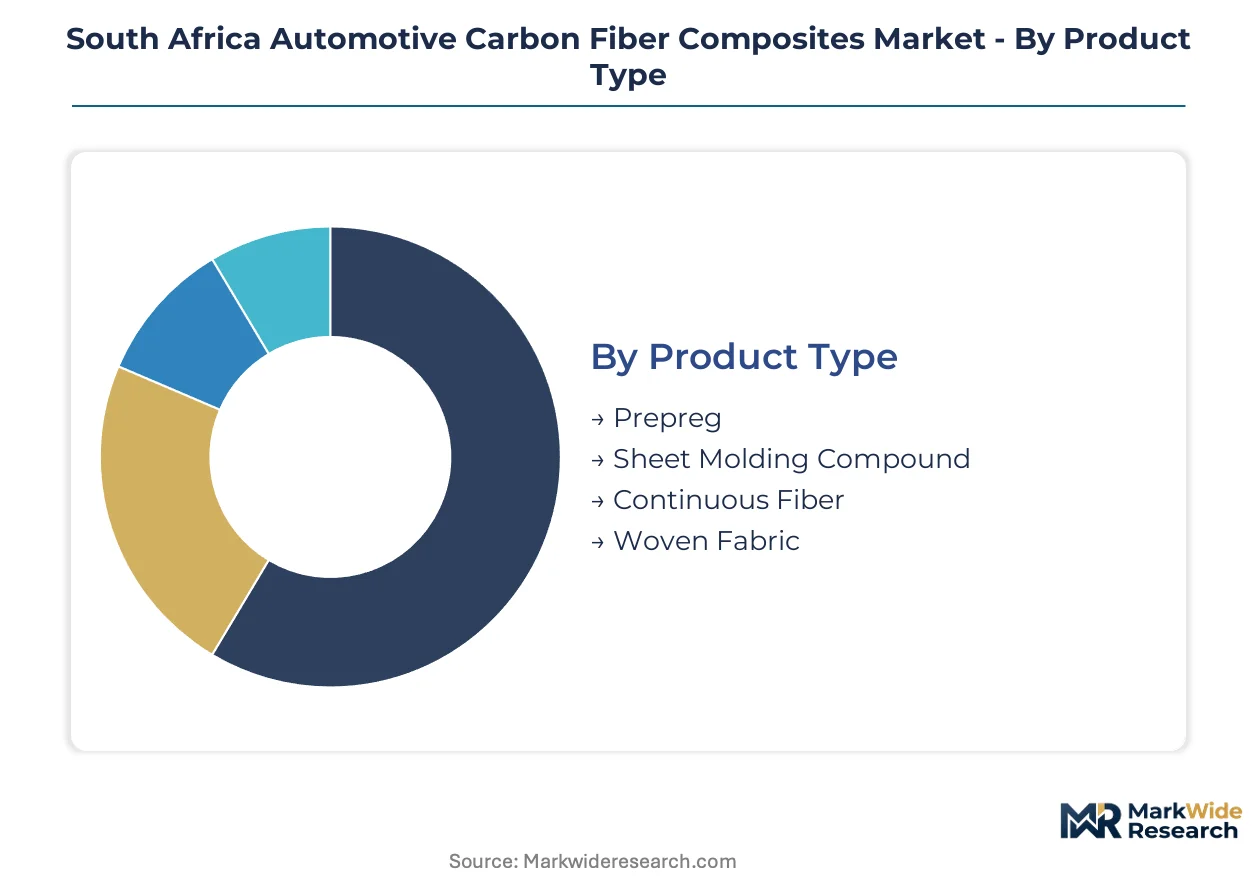
Segmentation in the South Africa Automotive Carbon Fiber Composites Market reveals how material form, processing method, and end-use application create distinct competitive arenas with varying margin profiles and qualification barriers. Each dimension exposes different pressure points from substitute materials and regulatory compliance costs.
Product Type:
Sheet molding compound faces the most acute substitution threat from glass fiber alternatives in cost-sensitive commercial vehicle programs, while continuous fiber maintains defensible positioning in structural load-bearing applications where specific stiffness requirements exclude metals.
- Prepreg:Epoxy-impregnated unidirectional or woven carbon fiber sheets requiring refrigerated storage and autoclave curing. Motorsport constructors in Gauteng Province anchor demand for aerospace-grade material specifications that resist aluminum substitution in monocoque structures.
- Continuous Fiber:Unidirectional tows or multi-axial fabrics without matrix pre-impregnation, enabling custom resin formulation by fabricators. Eastern Cape OEM supplier parks are expanding procurement for structural beam and battery enclosure applications where directional strength tailoring justifies processing complexity.
- Sheet Molding Compound:Chopped carbon fiber dispersed in thermoset resin paste for compression molding. Commercial vehicle interior trim programs specify this form for cost parity with advanced high-strength steel in non-structural applications.
- Woven Fabric:Bidirectional or multi-axial carbon fiber textiles for hand lay-up or resin transfer molding. Aftermarket body panel fabricators serving Gauteng performance vehicle modifiers represent the primary demand concentration.
Prepreg retains volume leadership; continuous fiber holds the steepest expansion curve.
Manufacturing Stage:
Cost tier stratification separates capital-intensive thermosetting infrastructure from emerging thermoplastic processing investments that compress per-part economics for commercial vehicle scale.
- Thermoplastic:Carbon fiber reinforced PEEK, PA6, or PP matrices processed via compression molding or automated fiber placement. Sub-three-minute cycle times are unlocking Eastern Cape OEM assembly contracts previously reserved for aluminum stampings.
- Thermosetting:Epoxy or vinylester matrices cured through autoclave, oven, or room-temperature processes. Established Gauteng motorsport fabricators maintain this capacity for maximum fiber volume fraction and surface finish quality.
- Hybrid:Multi-stage processes combining thermoset preforms with thermoplastic overmolding. Unexploited white space exists for structural components requiring localized stiffness gradients.
- Injection Molding:Short-fiber reinforced thermoplastic pellets for complex geometry parts with modest mechanical requirements. Interior trim suppliers leverage existing polymer processing infrastructure.
Thermosetting commands installed base dominance; thermoplastic manufacturing stages are climbing the fastest.
End User:
Customer type concentration determines qualification timeline tolerance and specification stringency, with luxury vehicle programs absorbing longer development cycles than commercial vehicle procurement.
- Sports Cars:Low-volume, high-performance vehicles where carbon fiber monocoques and body panels justify extreme lightweighting premiums. Gauteng-based constructors specify autoclave-cured prepregs with aerospace-grade fiber volume fractions.
- Electric Vehicles:Battery enclosure and structural floor pan applications where crashworthiness and thermal management requirements favor carbon fiber over aluminum. Eastern Cape OEM assembly plants are qualifying thermoplastic compression-molded solutions.
- Luxury Vehicles:Limited-production sedans and SUVs with visible carbon fiber trim and structural components. Interior and exterior aesthetic applications tolerate higher per-kilogram costs than mass-market segments.
- Commercial Vehicles:Bus, truck, and van programs where total cost of ownership calculations dominate material selection. Sheet molding compound competes directly with steel and aluminum in non-structural applications.
Sports cars retain specification leadership; electric vehicles are gaining share fastest.
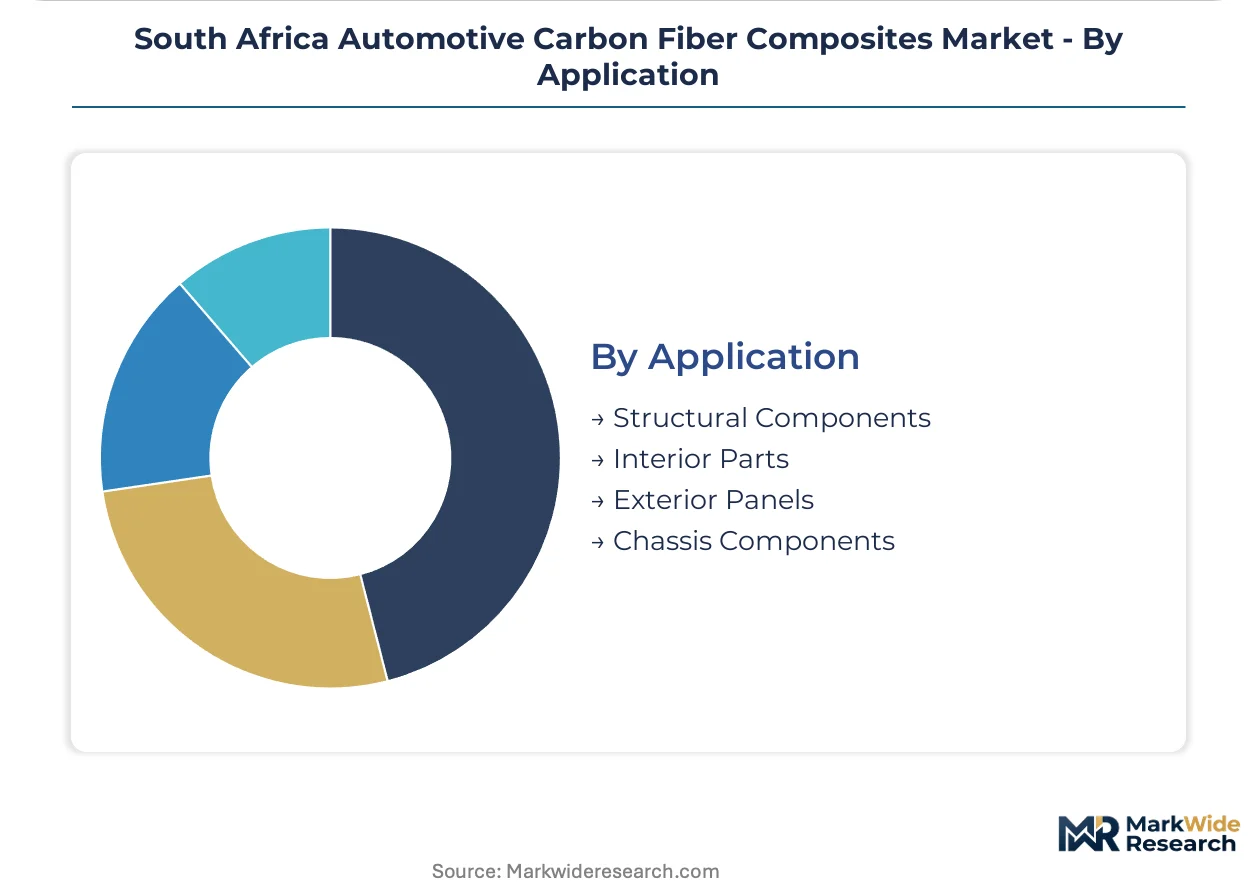
Application:
Margin concentration correlates with crashworthiness certification burden, creating protected positions for qualified suppliers in structural segments versus commoditized competition in interior trim.
- Structural Components:Load-bearing elements including crash structures, suspension links, and battery enclosures subject to OEM liability exposure. Eighteen to twenty-four month qualification protocols deter new entrants.
- Chassis Components:Subframes, crossmembers, and mounting brackets where stiffness-to-weight ratios influence vehicle dynamics. Gauteng motorsport engineering consultancies are transferring race-derived designs to limited road car production.
- Exterior Panels:Hoods, roofs, doors, and fenders where surface finish quality and dent resistance compete with aluminum sheet. Aftermarket suppliers dominate visible weave aesthetic applications.
- Interior Parts:Dashboard carriers, seat shells, and trim elements where SANS flammability standards govern material selection. Reformulation costs for intumescent coatings are compressing fabricator margins.
Structural components retain margin leadership; chassis components show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Gauteng Province where motorsport constructors absorb aerospace-grade fiber premiums, while Eastern Cape fabricators compete on logistics proximity to OEM assembly plants under tighter margin constraints.
Gauteng Province
High-performance vehicle manufacturers in Johannesburg and Pretoria drive structural component procurement for monocoque chassis and body panels. The Automotive Production and Development Programme ties local content verification to manufacturing value-add thresholds, incentivizing domestic composite assembly. The Rosslyn automotive supplier park hosts expanding resin transfer molding investments serving luxury vehicle programs.
Eastern Cape
OEM assembly plants in Gqeberha and East London qualify thermoplastic compression-molded battery enclosures and structural floor pans. The Department of Trade, Industry and Competition administers APDP rebate structures that reward component fabricators locating within 50 kilometers of vehicle assembly operations. The Coega Industrial Development Zone anchors inbound precursor logistics and finishing capacity.
Western Cape
Aftermarket body panel fabricators serving Cape Town performance vehicle modifiers sustain woven fabric demand for visible carbon fiber aesthetic applications. South Africa's National Regulator for Compulsory Specifications enforces SANS flammability standards that govern interior trim material selection. The Atlantis Special Economic Zone hosts emerging reclamation facilities for end-of-life composite recovery.
KwaZulu-Natal
Commercial vehicle interior trim suppliers in Durban specify sheet molding compound for cost parity with advanced high-strength steel in non-structural bus and truck applications. The country's automotive material standards evolution toward recyclability claims pressures reformulation of intumescent coatings. The Dube TradePort logistics hub enables just-in-time precursor delivery to regional fabricators.
South Africa Automotive Carbon Fiber Composites Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the South Africa Automotive Carbon Fiber Composites Market. The supplier base concentrates around precursor manufacturers with captive PAN supply chains, specialized composite fabricators serving motorsport niches, and diversified automotive tier suppliers scaling thermoplastic capacity. Three archetypes dominate: upstream fiber producers controlling qualification pathways, mid-cap fabricators with autoclave infrastructure lock-in, and emerging thermoplastic specialists compressing cycle times. Competitive moves center on backward integration into polyacrylonitrile spinning and strategic positioning near Eastern Cape OEM assembly plants to capture APDP localization credits.
Among fiber and precursor specialists, Hexcel Corporation, SGL Carbon SE, and Teijin Limited occupy positions that exemplify divergent integration strategies. Hexcel represents the captive supply chain archetype with aerospace-grade fiber qualification pathways. SGL Carbon SE anchors the European technical center proximity model through oxidation furnace investments. Teijin Limited sits within the thermoplastic differentiation tier with unidirectional tape technologies that reduce structural part cycle times.
| Leading Market Players |
|---|
| Hexcel Corporation |
| Mitsubishi Chemical Group Corporation |
| SGL Carbon SE |
| Teijin Limited |
| BFG International |
| Solvay SA |
| Magna International Inc. |
| Nippon Sheet Glass Co. Ltd |
| Lanxess AG |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts for polyacrylonitrile precursor lock in both supply access and price visibility for Gauteng motorsport fabricators, insulating them from currency volatility while compressing margins for Eastern Cape tier suppliers exposed to spot market fluctuations. The Automotive Production and Development Programme's local content verification requirements create pricing premiums for domestic assembly value-add that imported components cannot capture.
Pricing Analysis
Configured-to-order pricing for aerospace-grade prepreg commands substantial premiums over standard thermoplastic sheet pricing, with differentiation driven by fiber volume fraction certification and crashworthiness qualification tier. Three-tier pricing structure across motorsport-specification, OEM-structural, and commercial-vehicle-interior levels stratifies the market, with price erosion running through sheet molding compound segments as glass fiber substitution intensifies. Commercial vehicle procurement teams exhibit highest price sensitivity, while Gauteng motorsport constructors absorb premiums for monocoque-grade material.
Supply Chain Analysis
Strategic stockpiling of PAN precursor dominates inventory strategy among established fabricators, buffering against European and Asian supply base disruptions that plague just-in-time dependent entrants. Geographic concentration in Germany, Japan, and the United States for oxidation furnace equipment and polyacrylonitrile fiber production creates single-source vulnerability for South African fabricators. Raw material dependencies span acrylonitrile monomer, carbon fiber tow, and epoxy resin formulations. Distribution runs through Coega Industrial Development Zone logistics hubs serving Eastern Cape OEM supplier parks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thermoplastic cycle time compression below three minutes constitutes a technological inflection that disrupts incumbent autoclave infrastructure economics, positioning the South Africa Automotive Carbon Fiber Composites Market for high-growth expansion beyond motorsport niches.
For Market Incumbents: Fortify qualification pathway control by deepening backward integration into PAN precursor supply and accelerating thermoplastic press capacity redeployment in Eastern Cape supplier parks. Steel-aluminum hybrid substitution from German and Japanese OEM technical centers threatens structural component margins, making crashworthiness certification investment the critical defensive lever against emerging thermoplastic specialists. For New Entrants and Emerging Players: Anchor in thermoset-thermoplastic hybrid structures for battery enclosure applications, the most penetrable white space where localized overmolding of continuous fiber inserts meets unmet demand from Eastern Cape electric vehicle assembly programs. Direct precursor supply agreements with European PAN producers, bypassing traditional composite distributors, offer the strongest go-to-market angle for qualified tier-two fabricators. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap fabricators with captive thermoplastic processing capabilities and established SANS certification status, positioned for acquisition by diversified automotive tier suppliers scaling composite capacity. Over the projection horizon, viability hinges on APDP localization credit capture and recyclability certification positioning. The signal to watch is EU Carbon Border Adjustment Mechanism alignment pressure on South African automotive exports, which would accelerate low-carbon precursor sourcing decisions and reshape competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Thermoplastic Capacity Expansion | Sub-three-minute cycle times unlock Eastern Cape OEM assembly contracts previously reserved for aluminum. |
| Backward Integration into PAN Precursor | Captive polyacrylonitrile supply chains insulate margins from currency volatility and extended lead times. |
| Crashworthiness Certification Investment | Eighteen-month qualification protocols create protected positions in structural components against new entrants. |
| APDP Localization Credit Capture | Proximity to Eastern Cape OEM assembly plants maximizes rebate structures under Department of Trade, Industry and Competition administration. |
| Recyclability Capability Development | SANS standards evolution toward end-of-life recovery verification creates first-mover premiums for pyrolysis investment. |
Research Methodology
A spread of perspectives from OEM platform engineers, Tier 1 supplier procurement leads, composite fabricator plant managers, and aftermarket distributor operations converged on the working assumptions shaping this analysis. Primary interview intelligence combined with secondary validation from vehicle production databases, customs and trade flow records, IHS Markit registration data, and Automotive Production and Development Programme administrative filings. Bottom-up capacity and demand modeling triangulated against top-down macroeconomic indicators.
Segmentation dimensions modeled span manufacturing stage, product type, end-use vehicle class, and regional production cluster across the analysis window. CAGRs derived from regression analysis of historical production volumes, content-per-vehicle trajectories, and substitution elasticity parameters for aluminum and advanced high-strength steel. Forecast inputs incorporated APDP rebate structure evolution and EU Carbon Border Adjustment Mechanism alignment scenarios.
Decision-makers should treat outputs as directional under sustained APDP incentive frameworks and stable precursor import logistics; material deviation would warrant model refresh. Revision becomes warranted when thermoplastic cycle time compression crosses commercial vehicle volume thresholds or when SANS flammability standards tighten beyond current reformulation capabilities.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Collapsible Jerry Can Market
Vehicle Components
Crash Lock Box Market
Vehicle Components
EGR Valve Market
Vehicle Components
Gas Station Equipment Market
Vehicle Components
Global Car Accessories Market
Vehicle Components
Steering Tie Rod Market
Vehicle Components
Gas-Powered Chainsaw Market
Vehicle Components
Aircraft and Marine Turbochargers Market
Vehicle Components
Wheel Seals Market
Vehicle Components
Off-Highway Diesel Engine Market
Vehicle Components
Automotive Air Flow Sensors Market
Vehicle Components
Automotive Powertrain Sensors Market
Vehicle Components
Mobile Liquid Tanks Market
Vehicle Components
Advanced Driver Assistance System (ADAS) Sensor Market
Vehicle Components
Global Automotive Constant Vehicle Joint Boots Market
Vehicle Components
Vehicle Exhaust Hose Market