
 Global Automotive Starter and Alternator Market | 2026-2036
Global Automotive Starter and Alternator Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Starter and Alternator Market Intelligence
Performance differentiation between premium smart alternators and commodity-grade conventional starters is consolidating the supply base around electronic integration capabilities. Robert Bosch GmbH leverages its deep expertise in vehicle electronics to lead in high-efficiency systems. Valeo SA competes through its development of integrated starter-generator units for mild-hybrid vehicles. Meanwhile, Prestolite Electric Incorporated specializes in robust components for the heavy-duty commercial truck and agriculture machinery segments.
Automotive starters are electric motors designed to crank internal combustion engines for ignition. Alternators are electromechanical generators that charge the battery and power the vehicle's electrical system, typically operating on 12V or 24V platforms. Within product types, smart alternators are displacing conventional units in new vehicles to meet fuel economy targets. The OEM end-user segment constitutes the largest channel, though the aftermarket for commercial trucks provides significant recurring revenue.
Regulations from the US EPA on vehicle emissions directly influence alternator efficiency mandates. In parallel, the EU's RoHS directive restricts hazardous substances in electronic components, while China’s GB standards define performance and durability criteria for all vehicle parts. Component suppliers face a strategic choice between optimizing 12V start-stop systems and committing to the development of more complex 48V mild-hybrid architectures.
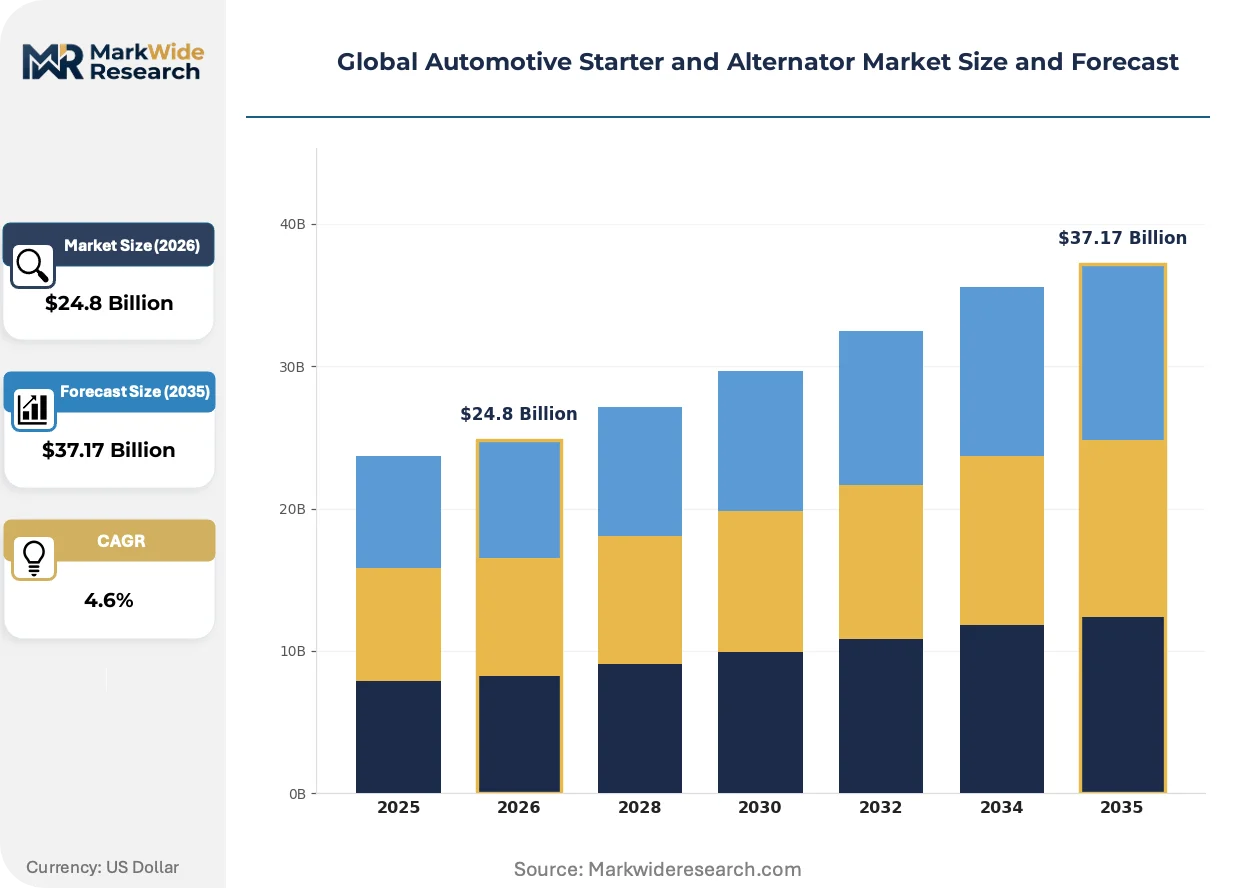
Market Dynamics
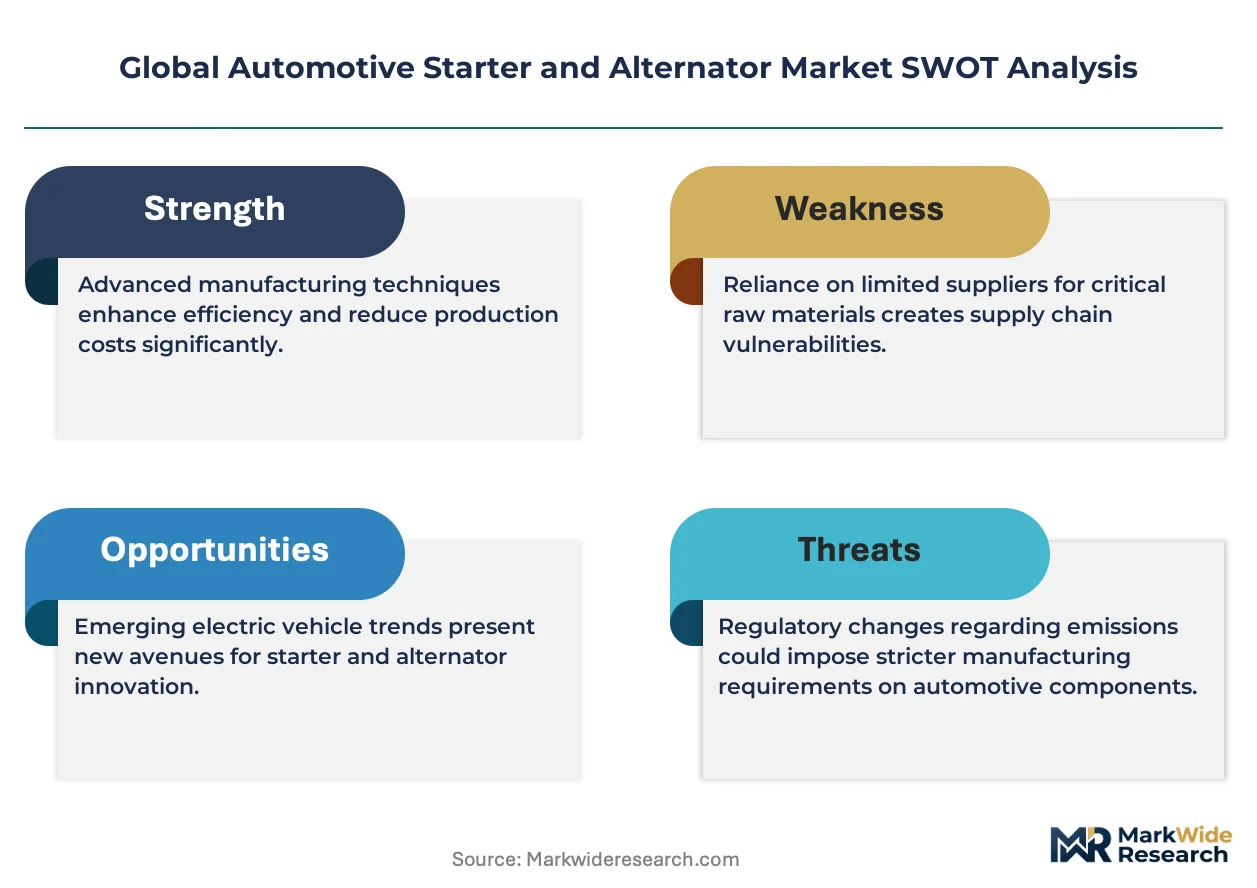
The market's central dynamic is the tension between incremental efficiency gains in 12V systems, driven by emissions regulations, and the strategic imperative to invest in 48V mild-hybrid architectures that represent a more profound technological shift.
Growth Catalysts
- Fleet Modernization:Demand from commercial truck fleets, particularly in China's logistics sector, for durable 24V starters and high-output alternators continues to expand as operators replace older vehicles with more efficient models.
- Emissions Regulations:Mandates from bodies like the US EPA on vehicle fuel economy directly compel automakers to adopt more efficient components, including smart alternators that reduce parasitic engine load.
- Start-Stop System Adoption:The integration of automatic start-stop technology in mass-market passenger vehicles to conserve fuel in urban driving conditions creates a direct and growing demand for more robust starter motors.
Market Restraints
- BEV Substitution Threat:The long-term growth of battery electric vehicles (BEVs) presents a fundamental substitution threat, as these vehicles do not require a conventional starter motor or an engine-driven alternator.
- Input Cost Volatility:Manufacturing costs are sensitive to price fluctuations for key raw materials such as copper for windings and rare earth elements used in high-efficiency permanent magnet alternators.
- System Integration Cost:The higher initial cost and engineering complexity of 48V mild-hybrid systems, including integrated starter-generators, can slow their adoption compared to proven and less expensive 12V start-stop solutions.
Strategic Opportunities
- Remanufacturing for Aftermarket:A significant opportunity exists in the organized remanufacturing of starters and alternators, creating a cost-effective aftermarket channel for fleet operators and service centers focused on total cost of ownership.
- Integrated Starter-Generators:The development of belt-driven and crankshaft-mounted integrated starter-generator (ISG) units for 48V mild-hybrid systems opens a new, high-value product category for suppliers with strong mechatronics capabilities.
- Off-Highway Segments:Targeting specialized, heavy-duty applications in agriculture, construction, and mining machinery in markets like Brazil and India provides a niche for highly durable and customized starter and alternator systems.
Industry Challenges
- Software and ECU Integration:Ensuring seamless communication and software compatibility between smart alternators and a vehicle's main engine control unit (ECU) across diverse OEM platforms is a significant technical hurdle.
- Capital-Intensive Re-tooling:Transitioning production lines from manufacturing conventional starters and alternators to complex smart alternators or ISGs requires substantial capital investment in new assembly and testing equipment.
- Multi-Jurisdictional Compliance:Component suppliers face operational complexity in managing compliance simultaneously with differing regulations, such as the EU's RoHS, China's GB standards, and US EPA rules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Starter and Alternator Market |
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $37.17 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Brushless Starter, Gear Reduction Starter, Permanent Magnet Alternator, Conventional Starter, Smart Alternator Technology: Brushless DC Motor, Switched Reluctance, Induction Motor, Permanent Magnet Synchronous Motor, Electronic Control Unit Application: Electric Vehicles, Commercial Trucks, Agriculture Machinery, Construction Equipment, Marine Vessels End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers, Repair Workshops |
| Companies Covered | Hitachi Astemo Ltd., Mitsuba Corporation, Robert Bosch GmbH, Cummins Inc., BorgWarner Inc., Denso Corporation, Mitsubishi Electric Corporation, Prestolite Electric Incorporated, Valeo SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Starter and Alternator Market Strategic Shifts & Innovations
The evolution from electromechanical devices to intelligent electronic systems defines the current technological trajectory. This shift is driven by vehicle-wide demands for better energy management, fuel efficiency, and integration with advanced driver-assistance systems.
Smart alternators incorporate microcontrollers and utilize LIN bus communication protocols to dynamically adjust charging voltage and current. These systems are now standard in new passenger vehicles from major OEMs to meet fuel economy and emissions targets. This technology is automating the vehicle's entire energy management strategy, actively reducing engine load to optimize efficiency based on real-time conditions.
The European Union's RoHS directive places firm restrictions on hazardous substances within electronic components, directly influencing material selection for starters and alternators. This forces manufacturers to re-engineer products, substituting materials like lead-based solders and certain flame retardants. The aftermarket and heavy-duty segments feel this impact most acutely, requiring extensive re-validation to ensure long-term reliability with compliant materials.
A preference for remanufactured components is growing within the professional aftermarket, especially among large commercial fleet managers. This trend disrupts the linear sales channel for new parts, fostering a circular model where the return and refurbishment of old units, or "cores," is essential. The practice is most developed in the North American and European commercial vehicle sectors, where it lowers the total cost of ownership.
Global Automotive Starter and Alternator Market Segmentation
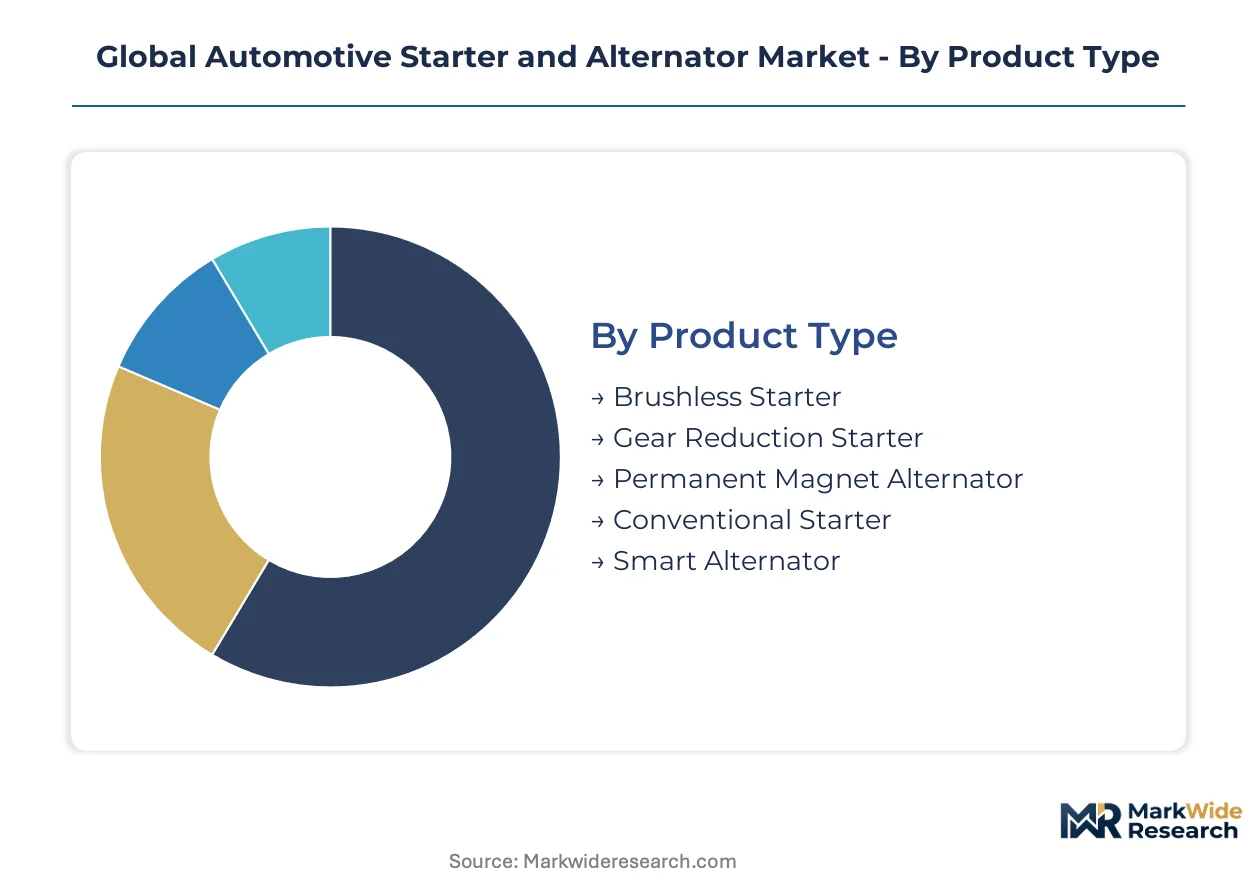
The global automotive starter and alternator market segments reflect the diverse technological requirements and end-user demands across various vehicle types. Understanding these segments is crucial for identifying areas of innovation, market concentration, and strategic growth opportunities for component manufacturers.
Product Type:
The market for starters and alternators differentiates significantly between high-volume, cost-optimized components and premium, efficiency-driven units.
- Smart Alternator:These advanced units incorporate microcontrollers and LIN bus communication protocols to dynamically adjust charging voltage and current, optimizing energy management. Demand is concentrating in new passenger vehicles, driven by stringent fuel economy targets and emissions mandates from bodies like the US EPA.
- Brushless Starter:Designed without carbon brushes, these starters offer enhanced durability, higher efficiency, and reduced maintenance requirements. Demand is expanding in the heavy-duty commercial truck and off-highway segments, where reliability and extended service life are paramount.
- Gear Reduction Starter:These starters utilize a gear train to increase torque output while reducing the size and weight of the motor. They find widespread use in mass-market passenger vehicles.
- Permanent Magnet Alternator:These alternators use permanent magnets in their rotor, contributing to higher efficiency and a more compact design. They are increasingly adopted in various vehicle platforms.
- Conventional Starter:Traditional electric motors designed for cranking internal combustion engines, these units remain prevalent in older vehicles and cost-sensitive applications.
Mature deployment sits with Conventional Starter units. Newer deployment is concentrated in Smart Alternator systems.
Technology:
Performance differentiation across starter and alternator technologies influences their adoption in various vehicle architectures.
- Permanent Magnet Synchronous Motor:This technology offers high efficiency and power density, making it suitable for integrated starter-generator (ISG) units in 48V mild-hybrid systems. Demand is rising with the strategic shift towards electrification.
- Electronic Control Unit:ECUs are integral to smart alternators and ISG systems, managing power flow, communication with the vehicle's engine control unit, and advanced energy management strategies. Integration complexity is a key challenge for suppliers across diverse OEM platforms.
- Brushless DC Motor:These motors are known for their high efficiency, long lifespan, and low maintenance, finding applications in various automotive auxiliary systems. They are critical for advanced power components.
- Switched Reluctance:This motor technology provides robustness and high-speed operation, often considered for specialized applications requiring extreme durability. Its use is limited to specific niches.
- Induction Motor:A widely used and cost-effective motor type, induction motors are found in various automotive applications, including some starter designs. They offer reliable performance.
Future development is largely centered on Permanent Magnet Synchronous Motor technology. Integration complexity is most pronounced with Electronic Control Unit applications.
Application:
The operational environment and specific power requirements of different vehicle types dictate the design and demand for starters and alternators.
- Commercial Trucks:This segment demands robust 24V starters and high-output alternators to support heavy electrical loads and ensure reliability in demanding logistics operations. Fleet modernization, particularly in China's logistics sector, drives this demand.
- Electric Vehicles:Battery electric vehicles fundamentally displace conventional starters and engine-driven alternators, posing a long-term substitution threat to the market. This segment relies on power electronics and traction motors.
- Agriculture Machinery:Heavy-duty starters and alternators are essential for agricultural equipment operating in harsh conditions, requiring durability and high cranking power. This niche demands customized solutions.
- Construction Equipment:Similar to agriculture, construction machinery requires highly durable and powerful starter and alternator systems for reliable operation in challenging environments. This segment prioritizes ruggedness.
- Marine Vessels:Specialized starters and alternators are designed for marine applications, often featuring corrosion resistance and specific certifications for maritime use. This segment has unique environmental demands.
Commercial Trucks are seeing the steepest expansion trajectory. Electric Vehicles represent the fastest-growing substitution threat.
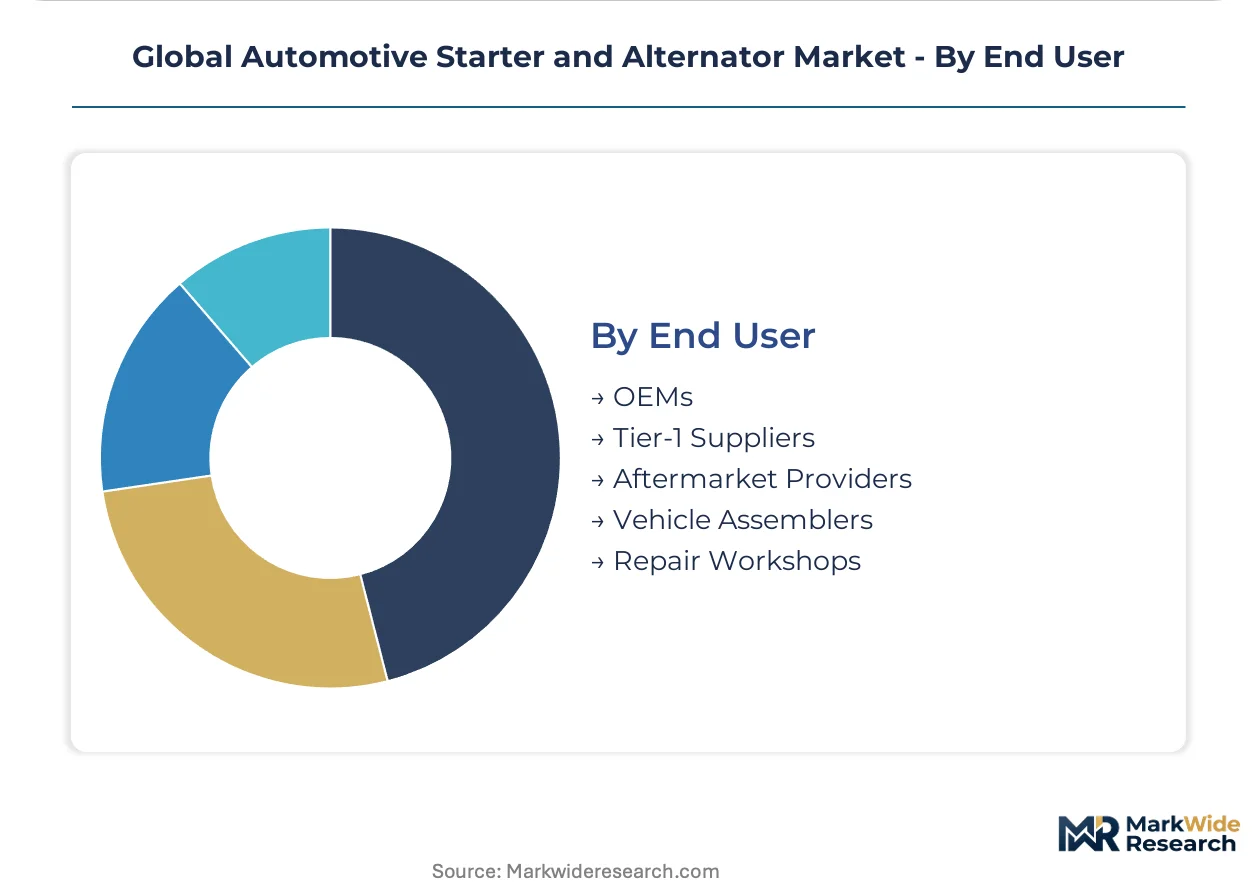
End User:
Procurement channels for automotive starters and alternators vary significantly, influencing product specifications and distribution strategies.
- OEMs:Original Equipment Manufacturers represent the largest channel, procuring first-fit components directly for new vehicle production lines. They demand integrated systems that meet strict design specifications and fuel economy mandates.
- Aftermarket Providers:This segment supplies replacement parts and remanufactured units for vehicles already in service, particularly for commercial fleets seeking to lower total cost of ownership. Remanufacturing offers a cost-effective alternative.
- Tier-1 Suppliers:These companies integrate starter and alternator components into larger sub-assemblies or complete systems for OEMs. They play a critical role in the supply chain.
- Vehicle Assemblers:Companies that assemble vehicles from various components procure starters and alternators as part of their final production process. They focus on integration and quality control.
- Repair Workshops:These establishments provide installation and maintenance services for starters and alternators, sourcing parts from aftermarket channels. They are crucial for service delivery.
OEMs dominate initial sales volumes. Aftermarket Providers are critical for long-term service and cost management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta region, a major industrial hub in China, drives significant activity in the automotive starter and alternator market. This area benefits from robust manufacturing capabilities and extensive logistics networks. Global demand for these components reflects varying regional regulatory pressures and technological adoption rates.
China
Demand for durable 24V starters and high-output alternators expands in China's commercial truck fleets, supporting its vast logistics and construction industries. The national GB standards define critical performance and durability criteria for all vehicle components. Industrial clusters in cities like Shanghai and Guangzhou are centers for both domestic production and international supply chain integration.
United States
The United States market is influenced by stringent US EPA emissions regulations, which compel automakers to integrate more efficient smart alternators. Adoption of automatic start-stop technology in passenger vehicles also creates sustained demand for robust starter motors. Major automotive manufacturing centers in Michigan, Ohio, and South Carolina are focal points for OEM procurement.
Germany
Germany leads in the development of advanced 48V mild-hybrid architectures and integrated starter-generator units, driven by ambitious EU emissions targets. The EU's RoHS directive directly influences material selection for electronic components, ensuring compliance across the supply chain. Bavaria and Baden-Württemberg host significant research and development facilities for leading automotive suppliers.
India
India's agriculture and construction sectors generate substantial demand for highly durable and customized heavy-duty starters and alternators. Government initiatives supporting infrastructure development and rural mechanization further stimulate this segment. Automotive component manufacturing hubs in Chennai and Pune cater to both domestic and export markets.
Brazil
Brazil's agricultural machinery segment requires robust starter and alternator systems capable of operating in challenging environmental conditions. The country's expanding commercial truck fleet also contributes to sustained aftermarket demand. Manufacturing operations in São Paulo and Minas Gerais serve as key production centers for the South American market.
Global Automotive Starter and Alternator Market Key Industry Players
Capital-heavy producers compete with asset-light designers within the automotive starter and alternator market. The supply base consolidates around electronic integration capabilities, reflecting performance differentiation between premium smart alternators and commodity-grade conventional starters. Key strategic archetypes include integrated electronics specialists, heavy-duty component providers, and remanufacturing experts. Dominant competitive moves involve strategic investments in mild-hybrid development and targeted aftermarket expansion.
Within the integrated electronics tier, Robert Bosch GmbH, a German-based multinational engineering and electronics company, exemplifies leadership in high-efficiency systems. Valeo SA, a French automotive supplier, occupies a position through its development of integrated starter-generator units for mild-hybrid vehicles. Prestolite Electric Incorporated, a US-based company, anchors the heavy-duty commercial truck and agriculture machinery segments with its robust component specialization.
| Leading Market Players |
|---|
| Hitachi Astemo Ltd. |
| Mitsuba Corporation |
| Robert Bosch GmbH |
| Cummins Inc. |
| BorgWarner Inc. |
| Denso Corporation |
| Mitsubishi Electric Corporation |
| Prestolite Electric Incorporated |
| Valeo SA |
| Others |
Cost & Logistics Intelligence
OEM demand for integrated starter-generator systems increasingly dictates component specifications, compelling suppliers to invest in complex electronic integration capabilities, which in turn influences pricing structures. This dynamic shifts pricing power towards suppliers with advanced technological offerings.
Pricing Analysis
Performance-based pricing anchored to fuel efficiency gains and system reliability dominates the automotive starter and alternator market. Price differentiation stems from the quality grade of electronic components and the certification level for advanced 48V mild-hybrid units. Pricing pressure stems from the long-term threat of battery electric vehicle substitution, particularly impacting conventional 12V system components. Commercial fleet operators are highly price-sensitive for aftermarket parts, while OEMs prioritize technological sophistication and integration.
Supply Chain Analysis
Workforce availability for skilled electronics manufacturing in China and Germany influences the production of advanced alternators. The supply chain relies heavily on key raw materials such as copper for windings and rare earth elements for permanent magnet alternators. Commodity price volatility presents a structural risk for manufacturers, impacting profitability. Distribution runs through a dual model, with direct sales to OEMs and a robust aftermarket channel supported by remanufacturing networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is increasingly a vertical-integration race, with players actively pursuing upstream control over software development and electronic control unit integration.
For Market Incumbents:Acquire advanced software integration expertise to enhance smart alternator and ISG functionality. Defend against battery electric vehicle substitution threats by accelerating investment in 48V mild-hybrid technologies and expanding remanufacturing capabilities for the aftermarket. Control over intellectual property in power electronics acts as a critical lever against emerging competitors.
For New Entrants and Emerging Players:The EU's RoHS directive in Europe opens a window for suppliers specializing in compliant, hazardous-substance-free electronic components. Target the off-highway segments in India and Brazil, which are less saturated with advanced solutions and prioritize durability. A go-to-market angle focusing on customized, robust components with extended warranties for harsh operating conditions can provide differentiation.
For Investors and Strategic Acquirers:The window for entry favors component specialists with proven mechatronics capabilities and existing OEM relationships. Long-term viability hinges on the successful transition from conventional components to advanced 48V mild-hybrid and smart alternator systems over the next decade. Watch for increased M&A activity among Tier-1 suppliers seeking to consolidate electronic integration capabilities as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in 48V Mild-Hybrid R&D | This initiative ensures competitiveness against the long-term threat of battery electric vehicle substitution. |
| Expand Remanufacturing Operations | This strategy addresses the growing preference for cost-effective aftermarket components among commercial fleet managers. |
| Develop Advanced ECU Integration | Seamless communication between components and OEM platforms enhances system performance and market adoption. |
| Secure Rare Earth Element Supply Chains | Mitigating input cost volatility for critical materials like rare earth elements stabilizes production economics. |
| Target Off-Highway Customization | Providing tailored, durable solutions for agriculture and construction machinery captures niche, high-value demand. |
Research Approach
Document review covered industry reports, regulatory filings from the US EPA and EU RoHS, and technical specifications from major OEMs, complemented by interviews with Tier-1 supplier procurement leads, OEM platform engineers, aftermarket distributors, and commercial fleet managers. This approach ensured a robust understanding of market dynamics. Bottom-up data collection was triangulated with top-down market sizing to validate demand projections.
The cross-reference approach integrated historical market performance data with expert panel input to project future trends across the analysis window. Segmentation dimensions modeled included product type, technology, application, end-user, and regional production clusters. Compound annual growth rates were derived through a weighted average of historical trends and anticipated technological adoption rates. Forecast inputs considered vehicle production forecasts and raw material price projections.
Caveats apply where rapid shifts in battery electric vehicle adoption rates or unforeseen changes in global raw material supply could materially shift the outlook for conventional components. Forecasts reflect assumptions regarding regulatory stability and technological evolution within the automotive sector. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
Automotive Ultracapacitor Market
Automotive Electrical & Electronics
Asia Pacific Automotive Camera Market
Automotive Electrical & Electronics
Switchrack Assemblies Market
Automotive Electrical & Electronics
India Automotive Sensors Market
Automotive Electrical & Electronics
Europe Automotive Steering Sensor Market
Automotive Electrical & Electronics
Africa and Middle East Automotive Tpms Market
Automotive Electrical & Electronics
Global Automotive Electronic Lock Differential Market
Automotive Electrical & Electronics
Automotive Engine Management Sensors Market
Automotive Electrical & Electronics
Personal Mobility Devices Market
Automotive Electrical & Electronics
Car Bulb Market
Automotive Electrical & Electronics
Ambulance Power Inverter Market
Automotive Electrical & Electronics
GCC Automotive Lead-Acid Battery Market
Automotive Electrical & Electronics
India Automotive Camera Market
Automotive Electrical & Electronics
Electric Vehicle Shielded HV Cables Market
Automotive Electrical & Electronics
Automotive E-Compressor Market
Automotive Electrical & Electronics
Wireline Trucks Market