
 Conventional Motorcycles and Scooters Market | 2026-2036
Conventional Motorcycles and Scooters Market Size, Share, and Industry Trends Forecast 2026-2036
Conventional Motorcycles and Scooters Market Analysis
Electrification-adjacent combustion refinement is reshaping how conventional powertrains are engineered for efficiency without sacrificing performance. Honda Motor Co., Ltd. leverages its global manufacturing footprint to sustain cost leadership across multiple displacement categories. Yamaha Motor Co., Ltd. anchors its competitive stance through motorsport-derived technology transfer into consumer models. Hero MotoCorp Ltd. dominates the high-volume commuter segment in South Asia through extensive distribution depth.
Conventional motorcycles and scooters denote internal-combustion-engine two-wheelers with gasoline-powered reciprocating engines, typically featuring single or multi-cylinder configurations ranging from 50cc to over 1000cc, constructed from steel tube frames with chain or belt final drive, serving personal mobility, commercial transport, and recreational purposes. The scooter category leads unit volumes globally due to urban maneuverability and step-through accessibility, while sportbike and touring segments command higher per-unit margins through premium componentry and performance positioning. Engine capacity stratification shows 125cc models capturing the largest addressable base for emerging-market commuters, whereas 500cc-plus displacement tiers concentrate enthusiast demand in North American and European markets.
The US Environmental Protection Agency and California Air Resources Board enforce tailpipe emission thresholds that compel manufacturers to invest in catalytic converter integration and fuel-injection systems, while India's BIS and the European Union's Euro 5 standards create divergent compliance pathways across production hubs. The EU F-Gas Regulation and REACH chemical restrictions additionally constrain material choices for seals, lubricants, and coatings used in powertrain assembly. Stakeholders must monitor how regulatory fragmentation between major markets influences platform commonality decisions and localized engineering investments.
Market Dynamics
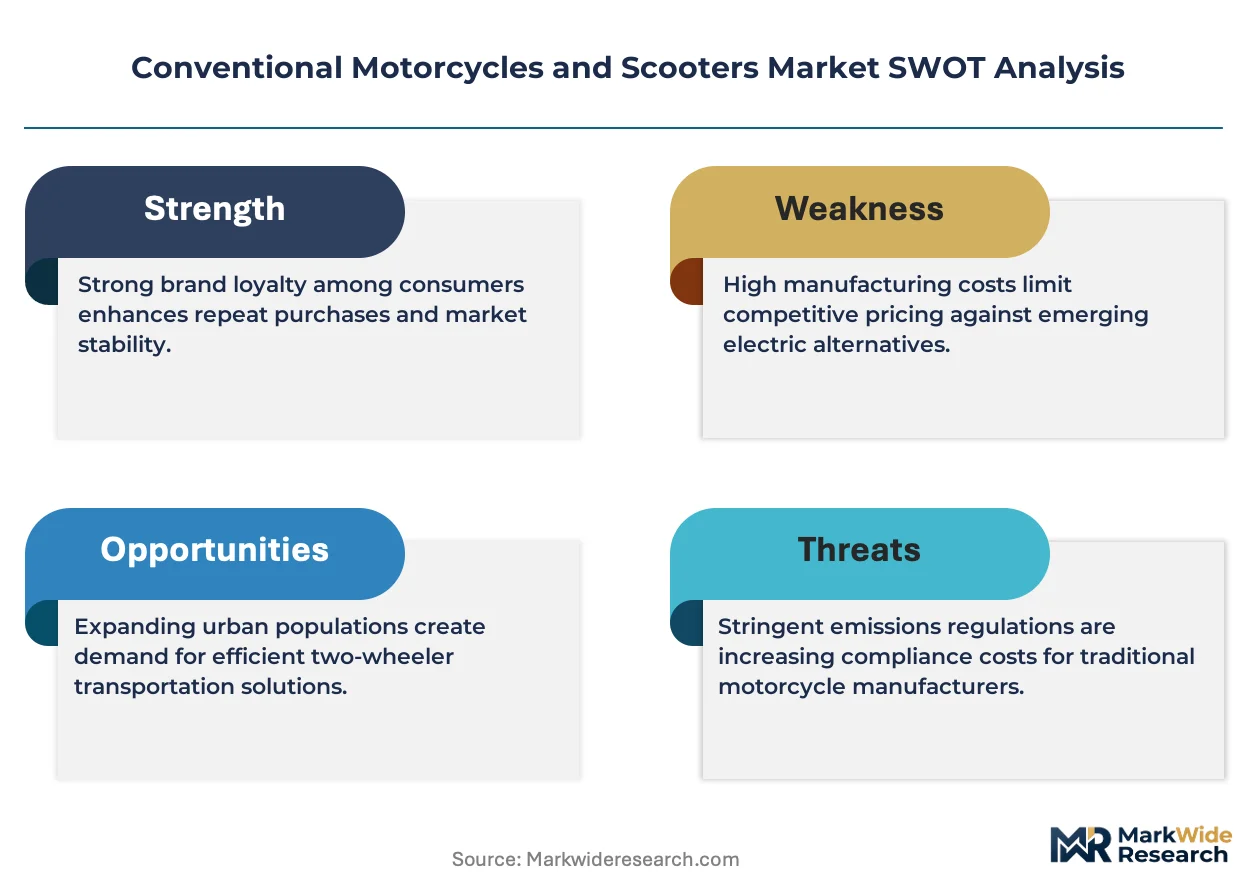
India's BIS emission norms and fuel-efficiency mandates are forcing manufacturers to reengineer powertrain architectures while preserving cost structures for price-sensitive commuter segments. This regulatory compression sits at the center of competitive strategy across all displacement categories.
Growth Catalysts
- Urban Delivery Services:Last-mile logistics operators in Indonesia, Vietnam, and the Philippines are scaling fleet procurement of 110-125cc scooters for dense metropolitan corridors. Route optimization software integration is raising vehicle utilization rates.
- EU F-Gas Regulation:Refrigerant restrictions on mobile air conditioning systems are accelerating adoption of compact liquid-cooled engines that reject heat without climate-damaging working fluids.
- Steel Tube Frame Refinement:Advanced high-tensile steel grades are enabling lighter chassis designs that improve fuel economy without sacrificing load-bearing capacity for commercial applications.
Market Restraints
- Platinum Group Metal Volatility:Catalytic converter substrates depend on palladium and rhodium prices that fluctuate with automotive sector demand, squeezing margin on sub-150cc models where cost-per-unit is constrained.
- Foundry Concentration in India:Aluminum die-casting for engine blocks clusters in Tamil Nadu and Gujarat industrial belts, creating geographic supply risk during monsoon logistics disruptions.
- Electric Two-Wheeler Substitution:Battery-powered scooters with removable pack architectures are capturing urban commuter trials in Chinese and European pilot zones, threatening gasoline scooter replacement cycles.
Strategic Opportunities
- African Secondary Cities:Nigeria, Kenya, and Ethiopia exhibit underpenetrated formal dealer networks where independent assembler partnerships could establish first-mover service infrastructure.
- Ethanol Flex-Fuel Convergence:Brazil's ANP biofuel mandates and India's E20 blending targets are creating demand for multi-fuel injection mapping that leverages common hardware across regulatory zones.
- Direct-to-Fleet Digital Channels:Corporate leasing platforms are bypassing traditional dealer markups for delivery and ride-hail operators, compressing transaction costs and accelerating replacement cycles.
Industry Challenges
- Powertrain Calibration Talent Scarcity:Fuel injection and catalytic converter matching for diverse altitude and temperature conditions requires scarce combustion engineers, particularly for Himalayan and Andean market variants.
- Euro 5 Homologation Timelines:Certification cycles for evaporative emission control and onboard diagnostic systems extend 18-24 months, delaying platform refreshes in European export markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Conventional Motorcycles and Scooters Market |
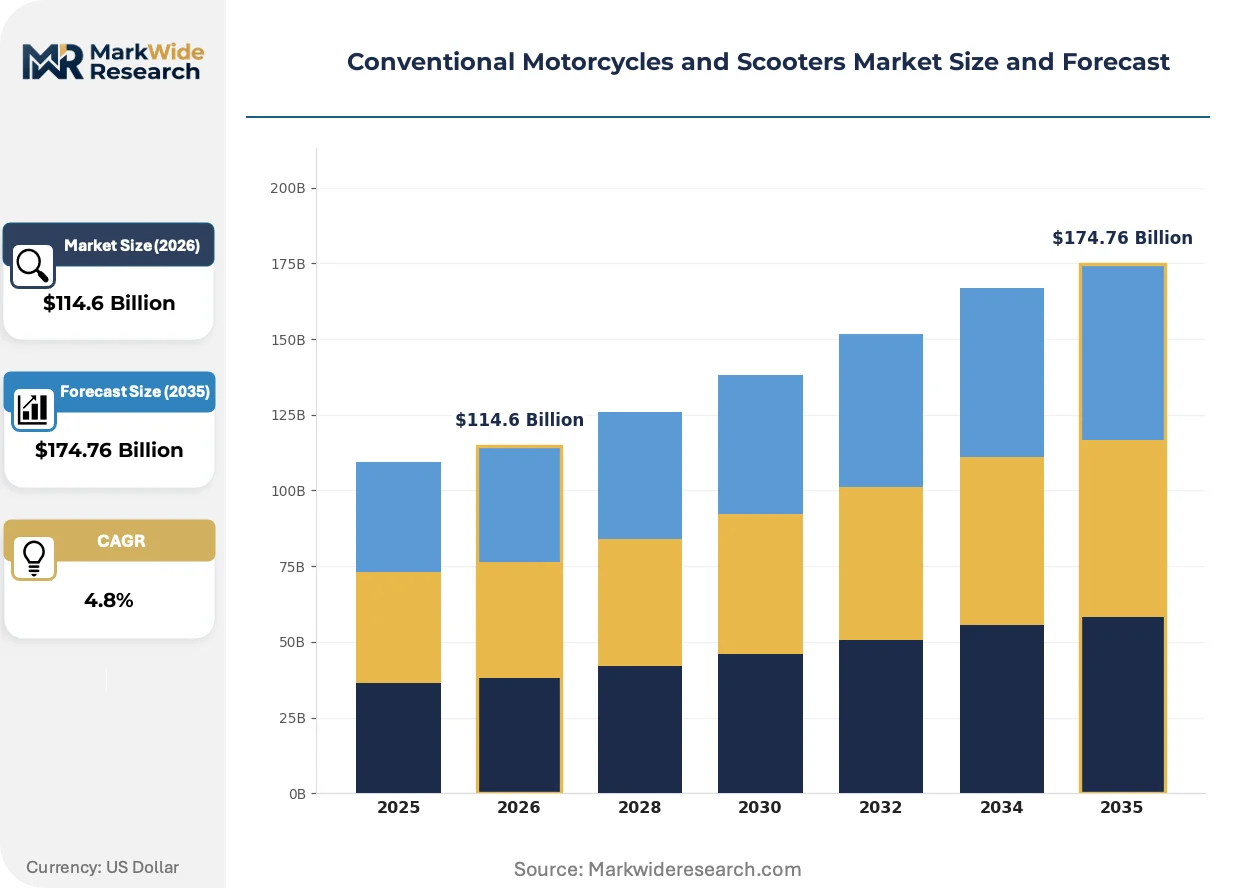
| Market Size in 2026 | $114.6 Billion |
| Market Size in 2035 | $174.76 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cruiser, Sportbike, Touring, Scooter Engine Capacity: 125cc, 250cc, 500cc, 1000cc Usage Type: Commute, Racing, Leisure, Delivery End User: Daily Riders, Enthusiasts, Renters, Delivery Services |
| Companies Covered | Honda Motor Co., Ltd., Yamaha Motor Co., Ltd., Hero MotoCorp Ltd., Bajaj Auto Ltd., TVS Motor Company, Suzuki Motor Corporation, Piaggio and C. SpA, Royal Enfield, KTM AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Conventional Motorcycles and Scooters Market Emerging Trajectories
Powertrain engineering is migrating toward combustion refinement rather than displacement expansion, with manufacturers extracting efficiency from existing architectures through friction reduction and thermal management advances. This trajectory favors incumbents with sunk tooling investments.
Gasoline direct injection is migrating from premium sportbike segments to mass-market commuter platforms. Southeast Asian fleet operators are piloting 125cc GDI scooters for delivery routes where stop-start frequency degrades port-injection efficiency. The technology is migrating from performance positioning to total-cost-of-ownership optimization, compressing the historical feature-tier hierarchy.
California Air Resources Board's evaporative emission standards are mandating sealed fuel systems and carbon canister integration that adds component cost and packaging complexity. Small-displacement manufacturers serving the US market must redesign tank and frame junctions. The 50-150cc scooter segment is responding with modular canister designs that share tooling across multiple body styles.
After-sales service unbundling is fragmenting the traditional dealer revenue model. Independent repair networks in Thailand and Colombia are capturing routine maintenance through diagnostic tool accessibility and non-proprietary parts channels. Urban commuter segments exhibit highest channel-switching propensity where service density outweighs brand loyalty.
Conventional Motorcycles and Scooters Market Segmentation
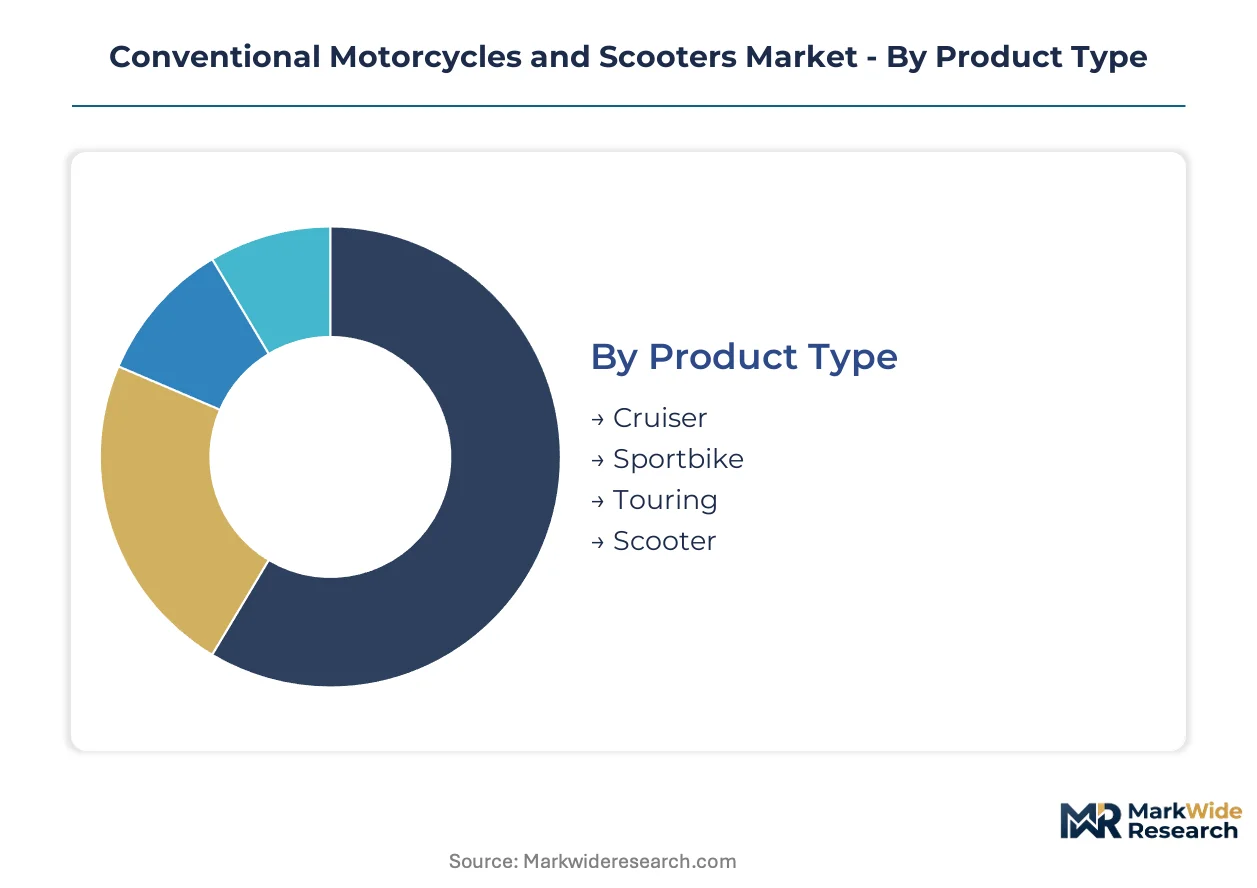
Segmentation in conventional two-wheelers reveals how displacement, application, and ownership models create divergent margin profiles and replacement cycles. Manufacturers configure platform architectures around these divisions to balance volume scale against premium positioning.
Product Type:
Scooters turn inventory fastest through urban commuter replacement, while sportbikes and touring machines cycle slower through enthusiast hands with longer holding periods.
- Scooter:Step-through architectures with automatic transmissions dominate metropolitan mobility in Jakarta, Ho Chi Minh City, and Manila. Fleet procurement from last-mile delivery operators in Indonesian and Vietnamese corridors compresses replacement cycles below private ownership patterns.
- Sportbike:Performance-oriented fairing designs with high-revving engines concentrate demand among enthusiast segments in European and North American markets. Euro 5 homologation costs and evaporative emission controls squeeze margin on sub-600cc sportbike variants.
- Cruiser:Low-slung riding positions with torque-biased engine mapping appeal to North American and Australian recreational buyers. Longer ownership tenures and aftermarket customization extend revenue capture into parts and accessories channels.
- Touring:Wind protection, luggage capacity, and long-distance ergonomics command premium pricing in German and US highway corridors. Higher per-unit margins offset lower absolute volumes through dealer service attachment rates.
Scooters dominate installed base. Sportbike is where expansion concentrates among premium displacement tiers.
Engine Capacity:
Cost tier stratification shows 125cc models anchoring emerging-market affordability while 500cc-plus brackets capture developed-market margin extraction.
- 125cc:Single-cylinder air-cooled architectures with carburetor or basic fuel-injection systems serve price-sensitive commuters across Indian and Southeast Asian urban corridors. BIS emission compliance and fuel-efficiency mandates force continuous powertrain refinement without passing cost to buyers.
- 250cc:Twin-cylinder or large-bore single configurations bridge commuter utility and recreational entry in Brazilian and Thai markets. Ethanol flex-fuel compatibility requirements from Brazil's ANP shape injection mapping and material selection.
- 500cc:Parallel-twin or V-twin layouts target European A2 license restrictions and emerging-market premium upgraders. California Air Resources Board certification adds evaporative emission hardware cost that challenges price positioning.
- 1000cc:Multi-cylinder performance engines with advanced electronics concentrate in German, Japanese, and US enthusiast segments. Platinum group metal exposure in catalytic converters creates margin volatility tied to automotive sector demand cycles.
125cc holds the broadest geographic footprint. 250cc is climbing the fastest as emerging-market income thresholds shift.
Usage Type:
Application-driven segmentation separates high-frequency commercial utilization from intermittent recreational deployment with divergent durability requirements.
- Commute:Daily urban mobility with stop-start traffic patterns prioritizes fuel efficiency and low-speed maneuverability. Indian and Indonesian metropolitan corridors concentrate demand for 110-125cc scooters and motorcycles with automatic or semi-automatic transmissions.
- Delivery:Commercial fleet utilization with extended daily operating hours demands reinforced frames and cooling systems for thermal durability. Route optimization software integration in Vietnamese and Philippine logistics markets raises vehicle utilization rates above private ownership patterns.
- Leisure:Weekend recreational riding with seasonal usage patterns emphasizes styling and brand affiliation over total-cost-of-ownership metrics. European and North American markets concentrate demand for cruiser and touring configurations.
- Racing:Track-day and competition use with minimal street legality requirements drives technology transfer from motorsport programs. Homologation specials in Japanese and Italian markets command scarcity premiums through limited production runs.
Commute dominates unit economics through volume density. Delivery is gaining share fastest as urban logistics formalizes.
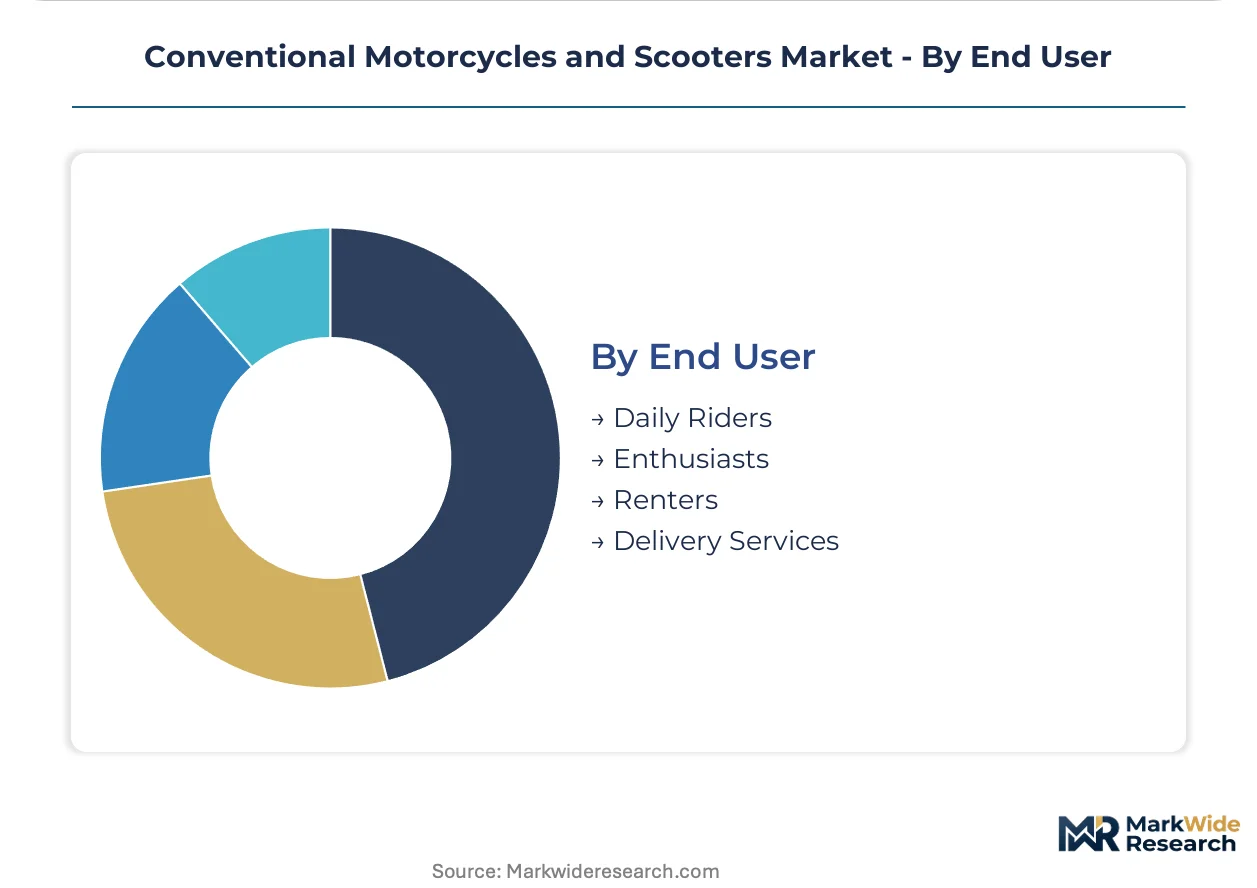
End User:
Customer type segmentation distinguishes ownership models with varying service attachment, financing penetration, and replacement trigger sensitivity.
- Daily Riders:Owner-operators dependent on two-wheelers for primary transportation exhibit highest service loyalty and parts consumption. Indian and Indonesian markets concentrate this segment with extended ownership horizons and informal maintenance channels.
- Delivery Services:Fleet-operated vehicles under corporate ownership enable direct-to-fleet procurement bypassing dealer markups. Indonesian and Vietnamese logistics platforms accelerate replacement cycles through utilization-based depreciation models.
- Enthusiasts:Discretionary purchasers with multiple vehicle ownership and upgrade frequency drive premium segment innovation absorption. German, Japanese, and North American markets concentrate this segment with highest accessory attach rates.
- Renters:Short-term usage through peer-to-peer platforms or commercial rental fleets prioritizes damage resistance and simplified operation. Thai and Colombian urban tourism corridors concentrate this emerging channel with highest vehicle turnover velocity.
Daily Riders anchor aftermarket revenue. Delivery Services is where procurement digitization concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India exports conventional two-wheelers to African and Southeast Asian markets through Chennai and Mundra port corridors. Japanese manufacturers supply premium displacement tiers into European and North American distribution networks. Thai and Indonesian assembly hubs feed regional ASEAN demand with localized content requirements.
India
Domestic commuter demand concentrates in 110-125cc scooters and motorcycles for urban mobility across Mumbai, Delhi, and Bangalore metropolitan corridors. BIS emission norms and fuel-efficiency mandates force continuous powertrain reengineering without cost pass-through to price-sensitive buyers. Tamil Nadu and Gujarat industrial belts host aluminum die-casting clusters for engine block manufacturing.
Indonesia
Last-mile delivery fleet procurement drives 125cc scooter volumes in Jakarta, Surabaya, and Bandung urban logistics corridors. The country's national energy regulator enforces biodiesel blending mandates that shape fuel injection calibration requirements. Bekasi and Karawang manufacturing zones concentrate assembly operations for domestic consumption and regional export.
Vietnam
Route optimization software integration raises commercial vehicle utilization rates for delivery operators in Ho Chi Minh City and Hanoi. The Ministry of Transport enforces periodic technical inspection standards that accelerate replacement cycles for high-mileage fleet units. Vinh Phuc and Hanoi provinces anchor northern assembly capacity serving Red River Delta demand.
Thailand
Tourism-dependent rental fleets in Bangkok, Phuket, and Chiang Mai prioritize damage-resistant scooter configurations with simplified operation protocols. The country's industrial standards institute mandates exhaust emission testing that shapes catalytic converter specifications. Rayong and Chonburi eastern seaboard zones concentrate component supply for ASEAN regional production.
Brazil
Ethanol flex-fuel compatibility requirements from ANP biofuel mandates create demand for multi-fuel injection mapping across São Paulo and Rio de Janeiro metropolitan markets. The national petroleum regulator enforces E27 blending ceilings that constrain hardware design parameters. Manaus free trade zone hosts assembly operations leveraging import duty exemptions for regional distribution.
Conventional Motorcycles and Scooters Market Vendor Landscape
On the supply side, the industry is consolidating around integrated powertrain manufacturers with captive foundry and transmission capabilities. Tiered competition separates scale-driven commuter specialists, premium displacement engineering houses, and regional assembly partners serving protected markets. Dominant competitive moves include ethanol flex-fuel hardware convergence across Brazil and India regulatory zones, and direct-to-fleet digital channel development bypassing traditional dealer markups.
Among Japanese engineering conglomerates with motorsport heritage, Honda Motor Co., Ltd., Yamaha Motor Co., Ltd., and Suzuki Motor Corporation exemplify the premium-tier archetype with technology transfer programs and global manufacturing footprints. These entities occupy positions where combustion refinement investments sustain competitive differentiation against electric substitution threats. Indian volume manufacturers including Hero MotoCorp Ltd., Bajaj Auto Ltd., and TVS Motor Company anchor the high-volume commuter segment through distribution depth across South Asian metropolitan corridors and African secondary city networks. European specialists Piaggio and C. SpA, Royal Enfield, and KTM AG represent premium positioning archetypes with heritage brand equity and enthusiast segment focus.
| Leading Market Players |
|---|
| Honda Motor Co., Ltd. |
| Yamaha Motor Co., Ltd. |
| Hero MotoCorp Ltd. |
| Bajaj Auto Ltd. |
| TVS Motor Company |
| Suzuki Motor Corporation |
| Piaggio and C. SpA |
| Royal Enfield |
| KTM AG |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Tamil Nadu aluminum die-casting clusters is compressing supplier margins while forcing OEMs to absorb catalytic converter cost inflation on sub-150cc models. This utilization asymmetry between engine block foundries and emission-control component suppliers is reshaping contract negotiations across Indian and Southeast Asian production hubs.
Pricing Analysis
Carburetor-to-fuel-injection technology-generation pricing gaps are widening as BIS emission compliance costs concentrate in 125cc commuter tiers. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and after-sales service bundling. Pricing pressure stems from platinum group metal volatility in catalytic converters. Fleet procurement operators exhibit lowest price sensitivity through utilization-based depreciation models, while individual commuters in Indian metropolitan corridors face highest cost pass-through resistance.
Supply Chain Analysis
Tariff exposure between India and ASEAN markets dominates supply chain risk calculations for component sourcing decisions. Manufacturing concentrates in India, Thailand, and Indonesia for frame fabrication and final assembly. Aluminum ingot and platinum group metals draw from concentrated mining jurisdictions. Single-source vulnerability persists in carbon canister supply for California Air Resources Board compliance. Distribution runs through captive dealer networks in mature markets and independent assembler partnerships in African secondary cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Battery-powered two-wheeler substitution is eroding gasoline scooter replacement cycles in Chinese and European urban pilot zones, forcing incumbents to defend installed base through combustion refinement investments.
For Market Incumbents: Harden powertrain calibration capabilities against electric substitution threats by capturing scarce combustion engineering talent for Himalayan and Andean altitude-variant development. Deepen backward integration into catalytic converter substrate supply to buffer platinum group metal price swings. Prioritize ethanol flex-fuel hardware convergence across Brazil and India regulatory zones to maximize platform commonality. For New Entrants and Emerging Players: African secondary cities with underpenetrated formal dealer networks represent the most penetrable entry point for independent assembler partnerships establishing first-mover service infrastructure. Direct-to-fleet digital channels bypassing traditional dealer markups offer compressed transaction cost structures for Indonesian and Vietnamese logistics operators. Target route optimization software integration as the primary go-to-market wedge for commercial fleet procurement. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across Euro 5 homologation and evaporative emission control certification cycles. Long-term viability over the next decade hinges on acquiring foundry-integrated manufacturers with captive transmission capabilities rather than pure assembly operations. Watch electric two-wheeler subsidy phase-out schedules as the critical inflection signal for gasoline platform residual value.| Strategic Initiative | Industry Significance |
|---|---|
| Ethanol Flex-Fuel Hardware Convergence | Enables common injection mapping across Brazil ANP and India E20 regulatory mandates. |
| Direct-to-Fleet Digital Channel Development | Bypasses dealer markups for Indonesian and Vietnamese last-mile logistics operators. |
| Catalytic Converter Backward Integration | Buffers margin volatility from palladium and rhodium automotive sector demand cycles. |
| Gasoline Direct Injection Migration | Extracts efficiency from 125cc commuter architectures without displacement expansion. |
| African Secondary City Service Infrastructure | Establishes first-mover advantage through independent assembler partnerships in Nigeria and Kenya. |
Methodological Framework
The analysis maps scooter, sportbike, cruiser, and touring sub-sectors, each validated through OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distributor operations heads, and fleet procurement managers at Indonesian logistics platforms. Primary interview insights triangulate against customs and trade data, vehicle production databases, IHS Markit registration data, and SEC 10-K filings from listed manufacturers. Bottom-up segment sizing reconciles with top-down macroeconomic indicators across the analysis window.
Assumptions held fixed include BIS emission norm compliance timelines and EU F-Gas Regulation refrigerant restrictions, while electric two-wheeler substitution rates and platinum group metal price trajectories were varied across sensitivity scenarios. The forecast framework models displacement tiers, product architectures, usage applications, and end-user ownership patterns. CAGRs derive from segment-level volume projections calibrated against historical replacement cycle data and fleet utilization rate trends from Vietnamese route optimization deployments.
Practitioners should monitor electric two-wheeler subsidy policy shifts and platinum group metal automotive demand cycles for early signals requiring forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
Global Carbon Fiber Bike Market
Bikes and Motorcycles
Two Wheeler Kick Lever Market
Bikes and Motorcycles
Child Bike Seats Market
Bikes and Motorcycles
Germany E-Bike Market
Bikes and Motorcycles
Hydrobike Market
Bikes and Motorcycles
South America Two-Wheeler Market
Bikes and Motorcycles
Asia-Pacific Motorcycle Market
Bikes and Motorcycles
Latin America Two-Wheeler Market
Bikes and Motorcycles
South Africa Two-Wheeler Market
Bikes and Motorcycles
Bicycle Brake Lever Market
Bikes and Motorcycles
Folding Bikes Market
Bikes and Motorcycles
300cc Motorcycle Market
Bikes and Motorcycles
Bike Computer Market
Bikes and Motorcycles
Motorcycle Accessories Market
Bikes and Motorcycles
Aluminum Alloy Bicycle Crankset Market
Bikes and Motorcycles
China Two Wheeler Market