
 Automotive E-Compressor Market | 2026-2036
Automotive E-Compressor Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive E-Compressor Market Intelligence
Buyer concentration among electric vehicle OEMs is shifting as new entrants from China and Europe fragment the traditional customer base while established automakers consolidate thermal system procurement. DENSO CORPORATION leverages its integrated powertrain expertise to anchor supply relationships with Japanese and European OEMs. Valeo competes through its dedicated electric thermal management division, while BorgWarner Inc. extends its e-mobility portfolio into compressor systems via organic capability buildout.
An automotive e-compressor is a hermetically sealed electric motor-driven compressor unit that pressurizes refrigerant within a closed-loop HVAC or battery thermal management circuit, typically operating at voltages between 200V and 800V DC depending on vehicle architecture. Scroll compressors dominate the product type landscape due to superior efficiency and lower noise signatures in passenger electric vehicles, while centrifugal designs are gaining traction in heavy-duty commercial applications where higher mass flow rates are required. The OEM installation channel captures the bulk of value given the integration complexity with vehicle thermal management controllers, though aftermarket demand is emerging for fleet retrofit programs.
The EPA regulates refrigerant leakage rates and SNAP program approvals under the Clean Air Act, while the EU F-Gas Regulation phases down hydrofluorocarbon quotas and mandates lower-GWP alternatives in automotive climate systems. China's MIIT enforces dual carbon goals that push domestic OEMs toward high-efficiency electric compressors with CO2 or R-1234yf compatibility. Stakeholders must monitor how refrigerant chemistry transitions and voltage platform standardization reshape supplier qualification requirements and manufacturing capital deployment.
Market Dynamics
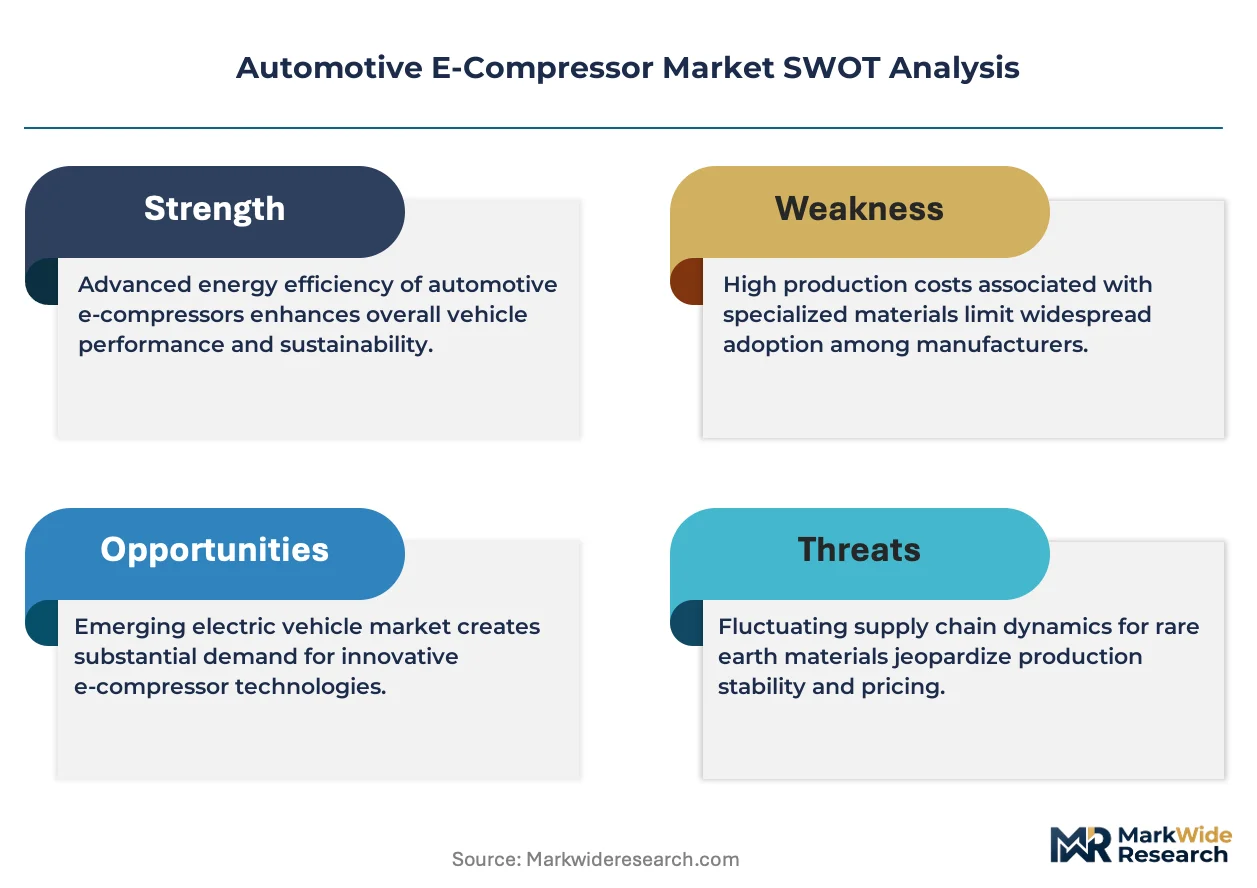
The automotive e-compressor market is being fundamentally restructured by voltage platform standardization, as OEMs consolidate around 400V and 800V architectures that demand redesigned motor windings, power electronics, and thermal interfaces from suppliers.
Growth Catalysts
- Battery thermal management expansion:Electric vehicle OEMs are mandating dedicated cooling circuits for high-energy-density battery packs, creating dedicated demand channels for high-voltage compressor units.
- EU F-Gas Regulation phase-down:The European Union's hydrofluorocarbon quota reductions are forcing automotive HVAC suppliers to engineer compressors compatible with CO2 and R-1234yf refrigerants.
- China MIIT dual carbon enforcement:The Ministry of Industry and Information Technology's efficiency mandates are accelerating domestic OEM adoption of electrically driven compressor systems over belt-driven alternatives.
Market Restraints
- Rare earth magnet supply concentration:Neodymium and dysprosium sourcing dependencies on Chinese processing facilities expose compressor motor manufacturers to input cost volatility and export restriction risks.
- High-voltage safety certification complexity:ISO 6469 and IEC 60664 clearance requirements for 800V systems extend product qualification timelines and inflate development expenditure.
- Scroll compressor manufacturing concentration:Precision machining capacity for orbiting scroll components remains concentrated among Japanese and German tooling suppliers, limiting supply elasticity.
Strategic Opportunities
- Commercial vehicle electrification:Heavy-duty truck and bus thermal management systems represent an underpenetrated application segment with distinct mass flow and duty cycle requirements.
- India PLI scheme for automotive components:The Production Linked Incentive program offers cost-offset opportunities for compressor manufacturers establishing local assembly operations.
- Heat pump HVAC convergence:Integration of reversible refrigeration cycles for cabin heating and battery conditioning enables component suppliers to capture expanded system value.
Industry Challenges
- Power electronics integration expertise:Compressor suppliers face acute talent scarcity in inverter design, EMC mitigation, and functional safety engineering for automotive-grade motor control.
- Vehicle platform validation cycles:OEM thermal system sign-off protocols spanning climatic wind tunnel testing and real-world durability programs compress supplier development schedules.
- Refrigerant chemistry transition synchronization:Misalignment between CO2 system adoption in Europe and R-1234yf persistence in North America forces parallel product line maintenance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive E-Compressor Market |
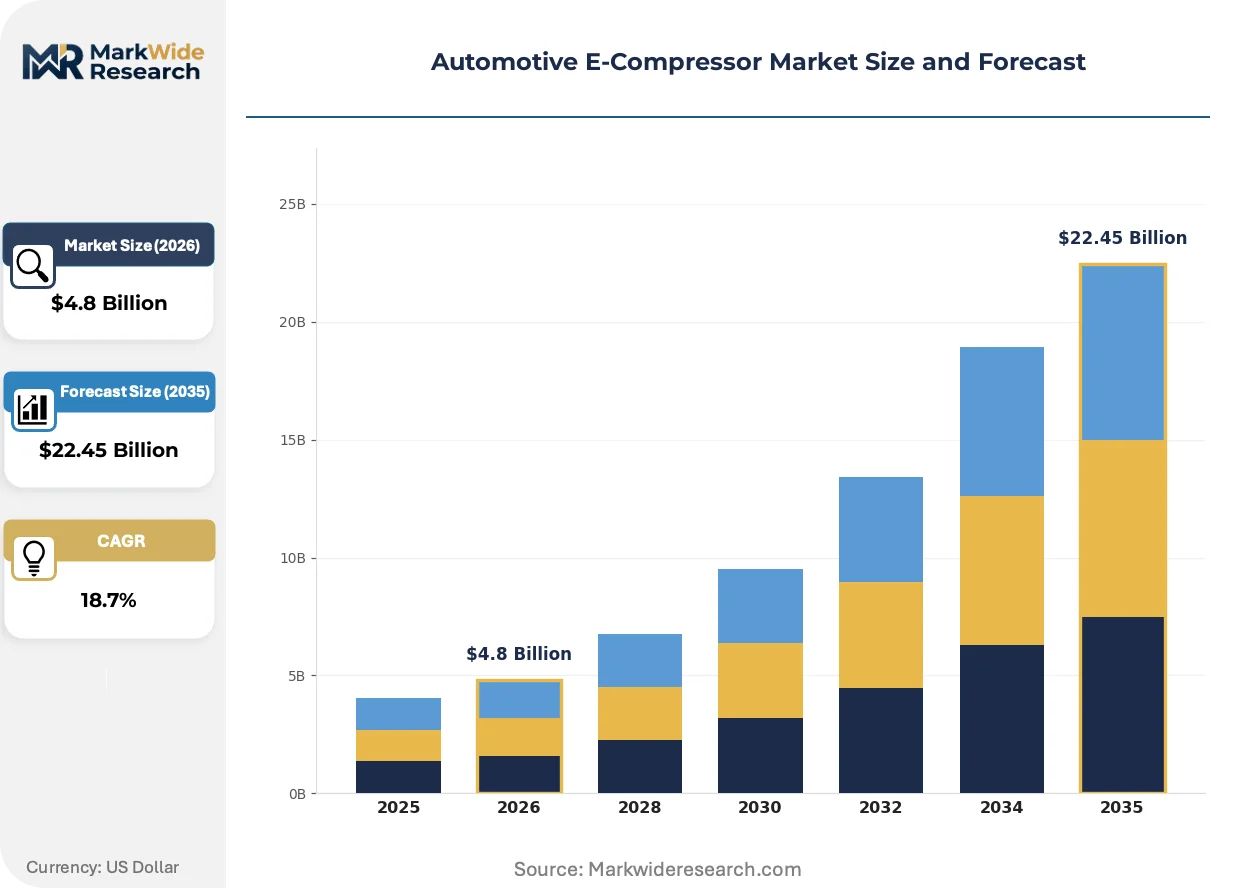
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.45 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Scroll, Reciprocating, Centrifugal, Rotary Application: Electric Vehicles, Hybrid Vehicles, Fuel Cell Vehicles, Commercial Vehicles Installation: OEM, Aftermarket, Integrated Solutions, Standalone Systems End User: Passenger Cars, Light Trucks, Heavy Trucks, Buses |
| Companies Covered | Valeo, TOYOTA INDUSTRIES CORPORATION, DENSO CORPORATION, Mitsubishi Electric Corporation, BorgWarner Inc., Hanon Systems, SANDEN CORPORATION, Robert Bosch GmbH, MAHLE GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive E-Compressor Market Strategic Shifts & Innovations
Voltage architecture bifurcation and refrigerant chemistry transitions are compressing supplier development cycles while opening technical differentiation avenues for component manufacturers with integrated system capabilities.
Scroll compressor technology is consolidating its position as the dominant positive displacement architecture for passenger electric vehicles, with European and Japanese OEMs specifying orbiting scroll designs for their superior volumetric efficiency at partial load conditions. Tier 1 suppliers are integrating variable-speed inverter drives directly into compressor housings, collapsing the traditional separation between motor and controller procurement. This integration is consolidating supplier tiers, as power electronics capabilities become prerequisite for compressor contract qualification.
The EPA SNAP program approvals under the Clean Air Act are tightening refrigerant eligibility criteria, disqualifying high-GWP hydrofluorocarbon blends from new vehicle platform certifications. Automotive HVAC engineers are responding by redesigning compressor displacement volumes and material compatibility for CO2 transcritical cycles. North American OEM sourcing teams are most affected, as they balance California Air Resources Board mandates against federal compliance pathways.
Fleet operators are unbundling thermal system service contracts from vehicle procurement agreements, creating direct aftermarket channels for compressor replacement and retrofit programs. This disintermediation is compressing traditional OEM captive parts margins while opening volume opportunities for independent remanufacturers. Heavy-duty commercial fleets in Germany and the United States are piloting this model most aggressively, driven by total cost of ownership transparency requirements in electrification transition planning.
Automotive E-Compressor Market Segmentation
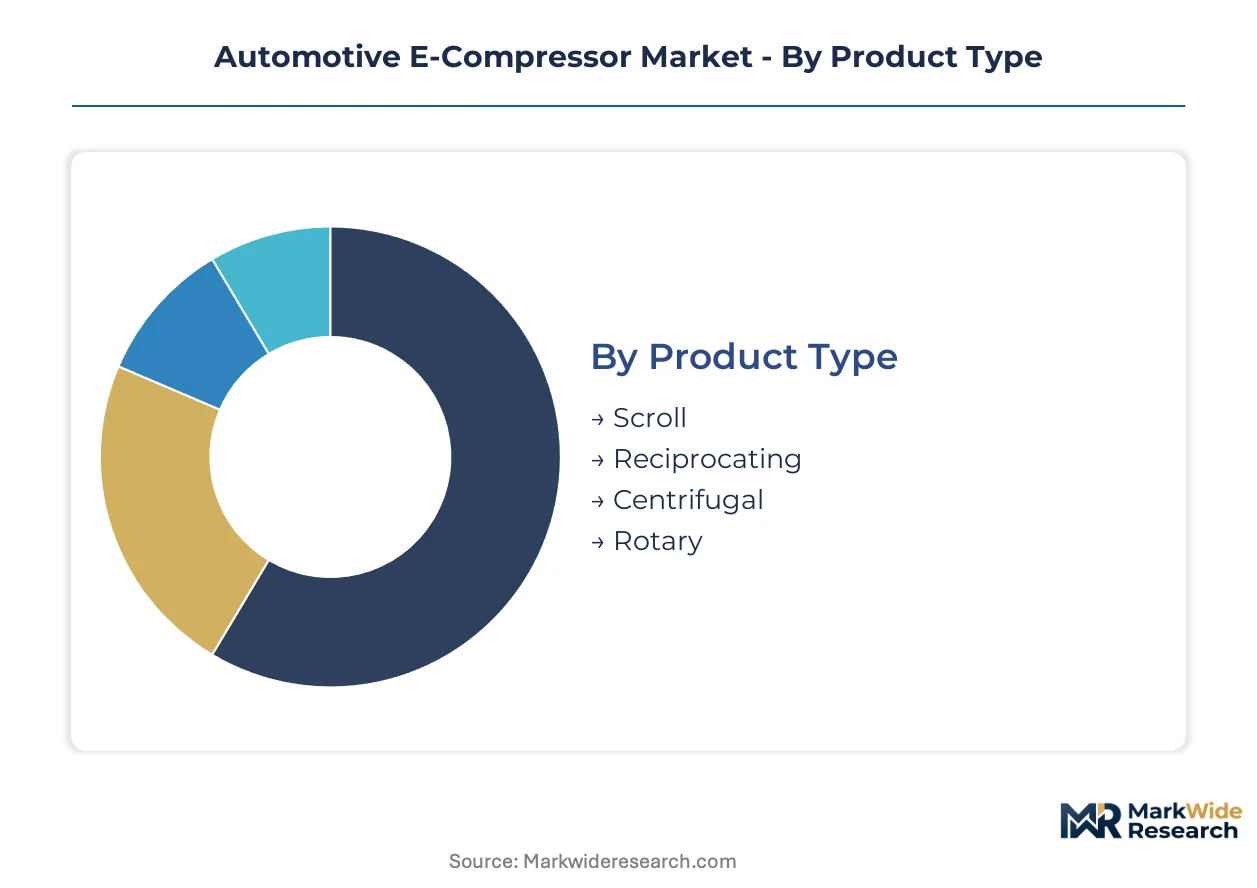
Segmentation in automotive e-compressors reveals how voltage architecture, refrigerant chemistry, and vehicle electrification intensity reshape procurement patterns across OEM and aftermarket channels. Compressor suppliers must align product portfolios with diverging thermal management requirements across passenger, commercial, and fuel cell platforms.
Product Type:
Buyers differentiate by efficiency requirements at partial load conditions and noise signatures critical to cabin comfort ratings.
- Scroll:Orbiting scroll mechanisms deliver superior volumetric efficiency across variable-speed operation, making them dominant in passenger electric vehicles where NVH performance directly influences consumer satisfaction scores. European and Japanese OEMs specify scroll designs for 400V and 800V battery thermal management circuits.
- Centrifugal:Dynamic compression enables higher mass flow rates required by heavy-duty commercial thermal systems, with demand concentrating in German and US long-haul truck electrification programs where duty cycles demand continuous high-output cooling.
- Reciprocating:Piston-driven positive displacement suits cost-sensitive hybrid applications with lower voltage architectures.
- Rotary:Vane and screw variants serve niche fuel cell humidification and auxiliary cooling functions.
Scroll leads volumes today; centrifugal is gaining share fastest in commercial electrification segments.
Application:
Vehicle electrification intensity determines compressor voltage platform, refrigerant compatibility, and integration depth with thermal management controllers.
- Electric Vehicles:Dedicated high-voltage compressor units serve dual-circuit architectures separating cabin HVAC from battery conditioning, with OEMs mandating integrated inverter drives for system efficiency optimization. Chinese MIIT efficiency enforcement accelerates domestic procurement of electrically driven systems.
- Commercial Vehicles:Heavy-duty truck and bus thermal loads require scaled displacement volumes and reinforced mechanical durability, with fleet operators in Germany piloting service-contract unbundling that opens direct aftermarket channels.
- Hybrid Vehicles:Belt-electric hybrid compressor configurations persist where 48V mild-hybrid architectures limit full electrification.
- Fuel Cell Vehicles:Specialized compressors manage stack humidification and cathode air supply with oil-free operation requirements.
Electric vehicles dominate current procurement volumes; commercial vehicles are expanding most quickly as heavy-duty electrification accelerates.
Installation:
Channel selection reflects integration complexity with vehicle thermal management controllers and fleet operator service strategies.
- OEM:Factory installation captures system-level value through embedded compressor-inverter-controller integration, with thermal management sign-off protocols spanning climatic wind tunnel validation. OEM captive channels concentrate procurement among established Tier 1 suppliers with power electronics capabilities.
- Aftermarket:Fleet retrofit programs and replacement demand emerge as operators unbundle thermal service contracts from vehicle procurement, compressing traditional parts margins while opening volume for remanufacturers in US and German heavy-duty segments.
- Integrated Solutions:Packaged thermal management modules combine compressor, heat exchanger, and control electronics for simplified OEM sourcing.
- Standalone Systems:Discrete compressor units serve legacy platform replacements and specialty vehicle conversions.
OEM installation commands value concentration today; aftermarket channels are climbing the fastest as fleet electrification service models evolve.
End User:
Vehicle mass and duty cycle specifications determine compressor displacement, refrigerant charge, and durability engineering requirements.
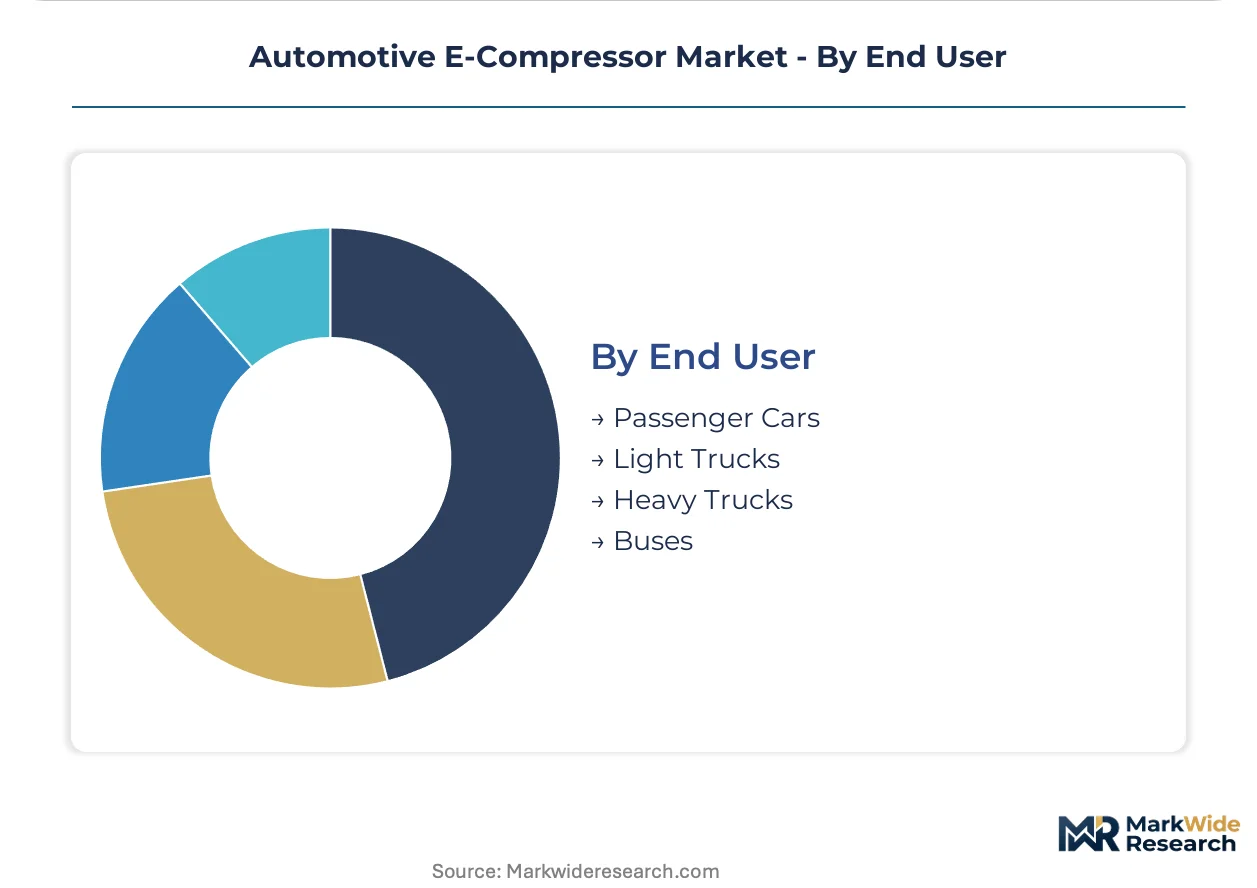
- Passenger Cars:Compact scroll compressors prioritize acoustic performance and packaging efficiency, with EU F-Gas Regulation phase-down forcing CO2 and R-1234yf compatibility redesigns across European OEM platforms.
- Heavy Trucks:Sustained high-load operation demands reinforced bearing systems and expanded displacement volumes, with US EPA refrigerant leakage standards and CARB mandates shaping qualification requirements for North American sourcing.
- Light Trucks:Mid-duty thermal loads balance efficiency and durability for utility and delivery applications.
- Buses:Urban transit duty cycles with frequent door openings require rapid pull-down capacity and heat pump reversibility for heating-dominated climates.
Passenger cars anchor current demand; heavy trucks are expanding most quickly as commercial electrification penetrates long-haul segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent pools in Stuttgart, Shanghai, and Detroit anchor the automotive e-compressor industry's geographic footprint. OEM procurement teams co-locate with these clusters to compress supplier qualification timelines and accelerate platform integration.
China
MIIT dual carbon enforcement accelerates domestic OEM procurement of high-voltage electric compressors over belt-driven alternatives. The ministry's efficiency mandates disqualify legacy thermal systems from new vehicle platform approvals. Shanghai and Shenzhen house the densest concentrations of e-compressor assembly operations serving BYD, NIO, and XPeng supply chains.
Germany
EU F-Gas Regulation phase-down forces compressor redesigns for CO2 transcritical cycles across Volkswagen, BMW, and Mercedes-Benz platforms. The KBA enforces refrigerant leakage standards that exceed baseline EU requirements for type approval. Stuttgart and Munich anchor supplier engineering centers where DENSO and MAHLE maintain thermal system development campuses.
United States
EPA SNAP program approvals under the Clean Air Act tighten refrigerant eligibility criteria for new vehicle certifications. CARB mandates in California accelerate CO2 and R-1234yf compatibility requirements ahead of federal timelines. Detroit and the Southeast manufacturing corridor concentrate OEM thermal system procurement teams for Ford and General Motors.
Japan
METI efficiency standards push domestic automakers toward integrated inverter-compressor architectures for battery thermal management. The ministry's technology roadmaps prioritize 800V platform standardization for export competitiveness. Nagoya and Tokyo house concentrated supplier engineering operations where TOYOTA INDUSTRIES and Mitsubishi Electric maintain captive development facilities.
South Korea
Ministry of Trade, Industry and Energy carbon neutrality targets accelerate Hyundai and Kia adoption of dedicated electric compressor systems. Domestic content requirements in free trade agreements shape supplier localization strategies. Seoul and Ulsan concentrate manufacturing operations where Hanon Systems anchors thermal module assembly for export markets.
Automotive E-Compressor Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across three distinct supplier tiers. Tier 1 integrated thermal system houses capture OEM factory-fit contracts through embedded inverter capabilities. Tier 2 component specialists supply scroll orbiting mechanisms and precision-machined housings to multiple assembler brands. Tier 3 material providers concentrate rare earth magnet processing and power semiconductor sourcing. Competitive moves center on backward integration into magnet supply chains and geographic expansion into India PLI scheme jurisdictions.
Within the integrated thermal system tier, DENSO CORPORATION, Valeo, and BorgWarner Inc. exemplify divergent strategic positioning. DENSO anchors Japanese and European OEM relationships through powertrain integration heritage. Valeo occupies a position as a dedicated electric thermal management pure-play with European headquarters structure. BorgWarner represents the diversified conglomerate archetype extending e-mobility portfolio breadth into compressor systems. These three companies illustrate how supplier qualification requirements for 800V architectures and refrigerant chemistry flexibility reshape competitive positioning.
| Leading Market Players |
|---|
| Valeo |
| TOYOTA INDUSTRIES CORPORATION |
| DENSO CORPORATION |
| Mitsubishi Electric Corporation |
| BorgWarner Inc. |
| Hanon Systems |
| SANDEN CORPORATION |
| Robert Bosch GmbH |
| MAHLE GmbH |
| Others |
Cost & Logistics Intelligence
Backward integration into rare earth magnet processing anchors both supply security and pricing power for compressor motor manufacturers, as Chinese export restrictions on neodymium and dysprosium force OEMs to qualify multi-source suppliers or absorb input cost volatility.
Pricing Analysis
Capacity additions in China are reshaping price floors for scroll compressor orbiting mechanisms, pressuring Japanese and German precision machining specialists. Three-tier pricing structure across premium 800V integrated systems, standard 400V modular units, and economy belt-driven alternatives separates qualification tiers. Cost compression in the economy tier is intensifying because domestic Chinese OEMs are consolidating procurement around local suppliers. Fleet operators in heavy-duty commercial segments demonstrate highest price sensitivity, while luxury passenger EV OEMs prioritize thermal performance over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from European and North American OEMs mandate multi-supplier qualification for rare earth magnets and power semiconductors, fragmenting procurement leverage. Manufacturing concentrates in China, Japan, and Germany for precision-machined scroll components and motor winding assemblies. The supply chain draws from concentrated rare earth processing facilities, silicon carbide wafer production, and aluminum die-casting operations. Single-source vulnerability in Japanese orbiting scroll tooling exposes Tier 1 assemblers to capacity constraints. Distribution runs through OEM captive channels for factory-fit contracts, with aftermarket remanufacturers emerging in US and German fleet service markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive e-compressor market functions as a regulatory compounder, with EU F-Gas Regulation phase-down and China MIIT dual carbon enforcement creating sustained demand displacement from belt-driven to electrically driven thermal systems.
For Market Incumbents: Extend inverter-compressor integration capabilities to defend against emerging Chinese pure-play specialists capturing domestic OEM volume. Secure captive magnet supply through joint venture structures with rare earth processors. Add 800V qualification capacity ahead of European platform standardization timelines. For New Entrants and Emerging Players: Fleet service contract unbundling in German and US heavy-duty segments offers direct aftermarket channel access without OEM captive parts network dependence. Target commercial vehicle electrification programs where scroll durability requirements differ from passenger specifications. Pursue power electronics talent acquisition in Stuttgart and Detroit engineering clusters. For Investors and Strategic Acquirers: Roll-up economics work for regional thermal module assemblers because OEM qualification barriers protect incumbent revenue streams while refrigerant chemistry transitions force parallel product line investments. Five-to-ten year viability hinges on 800V and CO2 system compatibility positioning. Monitor EPA SNAP program approval timelines for refrigerant eligibility shifts as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | 800V architecture convergence reduces supplier qualification burden for DENSO and Valeo. |
| Backward Integration | Magnet supply joint ventures mitigate Chinese export restriction exposure for motor manufacturers. |
| Heat Pump Convergence | Reversible refrigeration cycles expand component value capture for integrated system suppliers. |
| Geographic Manufacturing Footprint | India PLI scheme assembly operations offset cost disadvantages in European sourcing. |
| Battery Supply Agreement | Dedicated cooling circuit partnerships lock in high-voltage compressor volumes with BYD and CATL. |
Research Approach
Bottom-up vehicle production modeling reconciled against top-down Tier 1 supplier shipment tracking forms the analytical core of this study. Primary interviews with OEM platform engineers, Tier 1 supplier procurement directors, aftermarket fleet service managers, and thermal system R&D leads combined with secondary validation from vehicle registration databases, IHS Markit production forecasts, EPA SNAP program filings, and EU F-Gas Regulation quota tracking. The approach triangulates compressor unit demand against battery electric vehicle rollout schedules and thermal management content per vehicle assumptions.
Historical trendline analysis of scroll and centrifugal compressor adoption rates across passenger, commercial, and fuel cell platforms informs the projection framework. Segmentation modeling spans product type, voltage architecture, refrigerant chemistry compatibility, vehicle class, and regional production cluster. CAGRs derive from fitted growth curves applied to OEM platform launch timelines and fleet electrification policy enforcement schedules. Power electronics integration rates and rare earth magnet price indices feed industry-specific forecast sensitivity.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to refrigerant chemistry standardization divergence between CO2 and R-1234yf systems, 800V platform adoption velocity, and Chinese rare earth export policy shifts. Deviation in EPA SNAP program approval timelines or EU F-Gas Regulation enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
Nox Automotive Sensors Market
Automotive Electrical & Electronics
Global Automotive Charge Air Cooler Market
Automotive Electrical & Electronics
Global Automotive ECU Market
Automotive Electrical & Electronics
Automotive Alternator and Starter Motor Market
Automotive Electrical & Electronics
Car Bulb Market
Automotive Electrical & Electronics
Automotive Power Module Packaging Market
Automotive Electrical & Electronics
Automotive Electronic Expansion Valve Market
Automotive Electrical & Electronics
Europe Automotive Camera Market
Automotive Electrical & Electronics
Automotive Inverter Busbar Laminates Market
Automotive Electrical & Electronics
US Automotive EPS Market
Automotive Electrical & Electronics
Automotive Electronic Suspension System (ESS) Market
Automotive Electrical & Electronics
Asia Pacific Automotive Camera Market
Automotive Electrical & Electronics
North America Automotive Lead-Acid Battery Market
Automotive Electrical & Electronics
E-Bike Lights Market
Automotive Electrical & Electronics
Global Automotive DC-DC Converters Market
Automotive Electrical & Electronics
Automotive E-Axle Disconnect Actuator Market