
 Global Automotive Auxiliary Brake Market | 2026-2036
Global Automotive Auxiliary Brake Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Auxiliary Brake Market Intelligence
A divergence in capital investment for developing integrated electronic and regenerative braking systems is reorganizing the competitive landscape. Knorr-Bremse leverages its extensive R&D infrastructure to lead in advanced pneumatic and electronic systems for commercial vehicles. In contrast, specialists like SABO compete by focusing on cost-effective mechanical and hydraulic solutions for specific aftermarket segments. Jacobs Vehicle Systems sustains its market position through its specialized expertise in engine brake technology.
An automotive auxiliary brake is a secondary system designed to supplement a vehicle's primary service brakes, reducing wear and preventing overheating. These systems, such as engine brakes that create retarding power via exhaust back pressure, are critical for maintaining control on steep grades. Within brake types, exhaust and engine brakes command the largest share, primarily for commercial trucks and buses. The regenerative brake technology segment, however, is expanding rapidly with the electrification of passenger cars and the development of autonomous vehicles.
Regulatory frameworks are a primary influence on system design and adoption, particularly for commercial vehicles. Mandates from the United States' NHTSA under FMVSS and comparable vehicle safety standards in the European Union set stringent performance requirements. Concurrently, China's GB standards for heavy vehicles necessitate the integration of effective auxiliary braking. The central challenge for manufacturers is to engineer systems that meet these diverse global compliance demands while managing cost and weight.
Market Dynamics
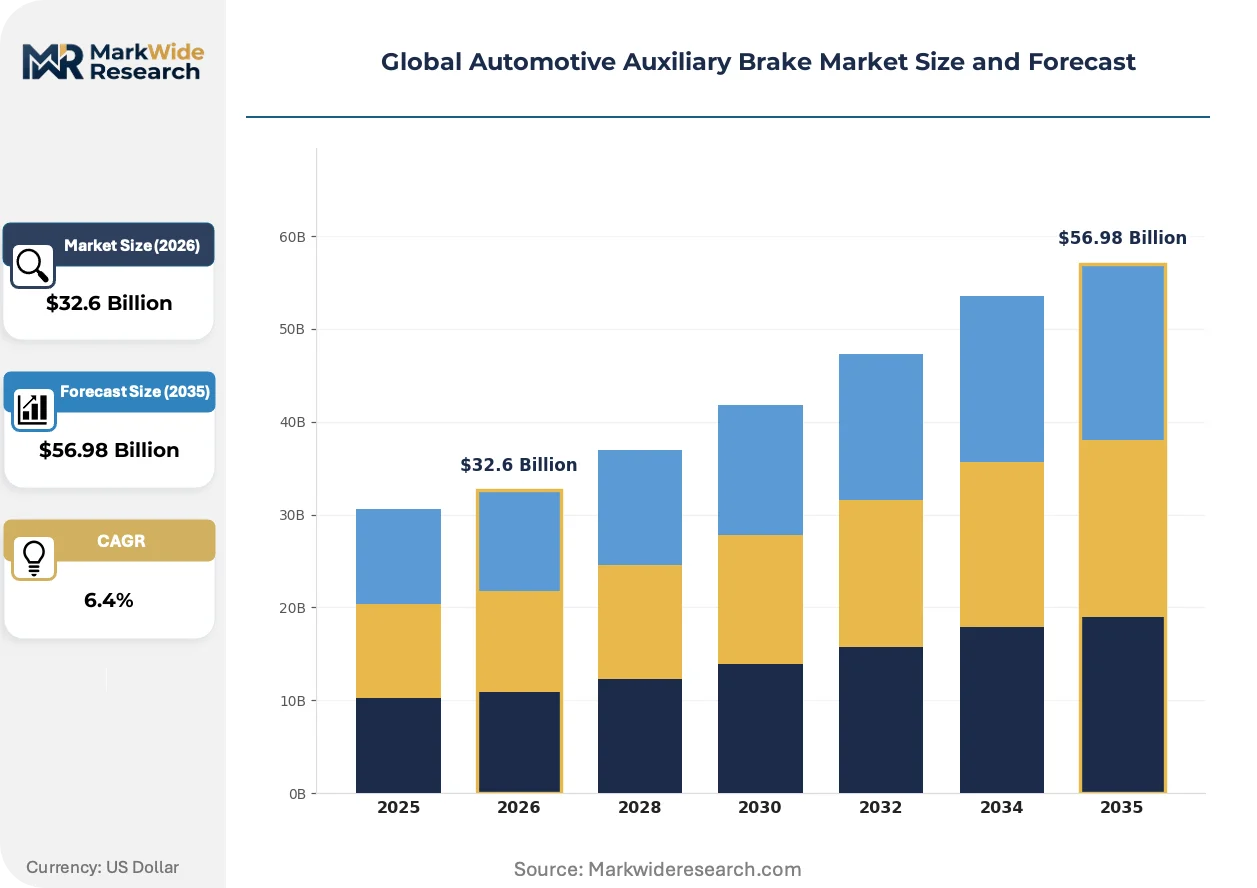
The market's central dynamic is the divergence between high-cost, integrated electronic systems for new heavy vehicles and cost-effective mechanical solutions for the aftermarket. This split is driven by tightening safety mandates and the parallel rise of vehicle electrification, creating distinct technology and cost pathways.
Growth Catalysts
- Stringent Safety Mandates:Regulations like the United States' FMVSS and China's GB standards for heavy vehicles compel the integration of auxiliary brakes to enhance safety and reduce primary brake failure on steep grades.
- Logistics Sector Expansion:Rapid growth in China's long-haul trucking and construction industries fuels demand for heavy-duty commercial vehicles equipped with robust engine and exhaust brakes to manage heavy loads.
- Vehicle Electrification:The expansion of electric passenger and commercial vehicle fleets drives the adoption of regenerative braking, which functions as an auxiliary system by converting kinetic energy into electrical energy.
Market Restraints
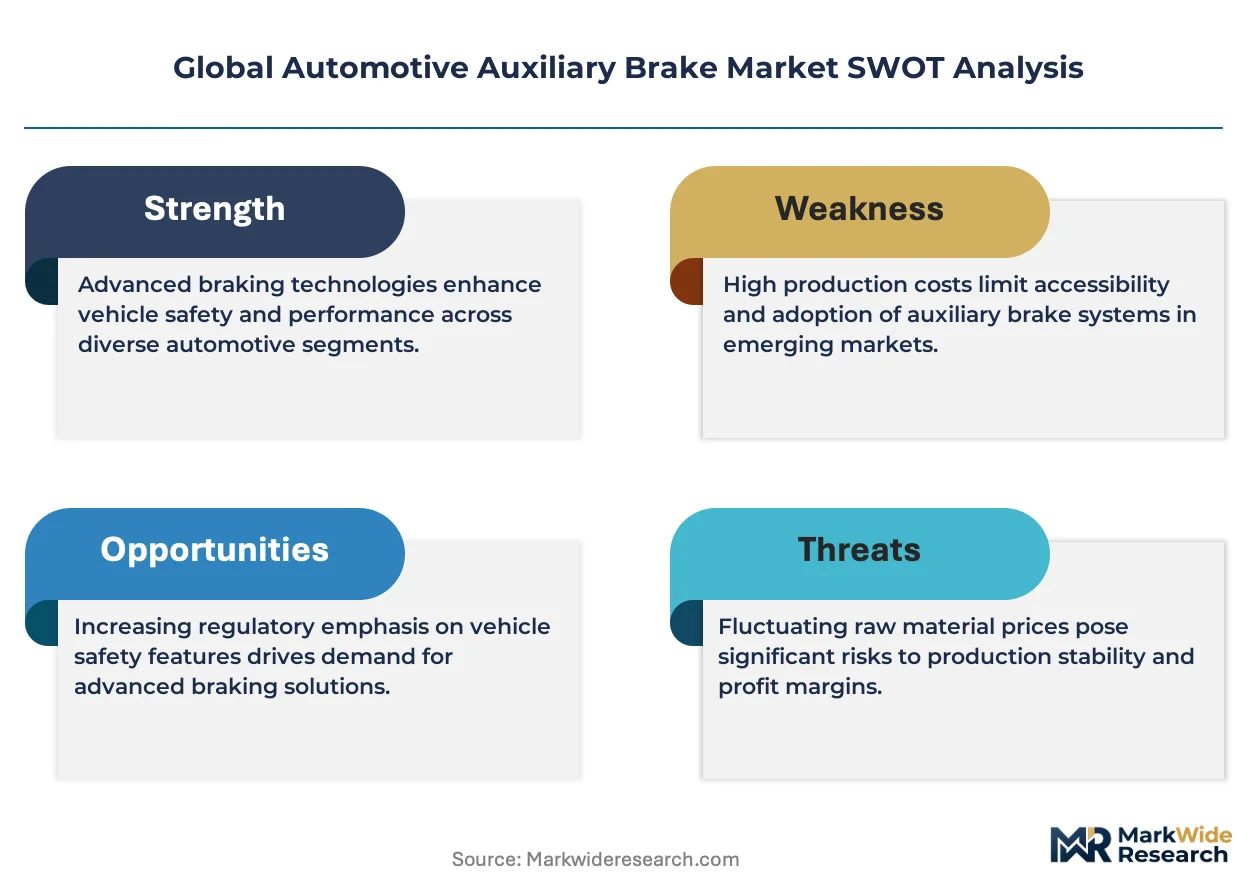
- High Initial Investment:The significant upfront cost of advanced electronic and regenerative braking systems acts as a barrier to adoption, particularly for small fleet operators and in price-sensitive developing markets.
- Weight and Complexity:Integrating auxiliary brake components adds weight and complexity to vehicle design, posing engineering challenges and potentially impacting fuel efficiency and payload capacity for non-electric vehicles.
- Aftermarket Price Sensitivity:In the aftermarket, especially for older trucks, there is strong preference for lower-cost, simpler mechanical and hydraulic retarders over more expensive, complex electronic upgrades.
Strategic Opportunities
- Aftermarket in Emerging Economies:Modernizing the aging commercial truck fleets in Latin American and Southeast Asian nations presents a significant opportunity for cost-effective aftermarket exhaust and hydraulic brake systems.
- Light Commercial Vehicle Electrification:The growing market for electric light commercial vehicles (e-LCVs) in urban logistics creates a new application segment for scaled-down, efficient regenerative braking technologies.
- ADAS Integration:Converging auxiliary braking controls with Advanced Driver-Assistance Systems (ADAS) enables predictive braking functions, creating opportunities for software-defined safety features and enhanced automation.
Industry Challenges
- Global Compliance Engineering:Manufacturers face the considerable challenge of designing systems that meet the diverse and often conflicting performance and certification standards of the EU, the US, and China.
- System Integration with Legacy Platforms:Integrating modern electronic auxiliary brakes with the varied and older vehicle electronic architectures found in the global fleet presents significant technical and software compatibility hurdles.
- R&D Capital Intensity:Developing next-generation regenerative and integrated electronic braking systems requires substantial and sustained capital expenditure on research, development, and testing infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Auxiliary Brake Market |
| Market Size in 2026 | $32.6 Billion |
| Market Size in 2035 | $56.98 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Electromagnetic, Hydraulic, Pneumatic, Vacuum, Mechanical, Regenerative Brake Type: Drum, Disc, Air, Exhaust, Engine, Electric Vehicle Category: Passenger Cars, Commercial Trucks, Buses, Two-Wheelers, Autonomous Vehicles, Specialty Vehicles Distribution Channel: OEMs, Aftermarket Dealers, Tier-1 Suppliers, Fleet Operators, Maintenance Workshops, Online Retailers |
| Companies Covered | Bendix, Wabco, Knorr-Bremse, Haldex, SABO, Jacobs Vehicle Systems, Robert Bosch GmbH, Continental AG, ZF Friedrichshafen AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Auxiliary Brake Market Strategic Shifts & Innovations
Electrification and software integration are fundamentally altering the function of auxiliary braking. The technology is evolving from a standalone mechanical supplement into an integral component of the powertrain, energy management, and automated safety systems, especially within commercial vehicles.
Software-Defined Braking
Integrated electronic braking systems combine service, parking, and auxiliary functions into a single, software-controlled unit. Commercial vehicle OEMs are adopting these systems for new heavy-duty truck platforms to reduce component redundancy and enable advanced safety features. This integration is decomposing the traditional market boundary between primary and secondary braking system suppliers.
Predictive Actuation via Regulation
European Union regulations mandating Advanced Emergency Braking Systems (AEBS) in new commercial vehicles are a primary influence. This policy is forcing OEMs to integrate auxiliary brake actuation with forward-looking radar and sensor data for automated interventions. The heavy-duty truck and bus segments are most affected, accelerating the shift from driver-activated systems to predictive safety protocols.
Total Cost of Ownership Focus
Fleet operators are increasingly prioritizing total cost of ownership (TCO) over upfront component price, considering factors like brake lining wear and energy recovery. This shift in procurement logic diminishes the appeal of simple mechanical retarders in favor of systems like regenerative brakes that offer operational savings. This TCO-centric evaluation is most prominent within the long-haul logistics fleets of North America and Europe.
Global Automotive Auxiliary Brake Market Segmentation
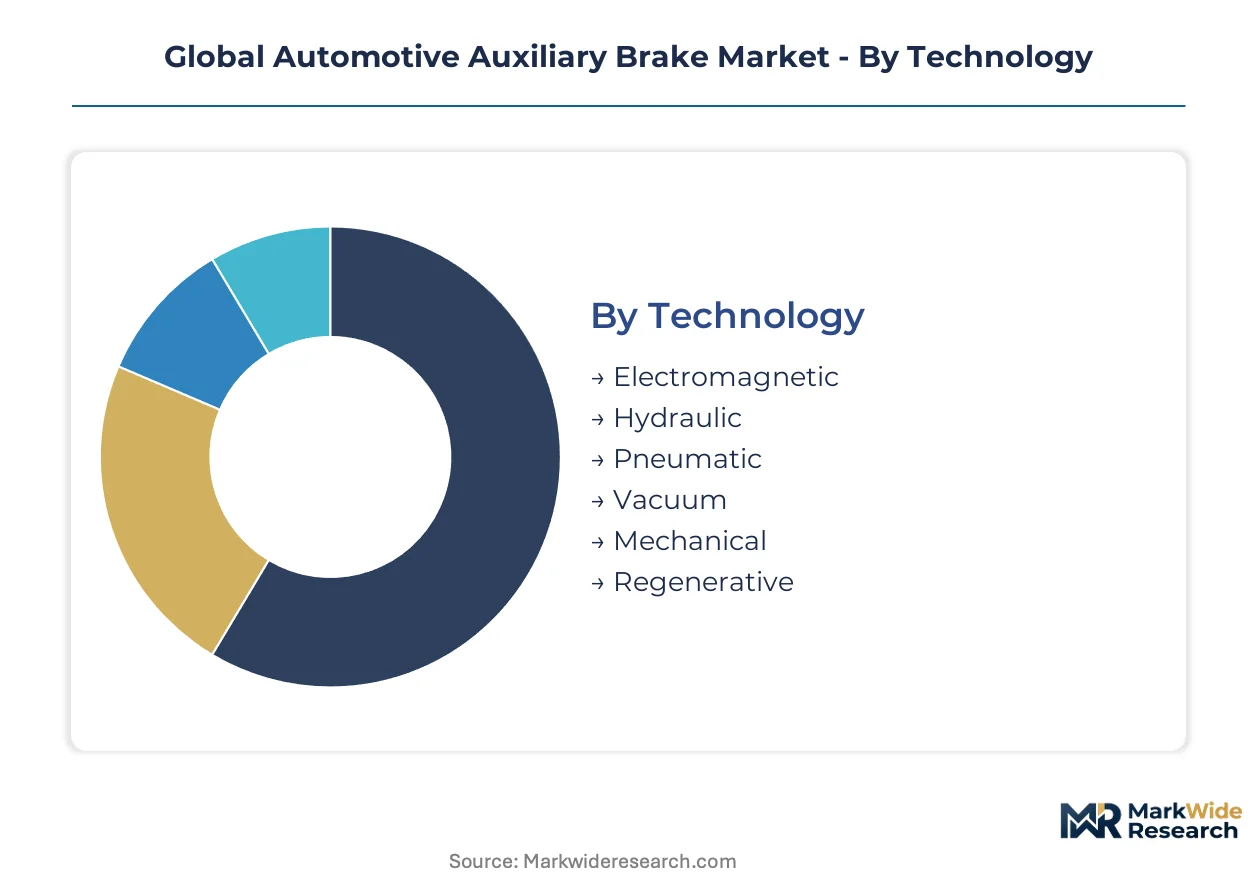
The global automotive auxiliary brake market segments across diverse technologies, brake types, vehicle categories, and distribution channels. These distinctions highlight the varied needs of vehicle manufacturers and operators. Understanding these segments is crucial for identifying areas of growth and technological evolution within the industry.
Technology:
Substitution pressure is reshaping the technology landscape, particularly for traditional mechanical systems facing displacement by advanced electronic and regenerative solutions.
- Regenerative:These systems convert kinetic energy into electrical energy during deceleration, storing it for later use. Demand concentrates in electric passenger cars and commercial vehicles due to electrification mandates and energy efficiency goals.
- Pneumatic:Utilizing compressed air to generate braking force, these systems are prevalent in heavy-duty commercial trucks and buses. Their robust design supports high braking demands in long-haul logistics across China and the United States.
- Electromagnetic:These retarders use electromagnetic fields to create resistance, suitable for medium to heavy commercial vehicles.
- Hydraulic:These systems use fluid pressure for retarding force, often found in specialized vehicles and some commercial applications.
- Vacuum:Relying on engine vacuum, these systems provide supplemental braking, typically in lighter commercial vehicle applications.
- Mechanical:Simple friction-based systems offer basic auxiliary braking, primarily in cost-sensitive aftermarket segments.
Mechanical systems anchor the volume base while regenerative technology gains share at the steepest rate.
Brake Type:
Cost tier differentiation influences the adoption of various brake types, with advanced electric and exhaust brakes commanding higher price points for performance benefits.
- Engine:These systems use engine compression to slow the vehicle, creating significant retarding power. They are critical for heavy-duty commercial trucks navigating steep grades in mountainous regions like the Alps and Rockies.
- Electric:These brakes use electric motors for deceleration and energy recovery, integral to electric and hybrid powertrains. Their application is expanding across passenger cars and light commercial electric vehicles.
- Drum:Traditional friction-based brakes, often found in older commercial vehicles and some industrial applications.
- Disc:Offering superior heat dissipation, these are common in passenger cars and increasingly in commercial vehicles.
- Air:These systems use compressed air to actuate brakes, standard in heavy commercial vehicles for reliable stopping power.
- Exhaust:These brakes restrict exhaust flow to generate back pressure, commonly used in commercial trucks for supplemental braking.
The diversity in brake types reflects specialized application needs, from heavy-duty commercial vehicle demands to passenger car electrification.
Vehicle Category:
Application-specific requirements dictate auxiliary brake system design, with heavy commercial vehicles demanding robust retardation and passenger cars focusing on energy efficiency.
- Commercial Trucks:These vehicles require powerful auxiliary brakes for heavy loads and long hauls, driven by safety regulations like NHTSA's FMVSS. China's logistics sector fuels significant demand for these robust systems.
- Autonomous Vehicles:Integration with ADAS and predictive braking is essential for these vehicles to ensure redundant safety. The development of Level 4 and 5 autonomous systems drives demand for highly reliable electronic auxiliary braking.
- Passenger Cars:Regenerative braking is the primary auxiliary system here, driven by electrification and fuel economy targets.
- Buses:Require durable auxiliary brakes for frequent stops and heavy passenger loads, especially in urban transport.
- Two-Wheelers:Auxiliary braking is less common, but some electric models incorporate regenerative features for extended range.
- Specialty Vehicles:Includes off-road, construction, and agricultural machinery, often using hydraulic or electromagnetic retarders.
Commercial Trucks represent a mature market segment, while Autonomous Vehicles are emerging as a high-growth application.
Distribution Channel:
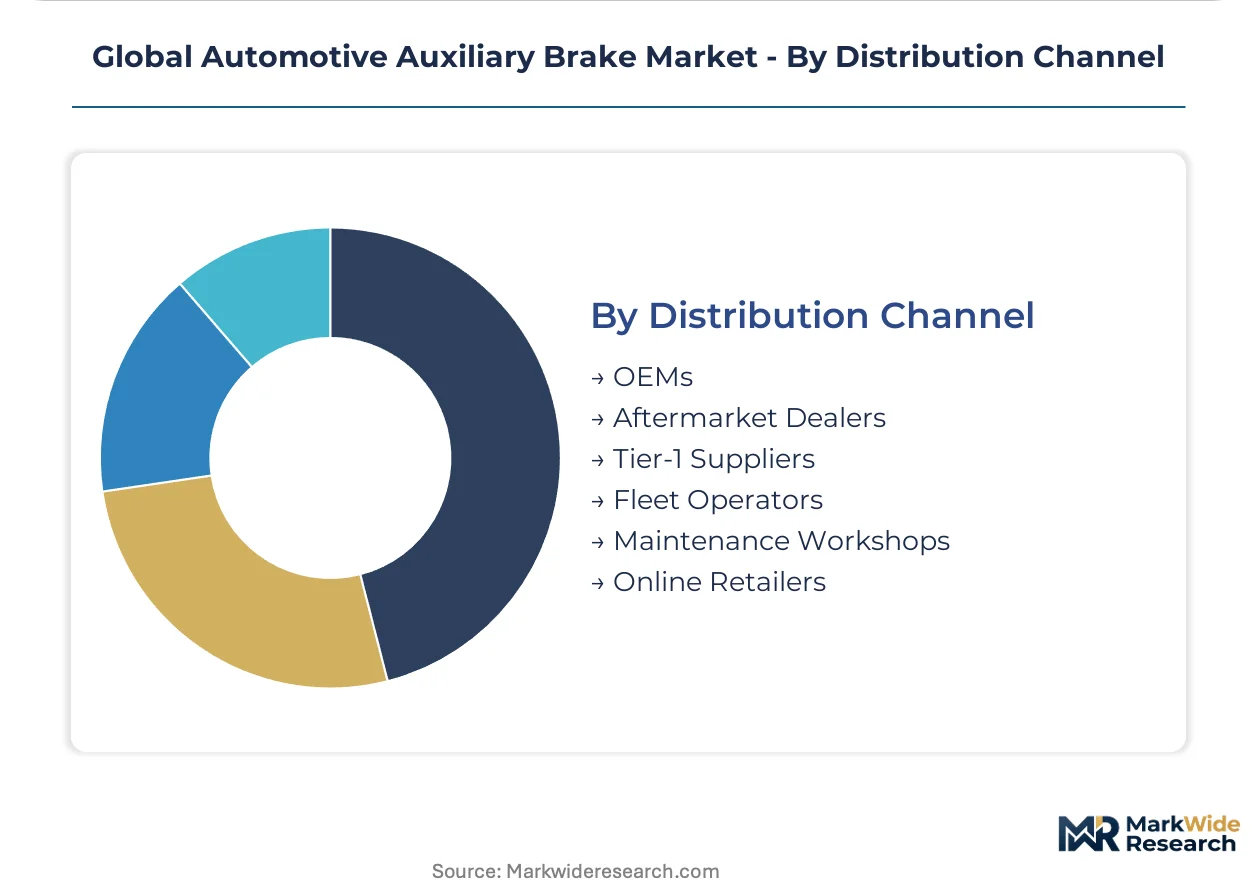
Supply concentration varies across distribution channels, with OEMs and Tier-1 suppliers dominating initial vehicle integration, while aftermarket channels cater to replacement and upgrades.
- OEMs:Original Equipment Manufacturers integrate auxiliary brake systems into new vehicles during production. This channel is driven by stringent safety regulations and vehicle design specifications from brands like Mercedes-Benz and Volvo.
- Aftermarket Dealers:These channels supply replacement parts and upgrade kits for existing vehicles. Cost-effective mechanical and hydraulic solutions are preferred by fleet operators in emerging economies like Brazil and India.
- Tier-1 Suppliers:These companies develop and manufacture components directly for OEMs, influencing technology standards.
- Fleet Operators:Purchase and maintain auxiliary brakes for their vehicle fleets, prioritizing total cost of ownership.
- Maintenance Workshops:Provide installation and repair services for auxiliary braking systems, particularly in the aftermarket.
- Online Retailers:Offer a growing platform for aftermarket parts, appealing to individual owners and smaller workshops.
OEMs exert strong influence on initial system specifications, while aftermarket channels drive continuous product lifecycle support.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The consumption mix for automotive auxiliary brakes varies significantly by region, with heavy commercial vehicle demand dominating in developing economies while electrified passenger car adoption drives regenerative braking in mature markets. Regulatory mandates and fleet modernization initiatives further shape regional market dynamics.
China
Rapid expansion of China's logistics and construction sectors fuels strong demand for robust engine and exhaust brakes in heavy-duty commercial vehicles. China's GB standards for heavy vehicles rigorously enforce the integration of effective auxiliary braking systems. Major manufacturing hubs like the Yangtze River Delta concentrate production and innovation for these critical vehicle components.
United States
Stringent safety mandates from the NHTSA under FMVSS compel the integration of advanced auxiliary braking, particularly in heavy-duty commercial trucks for long-haul transport. Fleet operators in regions like the Midwest and Pacific Northwest prioritize systems that reduce primary brake wear and enhance control on varied terrain. Research and development in autonomous vehicle braking systems is also prominent in technology clusters across California.
Germany
Germany's strong commercial vehicle manufacturing base and strict EU safety regulations drive demand for sophisticated pneumatic and electronic auxiliary braking systems. The KBA (Federal Motor Transport Authority) sets high performance standards for vehicle safety, influencing system design. Automotive engineering centers in Bavaria and Baden-Württemberg are at the forefront of developing integrated electronic braking solutions.
India
Modernizing India's aging commercial truck fleets creates a significant opportunity for cost-effective aftermarket exhaust and hydraulic brake systems. The Bureau of Indian Standards (BIS) continually updates vehicle safety norms, pushing for better braking performance in commercial vehicles. Manufacturing clusters in Maharashtra and Tamil Nadu are expanding production capacity for both OEM and aftermarket auxiliary brake components.
Brazil
Growth in Brazil's agricultural and mining sectors generates demand for heavy-duty commercial vehicles equipped with powerful auxiliary brakes to manage challenging terrains and loads. The country's national transportation authorities increasingly emphasize vehicle safety, impacting specifications for new truck models. Automotive production facilities in São Paulo and Minas Gerais are key centers for auxiliary brake system integration.
Global Automotive Auxiliary Brake Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, defining the competitive structure of the global automotive auxiliary brake market. This tiered landscape reflects the high capital intensity required for advanced R&D versus the agile specialization of niche players. Strategic partnerships and targeted portfolio diversification are common competitive moves among both large and specialized firms.
Integrated electronic system developers like Knorr-Bremse and Robert Bosch GmbH anchor the premium segment, leveraging extensive R&D infrastructure for advanced solutions. Specialists like SABO compete effectively by focusing on cost-effective mechanical and hydraulic solutions for specific aftermarket segments. Jacobs Vehicle Systems sustains its market position through specialized expertise in engine brake technology.
| Leading Market Players |
|---|
| Bendix |
| Wabco |
| Knorr-Bremse |
| Haldex |
| SABO |
| Jacobs Vehicle Systems |
| Robert Bosch GmbH |
| Continental AG |
| ZF Friedrichshafen AG |
| Others |
Cost & Logistics Intelligence
NHTSA's FMVSS and China's GB standards critically gate auxiliary brake supply qualification, simultaneously shaping price differentiation for compliant systems. This regulatory influence dictates both the technical specifications and the cost structures within the market.
Pricing Analysis
Long-term contract-based offtake agreements define pricing for OEM-integrated auxiliary brakes. Price differentiation stems from the specific certification level required (e.g., EU AEBS compliance) and the bundled after-sales service packages offered. Cost compression for mechanical systems is intensifying due to aftermarket price sensitivity, especially in developing markets. Small fleet operators exhibit the highest price sensitivity, while large commercial vehicle OEMs prioritize performance and compliance over lowest unit cost.
Supply Chain Analysis
Inventory management for complex electronic auxiliary braking systems requires precise lead-time forecasting. Geographic supply concentrates in Germany, China, and the United States, reflecting specialized manufacturing capabilities. The market draws from specialized alloys for friction materials, advanced electronic control units, and high-pressure pneumatic components. Single-source vulnerability for specific electronic components presents a structural supply chain risk. Distribution runs through direct OEM channels for new vehicles and independent aftermarket distributors for replacement parts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive auxiliary brake market exhibits a strong defensive moat, primarily due to regulatory entrenchment from stringent global safety standards like NHTSA's FMVSS.
For Market Incumbents:
Compound R&D investments in integrated electronic braking systems to maintain market leadership against emerging technology specialists. Leverage existing OEM relationships to co-develop next-generation software-defined braking solutions, mitigating the threat from new entrants focused solely on electrification. Deepen certification expertise across diverse global standards to create a barrier to entry for smaller players.
For New Entrants and Emerging Players:
Lead with cost-effective, easily integrable mechanical and hydraulic solutions for the underserved aftermarket in emerging economies. Target the light commercial vehicle electrification segment with scaled-down regenerative braking technologies, offering a pathway into the OEM supply chain. Develop localized distribution networks and service capabilities to address the specific needs of small fleet operators.
For Investors and Strategic Acquirers:
European Union AEBS mandates reshape the acquisition landscape, favoring firms with proven predictive braking software capabilities. The market offers long-term viability as a safety-critical component, underpinning vehicle operations for decades. Identify specialized software firms and advanced component manufacturers as prime acquisition targets. Watch for increasing ADAS integration rates across commercial vehicle platforms as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Reduces development costs and accelerates time-to-market for new auxiliary brake systems. |
| Software-Defined Vehicle Investment | Enables advanced safety features and predictive braking functions for autonomous vehicles. |
| Geographic Manufacturing Footprint | Mitigates supply chain risks and optimizes delivery costs for regional OEM assembly plants. |
| Aftermarket Channel Expansion | Captures a significant revenue stream from aging commercial fleets in developing regions. |
| Technology Licensing | Accelerates adoption of proprietary braking algorithms across diverse vehicle platforms. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with industry stakeholders and extensive secondary research. Primary research involved conversations with OEM engineers, fleet managers, Tier-1 procurement leads, and aftermarket distributors. This qualitative input was triangulated with quantitative data from secondary sources such as vehicle production databases, industry association reports, and regulatory filings to ensure robust insights.
The analytical framework projects market trajectories across the analysis window, modeling segmentation dimensions including technology, brake type, vehicle category, distribution channel, and regional regulatory frameworks. Compound annual growth rates were derived from historical data analysis and future market projections, incorporating key industry-specific forecast inputs like vehicle electrification rates and commercial truck production volumes over the projection horizon.
Forecasts assume regulatory continuity in United States, European Union, and China; material policy shifts would require re-modeling. These projections reflect the best available information and analytical assumptions, acknowledging potential risk factors such as sudden changes in vehicle safety mandates or raw material price volatility. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Motorcycle Catalyst Market
Automotive Parts
Global Automotive Plastics Market
Automotive Parts
Automotive Performance Parts Market
Automotive Parts
Motor Bearings Market
Automotive Parts
Small Engine Market
Automotive Parts
Center and Drag Link Market
Automotive Parts
China Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Hinges Market
Automotive Parts
Africa Passenger Vehicles Lubricants Market
Automotive Parts
Global Fuel and Oil Filters Market
Automotive Parts
Mexico Automotive Parts Aluminum Die Casting Market
Automotive Parts
Canada Automotive Parts Zinc Die Casting Market
Automotive Parts
Automotive Electric Drive Axle Market
Automotive Parts
North America Automotive Parts Aluminum Die Casting Market
Automotive Parts
Global Rubber Transmission Belts Market
Automotive Parts
Cam Trigger Kits Market