
 Europe Automotive Steering Sensor Market | 2026-2036
Europe Automotive Steering Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Automotive Steering Sensor Market Foresight
OEM procurement in the Europe Automotive Steering Sensor Market is consolidating around vertically integrated Tier-1 suppliers with full-system capabilities. Robert Bosch GmbH leverages its integrated manufacturing footprint across Germany and Hungary to dominate torque sensor supply for electric steering racks. Continental AG anchors its position through Hall-effect technology leadership and direct relationships with German premium vehicle assemblers. Sensata Technologies competes by specializing in high-temperature optical position sensors for motorsport-derived road car applications.
Automotive steering sensors measure angular position, rotational torque, and rack speed to enable precise electric power assistance and lane-keeping interventions, typically operating across temperature ranges from minus forty to one hundred twenty-five degrees Celsius with resolution below zero point one degrees. The devices translate mechanical steering input into electrical signals for ECU processing, forming the feedback loop essential for advanced driver assistance functionality. Torque sensors command the largest value share among product types because their strain-gauge or Hall-effect architectures determine steering feel calibration and safety-critical fail-operational performance. Hall-effect technology leads the technology dimension due to its contactless durability and immunity to electromagnetic interference in densely packaged engine bays, while capacitive sensing is gaining traction in cost-sensitive compact vehicle programs.
EU-type approval frameworks under UNECE regulations and the EU AI Act's risk-classification provisions for automated steering functions are tightening validation requirements for sensor redundancy and cybersecurity. EMA coordination with national type-approval authorities in Germany's KBA and France's ANSM-linked automotive divisions is harmonizing test protocols for steer-by-wire readiness. REACH compliance on rare-earth magnet content and the F-Gas Regulation's indirect pressure on thermal management materials are reshaping supplier qualification criteria. Stakeholders must monitor the transition from assisted to autonomous steering architectures where sensor fusion with lidar and camera systems redefines component specification and long-term sourcing commitments.
Market Dynamics
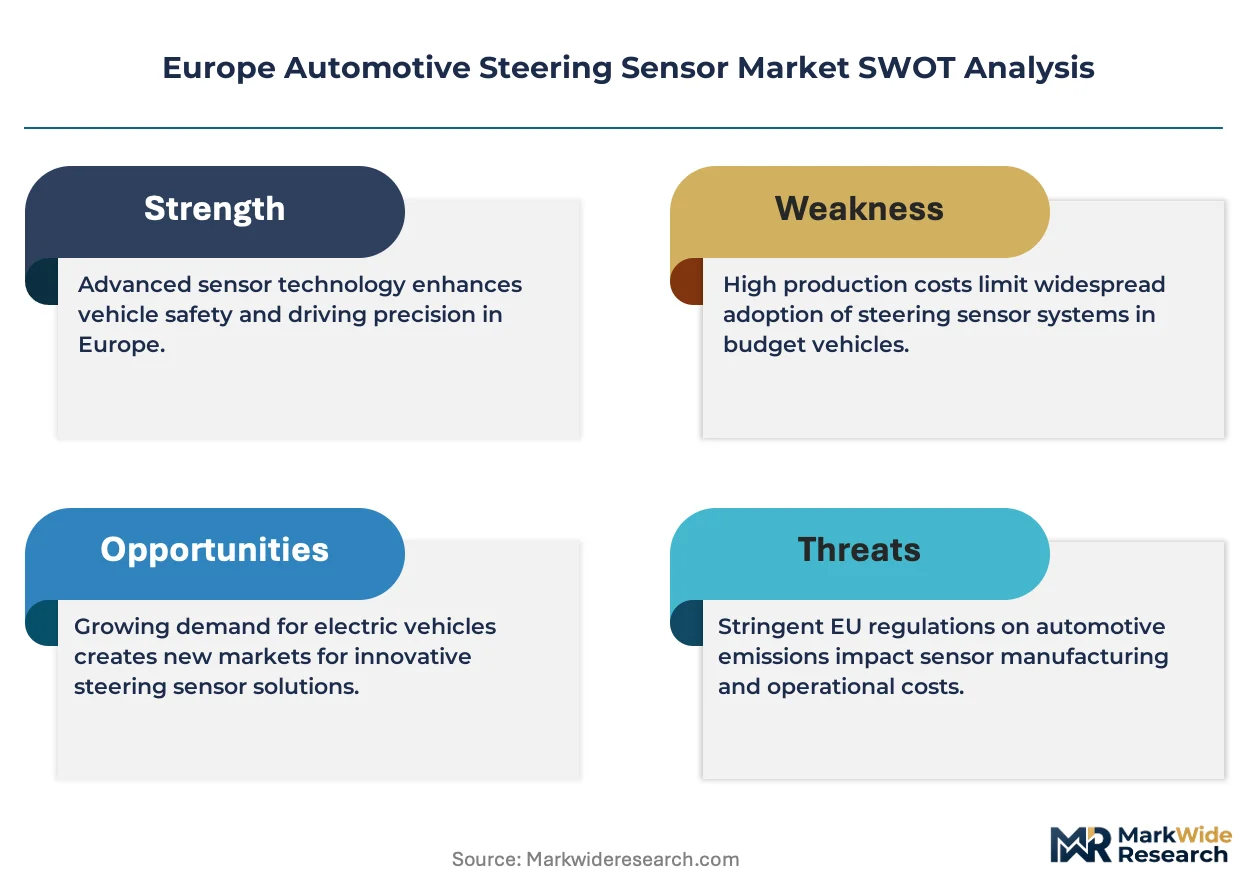
The EU Green Deal's fleet emission mandates are forcing automakers to accelerate steer-by-wire architectures, compressing supplier qualification timelines and demanding redundant sensor configurations that legacy torque-sensing architectures cannot satisfy.
Growth Catalysts
- EU Green Deal decarbonization targets:The 2035 internal combustion engine phase-out deadline is mandating full-electric powertrain conversions across German and French passenger vehicle lines, expanding addressable sensor volumes for rack-mounted torque modules.
- Hall-effect technology maturation:Contactless magnetic sensing architectures are eliminating mechanical wear points in steering columns, extending service intervals and reducing warranty exposure for Stellantis and Volkswagen Group platforms.
- Italy's motorsport-to-road technology transfer:Maranello and Modena engineering clusters are commercializing high-speed optical position sensors originally developed for Formula E applications into premium road car programs.
Market Restraints
- Rare-earth magnet supply concentration:Neodymium and dysprosium sourcing dependence on Chinese processing infrastructure exposes Hall-effect sensor manufacturers to input cost volatility and REACH compliance documentation gaps.
- Steer-by-wire validation timelines:UNECE R79 amendment processes and Germany's KBA type-approval protocols are extending development cycles to 48-60 months, freezing platform commitments and capital deployment.
- Strain-gauge torque sensor displacement:Magnetic sensing architectures are rendering conventional strain-gauge designs obsolete in new vehicle programs, stranding specialized production equipment and technical workforce competencies.
Strategic Opportunities
- Eastern European manufacturing localization:Hungary and Poland automotive clusters are attracting steering rack assembly investments from German Tier-1 suppliers, creating captive demand for proximity-sourced sensor modules.
- EU AI Act automated steering risk classification:The Act's Category 4 provisions for autonomous lane-keeping are mandating triple-redundant sensor architectures that double per-vehicle sensor content value.
- Capacitive sensing convergence with printed electronics:Roll-to-roll manufacturing integration is enabling cost-competitive compact vehicle programs in France and Spain to adopt position sensing previously restricted to premium segments.
Industry Challenges
- Functional safety engineer scarcity:ISO 26262 ASIL-D certification expertise is concentrated among German and Austrian engineering consultancies, creating recruitment bottlenecks for sensor validation teams.
- Cybersecurity integration complexity:UN R155 vehicle type approval requirements are forcing sensor firmware architectures to incorporate hardware security modules, adding 18-24 months to development schedules.
- Legacy CAN bus integration friction:Steer-by-wire sensor outputs must bridge to existing vehicle network protocols, requiring gateway electronics that consume packaging space and thermal budget in compact engine bays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Automotive Steering Sensor Market |
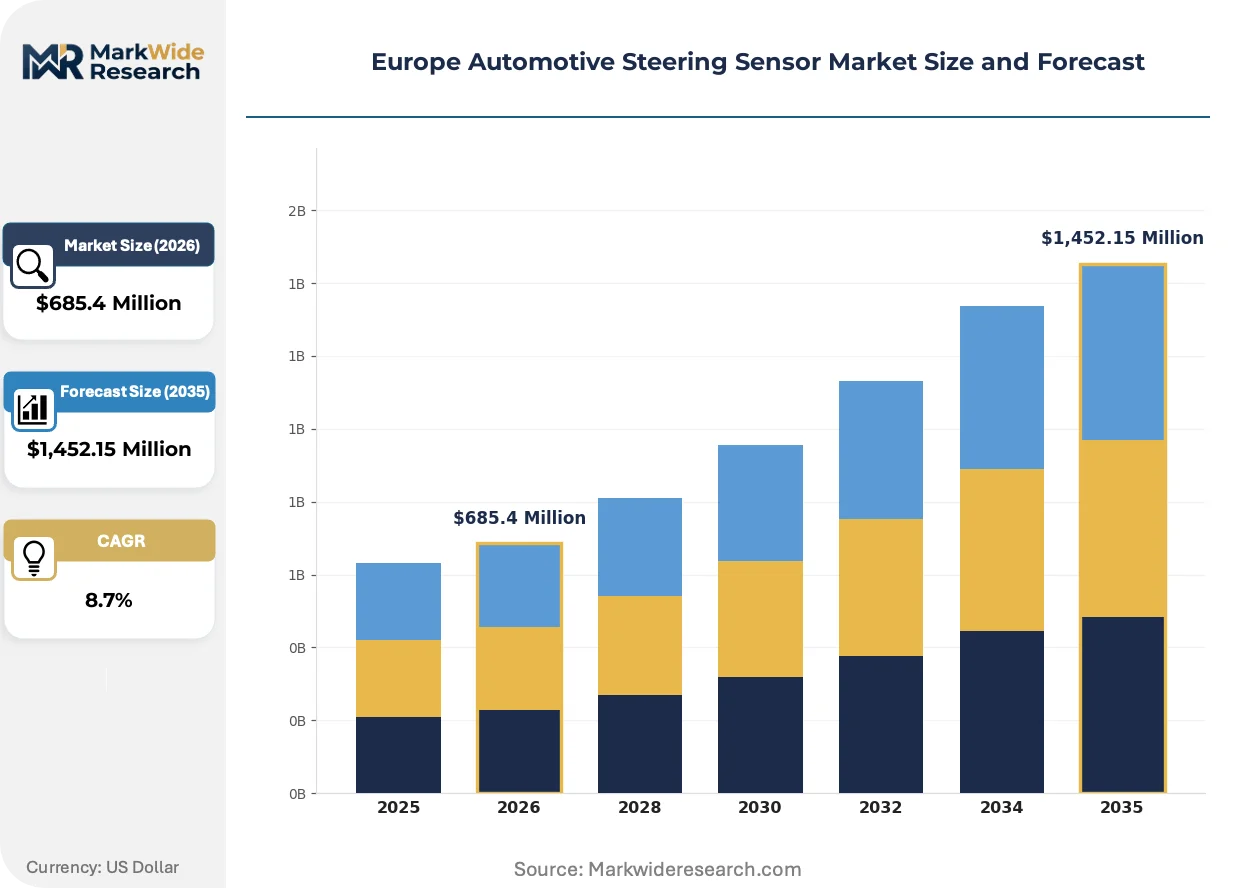
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,452.15 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
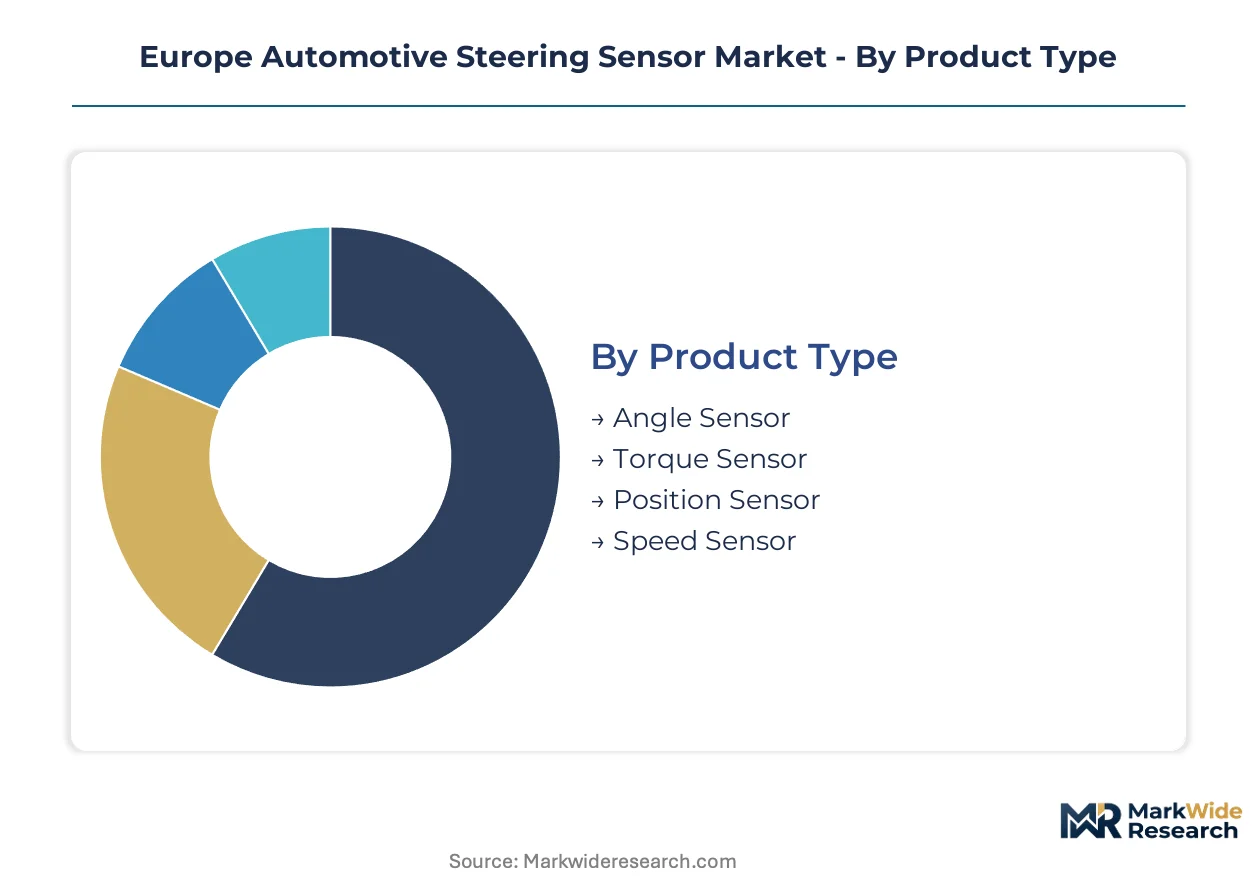
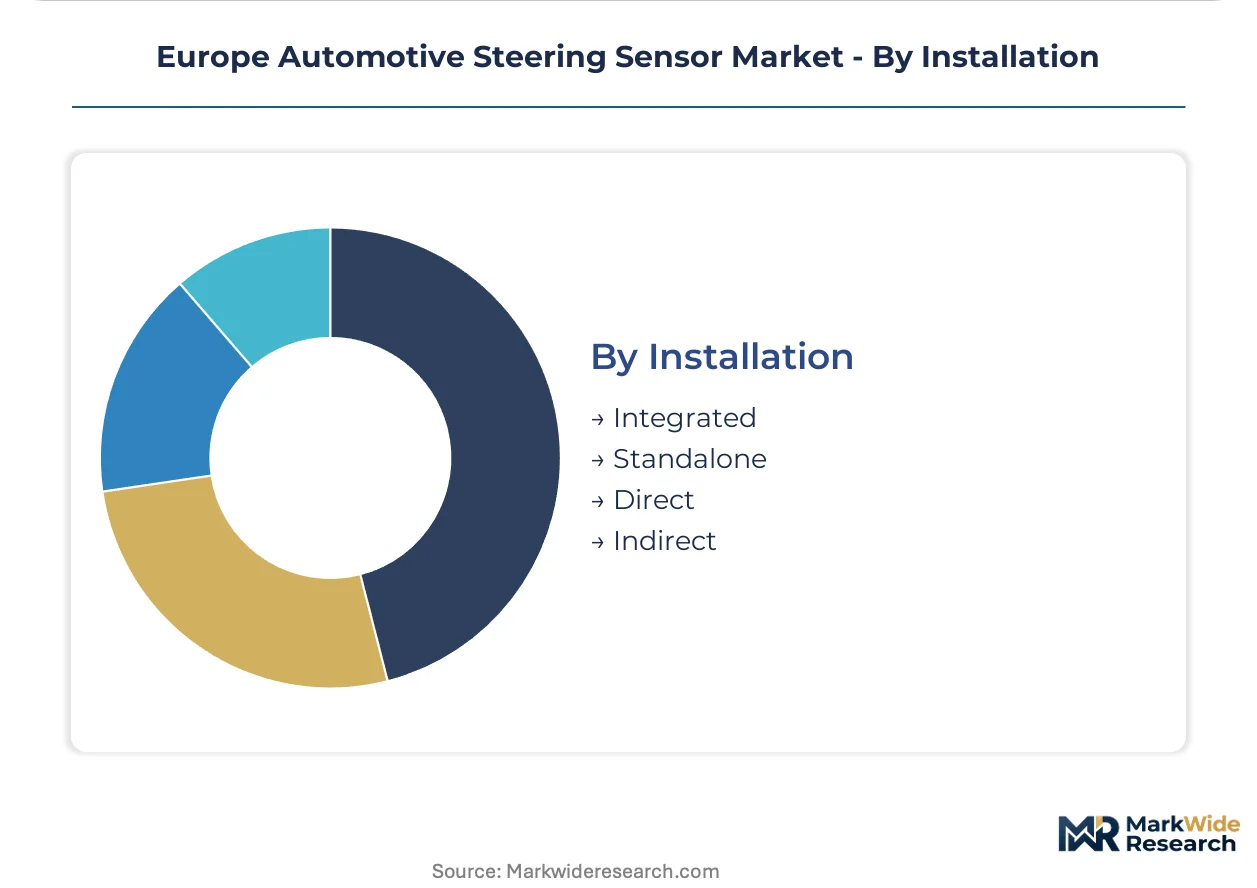
| Segmentation | Product Type: Angle Sensor, Torque Sensor, Position Sensor, Speed Sensor Technology: Electromagnetic, Optical, Capacitive, Hall Effect End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Installation: Integrated, Standalone, Direct, Indirect |
| Companies Covered | Robert Bosch GmbH, Continental AG, DENSO Corporation, Valeo SA, HELLA GmbH & Co. KgaA, Infineon Technologies, NXP Semiconductors, Sensata Technologies, TE Connectivity, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Automotive Steering Sensor Market Shifts & Advancements
Steering sensor architectures are converging with autonomous driving compute stacks, eliminating discrete component boundaries and forcing suppliers to reposition as software-integrated system providers rather than discrete hardware vendors.
Inductive position sensing is rewriting steering column packaging constraints by eliminating magnet-based drift compensation circuits. BMW and Mercedes-Benz are adopting this architecture for their 2026 platform generations, compressing sensor module height by 40 percent and enabling dashboard designs previously blocked by steering shaft intrusion. The technology is rewriting supplier competitive boundaries by rewarding coil-winding precision capabilities over magnetic material science expertise.
The EU AI Act's risk-based classification for automated steering functions is mandating deterministic sensor response times below 10 milliseconds. France's ANSM-linked automotive divisions are harmonizing test protocols with Germany's KBA, creating a unified validation pathway that reduces duplicate certification costs for suppliers serving both markets. Premium vehicle assemblers are responding by pre-qualifying dual-source sensor configurations to mitigate single-supplier dependency exposure.
Automaker technical sourcing teams are consolidating steering sensor procurement under full-system rack contracts rather than discrete component purchases. Tier-1 suppliers with captive torque and position sensing capabilities are displacing standalone sensor specialists in Volkswagen Group and Stellantis RFQ processes, compressing the viable vendor base to vertically integrated chassis system houses. This concentration is most visible in German premium segments where platform sharing across Audi, Porsche, and Bentley demands unified steering feel calibration.
Europe Automotive Steering Sensor Market Segmentation
Steering sensor procurement in Europe is fragmenting across multiple technical and commercial dimensions, forcing suppliers to align R&D roadmaps with divergent OEM integration strategies and aftermarket replacement cycles. Platform-specific sensor configurations now determine supplier selection criteria more than standalone component specifications.
Product Type:
Upgrade cycles from hydraulic to electric power steering are reordering product mix priorities across German and French vehicle programs.
- Torque Sensor:Strain-gauge and Hall-effect architectures measure torsional deflection in steering columns to enable precise power assistance calibration. German premium OEMs specify redundant dual-sensor configurations for steer-by-wire readiness. Torque sensors sit at the top of the volume ranking, with angle sensors climbing the fastest.
- Angle Sensor:Rotary encoders track steering wheel position with sub-degree resolution for lane-keeping and stability control integration. Italian sports car manufacturers source high-speed optical variants from Modena engineering clusters.
- Position Sensor:Rack-mounted linear position devices monitor steering rack travel for variable-ratio steering systems. French compact vehicle programs favor capacitive alternatives to reduce magnet content.
- Speed Sensor:Rotational velocity measurement supports adaptive steering rate damping in urban maneuvering modes. Polish aftermarket distributors stock universal-fit speed sensor modules for Eastern European vehicle parc.
Component value concentrates in torque and angle sensing functions, with rack position measurement gaining specification share in steer-by-wire architectures.
Technology:
Cost tier differentiation between premium and mass-market vehicle lines is hardening around sensing technology selection.
- Hall Effect:Contactless magnetic field detection eliminates mechanical wear and delivers ASIL-D compliant outputs for safety-critical steering functions. Robert Bosch GmbH dominates supply to Volkswagen Group platforms through integrated German-Hungarian manufacturing.
- Optical:LED-photodiode pairs encode position through coded disc interruption, achieving microsecond response times for motorsport-derived road applications. Maranello engineering suppliers commercialize Formula E-derived variants for Ferrari and Maserati programs.
- Electromagnetic:Inductive coil architectures are displacing magnet-based designs in BMW and Mercedes-Benz 2026 platform generations, compressing module height by forty percent.
- Capacitive:Electric field variation sensing enables printed electronics integration for cost-sensitive compact vehicle programs in Spain and France.
Hall-effect technology commands the specification majority, though inductive sensing is expanding most quickly in premium German segments.
End User:
Customer-type procurement concentration is consolidating around full-system suppliers with captive sensing capabilities.
- OEMs:Volkswagen Group, Stellantis, and BMW specify steering sensors exclusively through rack-assembly Tier-1 contracts, eliminating discrete component purchasing channels.
- Tier-1 Suppliers:Continental AG and ZF Friedrichshafen integrate captive torque and position sensing into complete electric steering rack modules for direct OEM supply.
- Vehicle Assemblers:Contract manufacturers in Hungary and Slovakia source pre-calibrated sensor modules from proximity-located Tier-1 facilities to minimize logistics complexity.
- Aftermarket Providers:Independent distributors in Poland and Czech Republic serve aging vehicle parc with replacement angle and torque sensors for legacy hydraulic steering conversions.
Tier-1 integrated supply captures the value concentration, with aftermarket channels expanding most quickly in Eastern European markets.
Installation:
Integration depth with steering rack assemblies is determining supplier competitive boundaries across European production clusters.
- Integrated:Torque and position sensors embedded within steering rack housings during Tier-1 assembly dominate new vehicle specification. German premium platforms mandate sealed integrated modules for warranty compliance.
- Standalone:Discrete column-mounted sensors persist in aftermarket replacement and legacy platform continuity programs. French independent garages favor standalone units for repair simplicity.
- Direct:Mechanical coupling to steering shafts without intermediate linkages characterizes current electric power steering architectures. KBA type-approval protocols validate direct installation for EU market entry.
- Indirect:Decoupled steer-by-wire configurations with no mechanical column connection are awaiting UNECE R79 amendment ratification before series deployment.
Integrated installation dominates volume, with direct mounting configurations gaining share fastest as steer-by-wire approaches commercialization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands greater steering sensor procurement volume than France, though Italian engineering clusters are commercializing motorsport-derived optical sensing faster than either neighbor.
Germany
Volkswagen Group and BMW specifications for steer-by-wire readiness are driving dual-redundant torque sensor demand. Germany's KBA type-approval protocols under UNECE R79 amendments are extending validation cycles to 48-60 months. Stuttgart and Munich engineering centers are concentrating Hall-effect sensor R&D for 2026 platform generations.
France
Stellantis electric power steering conversions for compact vehicle lines are expanding capacitive sensing procurement. ANSM-linked automotive divisions are harmonizing test protocols with German KBA standards. Auvergne-Rhône-Alpes manufacturing corridors are attracting printed electronics integration for cost-sensitive sensor modules.
Italy
Ferrari and Maserati programs are sourcing high-speed optical position sensors for premium road car applications. EU Green Deal fleet emission mandates are accelerating full-electric powertrain sensor specifications. Maranello and Modena engineering clusters are commercializing Formula E-derived sensing architectures.
Hungary
German Tier-1 suppliers are localizing steering rack assembly investments to serve proximity demand. REACH compliance documentation requirements are reshaping supplier qualification criteria for rare-earth magnet content. Győr and Budapest automotive clusters are capturing captive sensor module sourcing from integrated chassis system houses.
Poland
Aging vehicle parc replacement cycles are expanding aftermarket angle and torque sensor distribution. F-Gas Regulation pressures on thermal management materials are altering component specifications. Warsaw and Kraków independent distributors are stocking universal-fit speed sensor modules for Eastern European repair channels.
Europe Automotive Steering Sensor Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the European steering sensor value chain. The vendor base concentrates around vertically integrated Tier-1 chassis system suppliers with captive sensing capabilities. Three strategic archetypes dominate: full-system rack integrators, discrete sensor specialists, and semiconductor component suppliers. Competitive dynamics revolve around M&A consolidation for technology access and strategic partnerships for steer-by-wire validation timelines.
Within the integrated-system tier, Robert Bosch GmbH and Continental AG exemplify the vertically integrated model that is displacing standalone component vendors in OEM procurement processes. Sensata Technologies occupies a specialist position in high-temperature optical sensing applications. These three entities anchor the competitive structure that is compressing the viable supplier base to full-system providers as automakers consolidate steering sensor procurement under rack-assembly contracts.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| DENSO Corporation |
| Valeo SA |
| HELLA GmbH & Co. KgaA |
| Infineon Technologies |
| NXP Semiconductors |
| Sensata Technologies |
| TE Connectivity |
| Others |
Supply & Pricing Matrix
Dual-redundant torque sensor configurations for steer-by-wire readiness create a sharp bifurcation between ASIL-D certified premium tiers and cost-optimized compact vehicle programs, with this divergence manifesting in both component pricing spreads and the geographic clustering of qualified manufacturing capacity. German Tier-1 suppliers command pricing premiums through captive Hall-effect sensor production, while Eastern European assembly localization compresses logistics-adjusted costs for volume programs.
Pricing Analysis
Capacity additions in Hungary and Poland are reshaping price floors for rack-integrated sensor modules as German Tier-1 suppliers localize assembly operations. Three-tier pricing structure across premium, standard, and economy levels reflects ASIL-D certification grade and magnet content compliance documentation. Pricing pressure stems from rare-earth magnet cost volatility and REACH compliance overhead, with French compact vehicle programs exhibiting highest price sensitivity and German premium OEMs showing least elasticity due to steer-by-wire pre-qualification requirements.
Supply Chain Analysis
Reverse-logistics flows for remanufactured torque sensors are expanding through Polish aftermarket distributors serving aging Eastern European vehicle parc. Manufacturing concentration centers on Germany, Hungary, and China, with Hall-effect architectures drawing from neodymium and dysprosium processing infrastructure. Single-source vulnerability in rare-earth magnet supply exposes sensor manufacturers to input cost spikes. Distribution runs through vertically integrated Tier-1 rack assembly contracts rather than discrete component channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in Europe's automotive steering sensor market rests on the shift toward triple-redundant architectures mandated by EU AI Act Category 4 provisions, compressing per-vehicle sensor content value upward while strain-gauge displacement eliminates legacy cost structures.
For Market Incumbents: Deepen backward integration into Hall-effect magnet supply through qualified rare-earth sourcing partnerships in Hungary, while accelerating ASIL-D certification pipelines to defend against inductive sensing substitution by BMW and Mercedes-Benz platform engineers. Lock in long-term rack-assembly contracts with Stellantis and Volkswagen Group before UNECE R79 amendments finalize steer-by-wire validation timelines.
For New Entrants and Emerging Players: Direct-to-Tier-2 digital procurement platforms offer white-space access to standalone angle sensor replacement demand in Poland and Czech Republic aftermarket channels, bypassing incumbent-dominated OEM rack contracts. Target capacitive sensing modules for French and Spanish compact vehicle programs where printed electronics integration lowers capital barriers to entry.
For Investors and Strategic Acquirers: Consolidation pressure builds where ISO 26262 functional safety expertise concentrates among German and Austrian engineering consultancies, creating acquisition targets for sensor validation capabilities. Five-to-ten year viability favors specialists with steer-by-wire firmware integration competencies over discrete hardware vendors. Monitor UNECE R79 ratification progress as inflection signal for indirect installation architecture commercialization.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Volkswagen Group unified steering feel calibration across Audi, Porsche, and Bentley compresses supplier qualification overhead. |
| Battery Supply Agreement | Electric powertrain conversions mandate torque sensor volume commitments aligned with cell production ramp schedules. |
| Software-Defined Vehicle Investment | Sensor fusion with lidar and camera systems redefines firmware architecture specifications for autonomous steering. |
| Geographic Manufacturing Footprint | Hungarian and Polish cluster proximity reduces logistics complexity for German Tier-1 rack assembly operations. |
| Charging Infrastructure Partnership | EU Green Deal fleet emission mandates accelerate full-electric powertrain sensor demand across passenger vehicle lines. |
Research Methodology
Bottom-up electric power steering platform modeling reconciled against top-down Hall-effect sensor production tracking forms the analytical core of this study. Primary interviews with Tier-1 supplier procurement officers, OEM platform engineers, aftermarket distributors in Poland and Czech Republic, and KBA type-approval specialists combined with secondary validation from UNECE R79 amendment documentation, REACH compliance filings, EU AI Act risk classification guidance, vehicle production databases, and IHS Markit registration data. Triangulation across stakeholder inputs and regulatory sources ensures cross-verified demand and supply estimates.
Input-output matrices mapping steering rack assembly volumes to per-vehicle sensor content values generate volume and value outputs across the projection horizon. Segmentation dimensions modeled include propulsion architecture, vehicle class, ASIL-D certification tier, technology type, and regional production cluster. CAGRs derive from regression analysis of historical platform penetration rates and regulatory mandate acceleration curves, incorporating rare-earth magnet price indices and steer-by-wire readiness timelines as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for inductive position sensing would alter the outlook if BMW and Mercedes-Benz 2026 platform generations accelerate displacement of Hall-effect architectures. Forecasts reflect documented assumptions on UNECE R79 ratification timing and EU AI Act enforcement sequencing. Practitioners should monitor KBA-ANSM test protocol harmonization progress and F-Gas Regulation thermal management material restrictions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
Mexico Automotive Electric Actuators Market
Automotive Electrical & Electronics
Europe Automotive Tpms Market
Automotive Electrical & Electronics
Europe Automotive Camera Market
Automotive Electrical & Electronics
Commercial Vehicle Switches and Relays Market
Automotive Electrical & Electronics
Steering Wheel Switches Market
Automotive Electrical & Electronics
Europe Automotive Pressure Sensor Market
Automotive Electrical & Electronics
US Automotive EPS Market
Automotive Electrical & Electronics
Car Satellite Antenna Market
Automotive Electrical & Electronics
Automotive Airbag Electronic Control Unit Market
Automotive Electrical & Electronics
EPS Motors Market
Automotive Electrical & Electronics
Bicycle Electronic Drivetrain Market
Automotive Electrical & Electronics
Automotive Temperature and Humidity Sensors Market
Automotive Electrical & Electronics
New Energy Automotive Antenna Module Market
Automotive Electrical & Electronics
Automotive Esim Market
Automotive Electrical & Electronics
Stair Lift Motors Market
Automotive Electrical & Electronics
Brazil Automotive EPS Market