
 Asia Pacific Automotive Camera Market | 2026-2036
Asia Pacific Automotive Camera Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Automotive Camera Market Analysis
Capital-intensity divergence between integrated sensor suppliers and assembly-focused tier ones is bifurcating competitive returns across the Asia Pacific Automotive Camera Market. Continental AG leverages captive semiconductor partnerships to secure wafer allocation during supply crunches. Denso Corporation anchors its position through in-house CMOS design capabilities that reduce dependency on external foundries. Sony Corporation dominates image sensor supply to Japanese and Korean OEM programs, while Robert Bosch GmbH competes on system-level integration across multiple vehicle platforms.
Asia Pacific automotive cameras are electro-optical devices combining solid-state image sensors, precision optics, and embedded signal processors to capture real-time visual data for driver assistance and vehicle automation systems. These units typically operate across temperature ranges from minus forty to eighty-five degrees Celsius with IP6K9K sealing for underhood and exterior mounting. Front View and Surround View applications command the largest revenue pools as OEMs bundle multi-camera packages into premium and mid-tier electric vehicle trims. CMOS technology leads unit shipments due to lower power draw and on-chip integration advantages over legacy CCD architectures, while 360-Degree systems represent the fastest-expanding technology segment as parking assistance and low-speed maneuvering automation proliferate.
Japan's METI enforces functional safety standards aligned with ISO 26262 that govern camera system validation for domestic vehicle platforms. China's SAMR and MIIT coordinate GB standard updates mandating rear-view visibility and advancing autonomous driving test requirements that expand camera counts per vehicle. South Korea's MFDS and KATRI administer component reliability certifications that shape supplier qualification timelines. Stakeholders must monitor how divergent national homologation timelines affect platform commonality strategies across the region.
Market Dynamics
CMOS sensor supply concentration across South Korean and Taiwanese foundries is compressing tier-one camera module margins while elevating bargaining power for integrated semiconductor suppliers.
Growth Catalysts
- MIIT autonomous driving test mandates:China's expanding GB standard requirements for camera-equipped intelligent vehicles are accelerating multi-sensor platform rollouts across domestic EV lineups.
- Electric vehicle platform proliferation:Battery-electric architectures in Japan and South Korea are standardizing surround-view camera packages as baseline safety equipment rather than premium options.
- ISO 26262 functional safety adoption:METI-aligned validation protocols are forcing camera system upgrades that drive replacement cycles and qualification premiums for certified suppliers.
Market Restraints
- Wafer allocation bottlenecks:Concentrated CMOS fabrication capacity in Hsinchu and Pyeongtaek creates procurement vulnerability during semiconductor demand surges.
- Homologation fragmentation:Divergent SAMR, METI, and MFDS certification timelines force platform-specific engineering that erodes scale economies.
- Lidar cost compression:Advancing solid-state ranging sensors threaten camera-centric perception stacks in premium automation segments.
Strategic Opportunities
- Thailand and Indonesia assembly expansion:Japanese and Korean OEMs are localizing camera module production in ASEAN manufacturing corridors to capture regional EV incentives.
- In-cabin monitoring mandates:Driver distraction detection requirements emerging from KATRI and Chinese standard bodies are opening interior camera applications.
- 4D imaging radar fusion:Convergence of high-resolution cameras with radar processing is creating new perception-tier supplier roles.
Industry Challenges
- Automotive-grade ISP design talent:Shortage of signal processing engineers with ISO 26262 exposure is extending development timelines for tier-two entrants.
- IP6K9K thermal validation:Extended certification cycles for extreme-temperature sealing are delaying product launches by 8-14 months.
- Legacy CAN bus integration:Backward compatibility requirements with existing vehicle networks are constraining bandwidth for high-resolution camera streams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Automotive Camera Market |
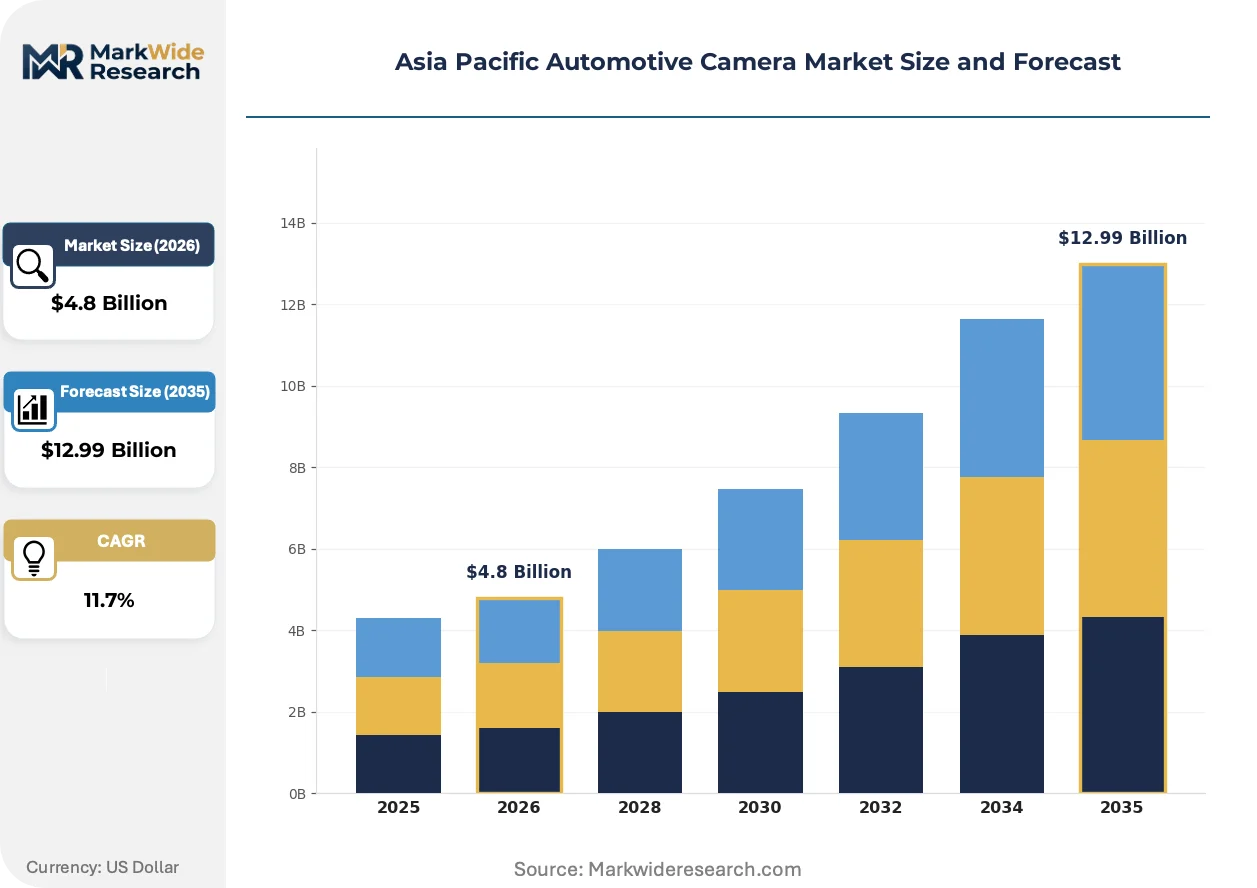
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Front View, Rear View, Surround View, Dash Camera Technology: CCD, CMOS, Infrared, 360-Degree Application: Passenger Vehicles, Commercial Vehicles, Electric Vehicles, Autonomous Vehicles Distribution Channel: OEMs, Aftermarket, E-Commerce, Retail |
| Companies Covered | Continental AG, Denso Corporation, Autoliv Inc, Robert Bosch GmbH, Panasonic Corporation, Valeo S.A., Sony Corporation, Magna International Inc., Aptiv PLC, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Automotive Camera Market Emerging Trajectories
Resolution escalation and edge-processing integration are fragmenting supplier tiers while regulatory mandates force faster validation cycles across Asia Pacific automotive programs.
8-megapixel front-facing cameras with embedded neural accelerators are bifurcating the supplier base. Premium EV platforms from Korean and Japanese OEMs are adopting these units for highway pilot functions. The technology is bifurcating competitive returns between integrated sensor designers and assembly-dependent module houses.
METI's alignment with ISO 26262 ASIL-B requirements is tightening validation protocols for camera systems deployed on domestic vehicle platforms. Suppliers must now submit fault-injection test documentation that extends qualification timelines. Japanese OEMs are responding by consolidating supplier panels to reduce re-certification overhead.
Fleet operators in China are demanding camera-system lifecycle data packages that unbundle hardware from predictive maintenance analytics. This consumption-pattern shift is compressing traditional tier-one service margins. The restructuring is most visible in Shenzhen and Shanghai commercial EV deployments where uptime guarantees dominate procurement criteria.
Asia Pacific Automotive Camera Market Segmentation
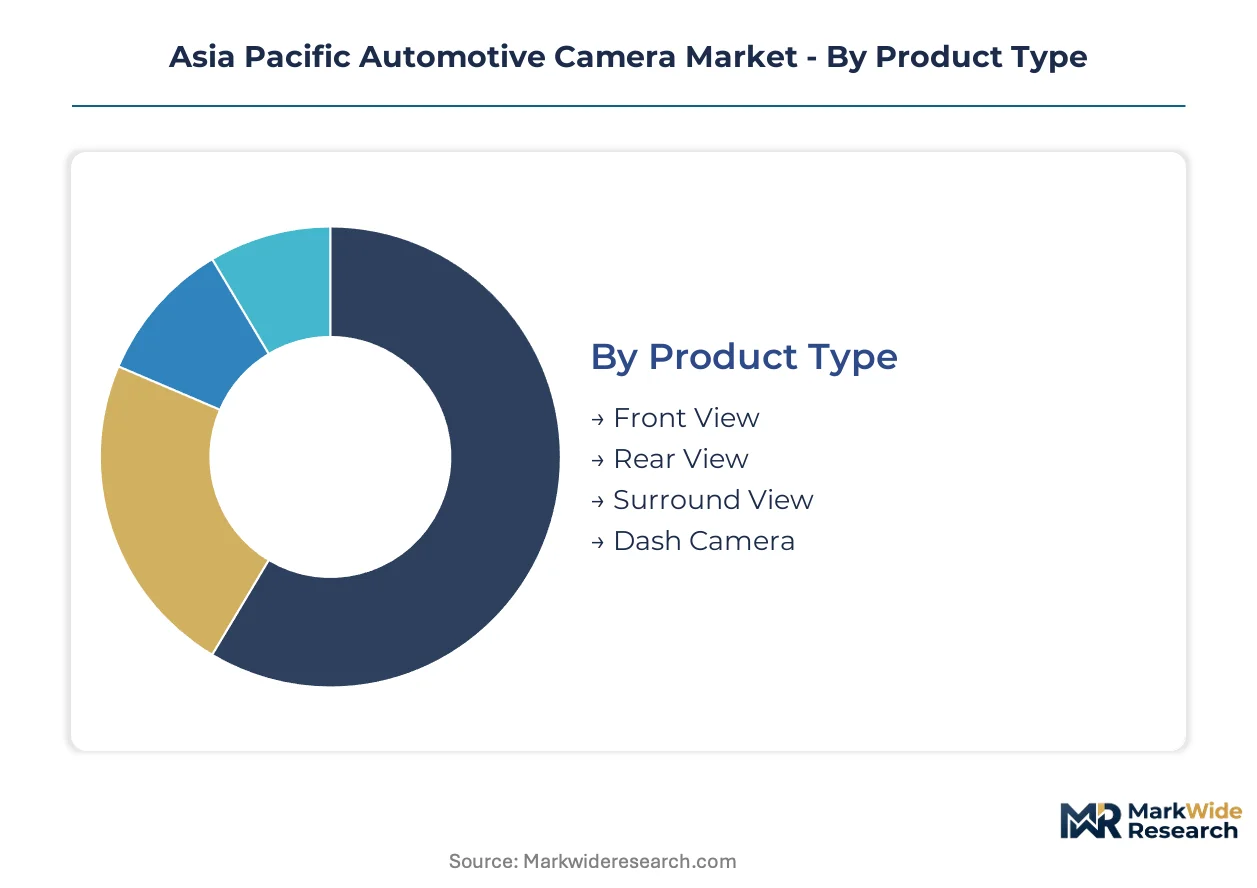
Camera module profitability varies sharply across mounting positions and sensor architectures. Suppliers must align R&D allocation with where OEMs are consolidating procurement volumes and where regulatory mandates are expanding minimum camera counts per vehicle platform.
Product Type:
Margin pools concentrate in multi-camera surround configurations that bundle four to six units per premium electric vehicle platform.
- Front View:Single-lane departure and collision avoidance units with 2-8 megapixel resolution. Chinese and Korean OEMs are standardizing these on mid-tier EVs as baseline ADAS equipment under tightening GB standard requirements.
- Surround View:Four-camera synthesis systems generating stitched bird's-eye imagery for parking automation. Japanese OEMs bundle these into battery-electric platforms as standard safety equipment rather than premium options, expanding unit volumes per vehicle.
- Rear View:Backup visibility units mandated under visibility regulations across multiple national markets.
- Dash Camera:Windshield-mounted recording devices serving insurance and fleet liability applications.
Surround View holds installed capacity. Front View is rotating up the share rankings.
Technology:
Cost structures diverge between mature CMOS architectures and emerging 360-degree processing requirements.
- CMOS:Dominant solid-state imaging technology with on-chip integration advantages and lower power draw than legacy alternatives. South Korean and Taiwanese foundries anchor wafer supply for automotive-grade variants, creating procurement leverage for integrated sensor suppliers.
- 360-Degree:Multi-sensor fusion systems combining four or more camera feeds into unified environmental models. Parking assistance and low-speed maneuvering automation are driving fastest adoption across premium EV lineups in Japan and South Korea.
- CCD:Legacy charge-coupled device technology with higher power consumption and limited new design wins.
- Infrared:Thermal imaging sensors for night vision and pedestrian detection in low-light conditions.
CMOS maintains volume leadership. 360-Degree is climbing the fastest as OEMs expand parking automation bundles.
Application:
Procurement concentration follows electric vehicle platform rollouts where camera counts per vehicle exceed internal combustion equivalents.
- Electric Vehicles:Battery-electric architectures standardizing surround-view packages and front-facing ADAS units as baseline equipment. Chinese OEMs lead multi-sensor integration under MIIT autonomous driving test mandates that expand camera requirements for intelligent vehicle certification.
- Passenger Vehicles:Traditional internal combustion and hybrid platforms with camera adoption driven by safety ratings and insurance incentives.
- Commercial Vehicles:Fleet operators in China demand lifecycle data packages that unbundle hardware from predictive maintenance analytics.
- Autonomous Vehicles:Robotaxi and shuttle programs requiring redundant camera arrays for perception stack validation.
Electric Vehicles command supplier attention. Commercial Vehicles is gaining share through fleet digitization requirements.
Distribution Channel:
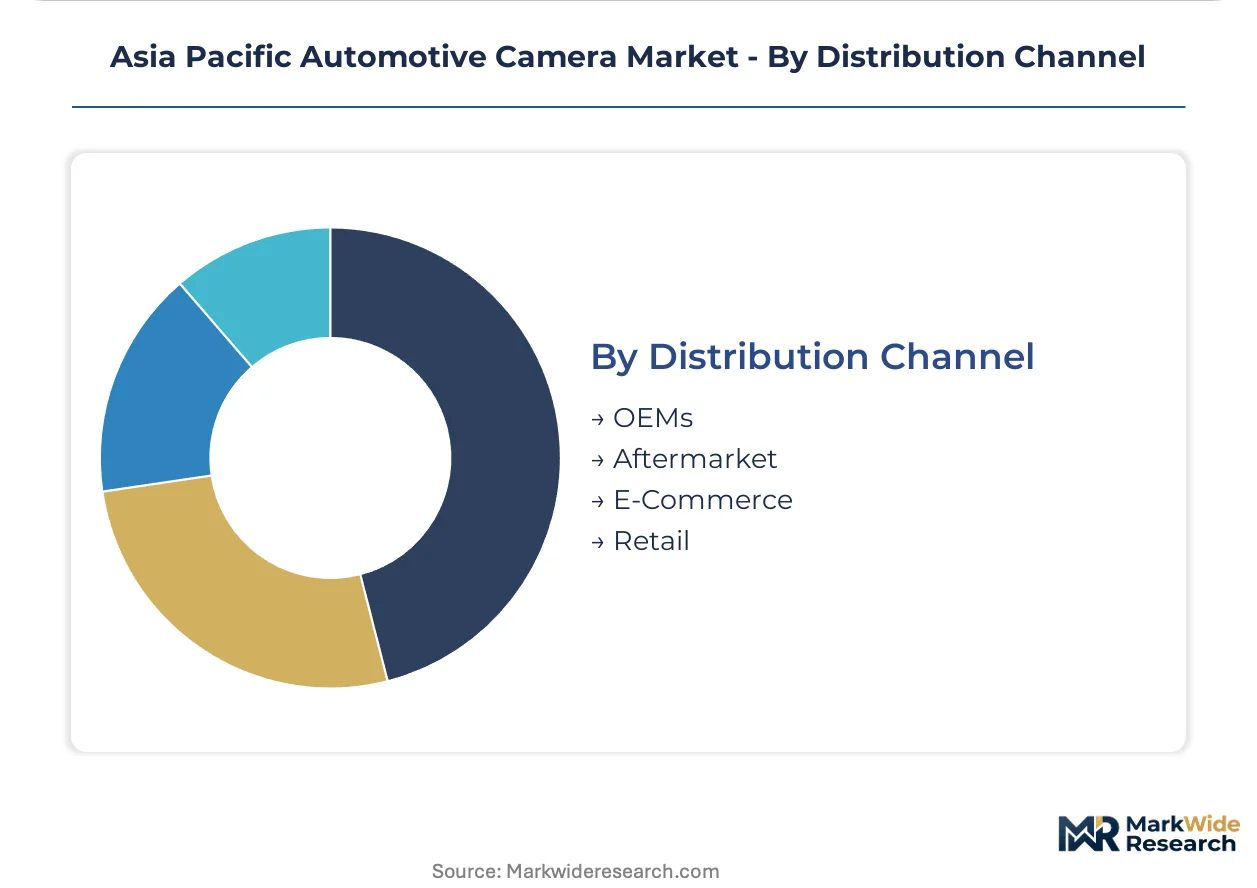
Channel economics favor direct OEM supply relationships with multi-year platform commitments over fragmented aftermarket transactions.
- OEMs:Direct procurement by vehicle manufacturers for factory installation. Japanese and Korean OEMs are consolidating supplier panels to reduce ISO 26262 re-certification overhead, favoring established tier-one relationships.
- Aftermarket:Post-sale installation through service networks and independent shops.
- E-Commerce:Direct-to-consumer and fleet procurement through digital platforms.
- Retail:Big-box and automotive specialty store distribution for consumer dash camera and upgrade markets.
OEMs anchor revenue stability. E-Commerce is expanding fastest in fleet and commercial segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in South Korean and Taiwanese semiconductor corridors while Japanese tier-one assemblers absorb margin compression from concentrated CMOS supply. This asymmetry shapes procurement strategies across the region's electric vehicle platforms.
China
MIIT autonomous driving test mandates are expanding camera counts per vehicle for intelligent vehicle certification. SAMR coordinates GB standard updates that mandate rear-view visibility and advance multi-sensor requirements. Shenzhen and Shanghai commercial EV fleets are driving demand for lifecycle data packages that unbundle hardware from predictive maintenance analytics.
Japan
METI enforces ISO 26262-aligned functional safety standards that govern camera system validation for domestic platforms. Japanese OEMs are consolidating supplier panels to reduce re-certification overhead. The Kanto region around Tokyo anchors premium EV platform development where surround-view cameras are standardizing as baseline safety equipment.
South Korea
MFDS and KATRI administer component reliability certifications that shape supplier qualification timelines for camera modules. Korean OEMs are standardizing 8-megapixel front-facing cameras with embedded neural accelerators for highway pilot functions. Pyeongtaek's foundry concentration creates procurement leverage for integrated semiconductor suppliers over assembly-focused tier ones.
Taiwan
Hsinchu's semiconductor fab cluster anchors wafer supply for automotive-grade CMOS variants, elevating bargaining power for sensor designers. The island's foundry capacity concentration compresses tier-one camera module margins during demand surges. Tainan and Taichung are expanding backend packaging capacity for automotive imaging chips serving regional EV programs.
Thailand
Japanese and Korean OEMs are localizing camera module production in ASEAN manufacturing corridors to capture regional EV incentives. The country's Board of Investment offers tax privileges for automotive electronics assembly. The Eastern Economic Corridor is attracting tier-one suppliers establishing regional hub operations for Southeast Asian EV platforms.
Asia Pacific Automotive Camera Market Vendor Landscape
Concentration sits with integrated semiconductor suppliers who control wafer allocation during supply crunches, while assembly-focused tier ones face margin compression from concentrated foundry supply. The vendor base spans three strategic archetypes: captive semiconductor designers with in-house CMOS capabilities, system integrators competing on multi-platform deployment, and sensor specialists dominating image component supply. Dominant competitive moves include strategic partnerships securing wafer allocation and geographic expansion into ASEAN manufacturing corridors capturing regional EV incentives.
Within the integrated tier, Continental AG and Denso Corporation exemplify divergent approaches to supply security—one leveraging captive semiconductor partnerships, the other anchoring position through in-house design capabilities reducing external foundry dependency. Robert Bosch GmbH occupies a system-integration position competing across multiple vehicle platforms. Sony Corporation sits within the sensor-specialist archetype dominating image component supply to Japanese and Korean OEM programs.
| Leading Market Players |
|---|
| Continental AG |
| Denso Corporation |
| Autoliv Inc |
| Robert Bosch GmbH |
| Panasonic Corporation |
| Valeo S.A. |
| Sony Corporation |
| Magna International Inc. |
| Aptiv PLC |
| Others |
Supply Flow & Price Mechanics
Fourteen-to-eighteen-week lead times for automotive-grade CMOS wafers concentrate pricing power in South Korean and Taiwanese foundries while compressing margins for assembly-dependent tier-one suppliers across the Asia Pacific Automotive Camera Market. This inventory-to-delivery lag anchors cost structures for camera modules destined for Japanese and Korean EV platforms.
Pricing Analysis
The customization-premium spread widens sharply between ISO 26262 ASIL-B certified camera systems and standard-grade alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale, with Japanese OEMs paying qualification premiums for METI-aligned validation documentation. Cost compression in mid-tier surround-view modules is intensifying because Chinese OEMs are consolidating procurement panels under MIIT autonomous driving mandates. Fleet operators in Shenzhen commercial EV deployments exhibit highest price sensitivity, while premium Japanese EV platforms show lowest sensitivity due to safety-equipment bundling requirements.
Supply Chain Analysis
Strait of Malacca transit underwrites raw material flows for precision optics glass and rare-earth phosphors feeding Taiwanese and South Korean sensor fabrication. Wafer supply concentrates in Hsinchu and Pyeongtaek, with backend packaging anchored in Tainan and Taichung expanding capacity for regional EV programs. Automotive camera production draws from silicon ingots, specialized optical glass, and electromagnetic shielding materials. Single-source vulnerability sits with concentrated CMOS foundry capacity during semiconductor demand surges. Distribution runs through direct OEM supply relationships with multi-year platform commitments rather than fragmented aftermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Shortage of signal processing engineers with ISO 26262 exposure is extending product development timelines and consolidating competitive advantage among incumbent tier-one suppliers with captive design capabilities.
For Market Incumbents: Consolidate supplier relationships through strategic wafer allocation partnerships with South Korean and Taiwanese foundries to defend against CMOS supply crunches. Deepen in-house ISP design capabilities to reduce dependency on external semiconductor sourcing as lidar cost compression threatens camera-centric perception stacks in premium automation segments. For New Entrants and Emerging Players: Lead with interior camera applications for driver distraction detection as KATRI and Chinese standard bodies advance in-cabin monitoring mandates. Target Thailand and Indonesia assembly expansion corridors where Japanese and Korean OEMs are localizing production to capture ASEAN EV incentives, using lifecycle data analytics bundling as the go-to-market angle. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underutilized automotive imaging divisions facing METI re-certification overhead. Long-term viability favors integrated sensor designers with captive foundry relationships over assembly-focused module houses. Watch for inflection when GB standard updates mandate rear-view visibility expansion across Chinese domestic EV lineups.| Strategic Initiative | Industry Significance |
|---|---|
| Wafer Allocation Partnership | Secures CMOS supply from Pyeongtaek and Hsinchu foundries during demand surges. |
| In-House ISP Design Investment | Reduces dependency on external semiconductor sourcing for METI-aligned validation. |
| ASEAN Manufacturing Localization | Captures Thailand Board of Investment tax privileges for regional EV platform supply. |
| Interior Camera Application Development | Addresses KATRI driver distraction detection mandates opening new revenue pools. |
| Lifecycle Data Analytics Bundling | Responds to Shenzhen fleet operator demands unbundling hardware from predictive maintenance. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with tier-one supplier procurement managers, OEM platform engineers, and aftermarket distributors, alongside secondary validation through vehicle production databases, IHS Markit registration data, MIIT autonomous vehicle certification filings, and customs trade records. Bottom-up and top-down triangulation reconciled module shipment volumes with platform-level camera content assumptions.
Across the analysis window, the forecasting framework modeled segmentation dimensions including mounting position, sensor architecture, vehicle propulsion type, OEM tier classification, and regional production cluster. CAGRs were derived from regression analysis of historical content-per-vehicle trajectories and regulatory mandate implementation timelines. Key inputs included GB standard update schedules, METI functional safety adoption curves, and foundry capacity expansion announcements from Hsinchu and Pyeongtaek.
The analysis sits within stated boundaries; outcomes outside sustained EV platform rollout momentum and stable semiconductor supply conditions would require recalibration. Practitioners should keep alternative scenarios live as MIIT autonomous driving test mandates and lidar cost compression trajectories evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
Commercial Vehicle Switches and Relays Market
Automotive Electrical & Electronics
Mexico Automotive Electric Actuators Market
Automotive Electrical & Electronics
Automotive Temperature and Humidity Sensors Market
Automotive Electrical & Electronics
Electric Motor Horn Market
Automotive Electrical & Electronics
North America Automotive Lead-Acid Battery Market
Automotive Electrical & Electronics
Motor Vehicle Sensor Market
Automotive Electrical & Electronics
South Korea Electric Power Steering (EPS) Sensor Market
Automotive Electrical & Electronics
New Energy Automotive Antenna Module Market
Automotive Electrical & Electronics
South Korea Automotive Electric Actuators Market
Automotive Electrical & Electronics
Global Automotive Electronically Controlled Air Suspension System Market
Automotive Electrical & Electronics
Automotive Electric Power Steering ECU Market
Automotive Electrical & Electronics
Europe Automotive Tpms Market
Automotive Electrical & Electronics
Electric Vehicle HV Cables Market
Automotive Electrical & Electronics
Automotive Lighting Actuators Market
Automotive Electrical & Electronics
Global Automotive on Board Power Inverter Market
Automotive Electrical & Electronics
UK Automotive Eps Market