

Residential Automatic Motor Starter Market Size, Share, and Industry Trends Forecast 2026-2036
Residential Automatic Motor Starter Market Insights
Licensed electrician shortages across North America and Western Europe is rotating project timelines and pushing builders toward pre-certified, plug-compatible motor starter modules. Schneider Electric leverages its deep channel presence in residential electrical distribution to sustain contractor loyalty. Siemens anchors its position through IEC-compliant digital starter platforms that simplify on-site commissioning. ABB competes with compact soft starter designs that reduce panel space in retrofit installations.
A residential automatic motor starter is an electromechanical or solid-state device that controls the starting current, torque, and protection logic for single-phase and three-phase motors in household and light commercial environments, typically rated between 0.5 kW and 15 kW. The device integrates overload relays, short-circuit protection, and contactor logic to prevent motor damage during startup cycles across pump, compressor, and fan loads. Soft starter and digital technology segments command premium positioning as homeowners and property managers prioritize energy efficiency and remote diagnostics. Electromechanical starters still occupy volume leadership in cost-sensitive new construction, though margin pools are thinning. Application demand clusters around pump control and HVAC systems, where variable load profiles reward programmable acceleration ramps.
NEMA ICS 2 and IEC 60947-4-1 shape product design mandates for contactor endurance and thermal protection calibration, while the EU Ecodesign Directive pressures manufacturers to document standby losses and material recyclability. In the United States, NEC Article 430 governs motor branch-circuit protection and directly influences starter specification sheets for residential inspectors. Stakeholders must monitor how tightening efficiency tiers and emerging cybersecurity requirements for connected starters reshape procurement criteria and supplier qualification timelines.
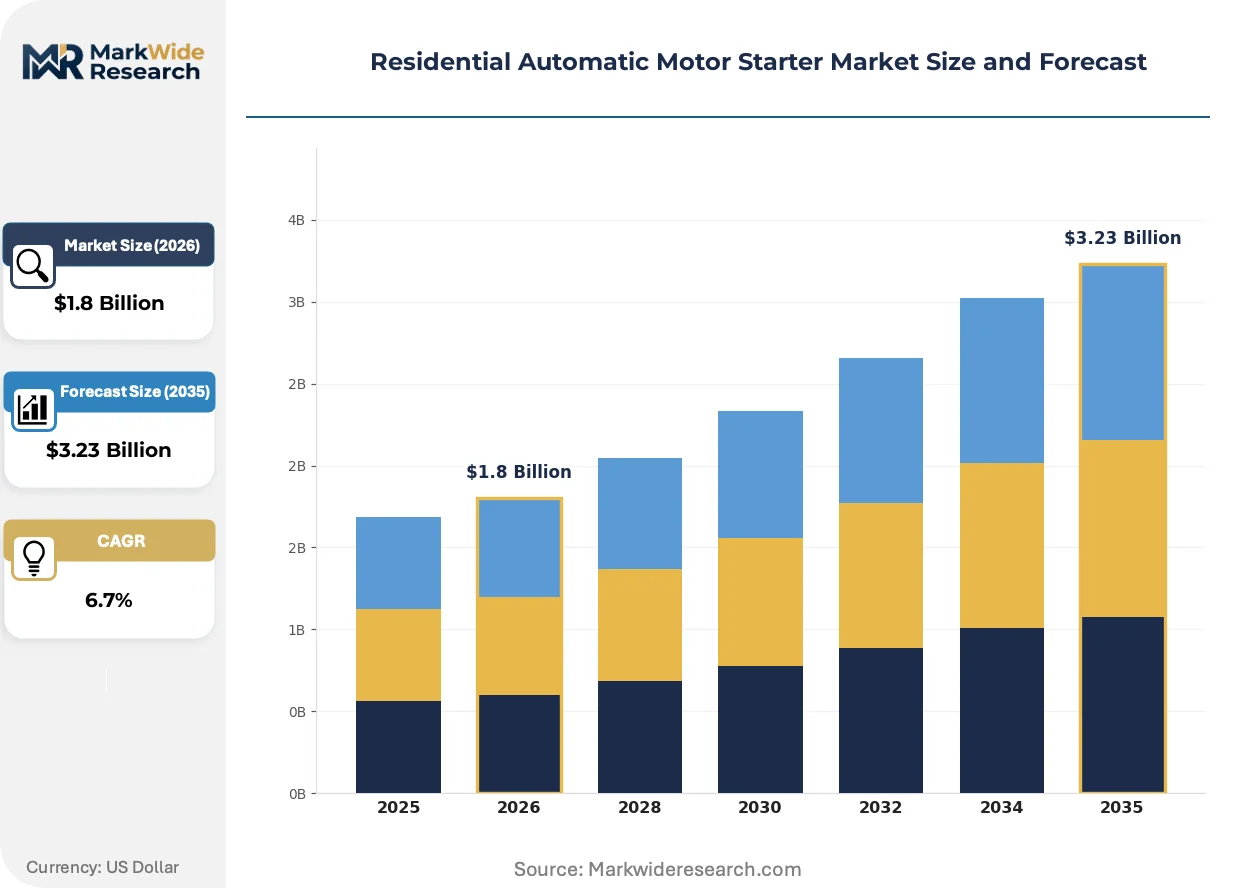
Market Dynamics
The residential automatic motor starter market is experiencing structural compression as electromechanical architectures give way to solid-state and digital platforms, driven by tightening efficiency mandates and the proliferation of connected HVAC infrastructure in new residential construction.
Growth Catalysts
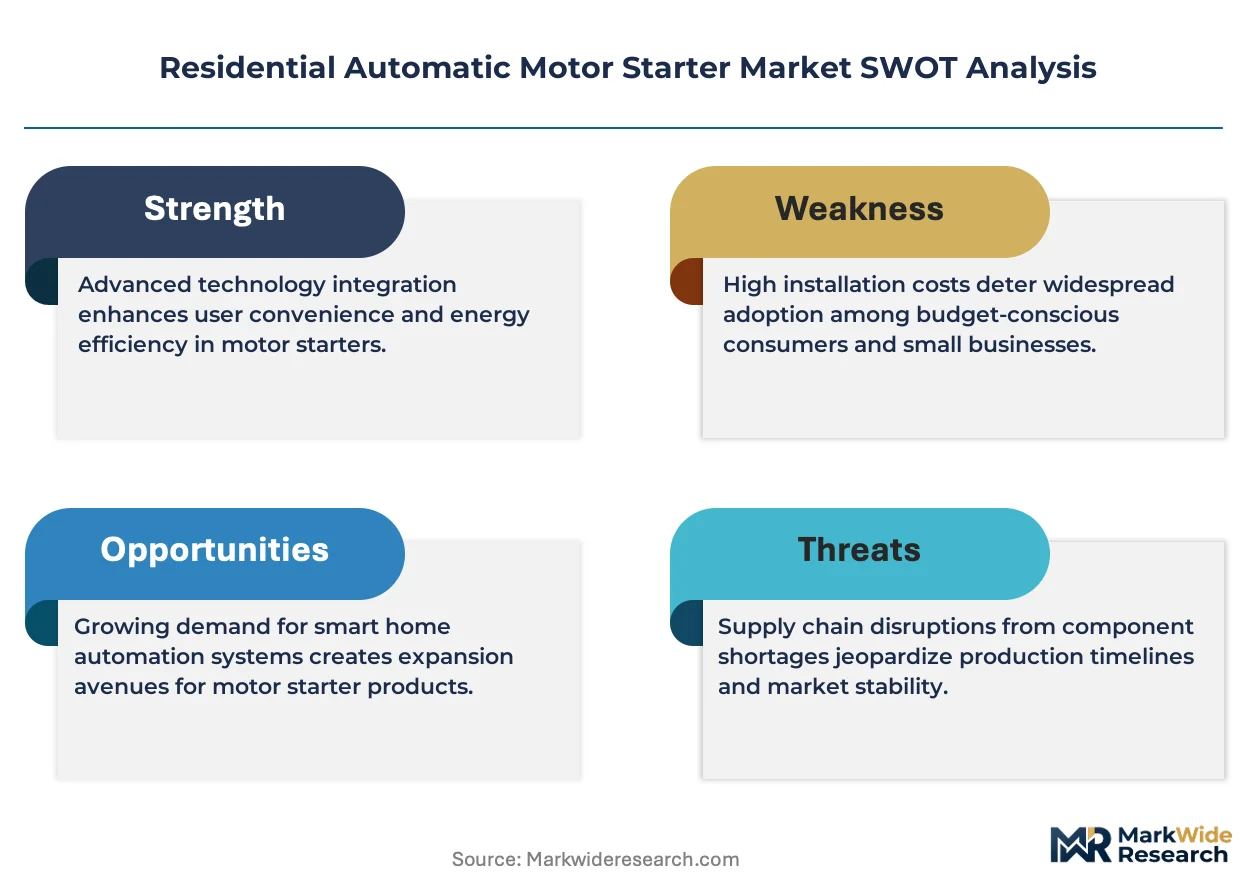
- NEMA ICS 2 compliance mandates:US residential inspectors now require certified thermal protection calibration, accelerating replacement cycles in retrofit markets and forcing specification upgrades in new builds.
- Heat pump deployment:European and North American decarbonization programs are expanding variable-load motor applications beyond traditional compressor duty cycles into hybrid heating systems.
- Smart home integration:Demand for remote diagnostics and programmable acceleration ramps is pulling digital starter adoption into mid-market residential segments previously served by basic electromechanical units.
Market Restraints
- Copper and rare earth magnet cost volatility:Input price swings for contactor windings and permanent magnet materials compress margin pools for electromechanical starter manufacturers.
- Licensed electrician scarcity:North American and Western European contractor shortages extend project timelines and limit addressable installation capacity regardless of product availability.
- Electromechanical substitution ceiling:Solid-state soft starters face thermal dissipation limitations above 15 kW in compact residential panel configurations, preserving legacy contactor dominance at higher power ratings.
Strategic Opportunities
- India residential electrification:BIS certification pathways and rural housing programs create white space for IEC-compliant starter platforms in pump control applications.
- EU Ecodesign Directive documentation requirements:Mandated standby loss reporting and material recyclability disclosures favor manufacturers with pre-assembled compliance portfolios.
- IoT-enabled predictive maintenance:Convergence of motor protection relays with cloud-based analytics platforms opens recurring revenue streams in property management channels.
Industry Challenges
- IEC 60947-4-1 certification timelines:Contactor endurance testing protocols extend product qualification cycles, delaying regional market entry for new platform launches.
- Legacy panel compatibility:Retrofit installations require mechanical form factor matching and wiring standard reconciliation, complicating digital starter penetration in existing housing stock.
- Cybersecurity integration:Connected starter architectures must now satisfy emerging network security protocols without compromising real-time motor protection response speeds.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Residential Automatic Motor Starter Market Trends and Innovations
Digital motor control architectures are fragmenting traditional starter value chains as semiconductor-based platforms displace electromechanical assemblies. This shift is compressing hardware margins while expanding software and service attach rates across residential HVAC and pump applications.
Solid-state soft starter technology is decomposing conventional contactor-relay assemblies by integrating thyristor-based current limiting with embedded microcontrollers. HVAC OEMs in Germany and the United States are specifying these platforms for variable-speed heat pump compressors. The technology is decomposing legacy supplier relationships as semiconductor firms capture value previously held by electromechanical component manufacturers.
The EU Ecodesign Directive's standby loss documentation requirements are forcing manufacturers to redesign power supply circuits and disclose material recyclability percentages. This mandate is compressing product development cycles and raising qualification costs. Residential starter portfolios targeting European markets now require dedicated compliance engineering resources distinct from North American NEMA-focused product lines.
Property management firms and multi-family developers are consolidating procurement around pre-certified starter modules that reduce on-site commissioning time. Distributors are responding with kitting services that bundle starters with compatible overload relays and short-circuit protection devices. This consolidation is most visible in United States Sun Belt markets where production homebuilders specify standardized electrical packages across high-volume developments.
Residential Automatic Motor Starter Market Segmentation
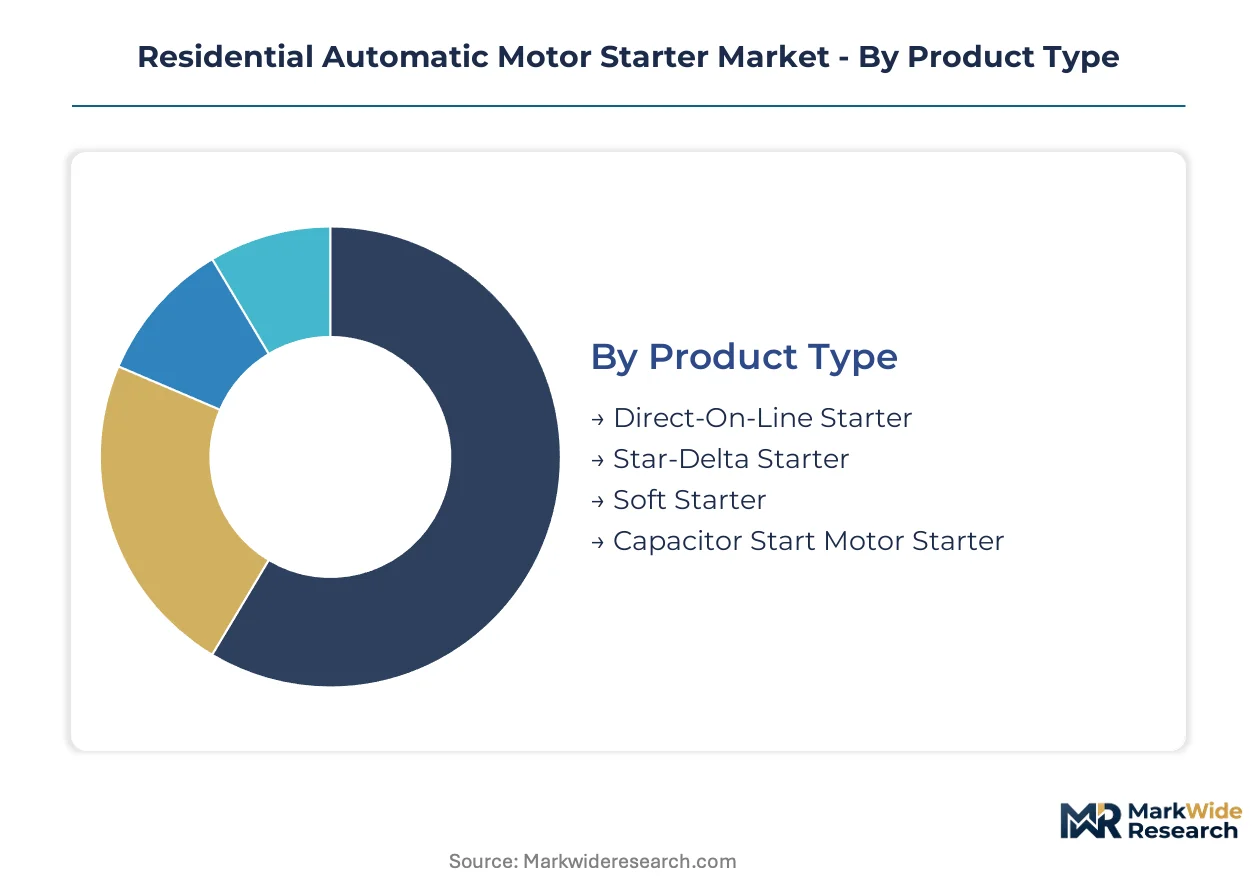
Residential automatic motor starter segmentation reveals distinct procurement patterns across electromechanical legacy systems and semiconductor-based platforms. Product type and technology choices directly determine panel space requirements, commissioning complexity, and compliance pathway costs for residential installations.
Product Type:
Direct-On-Line and Star-Delta starters dominate domestic retrofit markets in established housing stock across Germany and the United States, while Soft Starter exports concentrate in Asian manufacturing hubs serving heat pump OEMs.
- Direct-On-Line Starter:This electromechanical architecture applies full line voltage immediately to motor terminals through contactor closure. Demand concentrates in United States single-family new construction where NEC Article 430 compliance and cost minimization override efficiency considerations. Contractor familiarity and minimal commissioning requirements sustain specification dominance in volume residential developments.
- Soft Starter:Thyristor-based voltage ramping limits inrush current and mechanical stress on pump and compressor loads. German HVAC OEMs specify these platforms for variable-speed heat pump compressors under EU Ecodesign Directive efficiency tiers. The technology commands premium positioning in retrofit markets where panel space constraints and energy documentation requirements apply.
- Star-Delta Starter:Reduced-voltage starting method for three-phase motors above 5 kW, common in European residential elevator and larger pump applications requiring IEC 60947-4-1 contactor endurance certification.
- Capacitor Start Motor Starter:Single-phase auxiliary winding engagement for fractional horsepower motors in domestic water pump and garage door opener applications, prevalent in India rural electrification programs.
Direct-On-Line Starter commands the established base. The steepest expansion runs through Soft Starter.
Technology:
Cost tier stratification separates electromechanical volume production from digital and solid-state premium platforms, with microprocessor-based systems capturing mid-market residential segments previously served by basic contactor assemblies.
- Electromechanical:Contactor-relay assemblies with thermal overload protection remain the default specification for cost-sensitive new construction in United States Sun Belt markets. Copper winding cost volatility and licensed electrician scarcity compress margin pools for manufacturers without backward integration into contactor production.
- Digital:Embedded microcontroller platforms integrate programmable acceleration ramps, fault logging, and remote diagnostics capability. Property management firms in multi-family developments across California and Texas specify these for predictive maintenance and reduced service call frequency.
- Solid State:Thyristor-based current limiting without moving parts, specified where silent operation and extended cycle life outweigh electromechanical reliability familiarity.
- Microprocessor Based:Compact control units with configurable protection curves, bridging electromechanical cost structures and digital feature sets for residential contractor mid-tier procurement.
Electromechanical technology retains volume leadership. Digital platforms are climbing the fastest as smart home integration mandates expand.
Application:
Application demand clusters around variable-load profiles where programmable starting characteristics deliver measurable energy savings or equipment longevity benefits.
- HVAC Systems:Heat pump compressor and air handler motor control represents the highest-value specification opportunity. European decarbonization programs and United States IRA incentives expand variable-speed motor deployment beyond traditional on-off cycling, pulling soft starter and digital platform adoption.
- Pump Control:Residential well water and pressure booster systems require frequent start cycles that reward current limiting. Indian BIS certification pathways and rural housing electrification create white space for IEC-compliant starter platforms in this segment.
- Elevators:Low-rise residential lift motor control, concentrated in European and Asian urban infill developments with space-constrained machine rooms.
- Conveyor Belts:Light residential and accessory dwelling unit material handling applications, limited volume with specialized torque ramp requirements.
Pump Control commands the established base. HVAC Systems show the steepest expansion trajectory through heat pump deployment programs.
End User:
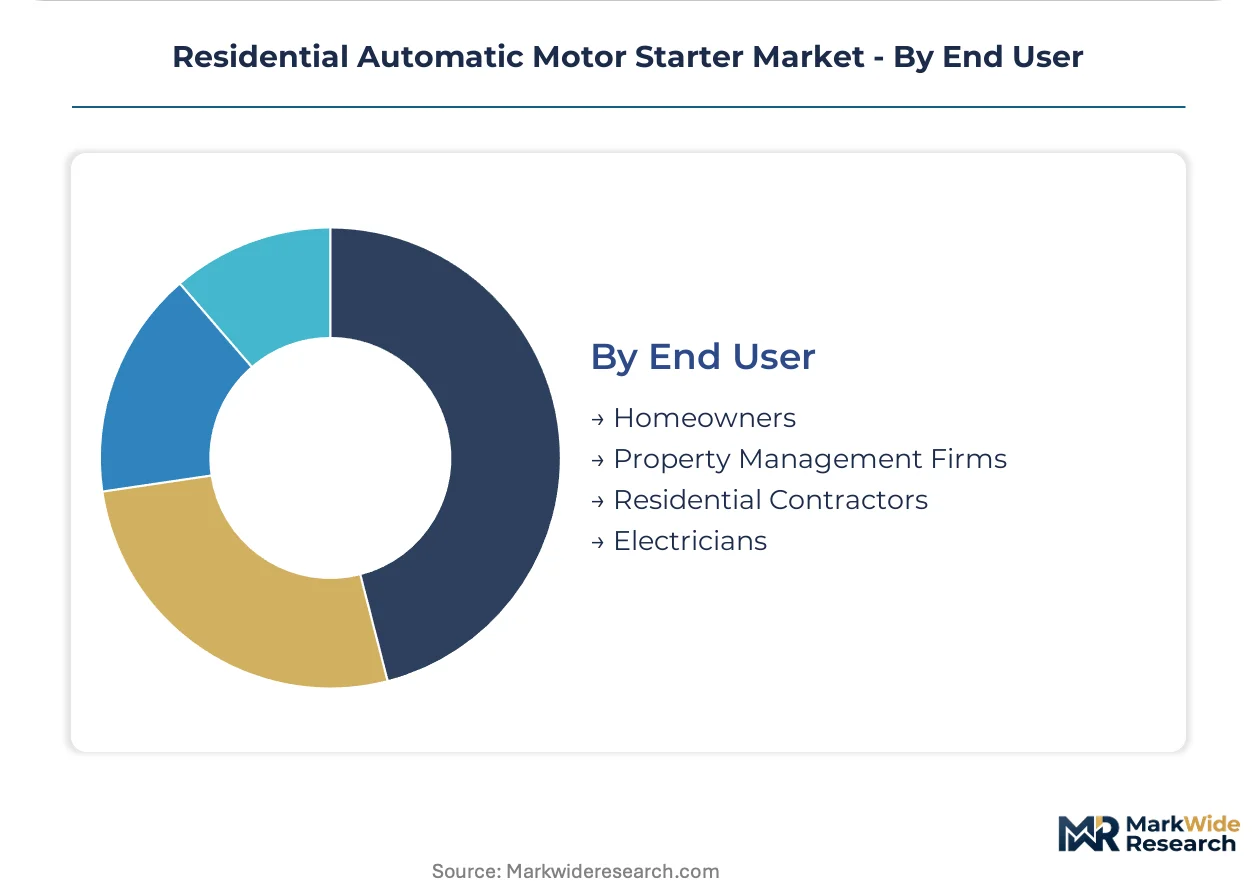
Procurement authority and technical sophistication vary sharply across end user categories, driving divergent channel strategies and product positioning approaches.
- Property Management Firms:Multi-family portfolio operators consolidate procurement around pre-certified starter modules that reduce on-site commissioning time and standardize maintenance protocols. These stakeholders prioritize remote diagnostics and cloud-based analytics platforms for distributed asset management.
- Residential Contractors:Production homebuilders in high-volume United States developments specify standardized electrical packages with minimal commissioning complexity. NEMA ICS 2 compliance documentation and plug-compatible form factors determine supplier selection.
- Electricians:Licensed trade professionals influence retrofit specification through established distributor relationships and field-proven product familiarity. Scarcity in North America and Western Europe extends project timelines regardless of product availability.
- Homeowners:Direct procurement limited to replacement scenarios and smart home enthusiast segments, typically through retail channels with installation service bundling.
Residential Contractors command the established base. Property Management Firms are gaining share fastest through portfolio-standardization mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NEC Article 430 governs motor branch-circuit protection in the United States, establishing regulatory gravity that shapes specification patterns across residential construction markets worldwide.
United States
Production homebuilders in Sun Belt markets specify standardized electrical packages with minimal commissioning complexity. NEMA ICS 2 compliance documentation and IRA heat pump incentives accelerate specification upgrades. Dallas-Fort Worth and Phoenix construction corridors concentrate demand for pre-certified plug-compatible modules.
Germany
HVAC OEMs specify variable-speed heat pump compressors under EU Ecodesign Directive efficiency tiers. The F-Gas Regulation pressures refrigerant system redesigns that cascade into motor control requirements. Stuttgart and Munich industrial clusters anchor specification authority for European residential developments.
China
Rural housing programs and urban smart home penetration expand addressable installation bases. GB standards and MIIT efficiency mandates tighten product certification requirements. Yangtze River Delta manufacturing hubs supply electromechanical starter volumes for domestic and export markets.
India
BIS certification pathways and rural electrification programs create white space for IEC-compliant starter platforms in pump control applications. CEA wiring regulations govern residential motor branch-circuit installations. Gujarat and Maharashtra industrial corridors concentrate domestic manufacturing capacity.
Japan
METI efficiency standards and aging residential stock drive retrofit demand for compact digital starter platforms. JIS certification requirements shape product qualification timelines. Kanto and Kansai metropolitan areas concentrate property management firm procurement consolidation.
Residential Automatic Motor Starter Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, producing a tiered competitive structure. Electromechanical volume manufacturers compete on copper winding integration and contactor production scale, while semiconductor-based platform developers capture premium positioning through programmable acceleration and remote diagnostics capability. Three archetypes dominate: integrated electrical distribution conglomerates with deep contractor channel presence; industrial automation specialists with IEC-compliant digital platforms; and regional electromechanical fabricators serving cost-sensitive new construction. Competitive moves concentrate on backward integration into contactor production and strategic kitting partnerships with electrical distributors.
Within the integrated conglomerate tier, Schneider Electric and Siemens exemplify channel-anchored positioning, while ABB occupies a position bridging industrial automation heritage with residential retrofit specialization. These three entities represent distinct geographic and technological anchoring strategies—French electrical distribution depth, German IEC platform standardization, and Swiss-Swedish compact soft starter design—without implying specific market share claims or strategic initiative attribution.
| Leading Market Players |
|---|
| Schneider Electric |
| Siemens |
| ABB |
| Eaton |
| Rockwell Automation |
| Mitsubishi Electric |
| Fuji Electric |
| Legrand |
| Havells |
| Others |
Pricing and Supply Chain Analysis
Long-term capacity reservation agreements with contactor winding suppliers lock in copper access and price visibility for electromechanical starter manufacturers serving United States Sun Belt construction markets. These contracts insulate procurement teams from spot volatility while constraining flexibility to pivot toward solid-state architectures when rare earth magnet costs spike.
Pricing Analysis
German HVAC OEMs pay 15-25% premiums over United States residential contractors for identical soft starter specifications, reflecting EU Ecodesign Directive compliance documentation and CE-marked thermal protection calibration. Three-tier pricing structure across premium digital platforms, standard electromechanical units, and economy DOL starters separates certification-grade products from basic NEC Article 430 compliance. Cost compression in economy tiers is intensifying because copper winding spot markets feed directly into contactor production costs. Production homebuilders exhibit highest price sensitivity, while property management firms prioritize predictive maintenance bundling over unit economics.
Supply Chain Analysis
Strait of Malacca transit underwrites rare earth magnet flows from Chinese separation plants to semiconductor fabrication facilities producing thyristor assemblies for soft starter platforms. Manufacturing concentrates in China, Germany, and the United States, with Yangtze River Delta hubs feeding electromechanical contactor volumes and Stuttgart industrial clusters anchoring IEC-compliant digital platform assembly. Supply chains draw from copper cathode, silicon steel laminations, and neodymium magnet feedstocks. Single-source vulnerability in rare earth separation exposes solid-state starter margins to export quota shocks. Distribution runs through electrical wholesale distributors with contractor loyalty programs and direct HVAC OEM specification channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as smart home integration mandates splinter procurement authority between property management platforms, production homebuilders, and retail homeowner channels, each demanding incompatible feature sets and compliance documentation.
For Market Incumbents: Fortify backward integration into contactor winding production to defend margin position against copper volatility and emerging semiconductor-based substitutes. Prioritize certification investment in IEC 60947-4-1 digital platforms to preempt regulatory displacement of electromechanical architectures in European markets. Channel control through distributor kitting partnerships remains essential as licensed electrician scarcity extends project timelines regardless of product availability. For New Entrants and Emerging Players: Cloud-based predictive maintenance analytics for multi-family property management portfolios represents a service-layer gap where incumbents under-serve with hardware-centric offerings. Target Indian pump control applications through BIS certification pathways and rural electrification program alignment. Go-to-market angle should emphasize IoT-enabled remote diagnostics that reduce service call frequency for portfolio operators. For Investors and Strategic Acquirers: Capital is best deployed toward semiconductor-anchored platform developers with embedded microcontroller capabilities and recurring software revenue potential. Long-term viability favors suppliers capable of bridging electromechanical cost structures with digital feature sets as the market transitions. Watch for inflection signals in NEC Article 430 amendment cycles that could accelerate solid-state substitution mandates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Contactor Production | Captive copper winding supply insulates margins from LME volatility for electromechanical manufacturers. |
| IEC 60947-4-1 Digital Platform Certification | CE-marked compliance opens specification pathways with German HVAC OEMs under EU Ecodesign tiers. |
| Distributor Kitting Partnership Expansion | Pre-assembled starter-overload-protection bundles reduce on-site commissioning time for contractor channels. |
| IoT-Enabled Predictive Maintenance Launch | Cloud analytics integration creates recurring revenue streams with property management firm consolidation. |
| Indian BIS Certification Pathway Investment | Rural electrification program alignment unlocks pump control white space in Gujarat and Maharashtra corridors. |
Research Methodology
A spread of perspectives from electrical distribution product managers, licensed contractor purchasing agents, HVAC OEM specification engineers, and property management technology directors converged on the working assumptions driving this analysis. Primary interview insights were validated against secondary sources including NEC Article 430 amendment records, EU Ecodesign Directive standby loss documentation, BIS certification registries, and customs trade data for copper winding and thyristor component flows. Bottom-up installation base modeling and top-down construction spending triangulation anchored volume estimates.
Segmentation dimensions modeled span product type architecture, technology platform, application load profile, and end-user procurement authority across the projection horizon. CAGRs were derived from installation base growth rates, replacement cycle compression under tightening efficiency mandates, and technology substitution curves. Forecast inputs incorporated heat pump deployment program trajectories in North America and Europe, plus rural electrification pipeline data from Indian CEA planning documents.
Underlying assumptions cover regulatory compliance timeline stability, copper and rare earth magnet price band persistence, and licensed electrician supply elasticity, with deviation risk concentrated in cybersecurity mandate acceleration for connected starters and sudden NEC code cycle compression. Practitioners should keep alternative scenarios live as IEC-NEMA regulatory harmonization discussions and solid-state thermal dissipation breakthroughs evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.