
 GCC Automotive Lead-Acid Battery Market | 2026-2036
GCC Automotive Lead-Acid Battery Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Automotive Lead-Acid Battery Market Intelligence
Aftermarket distribution networks across the Gulf Cooperation Council is rewriting how batteries reach end users. Clarios International Inc. leverages its regional logistics footprint to serve independent workshops and retail chains. Middle East Battery Company anchors domestic production capacity in Saudi Arabia, reducing import dependency for flooded and AGM variants. Al Dobowi Group competes through diversified industrial distribution, extending coverage into fleet maintenance contracts and commercial vehicle service bays.
The GCC automotive lead-acid battery is an electrochemical storage device comprising lead dioxide positive plates, sponge lead negative plates, and sulfuric acid electrolyte, engineered to deliver high cold-cranking amperage for internal combustion engine starting and shallow-cycle auxiliary power. Flooded batteries dominate volume in heavy-duty vehicle applications where cost sensitivity and serviceability outweigh sealed-unit convenience, while absorbent glass mat variants capture premium positioning in start-stop systems demanding deeper cycling resilience. Enhanced flooded battery technology leads growth among OEM fitments as automakers balance electrification cost pressures against stop-start fuel efficiency mandates.
Gulf Standardization Organization (GSO) technical regulations and Saudi Standards, Metrology and Quality Organization (SASO) product conformity programs enforce electrolyte containment and labeling requirements that filter non-compliant imports from Asian manufacturing bases. UAE's Ministry of Industry and Advanced Technology battery stewardship guidelines pressure distributors to document recycling chain custody, elevating operational costs for smaller aftermarket providers. Stakeholders must monitor how national recycling infrastructure investments and carbon intensity disclosure rules reshape supplier qualification criteria across Saudi Arabia, the UAE, and Kuwait.
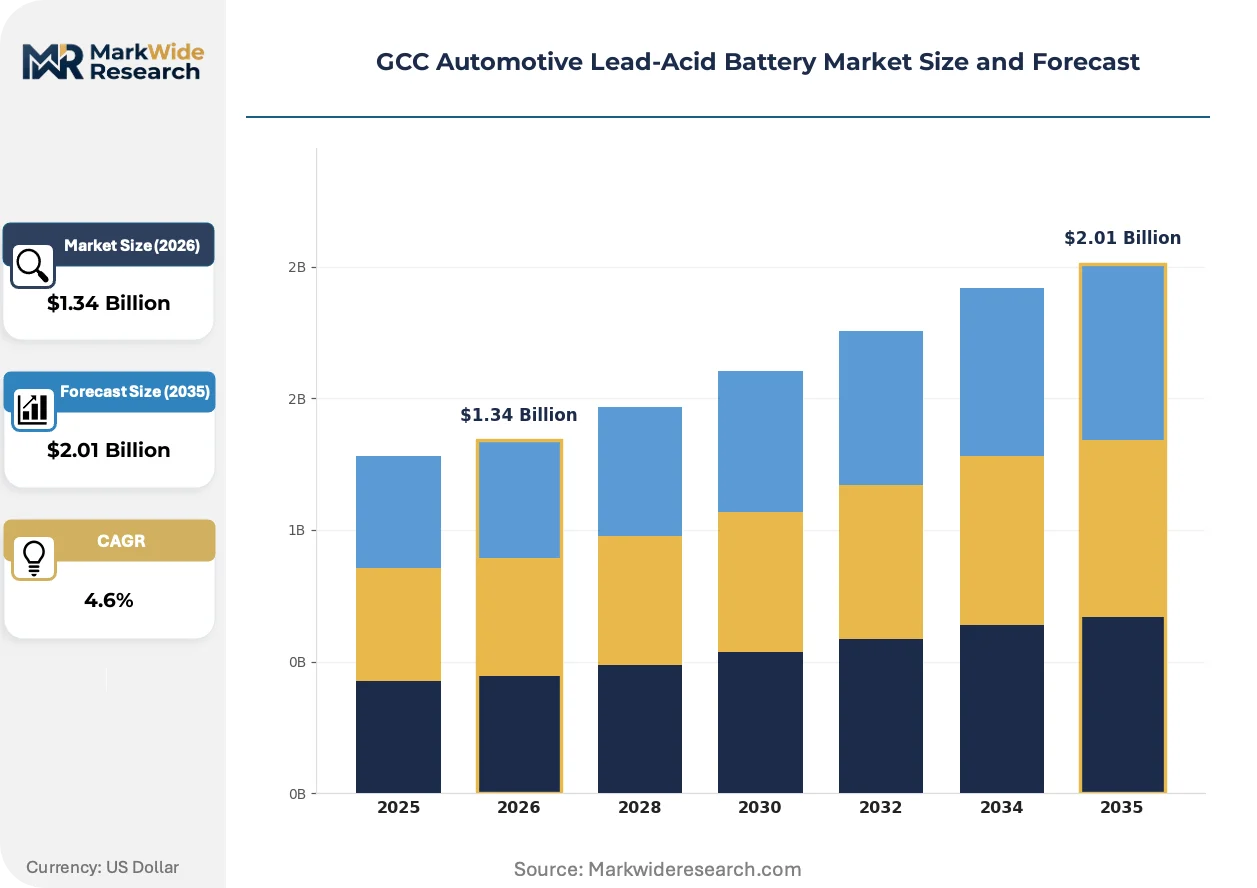
Market Dynamics
Fleet renewal programs across Saudi Arabia and the UAE are compressing replacement cycles, while GSO and SASO compliance mandates filter supplier eligibility and reshape procurement qualification standards for aftermarket distributors.
Growth Catalysts
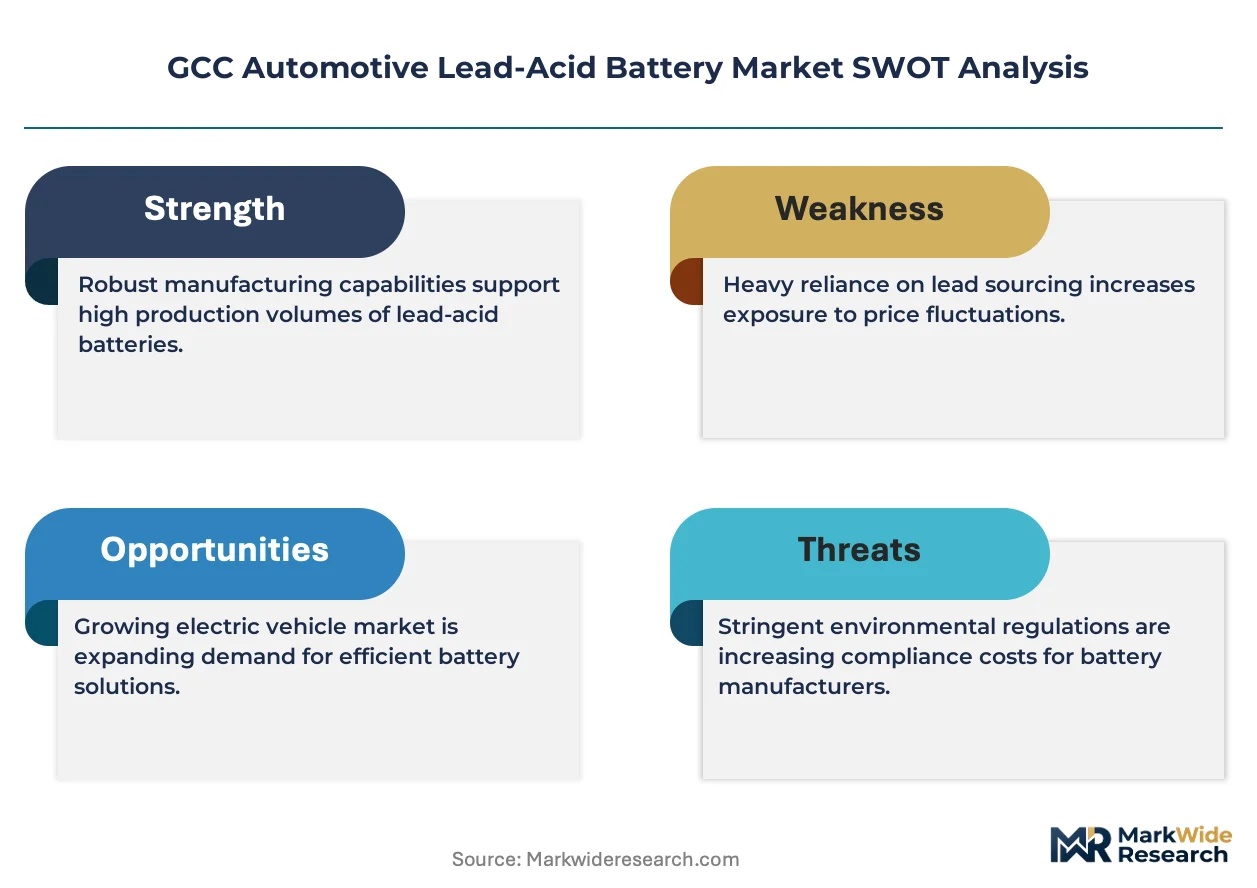
- SASO Product Conformity Programs:Certification requirements for electrolyte containment and labeling are eliminating low-grade imports, creating protected market space for qualified regional manufacturers and distributors.
- Start-Stop System Penetration:Enhanced flooded battery and AGM variants are capturing OEM fitments as automakers balance fuel efficiency mandates against hybridization cost pressures.
- Commercial Vehicle Fleet Expansion:Heavy-duty logistics operators in Saudi Arabia are extending service contracts, driving predictable aftermarket replacement demand through authorized workshop networks.
Market Restraints
- Lead Price Volatility:Raw material input costs for lead dioxide and sponge lead plates fluctuate with London Metal Exchange pricing, compressing margin buffers for flooded battery producers serving price-sensitive segments.
- Asian Import Concentration:Non-compliant manufacturing bases in Southeast Asia supply undifferentiated product that circumvents GSO technical regulations, creating price pressure at the budget tier.
- Lithium-Ion Substitution:Advanced chemistry batteries are displacing lead-acid in auxiliary power applications for electric vehicle platforms and premium passenger car segments.
Strategic Opportunities
- Kuwait Fleet Electrification Lag:Slower hybrid adoption timelines preserve internal combustion engine installed base, extending replacement window for conventional starting batteries in commercial applications.
- Recycling Chain Custody Documentation:UAE Ministry of Industry stewardship guidelines reward distributors with verified closed-loop collection systems, differentiating service capabilities against informal competitors.
- AGM-EFB Convergence:Absorbent glass mat and enhanced flooded battery technologies are merging performance characteristics, enabling single-platform manufacturing flexibility for regional producers.
Industry Challenges
- Hazardous Material Handling Certification:Gulf national standards for sulfuric acid transport and storage require specialized logistics infrastructure that smaller aftermarket providers struggle to fund.
- Workforce Technical Competency:Diagnostic capability for start-stop system battery management systems remains scarce among independent service technicians, limiting premium product penetration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Automotive Lead-Acid Battery Market |
| Market Size in 2026 | $1.34 Billion |
| Market Size in 2035 | $2.01 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flooded, Absorbent Glass Mat, Gel, Sealed Lead-Acid Application: Start-Stop Systems, Heavy-Duty Vehicles, Passenger Cars, Hybrid Vehicles Technology: Lead-Calcium, Lead-Antimony, Maintenance-Free, Enhanced Flooded Battery End User: OEMs, Aftermarket Providers, Dealerships, Fleet Operators |
| Companies Covered | Clarios International Inc., Middle East Battery Company, Reem Batteries & Power Appliances Co., EnerSys, FIAM Energy Technology SpA, C&D Technologies, Inc., Al Dobowi Group, Sunlight Group Energy Storage Systems, East Penn Manufacturing, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Automotive Lead-Acid Battery Market Strategic Shifts & Innovations
Battery management systems are digitizing performance monitoring across GCC fleet operations, while regulatory frameworks for circular economy compliance are hardening documentation requirements throughout the value chain.
Smart battery sensors are digitizing state-of-charge and state-of-health data transmission to fleet telematics platforms. Logistics operators in Saudi Arabia are deploying these systems to optimize replacement timing and reduce roadside failure incidents. Real-time performance visibility is digitizing procurement decisions, shifting purchasing authority from workshop floor managers to centralized fleet engineering departments.
GSO technical regulations for electrolyte containment and labeling are tightening enforcement mechanisms at Saudi and UAE ports of entry. Non-compliant Asian imports face elevated inspection rates and detention costs, reshaping competitive dynamics for aftermarket distributors. Domestic manufacturers with SASO certification are capturing shelf space previously occupied by unverified imports.
Fleet maintenance contracts are consolidating battery procurement into multi-year service agreements with performance guarantees. Commercial vehicle operators in the UAE are unbundling component sourcing from vehicle acquisition, creating dedicated battery supplier tiers within authorized service networks. This procurement rationalization is most advanced among temperature-controlled logistics providers operating cross-border routes between Dubai and Riyadh.
GCC Automotive Lead-Acid Battery Market Segmentation
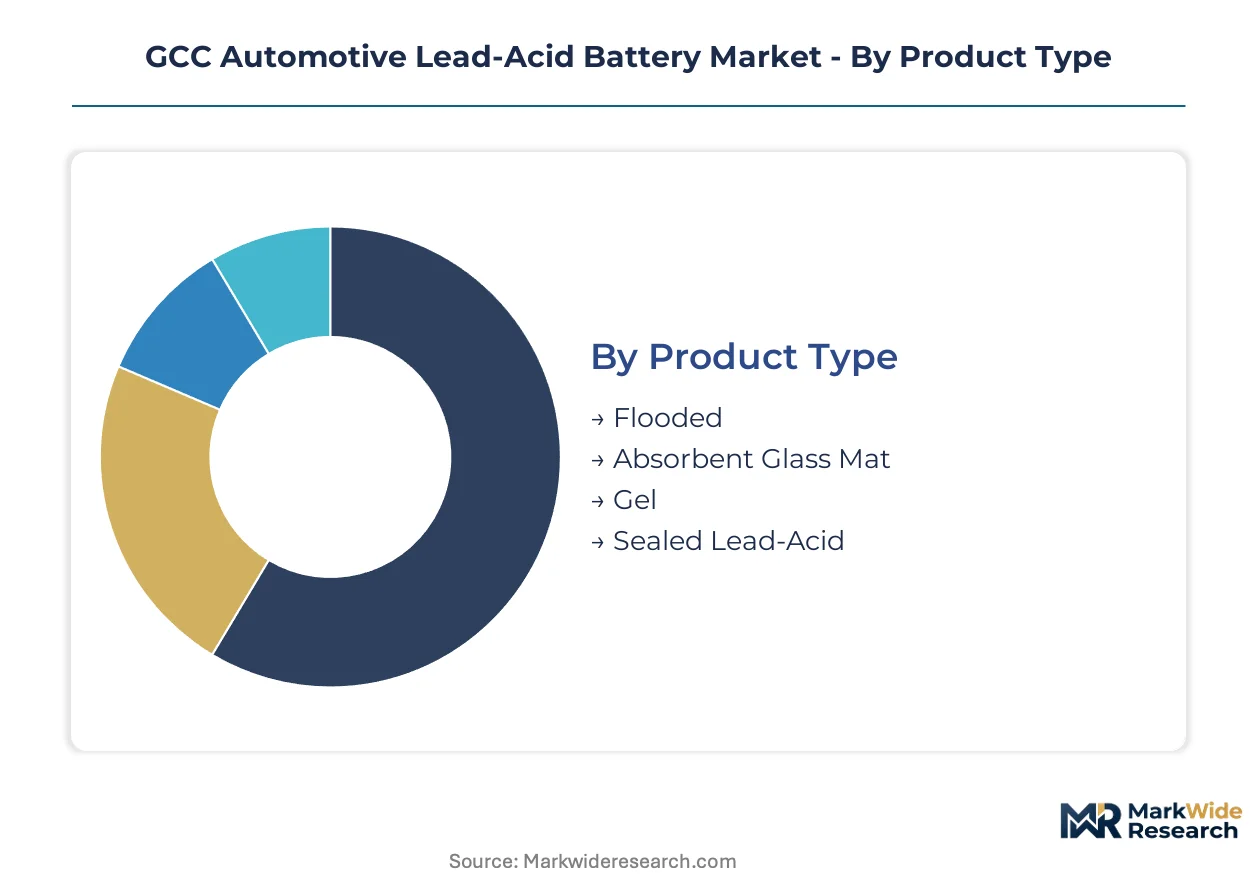
Segmentation in the GCC automotive lead-acid battery market reveals divergent replacement cycles across product architectures and end-use categories. Fleet operators compress turnover timelines through predictive maintenance, while passenger vehicle owners extend service intervals, creating tiered demand patterns that suppliers must navigate.
Product Type:
Flooded batteries turn over fastest in commercial fleets with aggressive preventive maintenance schedules, while sealed architectures cycle slowest in private vehicle applications where access constraints delay replacement.
- Flooded:Lead dioxide positive plates and sponge lead negative plates submerged in liquid sulfuric acid electrolyte deliver high cold-cranking amperage for internal combustion engine starting. Heavy-duty logistics operators across Saudi Arabia specify flooded units for serviceability and cost control in temperature-extreme operating conditions.
- Absorbent Glass Mat:Electrolyte suspended in fiberglass mat separators enables vibration resistance and deeper cycling resilience for start-stop applications. UAE fleet operators specify AGM variants for cross-border routes where frequent engine cycling accelerates battery degradation.
- Gel:Silica-thickened electrolyte immobilizes acid for spill-proof operation in marine and off-road vehicle auxiliary power roles. Niche penetration in Saudi Arabia's desert expedition vehicle segment.
- Sealed Lead-Acid:Valve-regulated recombinant design eliminates maintenance access requirements for passenger car owners. Standard fitment in entry-level vehicles where workshop density is limited.
Flooded batteries dominate installed base. AGM is where expansion concentrates.
Application:
Cost tier stratification separates premium start-stop fitments from economy-grade conventional starting applications, with heavy-duty commercial vehicles occupying the mid-tier on total-cost-of-ownership metrics.
- Start-Stop Systems:Cyclic duty demands enhanced cycling endurance from EFB and AGM architectures. Saudi Standards, Metrology and Quality Organization fuel efficiency compliance deadlines are accelerating OEM fitment rates.
- Heavy-Duty Vehicles:Flooded batteries with thick positive plates withstand deep discharge recovery in commercial trucking. UAE temperature-controlled logistics providers specify heavy-duty formulations for Dubai-Riyadh corridor operations.
- Passenger Cars:Conventional starting-lighting-ignition duty cycles favor cost-optimized flooded or maintenance-free designs. Aftermarket replacement timing extends beyond warranty periods across Kuwait's dispersed population centers.
- Hybrid Vehicles:Auxiliary power unit batteries face lithium-ion displacement pressure in full-hybrid architectures. Mild-hybrid 48V systems retain lead-acid for starter-generator functions in Saudi Arabia's initial electrification wave.
Passenger cars anchor volume. Start-stop systems are climbing the fastest.
Technology:
Volume concentration in maintenance-free architectures reflects Gulf consumer preference for sealed convenience, while margin accrues to enhanced flooded battery platforms capturing OEM start-stop mandates.
- Lead-Calcium:Calcium-alloyed negative grids reduce water consumption and self-discharge rates. Standard formulation for maintenance-free passenger car batteries across UAE retail channels.
- Lead-Antimony:Antimony content improves deep-cycle recovery and structural integrity under vibration. Retained in Saudi Arabian heavy-duty flooded batteries where service access permits watering.
- Maintenance-Free:Calcium-calcium grid chemistry eliminates electrolyte replenishment requirements. Dominates aftermarket replacement demand among independent vehicle owners in Kuwait.
- Enhanced Flooded Battery:Modified plate pasting and separator designs double cycling endurance versus conventional flooded units. Gulf Standardization Organization fuel efficiency regulations are positioning EFB as the default OEM fitment for cost-optimized stop-start systems.
Maintenance-free formulations command replacement volume. Enhanced flooded battery technology is gaining share fastest.
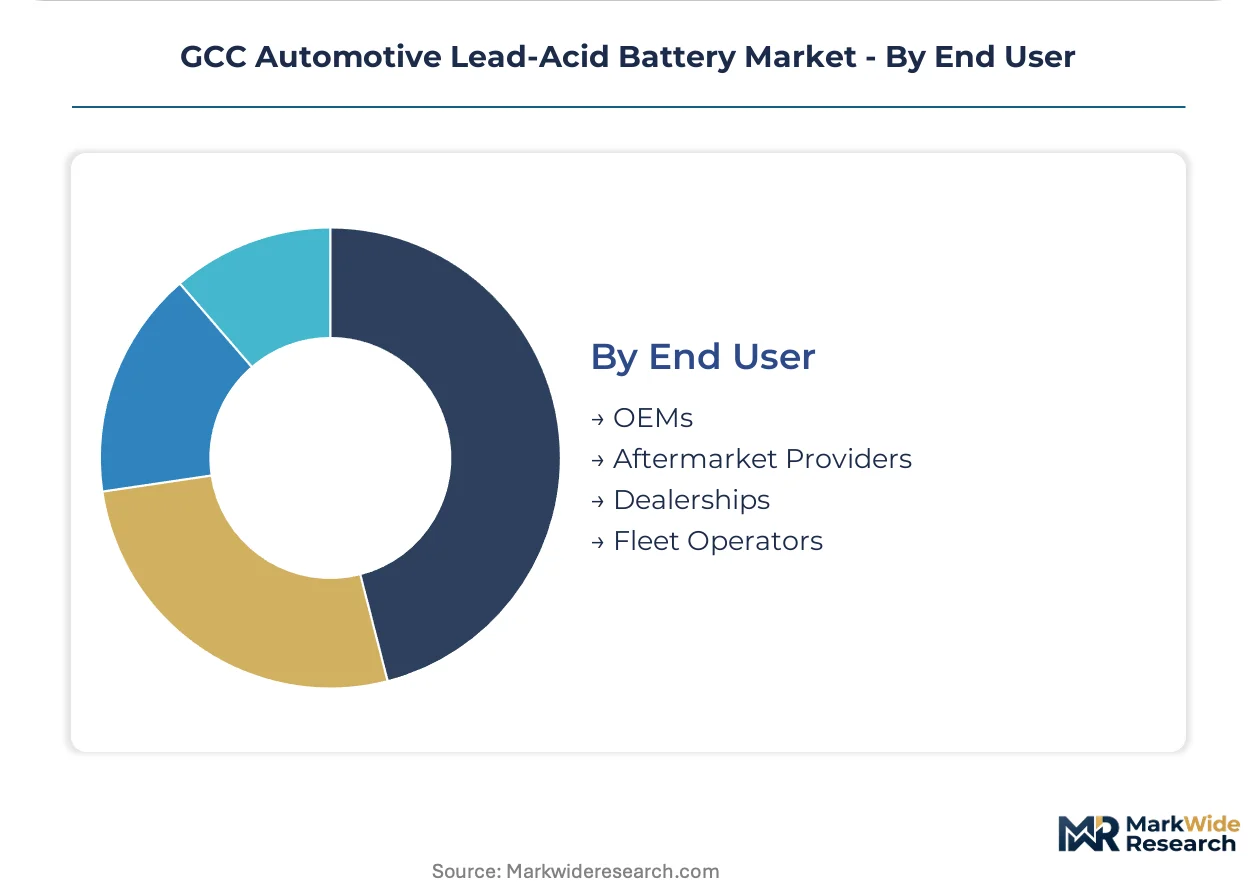
End User:
Customer type determines procurement authority concentration, with fleet operators centralizing decisions through engineering departments while aftermarket channels fragment purchasing across independent workshops.
- OEMs:Vehicle manufacturers specify battery platforms during platform development, locking in multi-year supply agreements. Saudi Arabian assembly operations are localizing EFB sourcing to meet SASO conformity program timelines.
- Aftermarket Providers:Independent distributors and retail chains serve replacement demand outside warranty coverage. UAE's Ministry of Industry stewardship guidelines are filtering informal competitors through recycling documentation requirements.
- Dealerships:Authorized service networks capture warranty-period replacements and brand-loyal customers. Consolidating procurement into regional distribution centers serving multiple franchise locations.
- Fleet Operators:Commercial vehicle owners unbundle battery sourcing from vehicle acquisition through multi-year service contracts. Saudi logistics operators are deploying telematics-integrated battery management systems to optimize replacement timing.
Aftermarket providers serve the widest customer base. Fleet operators are where contract value is expanding most steeply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
King Abdullah Port's container throughput underwrites Saudi Arabia's import dominance for automotive components across the Peninsula. Jebel Ali's free zone infrastructure anchors UAE distribution networks serving aftermarket channels from Oman to Kuwait.
Saudi Arabia
Fleet renewal programs at Saudi Aramco logistics subsidiaries and last-mile delivery operators compress replacement cycles for commercial vehicle batteries. SASO product conformity programs enforce electrolyte containment standards that filter non-compliant imports through elevated port inspection rates. Jeddah's industrial corridor hosts flooded battery assembly operations serving domestic OEM fitments and Red Sea export routes.
United Arab Emirates
Temperature-controlled logistics providers operating Dubai-Riyadh corridor routes specify AGM variants for frequent engine cycling in extreme heat. MOHAP stewardship guidelines pressure distributors to document recycling chain custody, elevating operational costs for informal aftermarket competitors. Jebel Ali free zone concentrates regional distribution centers for Clarios International Inc. and Al Dobowi Group serving GCC re-export markets.
Kuwait
Slower hybrid vehicle adoption timelines preserve internal combustion engine installed base, extending replacement windows for conventional starting batteries in commercial applications. The country's national standards organization enforces hazardous material handling certification for sulfuric acid transport that smaller providers struggle to fund. Shuwaikh Industrial Area hosts limited domestic assembly capacity, maintaining import dependency for premium AGM and EFB variants.
Qatar
Construction logistics fleets supporting FIFA World Cup legacy infrastructure projects sustain predictable aftermarket demand for heavy-duty flooded batteries. National environmental regulations mandate recycling documentation for battery distributors serving the Doha metropolitan area. Ras Laffan's industrial zone generates niche demand for sealed lead-acid units in marine and off-road auxiliary power applications.
Oman
Mining logistics operators in the Al Batinah region specify thick-plate flooded batteries for deep discharge recovery in remote operating conditions. Port of Salalah's transshipment growth exposes local distributors to GSO-compliant imports from UAE and Saudi manufacturing bases. Sohar Freezone attracts regional battery warehousing investments targeting Yemeni reconstruction demand and East African export routes.
GCC Automotive Lead-Acid Battery Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in cell and materials supply. The GCC automotive lead-acid battery market structures around three archetypes: multinational manufacturers with regional logistics footprints, domestic producers leveraging SASO certification for import substitution, and diversified industrial distributors extending into fleet maintenance contracts. Competitive moves concentrate on recycling chain custody documentation and telematics-integrated battery management system deployment.
Within the multinational tier, Clarios International Inc. and EnerSys occupy positions shaped by Jebel Ali distribution infrastructure and cross-border fleet service networks. Middle East Battery Company anchors domestic manufacturing capacity in Saudi Arabia, reducing import dependency for flooded and AGM variants. Al Dobowi Group exemplifies diversified industrial distribution, extending coverage into commercial vehicle service bays through multi-year fleet maintenance agreements.
| Leading Market Players |
|---|
| Clarios International Inc. |
| Middle East Battery Company |
| Reem Batteries & Power Appliances Co. |
| EnerSys |
| FIAM Energy Technology SpA |
| C&D Technologies, Inc. |
| Al Dobowi Group |
| Sunlight Group Energy Storage Systems |
| East Penn Manufacturing |
| Others |
Cost & Logistics Intelligence
Undercapacity at Saudi Arabia's domestic flooded battery assembly plants is compressing lead time premiums and forcing distributors to absorb freight volatility from Asian manufacturing bases, tightening margin buffers across aftermarket tiers.
Pricing Analysis
Volume-discount tiering structures separate fleet procurement contracts from retail aftermarket transactions. Pricing stratifies across SASO-certified premium grades, standard maintenance-free formulations, and economy flooded units subject to Asian import competition. Cost compression in the budget tier is intensifying because GSO port inspections are elevating detention costs for non-compliant shipments. Fleet operators exhibit the lowest price sensitivity due to total-cost-of-ownership calculations, while independent vehicle owners in Kuwait drive aggressive retail discounting.
Supply Chain Analysis
Extended payment terms from Jebel Ali distribution centers are financing inventory carrying costs for UAE-based aftermarket distributors serving cross-border routes. Lead dioxide and sponge lead plates draw from Chinese and South Korean smelting capacity, with sulfuric acid sourcing concentrated in Saudi Arabia's Eastern Province industrial corridor. Single-source vulnerability sits with AGM separator mat imports from Southeast Asian textile manufacturers. Distribution runs through authorized workshop networks for fleet accounts and independent retail chains for replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across the GCC aftermarket is creating niche entry points as SASO certification requirements filter informal competitors and concentrate procurement authority within fleet engineering departments.
For Market Incumbents: Build recycling chain custody documentation as a regulatory moat against Asian import competitors. Secure backward integration into lead smelting capacity within Saudi Arabia's industrial corridor to buffer London Metal Exchange volatility. Expand telematics-integrated battery management system deployment to lock in multi-year fleet service contracts before lithium-ion auxiliary power substitution accelerates.
For New Entrants and Emerging Players: Oman's Sohar Freezone offers underpenetrated warehousing capacity for distributors targeting Yemeni reconstruction demand and East African re-export routes. Kuwait's slower hybrid adoption timeline preserves extended replacement windows for conventional starting batteries in commercial applications. Lead with hazardous material handling certification investment to differentiate against informal competitors struggling with GSO compliance costs.
For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated mid-cap specialists with captive lead recycling capabilities and SASO-certified domestic assembly footprint. The long-term viability window favors platforms positioned for circular economy compliance rather than pure trading operations. Monitor lithium-ion cost parity trajectories in mild-hybrid 48V architectures as the inflection signal for lead-acid displacement pressure.
| Strategic Initiative | Industry Significance |
|---|---|
| Recycling Chain Custody Certification | UAE Ministry of Industry stewardship guidelines reward verified closed-loop collection systems with preferred supplier status. |
| EFB Platform Standardization | Gulf Standardization Organization fuel efficiency regulations position enhanced flooded battery as default OEM fitment. |
| Telematics-Integrated Battery Management | Saudi logistics operators deploy real-time state-of-health monitoring to optimize replacement timing and reduce roadside failures. |
| Domestic Lead Smelting Integration | Saudi Arabia's industrial corridor hosts capacity that reduces import dependency for lead dioxide and sponge lead inputs. |
| Cross-Border Fleet Service Contracts | Temperature-controlled logistics providers unbundle battery sourcing from vehicle acquisition through multi-year performance agreements. |
Research Approach
Initial hypotheses were tested against primary input from aftermarket distribution managers, fleet maintenance directors, OEM procurement leads, and regulatory affairs specialists at Gulf Standardization Organization member bodies, then refined against Saudi customs trade data, SASO certification registries, London Metal Exchange lead pricing archives, and vehicle production databases from IHS Markit. Bottom-up channel volume estimates triangulated with top-down macroeconomic absorption models.
Demand-supply balance dynamics anchored the analytical framework across the analysis window, with segmentation modeling across product architecture, application duty cycle, technology chemistry, and end-user procurement authority. CAGRs derived from replacement cycle compression rates and fleet expansion trajectories. Forecast inputs incorporated SASO conformity program enforcement intensity and start-stop system penetration curves by vehicle class.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese lead-acid manufacturers or accelerated lithium-ion cost reduction would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
South Korea Electric Power Steering (EPS) Sensor Market
Automotive Electrical & Electronics
Electric Vehicle Shielded HV Cables Market
Automotive Electrical & Electronics
Bicycle Electronic Drivetrain Market
Automotive Electrical & Electronics
Personal Mobility Devices Market
Automotive Electrical & Electronics
Electric Vehicle HV Cables Market
Automotive Electrical & Electronics
Europe Electric Power Steering Market
Automotive Electrical & Electronics
Automotive LED Market
Automotive Electrical & Electronics
Automotive Starting System Market
Automotive Electrical & Electronics
Automotive Thermoelectric Generator Market
Automotive Electrical & Electronics
Automotive Airbag Electronic Control Unit Market
Automotive Electrical & Electronics
Motor Vehicle Sensor Market
Automotive Electrical & Electronics
Global Automotive on Board AC-DC Power Inverters Market
Automotive Electrical & Electronics
Europe Automotive Steering Sensor Market
Automotive Electrical & Electronics
Automotive Charge Port Actuator Market
Automotive Electrical & Electronics
Europe Automotive Pressure Sensor Market
Automotive Electrical & Electronics
Automotive Electronic Logging Device (ELD/E-Log) Market