
 Europe Automotive Lubricants Market | 2026-2036
Europe Automotive Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Automotive Lubricants Market Foresight
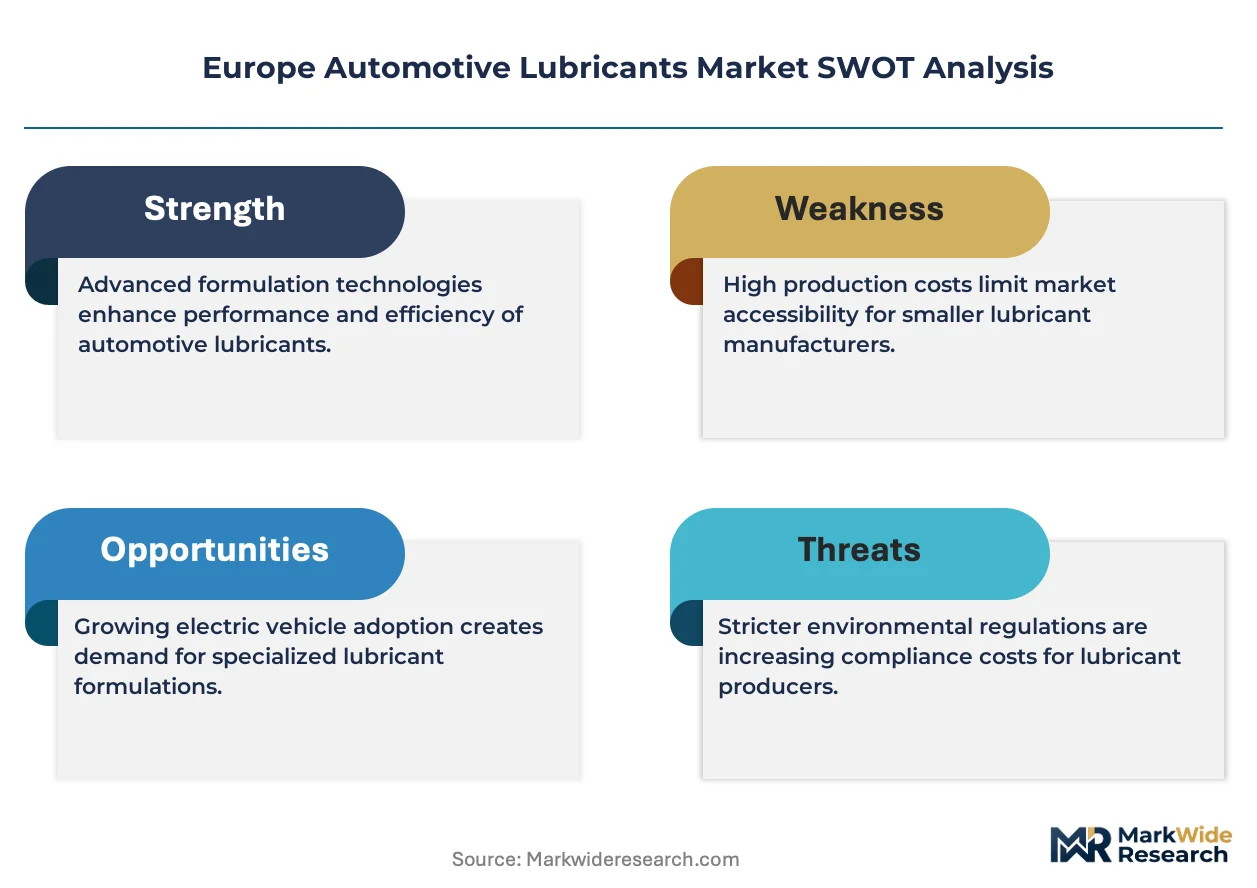
Fleet operator procurement in Europe is consolidating around national and cross-border leasing groups with centralized lubricant sourcing. TotalEnergies SE leverages its integrated refining and additive operations to secure multi-year supply agreements with these consolidated buyers. FUCHS SE anchors its position through specialized industrial lubricant expertise that extends into heavy-duty automotive applications. BP plc competes by embedding itself within OEM-approved service networks across the United Kingdom and Continental Europe.
Automotive lubricants are formulated base oil and additive packages engineered to reduce friction, dissipate heat, and prevent wear in powertrain and chassis systems, with SAE viscosity grades and ACEA performance categories defining operational suitability. Engine oil dominates product type value pools due to high drain frequency and OEM specification complexity, while transmission fluid captures above-average margins through synthetic formulation requirements in dual-clutch and continuously variable transmissions. Passenger cars anchor application volume, though commercial vehicles generate superior per-unit lubricant consumption and service attach rates.
REACH compliance and the EU F-Gas Regulation shape formulation chemistry and labeling requirements for lubricants sold across member states, while ECHA substance restrictions drive substitution of certain additive chemistries. Germany's KBA and France's ANSM enforce national type-approval standards that filter into aftermarket product eligibility. Stakeholders must monitor the interplay between OEM drain interval extension programs and ACEA sequence updates that redefine minimum performance baselines.
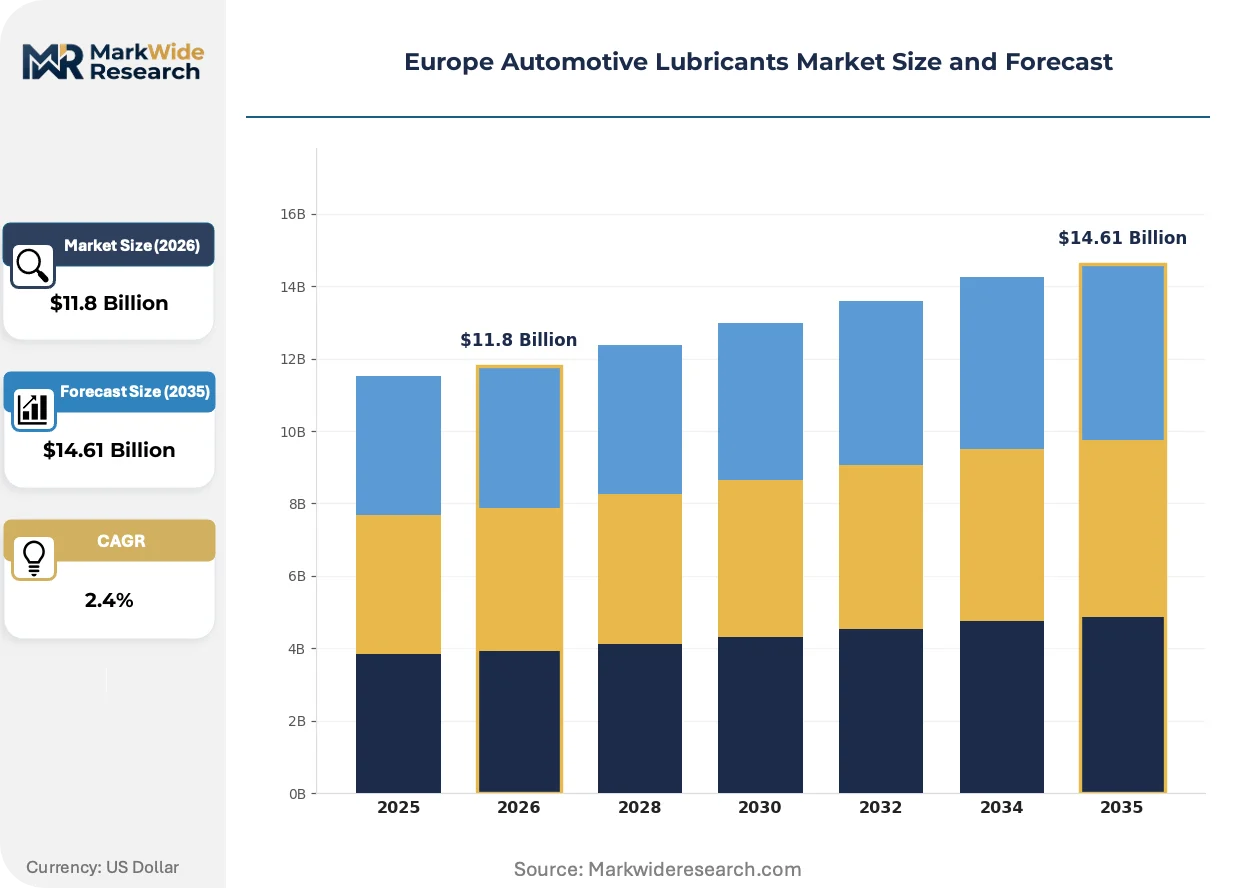
Market Dynamics
Fleet operator consolidation across Germany and France is compressing procurement channels into centralized leasing group tenders, forcing lubricant suppliers to restructure pricing and service bundling around multi-year volume commitments rather than spot transactions.
Growth Catalysts
- ACEA Oil Sequence Updates:The C6 and upcoming C7 specifications mandate lower high-temperature high-shear viscosity thresholds, compelling drain interval extensions that increase synthetic lubricant penetration in passenger car parc.
- Commercial Vehicle Electrification Hybrids:Heavy-duty fleets in Germany's Rhine-Ruhr corridor are deploying PHEV and range-extender architectures that retain internal combustion thermal management needs while adding e-axle lubrication requirements.
- E-Mobility Service Network Expansion:OEM-authorized workshops across France and Italy are retrofitting service bays for battery thermal management fluid exchanges, creating attach-rate opportunities for specialized coolants and dielectric lubricants.
Market Restraints
- API Group III Base Oil Supply Concentration:European refining capacity for high-viscosity-index base stocks concentrates in Rotterdam-Antwerp hub facilities, exposing formulators to single-source disruption risk during turnaround seasons.
- REACH Authorization Timelines:ECHA's substance evaluation backlog for zinc dialkyldithiophosphate alternatives is extending reformulation lead times beyond typical product development cycles.
- Extended Drain Interval Programs:BMW and Mercedes-Benz OEM service protocols now specify 30,000-kilometer engine oil changes for Euro 6d-compliant powertrains, compressing aftermarket volume per vehicle in service.
Strategic Opportunities
- Poland and Czech Republic Fleet Modernization:Cross-border logistics operators headquartered in Poznań and Ostrava are consolidating tractor assets, creating procurement scale for lubricant suppliers with regional blending presence.
- EU Green Deal Carbon Border Adjustments:The CBAM implementation timeline is incentivizing rerefined base oil qualification for scope 3 emissions reporting in automotive OEM supply chains.
- Dual-Clutch Transmission Fluid Conversion:Wet-clutch architectures in Volkswagen Group MQB-platform vehicles are reaching first major service intervals, generating synthetic ATF demand in independent aftermarket channels.
Industry Challenges
- Additive Chemist Talent Pipeline:European universities are producing fewer tribology and lubricant chemistry graduates than retiring formulator cohorts, constraining R&D throughput for ACEA sequence development.
- Legacy Workshop Equipment Retrofit Costs:Independent garages across Spain and Portugal face capital outlays for oil analysis equipment and sealed collection systems required by national waste oil regulations.
- OEM Approval Certification Delays:Volkswagen 508.00/509.00 and Mercedes-Benz 229.71 specification testing protocols are extending time-to-market for new synthetic 0W-20 formulations by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Automotive Lubricants Market |
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $14.61 Billion |
| CAGR (2026 – 2036) | 2.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Transmission Fluid, Brake Fluid, Grease Application: Passenger Cars, Commercial Vehicles, Motorcycles, Heavy-Duty Equipment End User: OEMs, Aftermarket Providers, Service Stations, Fleet Operators Distribution Channel: Online Sales, Retail Stores, Wholesalers, Distributors |
| Companies Covered | Shell plc, BP plc, TotalEnergies SE, ExxonMobil Corporation, FUCHS SE, LUKOIL, Chevron Corporation, Repsol SA, ENI S.p.A., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Automotive Lubricants Market Shifts & Advancements
Reformulation chemistry and service delivery models are diverging as electrification penetrates powertrain architectures while combustion efficiency regulations tighten. Suppliers must now engineer for thermal management complexity and procurement centralization simultaneously.
Polyalkylene glycol-based e-axle lubricants are modularizing thermal management and friction reduction functions previously handled by separate gearbox and motor coolant circuits. Tier 1 suppliers in Stuttgart and Munich are qualifying these fluids for 800-volt architectures ahead of 2025 platform launches. The convergence is compressing SKU portfolios and forcing additive suppliers to integrate dielectric and lubricity performance in single packages.
REACH Annex XIV authorization requirements for polycyclic aromatic hydrocarbon content in extender oils are forcing base oil slate requalification across European blenders. The ECHA restriction tightens allowable PAH thresholds in consumer-accessible products, affecting workshop-packaged chain lubricants and penetrating oils. German KBA type-approval documentation is now requiring third-party PAH testing certificates for aftermarket products seeking OEM service network eligibility.
Centralized procurement portals operated by leasing groups such as Arval and LeasePlan are displacing decentralized workshop purchasing across France and Benelux. Fleet maintenance managers now specify lubricant brands contractually, removing selection autonomy from individual service locations. The shift is most visible in commercial vehicle segments where total cost of ownership reporting requirements drive standardization on synthetic formulations with documented drain interval performance.
Europe Automotive Lubricants Market Segmentation
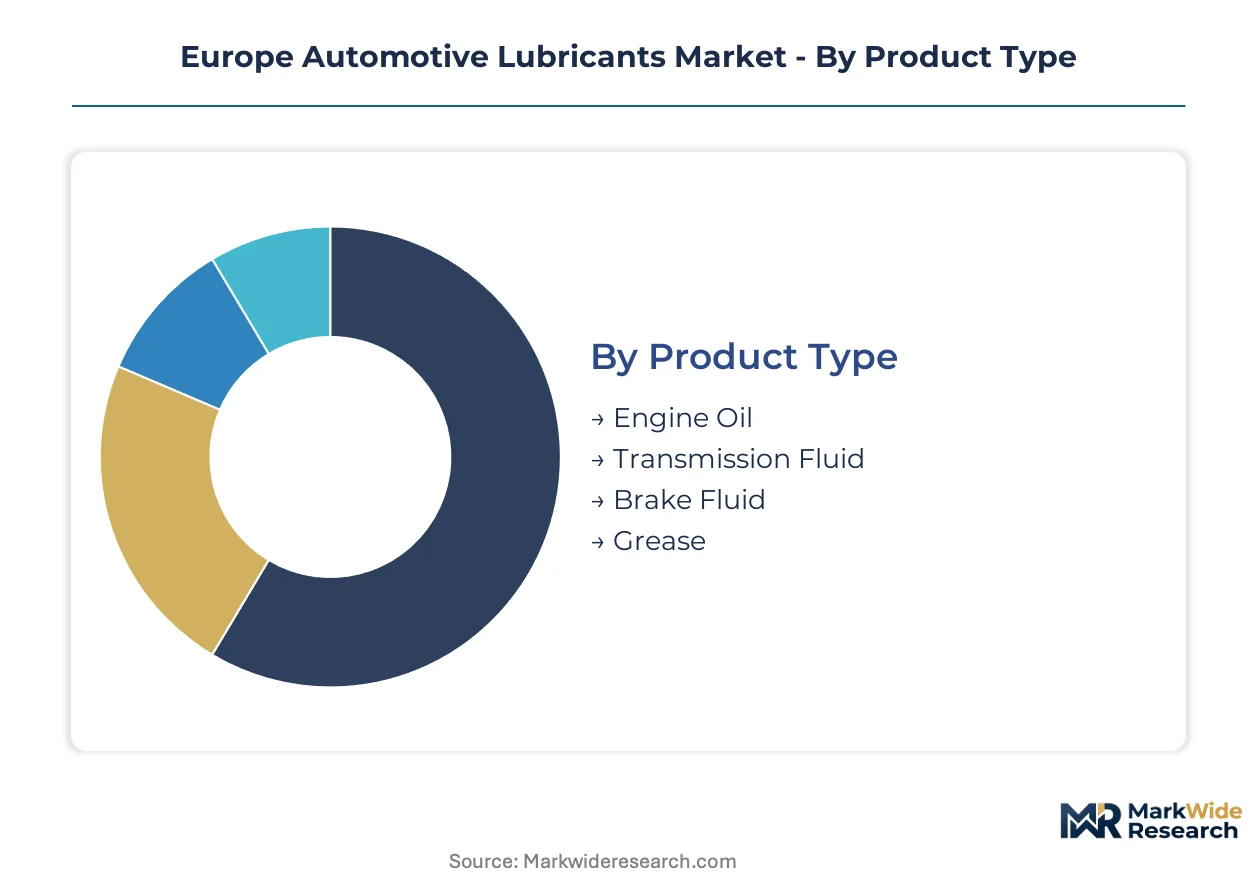
Segmentation in the Europe Automotive Lubricants Market reveals how procurement centralization and powertrain electrification are reshaping volume distribution across product categories. Suppliers must align portfolio depth with the diverging requirements of fleet operators consolidating around synthetic formulations and OEM service networks managing hybrid thermal architectures.
Product Type:
Integration depth varies sharply across lubricant categories, with standalone combustion-engine products facing displacement while embedded-system fluids gain specification complexity.
- Engine Oil:Formulated from Group II/III base stocks with detergent-dispersant and anti-wear additive packages meeting ACEA C5/C6 sequences for low-speed pre-ignition protection. Demand concentrates in Germany's commercial vehicle corridor where fleet operators specify 5W-30 and 0W-20 synthetics for extended drain intervals under centralized procurement contracts.
- Transmission Fluid:Synthetic formulations for dual-clutch and continuously variable transmissions require precise friction modification and shear stability. Wet-clutch architectures in Volkswagen Group vehicles reaching first major service intervals in France and Benelux are driving aftermarket conversion from mineral to synthetic ATF grades.
- Brake Fluid:Glycol-ether based hydraulic fluids meeting DOT 4 and DOT 5.1 specifications for high-temperature performance in ABS and ESP systems.
- Grease:Lithium-complex and polyurea-thickened lubricants for chassis, wheel bearing, and universal joint applications in heavy-duty fleets.
Engine oil leads volumes today; transmission fluid is gaining share fastest.
Application:
Customer concentration patterns split the market between high-volume passenger car parc maintenance and premium-margin commercial vehicle service attach rates.
- Passenger Cars:Light-duty vehicles dominate lubricant volume through high parc density and frequent service intervals, though per-unit consumption is compressing as OEM drain extension programs take hold across Euro 6d-compliant fleets.
- Commercial Vehicles:Heavy-duty trucks and buses generate superior per-unit lubricant consumption through larger sump capacities and severe-duty operating cycles. PHEV and range-extender deployments in Germany's Rhine-Ruhr logistics corridor are adding e-axle thermal management requirements to traditional engine and transmission needs.
- Motorcycles:Small-displacement two-wheelers in Italy and Spain use dedicated 10W-40 and 15W-50 formulations with wet-clutch compatibility.
- Heavy-Duty Equipment:Construction and agricultural machinery in Poland and Czech Republic require high-viscosity hydraulic fluids and universal tractor transmission oils.
Commercial vehicles command the steepest expansion trajectory as fleet modernization accelerates in Central European logistics hubs.
End User:
Procurement autonomy is migrating from decentralized service locations toward centralized decision-makers with total cost of ownership reporting mandates.
- OEMs:Vehicle manufacturers specify factory-fill lubricants for new production and captive service networks, with approval protocols like Volkswagen 508.00/509.00 and Mercedes-Benz 229.71 creating 18-24 month certification barriers for new synthetic formulations.
- Aftermarket Providers:Independent distributors and private-label suppliers compete on price-positioned mineral and semi-synthetic grades for legacy vehicle parc.
- Service Stations:Workshop networks face capital outlays for oil analysis equipment and sealed waste collection systems under national environmental regulations.
- Fleet Operators:Leasing groups including Arval and LeasePlan now specify lubricant brands contractually, removing selection autonomy from individual service locations across France and Benelux.
Fleet operators are capturing procurement share most aggressively; service stations face margin pressure from standardization mandates.
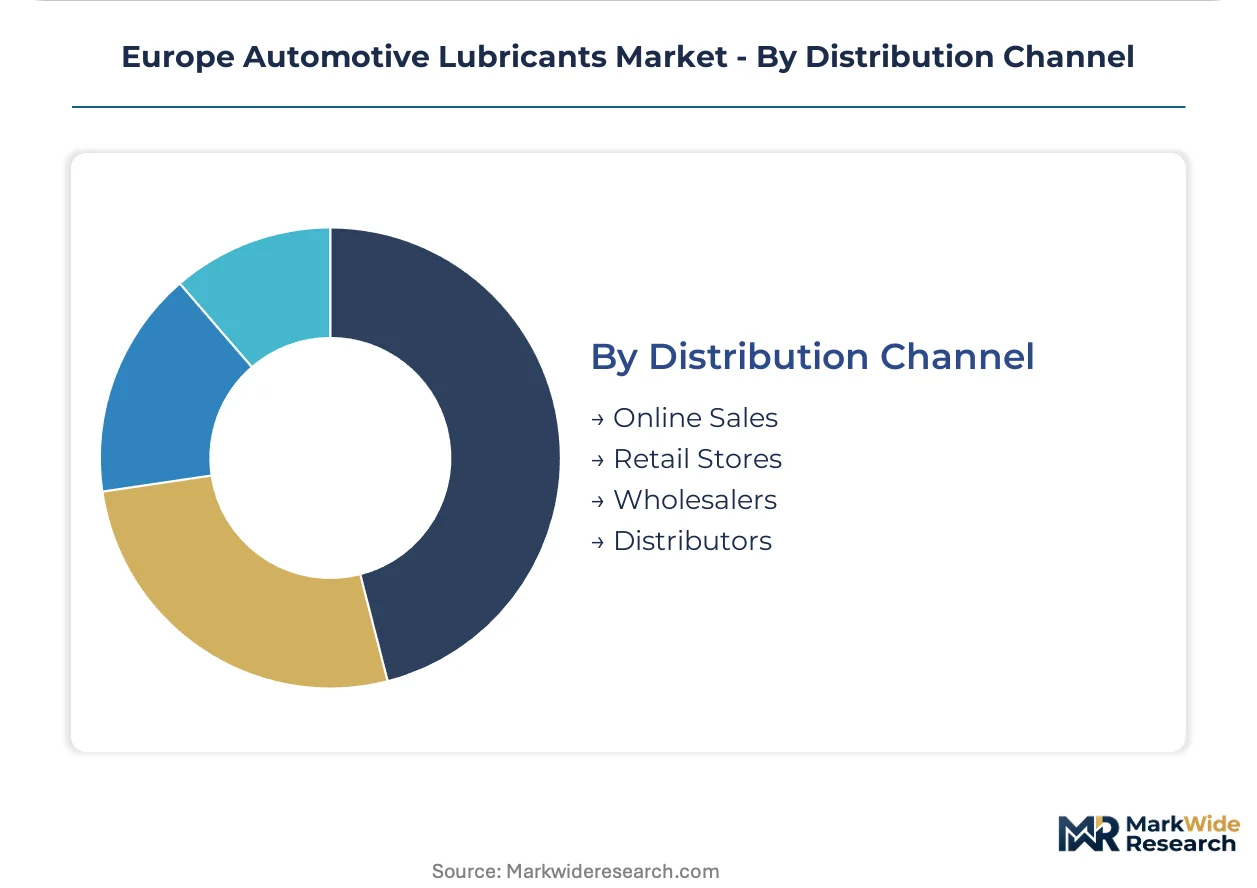
Distribution Channel:
Channel structure reflects the tension between bulk logistics efficiency for consolidated buyers and fragmented accessibility for independent workshops.
- Online Sales:E-commerce platforms are displacing traditional ordering for small workshops and DIY consumers, though bulk fleet contracts remain relationship-driven.
- Retail Stores:Automotive parts chains serve the independent aftermarket with packaged consumer quart and liter formats.
- Wholesalers:Regional distributors blend and package lubricants for local specification requirements, particularly in Spain and Portugal.
- Distributors:National and cross-border logistics operators manage drum and tote deliveries to fleet maintenance depots and OEM-authorized workshops.
Distributors anchor volume throughput; online sales are climbing the fastest as procurement digitization penetrates smaller service accounts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tribology and lubricant chemistry graduates concentrate in German and French university clusters, anchoring Europe's formulation R&D infrastructure while Central European logistics hubs expand fleet modernization programs.
Germany
Rhine-Ruhr logistics operators deploy PHEV and range-extender heavy-duty fleets that retain combustion thermal management needs while adding e-axle lubrication requirements. KBA type-approval standards enforce national documentation requirements that filter into aftermarket product eligibility. Stuttgart and Munich host Tier 1 suppliers qualifying polyalkylene glycol-based e-axle lubricants for 800-volt architectures ahead of platform launches.
France
ANSM enforces national type-approval standards alongside EU REACH compliance for lubricant formulations sold across member states. Arval and LeasePlan leasing groups operate centralized procurement portals that specify lubricant brands contractually, removing selection autonomy from individual service locations. Paris and Lyon anchor fleet maintenance networks where synthetic formulation standardization dominates commercial vehicle segments.
United Kingdom
OEM-authorized workshop networks embed approved lubricant suppliers within service protocols across Greater London and Midlands industrial corridors. BP plc competes through captive service network relationships rather than spot market transactions. Birmingham and Manchester host independent distributors facing capital outlays for oil analysis equipment under national waste oil regulations.
Poland
Poznań-based cross-border logistics operators consolidate tractor assets, creating procurement scale for lubricant suppliers with regional blending presence. EU Green Deal carbon border adjustments incentivize rerefined base oil qualification for scope 3 emissions reporting. Warsaw and Krakow industrial zones attract distributors managing drum deliveries to fleet maintenance depots.
Italy
OEM-authorized workshops retrofit service bays for battery thermal management fluid exchanges, creating attach-rate opportunities for specialized coolants and dielectric lubricants. ECHA substance restrictions drive substitution of certain additive chemistries in formulations sold across the peninsula. Turin and Milan anchor automotive service networks where wet-clutch architectures reach first major service intervals.
Europe Automotive Lubricants Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across a consolidated supplier base where multi-year fleet contracts displace spot transactions. Integrated refining and additive operations secure volume commitments from centralized leasing group tenders. Three archetypes dominate: integrated energy majors with captive base oil supply, specialized industrial lubricant formulators with heavy-duty expertise, and national oil companies with regional distribution density. Competitive moves center on backward integration into additive manufacturing and geographic expansion through regional blending assets.
Among integrated energy majors, Shell plc and BP plc occupy positions defined by captive supply chain control and OEM network embedding. TotalEnergies SE exemplifies the integrated refining archetype through multi-year supply agreement structures. FUCHS SE anchors the specialized industrial lubricant tier with expertise extending into heavy-duty automotive applications. These three companies represent the competitive spectrum from scale-driven energy integration to focused formulation specialization.
| Leading Market Players |
|---|
| Shell plc |
| BP plc |
| TotalEnergies SE |
| ExxonMobil Corporation |
| FUCHS SE |
| LUKOIL |
| Chevron Corporation |
| Repsol SA |
| ENI S.p.A. |
| Others |
Supply & Pricing Matrix
Group III base oil spot indices in the Rotterdam-Antwerp hub cascade through European lubricant supply chains into three distinct pricing tiers: premium synthetic formulations for OEM approvals, mid-grade synthetics for fleet contracts, and economy mineral grades for independent aftermarket channels. Fleet procurement centralization compresses margins on standard products while dielectric e-axle fluids and low-viscosity ACEA C6 formulations sustain premium capture.
Pricing Analysis
Capacity additions in Poland and Czech Republic are reshaping price floors for mid-tier synthetic formulations as regional blending assets reduce logistics premiums for Central European fleet operators. Pricing stratifies across premium, standard, and economy tiers based on ACEA sequence certification level and volume commitment scale. Cost compression in the economy tier intensifies because rerefined base oil qualification under EU Green Deal carbon reporting requirements accelerates supply-side substitution. Fleet operators with multi-year contracts exhibit lowest price sensitivity; independent workshops purchasing packaged quarts show highest sensitivity.
Supply Chain Analysis
Regional distribution centers in Germany, Netherlands, and Belgium anchor hub-and-spoke patterns that feed drum and tote deliveries to fleet maintenance depots across the Rhine-Ruhr corridor and Benelux logistics networks. API Group II and Group III base stocks draw from Rotterdam-Antwerp refining clusters, while polyalkylene glycol e-axle fluid feedstocks rest on specialized chemical manufacturing in Germany. Single-source vulnerability concentrates in high-viscosity-index base oil supply during seasonal turnaround windows. Distribution runs through national logistics operators managing bulk deliveries to OEM-authorized workshops and centralized fleet depots.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in Europe automotive lubricants hinges on synthetic formulation penetration in fleet contracts and dielectric fluid attach rates in hybrid thermal management systems. Cost-down drivers include rerefined base oil integration and regional blending footprint optimization.
For Market Incumbents: Deploy captive additive manufacturing capabilities to defend formulation exclusivity against emerging private-label suppliers gaining share through price-positioned mineral grades. Secure backward integration into rerefined base oil qualification to meet OEM scope 3 emissions reporting requirements. Anchor multi-year supply agreements with consolidating leasing groups before tender windows close. For New Entrants and Emerging Players: Polyalkylene glycol-based e-axle lubricants for 800-volt architectures offer technology-first entry into hybrid thermal management segments where incumbent certification lags platform launch timelines. Target Poland and Czech Republic fleet modernization programs where regional blending presence creates procurement scale without legacy infrastructure investment. Pursue toll-blending partnerships with established distributors to bypass capital-intensive base oil storage requirements. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized additive suppliers holding dielectric-lubricity integrated packages qualified for 800-volt architectures ahead of volume ramp. Five-to-ten year viability favors formulators with ACEA sequence development pipelines and captive rerefined base oil supply. Monitor Volkswagen and Mercedes-Benz OEM approval certification timelines as inflection indicators for synthetic 0W-20 market access.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Additive Manufacturing | Captive supply of detergent-dispersant packages reduces ECHA authorization timeline exposure for zinc dialkyldithiophosphate alternatives. |
| Regional Blending Capacity Expansion | Poland and Czech Republic assets capture cross-border logistics fleet procurement consolidating around Poznań and Ostrava hubs. |
| E-Axle Lubricant Qualification Programs | Polyalkylene glycol formulations for 800-volt architectures secure attach-rate positioning ahead of Stuttgart and Munich platform launches. |
| Long-Term Fleet Supply Agreements | Multi-year contracts with Arval and LeasePlan remove selection autonomy from individual service locations across France and Benelux. |
| Rerefined Base Oil Certification Investment | EU Green Deal carbon border adjustments incentivize scope 3 emissions reporting compliance in automotive OEM supply chains. |
Research Methodology
Bottom-up fleet operator and OEM service network modeling reconciled against top-down base oil production and additive supply tracking forms the analytical core of this study. Primary interviews with lubricant formulators, fleet procurement managers, OEM platform engineers, and aftermarket distributors combined with secondary validation from ACEA oil sequence documentation, ECHA substance restriction filings, and national KBA and ANSM type-approval registries. Customs data on Group II/III base oil trade flows and vehicle parc registration databases provided supply-side and demand-side triangulation anchors.
Input-output matrices map lubricant consumption per vehicle class against powertrain architecture penetration, drain interval extension programs, and synthetic formulation conversion rates across the projection horizon. Segmentation dimensions include product type, application category, end-user procurement structure, and distribution channel format. CAGRs derive from regression analysis of historical volume patterns adjusted for ACEA sequence update impacts and electrification-driven thermal management fluid demand. Forecast inputs incorporate OEM drain interval protocols and fleet modernization investment cycles without year-specific assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to REACH authorization timelines for additive chemistry substitutions and commercial vehicle electrification adoption curves. Outputs reflect documented assumptions around base oil supply concentration and procurement centralization velocity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
South Africa Automotive Hydraulic Actuators Market
Automotive Parts
Global Automotive Parts Remanufacturing Market
Automotive Parts
Mexico Automotive Parts Aluminum Die Casting Market
Automotive Parts
Automotive Washer System Market
Automotive Parts
Automotive Variable Valve Timing Market
Automotive Parts
Malaysia Passenger Vehicles Lubricants Market
Automotive Parts
Speed Bump Market
Automotive Parts
Automotive Electric Vacuum Pump Market
Automotive Parts
Germany Automotive Parts Aluminium Die Casting Market
Automotive Parts
Automotive Parts Die Casting Market
Automotive Parts
Germany Automotive Hydraulic Actuators Market
Automotive Parts
Passenger Car Motor Oil Market
Automotive Parts
Australia Automotive Airfilters Market
Automotive Parts
Middle East Automotive Lubricants Market
Automotive Parts
Automotive Oil Pressure Switch Market
Automotive Parts
Brake Shoe Market