
 Middle East Passenger Vehicles Lubricants Market | 2026-2036
Middle East Passenger Vehicles Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Passenger Vehicles Lubricants Market Foresight
Preventive maintenance subscriptions is decoupling lubricant sales from pure product transactions in the Middle East passenger vehicle ecosystem. Petromin Corporation leverages its Saudi service station network to bundle oil changes with digital fleet monitoring. ADNOC anchors supply security through in-house base oil production at Ruwais. Royal Dutch Shell Plc competes via synthetic formulation leadership tailored to Gulf climate extremes.
Middle East passenger vehicle lubricants are formulated hydrocarbon blends designed to reduce friction, dissipate heat, and prevent wear in internal combustion engines operating at ambient temperatures exceeding 50°C, with viscosity grades typically spanning SAE 0W-20 to 15W-40. Their primary commercial purpose is to extend engine life and maintain fuel efficiency under severe thermal stress. Engine oil dominates value capture given its higher replacement frequency and premium synthetic migration, while bio-based formulations represent the fastest-growing niche as environmental compliance tightens. Service stations retain the largest volume channel for immediate-consumption purchases, though distributor networks control bulk fleet supply.
Saudi Arabia's SFDA enforces lubricant quality standards aligned with API and ACEA specifications, while the UAE's MOHAP implements environmental discharge protocols affecting waste oil handling. Both frameworks elevate compliance costs for mineral oil suppliers and accelerate synthetic substitution. Stakeholders must monitor how evolving fuel economy regulations and electric vehicle penetration reshape lubricant demand intensity across the Gulf Cooperation Council.
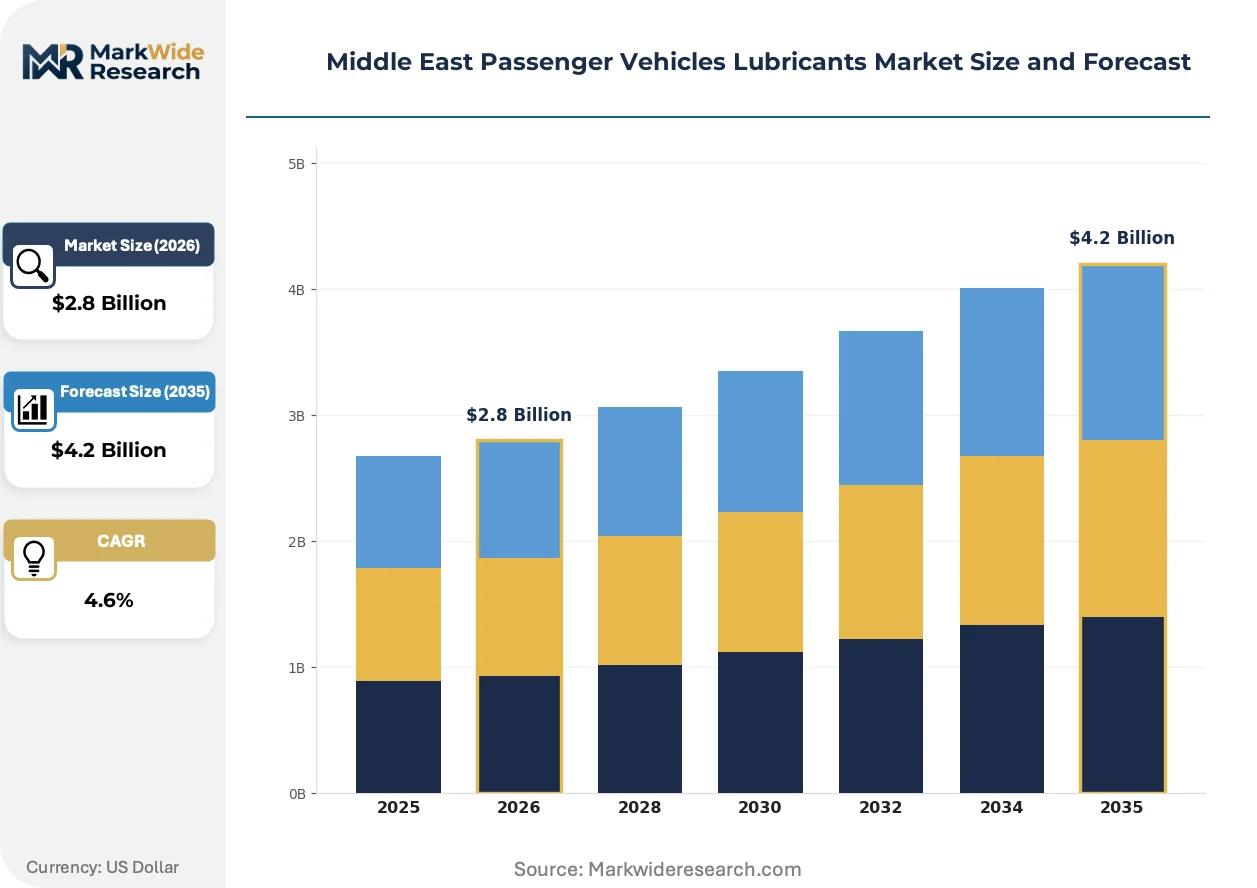
Market Dynamics
Fleet operators across the GCC now prioritize extended-drain synthetic formulations to minimize vehicle downtime in high-temperature operating environments exceeding 50°C ambient conditions.
Growth Catalysts
- SFDA Quality Mandates:Saudi Arabia's lubricant standards aligned with API and ACEA specifications are accelerating synthetic substitution among mineral oil suppliers.
- Fleet Digitization:Service station networks are bundling oil changes with real-time vehicle monitoring systems to lock in recurring lubricant volumes.
- Ruwais Base Oil Capacity:In-house production of Group II and III base stocks at the UAE's refining complex is reducing import dependency for regional blenders.
Market Restraints
- Group III Base Oil Concentration:Middle East supply chains depend heavily on Ruwais and Bahrain-based refiners, creating geographic vulnerability to single-source disruption.
- API SP/GF-6 Compliance Costs:Low-speed pre-ignition testing requirements for newer passenger vehicle engines are raising formulation expenses for smaller regional blenders.
- Electric Vehicle Penetration:Battery electric powertrains eliminate engine oil demand entirely, threatening long-term volume in UAE and Saudi Arabian urban corridors.
Strategic Opportunities
- Oman and Kuwait Fleet Markets:Underpenetrated distributor networks in these GCC states offer first-mover advantage for bulk synthetic supply contracts.
- MOHAP Waste Oil Protocols:UAE environmental discharge regulations are creating certified recycling infrastructure opportunities for closed-loop lubricant services.
- Bio-based Formulation Convergence:Estolide and plant-derived base stocks combined with additive packages from renewable feedstocks are opening premium positioning channels.
Industry Challenges
- ACEA C5/C6 Certification Timelines:Extended laboratory testing periods for low-viscosity, high-temperature-high-shear formulations are delaying product launches by 18-24 months.
- Legacy Fleet Heterogeneity:Service stations must stock SAE 0W-16 through 20W-50 grades simultaneously to cover Japanese, European, and American vehicle populations in the same catchment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Passenger Vehicles Lubricants Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Transmission Fluid, Brake Fluid, Coolant Formulation: Semi-Synthetic, Synthetic, Mineral, Bio-Based Packaging Type: Drums, Bottles, Cartons, Bulk Sales Channel: Retail, Online, Distributors, Service Stations |
| Companies Covered | Petromin Corporation, Behran Oil Company, ADNOC, Royal Dutch Shell Plc, Iranol Oil Company, Sepahan Oil Company, TotalEnergies, BP PLC (Castrol), ExxonMobil Corporation, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Passenger Vehicles Lubricants Market Shifts & Advancements
Synthetic formulation chemistry and digital service integration are compressing replacement cycles while elevating performance specifications for Gulf climate extremes.
Polyalphaolefin (PAO) and ester-based full synthetics is overtaking mineral and semi-synthetic grades in the 0W-20 and 5W-30 viscosity classes. Premium fleet operators in Saudi Arabia's Riyadh-Jeddah corridor are mandating 15,000-kilometer drain intervals, forcing independent workshops to upgrade inventory. This technology is compressing the addressable market for conventional Group I base oils to legacy vehicle segments only.
MOHAP's environmental discharge protocols for waste oil handling are mandating certified collection and re-refining infrastructure across the UAE. Blenders must now document chain-of-custody from drain to reprocessing facility, adding compliance overhead. Workshop networks in Dubai and Abu Dhabi are responding by partnering with licensed hazardous waste operators to retain service licenses.
Fleet procurement departments are consolidating lubricant purchasing through annual framework agreements with integrated service providers. Independent distributors serving smaller workshops are losing volume to direct manufacturer relationships with large transport operators. This concentration is most visible in Saudi Arabia's long-haul trucking sector, where Aramco-authorized service centers are capturing bulk engine oil demand.
Middle East Passenger Vehicles Lubricants Market Segmentation
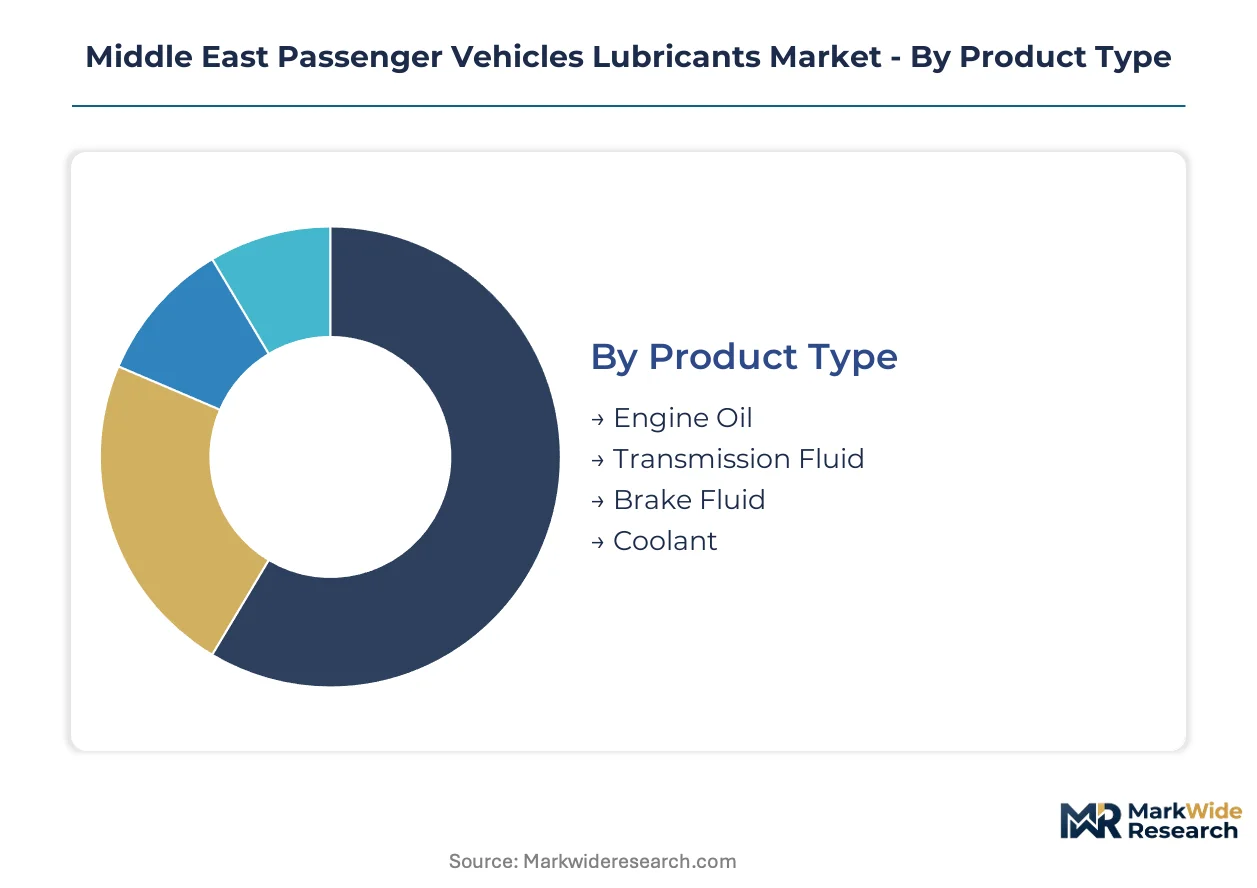
Passenger vehicle lubricant procurement across the Middle East fragments across four distinct segmentation axes. Product type and formulation chemistry drive technical specification, while packaging and channel structure determine last-mile economics and customer access patterns.
Product Type:
Standardization dominates high-volume categories with universal API specifications, while specialized fluids demand vehicle-specific formulation matching.
- Engine Oil:Hydrocarbon-based formulations spanning SAE 0W-20 to 15W-40 viscosity grades engineered for friction reduction and thermal stability. Fleet operators in Saudi Arabia's Riyadh-Jeddah corridor mandate 15,000-kilometer drain intervals, compressing replacement cycles and elevating synthetic penetration.
- Transmission Fluid:ATF and CVT-specific chemistries with distinct friction modification profiles for automatic versus continuously variable transmissions. Demand concentrates in UAE urban corridors where Japanese vehicle populations require OEM-matched fluid specifications.
- Brake Fluid:Glycol-ether and silicone-based formulations meeting DOT 3, DOT 4, and DOT 5.1 boiling point specifications for hydraulic brake systems.
- Coolant:Ethylene glycol and propylene glycol blends with corrosion inhibitor packages for aluminum engine block protection.
Leading the category by volume: Engine Oil. Growing fastest: Transmission Fluid.
Formulation:
Cost tiers stratify sharply between commodity mineral bases and premium synthetic chemistries, with bio-based positioning emerging at the premium edge.
- Semi-Synthetic:Group II/III base oil blends combining mineral feedstocks with synthetic additives for mid-tier performance positioning. Independent workshops across Dubai and Abu Dhabi stock these formulations as the default upgrade from mineral grades for vehicles aged 5-10 years.
- Synthetic:PAO and ester-based full synthetics delivering extended drain intervals and high-temperature-high-shear stability. SFDA-aligned quality mandates in Saudi Arabia are accelerating substitution as fleet operators eliminate mineral inventory.
- Mineral:Group I base oil formulations refined from crude petroleum with basic additive packages for legacy vehicle segments.
- Bio-Based:Estolide and plant-derived base stocks combined with renewable feedstock additives for environmental compliance positioning.
Volume leadership: Synthetic. Steepest expansion trajectory: Bio-Based.
Packaging Type:
Scale economics separate industrial bulk procurement from retail-ready formats serving fragmented workshop demand.
- Drums:200-liter steel containers for fleet and distributor bulk handling with pump dispensing systems.
- Bottles:1-liter to 5-liter polyethylene terephthalate and HDPE containers for retail shelf and immediate workshop consumption.
- Cartons:Multi-pack configurations for retail promotion and e-commerce shipment efficiency.
- Bulk:Tanker and flexitank delivery for integrated service station networks and large fleet direct supply.
Dominant by throughput: Bulk. Gaining share fastest: Bottles.
Sales Channel:
Customer type and purchase urgency dictate channel selection, with service integration eroding pure product transactions.
- Service Stations:Integrated oil change and maintenance facilities capturing immediate-consumption demand through bundled labor and parts. Petromin Corporation's Saudi network and ADNOC-authorized centers leverage real-time fleet monitoring to lock recurring volumes.
- Distributors:Regional wholesalers controlling bulk fleet supply and independent workshop penetration across underpenetrated Oman and Kuwait markets.
- Retail:Automotive parts stores and hypermarkets serving DIY consumers and small workshop cash purchases.
- Online:E-commerce platforms and lubricant-specific marketplaces with delivery logistics for remote and price-sensitive segments.
Channel leader by volume: Service Stations. Expanding most quickly: Online.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regional production concentrates in the UAE's Ruwais refining complex, while consumption gravity pulls toward Saudi Arabia's vehicle-dense urban corridors. This supply-demand asymmetry shapes cross-border trade flows and distributor network economics across the Gulf Cooperation Council.
Saudi Arabia
Fleet operators in the Riyadh-Jeddah corridor mandate 15,000-kilometer drain intervals under severe thermal stress exceeding 50°C ambient conditions. The Saudi Food and Drug Authority enforces API and ACEA-aligned lubricant quality standards that accelerate synthetic substitution. Aramco-authorized service centers are capturing bulk engine oil demand through integrated maintenance contracts with long-haul trucking operators.
United Arab Emirates
Japanese vehicle populations in Dubai and Abu Dhabi urban corridors drive demand for OEM-matched ATF and CVT fluid specifications. The Ministry of Health and Prevention implements environmental discharge protocols mandating certified waste oil collection and chain-of-custody documentation. ADNOC's in-house Group II and III base oil production at Ruwais reduces import dependency for regional blenders.
Iran
Domestic refiners serve a captive market isolated from international supply chains by trade restrictions. The national petroleum regulator maintains technical specifications for lubricant formulations serving legacy vehicle fleets. Tehran-based distribution networks concentrate volume in the capital's dense vehicle population.
Oman
Underpenetrated distributor networks create first-mover opportunity for bulk synthetic supply contracts targeting emerging fleet operators. The central environmental authority is developing waste oil handling frameworks modeled on UAE protocols. Muscat's port infrastructure positions the Sultanate as a potential re-export hub for lubricants serving regional markets.
Kuwait
Fleet procurement departments are consolidating lubricant purchasing through annual framework agreements with integrated service providers. The national oil company maintains blending capacity serving domestic demand and neighboring markets. Kuwait City's concentrated vehicle population supports immediate-consumption service station networks.
Middle East Passenger Vehicles Lubricants Market Competitive Landscape
Capital-heavy producers with captive base oil refining compete with asset-light formulators dependent on third-party feedstock supply. The vendor base stratifies into three tiers: integrated national oil companies controlling upstream supply, multinational blenders with synthetic formulation leadership, and regional distributors serving fragmented workshop demand. Dominant competitive moves include backward integration into base oil production and service station network expansion to lock recurring volumes.
Within the integrated national oil company tier, Petromin Corporation leverages its Saudi service station network to bundle oil changes with digital fleet monitoring, while ADNOC anchors supply security through Ruwais base oil capacity. Among international blenders, Royal Dutch Shell Plc exemplifies synthetic formulation leadership tailored to Gulf climate extremes. These three entities represent distinct archetypes: captive supply integration, downstream service bundling, and premium technology positioning.
| Leading Market Players |
|---|
| Petromin Corporation |
| Behran Oil Company |
| ADNOC |
| Royal Dutch Shell Plc |
| Iranol Oil Company |
| Sepahan Oil Company |
| TotalEnergies |
| BP PLC (Castrol) |
| ExxonMobil Corporation |
| Others |
Supply & Pricing Matrix
Group II and III base oil costs cascade through three distinct pricing tiers as Ruwais refinery output feeds regional blenders serving fleet operators, independent workshops, and retail channels across the GCC. SFDA-mandated API SP compliance elevates formulation expenses for smaller players, compressing margins at the economy tier while synthetic premiums widen at the fleet-contract level.
Pricing Analysis
Margin tightening in the mineral oil tier reflects SFDA-aligned quality mandates accelerating synthetic substitution. Three-tier pricing structure across premium, standard, and economy levels stratifies by formulation chemistry and certification grade, with PAO-based full synthetics commanding fleet-contract premiums. Cost-down pressure on semi-synthetic mid-tier accelerates because independent workshops in Dubai and Abu Dhabi upgrade inventory to capture drain-interval extensions. Fleet procurement departments exhibit lowest price sensitivity through annual framework agreements, while cash-paying retail consumers in Riyadh-Jeddah corridor workshops drive economy-tier volume.
Supply Chain Analysis
Group II and III base oil supply rests on Ruwais refinery capacity in the UAE and Bahrain-based production, with Iranian domestic refiners serving isolated captive demand. Additive packages, corrosion inhibitors, and viscosity modifiers feed from specialty chemical producers in Germany, Japan, and the United States. Single-source vulnerability concentrates in Ruwais geographic concentration, where disruption would cascade through Saudi and UAE blending operations. Distribution runs through Aramco-authorized service centers and Petromin network stations for fleet capture, with independent distributors controlling workshop penetration in underdeveloped Oman and Kuwait corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where SFDA API and ACEA alignment mandates erect formulation-testing barriers that favor capitalized incumbents with laboratory certification infrastructure.
For Market Incumbents: To counter electric vehicle penetration eliminating engine oil demand in UAE and Saudi urban corridors, deepen synthetic formulation R&D for transmission fluid and coolant diversification while securing backward integration into Ruwais base oil supply through long-term offtake agreements with ADNOC. For New Entrants and Emerging Players: Launch via bulk supply contracts to Omani fleet operators through Muscat port re-export positioning, exploiting underpenetrated distributor networks and emerging environmental authority frameworks modeled on UAE MOHAP protocols to establish closed-loop waste oil collection credentials before compliance mandates tighten. For Investors and Strategic Acquirers: ACEA C5/C6 certification timeline compression is the leading indicator that laboratory-capable mid-tier blenders will consolidate as testing backlogs delay product launches by 18-24 months. Acquisition targets should display captive base oil supply or locked distributor relationships in Kuwait and Oman, with waste oil re-refining infrastructure exposure offering MOHAP-aligned environmental positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base Oil Production | ADNOC's Ruwais capacity eliminates import dependency for regional blenders serving Saudi fleet demand. |
| Synthetic Formulation Certification Investment | API SP and ACEA C5/C6 laboratory capabilities lock out smaller competitors from premium fleet contracts. |
| Service Station Network Expansion | Petromin's Saudi footprint bundles oil changes with digital monitoring to capture recurring lubricant volumes. |
| Waste Oil Re-refining Infrastructure Buildout | MOHAP chain-of-custody requirements create licensed recycling moats for compliant operators in UAE. |
| Regional Distributor Acquisition in Oman and Kuwait | First-mover positioning in underpenetrated bulk fleet markets secures synthetic supply contract pipelines. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, cross-referenced with primary interviews involving lubricant blending plant managers, fleet procurement directors at Saudi long-haul operators, ADNOC technical sales leads, and independent workshop owners across Dubai and Abu Dhabi. Bottom-up volume modeling triangulated against top-down macroeconomic indicators derived from GCC vehicle registration databases and petroleum product trade flows.
Country-level granularity modeled Saudi Arabia, UAE, Iran, Oman, and Kuwait as distinct regulatory and demand clusters, with formulation chemistry, packaging format, and channel structure as cross-cutting segmentation dimensions. CAGRs were derived from trend extrapolation of synthetic penetration rates and fleet digitization adoption curves across the projection horizon, incorporating base oil capacity expansion timelines at Ruwais and electric vehicle penetration scenarios for urban corridor demand erosion.
Regulatory enforcement variance, electric vehicle adoption acceleration, and base oil supply disruption are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions about SFDA and MOHAP implementation timelines, with a small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Camshaft Lifters Market
Automotive Parts
Saudi Arabia Passenger Vehicles Lubricants Market
Automotive Parts
Garage Body Shop Equipment Market
Automotive Parts
Clutch Pedal Kit Market
Automotive Parts
Steel Cords for Radial Tyres Market
Automotive Parts
Global Automotive Cylinder Liner Market
Automotive Parts
South Korea Passenger Vehicles Lubricants Market
Automotive Parts
Germany Automotive Parts Zinc Die Casting Market
Automotive Parts
Global Automotive Flywheel Market
Automotive Parts
Europe Automotive Engine Oils Market
Automotive Parts
United States Automotive Parts Die Casting Market
Automotive Parts
Commercial Vehicle Brake Chambers Market
Automotive Parts
Engine Bearings Market
Automotive Parts
Italy Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Weatherstrips Market
Automotive Parts
Electric Coolant Pump Market