
 Powerglide Shifter Market | 2026-2036
Powerglide Shifter Market Size, Share, and Industry Trends Forecast 2026-2036
Powerglide Shifter Market Analytics
A capital-intensity divergence between players is redrawing competitive boundaries across the Powerglide shifter supply base. Hurst Shifters leverages decades of brand equity in drag racing circles to command premium positioning. TCI Automotive anchors its portfolio with integrated transmission-and-shifter systems that reduce installer complexity. Lokar competes through extensive custom cable and linkage catalogs serving one-off fabrication shops.
A Powerglide shifter constitutes a control interface that translates driver input into gear selection within GM's two-speed automatic transmission architecture, typically incorporating a detent mechanism, neutral safety switch circuit, and either mechanical linkage or electronic solenoid actuation to manage hydraulic valve body positioning. The mechanical technology segment retains dominant installed volume among budget-conscious builders, though electronic variants are capturing share in sanctioned racing where precise shift timing correlates with elapsed-time performance. Aftermarket end users represent the deepest margin pool, as enthusiasts prioritize aesthetic customization and tactile feedback over OEM-grade cost engineering. Installation type stratification shows modular systems growing fastest, since bracket-and-lever kits adapt across diverse floor pan geometries without welding or fabrication.
NHTSA equipment safety standards and EPA emissions compliance frameworks govern street-legal vehicle modifications in the United States, while SAE International publishes dimensional and durability test protocols that manufacturers reference for product validation. The EU's REACH chemicals regulation constrains surface coating formulations for European export shipments, and California Air Resources Board executive orders determine which shifter-controlled transmission combinations qualify for highway use in that state. Stakeholders must monitor evolving electrification timelines from Detroit Three OEMs, since factory EV conversion programs could compress the addressable market for traditional automatic transmission controls.
Market Dynamics
The electrification timeline of Detroit Three OEMs is compressing the addressable window for hydraulic automatic transmission controls, forcing aftermarket suppliers to diversify into electronic shift interfaces while defending legacy mechanical revenue streams.
Growth Catalysts
- Classic restoration demand:Southeastern United States drag racing clusters sustain dense aftermarket parts consumption for period-correct builds.
- REACH compliance adaptation:European coating reformulation requirements are prompting surface treatment innovation that transfers to premium product lines.
- Electronic solenoid actuation:Sanctioned racing circuits are adopting electronically controlled variants for precise shift timing correlation with elapsed-time performance.
Market Restraints
- Steel and aluminum input volatility:Machined lever and bracket components face margin pressure from commodity price swings.
- Single-region supply concentration:Fabrication shop demand clusters heavily in the southeastern United States, creating geographic revenue vulnerability.
- California Air Resources Board executive orders:Shifter-controlled transmission combination approvals for highway use remain restricted, limiting street-legal product configurations.
Strategic Opportunities
- Modular bracket-and-lever kits:Installation systems adapting across diverse floor pan geometries without welding are capturing share from fixed-mount alternatives.
- EPA emissions compliance frameworks:Modified vehicle equipment standards are creating certified product differentiation for electronically controlled variants.
- Hot rod fabrication shop channel:Direct technical support relationships with one-off builders offer margin expansion beyond mass retail distribution.
Industry Challenges
- Hydraulic valve body integration expertise:Talent scarcity in legacy automatic transmission architecture constrains product development velocity.
- SAE International durability validation:Extended test protocol timelines delay new product launches and compress development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Powerglide Shifter Market |
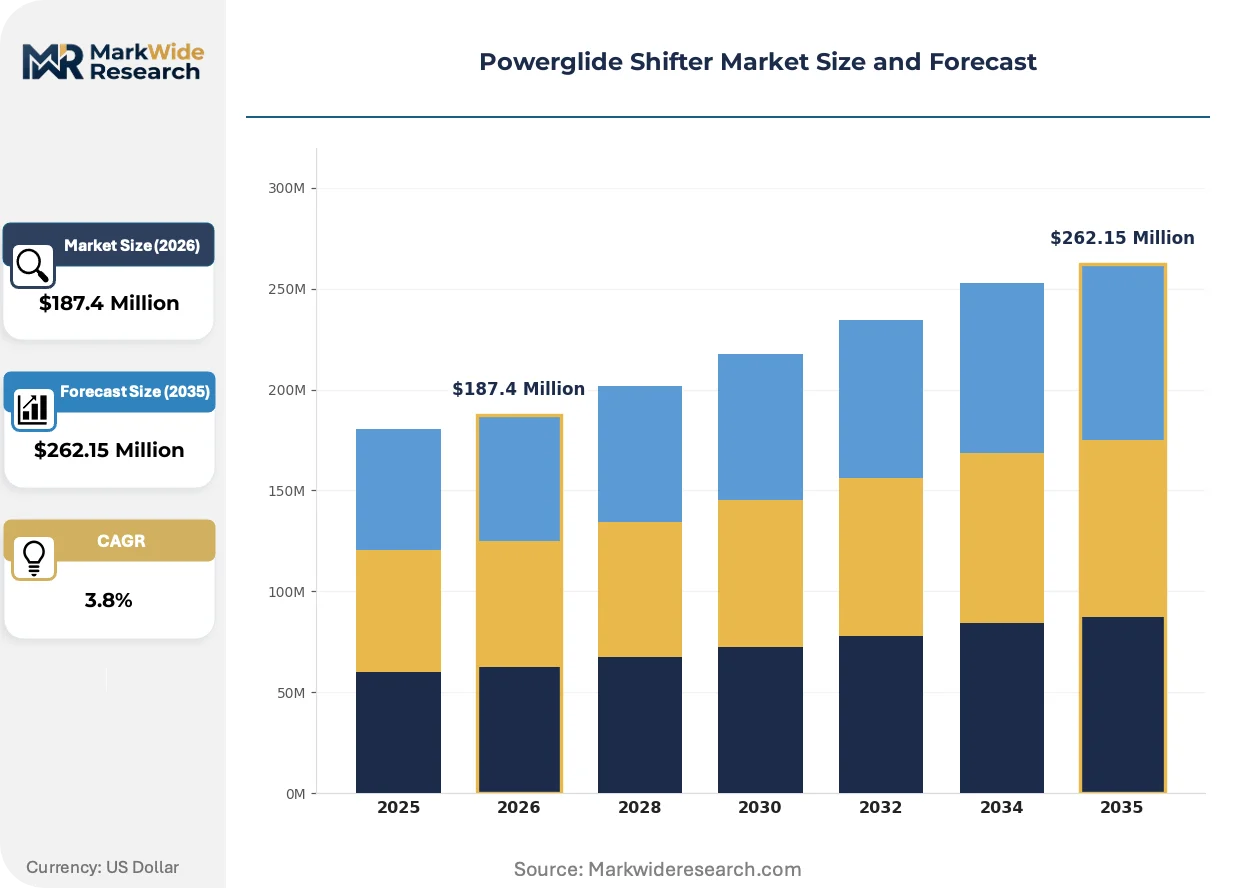
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $262.15 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic, Manual, Semi-Automatic, Sequential Technology: Electronic, Mechanical, Hydraulics, Pneumatics End User: Racers, Enthusiasts, OEMs, Aftermarket Installation: Standard, Custom, Modular, Integrated |
| Companies Covered | Hurst Shifters, Lokar, TCI Automotive, B&M Racing, American Shifter Company, Shiftworks Inc., Barton Industries, ATI Performance Products, Hughes Performance, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Powerglide Shifter Market Evolving Landscape
Powerglide shifter technology is bifurcating between heritage mechanical systems and electronically actuated interfaces, with regulatory pressure and racing performance requirements driving parallel development tracks.
Electronic solenoid actuation is fragmenting the competitive landscape between legacy mechanical suppliers and emerging controls specialists. Drag racing sanctioning bodies are adopting electronic variants for championship-level competition. This shift is fragmenting installed base loyalty as builders reassess supplier relationships based on calibration support capabilities rather than brand heritage alone.
NHTSA equipment safety standards are tightening neutral safety switch circuit requirements for street-legal modified vehicles. Manufacturers must redesign electrical harness integration points to satisfy updated validation protocols. Aftermarket end users in California face the most restrictive compliance pathway due to overlapping state and federal equipment mandates.
Builder procurement is migrating from catalog distributors toward direct manufacturer technical support channels. One-off fabrication shops now prioritize application engineering consultation over price minimization. This behavioral shift concentrates most visibly in the southeastern United States where hot rod build density supports dedicated field representation.
Powerglide Shifter Market Segmentation
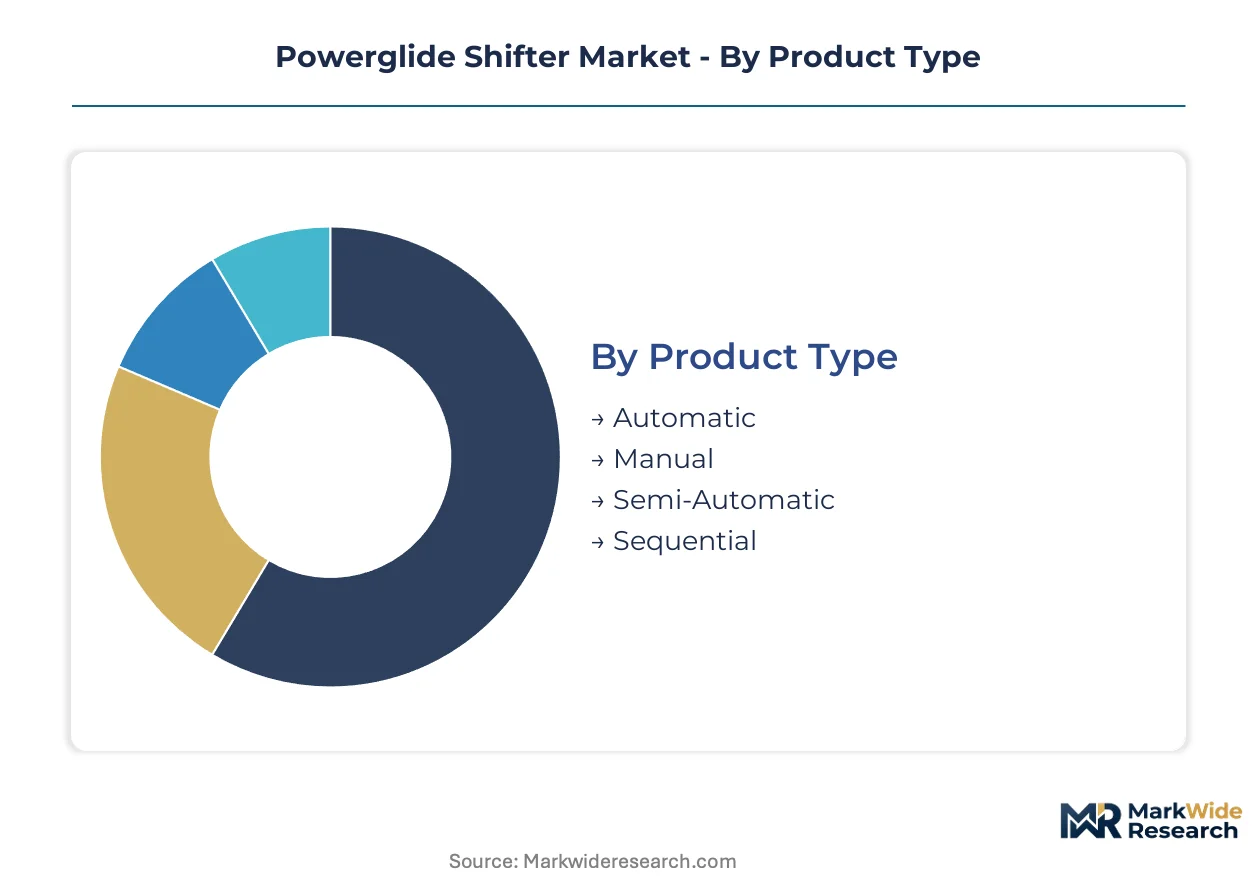
Powerglide shifter procurement patterns diverge sharply across builder archetypes, from sanctioned racers demanding millisecond shift precision to restoration purists prioritizing period authenticity. Segmentation clarity enables suppliers to align R&D spend with margin concentration rather than volume alone.
Product Type:
Automatic variants command the deepest margin pools, driven by drag racing sanctioning body adoption and the complexity premium for two-speed hydraulic control interfaces.
- Automatic:Two-speed hydraulic architecture with detent mechanism and neutral safety circuit integration. Demand concentrates in southeastern United States bracket racing circuits where elapsed-time consistency determines competitive outcomes. Builders pay premiums for valve body calibration support.
- Manual:Mechanical gate selection with H-pattern or linear detent configurations. Enthusiast restorers in California and Texas drive specification for period-correct interior aesthetics, though CARB compliance constraints limit street-legal configurations.
- Semi-Automatic:Clutchless manual actuation blending driver control with automated clutch engagement.
- Sequential:Linear gear selection via ratchet mechanism, common in road course applications.
Automatic holds installed capacity. Sequential is rotating up the share rankings.
Technology:
Electronic solenoid architectures are climbing the fastest as EPA emissions frameworks and racing performance standards converge on programmable shift control.
- Electronic:Solenoid-actuated valve body positioning with CAN bus integration and programmable shift scheduling. Sanctioned racing circuits in Florida and Georgia are mandating electronic variants for championship eligibility, fragmenting supplier relationships around calibration expertise.
- Mechanical:Cable or rod linkage translating lever motion to hydraulic valve body. Budget-conscious builders in North Carolina and Tennessee fabrication clusters sustain volume for heritage systems.
- Hydraulics:Direct hydraulic line pressure manipulation for shift actuation.
- Pneumatics:Compressed air-assisted shift force reduction, rare in consumer applications.
Mechanical retains volume leadership. Electronic is gaining share fastest.
End User:
Aftermarket channels generate superior margin capture through aesthetic customization and technical consultation premiums.
- Racers:Sanctioned competition participants requiring SAE durability validation and sanctioning body certification. Drag racing organizations in South Carolina and Alabama specify electronic variants with data logging integration.
- Enthusiasts:Hobbyist builders prioritizing tactile feedback and interior customization. Direct manufacturer technical support relationships are displacing catalog distributor procurement in Georgia and Florida hot rod clusters.
- OEMs:Original equipment manufacturers for limited-production specialty vehicles.
- Aftermarket:Parts distributors and specialty retailers serving non-competition builds.
Enthusiasts anchor revenue contribution. Racers are expanding the steepest expansion trajectory.
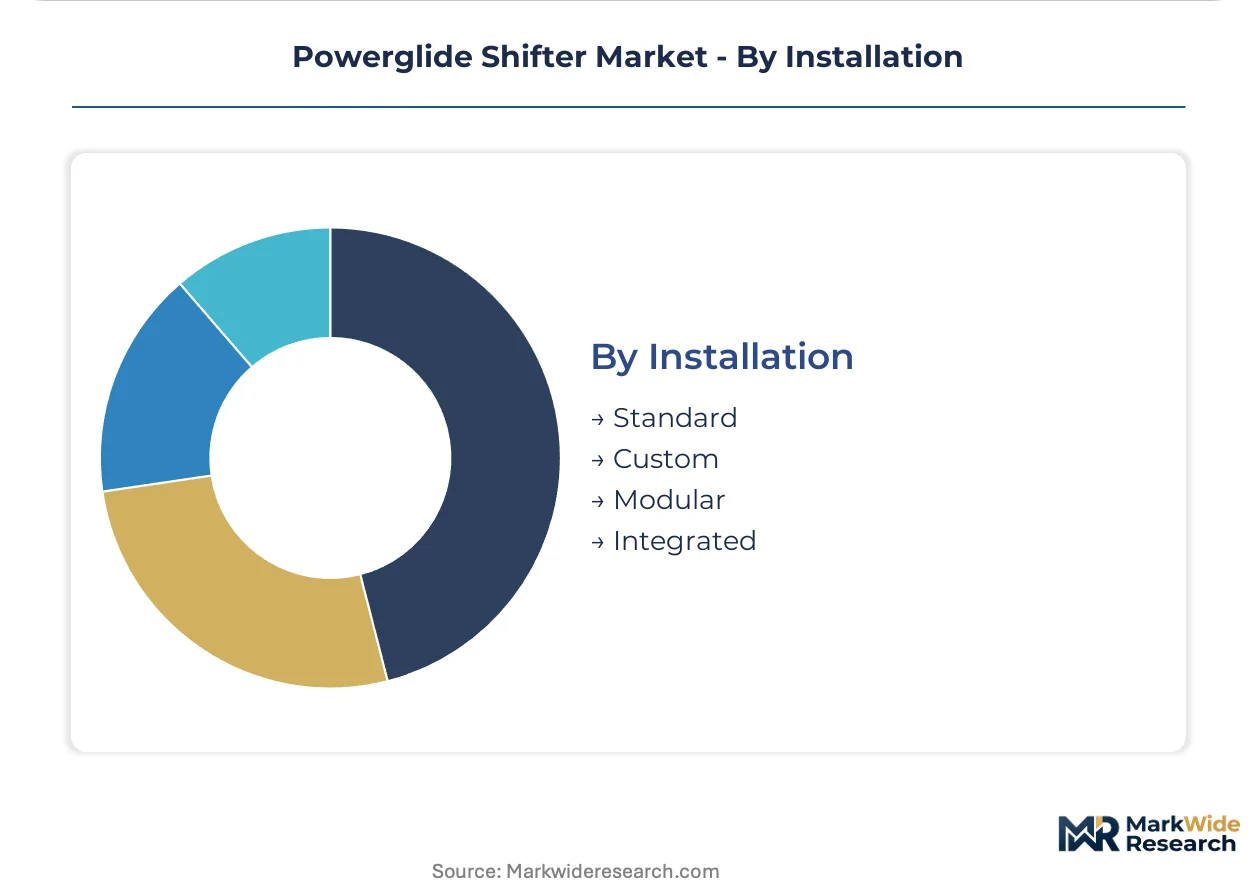
Installation:
Modular systems are capturing disproportionate margin expansion by reducing skilled labor requirements for diverse floor pan geometries.
- Modular:Bracket-and-lever kits adapting across floor pan configurations without welding or fabrication. One-off fabrication shops in Mississippi and Louisiana prioritize these systems for build schedule compression.
- Custom:Application-specific linkage requiring measurement and fabrication services.
- Standard:Fixed-mount configurations for common vehicle platforms with minimal adaptation.
- Integrated:Transmission-and-shifter combined systems reducing installer complexity.
Custom holds legacy installed base. Modular is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns for Powerglide shifters diverge sharply by geography, with the United States prioritizing drag racing performance while European demand centers on restoration authenticity and regulatory compliance adaptation.
United States
Southeastern drag racing circuits in Florida, Georgia, and South Carolina drive specification for electronic solenoid variants with data logging integration. NHTSA equipment safety standards govern neutral safety switch circuit requirements for street-legal modified vehicles. Hot rod fabrication clusters in Mississippi and Louisiana concentrate procurement of modular bracket-and-lever kits for build schedule compression.
Germany
Classic muscle car import restoration projects sustain niche demand for period-correct mechanical linkage systems. ECHA REACH chemicals regulation constrains surface coating formulations for European distribution, prompting reformulation investment. Stuttgart-area specialty automotive workshops prioritize OEM-grade tactile feedback in shifter specification for authenticity-focused builds.
United Kingdom
Historic vehicle motorsport exemption frameworks enable competition use of non-compliant transmission controls. DVSA safety inspection protocols for modified vehicles influence product validation requirements. Birmingham fabrication shops serve as the primary distribution node for cable-and-linkage catalogs targeting one-off builder projects.
Australia
Street machine culture in New South Wales and Victoria sustains aftermarket channel volume for aesthetic customization options. TGA-equivalent vehicle equipment standards administered by state transport authorities govern modified vehicle certification. Melbourne-based speed equipment distributors anchor procurement relationships with direct manufacturer technical support.
Canada
Cross-border parts sourcing from US suppliers dominates the addressable market given geographic proximity and integrated supply chains. Transport Canada CMVSS equipment standards align closely with NHTSA protocols, reducing regulatory adaptation burden. Ontario restoration shops concentrate demand for heritage mechanical systems serving 1960s GM platform rebuilds.
Powerglide Shifter Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the market structure reflecting capital-intensity divergence between transmission-system integrators and component-focused fabricators. The competitive landscape stratifies across three archetypes: heritage brand owners leveraging decades of drag racing equity, integrated transmission-and-shifter system providers reducing installer complexity, and custom cable-and-linkage specialists serving one-off fabrication demand. Dominant competitive moves include portfolio diversification into electronic control variants and geographic expansion through direct technical support relationships with fabrication shop channels.
Among heritage-positioned suppliers, Hurst Shifters and B&M Racing occupy positions anchored in decades of brand equity within drag racing circles. TCI Automotive exemplifies the integrated-system archetype with combined transmission-and-shifter offerings. Lokar represents the custom-fabrication specialist tier with extensive cable and linkage catalogs. These three company groupings illustrate how competitive positioning fragments across mechanical heritage defense, electronic control adoption, and application engineering depth.
| Leading Market Players |
|---|
| Hurst Shifters |
| Lokar |
| TCI Automotive |
| B&M Racing |
| American Shifter Company |
| Shiftworks Inc. |
| Barton Industries |
| ATI Performance Products |
| Hughes Performance |
| Others |
Value Network & Pricing Analysis
NHTSA equipment safety standards gate both supplier qualification and price differentiation simultaneously, as certification investment separates SAE-validated electronic solenoid variants from uncertified mechanical alternatives. Compliance burden concentrates margin capture among heritage suppliers with existing validation infrastructure, while uncertified entrants compete on raw material cost alone.
Pricing Analysis
Long-term offtake contracts dominate procurement between major fabrication shops and integrated transmission suppliers, insulating TCI Automotive and Hurst Shifters from spot aluminum volatility. Three-tier pricing structure across premium electronic, standard mechanical, and economy cable-actuated levels reflects SAE validation tier and valve body calibration support depth. Pricing pressure stems from steel input volatility squeezing machined bracket margins. Budget-conscious builders in Tennessee fabrication clusters exhibit highest price sensitivity, while sanctioned racers in Florida prioritize elapsed-time consistency over unit cost.
Supply Chain Analysis
Strategic stockpiling of aluminum billet and hardened steel rod characterizes supplier behavior given commodity price volatility and single-region demand concentration. Machined lever and bracket components draw from domestic US foundries and Mexican cross-border fabrication facilities, with surface coating chemistries sourced from REACH-compliant European suppliers. Single-source vulnerability concentrates in solenoid actuator subassemblies from specialized controls manufacturers. Distribution runs through direct technical support relationships with southeastern fabrication shops, displacing traditional catalog distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
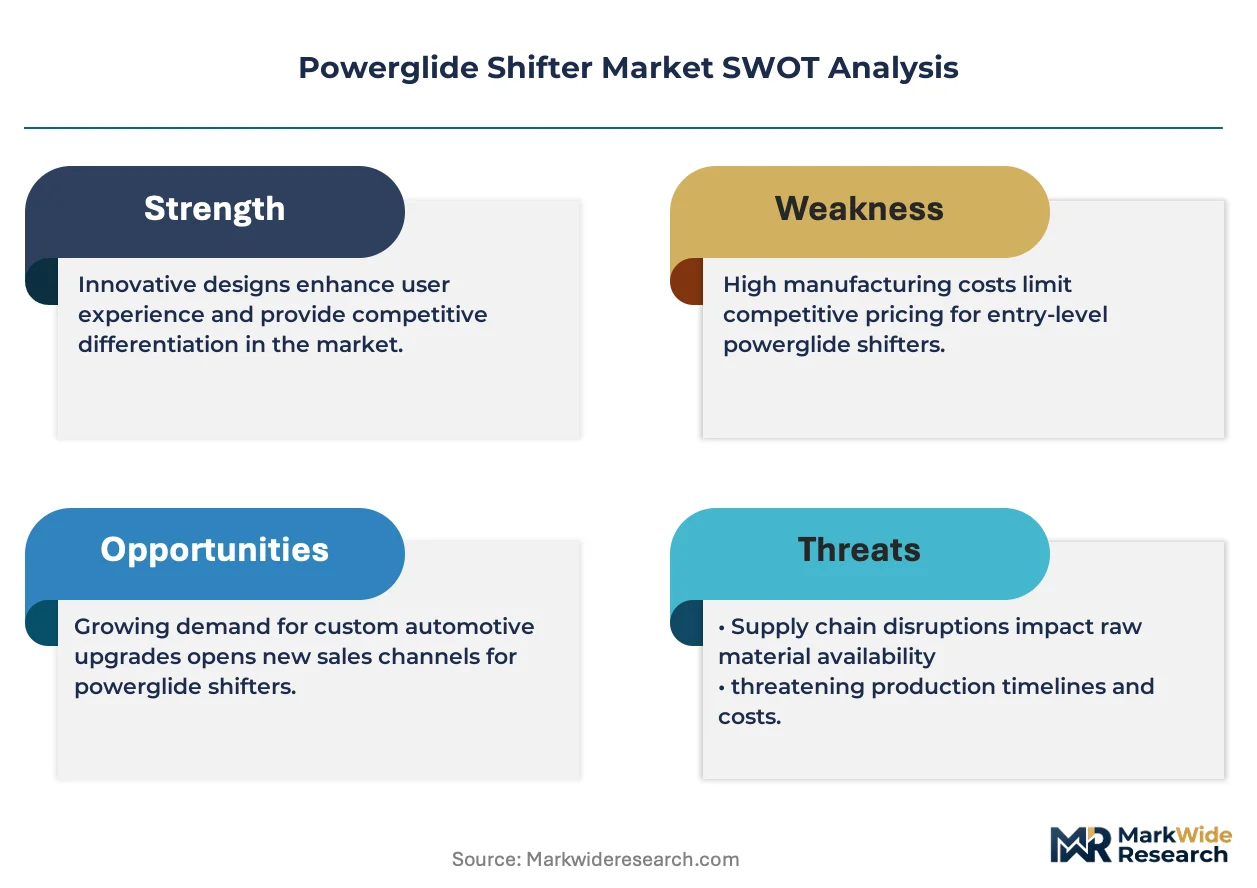
Electronic solenoid actuation represents a high-growth disruption as EPA emissions frameworks and drag racing sanctioning body mandates converge on programmable shift control. Regulatory inflection compresses the addressable window for purely mechanical heritage systems.
For Market Incumbents: Secure calibration expertise depth through targeted hiring from Detroit Three transmission engineering programs, defending against emerging controls specialists fragmenting championship-level racing relationships. Expand modular bracket-and-lever kit capacity in Mississippi and Louisiana fabrication clusters to capture build schedule compression demand. Electronic variant development velocity serves as the priority defensive lever against heritage brand equity erosion. For New Entrants and Emerging Players: Anchor in California restoration shops seeking CARB-compliant electronic shifter configurations for street-legal modified vehicles, the most restricted compliance pathway creating white-space shelter from incumbent saturation. Target direct manufacturer technical support gaps in Georgia and Florida hot rod clusters where builder procurement is migrating from catalog distributors. Application engineering consultation serves as the differentiated go-to-market angle against price-competitive heritage suppliers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across electronic solenoid architectures as CAN bus integration and programmable shift scheduling require software development infrastructure alien to mechanical heritage players. Acquisition target archetype: mid-tier mechanical suppliers with established fabrication shop relationships but lacking electronic variant pipelines, offering channel leverage for controls technology overlay. Signal to watch: drag racing sanctioning body mandate expansion beyond Florida and Georgia into Alabama and South Carolina circuits.| Strategic Initiative | Industry Significance |
|---|---|
| Electronic Control Variant Development | EPA emissions compliance frameworks and SAE validation protocols create certified product differentiation against mechanical alternatives. |
| Modular Bracket-and-Lever Kit Expansion | Build schedule compression demand from Mississippi and Louisiana fabrication shops drives share capture from fixed-mount systems. |
| Direct Technical Support Channel Investment | Builder procurement migration from catalog distributors in Georgia and Florida clusters enables margin expansion beyond mass retail. |
| Calibration Expertise Acquisition | Talent scarcity in legacy automatic transmission architecture constrains product development velocity for emerging entrants. |
| REACH-Compliant Surface Coating Reformulation | ECHA chemicals regulation adaptation transfers innovation to premium European export product lines. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of NHTSA equipment safety standards, EPA emissions compliance frameworks, and SAE International durability protocols. Primary interviews engaged transmission system engineers at TCI Automotive and Hurst Shifters, procurement leads at southeastern US fabrication shops, and regulatory affairs specialists familiar with CARB executive order pathways. Secondary validation drew from drag racing sanctioning body technical bulletins, Detroit Three OEM electrification timeline disclosures, and customs data tracking aluminum and steel input flows. Bottom-up build from product-level bill-of-materials analysis triangulates against top-down market sizing from end-user spend patterns.
Segmentation dimensions modeled span product type (automatic, manual, semi-automatic, sequential), technology (electronic, mechanical, hydraulic, pneumatic), end user (racers, enthusiasts, OEMs, aftermarket), and installation configuration (modular, custom, standard, integrated). CAGRs derive from elasticity-adjusted demand projections across the analysis window, incorporating electrification timeline compression scenarios and classic restoration demand sustainability assumptions. Industry-specific forecast inputs include valve body calibration service attach rates and modular kit adoption curves by fabrication shop density.
Decision-makers should treat outputs as directional under base assumptions of sustained southeastern US drag racing culture and stable EPA enforcement intensity; material deviation would warrant model refresh. Specific risk factors include accelerated Detroit Three EV conversion programs, REACH coating formulation cost spikes, and NHTSA neutral safety switch circuit requirement tightening. Revision becomes warranted when electronic solenoid sanctioning body mandates cross threshold coverage of 60% of championship-level competition circuits.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Rear Spoiler Market
Automotive Parts
India Automotive Parts Magnesium Die Casting Market
Automotive Parts
Air Filter Cartridges Market
Automotive Parts
Automotive Forging Market
Automotive Parts
India Automotive Hydraulic Actuators Market
Automotive Parts
Automotive Central Lubrication System Market
Automotive Parts
Brazil Automotive Airfilters Market
Automotive Parts
Suspension Bump Stopper Market
Automotive Parts
Europe Automotive Lubricants Market
Automotive Parts
Electric Parking Brake Actuator Components Market
Automotive Parts
Automotive Oil and Valve Stem Seals Market
Automotive Parts
Engine Bearings Market
Automotive Parts
Windshield Lifters Market
Automotive Parts
Global Automotive Coolant Reservoir Tank Market
Automotive Parts
Electric Vehicle Fasteners Market
Automotive Parts
Automotive Differential Housing Market