
 Odometer Market | 2026-2036
Odometer Market Size, Share, and Industry Trends Forecast 2026-2036
Odometer Market Analytics
Precision-grade odometer calibration is collapsing the tolerance gap between mechanical legacy systems and electronic measurement standards. Continental AG leverages its integrated cockpit electronics division to sustain dominance in digital cluster supply for European premium OEMs. Denso Corporation anchors its position through captive semiconductor sourcing and thermal-hardened display technologies for Asian vehicle platforms. Robert Bosch GmbH competes on sensor fusion architectures that merge wheel-speed data with GPS correction layers.
An odometer is a distance-measuring instrument that records cumulative vehicle travel through mechanical gear trains, electronic pulse counting from wheel-speed sensors, or satellite-derived position integration, with modern units achieving accuracy within 0.1% through multi-source sensor validation and serving as the legal basis for warranty terms, lease calculations, and resale valuation. Digital odometers now lead the product type dimension as automakers phase out analog dials in favor of reconfigurable displays, while GPS odometers represent the fastest-expanding technology segment due to telematics mandates and usage-based insurance penetration. Bluetooth-enabled units capture aftermarket margin pools by enabling smartphone-coupled diagnostics and tamper-evident logging for fleet compliance.
NHTSA enforces odometer disclosure accuracy under federal truth-in-mileage statutes, while the EU's UNECE R39 regulation mandates type-approved electronic odometers with sealed non-resettable memory, and Japan's MLIT aligns domestic safety standards with harmonized international vehicle certification frameworks. These overlapping compliance regimes force component suppliers to engineer multi-jurisdiction platforms with immutable audit trails and encrypted data storage. Stakeholders must monitor the divergence between legacy mechanical retrofit demand and native electronic architectures as software-defined vehicles render standalone odometer hardware obsolete.
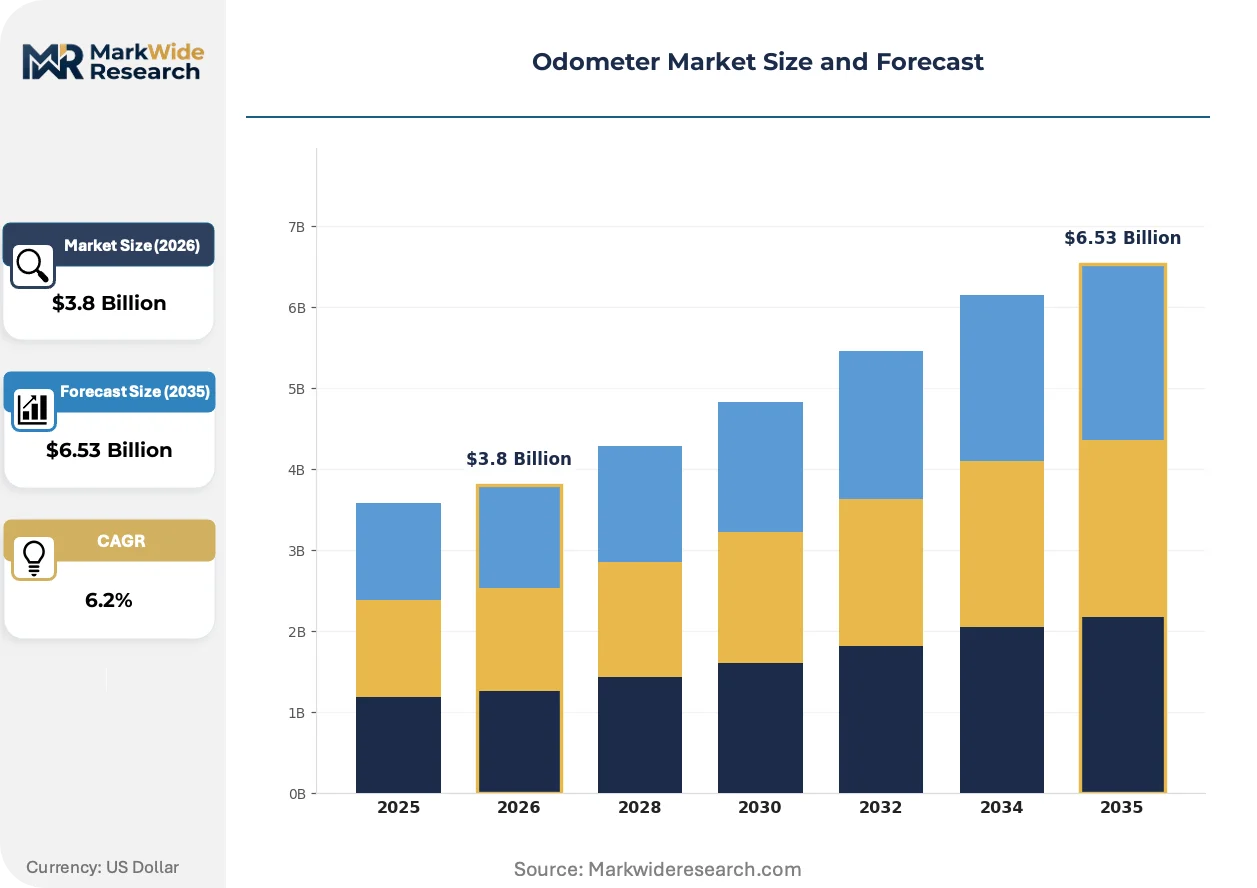
Market Dynamics
The transition from mechanical to electronic odometer architectures is compressing supplier margins while elevating firmware and calibration capabilities as the primary competitive differentiator in instrument cluster supply contracts.
Growth Catalysts
- UNECE R39 harmonization:European type-approval mandates for sealed non-resettable memory are accelerating OEM migration to electronic odometer platforms across Germany, France, and Italy.
- Telematics integration:Usage-based insurance penetration in commercial fleets is pulling GPS-corrected odometer modules into heavy-duty truck specifications.
- EV platform standardization:Chinese automakers are mandating smart instrument clusters with integrated odometer functions as domestic electric vehicle production scales.
Market Restraints
- Semiconductor supply concentration:Captive foundry capacity in Taiwan and South Korea constrains microcontroller availability for odometer module suppliers.
- Legacy mechanical retrofit demand:Classic vehicle restoration markets in the United States and Germany sustain demand for gear-train odometer components that electronic suppliers cannot address.
- Calibration equipment capex:Precision-grade test benches for electronic odometer validation require capital outlays that fragment the supplier base between tiered certification tiers.
Strategic Opportunities
- Aftermarket Bluetooth modules:Smartphone-coupled diagnostics and tamper-evident logging are opening margin pools in fleet compliance applications.
- Software-defined vehicle convergence:Odometer functionality is migrating into centralized domain controllers, creating openings for middleware suppliers.
- India automotive production:Local OEMs are adopting electronic instrument clusters under BIS automotive standards, generating fresh module demand.
Industry Challenges
- Firmware certification timelines:Multi-jurisdiction type-approval processes for encrypted odometer data storage extend product launch cycles by 8-14 months.
- Legacy system integration:Electronic odometer modules must maintain signal compatibility with mechanical speedometer cables in retrofit applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Odometer Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.53 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Odometer, Analog Odometer, GPS Odometer, Smart Odometer Technology: Mechanical, Electronic, Hybrid, Bluetooth-Enabled End User: Automotive OEMs, Aftermarket Retailers, Fleet Operators, DIY Enthusiasts Installation Type: Integrated, Standalone, Retrofit, Custom |
| Companies Covered | Continental AG, Denso Corporation, Nippon Seiki Co., Ltd., Yazaki Corporation, Robert Bosch GmbH, Magneti Marelli S.p.A., Visteon Corporation, Stoneridge Inc., Aptiv PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Odometer Market Evolving Landscape
Sensor fusion architectures and satellite-derived position integration are collapsing the accuracy gap between standalone odometer hardware and centralized vehicle computing platforms.
MEMS accelerometer-based odometer correction is miniaturizing. These solid-state sensors detect wheel-slip events and road surface anomalies to refine distance calculations. Commercial fleet operators in Germany and Japan are specifying them for winter-condition accuracy. The technology is miniaturizing module footprints while eliminating mechanical wear points.
NHTSA truth-in-mileage enforcement is tightening audit trail requirements for electronic odometer data. The regulation now mandates immutable logging for lease-return and resale transactions. Used vehicle remarketers in the United States are upgrading to tamper-evident systems to maintain auction eligibility.
Subscription-based odometer calibration services are displacing one-time equipment purchases. Independent repair shops and small fleet operators are adopting cloud-corrected distance logging. This shift concentrates most visibly in North American commercial vehicle service networks.
Odometer Market Segmentation
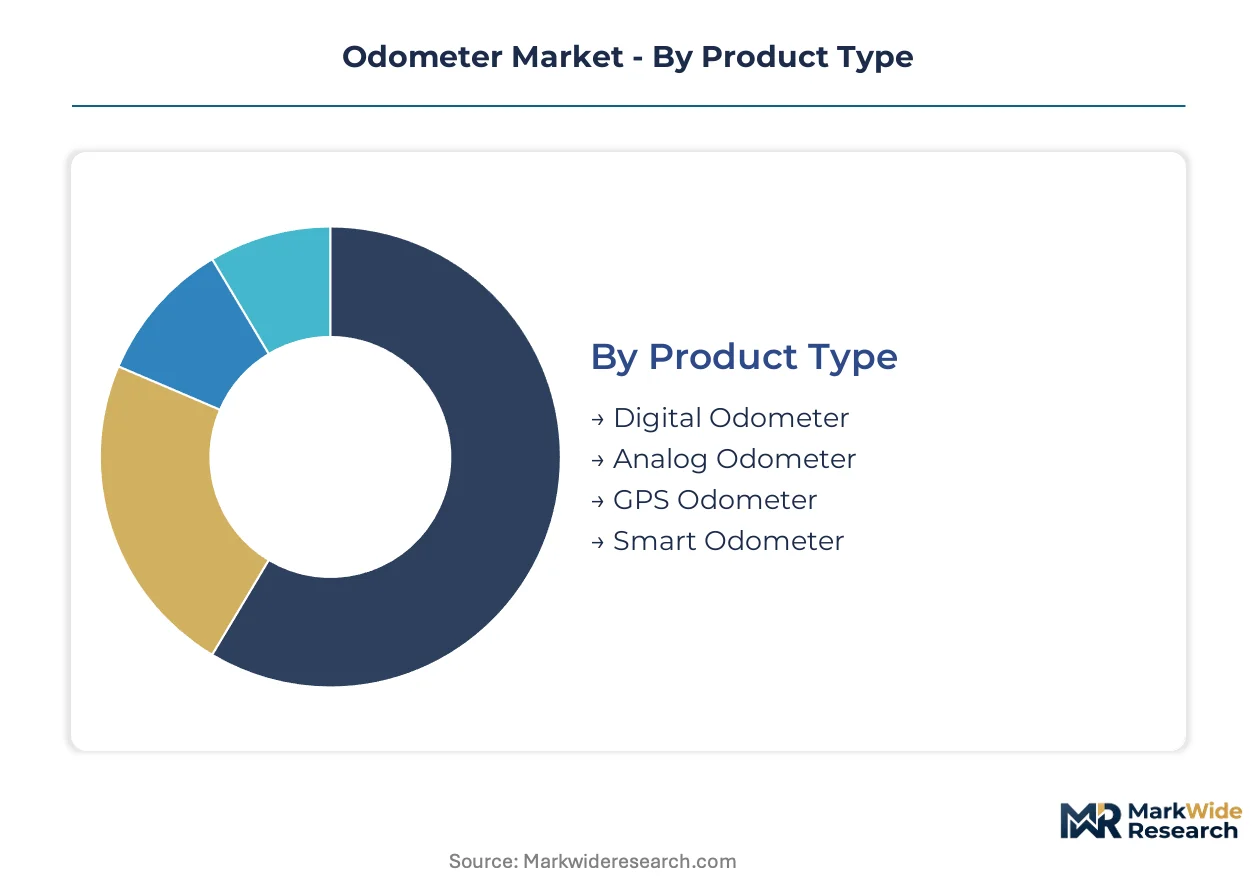
Odometer market segmentation reveals divergent substitution pressures across hardware architectures. Technology transitions and regulatory mandates are fragmenting demand across legacy mechanical systems, electronic platforms, and emerging connected modules.
Product Type:
Digital odometers face the most acute substitution pressure from centralized vehicle computing platforms, while analog and GPS variants occupy defensible niche positions.
- Digital Odometer:Reconfigurable LCD or OLED displays driven by microcontroller units process wheel-speed sensor pulses with software-defined accuracy. Automotive OEMs in Germany and Japan specify these for new vehicle platforms under UNECE R39 sealed-memory mandates. Firmware calibration capabilities differentiate suppliers as automakers phase out mechanical dials.
- Smart Odometer:Integrated instrument clusters combine odometer functions with telematics, navigation, and vehicle health monitoring through domain controller architectures. Chinese EV manufacturers mandate these units as domestic electric vehicle production scales, pulling demand from standalone modules.
- Analog Odometer:Mechanical gear-train indicators with rotating numbered drums persist in classic vehicle restoration markets where electronic retrofits violate authenticity requirements.
- GPS Odometer:Satellite-derived position integration calculates distance through differential correction algorithms, penetrating commercial fleet specifications for usage-based insurance applications.
Digital odometers retain volume leadership; smart odometers hold the steepest expansion curve.
Technology:
Cost tier stratification separates premium electronic architectures from economy mechanical systems, with hybrid and Bluetooth variants capturing mid-market positioning.
- Electronic:Solid-state pulse-counting systems with non-volatile memory storage achieve accuracy within 0.1% through multi-source sensor validation. Taiwan and South Korea foundry concentration constrains microcontroller availability for module suppliers serving NHTSA-regulated US markets.
- Bluetooth-Enabled:Wireless connectivity modules enable smartphone-coupled diagnostics and tamper-evident logging for fleet compliance. Independent repair shops and small fleet operators in North American service networks are adopting cloud-corrected distance logging through subscription calibration services.
- Mechanical:Gear-train odometers with rotating cable drives sustain demand from United States and Germany classic vehicle restoration markets that electronic suppliers cannot address.
- Hybrid:Combined mechanical display with electronic sensing bridges retrofit applications requiring signal compatibility with legacy speedometer cables.
Electronic technology commands the dominant revenue share; Bluetooth-enabled variants are expanding most quickly through aftermarket penetration.
End User:
Application concentration varies sharply between captive OEM supply and fragmented aftermarket channels, with fleet operators driving standardization demands.
- Automotive OEMs:Tier-1 suppliers integrate odometer modules into instrument clusters under multi-year platform contracts. Continental AG serves European premium manufacturers through cockpit electronics divisions while Denso Corporation anchors Asian supply with captive semiconductor sourcing.
- Fleet Operators:Commercial vehicle managers specify GPS-corrected modules for asset utilization optimization and maintenance scheduling. German and Japanese fleet specifications increasingly require MEMS accelerometer-based correction for winter-condition accuracy.
- Aftermarket Retailers:Distributors serve replacement demand for failed units and upgrade installations, with Bluetooth modules capturing margin pools in compliance applications.
- DIY Enthusiasts:Classic vehicle owners and restoration specialists sustain mechanical odometer component demand through specialty supply channels.
Automotive OEMs dominate procurement volume; fleet operators are gaining share fastest through telematics integration mandates.
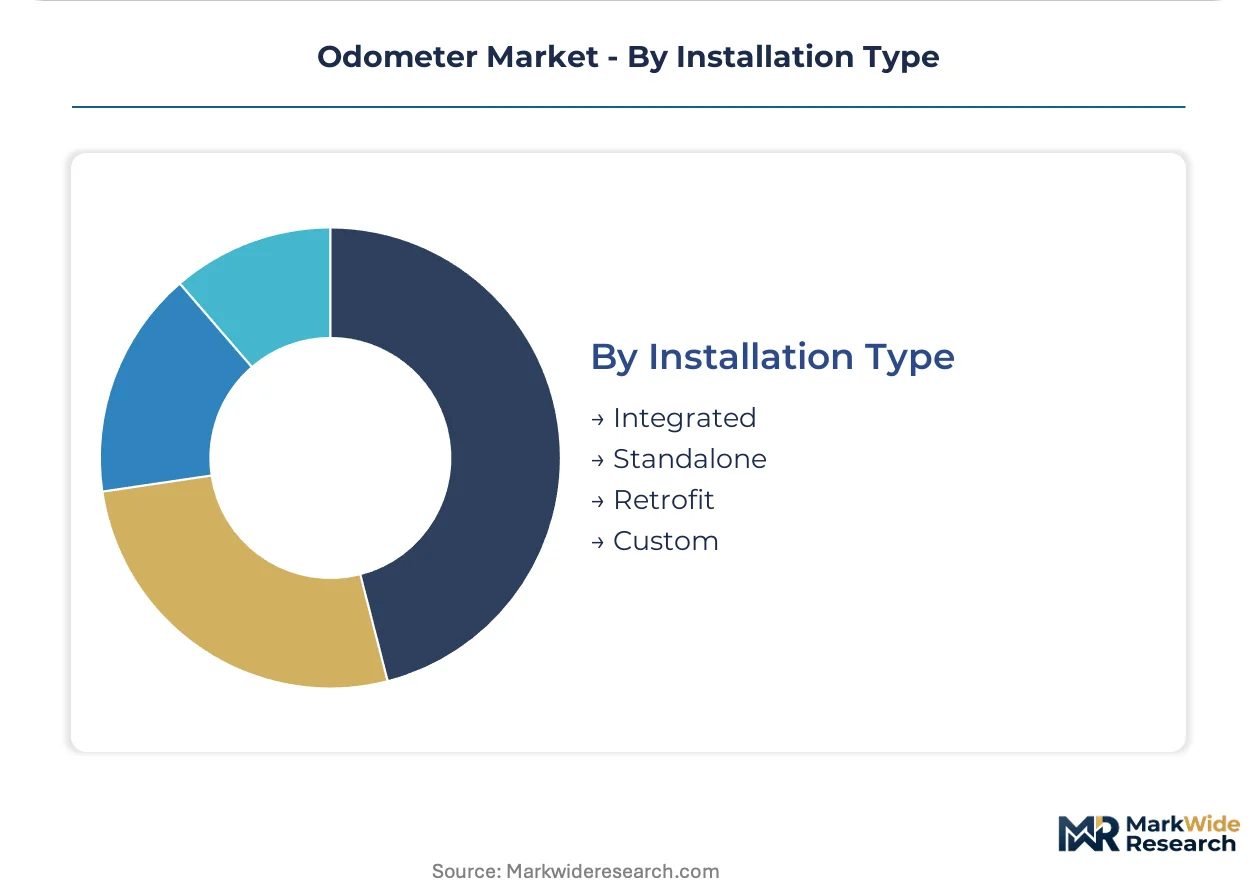
Installation Type:
Supply concentration favors integrated architectures while standalone and retrofit segments fragment across regional specialists.
- Integrated:Odometer functions embedded within instrument clusters or domain controllers dominate new vehicle production. Robert Bosch GmbH competes through sensor fusion architectures merging wheel-speed data with GPS correction layers.
- Retrofit:Replacement modules for legacy vehicles require mechanical speedometer cable compatibility, constraining electronic supplier participation. Calibration equipment capital requirements fragment certification tiers among installation providers.
- Standalone:Self-contained odometer units persist in heavy-duty truck and specialty vehicle applications where modular replacement reduces downtime.
- Custom:Bespoke installations for motorsport, military, and industrial vehicles demand application-specific accuracy and environmental hardening.
Integrated installation commands production volume; retrofit applications maintain steady demand through vehicle parc aging.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Component manufacturing for precision distance-measurement systems clusters in Germany, Japan, and the United States, where tier-1 automotive electronics suppliers maintain captive design centers and calibration facilities. Taiwan and South Korea foundries supply microcontroller silicon that constrains module availability across all three markets.
United States
Fleet telematics mandates and usage-based insurance penetration drive GPS-corrected odometer specifications in commercial vehicles. NHTSA truth-in-mileage statutes enforce immutable audit trails for lease-return and resale transactions. Detroit-area automotive electronics clusters supply instrument clusters to domestic OEMs while independent repair shops in the Midwest adopt subscription-based calibration services.
Germany
European premium OEMs source cockpit electronics from integrated suppliers under multi-year platform contracts. UNECE R39 type-approval mandates sealed non-resettable memory architectures that accelerate electronic odometer migration. Stuttgart and Munich automotive engineering centers develop sensor fusion architectures merging wheel-speed data with GPS correction layers.
Japan
Domestic vehicle platforms specify thermal-hardened display technologies and MEMS accelerometer-based correction for winter-condition accuracy. MLIT aligns safety standards with harmonized international certification frameworks. Nagoya and Tokyo instrument cluster suppliers anchor Asian supply chains through captive semiconductor sourcing relationships.
China
Domestic EV production scales pull demand for smart instrument clusters with integrated odometer functions as local OEMs mandate centralized domain controller architectures. MIIT automotive standards enforce electronic measurement accuracy requirements. Shenzhen and Shanghai electronics manufacturing clusters produce reconfigurable LCD and OLED display modules for both captive OEM supply and export markets.
India
Local OEM adoption of electronic instrument clusters generates fresh module demand as BIS automotive standards phase out mechanical measurement systems. Commercial fleet operators in Maharashtra and Gujarat specify aftermarket Bluetooth-enabled units for smartphone-coupled diagnostics and tamper-evident logging compliance.
Odometer Market Competitive Landscape
Concentration sits with diversified automotive electronics conglomerates that supply instrument clusters under multi-year platform contracts to captive OEM relationships. The vendor base spans three tiers: integrated cockpit electronics divisions with full-stack capabilities, specialized instrument cluster manufacturers with regional automotive relationships, and aftermarket module suppliers serving fleet compliance and restoration applications. Competitive moves center on sensor fusion technology licensing and backward integration into microcontroller sourcing to secure foundry allocation.
Within the integrated electronics tier, Continental AG and Denso Corporation exemplify divergent geographic anchoring strategies, while Robert Bosch GmbH occupies a position emphasizing sensor fusion architectures. Stuttgart-based Robert Bosch GmbH represents European engineering-centric competition. Aichi-based Denso Corporation exemplifies Asian supply chain integration with thermal-hardened display specialization. Hanover-based Continental AG anchors European premium OEM relationships through cockpit electronics divisions.
| Leading Market Players |
|---|
| Continental AG |
| Denso Corporation |
| Nippon Seiki Co., Ltd. |
| Yazaki Corporation |
| Robert Bosch GmbH |
| Magneti Marelli S.p.A. |
| Visteon Corporation |
| Stoneridge Inc. |
| Aptiv PLC |
| Others |
Value Network & Pricing Analysis
Foundry scale economies in Taiwan and South Korea concentrate microcontroller supply for odometer modules, compressing tier-2 supplier margins while elevating firmware calibration capabilities as the primary price floor determinant for electronic instrument clusters.
Pricing Analysis
NHTSA truth-in-mileage statutes dictate the pricing tier structure across the odometer market, with UNECE R39 type-approval mandates in Europe layering additional certification premiums. Three-tier pricing structure across premium, standard, and economy levels separates sealed-memory electronic architectures from mechanical retrofits and Bluetooth aftermarket modules. Cost compression in standard-tier electronic units is intensifying because Chinese EV OEMs negotiate volume-scale platform contracts. Fleet operators exhibit the highest price sensitivity due to telematics integration mandates, while classic vehicle restoration specialists absorb premium mechanical component pricing.
Supply Chain Analysis
Strait of Malacca transit routes anchor semiconductor logistics for odometer microcontroller supply, constraining module availability when regional port congestion spikes. Taiwan, South Korea, and Germany concentrate upstream foundry capacity and downstream cluster assembly. Raw material dependencies center on silicon wafers, automotive-grade display substrates, and rare-earth magnets for MEMS sensors. Single-source vulnerability in Taiwan foundry exposure represents the dominant structural risk. Distribution runs through captive OEM supply chains for integrated clusters, while aftermarket channels fragment across independent repair networks and fleet service providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The odometer market tracks automotive production cycles, with EV platform standardization in China and telematics mandates in North America driving replacement demand through the current upswing.
For Market Incumbents: Consolidate firmware certification capabilities and captive semiconductor sourcing relationships to defend against middleware suppliers encroaching on domain controller architectures. Prioritize backward integration into Taiwan foundry allocation contracts. Reinforce European premium OEM relationships through UNECE R39 compliance bundling. For New Entrants and Emerging Players: Differentiate on aftermarket Bluetooth module subscription services for fleet compliance applications in North American commercial vehicle networks. Target India's BIS-mandated electronic cluster transition as local OEMs phase out mechanical systems. Pursue cloud-corrected calibration partnerships with independent repair shops. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors sensor fusion specialists with GPS-corrected odometer IP and encrypted data storage capabilities. Long-term viability hinges on software-defined vehicle convergence rendering standalone hardware obsolete. Monitor MEMS accelerometer adoption rates in German and Japanese fleet specifications as inflection indicator for winter-condition accuracy demand.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Architecture Licensing | Bosch and Continental monetize wheel-speed GPS integration IP across Asian EV platforms. |
| Captive Foundry Allocation Contracting | Denso secures Taiwan semiconductor supply against tier-2 module supplier shortages. |
| Bluetooth Aftermarket Module Launch | Stoneridge captures fleet compliance margin pools through smartphone-coupled diagnostics. |
| UNECE R39 Certification Bundling | Continental packages sealed-memory compliance with premium cockpit electronics contracts. |
| Domain Controller Middleware Development | Aptiv migrates odometer functionality into centralized vehicle computing platforms. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of NHTSA enforcement actions, UNECE type-approval databases, and automotive production registries. Interviews with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and fleet telematics managers inform demand-side validation. Secondary sources include SEC 10-K filings from instrument cluster manufacturers, IHS Markit vehicle registration data, and Taiwan Semiconductor Industry Association capacity reports. Bottom-up module shipment estimates triangulate against top-down automotive production forecasts.
Segmentation dimensions modeled span product type, technology architecture, end-user category, and installation configuration across the projection horizon. Vehicle propulsion architecture, content per vehicle, and regional regulatory cluster variations shape unit economics. CAGRs derive from regression analysis of historical adoption curves and elasticity estimates against fleet telematics penetration rates and EV platform standardization timelines.
The analysis sits within stated boundaries; outcomes outside current UNECE R39 harmonization trajectories or Taiwan foundry capacity expansion assumptions would require recalibration. Forecasts reflect documented assumptions regarding semiconductor availability and regulatory enforcement intensity. Practitioners should keep alternative scenarios live as software-defined vehicle architectures and subscription-based calibration service adoption evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
France Commercial Vehicles Lubricants Market
Automotive Parts
Large Volume Injector Market
Automotive Parts
Global Automotive Springs and Damper Market
Automotive Parts
AC Electromagnetic Brakes Market
Automotive Parts
Mexico Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Ignition Coil Market
Automotive Parts
Canada Passenger Vehicles Lubricants Market
Automotive Parts
Global Auto Parts and Accessories Market
Automotive Parts
Global EV Speed Reducer Market
Automotive Parts
Turkey Passenger Vehicles Lubricants Market
Automotive Parts
Transfer Case Market
Automotive Parts
Die Cast Parts for Electric Vehicle Market
Automotive Parts
Resin Silencer Market
Automotive Parts
VVT and Start-Stop Systems Market
Automotive Parts
Air Springs Market
Automotive Parts
Argentina Automotive Engine Oils Market