
 Automotive Vents Market | 2026-2036
Automotive Vents Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Vents Market Analytics
A widening capital-intensity gap between membrane specialists and full-system integrators is rotating competitive advantage toward players with in-house material science capabilities. W. L. Gore & Associates leverages its fluoropolymer expertise to dominate high-performance breathable membrane segments. Valeo SA anchors European supply relationships through integrated HVAC-vent module production. MAHLE GmbH competes on thermal management system bundling that reduces OEM assembly complexity.
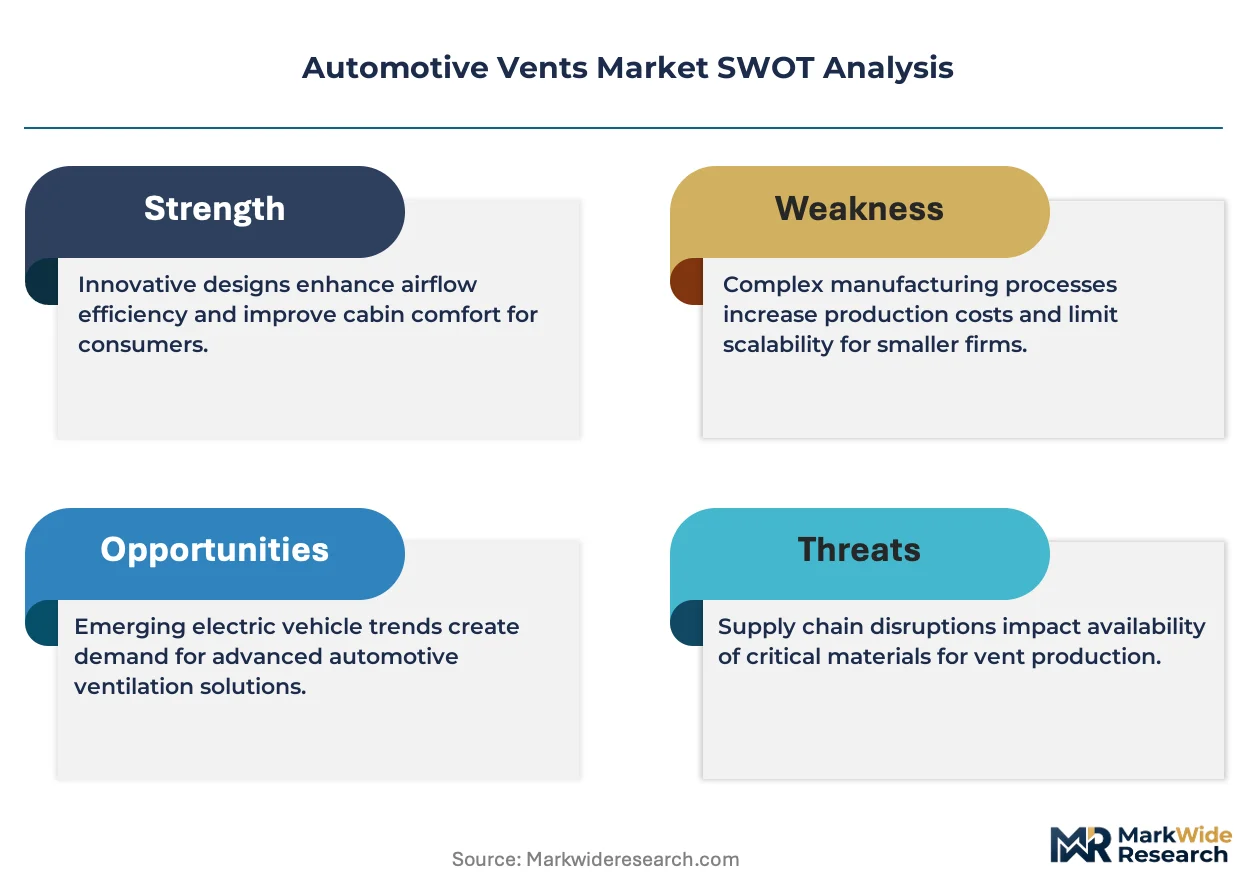
Automotive vents are airflow distribution components engineered from polypropylene, ABS, or aluminum alloys with specified aperture geometries to direct conditioned air into vehicle cabins at controlled velocities and temperatures. These components integrate with blower motors, evaporators, and heater cores to maintain occupant thermal comfort and defog critical sightlines. Dashboard vents and integrated sensor technology command premium positioning as cabin digitization accelerates, while manual control configurations face margin compression in mass-market segments. Electric vehicle applications represent the fastest-growing vehicle type category due to distinct battery thermal management and reduced engine-bay heat sourcing requirements.
NHTSA occupant safety standards and EPA material emissions frameworks govern vent material selection and cabin air quality compliance in the United States, while REACH and RoHS restrictions in Europe limit certain plasticizers and heavy metal content in vent subcomponents. OEM procurement teams must evaluate supplier certification breadth against these multi-jurisdictional requirements to avoid market access delays. Stakeholders should monitor evolving battery thermal interface specifications that will redefine vent system functional boundaries in next-generation electric architectures.
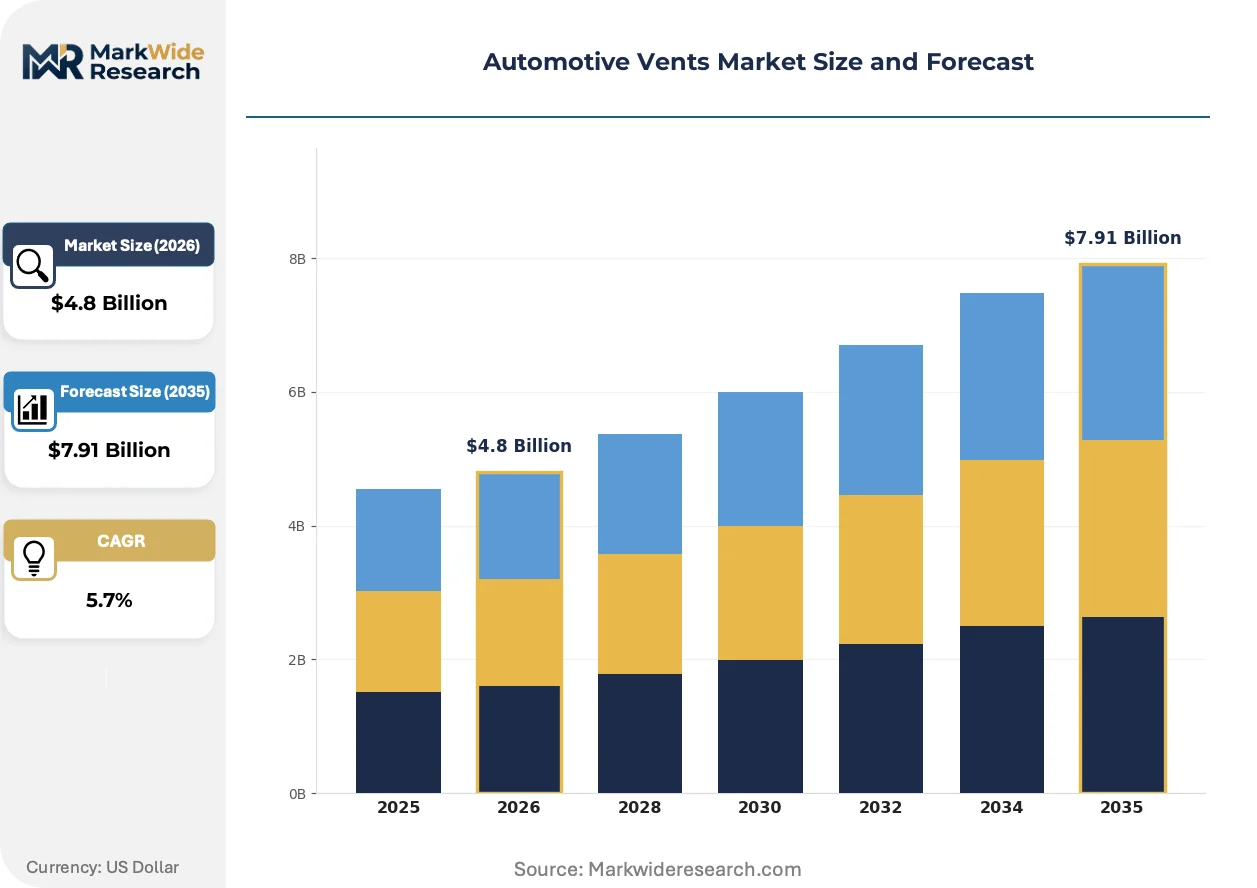
Market Dynamics
The electric vehicle transition is fragmenting thermal management architectures, forcing vent suppliers to engineer battery-cabin air segregation systems that legacy internal-combustion platforms never required.
Growth Catalysts
- EPA Tier 3 Emissions Standards:Cabin air quality mandates in the United States are compelling OEMs to specify advanced filtration-vent integration, expanding addressable content per vehicle.
- Polypropylene Membrane Advances:Material science breakthroughs in breathable polymers are enabling thinner, lighter vent constructions that reduce HVAC system energy draw.
- German Engineering Center Concentration:Stuttgart and Munich-based OEM technical headquarters are driving specification upgrades for integrated HVAC-vent modules across European nameplates.
Market Restraints
- Fluoropolymer Feedstock Volatility:PTFE and ePTFE membrane production depends on concentrated fluorochemical supply chains subject to environmental regulation tightening.
- Aluminum Alloy Price Swings:Premium vent variants using extruded aluminum face margin compression when London Metal Exchange pricing spikes.
- REACH Compliance Burden:ECHA substance restrictions on certain plasticizers and flame retardants force reformulation cycles that extend qualification timelines.
Strategic Opportunities
- India PLI Scheme for Auto Components:Production-linked incentives for advanced automotive parts are attracting vent system localization investments serving domestic OEM expansion.
- Sensor-Vent Convergence:Integration of particulate and CO2 sensing into dashboard vent housings creates new electronics-content revenue streams.
- Direct-to-Tier-1 Digital Procurement:OEMs are bypassing traditional distribution layers for standardized vent commodities, compressing channel margins but rewarding scale manufacturers.
Industry Challenges
- Thermal Simulation Talent Scarcity:Computational fluid dynamics expertise for battery-cabin coupled thermal modeling commands premium compensation and extends hiring cycles.
- Multi-Jurisdictional Certification Overlap:Simultaneous NHTSA, EPA, and REACH compliance creates testing redundancy that strains mid-tier supplier R&D budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Vents Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dashboard Vents, Center Vents, Side Vents, Vent Louvers Material: Plastic, Metal, Rubber, Composite Vehicle Type: Passenger Cars, Trucks, SUVs, Electric Vehicles Technology: Manual Control, Automatic Control, Integrated Sensors, HVAC Systems |
| Companies Covered | Faurecia SE, Porex Corporation, W. L. Gore & Associates, Nifco Inc., Filtration Group Corporation, Parker Hannifin, Donaldson Company, Valeo SA, MAHLE GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Vents Market Evolving Landscape
Active grille shutter systems and smart vent actuators are converging into unified thermal management electronics, collapsing the historical separation between exterior aerodynamics and interior climate control.
Laser-perforated membrane technologies are decomposing the traditional punched-aperture vent manufacturing paradigm. Tier-1 suppliers serving premium electric vehicle platforms are adopting these processes for acoustic tuning precision. The technology is decomposing established tooling-amortization models by eliminating hard-tool changeover costs for aperture pattern variations.
REACH authorization requirements for per- and polyfluoroalkyl substances are compelling membrane suppliers to accelerate fluorine-free alternatives. The regulation is forcing reformulation of breathable barrier layers that previously relied on PTFE chemistry. High-performance electric vehicle segments in Germany and Scandinavia are absorbing initial cost premiums for compliant materials.
Fleet procurement departments are consolidating vent supplier rosters to capture volume leverage on standardized HVAC modules. Direct sourcing agreements between rental and logistics fleet operators and Tier-1 integrators are displacing traditional aftermarket distribution for replacement vents. This concentration is most pronounced in United States commercial vehicle segments where total-cost-of-ownership analytics dominate specification decisions.
Automotive Vents Market Segmentation
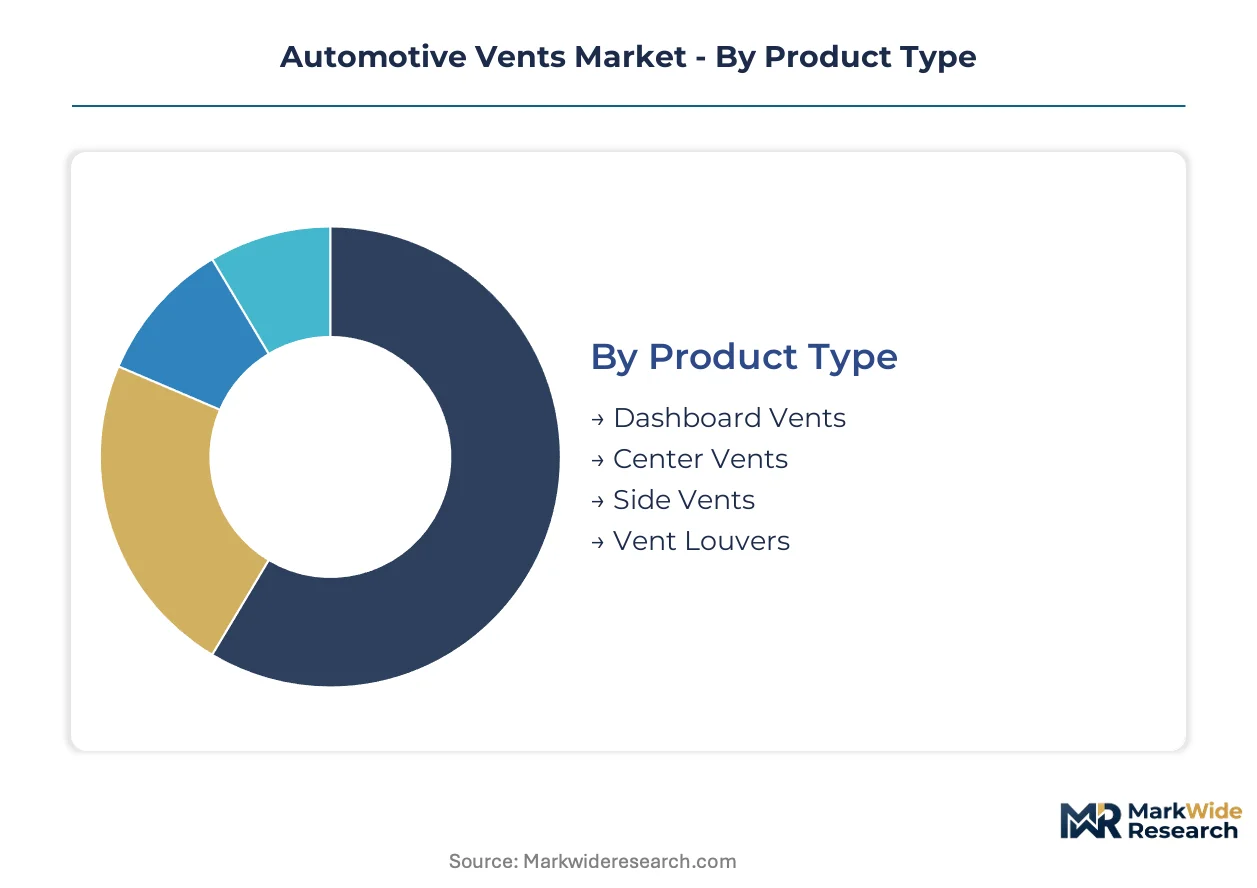
Automotive vent segmentation reveals how regulatory pressure and electrification are fragmenting procurement specifications. OEMs now source distinct vent architectures for battery thermal management versus cabin comfort functions.
Product Type:
EPA Tier 3 emissions standards and NHTSA safety protocols differentiate vent performance requirements across mounting positions and aperture geometries.
- Dashboard Vents:Multi-aperture polypropylene or ABS housings positioned at instrument panel centerlines for direct occupant airflow. German OEM engineering centers in Stuttgart specify integrated sensor modules here for premium electric vehicle platforms, absorbing higher unit costs for cabin digitization roadmaps.
- Center Vents:Symmetrically paired outlets flanking infotainment displays with standardized 60mm or 80mm nozzle diameters. Fleet procurement departments in the United States commercial vehicle segment concentrate volume on these configurations for HVAC module standardization across truck and van nameplates.
- Side Vents:Door-mounted or B-pillar integrated outlets serving rear cabin zones. Configurations remain manual-control dominant in mass-market segments.
- Vent Louvers:Adjustable blade assemblies controlling directional airflow. Aluminum variants face margin pressure from London Metal Exchange pricing volatility.
Established volume favors Center Vents; emerging adoption favors Dashboard Vents.
Material:
REACH substance restrictions and RoHS compliance timelines are forcing reformulation cycles that extend qualification timelines for compound suppliers.
- Plastic:Injection-molded polypropylene and ABS dominate mass production for weight reduction and acoustic damping. India PLI scheme incentives are accelerating localized compounding capacity for domestic OEM supply.
- Metal:Extruded aluminum alloys and stamped steel brackets for premium thermal conductivity and structural rigidity. REACH authorization pressures on fluoropolymer feedstocks are compressing membrane-integrated metal vent margins.
- Rubber:EPDM and silicone gaskets sealing vent-to-duct interfaces. Specifications tighten under EPA material emissions frameworks.
- Composite:Glass-fiber reinforced polymers bridging weight and strength requirements. German and Scandinavian electric vehicle segments absorb initial cost premiums for fluorine-free barrier alternatives.
Procurement scale concentrates in Plastic; performance premiums accrue to Composite.
Vehicle Type:
Battery thermal management complexity is decoupling vent system architectures from legacy internal-combustion platform designs.
- Passenger Cars:Sedan and hatchback configurations with standardized HVAC module footprints. Volume concentration supports direct-to-Tier-1 digital procurement channels.
- Trucks:Commercial vehicle specifications emphasizing durability and total-cost-of-ownership analytics. United States fleet operators consolidate supplier rosters here.
- SUVs:Extended cabin zones requiring multi-zone climate control with increased vent count per vehicle. Three-row configurations drive content expansion.
- Electric Vehicles:Distinct battery-cabin air segregation systems with reduced engine-bay heat sourcing. Sensor-vent convergence creates electronics-content revenue streams for integrated particulate and CO2 monitoring.
Current assembly volume centers on Passenger Cars; steepest expansion trajectory belongs to Electric Vehicles.
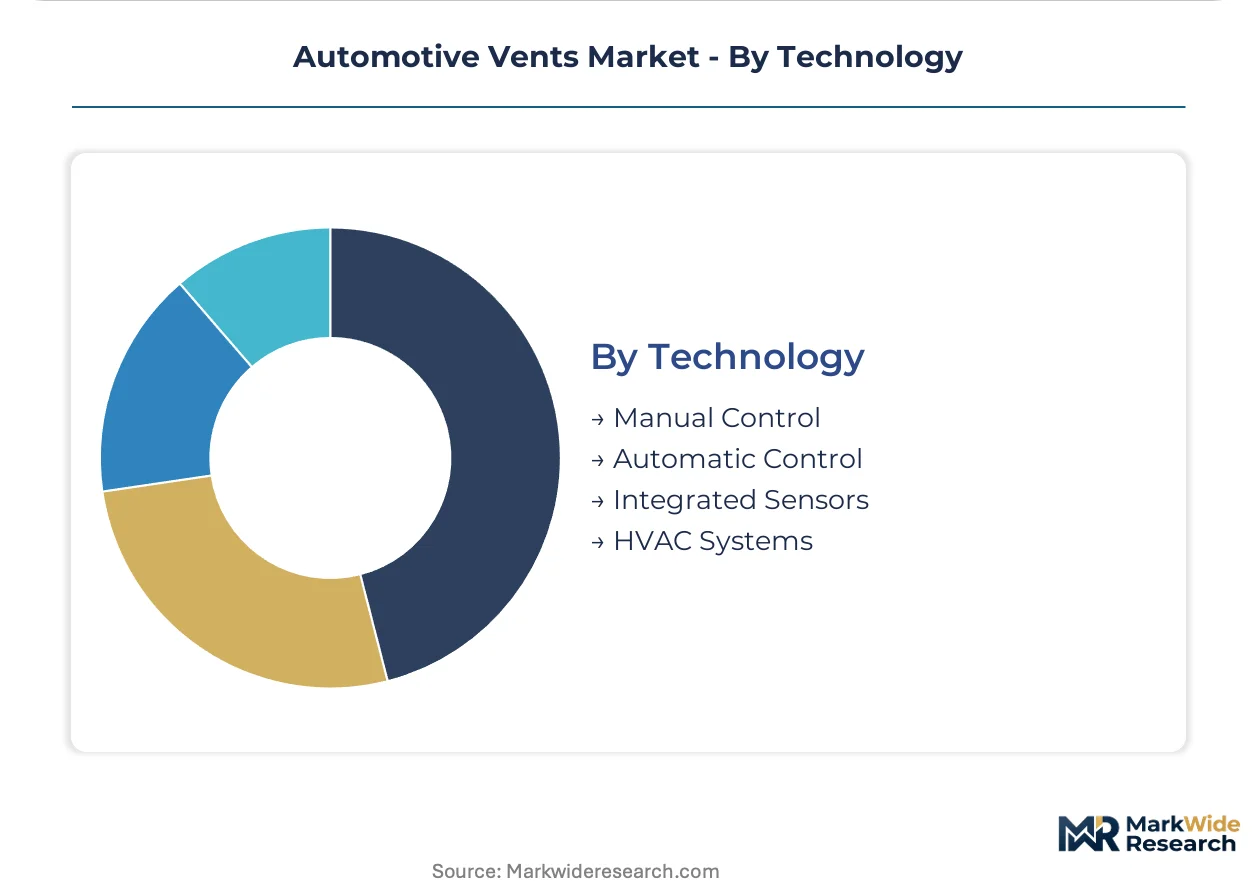
Technology:
Computational fluid dynamics expertise scarcity is extending hiring cycles for suppliers engineering coupled battery-cabin thermal models.
- Manual Control:Mechanical dial or slider actuation with cable-linkage mechanisms. Mass-market segments face margin compression as digitization accelerates.
- Automatic Control:Motorized damper actuation with temperature and humidity feedback loops. Smart vent actuators are converging with active grille shutter systems.
- Integrated Sensors:Particulate matter, CO2, and VOC detection embedded in vent housings. Dashboard mounting positions command premium positioning.
- HVAC Systems:Complete module integration including blower motors, evaporators, and heater cores. Valeo SA anchors European supply relationships through bundled production.
Assembly complexity favors HVAC Systems; margin expansion concentrates in Integrated Sensors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States fleet procurement departments demonstrate the lowest price elasticity, absorbing premium sensor-vent integration costs, while Indian mass-market segments exhibit acute sensitivity to polypropylene compound pricing fluctuations.
United States
NHTSA occupant safety standards and EPA Tier 3 emissions frameworks are tightening cabin air quality mandates. Fleet operators in the commercial vehicle segment consolidate supplier rosters to capture volume leverage on standardized HVAC modules. Detroit-area engineering centers specify advanced filtration-vent integration for premium electric vehicle platforms.
Germany
Stuttgart and Munich-based OEM technical headquarters drive specification upgrades for integrated HVAC-vent modules across European nameplates. REACH authorization requirements for per- and polyfluoroalkyl substances are compelling membrane suppliers to accelerate fluorine-free alternatives. Baden-Württemberg engineering clusters absorb initial cost premiums for compliant materials in high-performance electric vehicle segments.
China
Dual carbon goals and MIIT vehicle efficiency standards are reshaping thermal management system requirements for domestic electric vehicle manufacturers. Yangtze River Delta automotive clusters are localizing vent system production to serve BYD, NIO, and XPeng expansion. Shanghai-based engineering centers specify battery-cabin air segregation architectures distinct from legacy internal-combustion designs.
India
PLI scheme production-linked incentives for advanced automotive components are attracting vent system localization investments serving domestic OEM expansion. BIS certification requirements and DGFT import substitution policies favor domestic compound suppliers. Tamil Nadu and Gujarat manufacturing corridors are scaling polypropylene compounding capacity for Maruti Suzuki and Tata Motors supply.
Japan
METI energy efficiency standards and JIS automotive material specifications govern vent thermal performance and emissions compliance. Kanto region engineering centers integrate sensor-vent convergence into next-generation cabin digitization roadmaps. Toyota City supplier parks coordinate just-in-sequence delivery of HVAC-vent modules for hybrid and battery electric nameplates.
Automotive Vents Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure where membrane specialists command premium positioning and scale fabricators capture volume share. The vendor base spans fluoropolymer innovators, integrated HVAC module producers, and regional injection molding specialists. Two dominant archetypes emerge: material science leaders with in-house breathable membrane capabilities, and system integrators bundling thermal management complexity reduction. Competitive moves concentrate on strategic partnerships for sensor integration and geographic expansion into PLI-incentivized manufacturing corridors.
Within the material science tier, W. L. Gore & Associates exemplifies fluoropolymer expertise applied to high-performance breathable membrane segments, while Valeo SA anchors European supply relationships through integrated HVAC-vent module production. MAHLE GmbH occupies a position exemplifying thermal management system bundling that reduces OEM assembly complexity. These three entities represent the archetype spectrum from specialized membrane innovation through full-system integration.
| Leading Market Players |
|---|
| Faurecia SE |
| Porex Corporation |
| W. L. Gore & Associates |
| Nifco Inc. |
| Filtration Group Corporation |
| Parker Hannifin |
| Donaldson Company |
| Valeo SA |
| MAHLE GmbH |
| Others |
Value Network & Pricing Analysis
Capacity utilization at German and Chinese membrane compounding facilities shapes both supply concentration and price floors for breathable vent materials. Polypropylene resin procurement at scale anchors cost structures for mass-market dashboard and center vent variants, while fluoropolymer membrane specialists command premium positioning through captive material science capabilities.
Pricing Analysis
Aftermarket parts and service revenue tiers drive lifetime value capture for vent system suppliers. Three-tier pricing structure across premium sensor-integrated, standard automatic-control, and economy manual-control levels dominates OEM procurement. Price differentiation rests on REACH certification grade and HVAC module bundling scope. Cost compression in economy manual-control segments is intensifying because of direct-to-Tier-1 digital procurement channels. Fleet operators in the United States commercial vehicle segment demonstrate lowest price elasticity, absorbing sensor-vent integration premiums, while Indian mass-market buyers exhibit acute sensitivity to polypropylene compound fluctuations.
Supply Chain Analysis
Just-in-sequence delivery preferences dominate Toyota City supplier parks and Stuttgart engineering clusters, while strategic stockpiling of fluoropolymer feedstocks persists among membrane specialists facing REACH authorization uncertainty. Geographic supply concentration centers on Germany, China, and Mexico for injection-molded housings, with Japan and South Korea anchoring precision actuator production. Raw material dependencies draw from polypropylene resin, PTFE and ePTFE membranes, and aluminum alloy billets. Single-source vulnerability in fluorochemical feedstocks poses structural risk. Distribution runs through Tier-1 HVAC module integrators serving OEM final assembly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive vents market functions as a defensive-moat story anchored by regulatory entrenchment. Multi-jurisdictional certification requirements for NHTSA, EPA, and REACH compliance create switching costs that protect qualified supplier relationships.
For Market Incumbents: Secure membrane material science capabilities through backward integration into fluoropolymer or fluorine-free alternative production. Lock in long-term supply agreements with German and Chinese OEM engineering centers before specification cycles close. Capacity addition in Tamil Nadu and Gujarat manufacturing corridors captures India PLI scheme incentives. Certification investment in battery-cabin air segregation architectures defends against emerging thermal management specialists. For New Entrants and Emerging Players: Sensor-vent convergence service gaps in mass-market electric vehicle segments offer white-space entry points. Target manual-control replacement demand in aging internal-combustion fleets where incumbents have deprioritized R&D. Penetrable geography centers on India domestic OEM supply, where BIS certification and DGFT import substitution policies favor localized compounders. Go-to-market angle: direct digital procurement partnerships with fleet operators bypassing traditional Tier-1 channels. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors material science specialists with in-house membrane capabilities over pure-play system integrators. Long-term viability across the analysis window hinges on fluorine-free barrier transition completion and battery thermal interface specification ownership. Acquisition target archetype: mid-cap membrane compounders with REACH-compliant formulations and German OEM qualification. Signal to watch: ECHA substance restriction expansion timelines crossing implementation thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| Fluorine-Free Membrane Transition | REACH authorization pressures force PTFE alternative development for German electric vehicle supply. |
| Battery-Cabin Air Segregation Architecture | MIIT efficiency standards in China reshape thermal management specifications for domestic OEMs. |
| Sensor-Vent Module Integration | NHTSA safety standards in the United States drive particulate and CO2 detection embedding. |
| India PLI Scheme Localization | BIS certification requirements favor domestic compounding capacity for Maruti Suzuki and Tata Motors. |
| Direct Fleet Procurement Channel | United States commercial vehicle operators consolidate supplier rosters for total-cost-of-ownership leverage. |
Research Methodology
Cross-validation between primary interviews with Tier-1 supplier procurement managers, OEM platform engineers, aftermarket distributors, and dealership operations heads anchors the qualitative findings. Secondary validation draws from vehicle production databases, IHS Markit registration data, EPA Tier 3 emissions filings, and ECHA REACH substance restriction updates. Bottom-up segment sizing triangulates against top-down OEM HVAC module spend analysis.
Sensitivity analysis around polypropylene resin pricing, fluoropolymer feedstock availability, and electric vehicle penetration trajectories informs scenario boundaries. Segmentation dimensions modeled span vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster across the projection horizon. CAGRs derive from production volume forecasts weighted by vent count per vehicle and technology tier mix. Battery thermal interface specification evolution and sensor integration adoption curves serve as industry-specific forecast inputs.
Forecasts assume regulatory continuity in EPA, NHTSA, REACH, and India PLI scheme regimes; material policy shifts would require re-modeling. Specific risk factors include ECHA per- and polyfluoroalkyl substance authorization expansion, London Metal Exchange aluminum volatility, and OEM platform consolidation reducing vent specification diversity. Revision becomes warranted when battery-cabin thermal architecture standardization crosses adoption thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Seat Track Market
Automotive Parts
Vehicle Transfer Case Market
Automotive Parts
Electric Vehicle Aluminum Electric Drive Parts Market
Automotive Parts
Tappet Market
Automotive Parts
Automotive Axle and Propeller Shaft Market
Automotive Parts
Automotive Intercooler Market
Automotive Parts
Cylinder Head Cover Market
Automotive Parts
South Korea Automotive Parts Zinc Die Casting Market
Automotive Parts
Japan Ball Bearing Market
Automotive Parts
Brazil Automotive Parts Magnesium Die Casting Market
Automotive Parts
Europe Commercial Vehicles Lubricants Market
Automotive Parts
South Korea Passenger Vehicles Lubricants Market
Automotive Parts
Passenger Car Motor Oil Market
Automotive Parts
Wiper Blade Market
Automotive Parts
France Automotive Airfilters Market
Automotive Parts
Europe Automotive Lubricants Market