
 Car Recycling Market | 2026-2036
Car Recycling Market Size, Share, and Industry Trends Forecast 2026-2036
Car Recycling Market Analysis
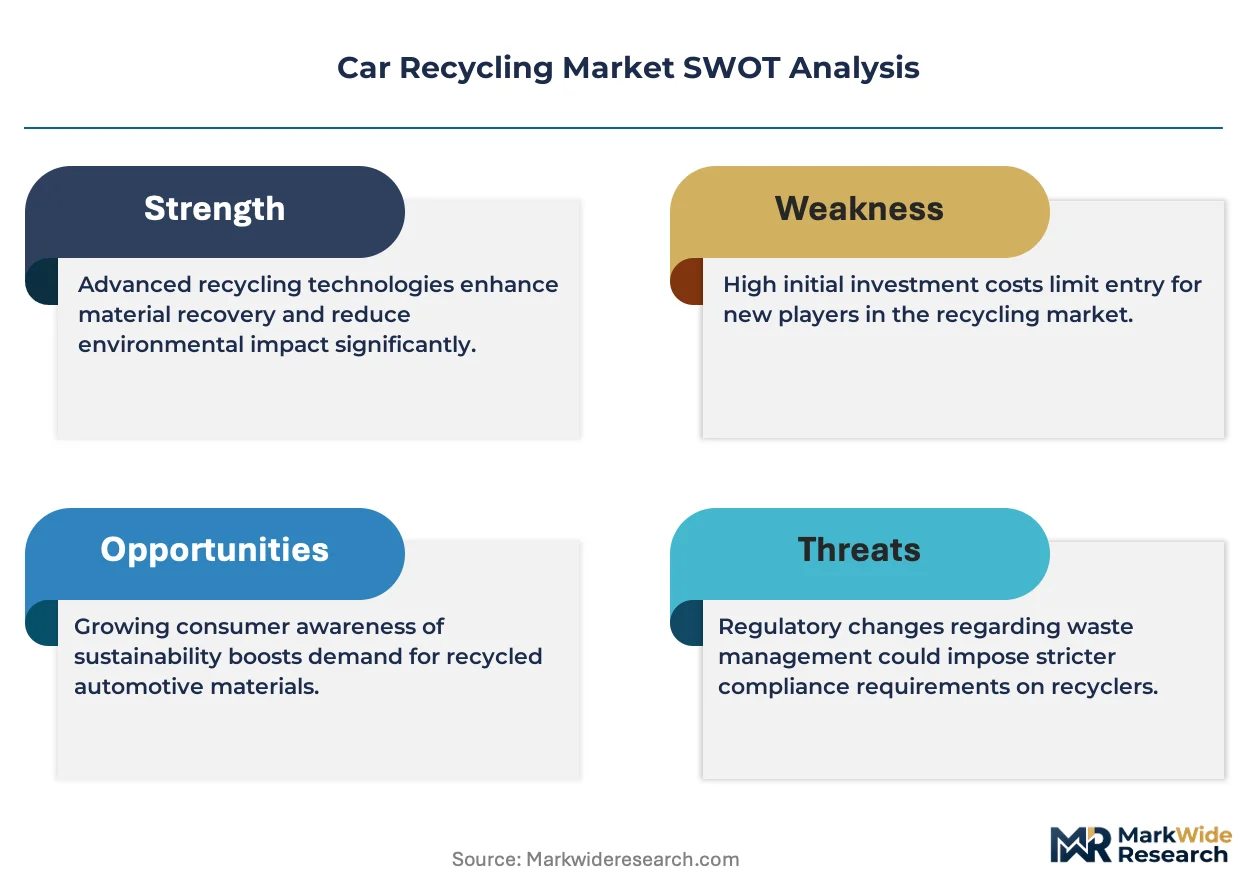
ELV Directive compliance thresholds is expanding the capital requirements for new entrants across European shredding operations. SEDA-Umwelttechnik GmbH anchors its position through integrated dismantling systems that process multiple vehicle categories on shared lines. Cyclic Materials differentiates via proprietary rare earth magnet recovery, a capability few competitors have scaled. Junk Car Medics controls a digital auction platform that connects scrap yards directly to steel mills, bypassing traditional broker layers.
Car recycling encompasses the systematic decommissioning, dismantling, and material recovery of end-of-life vehicles to reintroduce ferrous and non-ferrous metals, polymers, and glass into industrial supply chains; modern facilities achieve steel recovery rates exceeding 85 percent through combined shredding and magnetic separation processes. The primary purpose is to reduce virgin resource extraction while meeting manufacturer demand for recycled feedstock in automotive and construction applications. Steel dominates by volume across the Material Type dimension, though aluminum is gaining share as lightweight vehicle designs raise per-unit aluminum content in incoming scrap pools. Shredding leads the Recycling Process category in throughput volume, yet material recovery commands superior margins due to copper, rare earth, and precious metal concentration.
The EPA oversees hazardous fluid management and air emissions at US shredding facilities, while the EU's REACH framework restricts substances in recycled plastics destined for automotive reuse. China's MEE enforces dual carbon goals that tighten energy intensity standards for scrap-based steelmaking, redirecting regional scrap flows toward certified processors. Stakeholders must track how battery-electric vehicle penetration alters the material composition of future scrap streams, particularly the rising lithium-ion and copper fractions that existing shredding infrastructure handles poorly.
Market Dynamics
The collision of battery-electric vehicle retirement waves with legacy shredding infrastructure built for internal-combustion material profiles is forcing capital redeployment across dismantling networks. Turkey's electric arc furnace sector now competes with Southeast Asian mills for shredded steel feedstock, tightening arbitrage windows.
Growth Catalysts
- EU End-of-Life Vehicle Directive:Material recovery mandates tighten every three years, compelling shredder operators to upgrade sensor arrays for aluminum and copper separation. Compliance investments create barrier-to-entry advantages for scaled processors.
- Electric arc furnace expansion:Steelmakers in Turkey, India, and Vietnam prioritize shredded auto scrap over pig iron for rebar and flat-rolled products. Furnace operators pay premiums for consistent chemistry grades.
- Rare earth magnet recovery:Sensor-based sorting from Cyclic Materials and Sortera Alloys extracts neodymium and dysprosium from drive motors at yields previously unachievable through manual dismantling.
Market Restraints
- Scrap steel price volatility:Turkish rebar export demand fluctuates with construction cycles in the Middle East and North Africa, compressing shredder margins when barge freight rates spike simultaneously.
- Lithium-ion handling infrastructure:Existing shredding lines lack thermal containment and electrolyte neutralization systems required for battery-electric vehicle packs, stranding capital in legacy configurations.
- REACH substance restrictions:Recovered automotive plastics face downstream rejection when flame-retardant content exceeds thresholds, limiting polymer circularity to lower-value applications.
Strategic Opportunities
- India's vehicle scrappage policy:Mandatory fitness testing for commercial vehicles over fifteen years creates predictable feedstock volumes for organized dismantlers in Delhi-NCR and Maharashtra.
- Battery second-life applications:Stationary energy storage operators in California and Germany source retired EV modules before shredder entry, extending value extraction through cascade use.
- Digital auction platforms:Direct mill-to-yard connectivity bypasses traditional scrap broker layers, compressing transaction costs and improving price transparency for shredded ferrous grades.
Industry Challenges
- Hydrogen embrittlement detection:Advanced high-strength steels in newer vehicle architectures require spectroscopic sorting capabilities that few European shredders have deployed at commercial scale.
- Certification timeline compression:ELV Directive compliance audits now demand six-month documentation trails for material flows, straining mid-tier operators with limited quality management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Car Recycling Market |
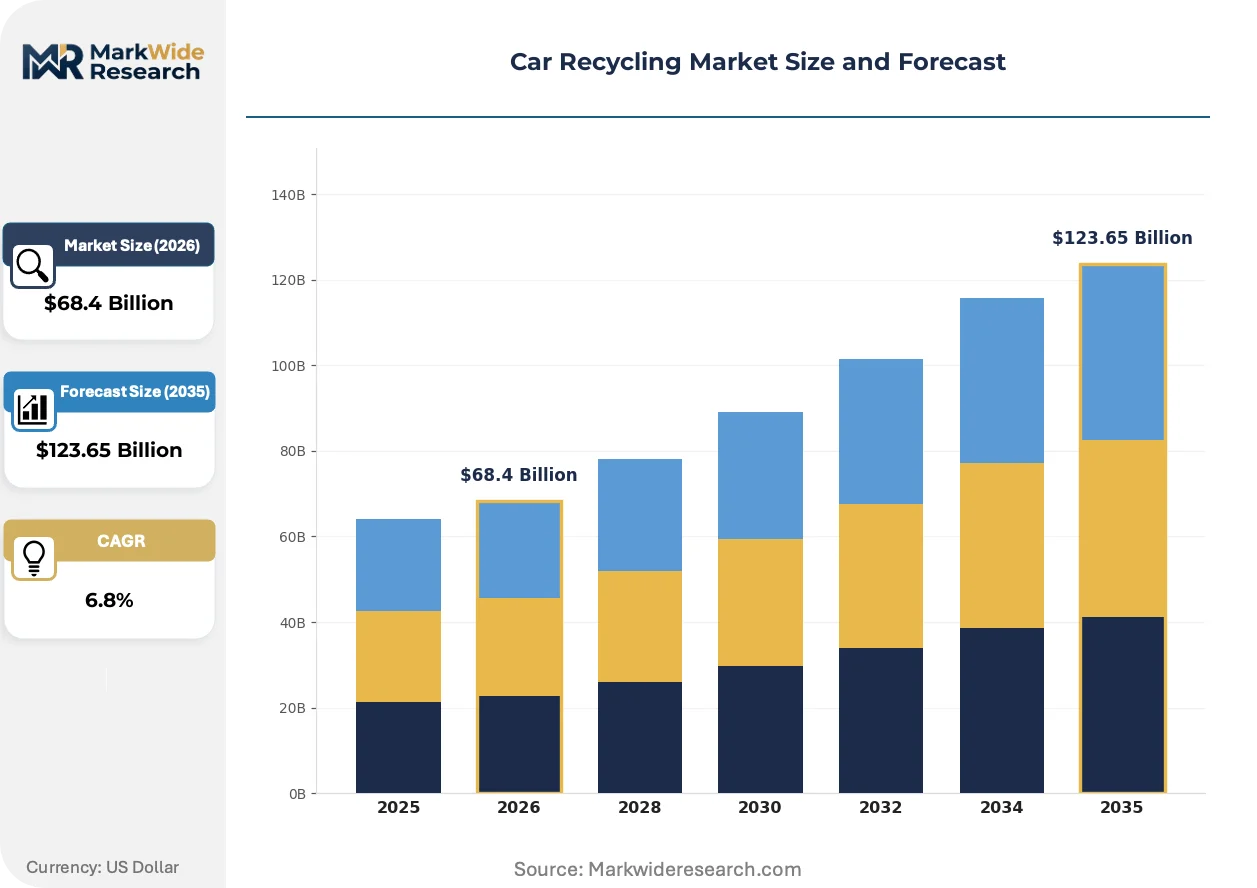
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $123.65 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Steel, Aluminum, Plastic, Glass End-of-Life Vehicle Category: Passenger Cars, Trucks, Motorcycles, Buses Recycling Process: Shredding, Dismantling, Refurbishing, Material Recovery Distribution Channel: Direct Sales, Online Platforms, Auctions, Scrap Yards |
| Companies Covered | Junk Car Medics, Vartega, SEDA-Umwelttechnik GmbH, ScrapMyCar, Cireon, Cyclic Materials, Rubicon, Agilyx, Sortera Alloys, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Car Recycling Market Emerging Trajectories
Automotive material evolution is fragmenting established recycling pathways. Lightweighting alloys, bonded multi-material assemblies, and solid-state battery chemistries each demand processing adaptations that shred-and-sort infrastructure handles poorly.
Sensor-based rare earth recovery is rewriting competitive positioning in non-ferrous separation. X-ray fluorescence and laser-induced breakdown spectroscopy now identify magnet alloys at conveyor speeds exceeding five meters per second. German steel mills and Japanese trading houses contract directly for these concentrated outputs, bypassing traditional mixed-heavy-fraction brokers. The technology is compressing payback periods for capital-intensive sorting investments from seven years to under four.
China's MEE dual carbon enforcement tightens energy intensity benchmarks for scrap-based steelmaking. Provincial regulators in Jiangsu and Hebei now require documented carbon footprints for shredded imports, favoring processors with ISO 14064-verified emissions accounting. This policy rotation redirects regional scrap flows toward certified dismantlers with integrated shredder-melter linkages, marginalizing informal collection networks.
Procurement consolidation among Turkish rebar producers reshapes feedstock sourcing patterns. Mill procurement teams now require guaranteed chemistry ranges and monthly volume commitments that fragmented European shredders struggle to meet. Long-term offtake contracts with fixed-adjustment mechanisms are displacing spot-market transactions, concentrating supply relationships around vertically integrated yard-to-mill operators in Belgium and the Netherlands.
Car Recycling Market Segmentation
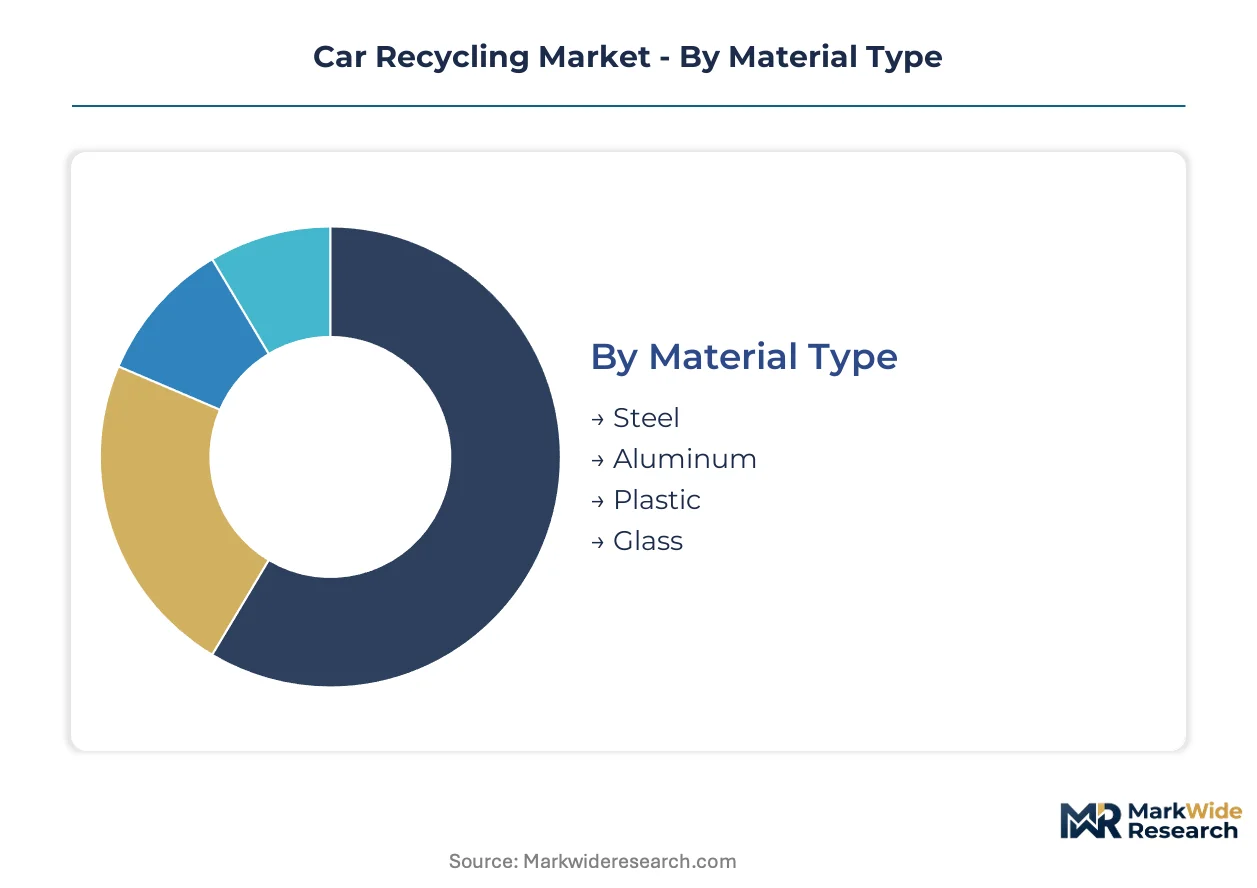
Car recycling economics hinge on material density and processing sophistication. Segmentation reveals where capital earns returns versus where commodity cycles erode margins.
Material Type:
Steel dominates tonnage flows while aluminum and rare earth fractions capture value premiums.
- Steel:Ferrous scrap from shredded vehicle hulks supplies electric arc furnaces in Turkey and Vietnam. Turkish rebar producers pay chemistry-grade premiums for consistent shredded auto feedstock.
- Aluminum:Lightweight vehicle architectures raise per-unit aluminum content in incoming scrap pools. Sensor-based sorting from Sortera Alloys extracts cast and wrought grades at conveyor speeds exceeding five meters per second.
- Plastic:Automotive polymers face downstream rejection under REACH flame-retardant thresholds, limiting circularity to lower-value construction applications.
- Glass:Laminated windshield fractions require specialized delamination equipment that few European shredders operate at commercial scale.
Today's leader: Steel. Tomorrow's challenger: Aluminum.
End-of-Life Vehicle Category:
Commercial vehicle retirement waves generate predictable feedstock volumes against fragmented passenger car collection.
- Passenger Cars:Lightweighting alloys and bonded multi-material assemblies complicate established shred-and-sort pathways. India's scrappage policy channels organized dismantlers toward fitness-tested commercial fleets instead.
- Trucks:Heavy-duty commercial vehicles concentrate steel mass and copper-dense electrical systems. India's mandatory fitness testing for vehicles over fifteen years creates reliable feedstock for Delhi-NCR processors.
- Motorcycles:Two-wheeler retirement volumes concentrate in Southeast Asian urban corridors with limited formal collection infrastructure.
- Buses:Transit fleet electrification schedules generate synchronized battery pack retirement waves requiring thermal containment capabilities.
Trucks anchor current throughput. Passenger cars hold the steepest expansion trajectory as battery-electric retirement volumes compound.
Recycling Process:
Throughput volume concentrates in shredding while material recovery commands superior margins.
- Shredding:Combined shredding and magnetic separation achieves steel recovery rates exceeding 85 percent. Legacy lines lack thermal containment systems required for lithium-ion battery packs.
- Dismantling:Manual decommissioning preserves rare earth magnet integrity before shredder entry. SEDA-Umwelttechnik GmbH processes multiple vehicle categories on shared dismantling lines.
- Refurbishing:Second-life battery modules bypass shredders entirely, supplying stationary storage operators in California and Germany through cascade use arrangements.
- Material Recovery:X-ray fluorescence and laser-induced breakdown spectroscopy identify magnet alloys at yields manual dismantling cannot match. Cyclic Materials contracts directly with German steel mills for concentrated rare earth outputs.
Shredding captures volume leadership. Material recovery is climbing the fastest as sensor technology compresses capital payback periods.
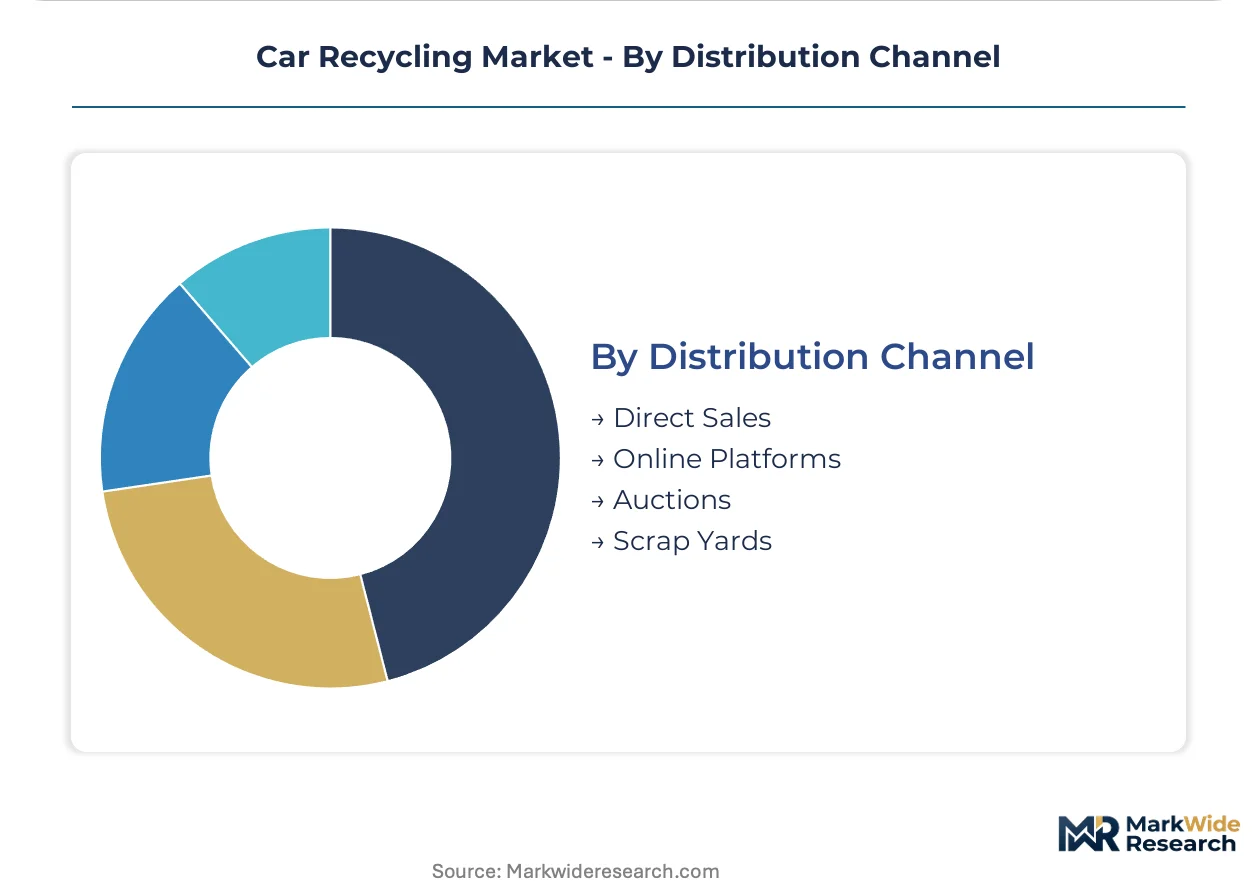
Distribution Channel:
Digital connectivity is displacing broker intermediaries in ferrous scrap transactions.
- Direct Sales:Turkish mill procurement teams now require guaranteed chemistry ranges and monthly volume commitments. Long-term offtake contracts displace spot-market transactions.
- Online Platforms:Junk Car Medics connects scrap yards directly to steel mills, compressing transaction costs and improving price transparency for shredded grades.
- Auctions:Digital auction platforms bypass traditional scrap broker layers, concentrating supply relationships around vertically integrated yard-to-mill operators.
- Scrap Yards:Fragmentated European yards struggle to meet Turkish rebar producer consolidation requirements for documented carbon footprints and ISO 14064-verified emissions accounting.
Direct sales maintains incumbent position. Online platforms are gaining share fastest as procurement digitization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled dismantling labor pools in Germany, Turkey, and India anchor regional processing capacity. Regulatory divergence across EPA, EU, and MEE jurisdictions fragments compliance architectures. Mill procurement consolidation in each geography favors operators with documented carbon accounting.
Germany
Electric arc furnace operators in the Ruhr Valley source shredded auto scrap for flat-rolled steel production. The EU End-of-Life Vehicle Directive mandates 95% material recovery rates by weight, forcing facility upgrades. SEDA-Umwelttechnik GmbH operates integrated dismantling systems from its Baden-Württemberg base.
Turkey
Rebar manufacturers along the Marmara Sea coast compete for consistent shredded steel chemistry grades. The country's Ministry of Environment enforces hazardous waste tracking for imported auto hulks. Izmir processors now offer guaranteed monthly volume commitments to secure mill offtake contracts.
United States
Stationary energy storage operators in California source retired EV modules before shredder entry. EPA hazardous fluid management rules govern dismantling facility emissions. Texas Gulf Coast shredders face rising barge freight costs when Turkish demand spikes.
China
Jiangsu and Hebei provincial regulators require ISO 14064-verified emissions accounting for shredded steel imports. The MEE dual carbon goals tighten energy intensity benchmarks for scrap-based steelmaking. Yangtze River Delta processors redirect flows toward certified dismantlers with integrated shredder-melter linkages.
India
Delhi-NCR dismantlers process fitness-tested commercial vehicles under mandatory scrappage policy. The Ministry of Road Transport mandates fifteen-year fitness testing for commercial fleets. Maharashtra organized dismantlers invest in sensor arrays to separate aluminum and copper fractions.
Car Recycling Market Vendor Landscape
The competitive structure tilts toward technology-integrated dismantling specialists over commodity shredders. Tier-one operators combine sensor-based sorting with direct mill relationships. Three archetypes dominate: integrated dismantling-system providers, rare earth recovery specialists, and digital auction platforms. Capacity consolidation and backward integration into dismantling represent the dominant competitive moves.
Among sensor-based sorting specialists, Cyclic Materials and Sortera Alloys exemplify the rare earth recovery archetype through proprietary magnet separation capabilities. SEDA-Umwelttechnik GmbH anchors the integrated-systems tier with multi-vehicle processing lines. Junk Car Medics occupies the digital platform position, connecting scrap yards directly to steel mills.
| Leading Market Players |
|---|
| Junk Car Medics |
| Vartega |
| SEDA-Umwelttechnik GmbH |
| ScrapMyCar |
| Cireon |
| Cyclic Materials |
| Rubicon |
| Agilyx |
| Sortera Alloys |
| Others |
Supply Flow & Price Mechanics
Barge freight rates from Texas Gulf Coast ports to Turkish Marmara Sea mills cascade through shredded steel contract pricing, compressing margins for European shredders when Turkish rebar export demand spikes simultaneously. Chemistry-grade premiums for consistent shredded auto feedstock separate long-term offtake contracts from spot-market transactions, with documented carbon footprints commanding additional tier separation.
Pricing Analysis
Shredded steel pricing splits between bundled long-term offtake contracts with guaranteed monthly volumes and unbundled spot-market sales subject to freight volatility. Price differentiation hinges on ISO 14064-verified emissions accounting and guaranteed chemistry ranges, with Turkish mill procurement teams paying premiums for both. Cost compression in spot-market tiers is intensifying because barge freight spikes and scrap steel price volatility coincide during Middle East construction cycles. Fragmented European yards exhibit highest price sensitivity due to inability to meet consolidation requirements, while vertically integrated yard-to-mill operators in Belgium and the Netherlands command pricing power through volume commitments.
Supply Chain Analysis
Regional distribution centers in Belgium and the Netherlands operate as consolidation hubs for fragmented European scrap flows destined for Turkish rebar mills. Supply concentrates in Germany, Turkey, and India, with skilled dismantling labor pools anchoring regional processing capacity. Raw material flows draw from end-of-life vehicle retirement waves, battery-electric vehicle pack volumes, and commercial fleet scrappage under India's mandatory fitness testing. Single-source vulnerability exists in rare earth magnet recovery, where Cyclic Materials and Sortera Alloys dominate sensor-based sorting capabilities. Distribution runs through digital auction platforms that bypass traditional scrap broker layers, connecting scrap yards directly to steel mills.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The car recycling market functions as a stable compounder, with regulatory mandates for material recovery tightening every three years under the EU End-of-Life Vehicle Directive and creating predictable reinvestment cycles.
For Market Incumbents: Anchor market position through backward integration into dismantling operations and certification investment for ISO 14064-verified emissions accounting. SEDA-Umwelttechnik GmbH demonstrates defensive positioning through multi-vehicle processing lines that spread capital across passenger car, truck, and bus categories. Sensor array upgrades for aluminum and copper separation represent the critical lever for ELV Directive compliance barrier maintenance against mid-tier operators with limited quality management systems. For New Entrants and Emerging Players: India's vehicle scrappage policy opens a window for organized dismantlers to capture predictable commercial vehicle feedstock volumes in Delhi-NCR and Maharashtra. Battery second-life applications before shredder entry represent the most penetrable white space, with stationary energy storage operators in California and Germany sourcing retired EV modules through cascade use arrangements. Digital platform connectivity offers a direct go-to-market angle for bypassing traditional scrap broker layers. For Investors and Strategic Acquirers: Consolidation pressure builds where fragmented European yards struggle to meet Turkish mill procurement requirements for documented carbon footprints and guaranteed chemistry ranges. The five-to-ten-year viability window favors technology-integrated dismantling specialists with sensor-based sorting capabilities over commodity shredders. Acquisition target archetype: rare earth recovery specialists with proprietary magnet separation capabilities. The signal to watch is battery-electric vehicle retirement wave timing and lithium-ion handling infrastructure deployment rates.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-Based Sorting Deployment | Cyclic Materials contracts directly with German steel mills for concentrated rare earth outputs. |
| Long-Term Offtake Contracting | Turkish rebar producers secure guaranteed chemistry ranges and monthly volume commitments from Belgian processors. |
| Digital Platform Integration | Junk Car Medics connects scrap yards directly to steel mills, compressing transaction costs. |
| Backward Integration into Dismantling | Vertically integrated yard-to-mill operators concentrate supply relationships around Rotterdam and Antwerp hubs. |
| Carbon Footprint Certification | ISO 14064-verified emissions accounting redirects Chinese scrap flows toward certified Jiangsu and Hebei processors. |
Methodological Framework
Coverage spans Germany, Turkey, the United States, China, and India, with primary inputs from each market's shredding and dismantling operations. The analysis combines structured interviews with facility operations managers, mill procurement leads at Turkish rebar producers, regulatory compliance officers, and aftermarket battery second-life operators with secondary validation from customs and trade data, EPA enforcement records, EU ELV Directive compliance filings, and MEE dual carbon policy disclosures. Bottom-up facility capacity modeling triangulates against top-down steel production and scrap consumption aggregates.
Granularity-level framing segments the market by material type, end-of-life vehicle category, recycling process, and distribution channel at the country level. CAGRs derive from regression analysis of historical scrap price series, vehicle retirement volume projections, and regulatory compliance cost trajectories across the analysis window. Industry-specific forecast inputs include battery-electric vehicle penetration rates affecting future scrap stream composition and electric arc furnace expansion schedules in Turkey, India, and Vietnam.
Revisions become necessary when battery-electric vehicle retirement waves accelerate beyond legacy shredding infrastructure adaptation timelines or when Turkish rebar export demand collapses due to Middle East construction cycle downturns. Forecasts reflect documented assumptions about sensor technology deployment rates and regulatory enforcement intensity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Maintenance & Aftermarket
Car Duster Market
Vehicle Maintenance & Aftermarket
Road Maintenance Service Market
Vehicle Maintenance & Aftermarket
Catenary Maintenance Vehicle Market
Vehicle Maintenance & Aftermarket
Automotive Aftermarket Glass Market
Vehicle Maintenance & Aftermarket
Classic Car Restoration and Restomod Services Market
Vehicle Maintenance & Aftermarket
OBD-Linked Predictive Maintenance Diagnostic Platforms Market
Vehicle Maintenance & Aftermarket
Vehicle Wash System Market
Vehicle Maintenance & Aftermarket
Middle East and Africa Automotive Aftermarket Glass Market
Vehicle Maintenance & Aftermarket
Non OEM EV MRO Market
Vehicle Maintenance & Aftermarket
APEJ Automotive Aftermarket Market
Vehicle Maintenance & Aftermarket
Nitrogen Tire Inflators Market
Vehicle Maintenance & Aftermarket
Car Polisher Market
Vehicle Maintenance & Aftermarket
Car Glass Cleaner Market
Vehicle Maintenance & Aftermarket
Car Care Products Market
Vehicle Maintenance & Aftermarket
Global Automotive Lubricants Aftermarket Market
Vehicle Maintenance & Aftermarket
Car and Truck Wash Market