
 Vietnam Passenger Vehicles Lubricants Market | 2026-2036
Vietnam Passenger Vehicles Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Passenger Vehicles Lubricants Market Analytics
Market Context with Strategic Players
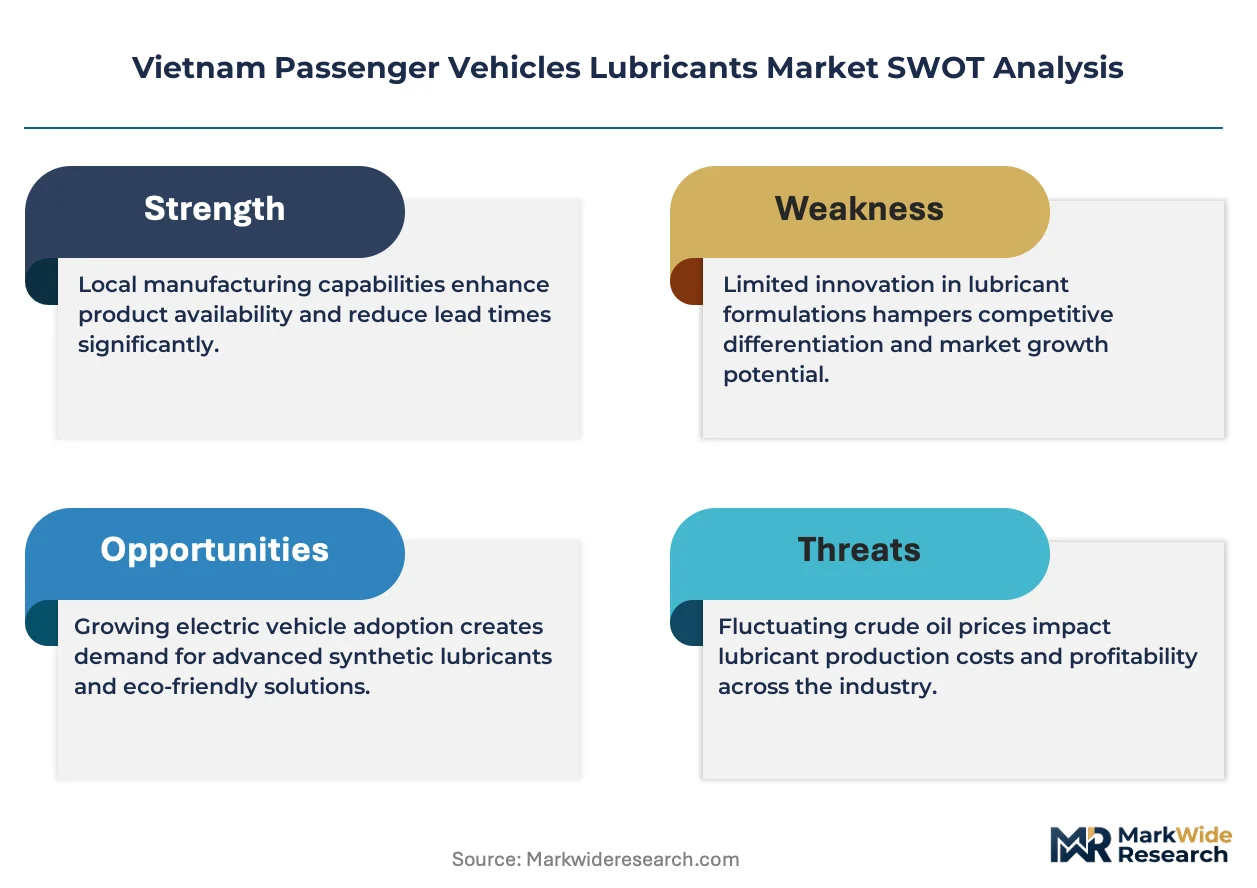
Premium synthetic formulations and commodity mineral oils are decoupling on price-performance positioning as Vietnamese consumers upgrade vehicle choices. Shell Vietnam leverages its nationwide retail network to anchor premium visibility in urban service stations. PVOIL competes through backward integration into base oil refining at its Dung Quat complex. BP Plc (Castrol) differentiates via technical partnerships with Japanese and Korean OEM assembly plants in Thai Nguyen and Vinh Phuc provinces.
Technical Definition and Structural Segments
Vietnam passenger vehicles lubricants comprise refined base oils blended with additive packages to reduce friction, dissipate heat, and prevent wear in internal combustion engines and drivetrains, with viscosity grades typically ranging from 0W-20 for modern gasoline direct-injection engines to 5W-40 for turbocharged applications. Engine oil dominates volume throughput due to mandatory drain intervals tied to warranty compliance, while transmission fluid commands margin premiums as continuously variable and dual-clutch automatics penetrate the sedan and SUV fleet. Workshop end users represent the fastest-growing demand channel as independent repair chains consolidate procurement away from fragmented retail purchases.
Regulatory Frame and Forward-Looking Close
Vietnam's Ministry of Transport enforces emission testing protocols through Circular 07/2021, while the Vietnam Register (VR) certifies lubricant performance claims against JASO and API standards; both frameworks elevate compliance costs for unbranded importers. The country's national standards body, STAMEQ, aligns domestic labeling with ASEAN harmonization roadmaps, reshaping product registration requirements. Stakeholders must monitor whether proposed carbon-neutral fuel standards will accelerate reformulated lubricant specifications before existing blending assets require retrofit.
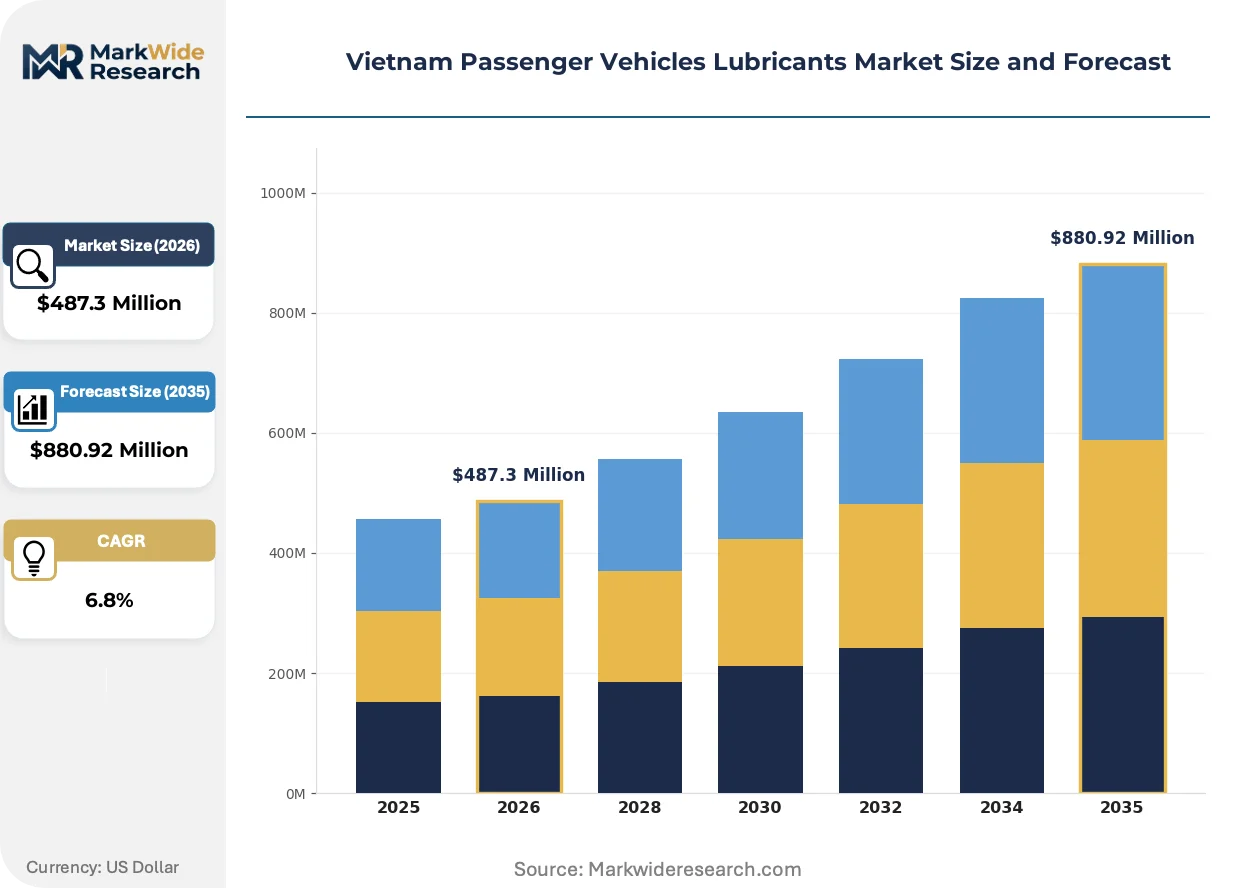
Market Dynamics
Circular 07/2021 is compressing drain intervals and forcing reformulation toward lower-viscosity grades as Vietnamese fleet operators face stepped-up emission testing protocols. The regulatory tightening is redistributing volume toward synthetic base stocks and away from commodity mineral oils.
Growth Catalysts
- Emission Standard Tightening:Vietnam's Ministry of Transport enforces stricter testing protocols under Circular 07/2021, compelling OEMs to specify lower-viscosity lubricants that reduce friction losses and improve fuel economy ratings.
- Ride-Hailing Fleet Expansion:Scheduled maintenance programs by fleet operators in Ho Chi Minh City and Hanoi are standardizing synthetic oil adoption across high-mileage vehicles operating under severe service conditions.
- Red River Delta Density:Vehicle concentration per capita in this northern corridor exceeds national benchmarks, concentrating aftermarket demand and enabling distributor scale economies.
Market Restraints
- Base Oil Import Dependency:Vietnam lacks domestic Group II/III base oil production, exposing blenders to freight cost volatility and currency fluctuation risks on API-certified feedstock.
- Unbranded Import Competition:Non-certified lubricants from regional traders exploit price-sensitive segments in secondary provinces, eroding margin pools for compliant registrants.
- Warranty Compliance Burden:OEM-authorized service networks enforce strict drain interval documentation, locking independent workshops out of newer vehicle parc service revenue.
Strategic Opportunities
- Mekong Delta Underpenetration:Can Tho and surrounding provinces exhibit lower synthetic penetration rates than northern corridors, presenting first-mover positioning for branded distributors.
- Continuously Variable Transmission Fluid:CVT-equipped vehicle sales growth creates a premium fluid category with technical switching costs and limited cross-compatibility.
- Workshop Channel Consolidation:Independent repair chains are centralizing procurement away from fragmented retail, favoring suppliers with direct fleet-account capabilities.
Industry Challenges
- Formulation Chemist Scarcity:Vietnam's technical talent pool for additive package blending and OEM co-engineering remains shallow relative to regional competitors.
- STAMEQ Registration Timelines:Product approval delays under ASEAN harmonization roadmaps extend time-to-market for reformulated SKUs.
- Legacy Equipment Compatibility:Older vehicle parc in provincial markets resists low-viscosity specifications, forcing dual inventory strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Passenger Vehicles Lubricants Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Transmission Fluid, Gear Oil, Hydraulic Oil Vehicle Type: SUV, Sedan, Hatchback, Coupe Distribution Channel: Retail, Online, Distributor, Service Station End User: Private Owners, Fleet Operators, Workshops, Car Dealerships |
| Companies Covered | Royal Dutch Shell Plc, Shell Vietnam, BP Plc (Castrol), Motul Vietnam JSC, PVOIL, Mekong Petrochemical JSC, TotalEnergies, AP Saigon Petro JSC, Petrolimex (PLX), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Passenger Vehicles Lubricants Market Evolving Landscape
Reformulation toward lower-viscosity grades is intersecting with channel consolidation and digital procurement platforms to reshape how lubricants reach end users. Three developments merit attention.
Additive package architecture is modularizing around discrete performance modules—detergent, dispersant, anti-wear, and friction modifier chemistries—that blenders can recombine for OEM-specific approvals. Vietnamese compounders are adopting this approach to reduce SKU complexity while maintaining Vietnam Register certification coverage. The modular design is compressing development cycles for Circular 07/2021-compliant formulations.
Vietnam's Ministry of Transport emission testing protocols are tightening enforcement through roadside inspection equipment deployment. The industrial consequence is accelerated parc turnover toward gasoline direct-injection and turbocharged engines requiring 0W-20 and 5W-30 specifications. Japanese and Korean OEM assembly plants in Thai Nguyen and Vinh Phuc provinces are responding by pre-specifying these grades in owner manuals.
Workshop procurement behavior is migrating toward consolidated distributor contracts with volume-tier pricing and technical support attachments. Independent repair chains in Hanoi and Ho Chi Minh City are displacing fragmented retail purchases through direct sourcing arrangements. This pattern is most visible in the Red River Delta corridor where vehicle density supports distributor route efficiency.
Vietnam Passenger Vehicles Lubricants Market Segmentation
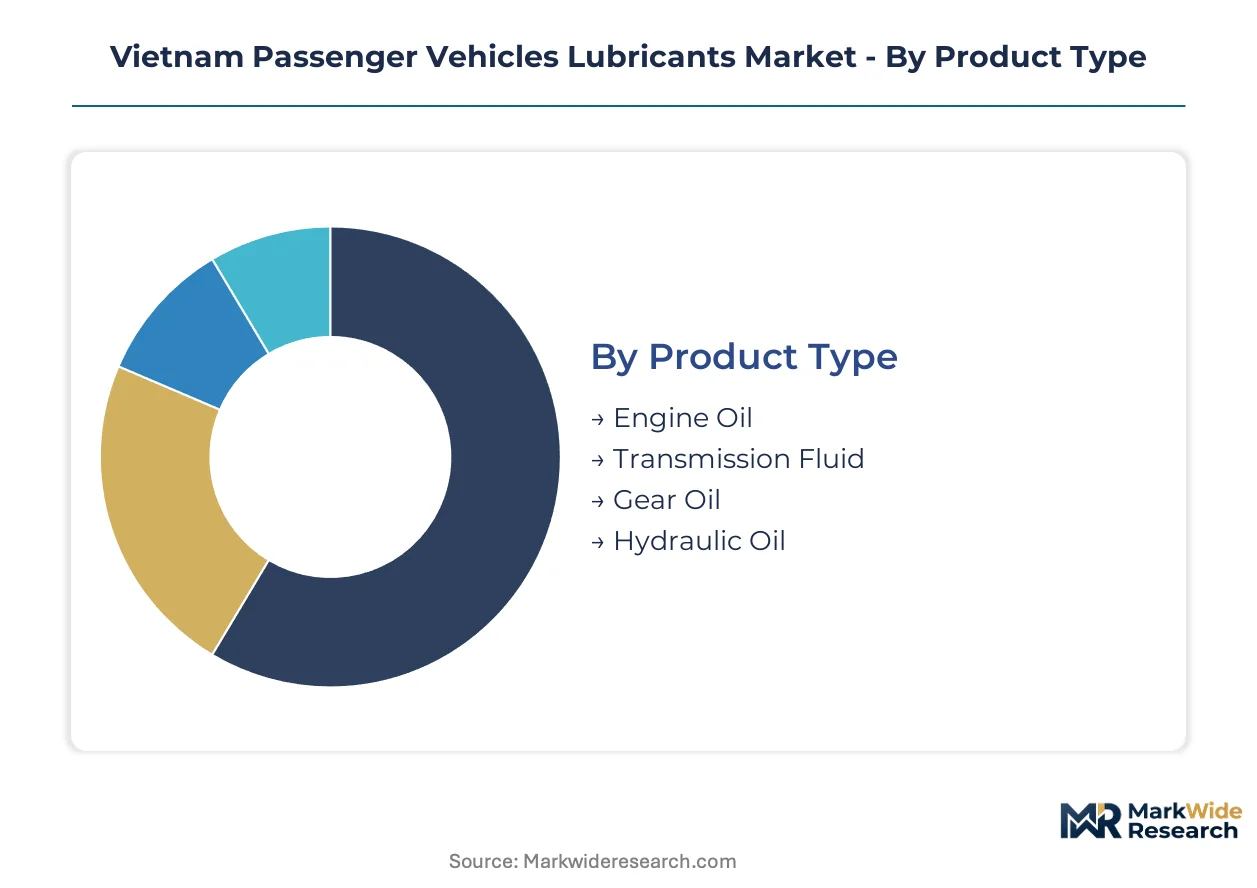
Segmentation in Vietnam's passenger vehicle lubricants market reveals distinct procurement patterns across product formulations, vehicle architectures, and channel structures. Each dimension carries implications for blending capacity allocation, certification requirements, and margin capture.
Product Type:
Product categories split between fluids consumed in standalone drain intervals versus those embedded in sealed transmission systems with extended service life.
- Engine Oil:Formulations range from mineral-based 15W-40 for legacy parc to full-synthetic 0W-20 for gasoline direct-injection engines under Circular 07/2021 compliance. Volume concentrates in the Red River Delta corridor where fleet operators standardize synthetic adoption for high-mileage vehicles. Regulatory tightening compresses drain intervals and elevates API SP and ILSAC GF-6 specifications as baseline requirements.
- Transmission Fluid:Specialized chemistries for continuously variable, dual-clutch, and torque-converter automatics command technical switching costs and limited cross-compatibility between OEM platforms. Demand clusters around Japanese and Korean assembly plants in Thai Nguyen and Vinh Phuc provinces where CVT-equipped sedans dominate production output. The segment captures margin premiums through proprietary additive packages co-engineered with transmission suppliers.
- Gear Oil:Hypoid formulations for differential and final-drive applications serve rear-wheel-drive and all-wheel-drive architectures in the expanding SUV parc.
- Hydraulic Oil:Power steering and brake system fluids represent smaller volume positions with specialized elastomer compatibility requirements.
Volume placements concentrate in Engine Oil; the faster expansion belongs to Transmission Fluid.
Vehicle Type:
Vehicle architectures distribute lubricant demand across divergent operating regimes, thermal loads, and OEM specification intensities.
- SUV:Higher displacement engines and all-wheel-drive configurations multiply fluid volumes per vehicle while demanding robust high-temperature stability for turbocharged powertrains. Urban adoption in Ho Chi Minh City and Hanoi drives synthetic penetration as owners prioritize warranty compliance and extended drain intervals.
- Sedan:The dominant parc category carries fragmented specification requirements spanning economy mineral oils to full-synthetic grades. Provincial markets retain older sedan fleets resistant to low-viscosity reformulation, forcing distributors to maintain dual inventory positions.
- Hatchback:Compact urban vehicles concentrate demand in first-owner segments with price-sensitive maintenance behaviors.
- Coupe:Niche sports-oriented architectures specify premium synthetic formulations with enhanced high-RPM protection chemistries.
Specification complexity peaks in SUV applications; hatchback maintenance behaviors impose the strongest price elasticity constraints.
Distribution Channel:
Channel structures reflect divergent customer acquisition costs, technical support requirements, and inventory velocity profiles across the value chain.
- Retail:Branded service stations and automotive parts stores serve individual owners with immediate-need purchasing patterns. Shell Vietnam leverages its nationwide retail network to anchor premium visibility in urban locations while competing against unbranded imports in secondary provinces.
- Service Station:Integrated oil-change operations capture high-margin installation labor alongside fluid sales, with loyalty programs driving repeat visitation. Workshop consolidation in Hanoi and Ho Chi Minh City is displacing fragmented retail purchases through direct fleet-account arrangements.
- Distributor:Route-based delivery to independent repair chains enables volume-tier pricing and technical support attachments.
- Online:E-commerce platforms serve price-comparison shoppers with limited technical consultation, concentrating in standard-grade engine oils with clear specification labeling.
Margin capture favors Service Station integration; Distributor routes are gaining share fastest through workshop chain consolidation.
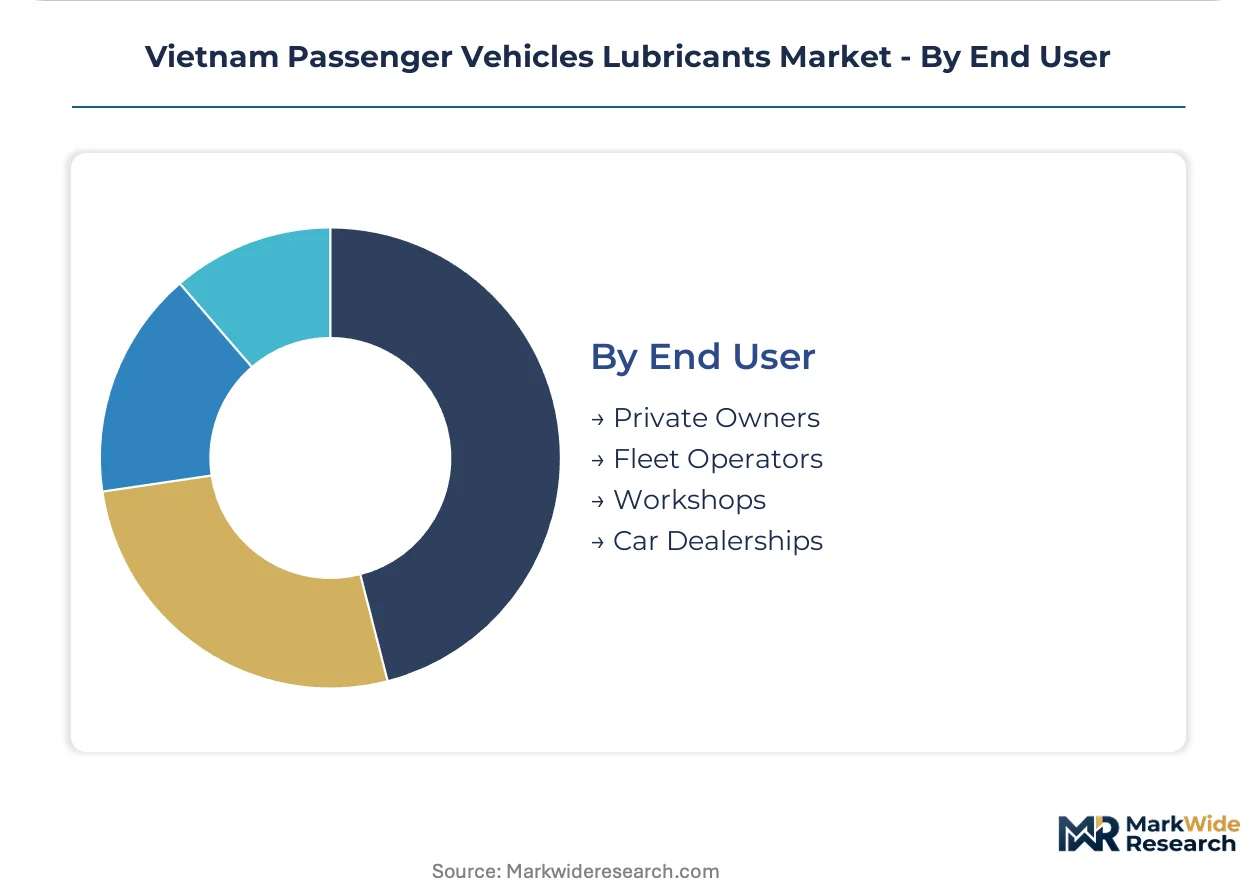
End User:
End-user categories separate individual consumption patterns from institutional procurement with centralized technical standards and volume aggregation.
- Fleet Operators:Ride-hailing and corporate fleet managers in Ho Chi Minh City and Hanoi enforce scheduled maintenance programs with synthetic oil mandates across high-mileage vehicles. Centralized procurement contracts specify Vietnam Register-certified products with documented drain intervals for warranty compliance.
- Workshops:Independent repair chains are consolidating procurement away from fragmented retail, favoring suppliers with direct technical support and inventory management capabilities. The channel represents the fastest-growing demand position as vehicle density in the Red River Delta supports distributor route efficiency.
- Private Owners:Individual vehicle owners exhibit price sensitivity and brand loyalty fragmentation, with specification awareness varying sharply by urban versus provincial location.
- Car Dealerships:OEM-authorized service networks enforce strict documentation requirements and proprietary fluid specifications, locking independent competitors out of newer vehicle parc revenue.
Procurement standardization advances fastest among Fleet Operators; Workshop channel consolidation is reshaping distributor competitive dynamics most dramatically.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Red River Delta corridor anchors Vietnam's passenger vehicle lubricants demand, with Hanoi and surrounding provinces concentrating vehicle density that exceeds national benchmarks. This northern industrial belt drives specification intensity through Japanese and Korean OEM assembly plants. The analysis examines five sub-regional markets that collectively shape procurement patterns and regulatory compliance requirements.
Red River Delta
Japanese and Korean OEM assembly plants in Thai Nguyen and Vinh Phuc provinces generate concentrated demand for 0W-20 and 5W-30 specifications. Vietnam's Ministry of Transport enforces Circular 07/2021 emission testing protocols most stringently in this corridor. Hanoi vehicle density supports distributor route efficiency and workshop chain consolidation.
Southeast Region
Ho Chi Minh City ride-hailing fleet operators standardize synthetic oil adoption across high-mileage vehicles under severe service conditions. The Vietnam Register certifies lubricant performance claims through roadside inspection equipment deployment. Binh Duong and Dong Nai industrial zones concentrate independent repair chains centralizing procurement.
Mekong Delta
Can Tho and surrounding provinces exhibit lower synthetic penetration rates than northern corridors, presenting first-mover positioning for branded distributors. STAMEQ registration timelines under ASEAN harmonization roadmaps extend time-to-market for reformulated SKUs. Provincial markets here retain older vehicle parc resistant to low-viscosity specifications.
North Central Coast
Thanh Hoa and Nghe An provinces serve as transit corridors connecting northern manufacturing belts to southern consumption centers. Base oil import dependency exposes regional blenders to freight cost volatility on API-certified Group II/III feedstock. Distributor networks in Vinh City struggle against unbranded import competition from regional traders.
Central Highlands
Gia Lai and Dak Lak provinces represent underpenetrated terrain where commodity mineral oils retain share against synthetic upgrading trends. Warranty compliance documentation requirements lock independent workshops out of newer vehicle parc service revenue. Dalat and Pleiku urban centers concentrate limited fleet operator activity in agricultural processing logistics.
Vietnam Passenger Vehicles Lubricants Market Competitive Landscape
Capital-heavy producers with captive refining assets compete with asset-light brand licensors and import-dependent blenders for position in Vietnam's passenger vehicle lubricants market. The competitive structure stratifies into three tiers: multinational majors leveraging global formulation libraries, national oil companies with backward integration into base oil supply, and regional specialists serving price-sensitive provincial segments. Strategic moves concentrate on workshop channel consolidation through direct fleet-account contracts and technical support attachments.
Within the multinational tier, Royal Dutch Shell Plc and BP Plc occupy positions anchored by technical partnerships with Japanese and Korean OEM assembly plants. Shell Vietnam exemplifies the retail-network archetype through nationwide service station visibility. PVOIL represents the integrated national champion with upstream control over base oil refining at its Dung Quat complex. Motul Vietnam JSC sits within the premium specialist category targeting performance-oriented vehicle owners.
| Leading Market Players |
|---|
| Royal Dutch Shell Plc |
| Shell Vietnam |
| BP Plc (Castrol) |
| Motul Vietnam JSC |
| PVOIL |
| Mekong Petrochemical JSC |
| TotalEnergies |
| AP Saigon Petro JSC |
| Petrolimex (PLX) |
| Others |
Value Network & Pricing Analysis
Backward integration into base oil refining at PVOIL's Dung Quat complex anchors supply security and pricing power for Vietnam's national champion, while import-dependent blenders absorb freight volatility and currency fluctuation on API-certified Group II/III feedstock. This structural asymmetry stratifies the competitive landscape between captive producers and exposed compounders.
Pricing Analysis
Outcome-based pricing tied to warranty compliance and documented drain intervals anchors premium capture for Vietnam Register-certified formulations. Price differentiation separates full-synthetic 0W-20 specifications from commodity mineral 15W-40 grades through API SP certification tiers and OEM technical partnerships. Pricing pressure intensifies in secondary provinces where unbranded regional imports exploit price-sensitive segments. Fleet operators in Hanoi and Ho Chi Minh City exhibit lowest price sensitivity due to centralized procurement mandates and warranty documentation requirements.
Supply Chain Analysis
Dual-sourcing requirements from Japanese and Korean OEM assembly plants in Thai Nguyen and Vinh Phuc provinces mandate qualified supplier rosters spanning Singapore, South Korea, and Thailand for additive package inputs. Base oil feedstock draws from Middle Eastern and Southeast Asian refiners, exposing blenders to shipping route congestion and bunker fuel cost swings. Single-source vulnerability concentrates in Group III synthetic base oil channels where regional capacity constraints limit alternative qualification. Distribution runs through consolidated distributor contracts serving workshop chain consolidation in the Red River Delta corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vietnam's passenger vehicle lubricants market reads as supply-constrained due to absent domestic Group II/III base oil production, propping pricing power for backward-integrated incumbents while compressing margins for import-dependent blenders.
For Market Incumbents: Cement workshop channel control through direct fleet-account contracts with technical support attachments in Ho Chi Minh City and Hanoi. Defend against unbranded import erosion by accelerating STAMEQ registration coverage for Circular 07/2021-compliant formulations. Prioritize additive package modularization to compress development cycles for OEM-specific approvals. For New Entrants and Emerging Players: Enter via underpenetrated Mekong Delta provinces where synthetic adoption lags northern corridors and distributor networks remain fragmented. Target Can Tho and surrounding agricultural logistics hubs with CVT fluid specialization for Japanese sedan fleets. Deploy route-based technical service capabilities to differentiate from commodity importers. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by multinational majors seeking captive base oil supply and Vietnam Register certification infrastructure. Long-term viability hinges on reformulation agility as emission standards tighten. Monitor STAMEQ approval velocity as inflection indicator for competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base Oil Refining | PVOIL's Dung Quat complex secures captive Group II supply against import volatility. |
| Workshop Channel Consolidation | Direct fleet-account contracts displace fragmented retail in Red River Delta corridor. |
| Modular Additive Package Architecture | Discrete performance modules compress Circular 07/2021 formulation development cycles. |
| CVT Fluid Technical Partnership | Co-engineering with Japanese transmission suppliers creates proprietary specification lock-in. |
| Mekong Delta Distribution Expansion | First-mover positioning in Can Tho exploits synthetic penetration gap versus northern markets. |
Research Methodology
Multi-period observation of vehicle registration data, lubricant import volumes, and workshop procurement patterns anchored the trend analysis, supplemented by interviews with blending plant managers, OEM procurement leads at Thai Nguyen assembly facilities, distributor route operators, and independent repair chain owners. Secondary validation drew from Vietnam Register certification records, STAMEQ product registration databases, Ministry of Transport emission testing protocols, and customs trade data on base oil feedstock imports. Bottom-up triangulation across channel volume estimates and top-down reconciliation against national vehicle parc data ensured analytical coherence.
Segment-weighting across product type, vehicle architecture, distribution channel, and end-user category shaped the analytical framework throughout the projection horizon. CAGRs derived from elasticity modeling against vehicle sales forecasts and regulatory compliance timelines. Industry-specific inputs included parc turnover assumptions tied to Circular 07/2021 enforcement intensity and synthetic penetration curves calibrated to fleet operator procurement standardization.
Revisions become necessary when base oil import tariff structures shift, STAMEQ registration timelines extend under ASEAN harmonization, or carbon-neutral fuel standards accelerate reformulation requirements beyond existing blending asset capabilities. Deviation in OEM assembly plant output from Thai Nguyen and Vinh Phuc provinces would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Insert Drive for Torque Wrench Market
Automotive Parts
Automotive Brake Fluid Market
Automotive Parts
Automotive Control Arms Market
Automotive Parts
UK Automotive Parts Aluminium Die Casting Market
Automotive Parts
Windshield Lifters Market
Automotive Parts
Automotive Engine Oil Coolant Market
Automotive Parts
Automotive Oil and Air Filters Market
Automotive Parts
Brake Shoe Market
Automotive Parts
Industrial Bearings Market
Automotive Parts
Canada Automotive Parts Die Casting Market
Automotive Parts
Europe Automotive Parts Zinc Die Casting Market
Automotive Parts
Road Snow Melt Market
Automotive Parts
Europe Automotive Aftermarket Spare Parts Market
Automotive Parts
United States Passenger Vehicles Lubricants Market
Automotive Parts
X-Arm Type Window Regulator Market
Automotive Parts
Motorcycle Catalyst Market