
 Morocco Automotive Lubricants Market | 2026-2036
Morocco Automotive Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
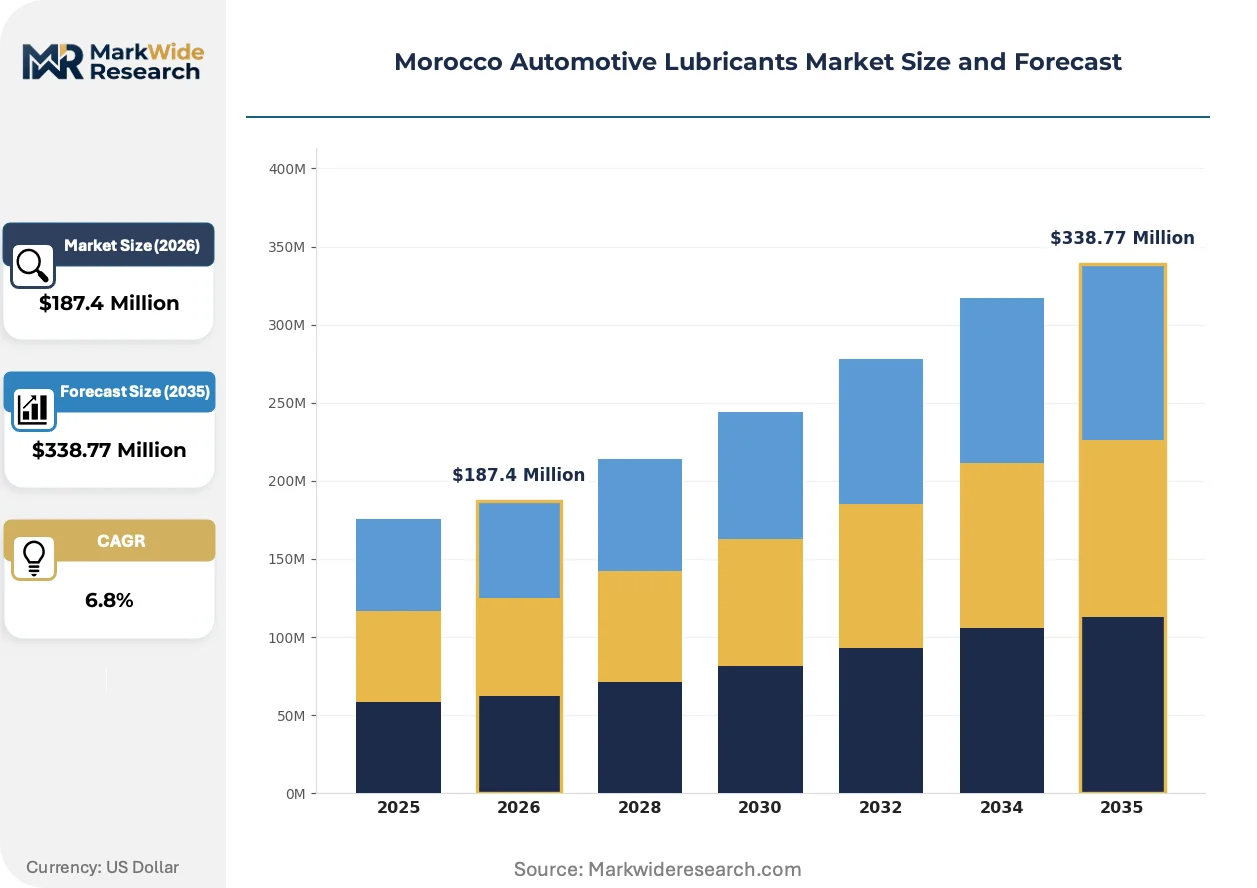
Morocco Automotive Lubricants Market Foresight
Fleet consolidation among Moroccan commercial transport operators is pivoting procurement toward bulk synthetic formulations. TotalEnergies leverages its coastal blending facility to anchor supply contracts with national logistics chains. Afriquia competes through its integrated gas station network, while FUCHS specializes in high-performance greases for mining and construction equipment.
Automotive lubricants are formulated base oil mixtures with viscosity modifiers, detergents, and anti-wear additives designed to reduce friction, dissipate heat, and prevent corrosion in powertrain systems. Engine oil commands the dominant volume share across Moroccan service channels, reflecting the country's aging passenger vehicle parc. Transmission fluid represents the fastest-growing product category as automatic gearbox penetration rises in urban taxi and ride-hail fleets. Packaging in bulk containers captures margin concentration from industrial and fleet accounts, while retail bottles serve the fragmented aftermarket.
Morocco's Ministry of Energy Transition and Sustainable Development enforces fuel economy standards that indirectly tighten lubricant performance requirements, while the country's national quality regulator verifies SAE and API certifications for imported formulations. Stakeholders must monitor how Euro VI-equivalent vehicle standards reshape additive specifications and whether domestic blending capacity expands to offset import dependency.
Market Dynamics
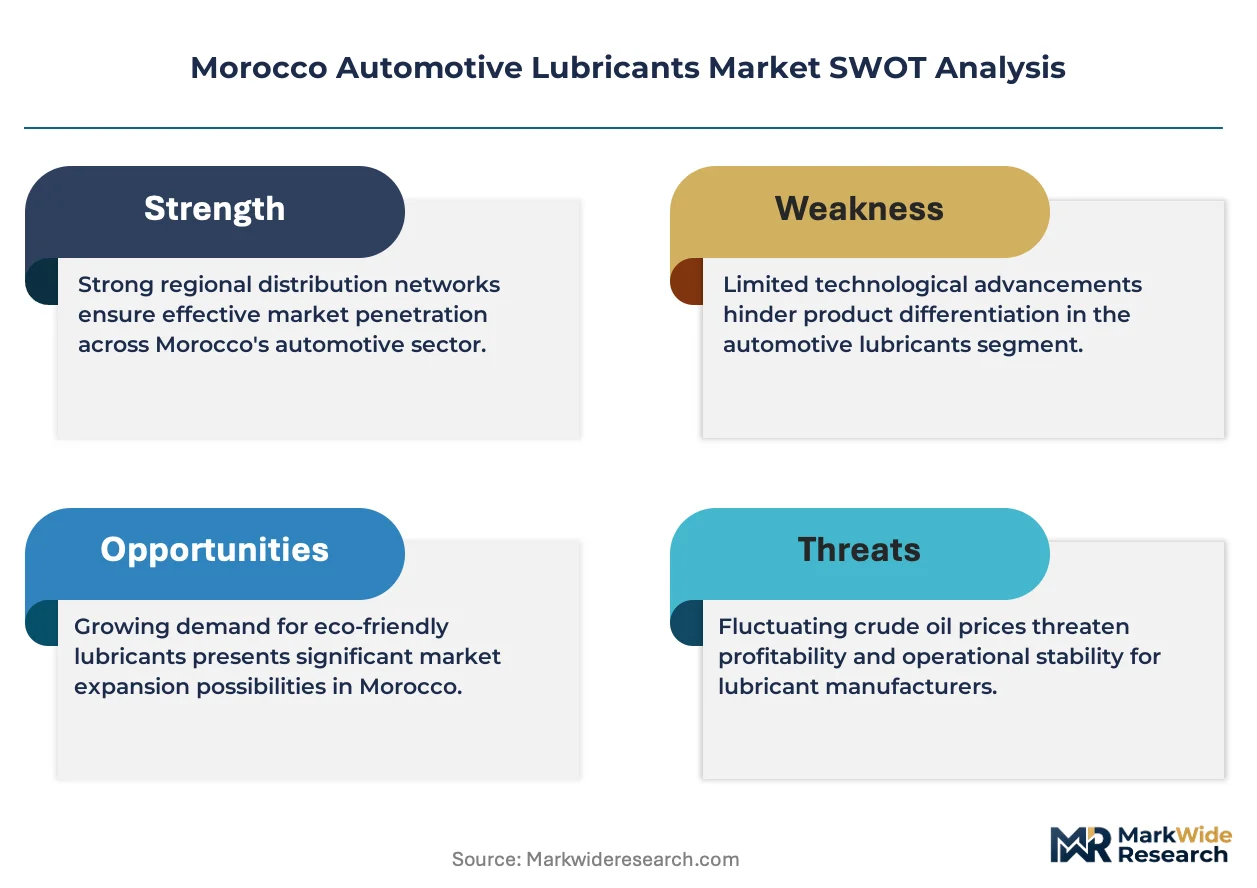
Fleet operators in Casablanca's logistics corridor are consolidating purchasing power, forcing lubricant suppliers to restructure contract terms around bulk synthetic formulations and performance guarantees rather than per-liter pricing.
Growth Catalysts
- Euro VI-equivalent standards:Morocco's Ministry of Energy Transition and Sustainable Development enforces emissions benchmarks that compel commercial transport operators to upgrade to high-performance lubricants with advanced additive packages.
- Automatic transmission penetration:Urban taxi and ride-hail fleets are accelerating replacement cycles for transmission fluid as dual-clutch and CVT systems enter the vehicle parc.
- Coastal blending infrastructure:Domestic formulation capacity at port-adjacent facilities reduces lead times for national logistics chains serving the Agadir-Casablanca-Tangier commercial axis.
Market Restraints
- Base oil import dependency:Morocco lacks Group III and PAO manufacturing capacity, exposing formulators to freight cost volatility from Middle Eastern and European refiners.
- API certification bottlenecks:The national quality regulator's verification timelines for imported additive packages delay product launches by six to nine months.
- Mineral oil substitution inertia:Aging passenger vehicle parc in secondary cities sustains demand for conventional formulations, compressing margin expansion for synthetic suppliers.
Strategic Opportunities
- Marrakech-Agadir tourism corridor:Car rental and hospitality fleet operators remain underserved by premium service networks, creating white space for mobile lubricant change units.
- Renewable energy equipment:Wind turbine gearbox lubrication requirements at the Tarfaya and Essaouira wind farms open industrial grease specialization pathways.
- Digital fleet management integration:Telematics-enabled oil condition monitoring allows suppliers to embed lubricant procurement into predictive maintenance contracts.
Industry Challenges
- Additive chemist scarcity:Moroccan technical universities produce limited lubricant formulation specialists, forcing blenders to recruit from Algerian and Tunisian talent pools.
- SAE viscosity grade harmonization:Divergent OEM specifications between European and Asian vehicle imports complicate inventory planning for service stations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Morocco Automotive Lubricants Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Transmission Fluid, Grease, Hydraulic Oil Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Heavy-Duty Vehicles Distribution Channel: Online Retail, Gas Stations, Auto Parts Stores, Warehouses Packaging Type: Drums, Bottles, Pails, Bulk Containers |
| Companies Covered | TotalEnergies, FUCHS, Afriquia, Winxo, Motul, OLA Energy, Royal Dutch Shell, Ziz Lubrifiant, Petrom, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Morocco Automotive Lubricants Market Shifts & Advancements
Synthetic base oil technology is rewriting performance benchmarks across Moroccan service channels, while regulatory pressure on commercial emissions accelerates formulation complexity. Digital tools are penetrating procurement workflows, compressing traditional distributor relationships.
Group III+ base stocks are converging with advanced detergent-dispersant packages to extend drain intervals for heavy-duty diesel fleets. Long-haul operators adopting these formulations reduce maintenance downtime by forty percent. This convergence is compressing the addressable market for mid-tier mineral blends in the Casablanca-Rabat freight corridor.
Morocco's Ministry of Energy Transition and Sustainable Development is tightening fuel economy verification protocols that indirectly mandate lower viscosity grades. Domestic blenders must reformulate product lines to maintain OEM approvals. Commercial transport operators face the steepest compliance costs as their vehicle mix skews toward post-2020 Euro VI-equivalent engines.
Service station networks are unbundling lubricant sales from mechanical labor, enabling direct-to-fleet bulk delivery contracts. Independent quick-lube outlets in Tangier and Fez are losing share to mobile service units operated by national distributors. This channel rotation is most visible in the ride-hail segment, where driver cooperatives negotiate consolidated purchasing agreements bypassing retail entirely.
Morocco Automotive Lubricants Market Segmentation
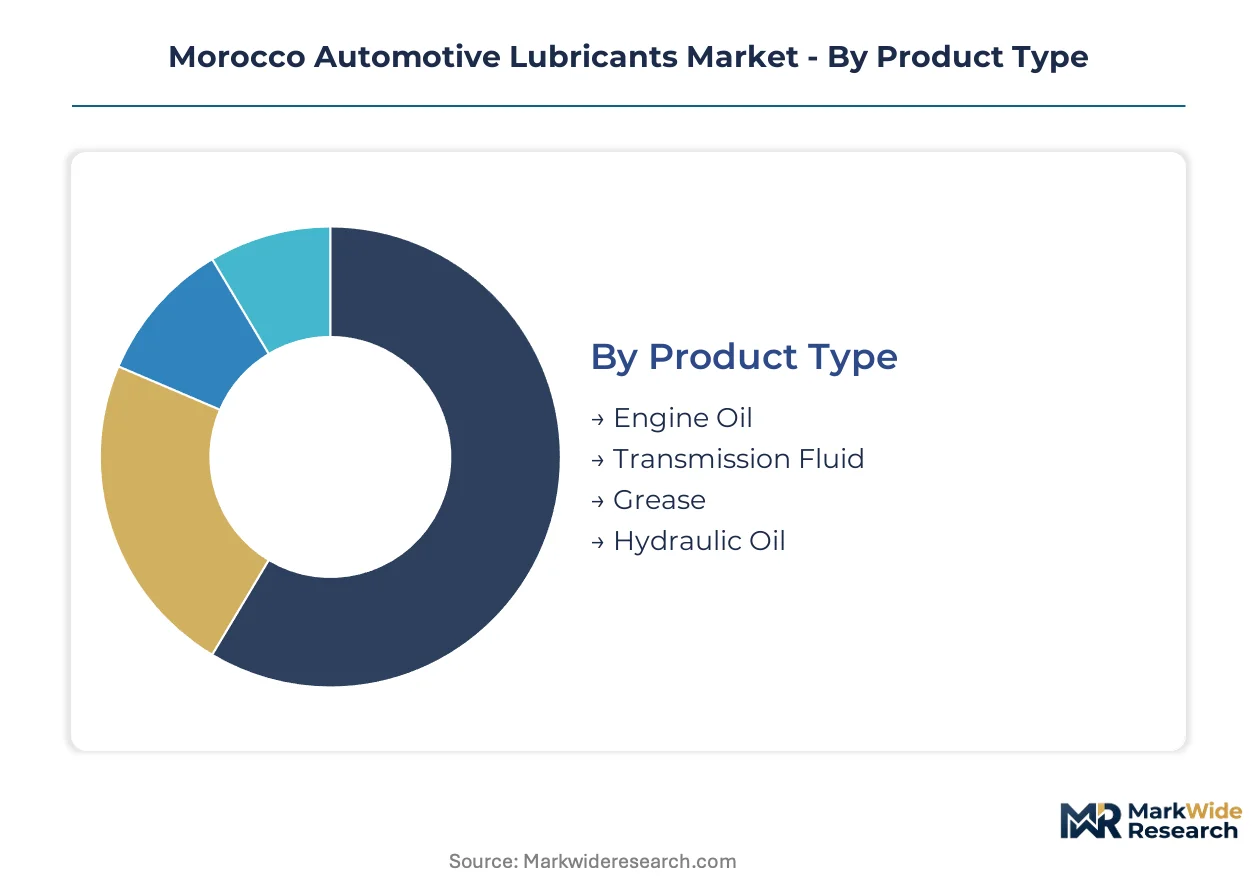
Morocco's automotive lubricant supply chain fragments across four distinct category axes. Each dimension captures a different competitive pressure—formulation technology, end-use concentration, channel control, and procurement scale.
Product Type:
Blending capacity concentrates around formulations serving the country's dominant vehicle service requirements.
- Engine Oil:Formulated base oil mixtures with viscosity modifiers and detergent-dispersant packages designed to reduce friction in powertrain systems. Casablanca's passenger vehicle service network absorbs the majority of volume as the country's aging vehicle parc sustains replacement demand. The Ministry of Energy Transition's fuel economy verification protocols indirectly tighten performance specifications for this category.
- Transmission Fluid:Specialized lubricants engineered for gear protection and thermal stability in automatic and manual transmission systems. Urban taxi and ride-hail fleets in Tangier and Rabat are accelerating replacement cycles as dual-clutch and CVT penetration rises. This segment is climbing the fastest as fleet operators upgrade to extended-drain formulations.
- Grease:Thickened lubricant formulations combining base oils with metallic soap or complex thickeners for boundary lubrication conditions. Mining equipment at Khouribga and construction machinery across the Marrakech-Safi corridor generate concentrated demand.
- Hydraulic Oil:Low-compressibility fluids with anti-wear and oxidation inhibitors for power transmission in hydraulic systems. Agricultural machinery in the Gharb and Doukkala plains represents the primary consumption cluster.
Engine Oil absorbs the bulk of installed capacity; Transmission Fluid is expanding most quickly.
Application:
End-use demand stratifies by vehicle ownership structure and operational intensity.
- Passenger Vehicles:Lubricant consumption tied to Morocco's private vehicle parc and aftermarket service intervals. Secondary cities sustain mineral oil demand while Casablanca-Rabat corridors pivot toward synthetic formulations.
- Commercial Vehicles:Fleet-operated trucks and vans subject to Euro VI-equivalent emissions compliance. Long-haul operators on the Agadir-Casablanca-Tangier axis are consolidating procurement around bulk synthetic contracts with performance guarantees.
- Two-Wheelers:Motorcycle and scooter lubrication requirements concentrated in urban delivery and personal mobility segments. Fez and Meknes represent underserved service network territories.
- Heavy-Duty Vehicles:Construction, mining, and specialized transport equipment with severe-duty operating cycles. The OCP mining complex at Khouribga and port logistics at Jorf Lasfar anchor regional demand clusters.
Passenger Vehicles command the deepest volume base; Commercial Vehicles are gaining share fastest through fleet consolidation.
Distribution Channel:
Channel structure reflects the tension between retail fragmentation and fleet-direct procurement.
- Online Retail:E-commerce platforms serving DIY maintenance consumers and small independent garages. Casablanca's digital logistics infrastructure enables next-day delivery coverage of northern urban corridors.
- Gas Stations:Forecourt lubricant sales integrated with fuel retail networks. Afriquia's national station footprint captures impulse purchases and emergency top-ups.
- Auto Parts Stores:Independent and chain-affiliated retailers serving the fragmented aftermarket. Inventory complexity from divergent OEM specifications complicates working capital management.
- Warehouses:Bulk storage and direct-distribution nodes for fleet and industrial accounts. TotalEnergies leverages coastal blending facility proximity to anchor national logistics chain contracts.
Gas Stations retain the broadest geographic footprint; Warehouses are expanding most quickly as fleet procurement consolidates.
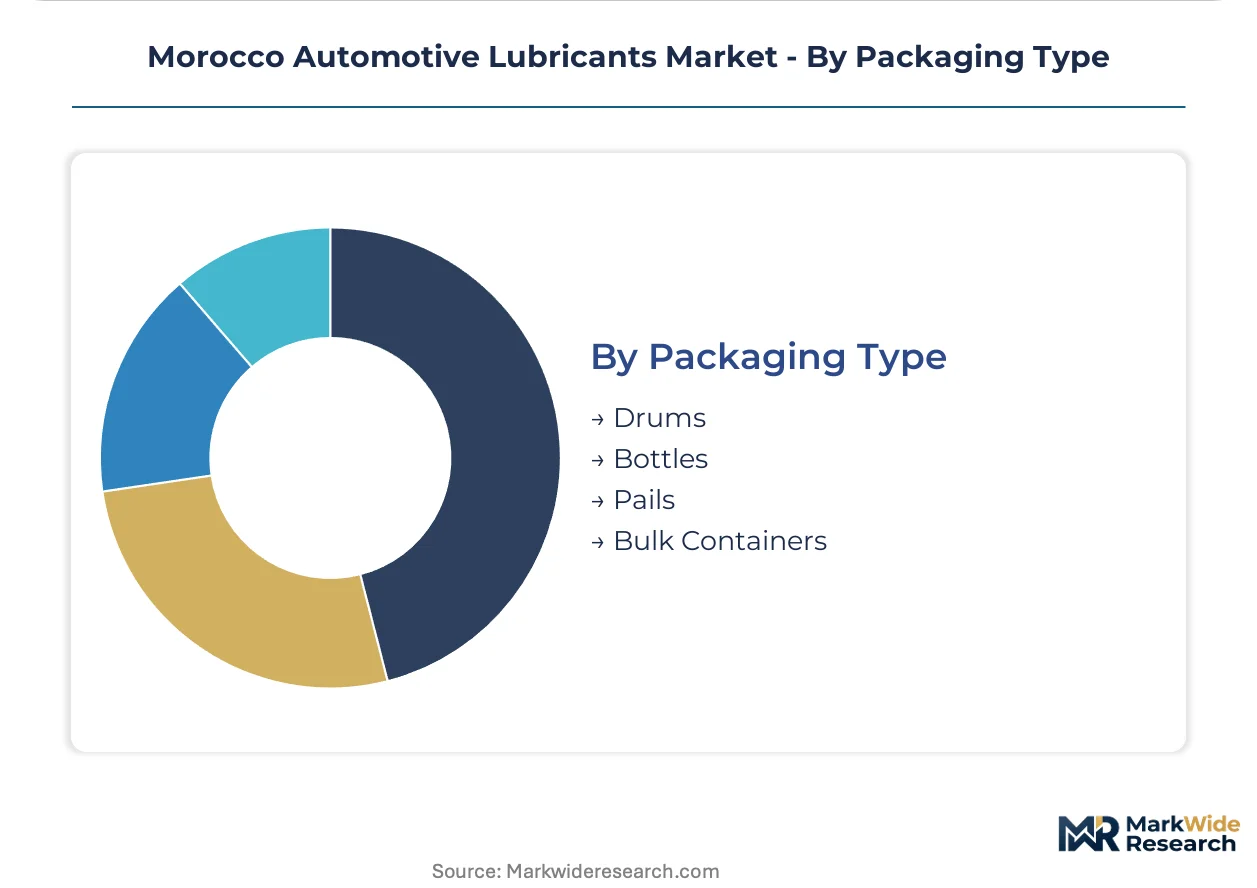
Packaging Type:
Container configuration separates retail convenience from industrial procurement economics.
- Drums:200-liter steel containers serving mid-size fleet operators and independent service stations. The Casablanca-Rabat freight corridor represents the primary consumption geography.
- Bottles:Consumer-format packaging for retail aftermarket and DIY maintenance. Margin compression from price transparency limits supplier profitability.
- Pails:Intermediate-capacity containers for small fleet and commercial workshop segments. Port-adjacent blending facilities reduce inland freight costs for this format.
- Bulk Containers:Tanker and flexitank deliveries for national logistics chains and industrial accounts. Coastal infrastructure enables direct vessel-to-tanker transfer, minimizing handling costs.
Bulk Containers capture the steepest margin concentration; Drums remain the workhorse format for mid-tier fleet penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Morocco's phosphate reserves at Khouribga and Youssoufia anchor domestic chemical processing capacity that feeds downstream lubricant additive manufacturing. The country's Atlantic coastline positions bulk blending facilities for regional export reach into West African markets.
Casablanca-Settat
Industrial lubricant demand concentrates at Jorf Lasfar port logistics and the Mohammedia refinery complex. Morocco's Ministry of Energy Transition enforces Euro VI-equivalent emissions verification for commercial fleets registered in this region. TotalEnergies operates coastal blending capacity serving national distribution networks.
Tangier-Tetouan-Al Hoceima
Automotive assembly plants at the Tangier Med industrial zone generate OEM-fill lubricant requirements for Renault and Stellantis production lines. The national quality regulator maintains API certification oversight for imported formulations entering through Mediterranean ports. Ride-hail fleet operators in Tangier urban corridors accelerate synthetic transmission fluid replacement cycles.
Marrakech-Safi
Tourism rental fleets and hospitality transport operators sustain seasonal lubricant demand peaks. Agricultural machinery across the Haouz Plain consumes hydraulic oil formulations for irrigation equipment. Mobile service units are penetrating underserved car rental channels along the Agadir coastal route.
Fez-Meknes
Secondary city vehicle parc sustains mineral oil demand despite synthetic conversion in coastal metros. The OCP mining complex at Khouribga generates concentrated grease consumption for phosphate extraction equipment. Independent quick-lube outlets retain market share against national distributor consolidation.
Rabat-Salé-Kénitra
Government fleet procurement centralization creates volume concentration for bulk synthetic contracts. Administrative vehicle pools face accelerated emissions compliance timelines under national energy transition mandates. Warehouse distribution nodes along the Atlantic rail corridor reduce inland freight costs for national logistics chains.
Morocco Automotive Lubricants Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue digital fleet integration and renewable energy equipment specialization. The supplier base concentrates around three archetypes: integrated energy majors with coastal blending infrastructure, regional distributors leveraging gas station networks, and industrial specialists targeting mining and construction verticals. Competitive positioning hinges on bulk contract restructuring and predictive maintenance service bundling rather than per-liter pricing.
Within the integrated energy tier, TotalEnergies and Royal Dutch Shell anchor supply relationships through port-adjacent formulation capacity. Afriquia occupies a position exemplifying network-based distribution archetypes, while FUCHS represents industrial specialization pathways. These three entities illustrate how geographic positioning, retail footprint density, and sector-specific formulation expertise respectively define viable competitive strategies in the Moroccan market.
| Leading Market Players |
|---|
| TotalEnergies |
| FUCHS |
| Afriquia |
| Winxo |
| Motul |
| OLA Energy |
| Royal Dutch Shell |
| Ziz Lubrifiant |
| Petrom |
| Others |
Supply & Pricing Matrix
Middle Eastern Group II/III base oil export benchmarks cascade through Moroccan blending economics, compressing margins for formulators lacking coastal storage infrastructure while amplifying pricing power for integrated operators with direct vessel-to-tanker transfer capabilities at Jorf Lasfar.
Pricing Analysis
Warranty-bundled service contracts now separate lubricant procurement from mechanical labor across Casablanca's fleet corridors. Three-tier pricing structure across premium synthetic, mid-tier semi-synthetic, and economy mineral levels stratifies by SAE certification grade and drain-interval guarantees. Cost compression in the mid-tier segment is intensifying because Afriquia's gas station network and TotalEnergies' coastal blending facility compete for identical logistics contracts. Price sensitivity peaks among independent quick-lube outlets in Fez and Meknes, while national logistics chains prioritize performance guarantees over per-liter rates.
Supply Chain Analysis
Morocco's domestic-content mandates for industrial procurement reshape sourcing patterns for state-affiliated fleet operators, nudging formulators toward local blending partnerships. Supply draws from Saudi Arabian and UAE Group II/III refiners, Spanish additive package suppliers, and domestic phosphate-derived detergent production at Khouribga. Raw material dependencies center on polyalphaolefin (PAO) synthetic base stocks, zinc dialkyldithiophosphate (ZDDP) anti-wear additives, and viscosity modifier polymers. Single-source vulnerability concentrates in API-certified additive packages facing six-to-nine-month national quality regulator verification timelines. Distribution runs through coastal blending facilities feeding warehouse nodes along the Atlantic rail corridor, with bulk tanker deliveries displacing drum-format mid-tier procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Morocco's automotive lubricants sector functions as a cost-of-compliance arena where Euro VI-equivalent emissions verification protocols erect formidable barrier-to-entry moats for formulators lacking pre-certified additive portfolios and coastal blending infrastructure.
For Market Incumbents: Anchor defensive positioning through backward integration into phosphate-derived detergent manufacturing at Khouribga, capturing captive supply of critical dispersant chemistries. Expand coastal storage capacity at Jorf Lasfar to offset freight cost volatility from Middle Eastern refiners. Digital fleet management platforms threaten traditional distributor relationships; embed lubricant procurement into predictive maintenance contracts before ride-hail cooperatives consolidate purchasing entirely. For New Entrants and Emerging Players: Launch via mobile service units targeting the Marrakech-Agadir tourism corridor, where car rental fleets remain underserved by premium networks. The renewable energy equipment segment—specifically wind turbine gearbox lubrication at Tarfaya and Essaouira—offers white-space specialization with limited incumbent competition. Pursue white-label blending partnerships with existing coastal facilities to bypass capital-intensive infrastructure requirements. For Investors and Strategic Acquirers: The window for entry favors industrial specialists with mining grease formulation expertise, as OCP's phosphate extraction operations at Khouribga sustain concentrated demand. Long-term viability hinges on additive chemist talent acquisition from Algerian and Tunisian technical universities. Monitor API certification queue lengths at the national quality regulator as the inflection signal—compression toward three-month timelines would unlock product launch velocity for compliant players.| Strategic Initiative | Industry Significance |
|---|---|
| Coastal Blending Capacity Expansion | Jorf Lasfar port-adjacent facilities reduce lead times for national logistics chains serving the Agadir-Casablanca-Tangier axis. |
| Phosphate-Derived Additive Integration | Backward integration into Khouribga detergent manufacturing captures captive supply of dispersant packages for engine oil formulations. |
| Digital Fleet Management Partnership | Telematics-enabled oil condition monitoring embeds lubricant procurement into TotalEnergies' predictive maintenance contracts. |
| Renewable Energy Equipment Specialization | Wind turbine gearbox lubrication requirements at Tarfaya and Essaouira open industrial grease pathways beyond automotive saturation. |
| Mobile Service Unit Deployment | Direct-to-fleet bulk delivery bypasses retail fragmentation in Tangier and Fez where independent quick-lube outlets retain share. |
Research Methodology
Trade publications, customs import records, and national energy ministry disclosures formed the secondary backbone, cross-referenced against primary interviews with lubricant blending plant managers, fleet procurement directors at national logistics chains, aftermarket service station operators, and Ministry of Energy Transition officials. Bottom-up volume estimates derived from vehicle parc analysis and service interval modeling were reconciled with top-down market sizing from industry association data.
Bottom-up modeling segmented consumption across engine oil, transmission fluid, grease, and hydraulic oil categories, further disaggregated by passenger vehicle, commercial vehicle, two-wheeler, and heavy-duty equipment end-uses. The analytical framework incorporated vehicle registration trends, OEM-fill specifications from Renault and Stellantis assembly at Tangier Med, and fleet operator consolidation patterns across the analysis window. CAGRs were derived from regression analysis of historical volume trajectories against regulatory phase-in schedules.
The model assumes a particular technology adoption path; alternative pathways for synthetic base oil conversion in Morocco's aging passenger vehicle parc would alter the outlook. Forecasts reflect assumptions about Euro VI-equivalent compliance timelines, additive package certification velocity, and coastal infrastructure investment continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Solenoid Market
Automotive Components
North America Automotive Hydraulic Actuators Market
Automotive Components
US Automotive Composites Market
Automotive Components
India Automotive Airfilters Market
Automotive Components
Global Flexible Shaft Couplings Market
Automotive Components
Automotive Pressure Plate Market
Automotive Components
Global Cylinder Deactivation System Market
Automotive Components
Automotive Stabilizer Bar Link Market
Automotive Components
Bulgaria Commercial Vehicles Lubricants Market
Automotive Components
Drive System Market
Automotive Components
Automotive Gear Oil Market
Automotive Components
Automotive Engine Bearings Market
Automotive Components
Automotive Light Bars Market
Automotive Components
Automotive Regenerative Braking System Market
Automotive Components
Automotive Catalytic Converter Market
Automotive Components
Global Automotive Gearbox Market